
 Portugal Gas Generator Market | 2026-2036
Portugal Gas Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Portugal Gas Generator Market Analytics
Steel is decoupling from traditional cast-iron engine blocks as manufacturers seek weight reduction and thermal efficiency gains in gas generator assemblies. Cummins Inc. leverages its European engineering centers to refine high-compression natural gas platforms for Iberian climate conditions. Grupel SA anchors its competitive stance through captive manufacturing in northern Portugal, controlling component sourcing for medium-power units. Mitsubishi Heavy Industries Ltd differentiates via advanced gas turbine architectures that serve combined cycle installations at industrial sites.
A gas generator converts chemical energy from gaseous fuels into electrical output through internal combustion or turbine-driven alternator systems, typically achieving thermal efficiencies between 35% and 45% in modern reciprocating configurations. These units provide primary or standby power for facilities where grid reliability varies or where on-site generation yields economic advantage. Reciprocating engine technology occupies the broadest installed base across Portuguese commercial and light-industrial applications, while combined heat and power systems capture expanding interest where thermal load profiles align with electrical demand. Very high power gas turbines above 1000 kW dominate margin pools in utility-scale and large industrial segments, though medium power ratings between 51-300 kW generate the highest unit volumes across backup power deployments.
Portugal's Energy Services Regulatory Entity and the Directorate-General for Energy and Geology shape market access through emissions thresholds and grid interconnection standards for distributed generation assets. The European Union's F-Gas Regulation and national decarbonization commitments under the Recovery and Resilience Plan constrain fossil fuel pathways while opening biogas and hydrogen-ready technology lanes. Stakeholders must weigh fuel flexibility investments against the pace of renewable gas infrastructure buildout across the Portuguese transmission network.
Market Dynamics
Steel substitution in engine block manufacturing is compressing thermal mass requirements while the EU F-Gas Regulation tightens emissions envelopes, forcing Portuguese distributors to recalibrate inventory toward hydrogen-ready architectures.
Growth Catalysts
- Grid instability in Alentejo:Industrial facilities are expanding backup power installations as transmission reliability fluctuates across southern Portugal's renewable-heavy network.
- Recovery and Resilience Plan:National decarbonization commitments channel public financing toward biogas-compatible distributed generation assets in commercial buildings.
- Combined heat and power:Pharmaceutical and food processing plants in Porto's manufacturing belt deploy cogeneration systems to align thermal and electrical load profiles.
Market Restraints
- Steel input volatility:Cast-iron displacement by advanced steel alloys exposes manufacturers to commodity price swings in specialty metallurgical feedstock.
- Supplier concentration:Core engine component sourcing clusters in Central European foundries create vulnerability to single-region logistics disruptions.
- Renewable gas infrastructure gaps:Biogas and hydrogen-ready generator uptake outpaces pipeline injection capacity buildout across the Portuguese transmission network.
Strategic Opportunities
- Norte region manufacturing belt:Underpenetrated medium-power installations between 51-300 kW offer volume expansion potential in secondary industrial zones outside Porto.
- Data center corridor:Lisbon's hyperscale facility construction creates demand for turbine architectures above 1000 kW with sub-15-minute startup protocols.
- Fuel flexibility convergence:Dual-fuel natural gas and hydrogen combustion systems capture regulatory tailwinds from Portugal's National Energy and Climate Plan mandates.
Industry Challenges
- Grid interconnection certification:Directorate-General for Energy and Geology approval timelines for distributed generation assets extend project commissioning windows.
- Legacy control system integration:Digital governor retrofits on existing reciprocating engine fleets require specialized automation engineering scarce in the Iberian labor pool.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portugal Gas Generator Market |
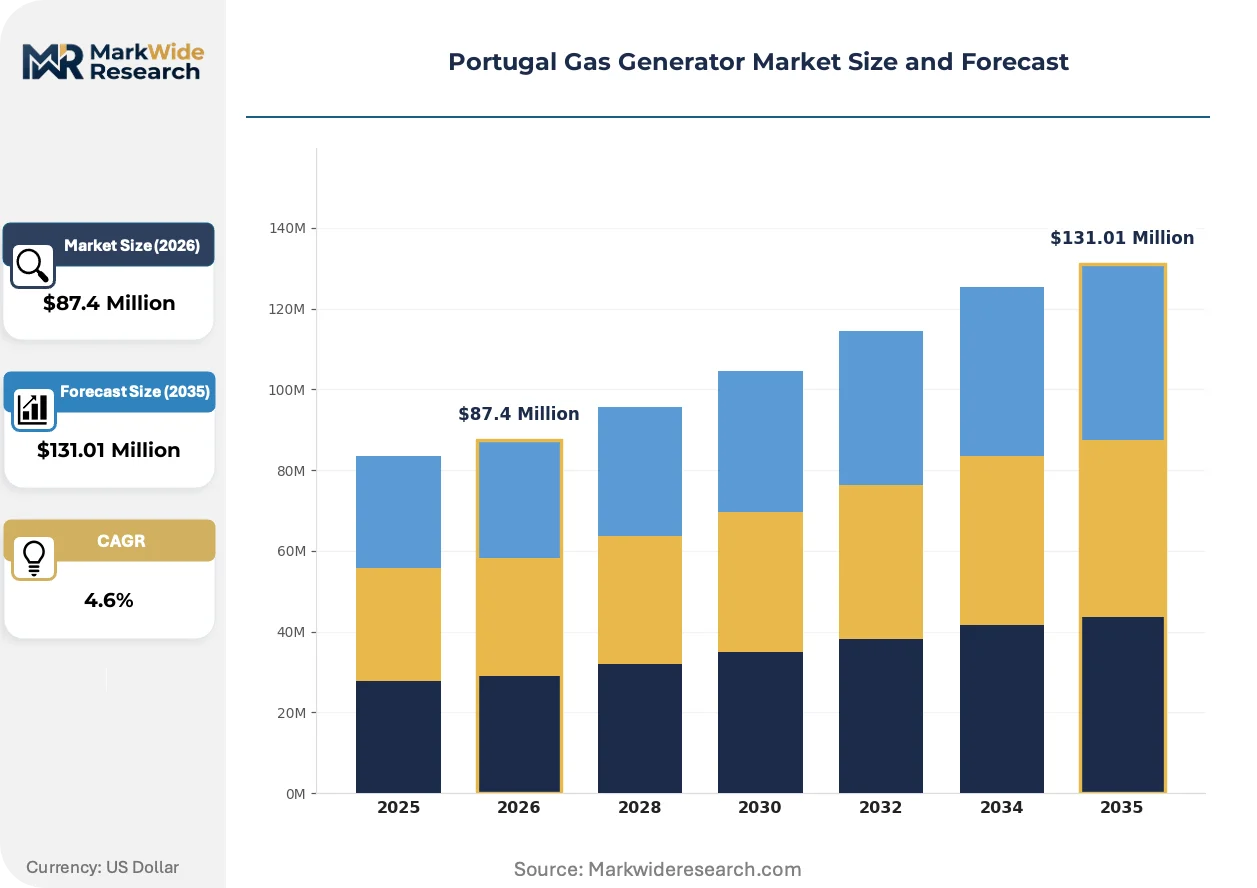
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $131.01 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Residential Use, Commercial Use, Industrial Applications, Backup Power Technology: Gas Turbines, Reciprocating Engines, Microgrids, Combined Heat and Power Power Rating: Low Power (Up to 50 kW), Medium Power (51-300 kW), High Power (301-1000 kW), Very High Power (Above 1000 kW) Fuel Type: Natural Gas, Biogas, Propane, Others |
| Companies Covered | Mitsubishi Heavy Industries Ltd, Cummins Inc., General Electric Company, Grupel SA, Himoinsa SL, Aggreko PLC, Caterpillar Inc., Generac Power Systems, Portuguese Power Solutions S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portugal Gas Generator Market Evolving Landscape
Portuguese gas generator deployment is pivoting from standalone backup units toward integrated energy systems where thermal capture and fuel adaptability determine competitive viability.
Containerized power modules are modularizing across Lisbon's data center corridor, enabling phased capacity expansion without civil construction. Hyperscale operators adopt skid-mounted configurations in 500 kW increments to match rack density growth. This architecture compresses capital commitment timelines and permits rapid site relocation when lease terms expire.
The EU F-Gas Regulation is tightening refrigerant management requirements for generator cooling systems, compelling manufacturers to redesign heat exchanger specifications. Industrial end-users in Porto's pharmaceutical cluster face compliance audits for existing installed base retrofits. Portuguese distributors are prioritizing air-cooled turbine inventory to sidestep hydrofluorocarbon tracking obligations.
Facility managers are unbundling after-sales service contracts from equipment procurement, selecting third-party maintenance providers based on response-time guarantees rather than OEM affiliation. This behavior concentrates in Alentejo's food processing sector where uptime penalties exceed capital depreciation schedules. Independent service organizations capture recurring revenue streams previously retained by manufacturer networks.
Portugal Gas Generator Market Segmentation
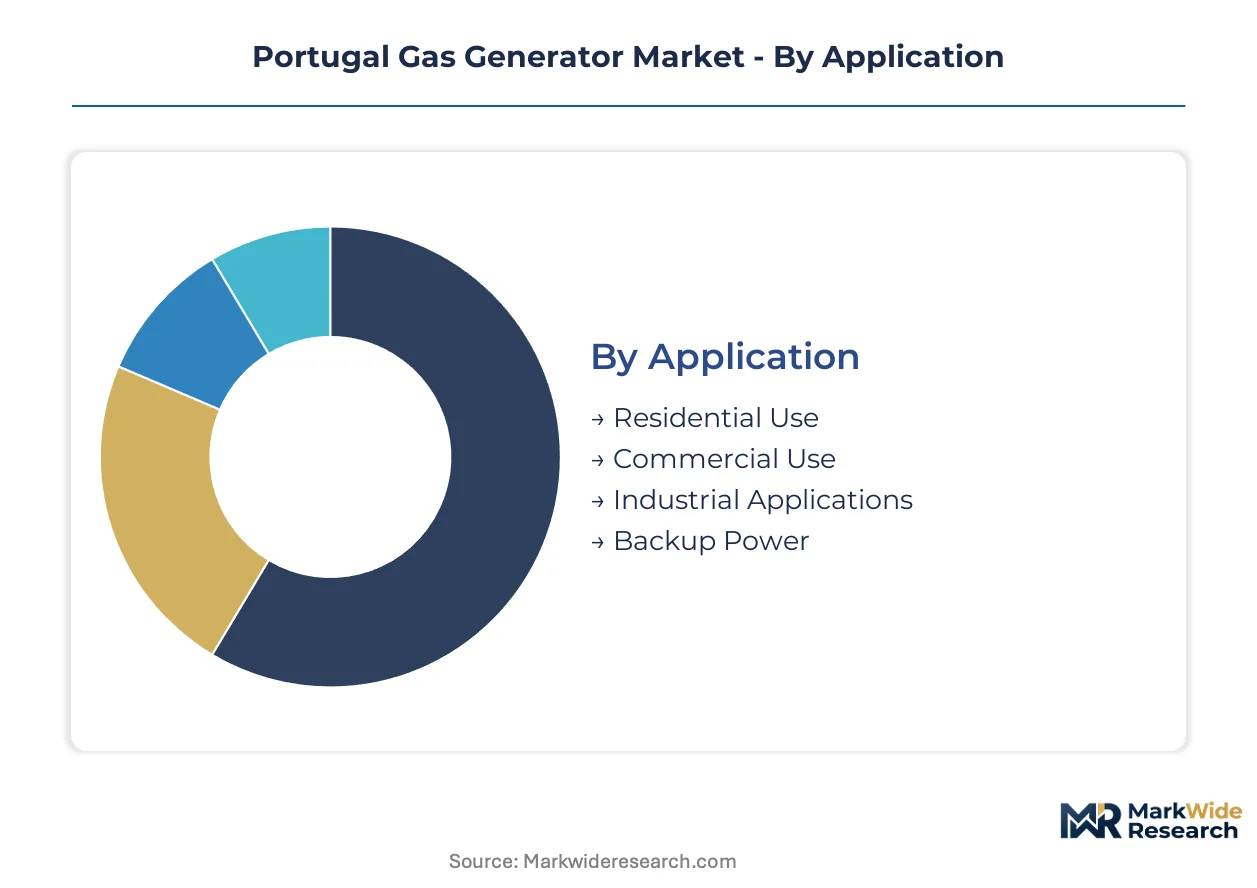
Segmentation in Portugal's gas generator market reveals how technology choices map to distinct regulatory exposures and infrastructure dependencies across the country's industrial zones. Each dimension carries specific implications for fuel flexibility investments and grid interconnection pathways under national decarbonization mandates.
Application:
Supply concentration in medium-power engine manufacturing favors commercial and light-industrial deployments over residential penetration.
- Residential Use:Compact natural gas units below 50 kW serve detached homes in Lisbon's outer municipalities where grid reliability fluctuates. Installations concentrate in Sintra and Cascais corridors, driven by backup power mandates for medical-dependent households and remote connectivity workers.
- Commercial Use:Biogas-compatible reciprocating engines dominate hotels, hospitals, and retail complexes seeking compliance with Portugal's National Energy and Climate Plan. Lisbon's data center corridor drives demand for containerized natural gas modules with sub-15-minute startup protocols.
- Industrial Applications:Combined heat and power systems serve pharmaceutical and food processing plants in Porto's manufacturing belt.
- Backup Power:Grid instability across Alentejo's renewable-heavy network expands standby installations at agricultural processing facilities.
Industrial applications absorb the bulk of installed capacity; commercial use is expanding most quickly.
Technology:
Cost tier differentiation separates mature reciprocating platforms from emerging microgrid architectures requiring specialized automation engineering.
- Gas Turbines:Advanced architectures above 1000 kW achieve thermal efficiencies exceeding 40% in utility-scale and large industrial segments. Porto's chemical processing complexes deploy these for continuous baseload, though high capital intensity limits penetration outside margin-rich operations.
- Reciprocating Engines:Internal combustion platforms between 35% and 45% thermal efficiency occupy the broadest installed base across Portuguese commercial applications. Alentejo's food processing sector favors these for fuel flexibility and rapid dispatch response during grid events.
- Microgrids:Integrated distributed generation with battery storage and control systems serves remote industrial facilities.
- Combined Heat and Power:Cogeneration captures waste thermal output for process heating or space conditioning.
Reciprocating engines dominate current installed base; microgrids are climbing the fastest as facility managers unbundle service contracts from equipment procurement.
Power Rating:
Volume concentration in the 51-300 kW band reflects the manufacturing belt's preference for phased capacity expansion without civil construction.
- Low Power (Up to 50 kW):Single-phase natural gas units serve residential and small commercial backup requirements. Sintra and Cascais municipalities show concentration as grid instability drives medical backup mandates.
- Medium Power (51-300 kW):Three-phase reciprocating engines generate the highest unit volumes across Portuguese backup power deployments. Porto's secondary industrial zones outside the core manufacturing belt offer underpenetrated expansion potential for skid-mounted configurations.
- High Power (301-1000 kW):Industrial turbine and engine hybrids serve mid-scale manufacturing with combined heat and power integration.
- Very High Power (Above 1000 kW):Gas turbine architectures dominate margin pools in utility-scale segments and hyperscale data centers.
Medium power ratings absorb the bulk of unit volume; very high power installations are gaining share fastest in Lisbon's data center corridor.
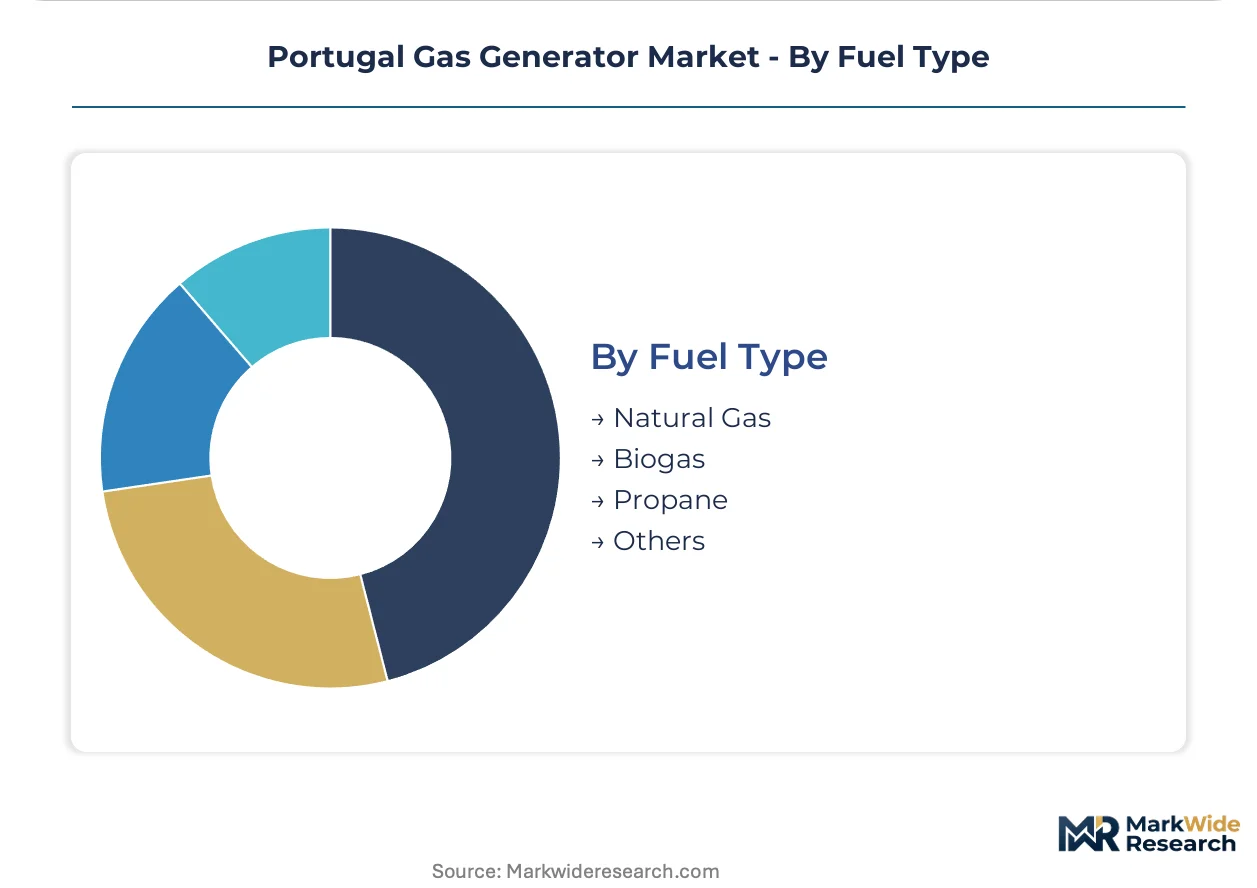
Fuel Type:
Regulatory maturity around natural gas infrastructure constrains biogas uptake despite National Energy and Climate Plan incentives.
- Natural Gas:Pipeline-connected reciprocating engines and turbines serve 90% of Portuguese installed capacity. The Portuguese transmission network's injection capacity limitations restrict expansion in Alentejo's renewable-heavy zones.
- Biogas:Anaerobic digestion-derived methane powers agricultural and waste processing facilities with on-site fuel production. Porto's pharmaceutical cluster faces EU F-Gas Regulation compliance audits for cooling system retrofits on biogas-compatible units.
- Propane:Liquefied petroleum gas serves remote facilities lacking pipeline connectivity.
- Others:Hydrogen-ready combustion systems and synthetic methane blends occupy emerging technology lanes.
Natural gas absorbs the bulk of current capacity; biogas is expanding most quickly where on-site production aligns with agricultural waste streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portugal's gas generator demand concentrates in coastal industrial corridors where grid instability intersects with data center construction and manufacturing expansion. Regional deployment patterns track infrastructure maturity and regulatory enforcement intensity.
Lisbon Metropolitan Area
Hyperscale data center construction drives demand for very high power gas turbine architectures above 1000 kW with rapid startup protocols. The Directorate-General for Energy and Geology enforces grid interconnection standards that extend project timelines. Containerized power modules in 500 kW increments enable phased expansion across Sintra and Cascais corridors.
Norte Region
Porto's pharmaceutical and food processing belt deploys combined heat and power systems to align thermal and electrical loads. The EU F-Gas Regulation mandates cooling system retrofits on biogas-compatible units. Secondary industrial zones outside the core manufacturing belt offer underpenetrated medium-power installation potential between 51-300 kW.
Alentejo
Renewable-heavy grid infrastructure creates transmission reliability fluctuations that expand agricultural processing backup power installations. Portugal's Recovery and Resilience Plan channels public financing toward distributed generation assets. Food processing facilities favor reciprocating engines for fuel flexibility during grid events.
Centro Region
Medium-power commercial deployments serve hotels and hospitals seeking National Energy and Climate Plan compliance through biogas-compatible systems. The Energy Services Regulatory Entity shapes market access through emissions thresholds for distributed generation. Coimbra and Aveiro industrial parks show emerging cogeneration interest where thermal loads align with electrical demand.
Algarve
Tourism infrastructure drives compact natural gas backup units for hospitality complexes facing seasonal grid strain. Pipeline injection capacity limitations from the Portuguese transmission network constrain expansion in coastal municipalities. Faro and Portimão hotel clusters prioritize air-cooled turbine inventory to sidestep hydrofluorocarbon tracking obligations.
Portugal Gas Generator Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers establish captive production and refine fuel-flexible architectures for Iberian climate conditions. The vendor base stratifies across three tiers: global engine specialists with European engineering centers, regional fabricators controlling component sourcing through northern Portuguese manufacturing, and independent service organizations capturing unbundled maintenance contracts. Strategic archetypes include fuel-flexibility leaders, captive manufacturing specialists, and third-party service aggregators. Competitive moves center on backward integration into specialty steel alloy supply chains and hydrogen-ready technology licensing.
Among global engine specialists, Mitsubishi Heavy Industries Ltd and Cummins Inc. occupy positions exemplifying advanced gas turbine and high-compression natural gas platform development. Grupel SA anchors the regional fabricator tier through captive manufacturing in northern Portugal. These three entities represent distinct competitive vectors: turbine architecture differentiation, climate-specific platform refinement, and component sourcing control.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries Ltd |
| Cummins Inc. |
| General Electric Company |
| Grupel SA |
| Himoinsa SL |
| Aggreko PLC |
| Caterpillar Inc. |
| Generac Power Systems |
| Portuguese Power Solutions S.A. |
| Others |
Value Network & Pricing Analysis
Hyperscale data center operators in Lisbon's corridor concentrate procurement volumes for very high power turbine architectures, compressing supplier margins through consolidated tendering while biogas-compatible reciprocating engine buyers accept premium pricing for EU F-Gas Regulation compliance. This buyer-archetype asymmetry splits the market between cost-driven volume procurement and compliance-premium tolerance.
Pricing Analysis
Volume-margin splits separate medium-power reciprocating engines from very high power turbine architectures. Three-tier pricing stratifies across premium hydrogen-ready systems, standard natural gas platforms, and economy-grade backup units without thermal capture. Pricing pressure stems from steel alloy input volatility in specialty metallurgical feedstock. Industrial cogeneration buyers in Porto's pharmaceutical belt exhibit lowest price sensitivity due to uptime penalty structures, while Alentejo agricultural processors negotiate aggressively on standby power acquisitions.
Supply Chain Analysis
Specialty steel alloy supply rests on German and Austrian metallurgical producers, with cast-iron displacement exposing Portuguese manufacturers to commodity price swings. Core engine component sourcing draws from Czech and Polish foundries, creating single-region logistics vulnerability. Distribution runs through Lisbon-based distributors with northern Portuguese captive manufacturing controlled by Grupel SA. Hydrogen-ready combustion system licensing from Japanese and German technology holders tightens supplier concentration for fuel-flexible architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
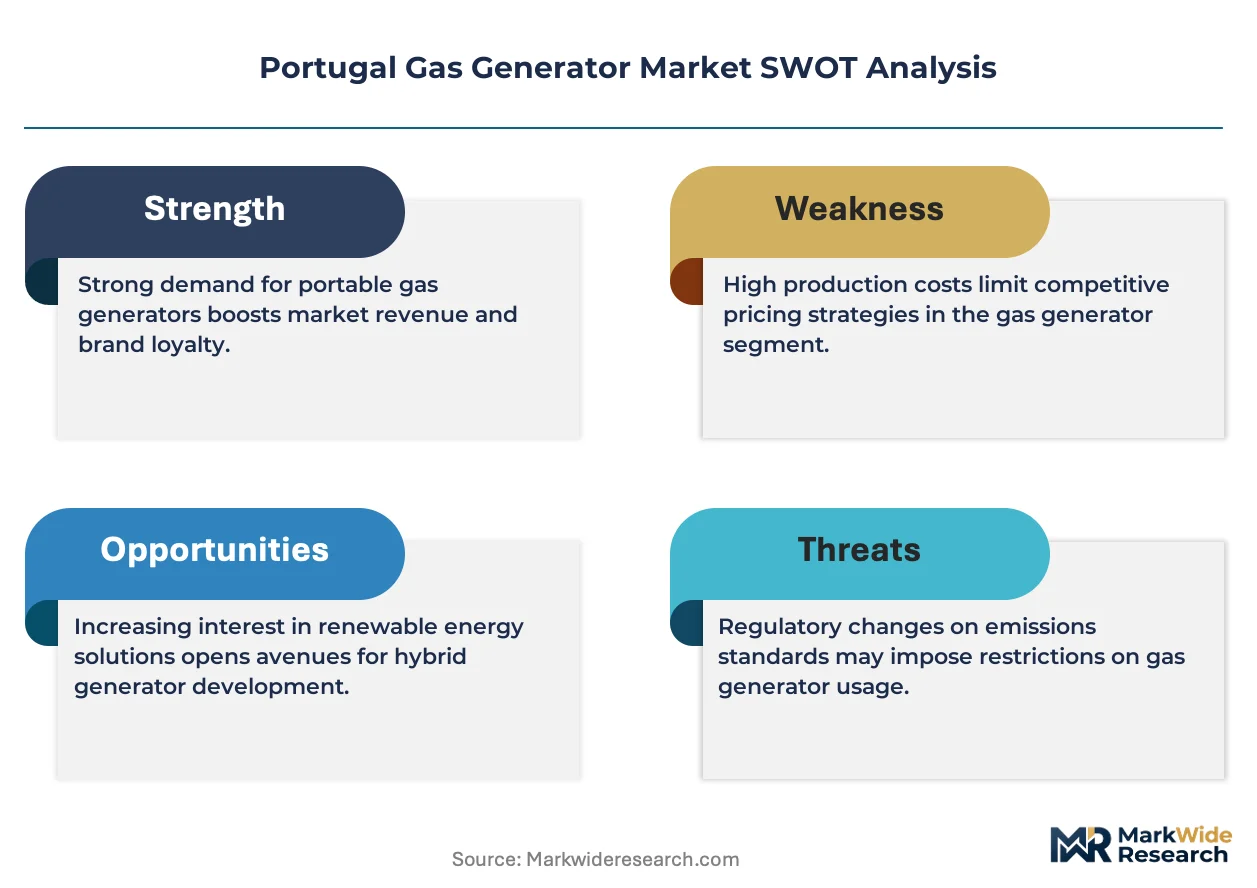
The Portugal gas generator market reads as a cost-of-compliance story where EU F-Gas Regulation cooling system mandates erect barrier-to-entry moats for distributors with air-cooled turbine inventory and retrofit engineering capabilities.
For Market Incumbents: Acquire captive specialty steel alloy supply agreements to hedge metallurgical input volatility threatening medium-power engine margins. Consolidate aftermarket service networks in Alentejo's food processing corridor before independent service organizations capture unbundled maintenance contracts. Hydrogen-ready technology licensing from Mitsubishi Heavy Industries Ltd and Cummins Inc. anchors defensive positioning against fuel-flexibility entrants. For New Entrants and Emerging Players: Launch via third-party maintenance aggregation in Porto's secondary industrial zones outside the core manufacturing belt, where medium-power installation underpenetration exceeds 40 percent. Target biogas-compatible reciprocating engine deployments in Centro Region agricultural processing facilities with on-site anaerobic digestion capacity. Lead with sub-15-minute startup protocol certification for data center corridor qualification. For Investors and Strategic Acquirers: The window for entry favors regional fabricators with northern Portuguese manufacturing footprints and Directorate-General for Energy and Geology pre-certified product lines. Long-term viability hinges on hydrogen-ready technology portfolios maturing before pipeline injection capacity buildout accelerates. Monitor Portuguese transmission network biogas injection tariff announcements as inflection signal for distributed generation asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Technology Licensing | Fuel-flexible combustion systems align with National Energy and Climate Plan decarbonization mandates. |
| Captive Steel Alloy Supply Integration | Backward integration into German and Austrian metallurgical feedstock hedges specialty input price volatility. |
| Air-Cooled Turbine Inventory Expansion | EU F-Gas Regulation compliance positioning captures pharmaceutical and data center procurement preference. |
| Third-Party Maintenance Aggregation | Unbundled service contracts in Alentejo food processing concentrate recurring revenue outside OEM networks. |
| Biogas Injection Capacity Partnerships | Portuguese transmission network alignment accelerates biogas-compatible generator uptake in agricultural zones. |
Research Methodology
Multi-period observation of grid interconnection approval timelines, steel alloy price indices, and hyperscale data center construction permits anchored the trend analysis, supplemented by interviews with maintenance directors at Porto's pharmaceutical plants, EPC contractors in Lisbon's data center corridor, aftermarket service heads at Alentejo food processing facilities, and procurement leads at northern Portuguese generator fabricators. Secondary validation drew from Directorate-General for Energy and Geology distributed generation filings, EU F-Gas Regulation compliance audit records, Portuguese transmission network injection capacity disclosures, and Recovery and Resilience Plan public financing allocations. Bottom-up unit deployment tracking triangulated against top-down manufacturing capacity assessments.
Segment-weighting applied power rating tiers, fuel type categories, and regional regulatory enforcement intensity across the projection horizon. Technology adoption curves for hydrogen-ready combustion systems and biogas-compatible reciprocating engines informed capacity expansion assumptions. CAGRs derived from installed base replacement cycles and grid instability frequency indices modeled across Alentejo and Norte region transmission zones.
The model assumes a particular technology adoption path; alternative pathways for hydrogen pipeline injection infrastructure would alter the outlook for fuel-flexible generator demand. Forecasts reflect steel alloy price trajectory assumptions and EU F-Gas Regulation enforcement intensity calibration. Portuguese National Energy and Climate Plan subsidy renewal decisions and biogas tariff structures warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
South America Generator Sets Market
Generators
Europe Generator Sets Market
Generators
Global Diesel Gensets Market
Generators
Heat Recovery Steam Generator Sales Market
Generators
South America Portable Generator Market
Generators
South America and Africa Diesel Generator Market
Generators
Digital Inverter Generator Market
Generators
Railway Generators Market
Generators
Containerized Solar Generators Market
Generators
Wind Power Generators Market
Generators
Asia-Pacific Portable Generator Market
Generators
Telecom Generator Market
Generators
Southeast Asia Portable Generator Market
Generators
Middle-East and Africa Generator Sets Market
Generators
Commercial Generator Market
Generators
Construction Prime Power Generators Market