
 Tri Fuel Generators Market | 2026-2036
Tri Fuel Generators Market Size, Share, and Industry Trends Forecast 2026-2036
Tri Fuel Generators Market Insights
China is fragmenting tri-fuel generator manufacturing capacity as domestic producers expand assembly lines for export-oriented propane-natural-gas-gasoline units. Cummins Inc. anchors North American engineering standards through its heavy-duty standby platform development. Champion Power Equipment competes aggressively in portable tri-fuel segments via mass retail channel control. Generac Holdings Inc. dominates residential standby installations with integrated smart-load management systems.
Tri-fuel generators are internal combustion engine systems engineered to operate interchangeably on gasoline, propane, and natural gas through carburetor or fuel-injection modifications, typically delivering 3-20 kW for residential units and exceeding 50 kW for commercial installations. These systems serve critical backup power functions where fuel supply redundancy prevents single-point failures during natural disasters or grid instability. Standby generators command the highest margin pools due to permanent installation contracts and maintenance service attach rates, while portable generators sustain volume leadership through emergency preparedness retail cycles. Inverter generators represent the fastest-growing technology segment as electronics-sensitive loads demand harmonic distortion below 3 percent.
EPA certifies tri-fuel generators under Tier 4 Final and CARB emissions frameworks, forcing manufacturers to deploy catalytic aftertreatment and precision fuel mapping that adds cost but unlocks California market access. OSHA workplace safety standards governing construction site temporary power further shape product configuration requirements for ground-fault protection and fuel-line integrity. Stakeholders must monitor evolving state-level building codes that increasingly mandate multi-fuel backup capability in critical infrastructure design standards.
Market Dynamics
EPA Tier 4 Final emissions compliance and state-level carbon mandates are compressing combustion architecture timelines while simultaneously unlocking California market access for certified tri-fuel systems.
Growth Catalysts
- Hurricane-prone infrastructure vulnerability:Emergency services agencies across Texas and Florida are mandating multi-fuel redundancy in critical facility backup specifications.
- CARB certification pathways:California's Air Resources Board frameworks now accommodate tri-fuel configurations with catalytic aftertreatment, creating regulatory precedent for clean combustion.
- Remote oil-field power demand:Permian Basin operators require portable tri-fuel units to circumvent pipeline dependency during extraction operations.
Market Restraints
- Platinum-group metal cost volatility:Catalytic converter substrates depend on palladium and rhodium spot markets that swung forty percent in twenty-four months.
- Carburetor calibration complexity:Precision fuel mapping across three distinct energy densities demands specialized technician labor pools concentrated in Midwest manufacturing corridors.
- Natural gas infrastructure gaps:Rural counties in Appalachia and Mountain West regions lack pipeline connectivity that would enable standby generator fuel switching.
Strategic Opportunities
- Smart-load management convergence:Integration of inverter technology with cellular monitoring creates premium positioning in residential standby segments.
- Texas grid instability premium:ERCOT reliability failures are accelerating homeowner voluntary backup system installations beyond code mandates.
- Propane distribution partnerships:Rural cooperatives in agricultural counties are bundling generator sales with bulk fuel delivery contracts.
Industry Challenges
- Emissions calibration technician scarcity:EPA certification requirements for field service personnel outpace vocational training program output in manufacturing states.
- Legacy electrical panel compatibility:Smart transfer switch integration demands rewiring in pre-2010 residential installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tri Fuel Generators Market |
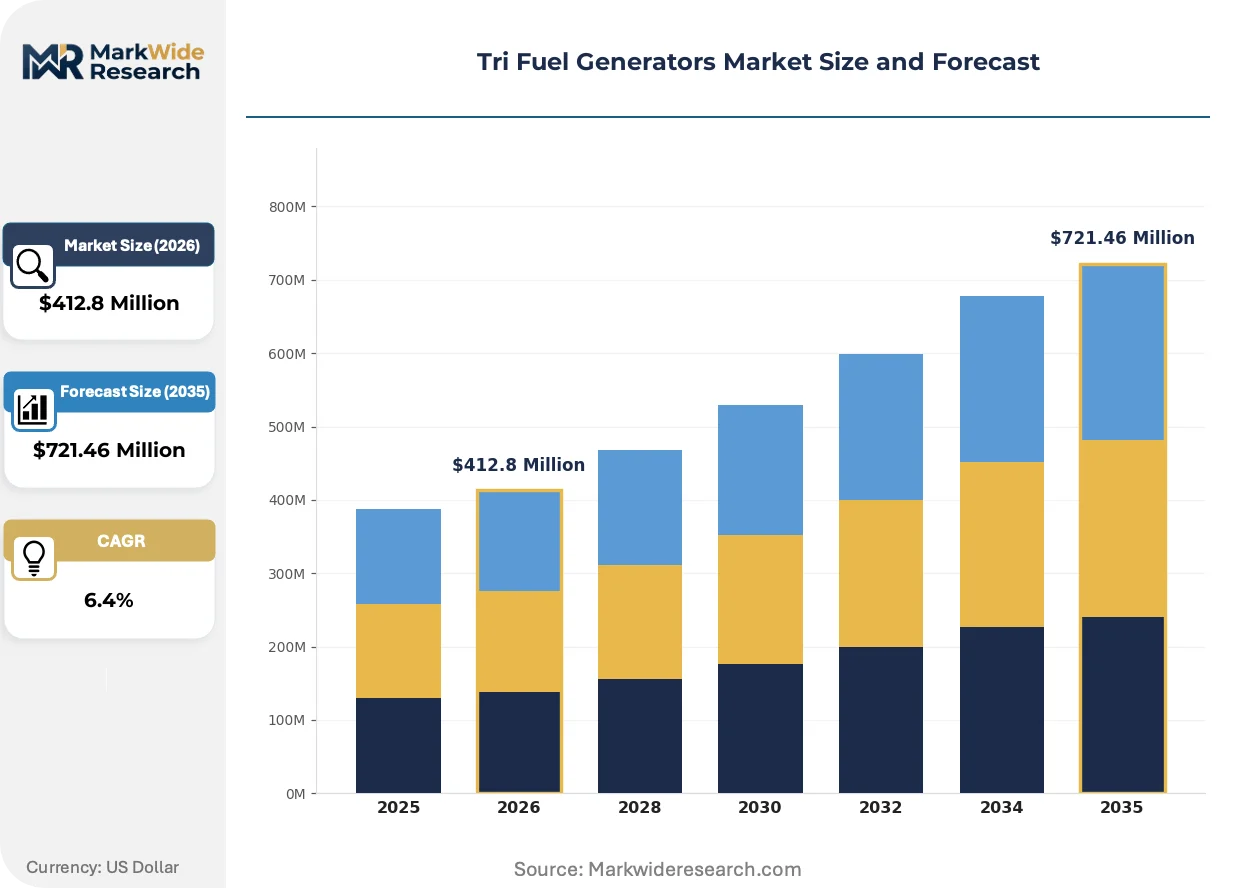
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $721.46 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Generators, Standby Generators, Inverter Generators, Commercial Generators Technology: Gasoline, Natural Gas, Propane, Hybrid End User: Residential, Industrial, Agriculture, Emergency Services Application: Backup Power, Remote Locations, Construction Sites, Events |
| Companies Covered | Generac Holdings Inc., Cummins Inc., Caterpillar Inc., Wärtsilä Corporation, Westinghouse Electric Corporation, DuroMax Power Equipment, Champion Power Equipment, Honda Motor, Genmax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tri Fuel Generators Market Trends and Innovations
Tri-fuel generator architecture is bifurcating between premium inverter-electronics integration and cost-optimized conventional alternator platforms serving distinct buyer risk profiles.
Power electronics is digitizing generator output quality through microprocessor-controlled inverters that maintain total harmonic distortion below three percent. Medical device manufacturers and data center operators are specifying these units for sensitive load protection. The technology is digitizing competitive differentiation between mass-market portable units and premium standby installations.
EPA enforcement of Tier 4 Final standards for non-road engines is eliminating carbureted gasoline-only designs from interstate commerce. Manufacturers must deploy closed-loop fuel injection with oxygen sensor feedback to achieve nitrogen oxide thresholds. California market access now requires CARB executive order certification that adds eighteen-month development timelines for new product introductions.
Buyers are unbundling maintenance contracts from initial equipment procurement as third-party service networks proliferate in deregulated utility territories. Independent electrical contractors in Texas and Florida are capturing recurring revenue streams previously retained by manufacturer-authorized dealers. This pattern concentrates in states with highest grid reliability failure frequency where generator runtime hours justify preventive service scheduling.
Tri Fuel Generators Market Segmentation
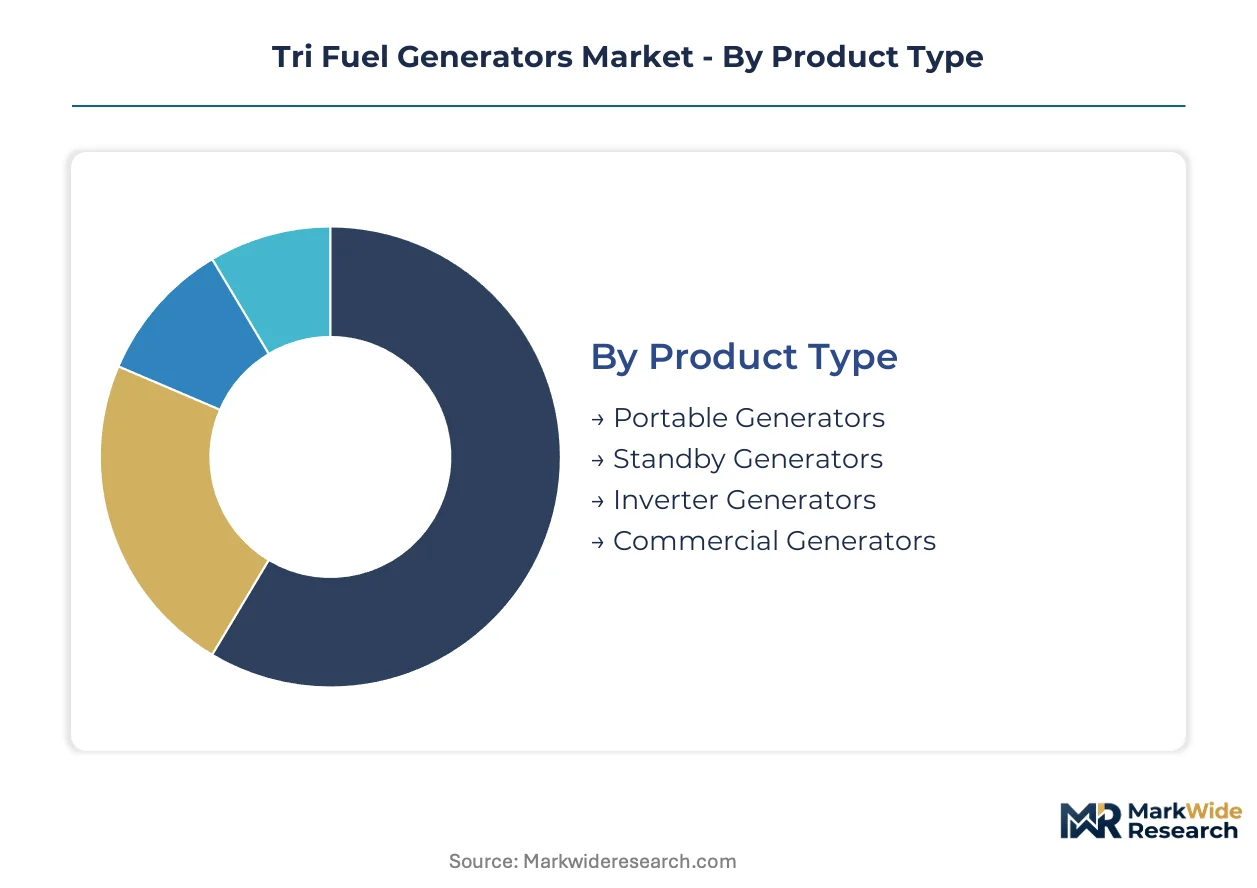
Tri-fuel generator segmentation reveals divergent service economics across installation permanence and runtime duty cycles. After-sales revenue attachment rates vary fourfold between permanently installed standby systems and retail-portable units, reshaping manufacturer channel strategies and margin architecture.
Product Type:
After-sales-service intensity separates permanent-installation contracts from transactional retail sales, with maintenance attach rates driving lifetime value calculations across manufacturer portfolios.
- Standby Generators:Permanently installed automatic-start systems engineered for 20-50 kW residential and commercial loads with integrated transfer switches. Texas homeowner installations surged following ERCOT grid failures, with maintenance contracts capturing fifteen-year service revenue streams that exceed original equipment margins.
- Portable Generators:Mobile 3-10 kW units with manual fuel selection and wheel-kit mobility for emergency deployment. Hurricane-prone Florida counties concentrate procurement through big-box retail channels where seasonal demand spikes compress inventory turns and dilute service attachment.
- Inverter Generators:Microprocessor-controlled output systems maintaining harmonic distortion below 3% for electronics-sensitive loads.
- Commercial Generators:Industrial-grade systems exceeding 50 kW for continuous-duty applications in remote oil-field operations.
By volume, Portable Generators lead. By growth pace, Inverter Generators are expanding most quickly.
Technology:
Cost tier stratification emerges from fuel-system complexity, with dual-injection architectures commanding premium positioning against carbureted legacy platforms.
- Propane:Stored-liquid fuel systems enabling indefinite shelf stability and rural deployment without pipeline dependency. Agricultural cooperatives in Midwest grain counties bundle bulk propane delivery with generator procurement, creating captive fuel-supply relationships that lock in equipment brand selection.
- Natural Gas:Pipeline-tethered systems with lowest per-kilowatt-hour operating cost for urban and suburban standby installations. California CARB certification requirements favor natural-gas-dominant operation for emissions compliance in new construction mandates.
- Gasoline:Ubiquitous fuel availability supporting emergency portability despite storage degradation and higher emissions profiles.
- Hybrid:Battery-buffered systems with generator-sourced recharging for reduced runtime hours and fuel consumption.
By installation base, Natural Gas dominates. By adoption velocity, Hybrid configurations are gaining share fastest.
End User:
Application-driven duty cycles segment customer lifetime value, with industrial runtime hours justifying predictive maintenance investments absent in intermittent residential use.
- Emergency Services:Mission-critical backup specifications mandating multi-fuel redundancy for hospital, fire station, and 911 center continuity. Texas state procurement standards now require tri-fuel capability for critical infrastructure grant eligibility, accelerating municipal fleet replacement.
- Industrial:Continuous-duty manufacturing and processing operations where power interruption triggers catastrophic production losses. Permian Basin oil-field operators specify portable tri-fuel units to circumvent natural gas pipeline dependency during extraction site establishment.
- Residential:Voluntary homeowner installations driven by grid reliability anxiety and insurance premium reductions.
- Agriculture:Seasonal irrigation and livestock operations requiring mobile power without grid connectivity.
By revenue concentration, Industrial leads. By expansion trajectory, Emergency Services shows steepest growth.
Application:
Geography shapes deployment patterns, with coastal vulnerability and infrastructure remoteness concentrating demand in distinct regional clusters.
- Backup Power:Grid-failure protection for residential, commercial, and institutional facilities with automatic or manual transfer switching. Florida building code amendments post-Hurricane Ian accelerated whole-house standby mandates in coastal counties, concentrating contractor installation capacity.
- Remote Locations:Off-grid power for mining, oil-field, and telecommunications infrastructure without utility connectivity. Mountain West telecommunications tower operators specify tri-fuel redundancy to eliminate single-fuel supply chain vulnerabilities at isolated sites.
- Construction Sites:OSHA-regulated temporary power for building trades with ground-fault protection requirements.
- Events:Mobile power for outdoor entertainment and agricultural fairs with noise and emissions restrictions.
By deployment scale, Backup Power leads. By growth momentum, Remote Locations is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tri-fuel generator manufacturing clusters concentrate in China and the United States, with assembly capacity fragmenting across domestic producers and export-oriented facilities serving hurricane-prone and remote-power markets worldwide.
United States
Texas and Florida drive procurement through hurricane vulnerability and ERCOT grid instability, with emergency services agencies mandating multi-fuel redundancy. EPA Tier 4 Final certification requirements shape product development timelines. Houston-Gulf Coast contractors capture installation volume from post-storm rebuilding cycles and oil-field remote power specifications.
China
Domestic producers expand assembly lines for propane-natural-gas-gasoline export units targeting North American and Southeast Asian markets. GB standards and MIIT industrial policy guide combustion efficiency targets. Zhejiang and Guangdong manufacturing corridors host the primary export-oriented generator assembly clusters.
Germany
Industrial standby specifications favor precision-engineered fuel-injection systems for manufacturing continuity. EU Green Deal emissions frameworks and F-Gas Regulation compliance requirements influence clean combustion R&D. Bavaria and Baden-Württemberg industrial zones concentrate engineering talent for premium generator control systems.
India
Agricultural irrigation and rural electrification gaps sustain demand for portable multi-fuel units without pipeline dependency. BIS certification requirements and state-level renewable hybrid mandates shape product configurations. Maharashtra and Gujarat manufacturing hubs assemble cost-optimized units for domestic and African export markets.
Japan
Disaster preparedness culture and seismic grid vulnerability sustain residential standby installations. METI energy security policies encourage fuel-source diversification for critical infrastructure. Kanto and Kansai metropolitan areas concentrate premium inverter generator demand from electronics-sensitive commercial users.
Tri Fuel Generators Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying carburetors, fuel injection modules, and catalytic aftertreatment. Market structure shows moderate consolidation around full-system manufacturers with captive distribution networks. Three archetypes dominate: vertically integrated power equipment conglomerates, portable generator specialists with retail channel control, and industrial engine manufacturers cross-selling into standby applications. Competitive moves center on smart-load management technology licensing and maintenance service network expansion.
Among North American platform integrators, Generac Holdings Inc. and Cummins Inc. exemplify divergent strategic positioning within the standby generator tier. Champion Power Equipment occupies a distinct position in portable segments through mass retail channel penetration. These three anchors illustrate how fuel-system engineering depth, distribution architecture, and service attach-rate economics separate premium permanent-installation contracts from transactional emergency-preparedment sales cycles.
| Leading Market Players |
|---|
| Generac Holdings Inc. |
| Cummins Inc. |
| Caterpillar Inc. |
| Wärtsilä Corporation |
| Westinghouse Electric Corporation |
| DuroMax Power Equipment |
| Champion Power Equipment |
| Honda Motor |
| Genmax |
| Others |
Pricing and Supply Chain Analysis
Platinum-group metal cost volatility determines both pricing tier spreads and supply chain shape across tri-fuel generator manufacturing. Palladium and rhodium spot market swings force tiered cost absorption strategies while catalytic converter sourcing constraints compress margins at the economy end of the spectrum.
Pricing Analysis
EPA Tier 4 Final certification dictates the pricing tier structure across the tri-fuel generator landscape. Three-tier pricing structure across premium, standard, and economy levels separates CARB-certified inverter systems from conventional alternator platforms and uncertified import units. Price differentiation rests on emissions compliance grade and after-sales service bundling rather than raw kW output alone. Pricing pressure stems from catalytic substrate cost pass-through demands, with municipal emergency services procurement showing least price sensitivity due to grant-funded mandates.
Supply Chain Analysis
Export control regimes on precision fuel-injection technology limit component flows from Germany and Japan to Chinese assembly plants. Manufacturing concentrates in China, the United States, and India, with Zhejiang corridor facilities drawing from Midwestern fuel-system engineering and Bavarian control electronics. Raw material dependencies include platinum-group metals for catalytic substrates, copper winding stock for alternators, and precision-machined carburetor castings. Single-source vulnerability concentrates in palladium refining capacity. Distribution runs through manufacturer-authorized dealer networks for standby systems and mass retail channels for portable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-solar hybrid systems threaten substitution for sub-10 kW residential loads, forcing incumbents to defend runtime reliability advantages during extended grid failures.
For Market Incumbents: Insulate service revenue streams by capturing independent contractor networks through proprietary diagnostic tool licensing and exclusive parts distribution. Deepen backward integration into fuel-injection module production to offset platinum-group metal cost pass-through volatility. Champion Power Equipment's retail channel control demonstrates how mass-market positioning defends against emerging Asian portable competitors. For New Entrants and Emerging Players: Mid-market commercial buildings in hurricane-prone Florida counties represent the most penetrable entry point for certified standby systems below Generac's residential dominance. Agricultural cooperatives in Midwest grain counties offer captive fuel-supply bundling opportunities that lock in equipment brand selection. A go-to-market alliance with regional propane distributors bypasses established dealer network barriers. For Investors and Strategic Acquirers: EPA Tier 4 Final enforcement deadlines reshape the acquisition landscape toward CARB-certified product portfolios with eighteen-month development runway completion. Long-term viability favors platform integrators with captive fuel-system engineering rather than pure assembly operations. The signal to watch is state-level building code amendments mandating multi-fuel backup in critical infrastructure design standards.| Strategic Initiative | Industry Significance |
|---|---|
| Smart-Load Management Integration | Cellular monitoring convergence with inverter technology captures premium residential positioning in Texas. |
| Catalytic Aftertreatment Scale-Up | Closed-loop fuel injection with oxygen sensor feedback unlocks California market access under CARB frameworks. |
| Propane Distribution Partnership | Rural cooperative bundling in agricultural counties creates captive fuel-supply relationships that lock brand selection. |
| Maintenance Service Network Expansion | Independent electrical contractor capture in deregulated utility territories secures recurring revenue streams. |
| Remote Oil-Field Specification Development | Permian Basin portable unit certification circumvents natural gas pipeline dependency during extraction site establishment. |
Research Methodology
A standing panel of generator OEM product managers, EPA certification engineers, municipal emergency services procurement officers, and independent electrical contractors provided ongoing calibration throughout the study period. Primary interview data combined with secondary validation from EPA certification databases, CARB executive order filings, ERCOT reliability reports, and FEMA disaster procurement records. Bottom-up unit shipment analysis triangulated against top-down fuel consumption estimates across the projection horizon.
Scenario-bracketing framed the analytical approach across the analysis window, modeling demand trajectories under grid reliability stress cases and emissions regulatory acceleration paths. Segmentation dimensions included product type permanence, fuel system technology, end-user duty cycle intensity, and regional infrastructure vulnerability cluster. CAGRs derived from installation base growth rates and replacement cycle compression in hurricane-prone counties. Forecast inputs incorporated state-level building code amendment timelines and platinum-group metal price elasticity assumptions.
Macroeconomic conditions sit as an overlay; deviation in residential construction starts, agricultural commodity prices, or oil-field capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions regarding EPA enforcement consistency and state-level carbon mandate adoption pace. Material shifts in federal critical infrastructure resilience grant allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Silent Generator Market
Generators
Middle-East and Africa Generator Sets Market
Generators
Asia-Pacific Gas Generator Market
Generators
Industrial Generator Market
Generators
Digital Inverter Generator Market
Generators
Railway Generators Market
Generators
Commercial Generator Market
Generators
Global Diesel Gensets Market
Generators
Turbo Generator Market
Generators
Generator Sales Market
Generators
Europe Portable Generator Market
Generators
Africa Portable Generator Market
Generators
South America and Africa Diesel Generator Market
Generators
Middle East and Africa Gas Generator Market
Generators
Europe Gas Generator Market
Generators
North America Gas Generator Market