
 Hand Crank Power Generator Market | 2026-2036
Hand Crank Power Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Hand Crank Power Generator Market Foresight
Buyer concentration across emergency services and outdoor retail channels is restructuring procurement patterns for hand crank power generators. Goal Zero leverages its established solar-hybrid ecosystem to anchor premium positioning in recreational channels. K-TOR competes through extreme portability, specializing in pocket-sized units for ultralight backpackers. Freeplay Energy sustains its humanitarian focus, dominating institutional and NGO supply chains with ruggedized designs.
A hand crank power generator converts mechanical rotation into electrical output through electromagnetic induction, typically producing 5-20 watts via permanent magnet alternators with gear ratios optimized for human cadence. The device serves as an autonomous power source when fuel availability, battery depletion, or grid failure eliminates conventional alternatives. Portable generators occupy the largest volume tier, though hybrid systems integrating solar panels and hand cranking command the strongest margin pools. Emergency backup applications lead absolute demand, while educational demonstrations represent the fastest-expanding segment as STEM curricula emphasize kinetic energy conversion.
The Consumer Product Safety Commission governs electrical safety standards for consumer-grade units, while FCC certification applies to models incorporating radio or USB charging functions. ISO 8528-12 addresses small generator performance benchmarks, and California's Title 20 energy efficiency regulations constrain standby power draw in battery-integrated models. Stakeholders must monitor evolving disaster preparedness grant programs and outdoor recreation infrastructure investments to anticipate demand inflections.
Market Dynamics
FEMA procurement guidelines mandating human-powered backup systems for disaster response kits are restructuring vendor qualification criteria and channel access across the hand crank power generator market. This institutional demand pull is compressing sales cycles for certified suppliers while marginalizing uncertified competitors.
Growth Catalysts
- Emergency Preparedness Mandates:Federal Emergency Management Agency kit specifications require hand crank units for off-grid redundancy, institutionalizing demand through disaster response procurement channels.
- Neodymium Magnet Supply:Permanent magnet alternator efficiency gains from rare-earth magnet sourcing are improving watt-per-kilogram output ratios for portable designs.
- Outdoor Recreation Infrastructure:United States federal trail maintenance and backcountry shelter investments are expanding addressable points of sale through park service retail partnerships.
Market Restraints
- Copper Winding Cost Volatility:Electromagnetic coil production depends on copper price fluctuations, compressing margin stability for alternator manufacturers without forward contracts.
- Lithium-Ion Substitution Threat:Lightweight battery banks with solar recharging are displacing mechanical generation for casual recreational users prioritizing silent operation.
- California Title 20 Compliance:Standby power draw restrictions on battery-integrated models force design compromises that increase unit cost and complexity.
Strategic Opportunities
- STEM Curriculum Integration:Kinetic energy conversion demonstrations represent an underpenetrated channel where educational distributors seek ruggedized classroom-durable units.
- Solar-Hand Crank Hybrid Convergence:Dual-input systems combining photovoltaic and mechanical generation command premium positioning in recreational markets.
- NGO Institutional Procurement:Humanitarian supply chains prioritize ISO 8528-12 certified units for field deployment, creating volume contracts outside commercial retail.
Industry Challenges
- FCC Certification Timelines:USB charging and radio-integrated models face extended electromagnetic compatibility testing periods that delay product launches.
- Gear Train Precision Manufacturing:Cadence-optimized gear ratios require specialized machining capabilities scarce among contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand Crank Power Generator Market |
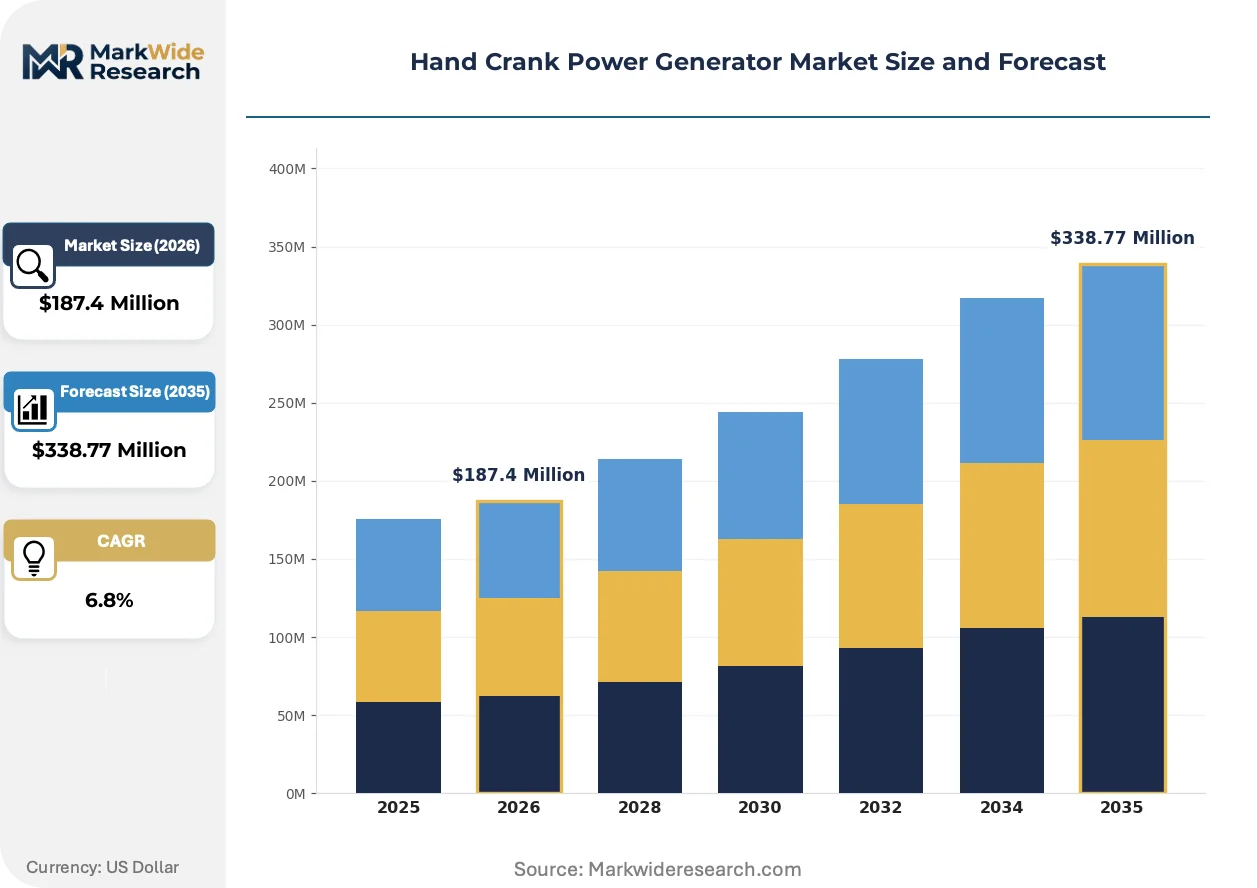
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Generators, Standalone Units, Hybrid Systems, Compact Models End User: Outdoor Enthusiasts, Emergency Services, Educational Institutions, Homeowners Application: Camping, Emergency Backup, Educational Demonstrations, Off-Grid Living Deployment: Manual Operation, Handheld Devices, Designed for Field Use, Fixed Installations |
| Companies Covered | Goal Zero, K-TOR, Eton Corporation, OWI Inc, Electric Pedals, Lion Energy, Freeplay Energy, SunJack, Powertraveller, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand Crank Power Generator Market Shifts & Advancements
Permanent magnet alternator technology is consolidating market structure around suppliers with captive magnet sourcing and precision winding capabilities. This technical shift favors integrated manufacturers over assembly-only operations.
Neodymium-iron-boron magnet arrays are consolidating efficiency benchmarks for hand crank generators by enabling higher flux density in compact alternator geometries. Search-and-rescue equipment purchasers are specifying these configurations for cold-weather reliability where battery performance degrades. The technology is consolidating procurement qualification standards around magnet traceability and temperature coefficient specifications.
California's Title 20 energy efficiency regulations are forcing redesign of battery-integrated hand crank units to minimize standby power consumption. Manufacturers must now implement load-sensing circuits that disconnect charging rails when no device is detected. Consumer-grade product lines face the steepest compliance costs, pushing some suppliers toward pure mechanical-output designs that fall outside the regulation's scope.
Consolidated buying by emergency services agencies is compressing vendor diversity in institutional channels. State-level disaster preparedness grant programs are standardizing on FEMA-compliant kit configurations, reducing specification variation. This concentration is most visible in United States municipal procurement, where multi-year framework agreements lock out smaller suppliers lacking certification documentation.
Hand Crank Power Generator Market Segmentation
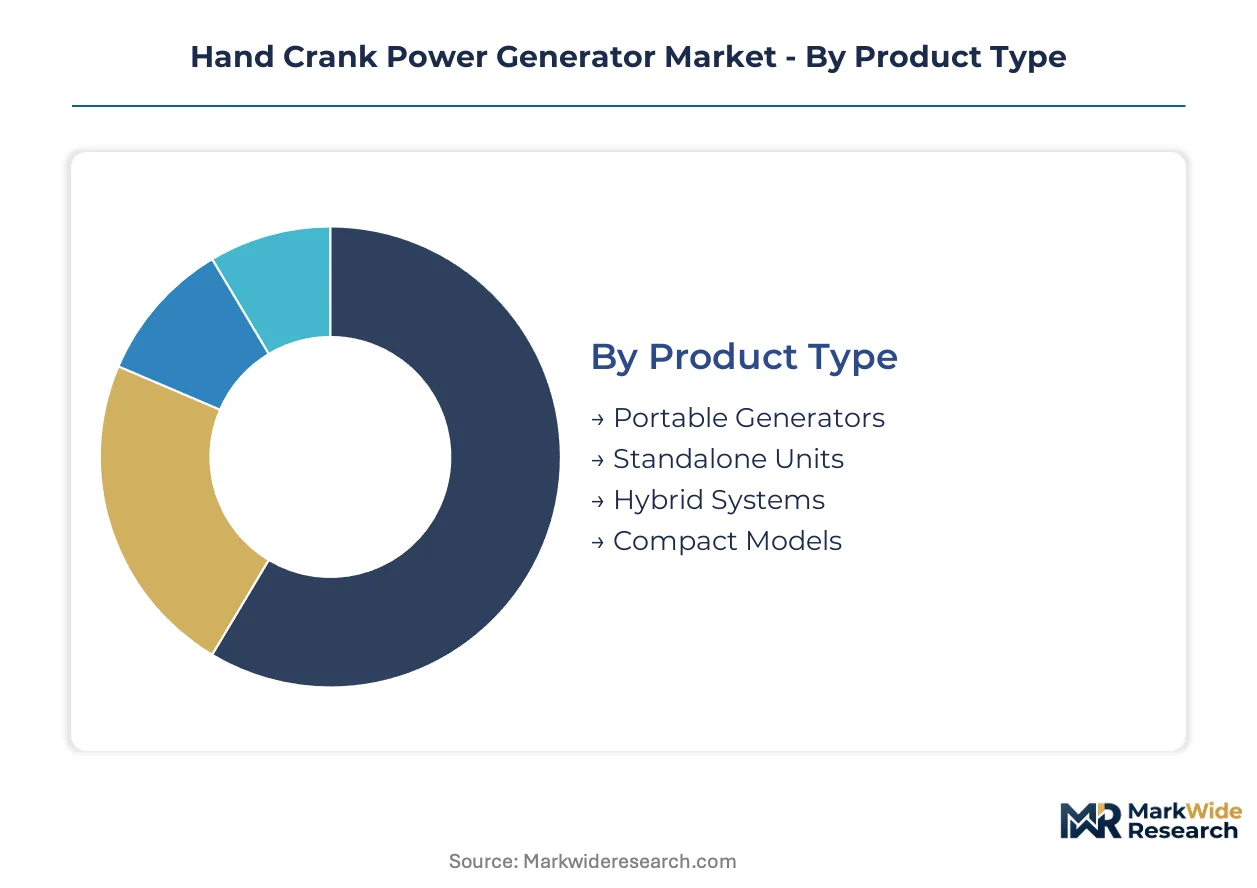
Hand crank power generator procurement patterns diverge sharply across product configurations and use cases, with certification requirements from FCC, CPSC, and ISO 8528-12 determining channel access and margin structures. Segmentation reveals where design trade-offs between portability, durability, and power output concentrate commercial value.
Product Type:
FCC certification applies to units with USB charging or radio integration, while CPSC electrical safety standards govern all consumer-grade products. ISO 8528-12 performance benchmarks dominate institutional procurement, particularly for emergency services deployment.
- Portable Generators:These units balance wattage output with transportability, typically housing permanent magnet alternators in weather-resistant enclosures. Demand concentrates among outdoor enthusiasts in the United States, where federal trail infrastructure investments expand retail access through park service partnerships. Copper winding specifications and neodymium magnet arrays determine competitive positioning.
- Hybrid Systems:Dual-input configurations combining photovoltaic panels with hand crank mechanisms command premium positioning in recreational channels. California Title 20 standby power restrictions force load-sensing circuit designs that increase unit cost. Solar-hand crank convergence represents the steepest expansion trajectory as consumers seek redundant off-grid power.
- Standalone Units:Pure mechanical-output designs bypass battery-integrated regulations, appealing to price-sensitive institutional buyers.
- Compact Models:Pocket-sized units prioritize ultralight specifications for backpacking applications.
Leading the category by volume: Portable Generators. Growing fastest: Hybrid Systems.
End User:
Customer type determines specification rigor, with emergency services demanding traceable magnet sourcing and temperature coefficient documentation that casual recreational users ignore.
- Emergency Services:FEMA kit specifications mandate human-powered backup systems, institutionalizing demand through disaster response procurement channels. Search-and-rescue equipment purchasers specify neodymium-iron-boron configurations for cold-weather reliability where battery performance degrades. Multi-year framework agreements compress vendor diversity.
- Outdoor Enthusiasts:Recreational buyers prioritize silent operation and weight reduction, creating substitution pressure from lithium-ion battery banks with solar recharging. Goal Zero's solar-hybrid ecosystem anchors premium positioning in this channel.
- Educational Institutions:STEM curriculum integration drives demand for classroom-durable units with visible kinetic energy conversion mechanisms.
- Homeowners:Disaster preparedness culture in the United States supports steady procurement of entry-level models for residential emergency kits.
Dominating procurement volume: Emergency Services. Expanding most quickly: Educational Institutions.
Application:
Use case intensity dictates gear train precision requirements, with continuous field deployment demanding specialized machining capabilities scarce among contract manufacturers.
- Emergency Backup:Off-grid redundancy applications lead absolute demand, driven by FEMA procurement guidelines and state-level disaster preparedness grant programs. Institutional buyers prioritize ISO 8528-12 certified units with documented alternator efficiency benchmarks. Ruggedized designs from humanitarian suppliers dominate NGO supply chains.
- Camping:Recreational overnight use favors lighter units with simplified gear ratios optimized for intermittent operation.
- Educational Demonstrations:Kinetic energy conversion visibility requirements favor transparent housings and measurable electrical output displays for classroom settings.
- Off-Grid Living:Permanent installation applications seek higher wattage outputs with fixed mounting hardware and weatherproofing.
Commanding largest revenue pool: Emergency Backup. Gaining share fastest: Educational Demonstrations.
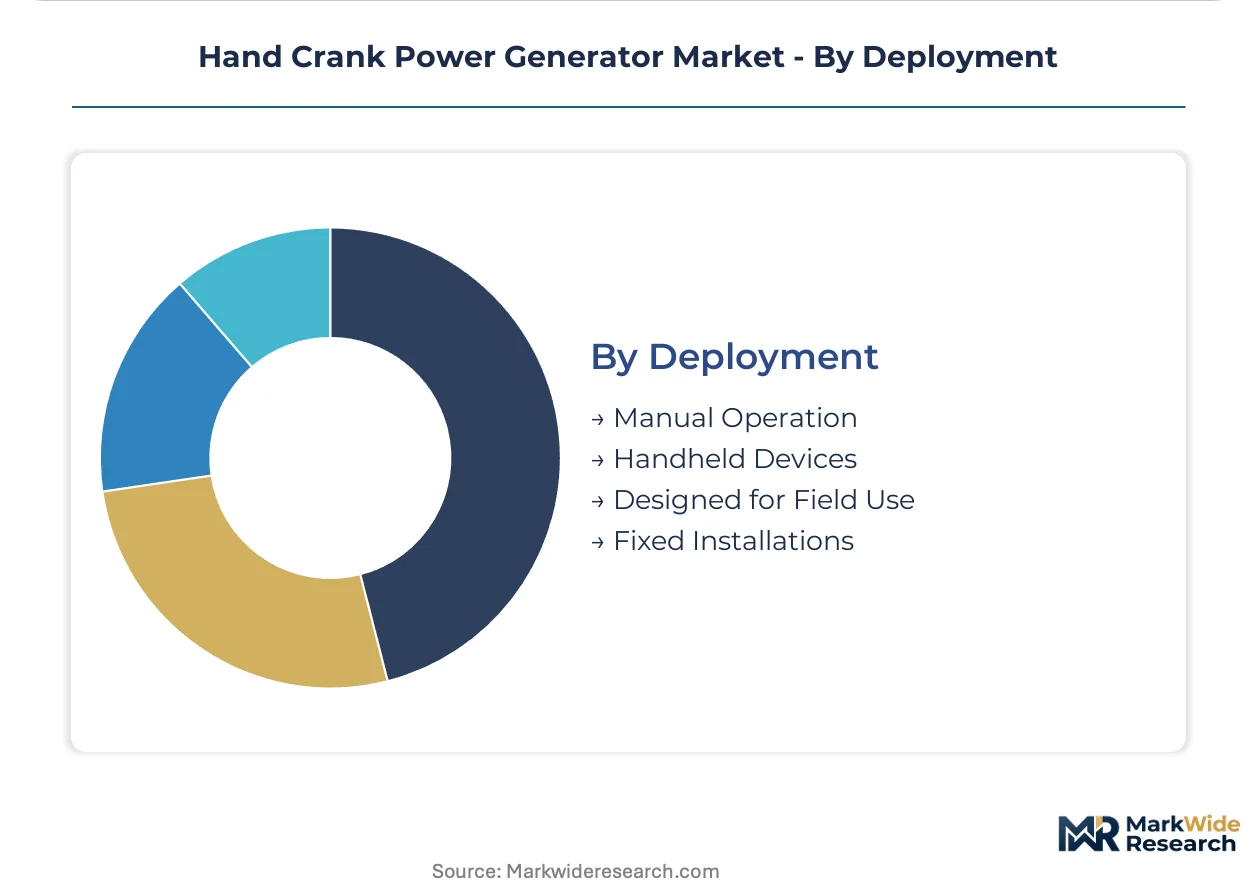
Deployment:
Physical interaction mode determines ergonomic design constraints and cadence optimization for sustainable human power input.
- Manual Operation:Traditional crank mechanisms with gear ratios tuned to average human cadence dominate production volume. Precision winding capabilities and captive magnet sourcing favor integrated manufacturers over assembly-only operations.
- Handheld Devices:Single-hand operation requires compact alternator geometries with reduced flux density.
- Designed for Field Use:Military and expedition specifications demand impact resistance and sub-zero operational reliability.
- Fixed Installations:Shelter-mounted units at backcountry facilities leverage mechanical advantage from larger crank diameters.
Highest shipment volumes: Manual Operation. Steepest growth curve: Designed for Field Use.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neodymium magnet mining in China's Inner Mongolia and rare-earth processing clusters in Jiangxi Province anchor upstream material flows for permanent magnet alternator production. These feedstock localities concentrate magnet sourcing for portable generator manufacturers across North America and Europe.
United States
FEMA procurement guidelines and state-level disaster preparedness grant programs drive institutional demand through municipal emergency response channels. The Consumer Product Safety Commission governs electrical safety standards for consumer-grade units entering retail distribution. Manufacturing concentrates in the Mountain West region, where outdoor recreation equipment suppliers integrate hand crank assemblies into broader off-grid power portfolios.
Germany
Industrial automation demand from Mittelstand engineering firms supports precision gear train component sourcing for European generator assemblers. REACH regulations govern chemical substance restrictions in electrical equipment coatings and housing materials. Production clusters in Baden-Württemberg host specialized machining contractors supplying cadence-optimized gear ratios to portable power equipment manufacturers.
Japan
METI energy security initiatives promote human-powered backup systems for critical infrastructure resilience planning. JIS standards establish performance benchmarks for small generator electromagnetic compatibility and mechanical durability. Industrial concentration in the Chubu region around Nagoya leverages automotive supplier networks for precision alternator winding capabilities.
India
Rural electrification gaps and disaster response capacity building by the National Disaster Management Authority sustain procurement from institutional buyers. BIS certification requirements for electrical equipment constrain import channels for uncertified suppliers. Manufacturing activity clusters in Gujarat, where contract electronics assemblers serve export markets for portable power devices.
United Kingdom
Search-and-rescue charitable organizations and mountain rescue services specify cold-weather reliable power equipment for volunteer deployment kits. CE marking requirements align with EU market access standards for electromagnetic compatibility and electrical safety. Distribution concentrates through outdoor retail partnerships in the Lake District and Scottish Highlands recreation corridors.
Hand Crank Power Generator Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue solar-hybrid convergence and educational channel specialization. The vendor base stratifies across integrated manufacturers with captive magnet sourcing and assembly-only operations dependent on contract winding suppliers. Three archetypes dominate: solar-hybrid ecosystem anchors, ultralight portability specialists, and humanitarian supply chain incumbents. Competitive positioning hardens through FCC certification documentation and ISO 8528-12 performance benchmarking rather than price competition alone.
Within the solar-hybrid tier, Goal Zero exemplifies ecosystem-based positioning that bundles hand crank units with photovoltaic panels and battery storage. K-TOR represents the ultralight specialization archetype, occupying a fabrication position centered on pocket-sized mechanical designs for weight-constrained users. Freeplay Energy anchors the institutional procurement channel, sitting within humanitarian supply chains that prioritize ruggedized field deployment specifications over retail consumer features.
| Leading Market Players |
|---|
| Goal Zero |
| K-TOR |
| Eton Corporation |
| OWI Inc |
| Electric Pedals |
| Lion Energy |
| Freeplay Energy |
| SunJack |
| Powertraveller |
| Others |
Supply & Pricing Matrix
Emergency services procurement concentration across United States municipal agencies anchors a contract-based pricing structure where multi-year framework agreements lock in volume tiers and certification premiums. This buyer archetype consolidation compresses price negotiation cycles for FEMA-compliant suppliers while marginalizing uncertified competitors through specification barriers.
Pricing Analysis
Portable generators ship at volume-dominant price points while hybrid solar-hand crank systems capture margin premiums through dual-input redundancy. Pricing stratifies across premium, standard, and economy tiers based on ISO 8528-12 certification grade and neodymium magnet traceability documentation. Cost compression in consumer-grade lines is intensifying because California Title 20 compliance forces load-sensing circuit redesigns. Educational institutions exhibit highest price sensitivity due to constrained procurement budgets, whereas search-and-rescue agencies prioritize cold-weather reliability over unit cost.
Supply Chain Analysis
Neodymium magnet supply rests on mining operations in China's Inner Mongolia and processing clusters in Jiangxi Province, with precision gear train fabrication concentrated in Germany's Baden-Württemberg region and Japan's Chubu industrial corridor. Permanent magnet alternator production draws from copper winding suppliers facing commodity price volatility, rare-earth magnet arrays requiring temperature coefficient documentation, and specialized machining contractors for cadence-optimized gear ratios. Single-source vulnerability in Chinese rare-earth processing creates tariff exposure for North American assemblers lacking alternative magnet sourcing. Distribution runs through outdoor retail partnerships, institutional procurement channels, and educational equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from FEMA certification requirements and FCC electromagnetic compatibility testing timelines is forcing weaker assembly-only operations toward exit or acquisition, favoring integrated manufacturers with captive magnet sourcing and precision winding capabilities.
For Market Incumbents: Lock in multi-year municipal framework agreements before state-level disaster preparedness grant programs standardize on consolidated vendor lists. Deepen upstream control over neodymium magnet traceability documentation to defend against rare-earth supply disruption. Invest in ISO 8528-12 performance benchmarking infrastructure to maintain institutional channel access against emerging solar-hybrid competitors. For New Entrants and Emerging Players: Begin with STEM curriculum integration channels where educational distributors seek classroom-durable units with visible kinetic energy conversion mechanisms, the most penetrable segment lacking established supplier relationships. Target ultralight backpacking applications through pocket-sized mechanical designs that bypass battery-integrated regulatory complexity. Pursue direct-to-educator digital marketing to circumvent incumbent outdoor retail shelf dominance. For Investors and Strategic Acquirers: The window for entry favors integrated manufacturers with captive magnet sourcing and precision alternator winding capabilities over assembly-dependent operations. Acquisition targets should demonstrate documented neodymium-iron-boron temperature coefficient specifications and existing FEMA kit supplier status. Watch state-level disaster preparedness grant program standardization as the inflection signal for institutional procurement consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Sourcing | Captive neodymium supply from Inner Mongolia mining operations insulates against Chinese export restriction volatility. |
| ISO 8528-12 Certification Investment | Performance benchmarking documentation unlocks multi-year NGO and emergency services framework agreements. |
| Solar-Hand Crank Hybrid Product Launch | Dual-input redundancy commands premium positioning in United States recreational channels through Goal Zero ecosystem competition. |
| STEM Curriculum Channel Partnership | Educational distributor relationships create volume contracts outside saturated outdoor retail shelf space. |
| Precision Gear Train Manufacturing Scale-Up | In-house cadence-optimized machining capabilities reduce dependency on scarce Baden-Württemberg contract manufacturers. |
Research Methodology
Trade association filings, customs and import-export records, and SEC 10-K disclosures from publicly traded outdoor equipment manufacturers formed the secondary backbone for market sizing validation. Primary interviews with FEMA procurement officers, outdoor retail category buyers, precision gear train machining contractors, and neodymium magnet distributors combined with secondary source triangulation through bottom-up unit shipment analysis and top-down spending pattern reconciliation.
Historical trendline analysis across permanent magnet alternator efficiency improvements, copper price volatility patterns, and disaster preparedness grant program disbursement trajectories informed the analytical framework. Segmentation modeling incorporated product configuration, end-user archetype, application intensity, and deployment mode dimensions throughout the forecast period. CAGRs derived from unit volume projections weighted by average selling price evolution across certification tiers, with specific inputs from rare-earth magnet supply constraint scenarios and California Title 20 compliance cost pass-through assumptions.
Underlying measurement precision varies by segment; emergency services procurement data carries tighter precision than educational institution spending estimates due to consolidated reporting requirements. Forecasts reflect documented assumptions about neodymium supply chain stability, FEMA kit specification continuity, and lithium-ion battery substitution rates in recreational applications. A small set of triggers—rare-earth export restriction announcements, state-level grant program standardization timelines, and copper futures volatility spikes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Generator [Up to 100 Kva] Market
Generators
Middle-East and Africa Generator Sets Market
Generators
North America Portable Generators Market
Generators
Boiler Turbine and Generator BTG Sales Market
Generators
Construction Prime Power Generators Market
Generators
Europe Portable Generator Market
Generators
Heat Recovery System Generator Market
Generators
Global Diesel Gensets Market
Generators
South America Gas Generator Market
Generators
Industrial Generator Sets Market
Generators
South America Diesel Generator Market
Generators
East Africa Diesel Generator Market
Generators
South Africa Diesel Generator Market
Generators
Digital Inverter Generator Market
Generators
South America Generator Sets Market
Generators
Gasoline Generator Market