
 Railway Generators Market | 2026-2036
Railway Generators Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Generators Market Analytics
A shortage of certified traction-power engineers is redrawing competitive dynamics across the railway generators landscape. Cummins Inc. leverages its diesel-electric integration expertise to anchor North American freight locomotive retrofits. Siemens AG sustains technology leadership through in-house power electronics design for European high-speed corridors. Bharat Heavy Electricals Limited dominates domestic tendering for Indian Railways auxiliary power plants.
Railway generators are electromechanical devices that convert mechanical energy into electrical power for traction, auxiliary, and station supply functions, typically operating at 400V to 25kV depending on rail system architecture. Diesel generators remain the installed base majority but face structural margin compression as hybrid architectures capture new-build preference. The 1-5 MW power rating band leads volume shipments for mainline operations, while above-10 MW units command premium pricing for heavy-haul freight corridors. Urban transit applications are outpacing freight transport in generator refresh cycles as metro operators prioritize redundancy for platform safety systems.
EPA Tier 4 compliance timelines and EU Stage V non-road engine standards are elevating product development costs for conventional diesel architectures. India's CEA grid-connectivity mandates and BIS emission norms for captive power are reshaping procurement specifications for rail operators. China's MIIT dual carbon goals are accelerating MIIT-certified hybrid generator trials on Beijing-Shanghai trunk lines. Stakeholders must monitor how battery-buffered generator sets perform in extended cold-weather duty cycles before committing fleet-wide replacement schedules.
Market Dynamics
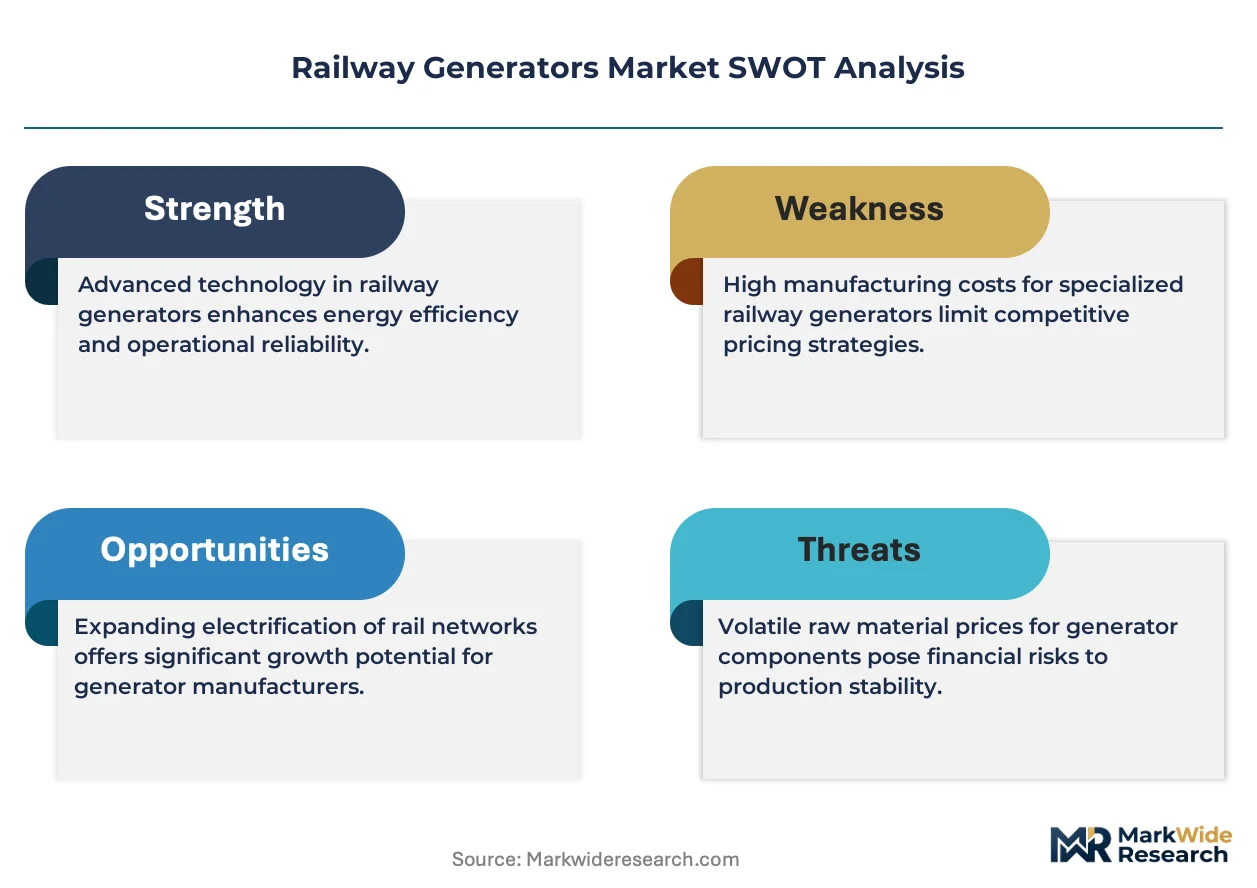
Hybrid generator architectures are compressing margins for conventional diesel suppliers while creating tiered entry barriers based on power electronics integration depth and battery-buffer certification.
Growth Catalysts
- Indian Electrification Mandates:Indian Railways' push for 100% mainline electrification by 2024 is accelerating procurement of high-capacity auxiliary power units for non-electrified branch lines and backup applications.
- EU Stage V Standards:The European Union's Stage V non-road engine emission regulations are forcing diesel generator redesigns toward hybrid-electric systems with integrated after-treatment.
- Urban Metro Expansion:Vietnam, Indonesia, and the Philippines are deploying redundant generator infrastructure for platform safety systems in new rapid transit corridors.
Market Restraints
- Platinum Group Metal Costs:Diesel exhaust after-treatment systems require palladium and rhodium catalysts, exposing manufacturers to volatile precious metal commodity markets.
- Certified Engineer Scarcity:A shortage of traction-power engineers in North America and Europe is extending commissioning timelines and inflating labor costs for complex hybrid installations.
- Lithium Supply Concentration:Battery-buffered generator sets depend on lithium-ion cells where raw material processing concentrates in a limited number of jurisdictions.
Strategic Opportunities
- Cold-Climate Hybrid Validation:Extended winter duty-cycle testing in Scandinavia and Canada offers first-mover advantage for suppliers proving battery reliability below -25°C.
- Stationary Rail Microgrids:China's MIIT-certified trials on Beijing-Shanghai trunk lines demonstrate revenue potential for grid-connected generator sets providing ancillary services.
- Freight Locomotive Retrofit:North American Class I railroads face EPA Tier 4 compliance deadlines for aging diesel fleets, creating replacement demand for modular hybrid power packs.
Industry Challenges
- Power Electronics Integration Complexity:Combining diesel prime movers with battery management systems and inverters requires cross-functional expertise spanning mechanical and electrical engineering disciplines.
- Dual Certification Timelines:Products must simultaneously satisfy EPA Tier 4, EU Stage V, and national rail safety standards, extending time-to-market by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Generators Market |
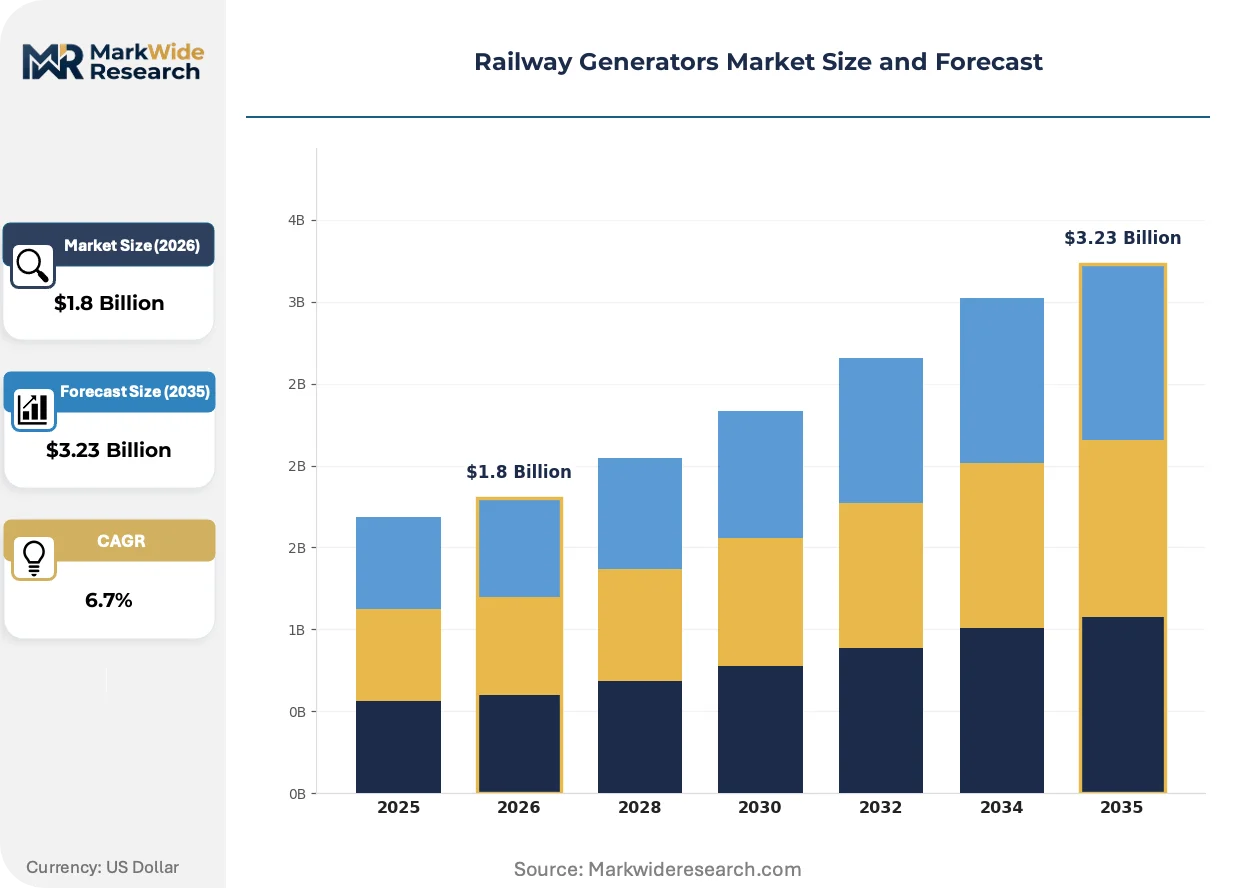
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel Generators, Gas Turbine Generators, Electric Generators, Hybrid Generators Power Rating: Less than 1 MW, 1-5 MW, 5-10 MW, Above 10 MW Application: Mainline Operations, Urban Transit, Freight Transport, Switchyard Supply End User: Rail Operators, Maintenance Service Providers, Manufacturers, Government Agencies |
| Companies Covered | Siemens AG, General Electric, Cummins Inc., Bharat Heavy Electricals Limited, Jenoptik, Nidec Generator Corporation, Ingeteam Traction Systems, VEM Group, Kirloskar Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Generators Market Evolving Landscape
Power semiconductor advances and embedded battery chemistry are fragmenting traditional generator procurement into subsystem-specialist sourcing, rewiring competitive boundaries between engine OEMs and electrical component suppliers.
Silicon carbide (SiC) MOSFETs are replacing conventional IGBT modules in traction inverters, enabling higher switching frequencies and reduced thermal losses. European high-speed rail operators are piloting SiC-based auxiliary power units on 25kV corridors. The technology is bifurcating supplier tiers between integrated power electronics designers and legacy engine manufacturers lacking in-house semiconductor capabilities.
EPA Tier 4 Final and EU Stage V regulations are tightening particulate matter and nitrogen oxide limits for non-road diesel engines. After-treatment complexity has elevated development costs for conventional architectures. Freight operators in the United States are deferring new-build purchases and extending existing fleet service intervals to avoid compliance-driven capital outlays.
Service contracting is fragmenting from bundled maintenance agreements toward discrete subsystem warranties covering batteries, inverters, and prime movers separately. Metro operators in Asia-Pacific urban systems are unbundling generator service packages to optimize lifecycle costs across heterogeneous fleet ages. This pattern is most visible in Vietnam and Indonesia, where rapid network expansion has created mixed-vendor installed bases.
Railway Generators Market Segmentation
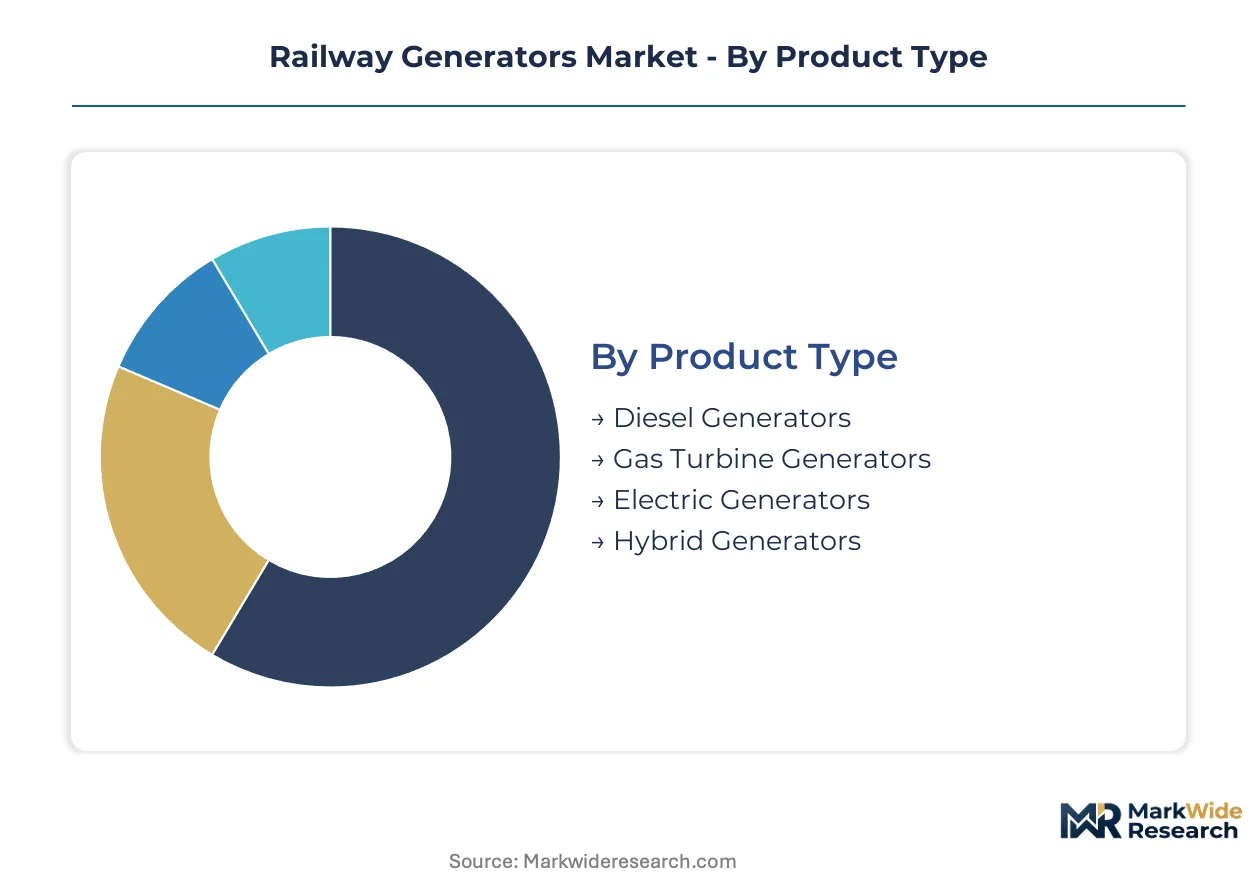
Railway generator procurement channels diverge sharply by segment. Diesel and hybrid architectures flow through rail operator direct tenders, while gas turbine and electric units concentrate in government-funded corridor electrification programs. Understanding these channel dynamics shapes go-to-market strategy for component suppliers and system integrators.
Product Type:
Diesel generators dominate freight operator procurement channels. Hybrid units are capturing urban transit tenders. Gas turbine and electric architectures flow through national infrastructure ministries.
- Diesel Generators:Conventional reciprocating engine sets operating at 400V to 3.3kV for auxiliary and emergency traction power. Indian Railways and North American Class I railroads anchor procurement volumes for branch-line electrification gaps and backup duty cycles. EPA Tier 4 Final compliance costs are compressing margins and extending replacement intervals.
- Hybrid Generators:Integrated diesel-electric architectures combining prime movers with lithium-ion buffers and SiC traction inverters. European high-speed corridors and Chinese MIIT-certified trunk lines are validating cold-climate performance below -25°C. Battery management system certification is creating tiered entry barriers.
- Gas Turbine Generators:Aeroderivative and industrial turbine sets for stationary rail yard power and grid-stabilization microgrids. China's Beijing-Shanghai corridor trials demonstrate ancillary services revenue potential.
- Electric Generators:Motor-generator sets and rotary converters for 25kV AC to 750V DC transformation in fully electrified networks. Procurement concentrates in French and Japanese Shinkansen maintenance contracts.
By volume, diesel generators lead. By growth pace, hybrid generators are expanding most quickly.
Power Rating:
Cost tiers stratify procurement behavior. Sub-megawatt units serve station backup. Mid-range ratings dominate mainline auxiliary contracts. Heavy-haul corridors demand premium above-10 MW systems.
- 1-5 MW:Auxiliary power units for locomotive hotel loads, signaling systems, and station supply. Indian Railways electrification mandates are accelerating tender volumes for non-electrified branch lines. This band captures the highest shipment volumes across Asia-Pacific urban transit expansions.
- Above 10 MW:Heavy-haul prime power for freight corridors and grid-connected rail microgrids. Australian iron ore railways and Chinese coal transport lines anchor demand. Premium pricing reflects custom engineering and extended warranty terms.
- Less than 1 MW:Compact gensets for switchyard control systems and platform safety redundancy. Metro operators in Vietnam and Indonesia unbundle these from main contracts for lifecycle cost optimization.
- 5-10 MW:Mid-capacity units for regional passenger corridors and maintenance depot supply. Procurement splits between direct operator tenders and maintenance service provider frameworks.
By installed base, 1-5 MW systems dominate. By margin expansion, above-10 MW configurations are climbing the fastest.
Application:
Customer maturity varies by use case. Urban transit operators prioritize redundancy. Freight transport defers capital cycles. Mainline and switchyard applications split between government and private procurement.
- Urban Transit:Metro and light rail systems requiring N+1 redundant generator infrastructure for platform safety and tunnel ventilation. Procurement in Vietnam, Indonesia, and the Philippines is outpacing freight refresh cycles.
- Mainline Operations:Intercity passenger corridors demanding continuous auxiliary power across electrified and non-electrified segments. India's 100% electrification push is reshaping specifications toward backup-only duty.
- Freight Transport:Heavy-haul and intermodal operations with extended fleet service intervals to defer EPA Tier 4 compliance capital outlays. North American Class I railroads are piloting modular hybrid retrofits.
- Switchyard Supply:Classification yard power for retarder controls, lighting, and communication systems. Procurement concentrates in maintenance service provider contracts rather than direct operator ownership.
By contract value, mainline operations lead. By refresh frequency, urban transit is gaining share fastest.
End User:
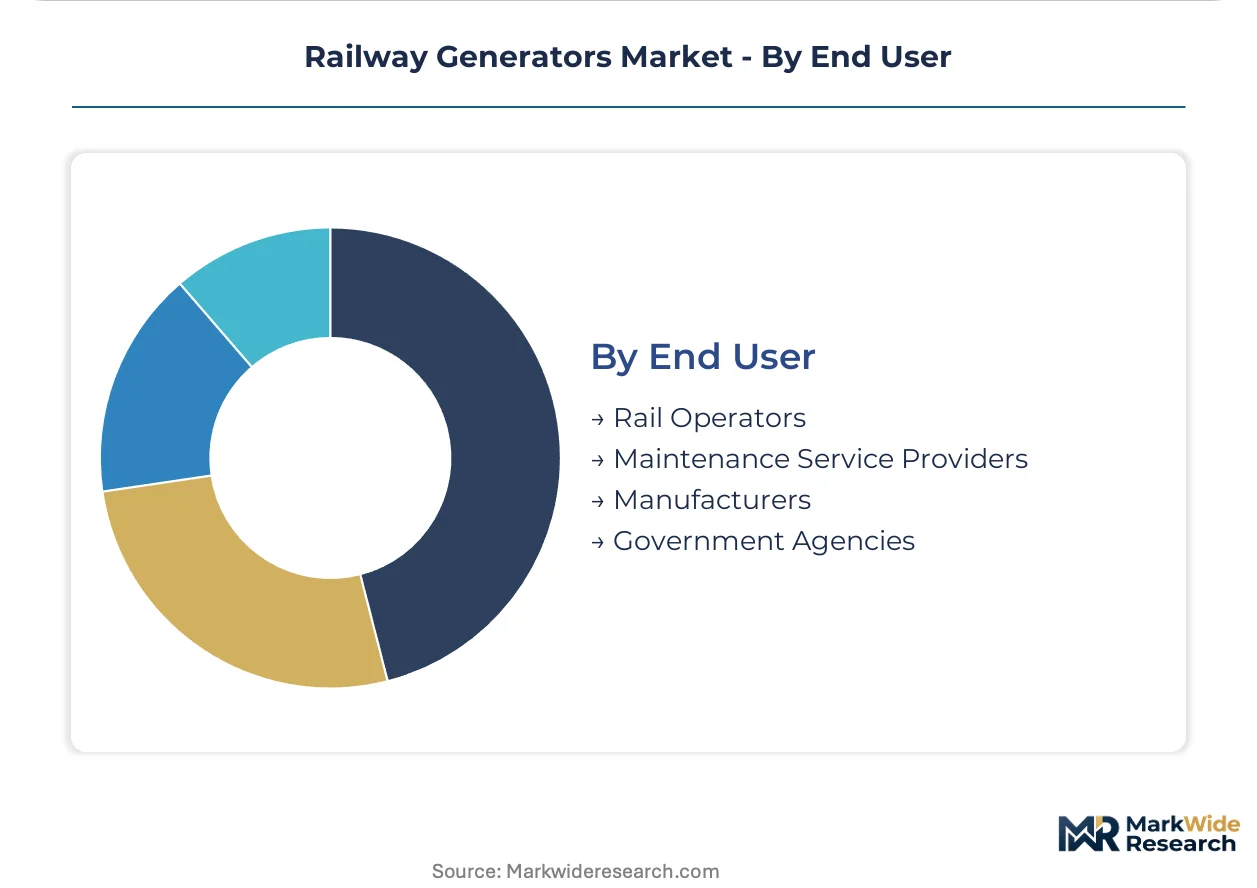
Volume concentration sits with rail operators. Margin capture flows to maintenance specialists. Government agencies shape specifications. Manufacturers anchor OEM supply.
- Rail Operators:National railways and private freight carriers owning fleet-wide generator procurement. Indian Railways and European high-speed operators dominate tender volumes.
- Maintenance Service Providers:Third-party contractors unbundling subsystem warranties across batteries, inverters, and prime movers. Asia-Pacific metro expansions are fragmenting service contracts.
- Manufacturers:Locomotive and multiple-unit OEMs integrating generators into new-build platforms. Siemens and Cummins anchor North American and European supply chains.
- Government Agencies:Infrastructure ministries funding corridor electrification and grid-connectivity mandates. India's CEA and China's MIIT certify hybrid trial specifications.
By procurement volume, rail operators lead. By contract sophistication, maintenance service providers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's CEA grid-connectivity mandates and BIS emission norms are reshaping procurement specifications across the railway generators landscape. China accelerates MIIT-certified hybrid generator trials on trunk corridors. European operators navigate EU Stage V compliance timelines while North American freight railroads defer capital cycles.
India
Indian Railways' 100% mainline electrification push is accelerating tender volumes for high-capacity auxiliary power units on non-electrified branch lines. The CEA mandates grid-connectivity standards for captive power installations, forcing specification redesigns. BHEL dominates domestic tendering from manufacturing clusters in Bhopal and Hyderabad.
China
MIIT dual carbon goals are accelerating certified hybrid generator trials on the Beijing-Shanghai trunk line corridor. National rail infrastructure ministries fund grid-stabilization microgrid demonstrations. Manufacturing concentrates in the Yangtze River Delta around Shanghai and the Pearl River Delta near Guangzhou.
Germany
EU Stage V non-road engine regulations are forcing diesel generator redesigns toward hybrid-electric architectures with integrated after-treatment. The KBA certifies power electronics integration standards for high-speed corridors. Industrial clusters in Bavaria and Baden-Württemberg anchor European traction power engineering.
United States
EPA Tier 4 Final compliance deadlines are compressing margins for conventional diesel architectures across Class I railroad fleets. Freight operators extend service intervals to defer capital outlays on aging locomotive power packs. Manufacturing and retrofit activity concentrates in the Midwest rail belt and Texas energy corridor.
Vietnam
Metro expansion in Hanoi and Ho Chi Minh City is driving redundant generator infrastructure procurement for platform safety systems. National urban transit authorities mandate N+1 backup power specifications for tunnel ventilation. Equipment sourcing flows through maintenance service provider frameworks rather than direct operator ownership.
Railway Generators Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-level competitive structure. The upper tier combines diesel-electric integration depth with in-house power electronics design capabilities. Specialist competitors concentrate on subsystem supply—battery management systems, SiC traction inverters, or exhaust after-treatment modules. Dominant competitive moves include strategic partnerships between engine OEMs and semiconductor suppliers, plus geographic expansion through maintenance service provider contracts in Asia-Pacific urban transit markets.
Among Germany-based integrated industrial groups, Siemens AG exemplifies the power electronics-led archetype through in-house semiconductor design for high-speed rail corridors. Cummins Inc. anchors the diesel-electric integration tier, leveraging reciprocating engine expertise for North American freight locomotive applications. Bharat Heavy Electricals Limited occupies a position within the state-affiliated infrastructure tier, capturing domestic tender volumes through proximity to Indian Railways procurement channels.
| Leading Market Players |
|---|
| Siemens AG |
| General Electric |
| Cummins Inc. |
| Bharat Heavy Electricals Limited |
| Jenoptik |
| Nidec Generator Corporation |
| Ingeteam Traction Systems |
| VEM Group |
| Kirloskar Electric Company |
| Others |
Value Network & Pricing Analysis
Lead times for SiC traction inverters now stretch 26-32 weeks, concentrating pricing power with semiconductor foundries in Taiwan and Germany while compressing margins for diesel-electric integrators lacking captive power electronics capacity. This inventory pressure cascades through hybrid generator procurement, where battery management system certification costs amplify price differentiation across supplier tiers.
Pricing Analysis
Price spreads between European and Asia-Pacific deliveries widen by 15-20% after logistics and certification add-ons. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels dominates procurement. Pricing pressure stems from platinum group metal volatility in diesel after-treatment systems. Freight operators exhibit highest price sensitivity due to deferred replacement cycles, while urban transit authorities prioritize redundancy over unit cost.
Supply Chain Analysis
Inventory buffers for lithium-ion cells and SiC wafers have thinned to 45-60 days across Tier 1 suppliers. Manufacturing concentrates in China, Germany, and India for prime movers; South Korea and Japan for battery cells; Taiwan for power semiconductors. Raw material dependencies span palladium catalysts, lithium carbonate, and silicon carbide substrates. Single-source vulnerability in SiC wafer supply creates chokepoint exposure. Distribution runs through rail operator direct tenders and maintenance service provider frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-entrenchment defensive moat. Dual certification timelines for EPA Tier 4 and EU Stage V create 18-24 month barriers that favor incumbents with established compliance infrastructure.
For Market Incumbents: Fortify hybrid integration capabilities through backward integration into battery management system design. Cummins and Siemens anchor positions via in-house power electronics; challengers face displacement from subsystem specialists capturing SiC inverter margins. Prioritize certification investment in cold-climate battery validation to lock in Scandinavian and Canadian corridor contracts. For New Entrants and Emerging Players: Lead with battery-buffer subsystem supply rather than full generator integration. Stationary rail microgrids in China and Vietnam offer most penetrable white space. Target maintenance service provider channels in Asia-Pacific urban transit markets where unbundled procurement fragments incumbent bundling power. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-utility play because rail electrification mandates create recurring auxiliary power demand regardless of freight cycle volatility. Acquisition targets should display MIIT or CEA certification traction plus SiC inverter integration depth. Monitor battery reliability data below -25°C as inflection signal for hybrid architecture tipping points.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Electronics | Cummins and Siemens defend margin capture from semiconductor suppliers through captive SiC design. |
| Cold-Climate Certification Investment | First-mover validation below -25°C unlocks Scandinavian and Canadian trunk line procurement. |
| Maintenance Service Provider Partnership | Unbundled subsystem warranties in Vietnam and Indonesia fragment traditional bundled contracts. |
| Grid-Connected Microgrid Deployment | MIIT-certified Beijing-Shanghai trials demonstrate ancillary services revenue beyond backup duty. |
| Dual Certification Acceleration | Parallel EPA Tier 4 and EU Stage V timelines compress time-to-market for compliant architectures. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary fieldwork. Traction power engineers at Indian Railways, procurement leads at North American Class I railroads, and hybrid system integrators in Germany provided operational validation. Secondary sources included EPA certification filings, EU Stage V technical documentation, CEA grid-connectivity mandates, and MIIT dual carbon policy releases. Bottom-up tender analysis and top-down infrastructure spend estimates were triangulated.
Across the analysis window, volume and value outputs were modeled by power rating band, product architecture, application segment, and regional regulatory cluster. CAGRs were derived from tender pipeline tracking and fleet replacement schedule analysis. Forecast inputs incorporated platinum group metal price trajectories and lithium cell supply expansion curves.
Underlying assumptions cover electrification mandate adherence timelines and hybrid battery duty cycle performance, with deviation risk concentrated in cold-climate validation delays and semiconductor supply disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
South America Diesel Generator Market
Generators
Portugal Gas Generator Market
Generators
Hand Crank Power Generator Market
Generators
Middle-East and Africa Portable Generator Market
Generators
Middle East Portable Generator Market
Generators
Dual-Fuel Generator Market
Generators
Asia-Pacific Generator Sets Market
Generators
Onboard Marine Gensets Market
Generators
Europe Generator Sets Market
Generators
Diesel Generator Market
Generators
Generator Rental Market
Generators
Gasoline Generator Market
Generators
South Africa Diesel Generator Market
Generators
Generator Sales Market
Generators
Kuwait Diesel Gensets Market
Generators
Mobile Generators Market