
 Asia-Pacific Gas Generator Market | 2026-2036
Asia-Pacific Gas Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Gas Generator Market Outlook
Buyer concentration among data center operators and semiconductor fabricators is hardening across Southeast Asia and India. Cummins Inc leverages its reciprocating engine portfolio to anchor utility-scale projects in India and Vietnam. Caterpillar Inc sustains manufacturing scale through regional assembly hubs serving mining and oil & gas clients. Mitsubishi Heavy Industries Ltd dominates turbine-based installations for combined heat and power applications in Japan and South Korea.
Asia-Pacific gas generators convert natural gas, LPG, or biogas into electrical power through reciprocating engines or turbine systems, typically achieving thermal efficiencies between 35% and 45% depending on unit size and cycle configuration. These units provide baseload, peaking, or emergency power for industrial facilities, commercial complexes, and remote installations where grid reliability remains insufficient. Natural gas generators lead product type demand as urban air quality regulations tighten across Chinese and Indian megacities. Reciprocating engine technology occupies the largest installed base due to lower capital costs and maintenance accessibility. Hybrid systems integrating battery storage represent the fastest-growing technology segment as island grids and industrial microgrids proliferate.
India's Central Electricity Authority mandates emission standards for captive power plants that favor gas over diesel in designated critical load centers. China's Ministry of Ecology and Environment enforces dual carbon goals that restrict coal-fired distributed generation while permitting efficient gas turbines in industrial parks. Japan's METI promotes hydrogen-ready gas turbines through technology roadmaps affecting procurement specifications. Stakeholders must monitor how carbon border adjustment mechanisms and evolving gas supply contracts reshape total cost of ownership calculations across national markets.
Market Dynamics
Hybrid gas-battery microgrids are compressing traditional procurement cycles as data center operators and semiconductor fabricators across Southeast Asia and India bypass utility queues entirely. This technology convergence is redrawing competitive boundaries between reciprocating engine suppliers and energy storage integrators.
Growth Catalysts
- India's PLI scheme for manufacturing:Production-linked incentives redirect capital toward domestic gas generator assembly, cutting import dependency for critical power components.
- Data center load growth:Cloud operators in Singapore and Indonesia require 50-200 MW captive blocks that gas turbines deliver faster than grid interconnection permits allow.
- China's dual carbon goals:MEE enforcement restricts coal distributed generation while permitting efficient gas turbines in designated industrial parks.
Market Restraints
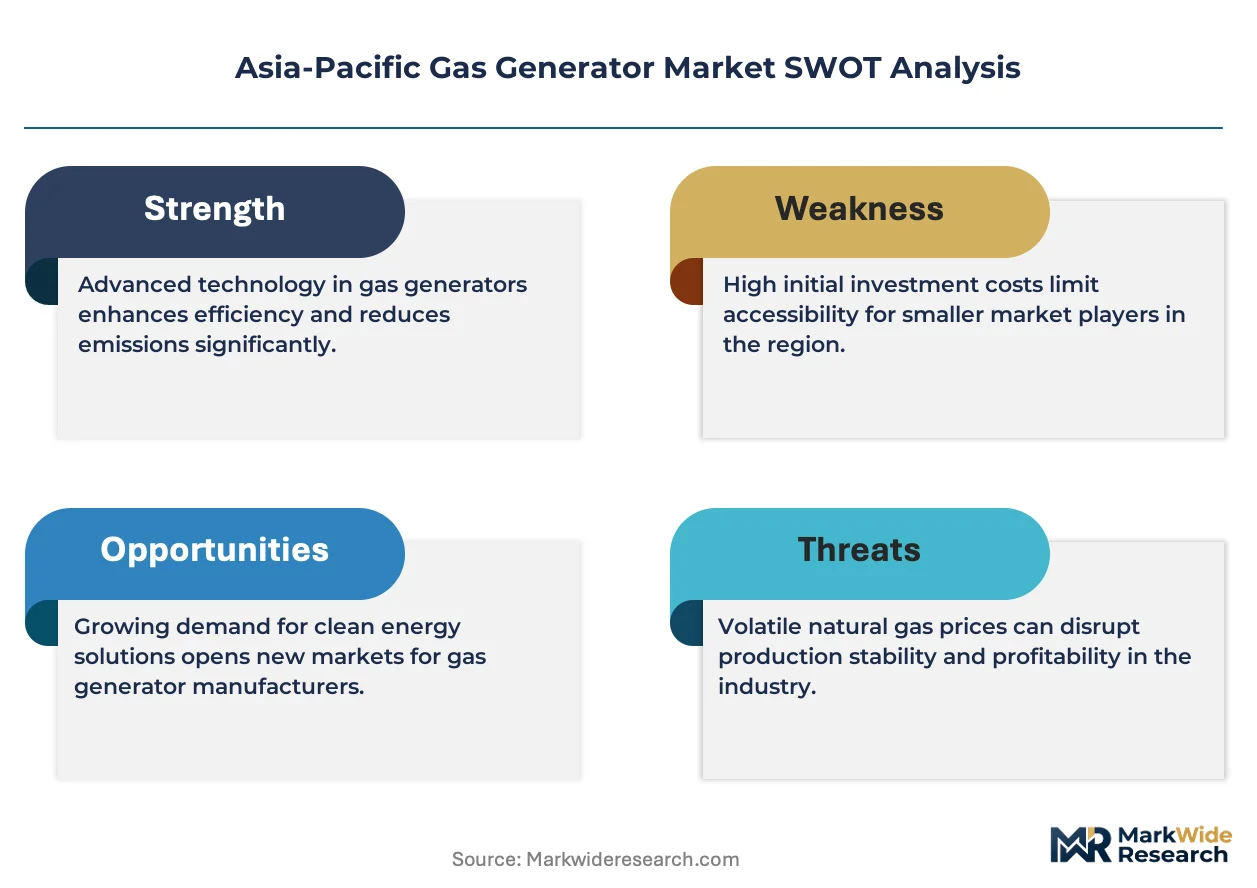
- LNG price volatility:Spot cargo fluctuations in Asia-Pacific import markets compress generator operating margins against fixed electricity tariffs.
- Turbine supply concentration:Heavy-frame gas turbine manufacturing concentrates among three Japanese and European OEMs, extending delivery timelines to 24-36 months.
- Grid parity pressure:Utility-scale solar-plus-storage in Vietnam and Thailand undercuts gas peaking economics on levelized cost metrics.
Strategic Opportunities
- Philippines island electrification:Archipelago geography favors decentralized gas microgrids where submarine cable costs prove prohibitive.
- Hydrogen-ready turbine retrofits:METI technology roadmaps in Japan create procurement specifications that future-proof capital investments.
- Biogas feedstock integration:Palm oil mill effluent and agricultural waste in Malaysia and Indonesia enable carbon-negative generation claims.
Industry Challenges
- Specialized commissioning engineers:Grid-code compliance for island mode operation requires scarce technicians familiar with both reciprocating engines and power electronics.
- Dual-fuel system integration:Retrofitting diesel-gas flexibility adds control complexity that voids existing maintenance warranties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Gas Generator Market |
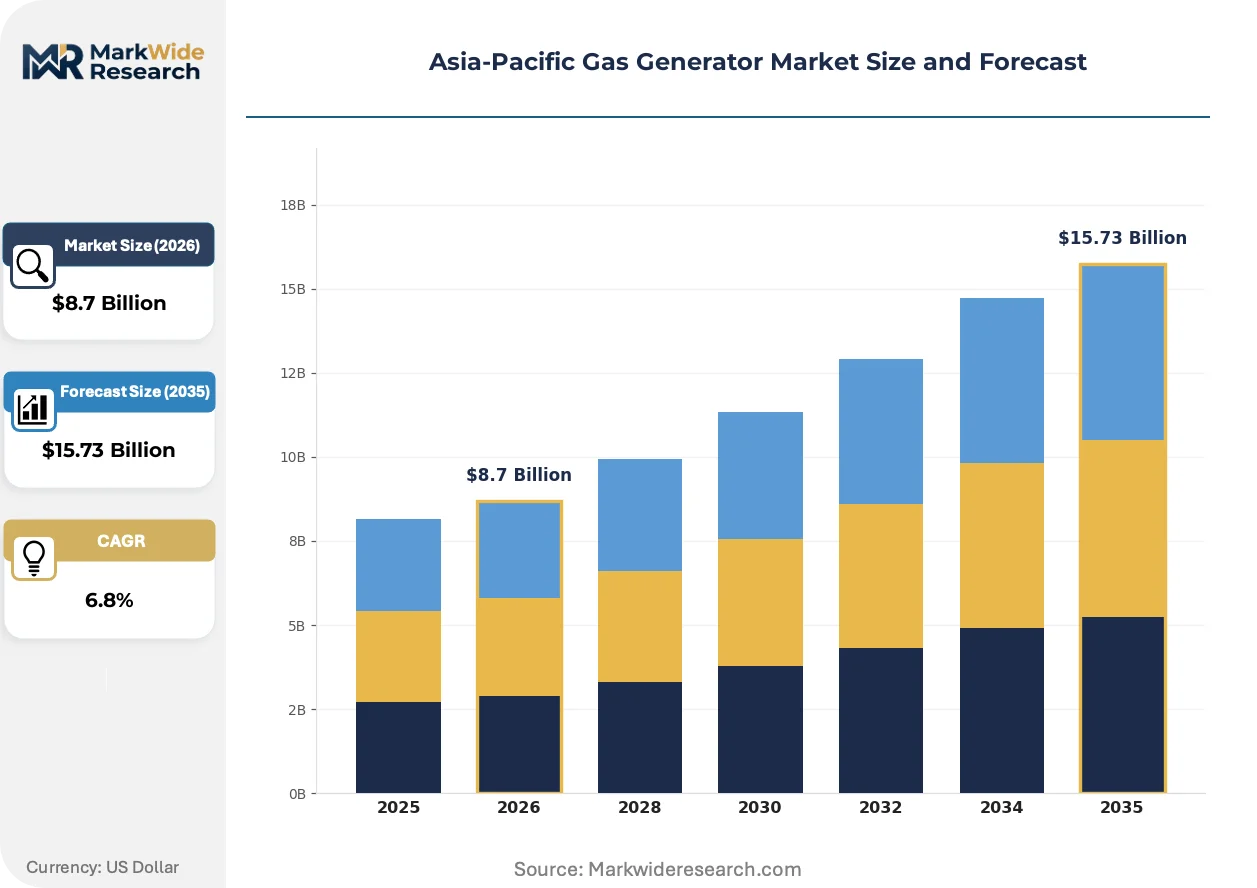
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel Generator, Natural Gas Generator, Bi-Fuel Generator, LPG Generator Application: Residential Use, Commercial Backup, Industrial Power, Remote Area Power Supply End User: Manufacturing Sector, Oil & Gas Industry, Construction Industry, Telecommunications Technology: Reciprocating Engine, Turbine Technology, Hybrid Systems, Fuel Cell Technology |
| Companies Covered | Caterpillar Inc, Cummins Inc, Kohler Co, Yanmar Co. Ltd, Kirloskar Electric Company Limited, Generac Holdings Inc, MTU Onsite Energy, Mitsubishi Heavy Industries Ltd, Himoinsa S.L., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Gas Generator Market Strategic Shifts
Digital twins and predictive analytics are compressing maintenance intervals while remote monitoring platforms shift service revenue from breakdown response to uptime guarantees. Equipment suppliers now compete on availability contracts rather than unit pricing alone.
Containerized gas generator blocks with integrated heat recovery are rewriting deployment economics for industrial microgrids. Food processors and textile mills in Vietnam's northern provinces adopt these skid-mounted systems within 8-12 week installation windows. The technology is rewriting the traditional 18-month project timeline that favored permanent turbine installations.
China's GB 13271 emission standards for stationary sources tighten NOx and particulate limits for gas-fired distributed generation. MEE enforcement in the Yangtze River Delta and Pearl River Delta industrial clusters forces retrofits or replacements of pre-2015 generator sets. Manufacturers respond with selective catalytic reduction packages and lean-burn combustion upgrades.
Power purchase agreements with guaranteed heat offtake are displacing simple electricity sales in South Korean and Japanese industrial parks. Chemical and pharmaceutical buyers in Ulsan and Osaka Bay clusters now contract for steam-and-power bundles rather than kilowatt-hour tariffs. This contractual evolution is most visible in combined heat and power applications where thermal load stability underwrites generator capacity factors above 75 percent.
Asia-Pacific Gas Generator Market Segmentation
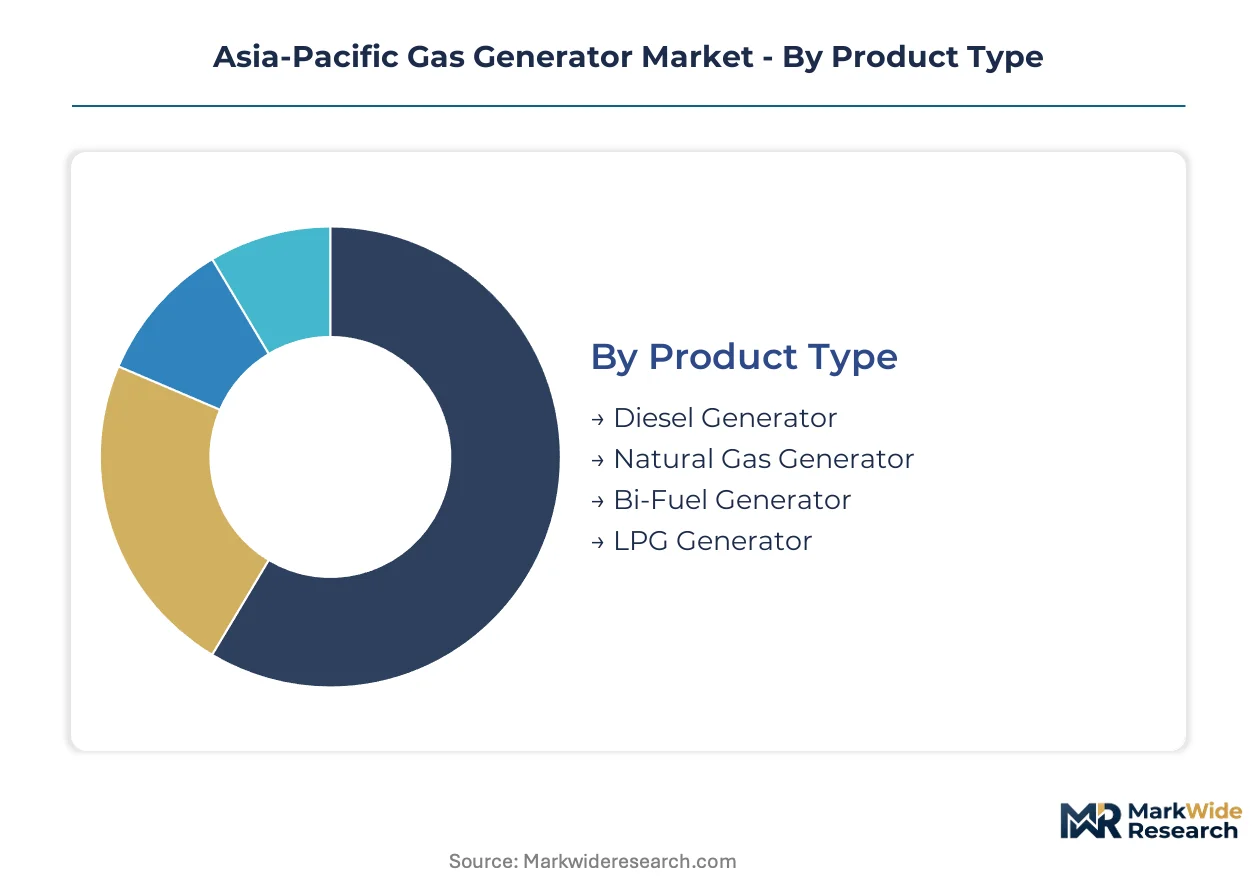
Segmentation in the Asia-Pacific gas generator market reveals how technology choices, fuel flexibility, and end-use requirements reshape procurement patterns across industrial parks and island grids. Understanding these divisions exposes where capital concentrates and which configurations bypass traditional utility infrastructure entirely.
Product Type:
Standalone generator sets dominate captive power installations, while bi-fuel and hybrid configurations embed into microgrids requiring fuel-switching resilience.
- Natural Gas Generator:Lean-burn combustion systems achieve thermal efficiencies between 35% and 45% depending on unit scale and cycle configuration. Demand concentrates in India's western industrial corridor spanning Gujarat and Maharashtra, where the Central Electricity Authority mandates emission standards that favor gas over diesel in designated critical load centers.
- Diesel Generator:Compression-ignition engines deliver higher torque response for construction and mining applications where load spikes exceed gas turbine ramp rates. Procurement is shifting toward dual-fuel retrofit kits in Vietnam's northern provinces as GB 13271-equivalent air quality rules tighten in cross-border industrial zones.
- Bi-Fuel Generator:Parallel diesel-gas combustion enables 30-70% gas substitution ratios without derating. Food processors in Thailand's Eastern Economic Corridor adopt these for biogas integration from agricultural waste streams.
- LPG Generator:Pressurized propane systems serve remote telecommunications towers across the Philippines archipelago where LNG infrastructure remains absent.
Volume placements concentrate in Natural Gas Generator; the faster expansion belongs to Bi-Fuel Generator.
Application:
Application segmentation tracks how deployment scale and grid proximity determine technology selection and fuel choice.
- Industrial Power:Continuous-duty installations above 10 MW capacity anchor combined heat and power configurations in South Korean and Japanese chemical clusters. Power purchase agreements with guaranteed heat offtake now displace simple electricity sales in Ulsan and Osaka Bay industrial parks.
- Commercial Backup:Peaking and emergency systems serve data centers in Singapore and Indonesia requiring 50-200 MW captive blocks. Cloud operators bypass utility interconnection queues entirely, compressing traditional procurement cycles.
- Remote Area Power Supply:Containerized skid-mounted systems deploy within 8-12 week windows across Vietnam's northern provinces where submarine cable costs prove prohibitive.
- Residential Use:Small-scale standby units below 50 kW address grid instability in suburban Jakarta and Manila fringe developments.
Industrial Power commands the largest installed base; Remote Area Power Supply is climbing the fastest as archipelago electrification accelerates.
End User:
End user segmentation reflects sector-specific uptime requirements and thermal load profiles that dictate generator sizing and redundancy architecture.
- Manufacturing Sector:Textile mills and electronics fabricators in Vietnam and Bangladesh deploy gas generators for baseload displacement of unreliable grid supply. Containerized blocks with integrated heat recovery rewrite deployment economics for these facilities.
- Oil & Gas Industry:Upstream platforms and pipeline compressor stations across Indonesia's Rokan and Mahakam fields require explosion-proof enclosures and fuel gas conditioning skids.
- Construction Industry:Mobile rental fleets serve infrastructure projects in India's Delhi-Mumbai Industrial Corridor where grid extension lags site activation.
- Telecommunications:Tower operators in Myanmar and Laos specify LPG and small gas sets for off-grid base stations as diesel theft and logistics costs escalate.
Manufacturing Sector absorbs the highest unit volumes; Telecommunications shows the steepest expansion trajectory as 5G rollout accelerates rural site densification.
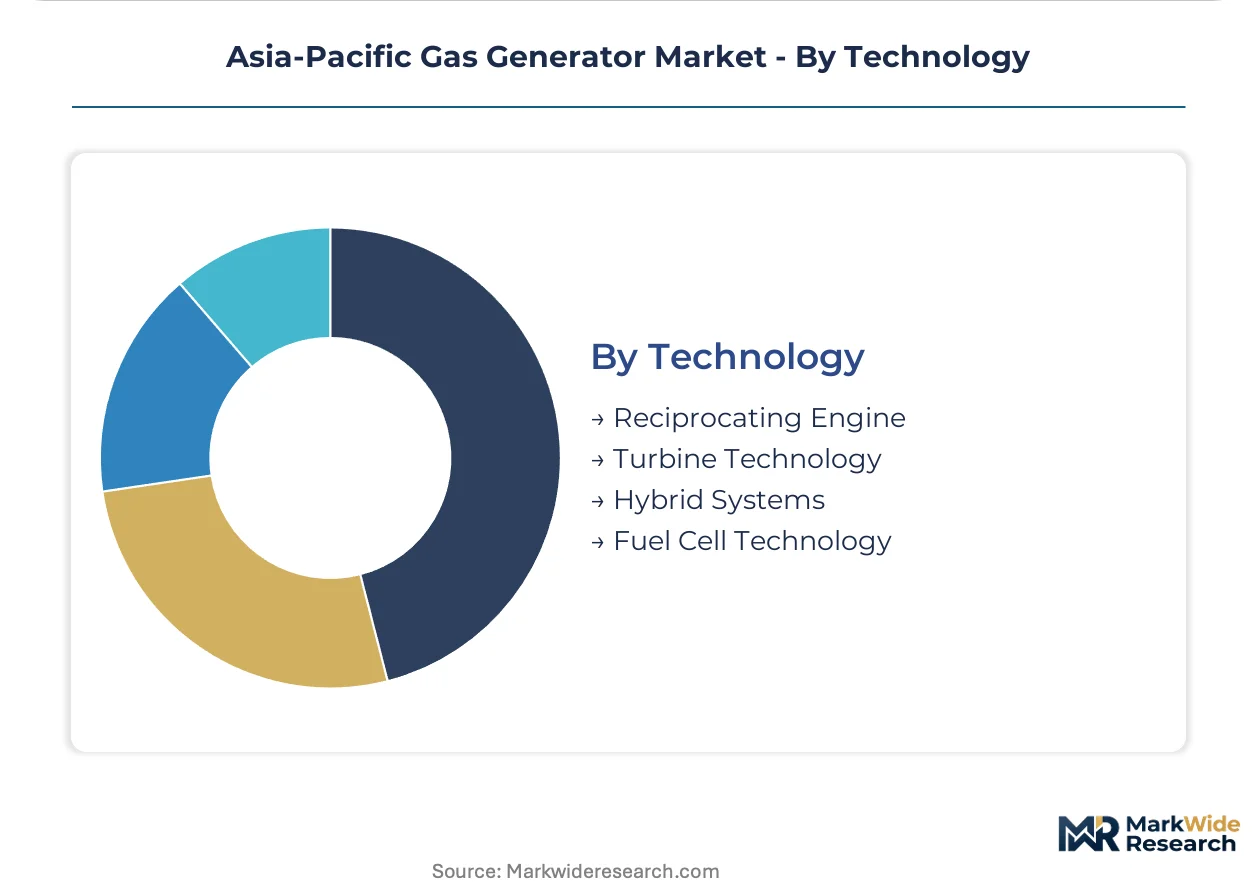
Technology:
Technology segmentation distinguishes between mature reciprocating platforms, capital-intensive turbines, and emerging hybrid architectures.
- Reciprocating Engine:Piston-driven systems occupy the largest installed base due to lower capital costs and maintenance accessibility. Caterpillar Inc and Cummins Inc leverage regional assembly hubs to serve mining and utility-scale projects across India and Vietnam.
- Turbine Technology:Heavy-frame gas turbines deliver combined cycle efficiencies above 50% for utility-scale installations. Manufacturing concentrates among Japanese and European OEMs, extending delivery timelines to 24-36 months.
- Hybrid Systems:Battery-integrated gas microgrids represent the fastest-growing technology segment as island grids and industrial microgrids proliferate. This technology convergence redraws competitive boundaries between engine suppliers and energy storage integrators.
- Fuel Cell Technology:Solid oxide and molten carbonate systems remain nascent in Asia-Pacific, with pilot installations limited to Japanese hydrogen-ready demonstrations under METI technology roadmaps.
Reciprocating Engine retains dominant share; Hybrid Systems are gaining share fastest as data center operators and semiconductor fabricators adopt gas-battery configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Natural gas basins in Australia's Northwest Shelf and coal seam reserves in Queensland anchor feedstock security for distributed generation across the region. These hydrocarbon localities shape procurement economics from Perth to Manila.
India
Data center operators in Mumbai and Chennai require 50-200 MW captive blocks as grid interconnection queues extend beyond 24 months. The Central Electricity Authority mandates emission standards for captive power plants that favor gas over diesel in designated critical load centers. Gujarat's western industrial corridor concentrates textile mills and pharmaceutical fabricators deploying combined heat and power configurations.
China
Industrial parks in the Yangtze River Delta seek efficient gas turbines to replace coal-fired distributed generation. The Ministry of Ecology and Environment enforces dual carbon goals that restrict coal while permitting efficient gas turbines in designated zones. Shenzhen and Dongguan electronics clusters accelerate procurement of lean-burn combustion systems to meet GB 13271 emission standards.
Japan
Chemical and pharmaceutical buyers in Osaka Bay industrial parks contract for steam-and-power bundles rather than kilowatt-hour tariffs. METI promotes hydrogen-ready gas turbines through technology roadmaps affecting procurement specifications. Ulsan-facing industrial complexes on Kyushu adopt combined cycle configurations achieving thermal efficiencies above 50 percent.
Vietnam
Food processors in northern provinces deploy containerized skid-mounted systems within 8-12 week installation windows. Cross-border industrial zones adopt GB 13271-equivalent air quality rules tightening NOx limits for gas-fired generation. Hai Phong and Bac Ninh manufacturing corridors bypass submarine cable costs through decentralized microgrids.
Indonesia
Cloud operators in Jakarta and Batam require captive power blocks faster than utility permits allow. Palm oil mill effluent in Sumatra enables biogas feedstock integration for carbon-negative generation claims. Rokan and Mahakam upstream fields demand explosion-proof enclosures and fuel gas conditioning skids for platform installations.
Asia-Pacific Gas Generator Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue hybrid battery integration and hydrogen-ready retrofits. The market structures around three tiers: heavy-frame turbine OEMs with 24-36 month delivery timelines, reciprocating engine assemblers leveraging regional manufacturing hubs, and energy storage integrators compressing traditional procurement cycles. Strategic archetypes include utility-scale project anchors, microgrid solution bundlers, and aftermarket service platforms. Dominant competitive moves encompass geographic expansion through regional assembly licensing and portfolio diversification into hybrid gas-battery configurations.
Among US-based engine manufacturers, Caterpillar Inc and Cummins Inc exemplify the reciprocating engine tier with regional assembly scale. Caterpillar anchors mining and oil & gas client relationships through manufacturing presence. Cummins represents the utility-scale project vector across India and Vietnam. Japanese heavy industrial conglomerates occupy the turbine tier; Mitsubishi Heavy Industries Ltd sits within the combined heat and power specialization for East Asian industrial parks. These three entities illustrate how technology choice—reciprocating versus turbine versus hybrid—determines competitive boundaries more than geographic origin alone.
| Leading Market Players |
|---|
| Caterpillar Inc |
| Cummins Inc |
| Kohler Co |
| Yanmar Co. Ltd |
| Kirloskar Electric Company Limited |
| Generac Holdings Inc |
| MTU Onsite Energy |
| Mitsubishi Heavy Industries Ltd |
| Himoinsa S.L. |
| Others |
Value Chain & Pricing Dynamics
Heavy-frame turbine OEMs and reciprocating engine assemblers operate at divergent margin structures that reshape procurement economics across India's western industrial corridor and Vietnam's northern provinces. Premium-tier suppliers bundle 10-year service contracts and guaranteed uptime commitments into project pricing, while commodity assemblers compete on unit cost alone. This bifurcation concentrates buyer power among hyperscale data center operators who extract performance guarantees, while smaller industrial buyers absorb aftermarket risk.
Pricing Analysis
Warranty bundling separates premium turbine OEMs from standard reciprocating engine suppliers in Asia-Pacific procurement negotiations. Three-tier pricing structure across premium, standard, and economy levels tracks thermal efficiency ratings and emission compliance tiers under China's GB 13271 standards. Cost compression in the standard tier is intensifying because utility-scale solar-plus-storage in Vietnam and Thailand undercuts gas peaking economics. Data center operators in Singapore and Indonesia show least price sensitivity due to grid interconnection queue premiums, while textile mills in Bangladesh face acute margin pressure.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for heavy-frame gas turbines, while authorized distributor networks serve mid-scale industrial accounts across Southeast Asia. Manufacturing concentrates in Japan, South Korea, and China for turbine components, with India emerging as a reciprocating engine assembly hub under the PLI scheme. Supply chains draw from specialty steel forgings, precision castings, and SCR catalyst substrates. Single-source vulnerability concentrates in heavy-frame turbine manufacturing among three Japanese and European OEMs. Distribution runs through EPC contractors and regional equipment dealers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific gas generator procurement functions as a cost-of-compliance story where China's MEE enforcement of dual carbon goals and GB 13271 emission standards erects regulatory moats favoring OEMs with certified lean-burn combustion systems.
For Market Incumbents: Extend service contract portfolios into predictive maintenance platforms to capture recurring revenue as unit pricing compresses. Defend against energy storage integrators by anchoring hybrid gas-battery microgrid solutions for data center operators in Singapore and Indonesia. Deepen backward integration into hydrogen-ready turbine retrofits to align with Japan's METI technology roadmaps. For New Entrants and Emerging Players: Launch via containerized skid-mounted system distribution to bypass 24-36 month turbine delivery timelines. Target Philippines island electrification where submarine cable costs render centralized grid extension uneconomical. Penetrate through biogas feedstock integration partnerships with palm oil mill operators in Sumatra and Sarawak. For Investors and Strategic Acquirers: Re-rating potential sits with aftermarket service platforms given the scarcity of grid-code compliance engineers for island mode operation. Long-term viability favors asset-light integrators over capital-intensive turbine OEMs as procurement cycles compress. Watch hydrogen-ready certification penetration in Japanese industrial parks as the inflection signal for technology transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Turbine Retrofit | METI roadmaps in Japan create future-proofing procurement specifications for Osaka Bay chemical clusters. |
| Containerized Microgrid Deployment | Skid-mounted systems compress installation windows to 8-12 weeks for Vietnam food processors. |
| Biogas Feedstock Integration | Palm oil mill effluent in Sumatra enables carbon-negative generation claims for Indonesian fabricators. |
| Regional Assembly Licensing | India's PLI scheme redirects capital toward domestic gas generator assembly cutting import dependency. |
| Hybrid Battery Integration | Gas-battery configurations redraw competitive boundaries between engine suppliers and storage integrators. |
Study Parameters
Independent corroboration across EPC contractor interviews, utility planning officer surveys, and fuel supply specialist consultations underwrites the qualitative findings. Primary fieldwork engaged plant engineers at textile mills in Vietnam, maintenance directors at Indian pharmaceutical fabricators, and aftermarket service heads at regional equipment dealers. Secondary validation drew from FERC-style grid interconnection databases, IEA power sector outlooks, and customs records for generator set imports. Bottom-up project pipeline assessments triangulate against top-down macroeconomic indicators.
Comparable-period anchoring to historical capacity additions and grid instability indices shapes the projection horizon. Segmentation modeling spans fuel source, generation capacity tier, technology architecture, and regional regulatory framework. CAGRs derive from unit placement trajectories and average selling price movements across the analysis window. Forecast inputs include data center load growth curves, LNG spot price volatility bands, and emission standard enforcement timelines.
LNG price volatility, turbine OEM delivery timeline extensions, and grid parity acceleration from solar-plus-storage are the dominant revision risks. Forecasts reflect assumptions around regulatory enforcement consistency and gas infrastructure buildout pacing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Industrial Generator Market
Generators
Electric Generators Market
Generators
Generator Rental Market
Generators
Diesel Generator Market
Generators
South America Gas Generator Market
Generators
South America and Africa Diesel Generator Market
Generators
Asia-Pacific Diesel Generator Market
Generators
Asia-Pacific Generator Sets Market
Generators
Power Generator Rental Market
Generators
Europe Turbo Generator Market
Generators
South America Diesel Generator Market
Generators
Boiler Turbine and Generator BTG Sales Market
Generators
Middle East Portable Generator Market
Generators
Middle-East and Africa Generator Sets Market
Generators
China Generator Sets Market
Generators
Europe Gas Turbine Market