
 China Generator Sets Market | 2026-2036
China Generator Sets Market Size, Share, and Industry Trends Forecast 2026-2036
China Generator Sets Market Outlook
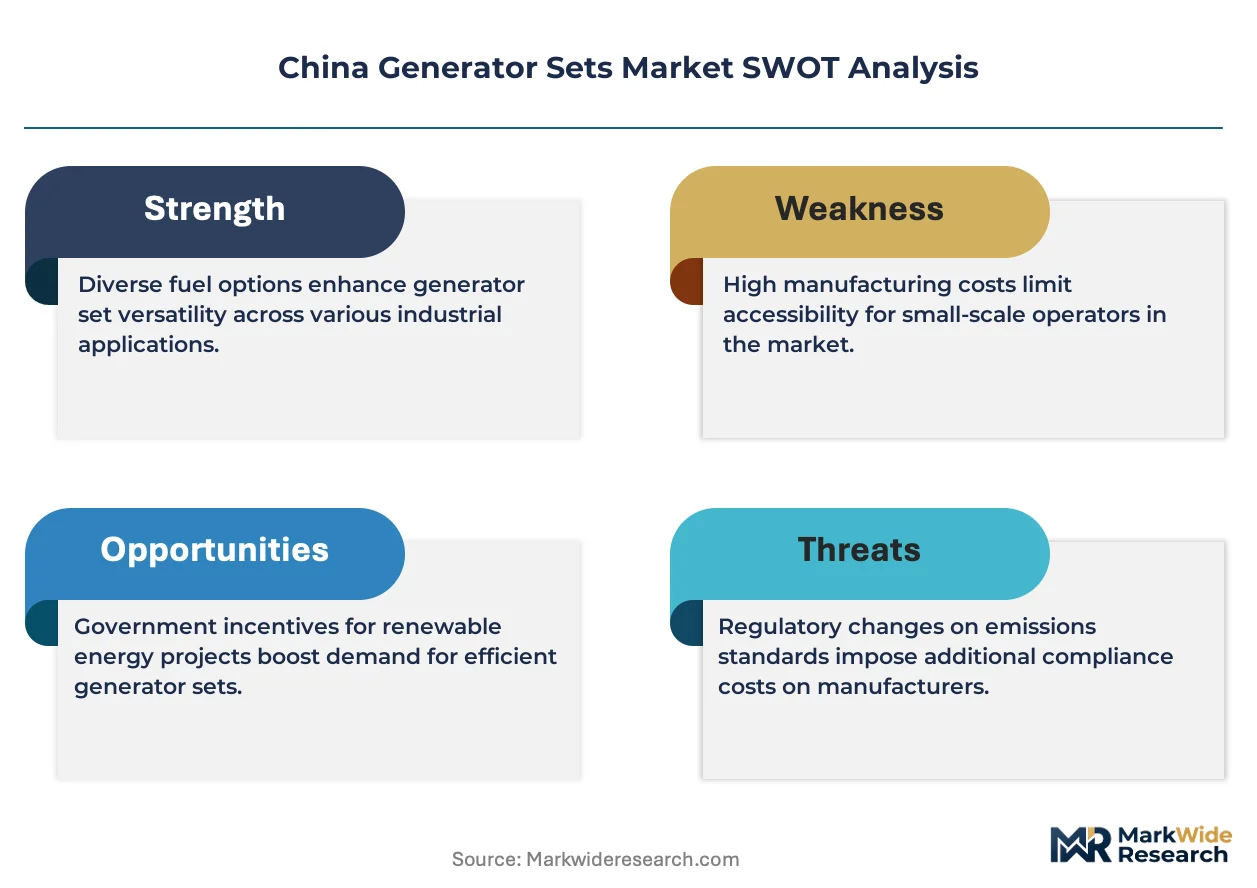
Tier-3 emission compliance is collapsing the competitive set for sub-500 kVA diesel units. Cummins (China) leverages its localized engine platform to anchor the premium stationary segment. Weichai sustains cost leadership through captive casting and machining capacity in Shandong province. Yuchai competes aggressively in the mobile and trailer-mounted categories with lighter powertrain architectures.
China generator sets are electromechanical power conversion systems rated from below 100 kVA to above 500 kVA, converting reciprocating engine output into grid-synchronous electricity through wound-field or permanent magnet alternators. These units provide prime, standby, and emergency power for industrial plants, commercial facilities, and critical infrastructure where grid reliability fluctuates. Diesel generator sets still occupy the dominant revenue share across all deployment modes, though gas generator configurations are gaining share in healthcare and commercial end-use segments where local air quality rules tighten fastest. Containerized deployments above 500 kVA carry the deepest margin pools due to customization complexity and extended service contracts.
MIIT enforces GB 20891 emission tiers for non-road engines, while SAMR administers CCC certification that gates market access for imported and domestically produced units. MEE provincial bureaus in Jiangsu and Guangdong are accelerating dual fuel retrofit mandates for existing industrial standby fleets. Stakeholders must monitor how carbon intensity benchmarks reshape procurement criteria for state-owned enterprise power tenders.
Market Dynamics
MIIT's GB 20891 Tier-3 emission enforcement is compressing the competitive set for sub-500 kVA diesel units, forcing manufacturers to redirect R&D toward gas-diesel hybrid architectures or exit the premium stationary segment entirely.
Growth Catalysts
- Data Center Expansion:Hyper-scale operators in Shanghai and Beijing are accelerating backup power procurement as uptime requirements tighten. This pulls demand toward containerized deployments above 500 kVA with extended service contracts.
- GB Standards Tightening:SAMR-administered CCC certification gates are elevating technical barriers for imported units. Domestic manufacturers with localized engine platforms capture displaced volume.
- Yangtze River Delta Concentration:Manufacturing corridor clustering creates dense service networks and parts availability. Proximity reduces lead times for industrial standby fleet retrofits.
Market Restraints
- Steel and Copper Volatility:Casting and winding material costs fluctuate with commodity cycles. Captive foundry capacity in Shandong province insulates some players but raises entry barriers for new competitors.
- Dual Fuel Retrofit Mandates:MEE provincial bureaus in Jiangsu and Guangdong are accelerating compliance timelines for existing industrial fleets. Capital requirements for gas infrastructure strain smaller operators.
- Permanent Magnet Alternator Substitution:Wound-field architectures face displacement in mobile applications where weight reduction dominates specification sheets.
Strategic Opportunities
- Healthcare Segment Gas Migration:Local air quality rules in urban clusters are opening share for gas generator configurations. Hospitals prioritize emissions compliance over diesel fuel cost advantages.
- Carbon Intensity Benchmarking:State-owned enterprise power tenders are incorporating lifecycle carbon metrics. Early movers with verified dual-fuel performance capture procurement preference.
- Remote Monitoring Convergence:Integration of IoT sensors with predictive maintenance algorithms enables service contract unbundling. This creates recurring revenue streams separate from equipment sales.
Industry Challenges
- Emissions Calibration Expertise Gap:Tier-3 compliance requires specialized combustion tuning capabilities. Talent scarcity in this function extends product development cycles.
- CCC Certification Timeline Compression:SAMR review periods for new engine platforms lag behind product refresh cycles. Delayed market entry erodes first-mover advantage in fast-moving segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Generator Sets Market |
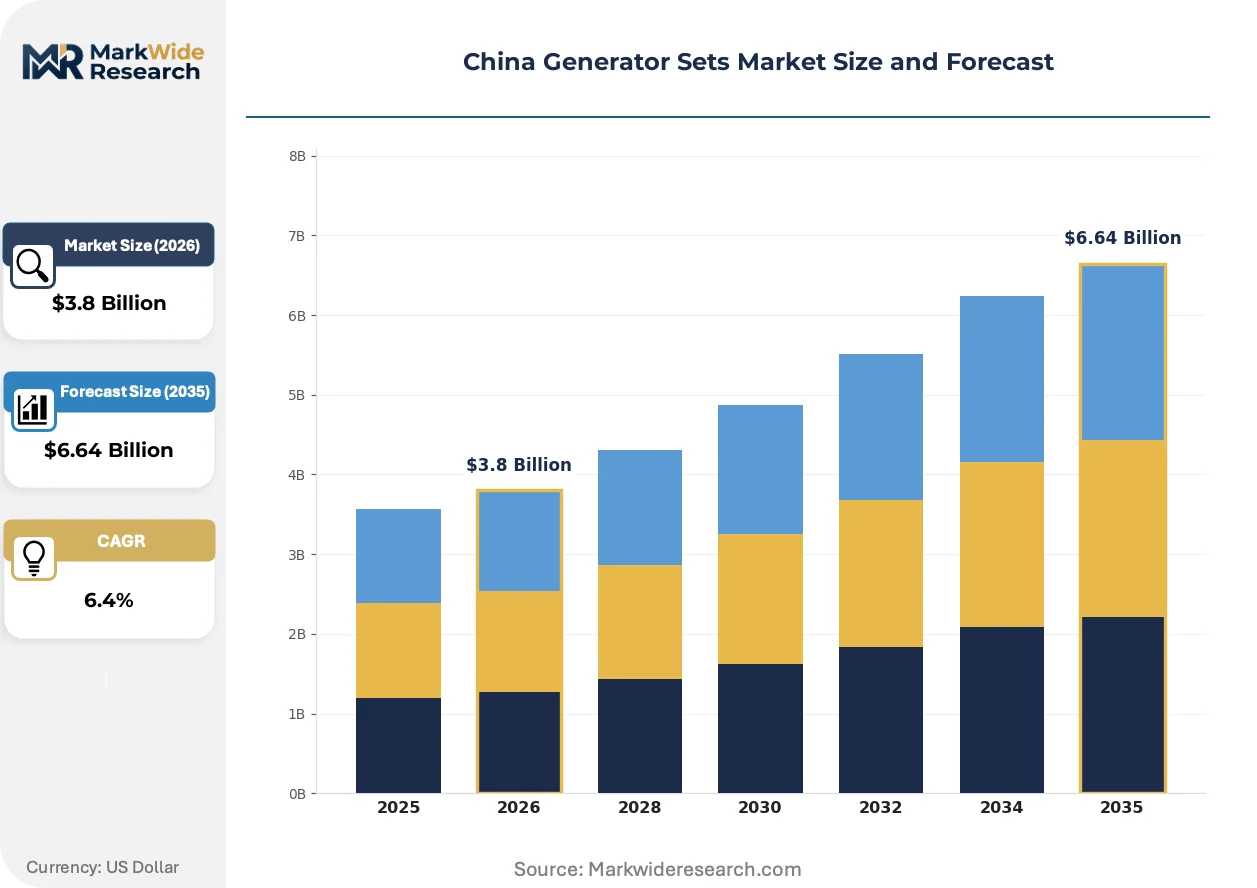
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Diesel Generator, Gas Generator, Dual Fuel Generator, Portable Generator Power Rating: Below 100 kVA, 100-300 kVA, 301-500 kVA, Above 500 kVA Deployment: Stationary, Mobile, Trailer-Mounted, Containerized End User: Industrial, Commercial, Residential, Healthcare |
| Companies Covered | Perkins (Wuxi), SDEC, Cummins (China), Yangdong, Deutz (Dalian), Weichai, FAWDE, Quanchai, Yuchai, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Generator Sets Market Strategic Shifts
Power electronics integration and emission control sophistication are redefining competitive advantage across China's generator set value chain. Technology trajectories favor players with captive semiconductor sourcing and combustion calibration expertise.
Silicon carbide power modules are replacing traditional IGBT inverters in premium alternator designs. Data center operators with sub-15-minute backup requirements are adopting these units fastest. The technology is miniaturizing thermal management footprints while sustaining harmonic distortion targets.
MIIT's dual carbon goals are tightening GB 20891 enforcement timelines for non-road engines. Industrial standby fleets face accelerated retrofit mandates in coastal provinces. Healthcare and commercial segments in Shanghai and Beijing are responding with gas-diesel hybrid procurement.
Buying committees now unbundle equipment procurement from long-term service contracts. State-owned enterprises and hyper-scale data centers are driving this shift. The Yangtze River Delta manufacturing corridor shows the most visible adoption of outcome-based maintenance agreements over traditional warranty structures.
China Generator Sets Market Segmentation
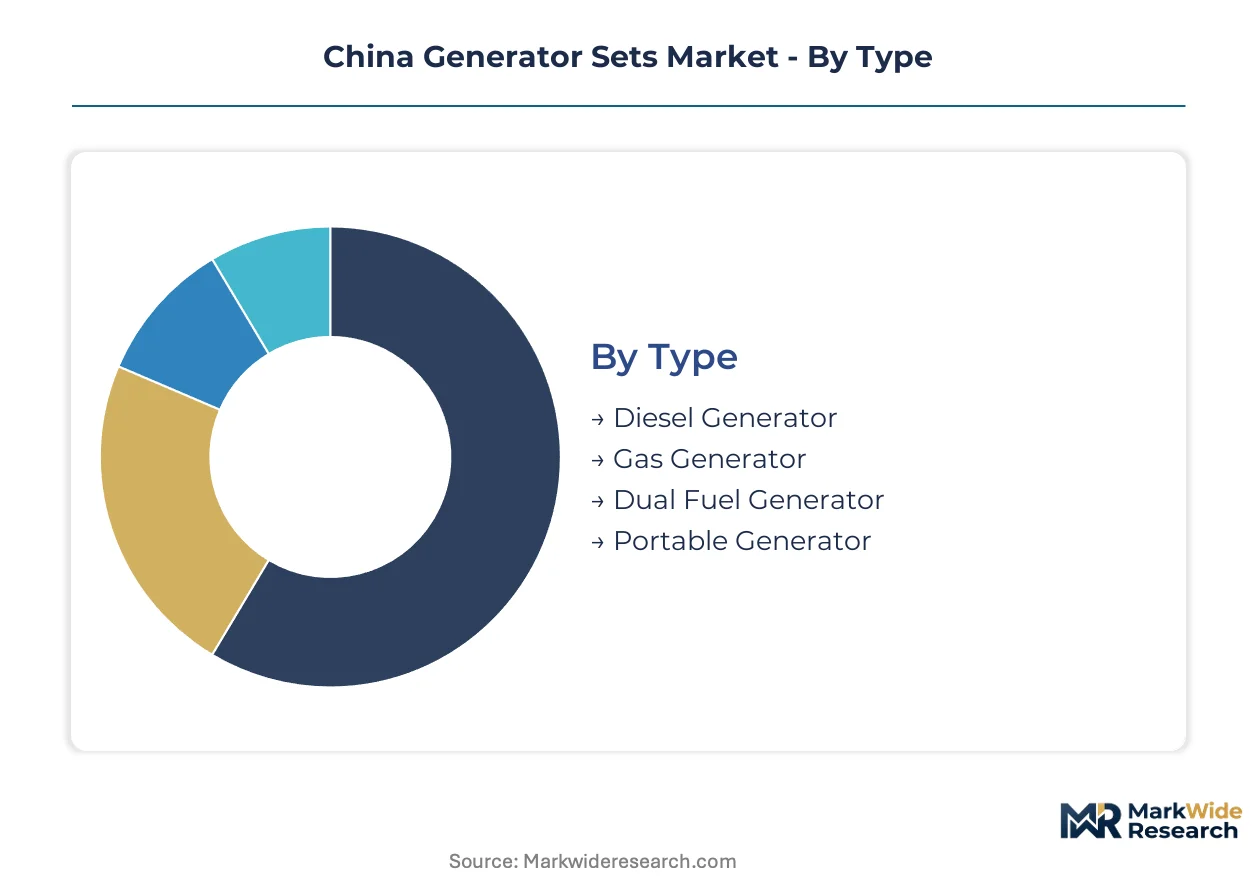
Generator set procurement in China fragments across fuel technology, scale thresholds, physical configuration, and end-use risk profiles. Each segmentation axis carries distinct margin structures and regulatory exposure that reshape competitive positioning.
Type:
Margin pools concentrate in configurations that balance emission compliance with fuel flexibility.
- Diesel Generator:Reciprocating compression-ignition engines dominate prime and standby applications across manufacturing corridors. Demand clusters in Yangtze River Delta industrial parks where grid reliability fluctuates seasonally.
- Gas Generator:Spark-ignited natural gas engines deliver lower particulate output for urban healthcare and commercial installations. Shanghai hospitals accelerate procurement ahead of municipal air quality enforcement timelines.
- Dual Fuel Generator:Compression-ignition platforms with gas substitution capability address MIIT's dual carbon compliance pathways.
- Portable Generator:Lightweight single-phase units serve construction sites and rural electrification with minimal installation infrastructure.
The dominant share belongs to Diesel Generator, while Gas Generator is closing the gap fastest.
Power Rating:
Unit economics invert across the rating spectrum, with customization intensity and service attach rates expanding above 300 kVA.
- Above 500 kVA:Synchronous machines with wound-field or permanent magnet excitation anchor hyperscale data center backup arrays. Beijing and Shanghai operators specify containerized architectures with 15-minute ride-through capability.
- 301-500 kVA:Mid-range industrial standby units balance capital efficiency against load-following flexibility for manufacturing campuses.
- 100-300 kVA:Compact footprint designs serve commercial building basements with constrained mechanical space.
- Below 100 kVA:Single-phase or small three-phase sets address residential and light commercial applications with intermittent duty cycles.
Above 500 kVA commands the deepest margin pools, while Below 100 kVA faces permanent magnet alternator substitution pressure.
Deployment:
Physical configuration determines transport logistics, acoustic treatment requirements, and service contract bundling potential.
- Containerized:ISO-dimensioned enclosures integrate fuel tanks, switchgear, and thermal management for rapid site deployment. Data center operators in Shanghai specify these for 500 kVA-plus installations with 10-year service agreements.
- Stationary:Skid-mounted open or canopy configurations anchor permanent industrial installations with dedicated foundation requirements.
- Trailer-Mounted:Highway-towable platforms with integrated fuel capacity serve emergency response and construction mobility needs.
- Mobile:Compact wheeled units prioritize maneuverability over runtime duration for event power and temporary maintenance coverage.
Stationary deployments retain volume leadership, though Containerized configurations are expanding most quickly in coastal data center clusters.
End User:
Procurement sophistication varies sharply across buyer types, with state-owned enterprises and hyperscale operators driving specification escalation.
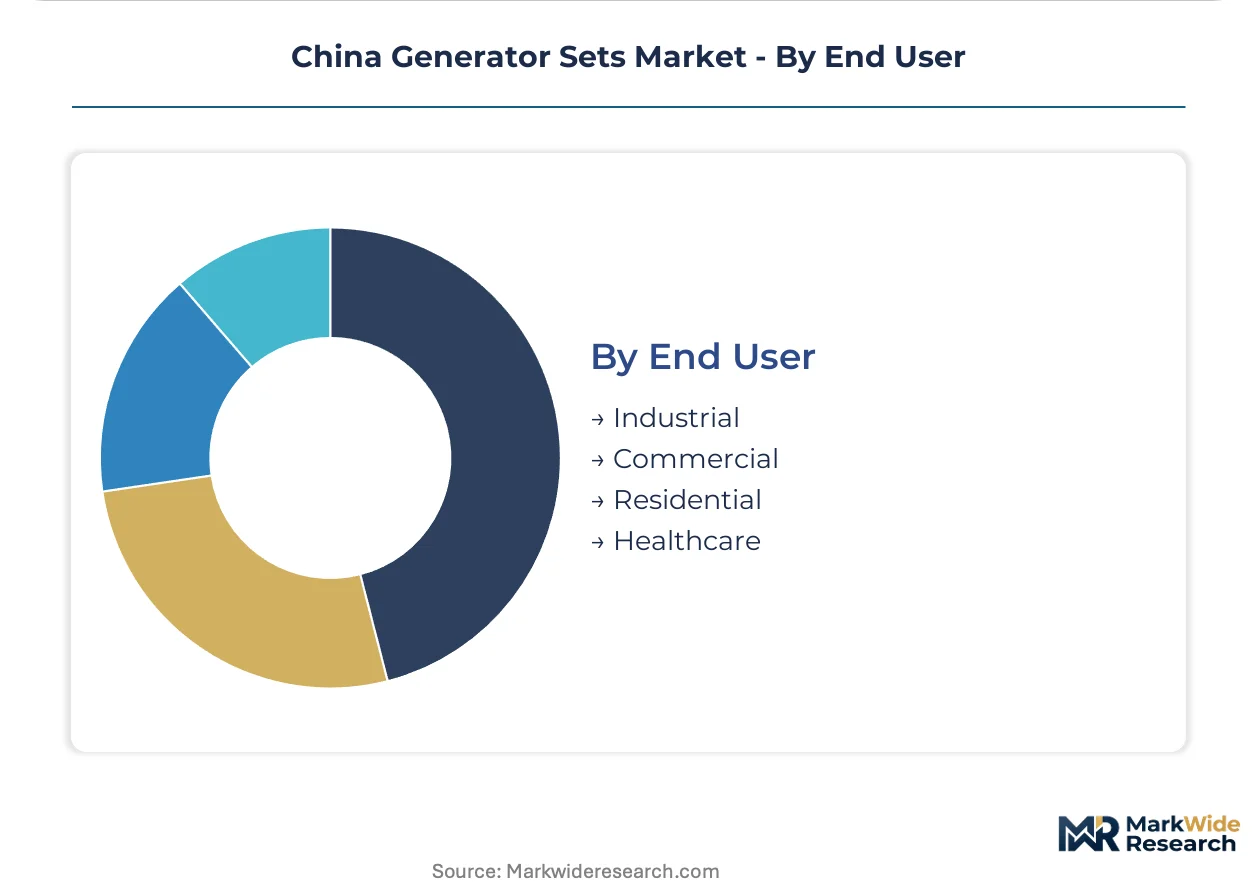
- Industrial:Manufacturing campuses in Jiangsu and Guangdong provinces specify prime power ratings with 8,000-hour annual duty cycles. Dual fuel retrofit mandates from MEE provincial bureaus are redirecting capital allocation toward gas compatibility.
- Healthcare:Hospital infrastructure demands sub-10-second start capability and 72-hour fuel autonomy for life safety loads. Beijing municipal regulations now require Tier-3 emission compliance for new installations.
- Commercial:Office complexes and retail centers prioritize acoustic attenuation and footprint minimization over fuel efficiency metrics.
- Residential:Single-family and small multi-family backup needs concentrate in tier-two cities with unreliable grid distribution infrastructure.
Industrial buyers absorb the highest absolute volume, while Healthcare is gaining share fastest under tightening urban emission protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across China's industrial geography. Yangtze River Delta buyers prioritize uptime reliability over unit economics, while inland provinces weigh capital efficiency more heavily in procurement decisions.
Yangtze River Delta
Hyperscale data center operators in Shanghai and Jiangsu drive demand for containerized units above 500 kVA. MEE provincial bureaus enforce accelerated dual fuel retrofit timelines for existing standby fleets. Suzhou and Hangzhou manufacturing corridors concentrate procurement for prime power applications with 8,000-hour annual duty cycles.
Pearl River Delta
Healthcare infrastructure in Guangzhou and Shenzhen shifts procurement toward gas generator configurations ahead of municipal air quality deadlines. SAMR-administered CCC certification gates elevate technical barriers for imported equipment. Dongguan industrial parks anchor mid-range stationary deployments for electronics manufacturing campuses.
Beijing-Tianjin-Hebei
State-owned enterprise power tenders incorporate lifecycle carbon intensity benchmarks that favor verified dual-fuel performance. Beijing municipal regulations now mandate Tier-3 emission compliance for new hospital installations. Tianjin port logistics clusters absorb trailer-mounted units for emergency response and temporary maintenance coverage.
Shandong Peninsula
Captive casting and machining capacity insulates domestic manufacturers from steel and copper commodity volatility. MIIT's GB 20891 enforcement compresses development cycles for sub-500 kVA diesel platforms. Weifang and Qingdao anchor cost-competitive production for mobile and trailer-mounted categories.
Sichuan-Chongqing
Western infrastructure projects drive demand for portable generators in rural electrification and construction applications. Local grid reliability fluctuations seasonally boost standby procurement for manufacturing facilities. Chongqing's automotive supply chain concentrates demand for compact footprint designs in constrained mechanical spaces.
China Generator Sets Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. The market consolidates around engine platform control and captive manufacturing capacity rather than pure brand equity. Three archetypes dominate: multinational joint ventures with localized engine platforms, domestic champions with backward-integrated casting operations, and regional specialists in mobile configurations. Competitive moves center on dual fuel R&D redirection and service contract unbundling for recurring revenue capture.
Among multinational joint ventures, Perkins (Wuxi), Cummins (China), and Deutz (Dalian) occupy positions that exemplify technology-forward positioning through localized engine platforms. These entities represent the premium stationary segment where emission compliance and extended service agreements determine procurement outcomes. Domestic champions including Weichai, Yuchai, and SDEC anchor cost-competitive supply through in-house production of critical castings and machining operations. Yangdong and Quanchai sit within the mobile-specialist tier, where lighter powertrain architectures address weight-sensitive applications. FAWDE exemplifies the mid-market position balancing fuel flexibility with manufacturing scale.
| Leading Market Players |
|---|
| Perkins (Wuxi) |
| SDEC |
| Cummins (China) |
| Yangdong |
| Deutz (Dalian) |
| Weichai |
| FAWDE |
| Quanchai |
| Yuchai |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day engine block lead times from Shandong foundries concentrate pricing power with domestic manufacturers holding captive casting capacity, while commodity volatility in copper windings and silicon steel compresses margins for assembly-only players lacking upstream integration.
Pricing Analysis
Extended service contracts and predictive maintenance subscriptions now drive lifetime value capture above equipment margins. Three-tier pricing structure across premium, standard, and economy levels stratifies by emission certification tier and dual-fuel capability. Cost compression in sub-500 kVA diesel units intensifies as MIIT Tier-3 compliance eliminates non-compliant competitors. Industrial buyers in Jiangsu manufacturing corridors show lowest price sensitivity, while inland construction contractors purchasing portable units exhibit highest elasticity.
Supply Chain Analysis
China anchors engine block casting and alternator winding production, while Japan and Germany supply precision fuel injection systems and silicon carbide power modules. The value chain draws from copper magnet wire, laminated silicon steel, and emissions-grade catalyst substrates. Single-source vulnerability concentrates in high-pressure common rail fuel systems from Bosch and Denso. Distribution runs through Yangtze River Delta OEM service depots and provincial machinery distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's generator sets market sits in cyclical recovery as data center construction in Shanghai and Beijing restarts backup power procurement programs deferred during prior capital rationing cycles.
For Market Incumbents: Consolidate around dual-fuel R&D platforms and captive foundry capacity to defend against emerging gas-generator specialists. Lock in 10-year service contracts with hyperscale data center operators before procurement committees unbundle equipment from maintenance. Prioritize CCC certification pipeline acceleration to outpace SAMR review delays eroding first-mover advantage. For New Entrants and Emerging Players: Differentiate on lightweight permanent magnet alternator architectures for mobile and trailer-mounted segments where Yangdong and Quanchai hold weaker IP positions. Target Sichuan-Chongqing construction electrification and western infrastructure projects underserved by coastal service networks. Lead with IoT-enabled remote monitoring as a subscription wedge against incumbent warranty bundles. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because emission calibration expertise scarcity and CCC certification barriers will strand sub-scale competitors. Focus acquisition screening on domestic champions with backward-integrated casting operations and verified dual-fuel performance data. Watch MEE provincial bureau enforcement timelines as the inflection signal for gas-generator share acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Fuel Platform Development | MIIT carbon goals redirect R&D spending toward gas-diesel hybrid architectures with verified substitution ratios. |
| Captive Foundry Capacity Expansion | Shandong-based casting and machining insulates Weichai from steel commodity cycles compressing competitor margins. |
| Predictive Maintenance Service Launch | IoT sensor integration enables outcome-based contracts unbundled from equipment sales for recurring revenue capture. |
| CCC Certification Fast-Track Investment | SAMR review period compression accelerates market entry for localized engine platforms against import-dependent rivals. |
| Healthcare Segment Gas Migration | Beijing and Shanghai municipal air quality rules open procurement preference for spark-ignited natural gas configurations. |
Study Parameters
Cross-validation between primary interviews and secondary data sources anchors the qualitative findings in this analysis. Conversations with data center infrastructure directors, industrial plant engineers, OEM procurement managers, and aftermarket service heads informed demand-side dynamics. These insights were validated against MIIT regulatory filings, SAMR certification databases, customs trade records, and provincial MEE enforcement notices. Bottom-up unit economics and top-down macroeconomic indicators were reconciled through iterative triangulation.
Sensitivity analysis around steel and copper price scenarios, emission enforcement timelines, and data center capex cycles stress-tested projection robustness. The analytical framework segments by fuel technology, power rating threshold, deployment configuration, and end-use risk profile across the modeling period. CAGRs were derived from installed base growth, replacement cycle acceleration, and share shift assumptions. Forecast inputs incorporated GB 20891 compliance cost curves and dual-fuel retrofit penetration curves by coastal province.
Material uncertainties — commodity volatility, SAMR certification delays, and MEE enforcement acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory trajectory and technology substitution rates that may shift with policy announcements. Recalibration cycles align with material shifts in MIIT emission tier announcements and provincial MEE mandate timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Diesel Generator Market
Generators
India Generator Sets Market
Generators
Residential Gas Generator Market
Generators
Europe Turbo Generator Market
Generators
Wind Power Generators Market
Generators
Gas Generator Market
Generators
Asia-Pacific Portable Generator Market
Generators
North America Gasoline Gensets Market
Generators
Turbo Generator Market
Generators
Middle East and Africa Gas Generator Market
Generators
Digital Inverter Generator Market
Generators
Asia-Pacific Diesel Generator Market
Generators
Emergency Power Generators Sales Market
Generators
Electric Generators Market
Generators
Middle East Portable Generator Market
Generators
Generator [Up to 100 Kva] Market