
 South America and Africa Diesel Generator Market | 2026-2036
South America and Africa Diesel Generator Market Size, Share, and Industry Trends Forecast 2026-2036
South America and Africa Diesel Generator Market Outlook
South Africa's Eastern Cape manufacturing expansion is reshaping regional supply dynamics for diesel generator deployment. Caterpillar Inc. leverages its extensive dealer network across sub-Saharan mining corridors. Cummins Inc. anchors aftermarket parts availability through localized assembly partnerships. Aggreko PLC competes on rental fleet flexibility for remote oil and gas projects.
Diesel generators are internal combustion engine systems converting diesel fuel into electrical energy through electromagnetic induction, typically operating at 50 Hz or 60 Hz with output voltages from 220V to 11kV depending on application scale. These units provide primary or emergency power for industrial, commercial, and institutional facilities where grid connectivity is unreliable or absent. Standby-rated systems dominate revenue pools across healthcare and data center applications where regulatory uptime requirements are strictest. Portable units represent the fastest-growing configuration in construction end-use, driven by modular infrastructure projects requiring mobile power distribution. Prime and continuous-rated segments above 500 kW sustain margin concentration in oil and gas extraction zones.
Brazil's ANEEL reliability standards, South Africa's Department of Mineral Resources and Energy emission guidelines, and Nigeria's SON product certification requirements collectively shape equipment specifications and import compliance pathways. South Africa's NERSA licensing framework for embedded generation is accelerating hybrid diesel-solar configurations in commercial installations. Stakeholders must monitor evolving carbon border adjustments and local content rules that will determine supplier qualification and project economics across both continents.
Market Dynamics
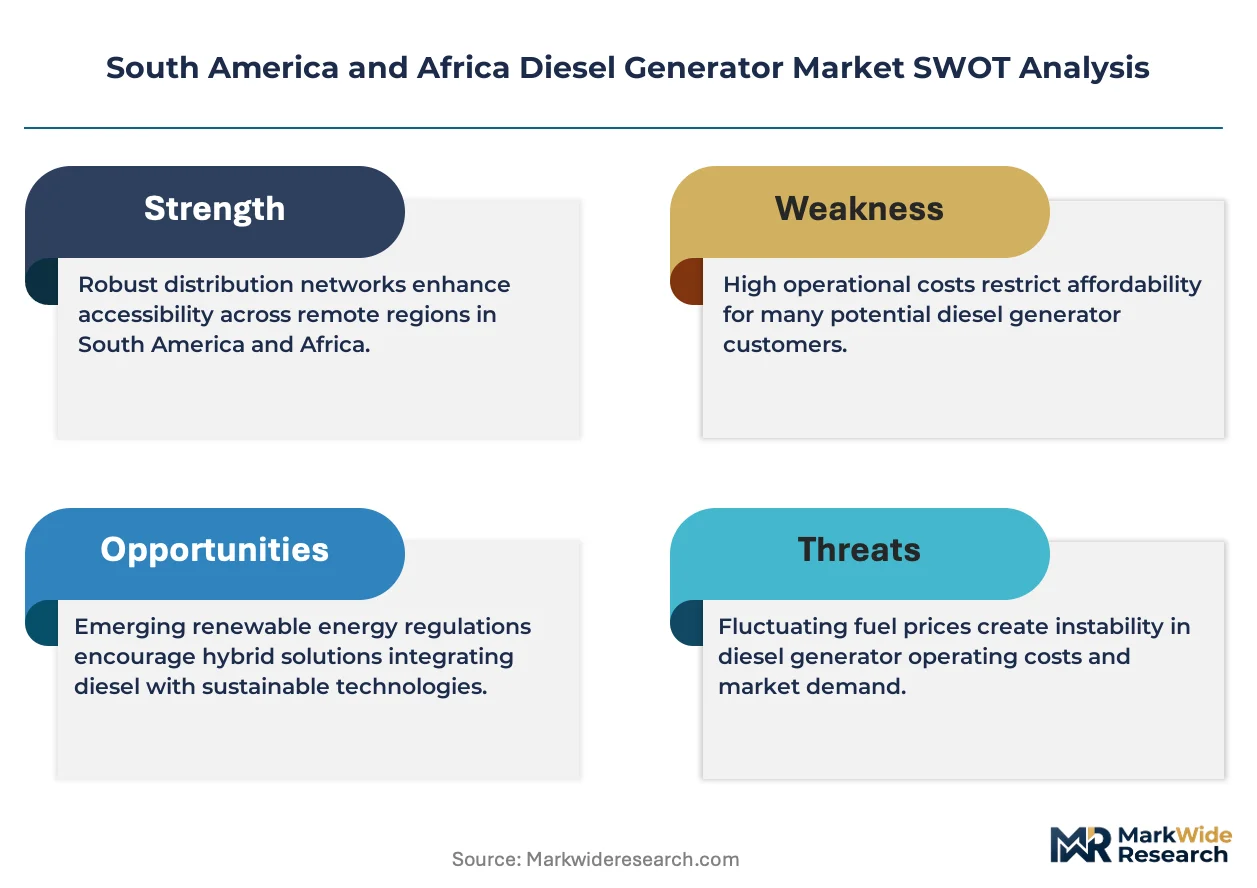
Grid instability across South Africa's Eskom network and Brazil's distribution bottlenecks is forcing industrial buyers toward captive power solutions. Mining houses and data center operators now treat diesel generation as infrastructure-critical rather than backup-only, reshaping procurement specifications and maintenance contracts.
Growth Catalysts
- Load-shedding mandates:South Africa's NERSA embedded generation licensing reforms enable commercial hybrid installations. Industrial parks in Gauteng and KwaZulu-Natal accelerate diesel-solar pairing approvals.
- Copper belt extraction:Zambia's North-Western Province and Chile's Atacama Desert anchor prime-rated generator deployment. Underground and open-pit operations require 24/7 power reliability unavailable from national grids.
- Healthcare infrastructure:Nigeria's federal hospital electrification program specifies standby-rated units for surgical theaters. Lagos and Abuja medical districts drive tier-1 certification demand.
Market Restraints
- Diesel price volatility:Pump price fluctuations in Angola and Nigeria compress operator margins. Fuel subsidy removals in Ghana and Kenya amplify total cost of ownership uncertainty.
- Emission compliance layering:South Africa's Department of Mineral Resources and Energy guidelines impose tiered exhaust standards. Retrofit costs for existing fleets deter small-scale rental operators.
- Battery substitution:Lithium-ion storage paired with solar PV displaces sub-100kW diesel units in Nigerian telecom towers. MTN and Airtel tower portfolios shift procurement toward battery-dominant configurations.
Strategic Opportunities
- Hybrid convergence:Diesel-PV-battery integration opens margin expansion in South African commercial real estate. Cape Town and Johannesburg office developments specify synchronized controllers for seamless switching.
- Angola's logistics corridors:Lobito Corridor rail and port electrification lacks grid extension timelines. Construction-phase power contracts favor mobile rental fleets over permanent installation.
- ANEEL reliability incentives:Brazil's regulatory framework penalizes distribution utilities for outage duration. Industrial customers in São Paulo and Minas Gerais states qualify for tariff rebates when maintaining certified backup systems.
Industry Challenges
- Technician certification gaps:Factory-trained service engineers for electronic engine management systems concentrate in Johannesburg and São Paulo. Remote site maintenance delays extend mean time to repair in Mozambique's gas fields.
- Import documentation complexity:Nigeria's SON product certification requires in-country testing for each generator model. Lagos port clearance timelines stretch 8-14 weeks, compressing project delivery windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America and Africa Diesel Generator Market |
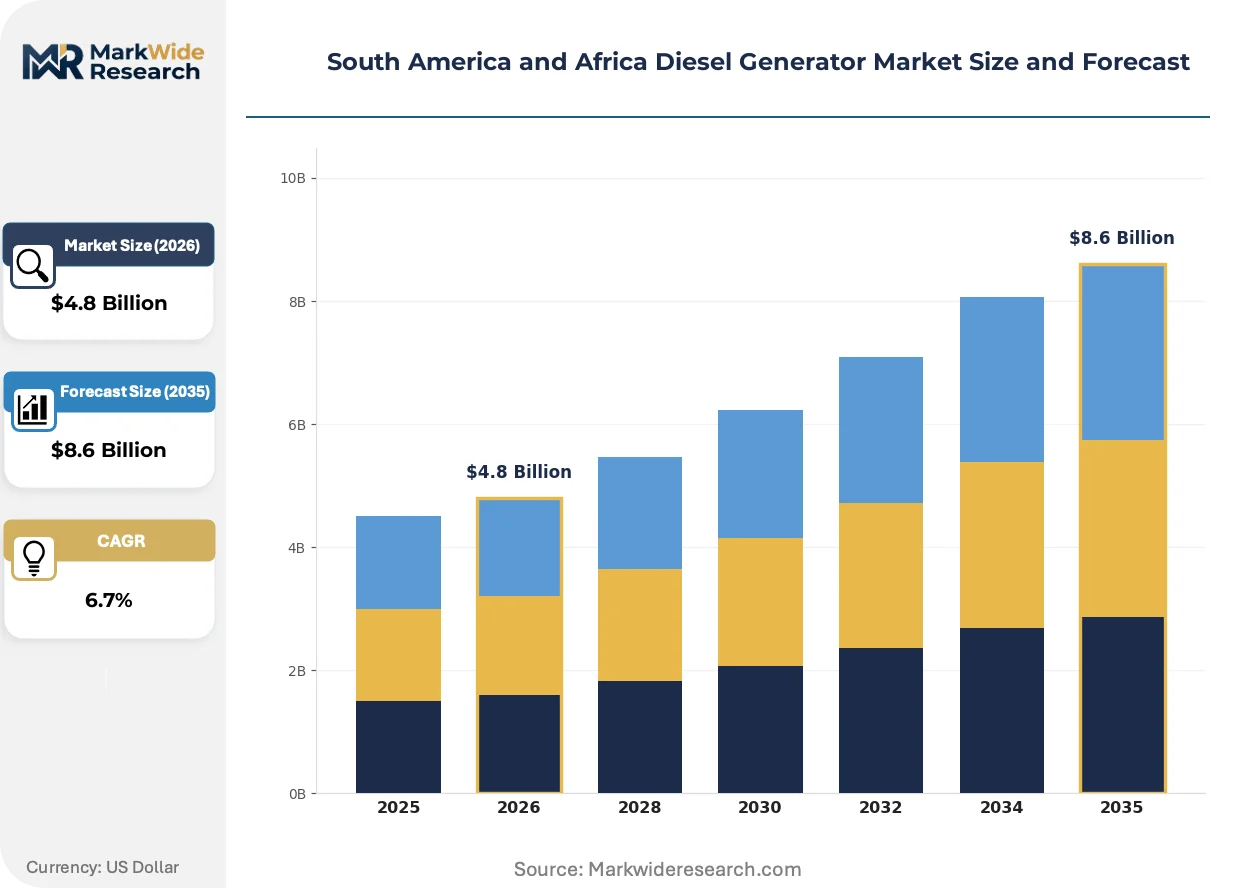
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Standby, Prime, Continuous End User: Construction, Oil & Gas, Healthcare, Manufacturing Power Rating: Up to 100 kW, 101 kW to 200 kW, 201 kW to 500 kW, Above 500 kW Fuel Type: Diesel, Biofuel, Natural Gas, Others |
| Companies Covered | Kohler Co, MTU Onsite Energy, Caterpillar Inc., AKSA Power Generation, Aggreko PLC, Cummins Inc., Generac Holdings Inc., Mikano International, Atlas Copco AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America and Africa Diesel Generator Market Strategic Shifts
Diesel generator architecture is fragmenting across three vectors: fuel flexibility, control system intelligence, and ownership models. Equipment suppliers and energy service companies are repositioning around integrated power-as-a-service offerings rather than standalone hardware sales.
Dual-fuel retrofit kits enabling diesel-natural gas blending are hybridizing combustion systems for cost-sensitive operators. Brazilian sugar-ethanol processors and South African petrochemical plants pilot these configurations to hedge diesel price exposure. The technology is hybridizing procurement criteria, forcing suppliers to certify engines for variable fuel quality across African supply chains.
Brazil's ANEEL grid reliability standards now mandate documented backup power continuity plans for critical infrastructure classification. Data centers and financial clearing houses in São Paulo face audit requirements for generator testing frequency and fuel storage duration. Healthcare networks in Rio de Janeiro and Brasília respond by consolidating maintenance contracts under specialized energy service providers.
Rental fleet operators are unbundling long-term power service agreements from equipment ownership. Mining contractors in Chile's Antofagasta Region and oil services firms in Nigeria's Niger Delta prefer operating leases with bundled fuel supply and 24/7 remote monitoring. This restructuring concentrates working capital requirements with lessors while transferring operational risk to specialized providers.
South America and Africa Diesel Generator Market Segmentation
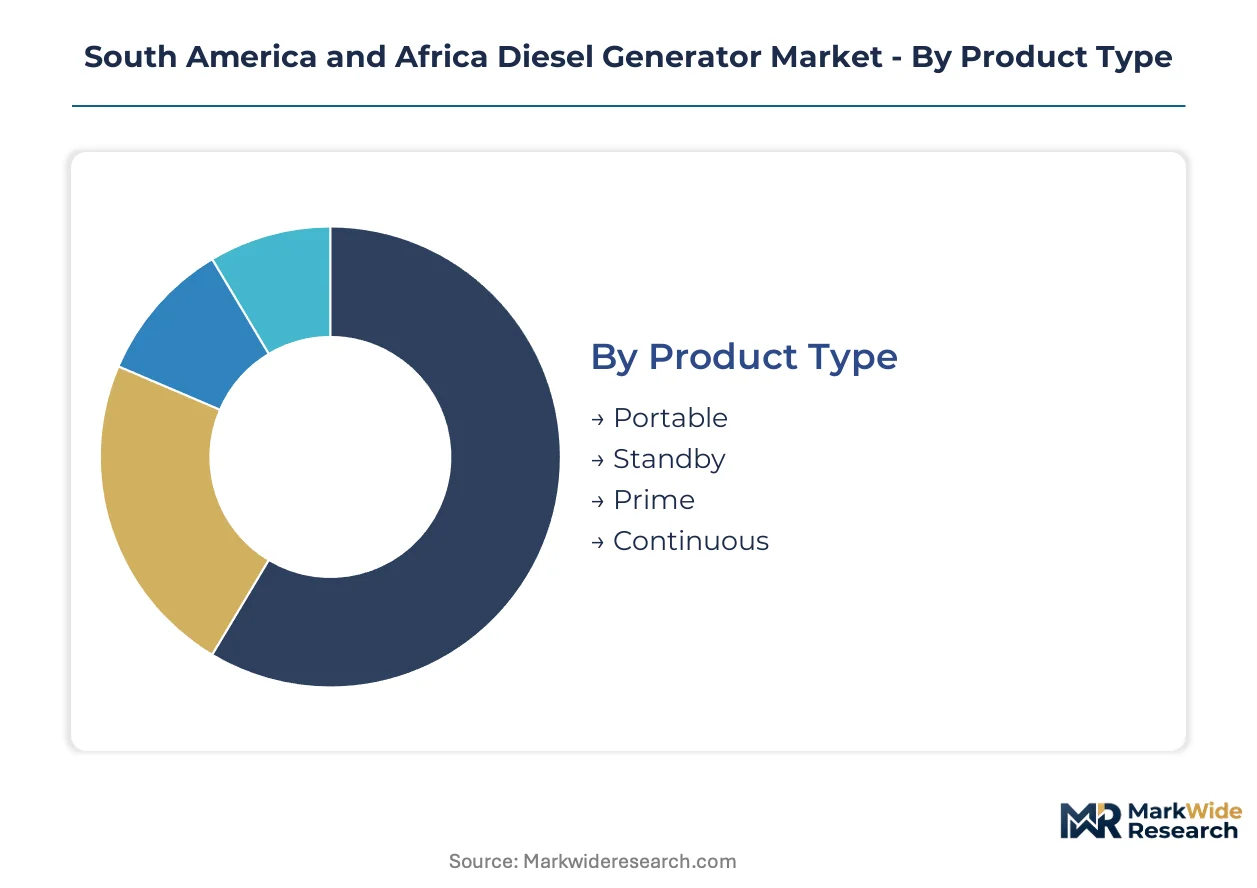
Diesel generator procurement across South America and Africa fragments sharply by duty cycle and fuel availability. Equipment specifications diverge between mining corridors requiring continuous-rated systems and urban commercial installations prioritizing standby certification. Understanding these segment boundaries clarifies margin concentration and aftermarket service intensity for suppliers.
Product Type:
After-sales-service intensity varies dramatically across duty cycles, with continuous-rated units demanding dedicated technician contracts and remote monitoring infrastructure.
- Portable:Compact skid-mounted or trailer-towed units deploy rapidly to construction sites and temporary events. Brazilian infrastructure contractors in São Paulo's urban renewal zones favor these for phased power distribution across dispersed work fronts.
- Standby:Automatic-start systems activate within 10 seconds of grid failure, sized for critical loads in hospitals and data centers. Nigeria's Lagos medical district mandates these for surgical theaters under federal hospital electrification guidelines.
- Prime:Designed for indefinite operation as primary power where grid extension is uneconomical. Zambia's North-Western Province copper mines specify these for 24/7 extraction operations beyond national grid reach.
- Continuous:Base-load rated for unlimited annual hours at constant load. Chile's Atacama Desert lithium extraction ponds and Angola's offshore oil platforms require these for process-critical refrigeration and pumping.
Standby holds the largest share; momentum sits with portable configurations.
End User:
Application-specific certification requirements reshape procurement patterns across verticals with diverging uptime mandates.
- Construction:Mobile power for earthmoving, concrete batching, and site lighting dominates rental fleet deployment. South Africa's Eastern Cape manufacturing expansion drives demand for modular generator arrays that relocate between project phases.
- Oil & Gas:Explosion-proof enclosures and offshore corrosion ratings command premium pricing. Nigeria's Niger Delta production facilities specify continuous-rated units with Class I Division 2 certification for hazardous atmosphere operation.
- Healthcare:Life-safety electrical codes mandate dual-start capability and 72-hour fuel autonomy. Brazil's ANEEL reliability standards now require documented testing protocols for hospital backup systems in Rio de Janeiro and Brasília.
- Manufacturing:Voltage stability and harmonic distortion tolerance protect sensitive production lines. Gauteng industrial parks in South Africa accelerate hybrid diesel-solar approvals under NERSA embedded generation licensing reforms.
Manufacturing captures the deepest installed base; healthcare is expanding most quickly on regulatory tailwinds.
Power Rating:
Unit economics and service contract structures shift meaningfully across kilowatt thresholds, with larger systems consolidating under specialized energy service providers.
- Up to 100 kW:Single-phase and small three-phase units serve retail, telecom, and residential backup. MTN and Airtel tower portfolios in Nigeria are displacing these with lithium-ion battery dominance.
- 101 kW to 200 kW:Mid-range commercial systems balance capital efficiency against load coverage. Cape Town office developments specify these for synchronized hybrid controllers with rooftop solar.
- 201 kW to 500 kW:Industrial-grade units with paralleling capability support manufacturing and mid-scale mining. Chile's Antofagasta Region contractors favor rental configurations in this band for workforce camp electrification.
- Above 500 kW:Containerized or skid-mounted high-voltage systems anchor prime power for extraction industries. Angola's Lobito Corridor rail construction awards mobile rental contracts in this tier for earthmoving equipment fleets.
Above 500 kW commands the steepest margin concentration; sub-100 kW faces the sharpest battery substitution pressure.
Fuel Type:
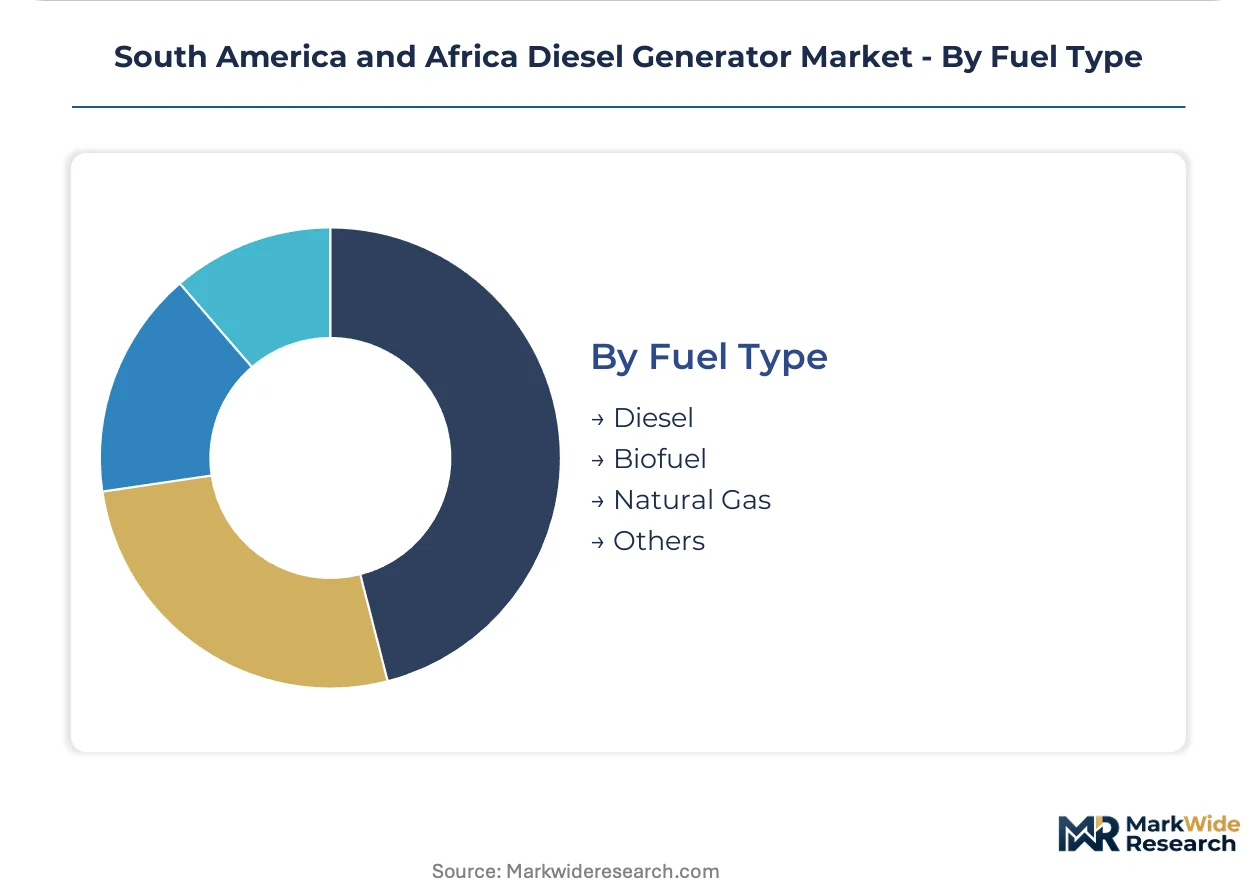
Supply chain reliability and price hedging strategies fragment procurement across combustion chemistries, with dual-fuel flexibility gaining traction in cost-sensitive operations.
- Diesel:Standard distillate fuel with established distribution infrastructure across both continents. Pump price volatility in Angola and Nigeria compresses operator margins and extends total cost of ownership uncertainty.
- Biofuel:Biodiesel blends and pure vegetable oil systems serve sustainability mandates and agricultural proximity advantages. Brazilian sugar-ethanol processors pilot these configurations to hedge diesel exposure.
- Natural Gas:Pipeline or compressed delivery where infrastructure exists, with dual-fuel retrofit kits enabling blending. South African petrochemical plants test these systems for variable fuel quality tolerance.
- Others:LPG, kerosene, and synthetic fuels for specialized applications or emergency stockpiling. Remote mining camps in Mozambique's gas fields maintain these as contingency against diesel supply interruption.
Diesel retains dominant share; natural gas is gaining share fastest on dual-fuel retrofit adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Generator assembly and distribution concentrate in South Africa's industrial corridors and Brazil's manufacturing zones, with mining-driven demand radiating into Zambia, Chile, and Angola. National regulatory frameworks diverge sharply on emission standards and import certification timelines.
Brazil
ANEEL reliability mandates penalize distribution utilities for outage duration, compelling São Paulo and Minas Gerais industrial customers to maintain certified backup systems. Sugar-ethanol processors in São Paulo state pilot dual-fuel diesel-natural gas configurations to hedge fuel price exposure. Urban renewal zones across Greater São Paulo deploy portable generator arrays for phased construction power.
South Africa
Eskom load-shedding and NERSA embedded generation licensing reforms accelerate hybrid diesel-solar approvals in Gauteng and KwaZulu-Natal industrial parks. The Department of Mineral Resources and Energy imposes tiered exhaust standards that raise retrofit costs for rental operators. Eastern Cape manufacturing expansion reshapes regional supply dynamics for prime-rated unit deployment.
Nigeria
Lagos-Ibadan industrial corridor concentration drives demand for prime-rated units where grid extension remains uneconomical. SON product certification requires in-country testing per generator model, stretching Lagos port clearance timelines to 8-14 weeks. Federal hospital electrification programs mandate standby-rated systems for surgical theaters in Lagos and Abuja medical districts.
Zambia
North-Western Province copper belt extraction anchors continuous-rated generator deployment for 24/7 underground and open-pit operations. National grid reliability gaps beyond urban centers force mining houses toward captive power infrastructure. Technician certification scarcity extends maintenance response times for electronic engine management systems.
Chile
Atacama Desert lithium extraction ponds and Antofagasta Region mining camps require base-load rated systems for process-critical refrigeration and pumping. ANEEL-aligned reliability expectations from multinational operators drive documented backup continuity plans. Workforce camp electrification favors rental configurations in the 201-500 kW band for modular deployment.
South America and Africa Diesel Generator Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream on engine and alternator supply. The market structures around three tiers: full-system providers with rental-service arms, regional assemblers with localized parts stocking, and pure-play lessors with mobile fleet specialization. Consolidation pressure concentrates in the mid-market as energy service companies absorb smaller rental operators. Dominant competitive moves include backward integration into alternator manufacturing and geographic expansion through dealer network acquisition.
Within the full-system integrator tier, Caterpillar Inc. and Cummins Inc. exemplify archetypes of embedded distribution density and aftermarket parts localization respectively. Aggreko PLC occupies a position representing rental fleet flexibility for remote project power. Kohler Co. anchors the premium standby certification segment for healthcare and data center uptime requirements. These three named entities collectively illustrate how competitive positioning fragments across ownership-model specialization rather than hardware differentiation alone.
| Leading Market Players |
|---|
| Kohler Co |
| MTU Onsite Energy |
| Caterpillar Inc. |
| AKSA Power Generation |
| Aggreko PLC |
| Cummins Inc. |
| Generac Holdings Inc. |
| Mikano International |
| Atlas Copco AB |
| Others |
Value Chain & Pricing Dynamics
Engine block casting capacity concentrates in China and India, anchoring cost structures for generator assemblers across São Paulo and Johannesburg industrial corridors. This upstream concentration transfers pricing power to integrated foundry-alternator suppliers while compressing margins for pure-play rental operators dependent on spot procurement.
Pricing Analysis
ANEEL reliability mandates dictate the pricing tier structure across Brazilian industrial markets, separating certified backup systems from uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and fuel efficiency certification tiers. Pricing pressure stems from lithium-ion battery substitution in Nigerian telecom tower applications, forcing diesel rental rates downward in sub-100 kW segments. Construction contractors in Angola's Lobito Corridor exhibit highest price sensitivity, while healthcare networks in Lagos and Abuja medical districts absorb premium tier pricing for life-safety certification.
Supply Chain Analysis
Diesel fuel refining capacity and alternator copper winding feed from South Africa, Brazil, and China shape component availability timelines for regional assemblers. Electronic control module sourcing rests on semiconductor fabrication in Taiwan and Malaysia, creating vulnerability to logistics chokepoints at Durban and Lagos ports. Distribution runs through Caterpillar and Cummins dealer networks across sub-Saharan mining corridors, with independent rental operators consolidating under energy service company umbrellas to secure volume procurement terms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Copper belt extraction cycles and Eskom load-shedding intensity position this market for cyclical recovery as mining capital expenditure resumes and grid instability persists.
For Market Incumbents: Entrench aftermarket parts localization through Johannesburg and São Paulo assembly partnerships, insulating against battery substitution threats in Nigerian telecom infrastructure. Deepen technician certification pipelines for electronic engine management systems to defend service contract renewal rates against emerging energy service company competitors. For New Entrants and Emerging Players: Mid-market hybrid diesel-solar installations in South African commercial real estate represent the most penetrable entry point, with Cape Town and Johannesburg office developments specifying synchronized controllers. Angola's logistics corridor construction-phase power contracts favor mobile rental fleet operators with bundled fuel supply capabilities, offering asset-light market access without permanent installation capital requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed rental fleet operators holding aging prime-rated inventory above 500 kW. Five-to-ten year viability hinges on dual-fuel retrofit adoption rates and carbon border adjustment implementation timelines. Watch NERSA embedded generation licensing velocity as the inflection signal for hybrid configuration demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Retrofit Program | Enables diesel-natural gas blending for Brazilian sugar-ethanol processors hedging fuel price exposure. |
| Hybrid Controller Integration | Synchronizes diesel-PV-battery switching for Cape Town commercial developments under ANEEL reliability mandates. |
| Technician Certification Pipeline | Addresses factory-trained engineer scarcity extending mean time to repair in Mozambique gas fields. |
| Dealer Network Acquisition | Consolidates distribution density across Zambia copper belt corridors for aftermarket parts availability. |
| Rental Fleet Operating Lease Restructuring | Transfers working capital burden to lessors while capturing recurring revenue from Niger Delta oil services firms. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, EIA fuel price series, and ANEEL regulatory filings. Plant engineers at Chilean lithium extraction facilities, aftermarket service heads at Zambian mining contractors, and procurement leads at Nigerian hospital networks provided operational perspective. Bottom-up unit deployment tallies triangulated against top-down energy consumption estimates across the analysis window.
Forecast inputs incorporate duty cycle segmentation, power rating tier penetration, and fuel type substitution elasticities. Modeled dimensions span portable, standby, prime, and continuous-rated configurations alongside construction, oil and gas, healthcare, and manufacturing end-use verticals. CAGRs derive from installed base turnover rates and regulatory-driven replacement cycles, with copper belt extraction intensity and grid reliability indices serving as industry-specific demand drivers throughout the projection horizon.
Stress conditions across diesel price volatility, battery cost decline curves, and emission compliance layering were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding NERSA licensing reform implementation and ANEEL reliability standard enforcement. Quarterly review of copper spot prices, Eskom load-shedding schedules, and lithium-ion battery substitution rates in Nigerian telecom infrastructure is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Asia-Pacific Diesel Generator Market
Generators
Generator [Up to 100 Kva] Market
Generators
Gas Generator Sets Market
Generators
North America Gasoline Gensets Market
Generators
Portugal Gas Generator Market
Generators
Europe Gas Turbine Market
Generators
Gas Generator Market
Generators
Global Portable Generator Market
Generators
Turbo Generator Market
Generators
Emergency Power Generators Sales Market
Generators
Gasoline Generator Market
Generators
Commercial Generator Market
Generators
Middle East and Africa Gas Generator Market
Generators
Dual-Fuel Generator Market
Generators
Construction Generator Sets Market
Generators
United States Diesel Generator Market