
 Global Gensets Market | 2026-2036
Global Gensets Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gensets Market Analysis
Data center power reliability is restructuring procurement patterns across the gensets value chain. Cummins Inc. leverages its integrated power systems portfolio to anchor large-scale data center contracts in North America. Caterpillar Inc. sustains manufacturing scale advantages through captive engine foundries and global dealer networks. Mitsubishi Heavy Industries competes on high-speed diesel technology leadership for mission-critical installations.
Gensets are engine-driven alternator assemblies that convert mechanical energy into electrical power, typically rated from sub-50 kW residential units to multi-megawatt industrial systems operating at 50 Hz or 60 Hz depending on regional grid standards. Their primary purpose is to provide standby, prime, or continuous power where grid supply is unreliable or unavailable. Diesel generators dominate installed base across heavy industrial and telecommunications end users due to fuel energy density and capital cost advantages, while gas generators gain share in commercial and grid-balancing applications where emissions regulations and pipeline access permit. Hybrid generators represent the fastest-growing installation category as battery-genset pairing cuts runtime hours and fuel consumption in variable-load scenarios.
EPA Tier 4 Final mandates selective catalytic reduction and diesel particulate filters on non-road engines above 56 kW, adding cost and complexity that favors suppliers with integrated aftertreatment engineering. EU Stage V and REACH compliance requirements restrict certain engine materials and drive modular product architectures for easier retrofit. India's CEA grid connectivity rules and state-level open access regulations influence whether industrial users deploy gensets for standby or continuous economics. Stakeholders must monitor how carbon border adjustments and local air quality enforcement reshape total cost of ownership calculations across diesel, gas, and hybrid configurations.
Market Dynamics
The gensets market is bifurcating around emissions compliance costs, with EPA Tier 4 Final and EU Stage V aftertreatment requirements forcing capital reallocation toward integrated power system architectures and away from standalone engine-assembled units.
Growth Catalysts
- Data center buildouts:Hyperscale operators in Singapore, Indonesia, and Malaysia are pre-positioning captive generation ahead of grid reliability constraints during monsoon seasons.
- CEA grid connectivity rules:India's Central Electricity Authority mandates dual-source redundancy for critical infrastructure, expanding standby genset deployment across pharmaceutical and semiconductor fabs in Gujarat.
- Hybrid battery-genset pairing:Lithium-ion buffer systems are cutting diesel runtime hours in telecom tower applications, improving total cost of ownership in variable-load scenarios.
Market Restraints
- Platinum group metal costs:Diesel particulate filters and selective catalytic reduction systems rely on palladium and rhodium, exposing OEM margins to South African and Russian supply concentration.
- Natural gas pipeline access gaps:Industrial clusters in Vietnam and the Philippines lack distribution infrastructure, blocking gas generator substitution despite lower emissions profiles.
- Skilled technician scarcity:Aftertreatment diagnostics and urea system maintenance require specialized training that remains concentrated in Tier 1 supplier networks.
Strategic Opportunities
- Carbon border adjustment preparation:EU importers are auditing Scope 1 emissions from captive power, creating retrofit demand for gas and hybrid units in export-oriented Indian textile hubs.
- Microgrid controller integration:Synchronous paralleling and load-sharing algorithms are enabling genset-battery-solar tri-hybrid architectures for islanded industrial parks.
- Secondary market refurbishment:EPA Tier 3 engine cores from North American telecom fleets are being remanufactured for Tier 2-equivalent deployment in African mining operations.
Industry Challenges
- Emissions certification timeline compression:EU Stage V type-approval cycles now exceed 18 months, delaying product launches and freezing engineering resources on regulatory compliance rather than performance innovation.
- Legacy control system interoperability:SCADA integration between 1990s-era genset controllers and modern building management systems requires custom protocol gateways that fragment service provider capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gensets Market |
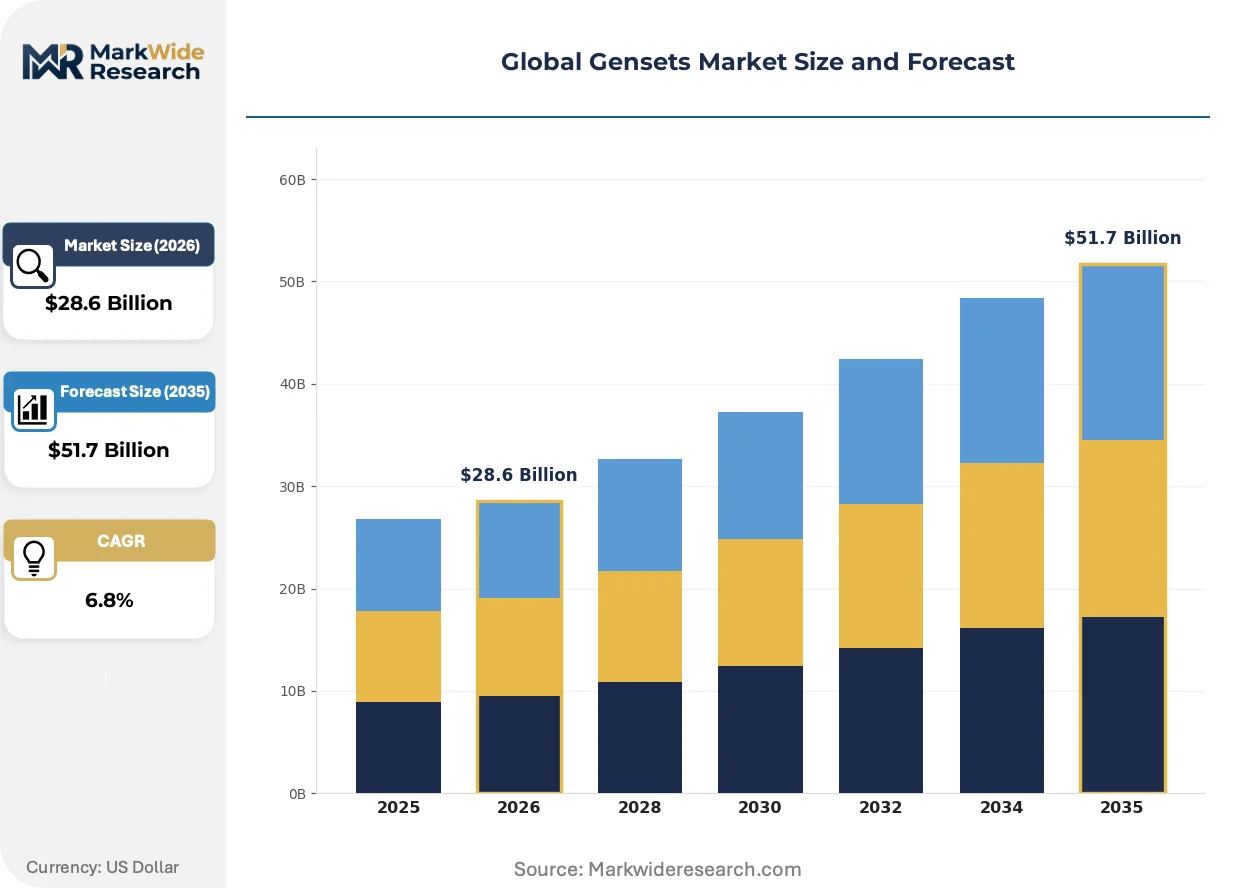
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Diesel Generators, Gas Generators, Hybrid Generators, Bi-Fuel Generators Installation: Portable, Stationary, Mobile, Containerized End User: Residential, Commercial, Industrial, Telecommunications Power Rating: Less than 50 kW, 50-100 kW, 101-250 kW, 251-500 kW |
| Companies Covered | Cummins Inc., Caterpillar Inc., Generac Holdings Inc., Kohler Co., Rolls-Royce Power Systems, Mitsubishi Heavy Industries, Atlas Copco, Himoinsa, Doosan Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gensets Market Emerging Trajectories
Power system architectures are converging around modular, software-defined platforms that decouple generation assets from control logic, compressing equipment procurement cycles and reshaping aftermarket service economics.
Containerized gas turbine gensets rated 20-50 MW are overtaking reciprocating diesel arrays for data center prime power in markets with firm pipeline access. Microsoft and Amazon Web Services procurement teams in Northern Virginia and Frankfurt are specifying aeroderivative packages for 10-minute start reliability. This technology is overtaking traditional medium-speed diesel blocks in applications above 15 MW continuous rating.
EPA Tier 4 Final non-road engine standards now mandate onboard diagnostics with wireless telematics transmission for engines above 56 kW. Rental fleet operators face mandatory compliance deadlines that compress equipment replacement cycles and favor suppliers with integrated telematics platforms. Construction and oilfield services segments in Texas and North Dakota are absorbing premium pricing for certified rental units to avoid work stoppage penalties.
Power-as-a-service contracting is displacing capital purchase models for industrial standby applications. Engineering-procurement-construction firms in Saudi Arabia and the UAE are bundling genset installation, fuel supply, and maintenance under fixed per-kWh tariffs. Manufacturing verticals with volatile production schedules in Jeddah and Dubai are adopting this structure to convert fixed asset exposure to variable operating expense.
Global Gensets Market Segmentation
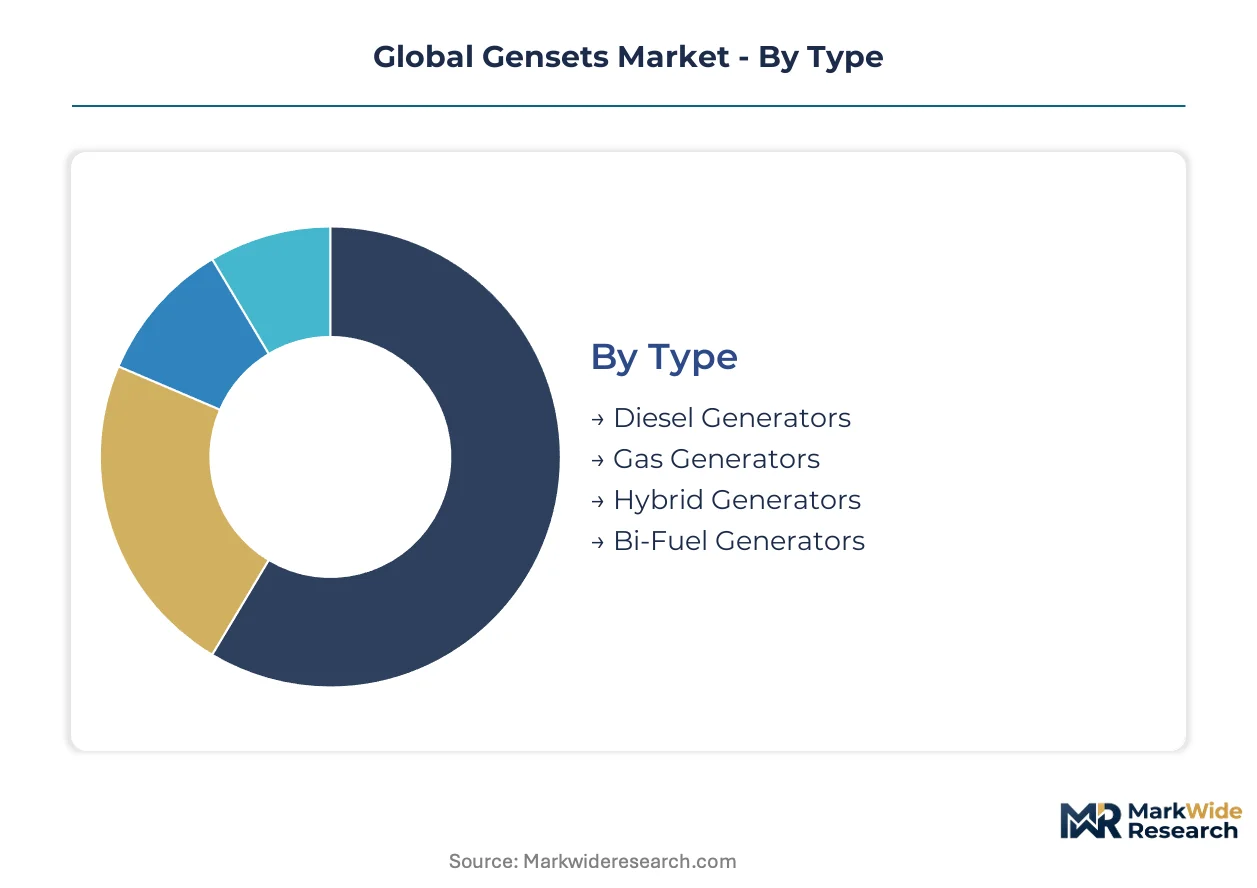
Genset procurement patterns diverge sharply across fuel types, installation formats, and power ratings. Understanding these fault lines reveals where capital is concentrating and which configurations face displacement from emissions regulations and hybrid alternatives.
Type:
Supply concentration favors integrated power system suppliers with captive engine manufacturing and aftertreatment engineering capabilities.
- Diesel Generators:Reciprocating engines burning distillate fuel dominate heavy industrial and mission-critical installations due to energy density and capital cost advantages. Data center operators in Singapore and semiconductor fabs in Gujarat, India rely on diesel blocks for base-load supplementation during grid instability.
- Gas Generators:Spark-ignited or dual-fuel engines running on pipeline natural gas or LNG deliver lower NOx and particulate emissions where distribution infrastructure exists. Commercial buildings in Frankfurt and district heating networks in Northern Virginia specify gas units to meet EU Stage V and EPA Tier 4 Final compliance deadlines.
- Hybrid Generators:Battery-genset pairing cuts runtime hours and fuel consumption in variable-load telecom tower applications across Southeast Asia.
- Bi-Fuel Generators:Engines capable of seamless diesel-to-gas switching provide fuel flexibility in markets with intermittent pipeline access like Vietnam and the Philippines.
Today's leader: Diesel Generators. Tomorrow's challenger: Hybrid Generators.
Installation:
Application requirements dictate form factor selection, with mobility premiums compressing margins for rental fleet operators.
- Stationary:Permanently installed units with concrete foundations and integrated fuel storage serve as prime power for industrial parks and data centers. These configurations command the highest capital investment but lowest lifecycle cost per kWh.
- Containerized:ISO-standard enclosures housing complete power modules enable rapid deployment and simplified logistics for remote mining operations in Australia and African extraction sites.
- Portable:Sub-50 kW wheeled units address residential backup and small commercial applications in storm-prone US Gulf Coast states.
- Mobile:Trailer-mounted systems serve construction and oilfield services segments in Texas and North Dakota facing EPA Tier 4 Final rental fleet compliance deadlines.
Stationary installations anchor revenue. Containerized formats are climbing the fastest.
End User:
Customer type determines reliability requirements, runtime expectations, and service contract structures.
- Industrial:Continuous-duty applications in chemical processing, mining, and manufacturing drive demand for 500+ kW medium-speed diesel blocks with 8,000+ hour annual runtimes.
- Telecommunications:Tower operators across India and Indonesia specify sub-100 kW units with remote monitoring for off-grid and unreliable-grid sites.
- Commercial:Office complexes, hospitals, and retail chains prioritize low-noise enclosures and rapid-start capability for life-safety loads.
- Residential:Single-family backup systems concentrate in hurricane-exposed Florida and Texas markets with mandatory natural gas connection codes.
Industrial buyers command pricing power. Telecommunications represents the steepest expansion trajectory.
Power Rating:
Unit economics and manufacturing scale separate commodity segments from engineered-to-order systems.
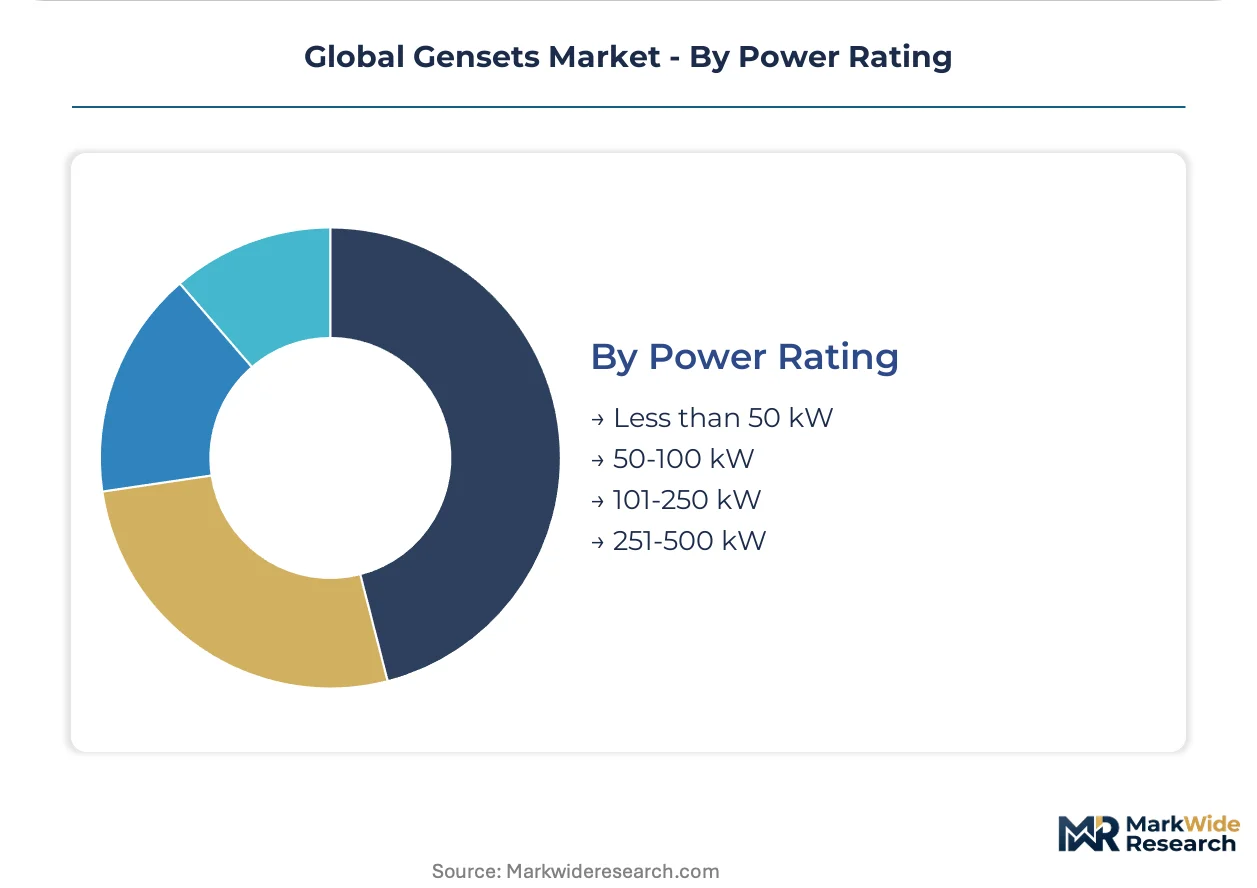
- 251-500 kW:Mid-range industrial units bridge the gap between commercial standby and continuous prime power applications. These configurations dominate pharmaceutical and semiconductor fab deployments in Gujarat and Tamil Nadu under India's CEA grid connectivity rules.
- Less than 50 kW:Single-phase residential and small commercial units compete on distributor network density and aftermarket parts availability.
- 50-100 kW:Three-phase light commercial systems serve retail chains and small healthcare facilities with 10-30 second start requirements.
- 101-250 kW:Heavy commercial and light industrial ratings address manufacturing verticals with moderate power density needs.
251-500 kW systems capture margin concentration. Sub-50 kW volumes face hybrid substitution pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting genset manufacturing toward jurisdictions with phased emissions compliance timelines, as Tier 4 Final aftertreatment costs compress margins in early-adopter markets and create production-cost gaps favoring delayed-implementation economies.
United States
Data center buildouts in Northern Virginia and Dallas-Fort Worth are absorbing multi-megawatt diesel and gas turbine packages for prime power redundancy. EPA Tier 4 Final mandates for non-road engines above 56 kW are compressing rental fleet replacement cycles in Texas and North Dakota oilfield services. Construction firms in Houston face mandatory onboard diagnostics with wireless telematics transmission deadlines.
Germany
Commercial district heating networks and hospital complexes in Frankfurt specify gas generators to meet EU Stage V compliance deadlines ahead of 2025 enforcement windows. ECHA REACH restrictions on engine materials are driving modular product architectures for easier retrofit. Industrial parks in Bavaria are auditing Scope 1 emissions from captive power ahead of carbon border adjustment implementation.
India
Pharmaceutical and semiconductor fabrication facilities in Gujarat and Tamil Nadu deploy 251-500 kW diesel blocks under CEA grid connectivity rules mandating dual-source redundancy. State-level open access regulations in Maharashtra determine whether industrial users operate gensets for standby or continuous economics. Textile export hubs in Surat face EU importer audits of captive power emissions.
Singapore
Hyperscale cloud operators are pre-positioning captive generation capacity ahead of monsoon-season grid reliability constraints. The city-state's limited land area favors containerized and high-power-density installations over sprawling diesel arrays. Financial services data centers in the central business district specify 10-minute start gas turbine packages for mission-critical loads.
Indonesia
Telecommunications tower operators across Java and Sumatra specify sub-100 kW units with remote monitoring for unreliable-grid and off-grid sites. Natural gas pipeline access gaps in industrial clusters outside Jakarta block generator fuel switching despite lower emissions profiles. Mining operations in Papua and Kalimantan rely on containerized diesel modules for rapid deployment logistics.
Global Gensets Market Vendor Landscape
Integrated power system bundling dominates the current landscape as suppliers combine engine manufacturing, aftertreatment engineering, and control software to capture data center and industrial contracts. The vendor base concentrates around three strategic archetypes: captive engine foundries with global dealer networks, high-speed diesel technology specialists, and modular containerized system integrators. Competitive positioning hinges on M&A activity consolidating aftertreatment capabilities and geographic expansion into Southeast Asian data center markets.
Among US-based integrated power system suppliers, Cummins Inc. and Caterpillar Inc. anchor the premium tier through captive manufacturing depth and emissions certification breadth. Mitsubishi Heavy Industries occupies a distinct position representing high-speed diesel technology leadership for mission-critical installations. These three exemplify how engine-foundry control and integrated aftertreatment engineering separate contract winners from component assemblers in Tier 4 Final and Stage V compliance environments.
| Leading Market Players |
|---|
| Cummins Inc. |
| Caterpillar Inc. |
| Generac Holdings Inc. |
| Kohler Co. |
| Rolls-Royce Power Systems |
| Mitsubishi Heavy Industries |
| Atlas Copco |
| Himoinsa |
| Doosan Corp |
| Others |
Supply Flow & Price Mechanics
Skilled aftertreatment technicians concentrated in Tier 1 supplier networks across Germany and the United States widen pricing-tier spreads between EPA Tier 4 Final-certified units and legacy-equivalent imports from delayed-implementation markets. Labor-cost differentials in diagnostic capability and urea-system maintenance compress margins for standalone engine assemblers while rewarding integrated power system suppliers with captive service infrastructure.
Pricing Analysis
Distributor margins spanning 15-25 percentage points separate factory-direct hyperscale contracts from dealer-channel commercial sales. Three-tier pricing structure across premium, standard, and economy levels reflects aftertreatment certification grade and telematics integration depth. Cost compression in sub-100 kW rental fleets is intensifying because EPA onboard diagnostics deadlines force accelerated replacement cycles. Telecom tower operators in Indonesia and India exhibit highest price sensitivity, while data center operators in Singapore and Northern Virginia prioritize 10-minute start reliability over capital cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for multi-megawatt gas turbine packages, while authorized dealer networks manage commercial and industrial segments. Manufacturing concentrates in the United States, Germany, and India for engine blocks, with Japan and South Korea supplying high-speed diesel technology. Palladium and rhodium for diesel particulate filters and selective catalytic reduction systems draw from South African and Russian mining concentration. Single-source vulnerability in platinum group metal supply exposes OEM margins to geopolitical disruption. Distribution runs through captive dealer networks for aftermarket parts and service contract attachment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as emissions compliance costs filter out component assemblers and concentrate share with integrated power system suppliers. Demand is shifting toward EPA Tier 4 Final and EU Stage V-certified premium specifications that bundle aftertreatment engineering with telematics-enabled predictive maintenance.
For Market Incumbents: Lock in data center and semiconductor fab contracts through captive engine foundry capacity and integrated aftertreatment engineering. Expand service technician training infrastructure in Southeast Asia ahead of grid reliability-driven buildouts. Defend against modular containerized system integrators by anchoring synchronous paralleling and microgrid control software capabilities. For New Entrants and Emerging Players: Secondary market refurbishment specialists represent an underserved buyer archetype seeking Tier 2-equivalent units for African mining and Southeast Asian islanded industrial parks. Target containerized diesel module demand in Papua and Kalimantan where rapid deployment logistics outweigh emissions certification premiums. Pursue power-as-a-service contracting structures in Saudi Arabia and UAE manufacturing verticals to bypass capital purchase barriers. For Investors and Strategic Acquirers: Integrated power system suppliers with captive aftertreatment engineering are the most active acquirer in this space, consolidating regional service capabilities and control software assets. The five-to-ten year viability window favors suppliers with backward integration into engine manufacturing and emissions certification breadth. Acquisition target archetype: modular containerized system integrators with Southeast Asian data center installation track records. Watch carbon border adjustment implementation in EU-destined export hubs as inflection indicator for gas and hybrid retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Aftertreatment Engineering Integration | Captive selective catalytic reduction and diesel particulate filter capabilities secure EPA Tier 4 Final contract eligibility. |
| Telematics Platform Deployment | Onboard diagnostics with wireless transmission satisfy rental fleet compliance deadlines in Texas and North Dakota. |
| Microgrid Controller Development | Synchronous paralleling algorithms enable genset-battery-solar tri-hybrid architectures for islanded industrial parks. |
| Southeast Asian Service Expansion | Technician training infrastructure captures data center buildouts in Singapore, Indonesia, and Malaysia. |
| Power-as-a-Service Contracting | Fixed per-kWh tariffs convert fixed asset exposure to variable operating expense for volatile manufacturing schedules. |
Methodological Framework
Multiple input streams — executive interviews with genset OEM product managers and aftermarket service heads, technical discussions with EPC contractors and data center power planners, and regulatory filings with EPA and EU Stage V certification bodies — were reconciled against secondary validation. Primary fieldwork engaged plant engineers at pharmaceutical and semiconductor fabs in Gujarat, procurement leads at telecommunications tower operators across Java and Sumatra, and maintenance directors at mining operations in Australia and Papua. Secondary sources included EPA non-road engine certification databases, ECHA REACH restriction notices, FERC interconnection filings, and customs trade data for engine block and aftertreatment component flows. Bottom-up unit shipment modeling and top-down power infrastructure capex analysis were triangulated for consistency.
Historical capacity expansion patterns were cross-referenced against panel input from utility planning officers and IPP project developers to anchor growth trajectory assumptions. Segmentation modeling spanned fuel type, installation format, power rating tier, end-use vertical, and regional regulatory framework across the projection horizon. CAGRs were derived from installed base replacement cycles, grid reliability indices, and emissions compliance timeline differentials. Forecast inputs incorporated pipeline gas infrastructure buildout rates in Vietnam and the Philippines, and lithium-ion battery cost curves affecting hybrid genset pairing economics.
Inputs from EPA certification databases and EPC contractor project pipelines were available through the study window; gaps in real-time platinum group metal spot pricing and South African mining output introduce uncertainty bands around aftertreatment cost assumptions. Forecasts reflect base-case assumptions regarding EU carbon border adjustment implementation scope and India's CEA grid connectivity rule enforcement consistency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Microturbine Market
Power Generation
South America Thermal Power Market
Power Generation
On-Grid Combined Heat and Power Market
Power Generation
Thermal Power Market
Power Generation
Coal Fired Power Generation Market
Power Generation
Marine Power Plant Market
Power Generation
Europe Thermal Power Market
Power Generation
Asia-Pacific Thermal Power Plant Market
Power Generation
Vietnam Power Generation EPC Market
Power Generation
Distributed Power Generation Market
Power Generation
Micro CHP Market
Power Generation
Mobile Power Plant Market
Power Generation
Global Black Start Generator Market
Power Generation
Distributed Generation Market
Power Generation
Malaysia Power Generation EPC Market
Power Generation
Tunisia Power Market