
 Wind Turbine Alternator Market | 2026-2036
Wind Turbine Alternator Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Alternator Market Analytics
Permanent magnet grade upgrades is redrawing competitive boundaries across the wind turbine alternator market. Siemens Gamesa Renewable Energy leverages captive rare-earth sourcing partnerships to secure magnet supply chains. Vestas Wind Systems anchors its alternator portfolio around modular direct-drive architectures. GE Vernova differentiates through doubly fed induction systems optimized for variable wind regimes.
A wind turbine alternator converts mechanical rotational energy from rotor blades into grid-synchronous electrical output, typically operating at 50 or 60 Hz with power ratings from kilowatts to multi-megawatt scales depending on drivetrain topology and cooling architecture. Permanent magnet synchronous designs now dominate offshore installations where efficiency and reliability requirements are most stringent, while induction-based systems retain cost advantages across mature onshore fleets. Direct drive technology captures expanding share in utility-scale applications as gearbox elimination reduces maintenance intervals and downtime exposure.
Germany's KBA certifies grid-code compliance for alternator synchronization, while the EU Green Deal and REACH frameworks constrain rare-earth material sourcing and end-of-life rotor disposal pathways. China's MIIT enforces GB standards for domestic turbine electrical component efficiency tiers. Stakeholders must monitor evolving magnet recycling mandates and regional content requirements that could fragment supplier qualification criteria across deployment zones.
Market Dynamics
Permanent magnet synchronous alternators are displacing conventional doubly fed induction systems across offshore wind farms, driven by efficiency mandates under the EU Green Deal and procurement of higher-output units by North Sea developers.
Growth Catalysts
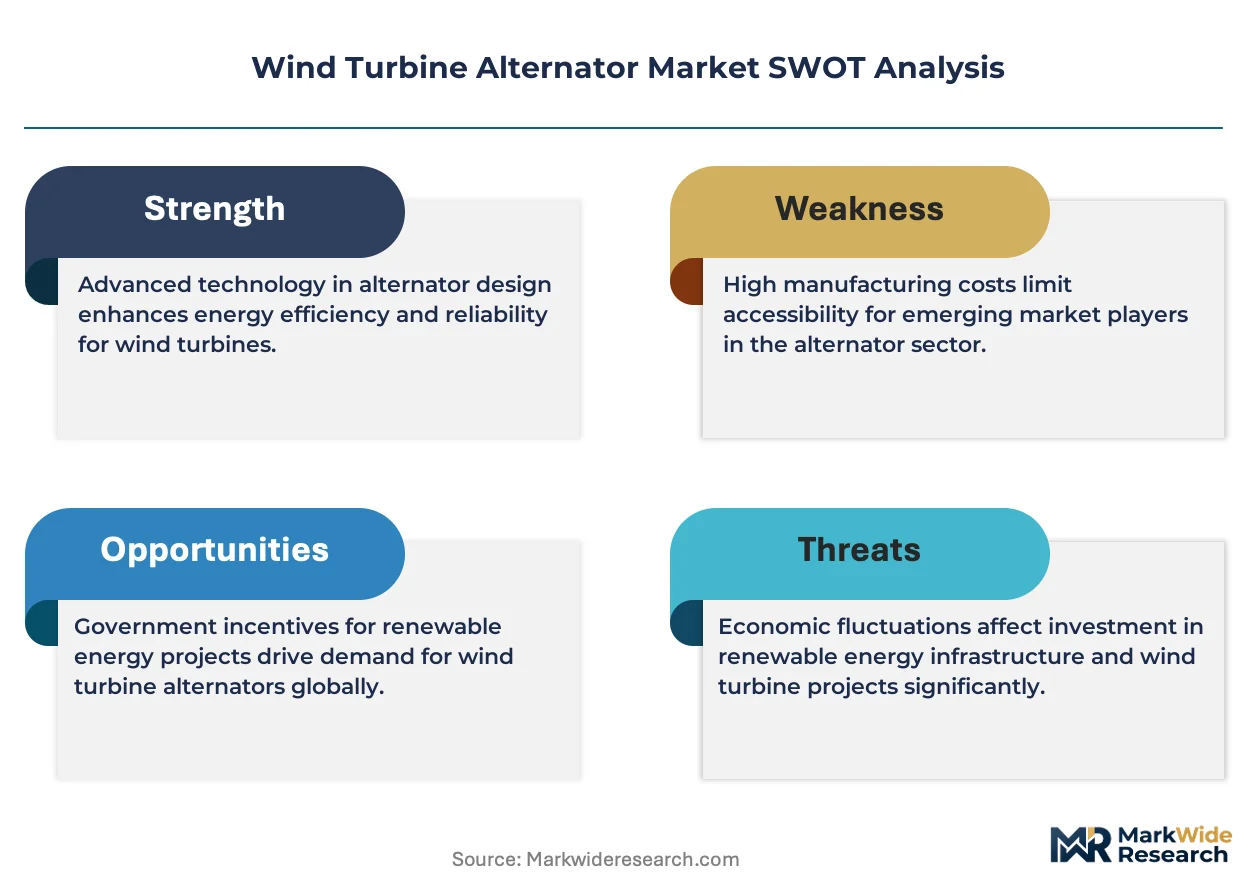
- EU Green Deal efficiency mandates:Grid-connected equipment standards in Germany, Denmark, and Spain tighten alternator synchronization requirements, forcing fleet upgrades.
- Offshore wind farm scaling:Developers along China's eastern seaboard and the North Sea corridor procure multi-megawatt direct-drive units to maximize capacity factors.
- Rare-earth magnet supply partnerships:Captive sourcing arrangements with Inner Mongolia and Australian rare-earth processors secure neodymium-dysprosium supply chains for permanent magnet production.
Market Restraints
- Neodymium price volatility:Rare-earth oxide spot markets expose alternator manufacturers to 40-60% input cost swings on permanent magnet grades.
- China supply concentration:Over 80% of separated heavy rare-earth processing concentrates in Jiangxi and Inner Mongolia, creating single-source vulnerability.
- REACH end-of-life constraints:EU rotor disposal pathways require documented rare-earth recovery rates, adding compliance overhead to offshore decommissioning budgets.
Strategic Opportunities
- India offshore licensing:Tamil Nadu and Gujarat state governments auction seabed leases with domestic content requirements, opening local alternator assembly demand.
- Magnet recycling infrastructure:Hydrometallurgical recovery facilities in Germany and Japan extract rare-earth elements from decommissioned turbine rotors at 95% purity.
- Direct-drive gearbox elimination:Synchronous permanent magnet architectures converge with advanced power electronics to remove mechanical transmission components entirely.
Industry Challenges
- Grid-code certification timelines:Germany's KBA synchronization testing extends 14-18 months for new alternator platforms, delaying project commissioning.
- Power electronics integration complexity:Full-converter interfaces with existing doubly fed induction fleets require custom control software and hardware retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Alternator Market |
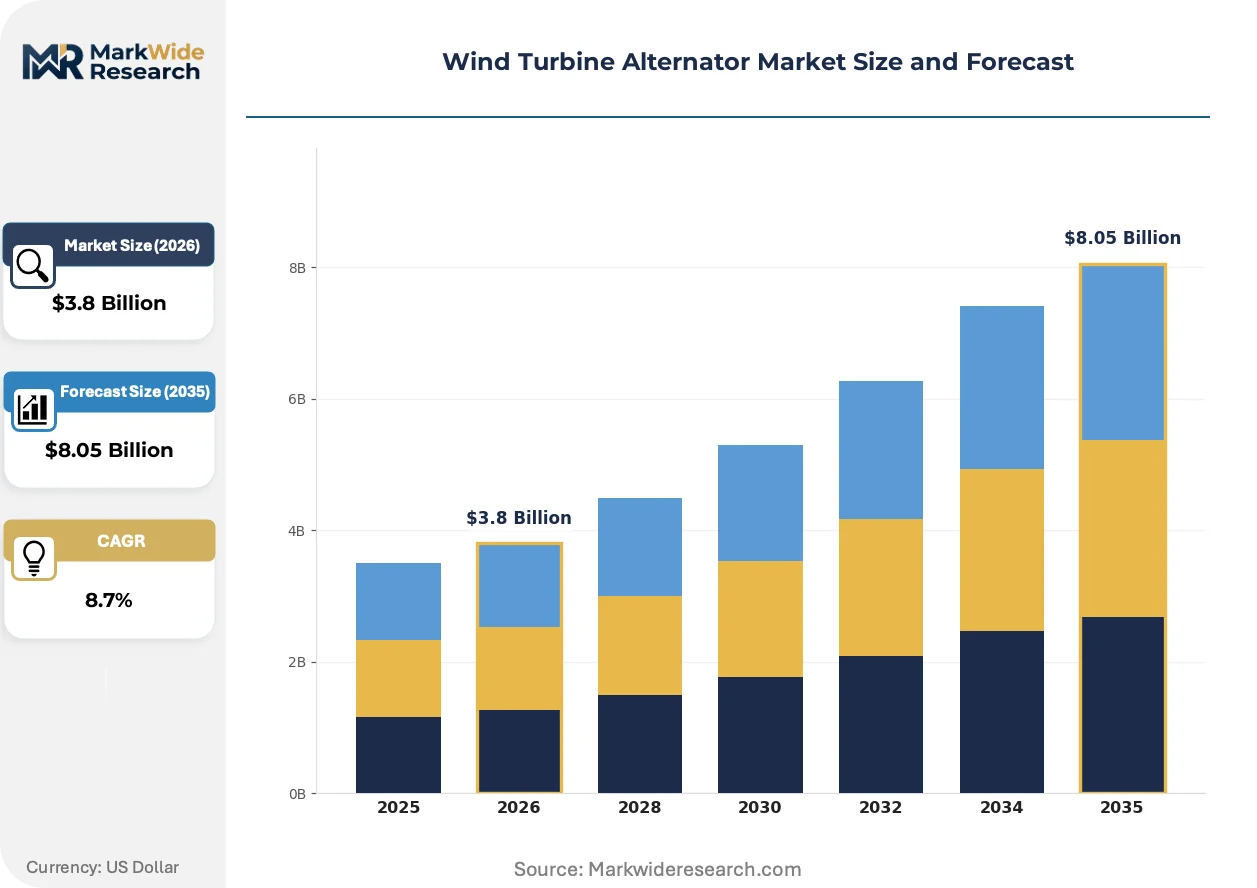
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Permanent Magnet, Synchronous, Induction, Gearless Application: Offshore Wind, Onshore Wind, Distributed Generation, Utility Scale End User: Energy Producers, Project Developers, Government Agencies, Research Institutions Technology: Direct Drive, Doubly Fed Induction, Vertical Axis, Horizontal Axis |
| Companies Covered | Siemens Gamesa Renewable Energy, Vestas Wind Systems, GE Vernova, Nordex, Goldwind, Envision Energy, Ming Yang Smart Energy, ENERCON, Doosan Heavy Industries & Construction, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Alternator Market Evolving Landscape
Alternator topology is bifurcating between high-efficiency permanent magnet offshore designs and cost-optimized onshore induction systems, with cooling architecture and magnet grade becoming primary differentiation vectors.
High-temperature superconductor field windings are displacing copper rotor coils in 10MW+ offshore prototypes, enabling 30% mass reduction and eliminating rare-earth dependency entirely. Vestas and Siemens Gamesa test these units at Danish demonstration sites. The structural consequence is a two-tier supply base separating superconductor-capable specialists from conventional magnet manufacturers.
REACH rare-earth substance restrictions now constrain magnet sourcing for EU-deployed alternators, forcing suppliers to document supply chain provenance through ECHA's SCIP database. Manufacturers respond by qualifying Malaysian and Vietnamese separation facilities outside Chinese concentration. Offshore projects in German and Dutch waters face the tightest compliance windows.
Utility procurement contracts now unbundle alternator supply from full-turbine OEM agreements, with Orsted and Equinor issuing direct RFPs for alternator-only packages. This disintermediation compresses margins for integrated turbine builders while opening Tier-2 alternator specialists to utility-scale volumes. The pattern is most pronounced in North Sea lease rounds where developers optimize component-level sourcing.
Wind Turbine Alternator Market Segmentation
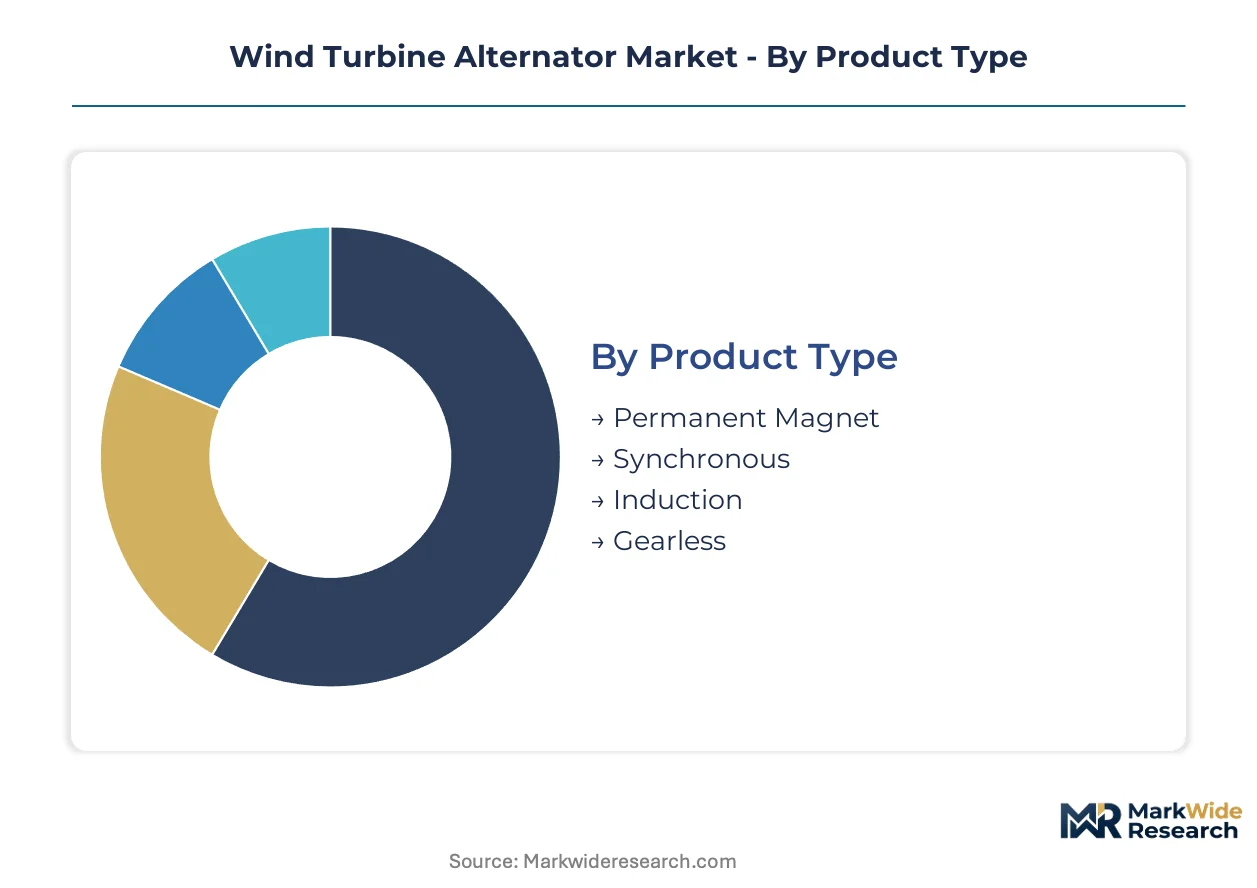
Wind turbine alternator procurement patterns diverge sharply across deployment contexts, with offshore developers prioritizing efficiency-certified synchronous designs while onshore fleets optimize for capital cost minimization. Regulatory tiering under the EU Green Deal and China's GB standards creates distinct qualification pathways that reshape supplier positioning across each segment boundary.
Product Type:
REACH substance restrictions and China's MIIT efficiency tiers enforce divergent material specifications across magnet grades and winding compositions, fragmenting supplier qualification requirements.
- Permanent Magnet:Neodymium-dysprosium alloy rotors deliver the highest torque density for offshore direct-drive architectures. North Sea developers specify these units for 10MW+ installations where downtime costs dominate lifecycle economics.
- Synchronous:Grid-synchronous field windings enable precise voltage regulation under variable wind regimes. Germany's KBA certifies these designs for grid-code compliance, making them mandatory for utility-scale feed-in across German, Danish, and Spanish transmission zones.
- Induction:Squirrel-cage rotor designs retain cost advantages across mature onshore fleets in lower wind resource regions.
- Gearless:Elimination of mechanical transmission reduces maintenance intervals for remote offshore installations.
Permanent magnet designs handle the majority of throughput; gearless configurations are expanding most quickly on share.
Application:
Capacity factor differentials between offshore and onshore sites drive order-of-magnitude variations in alternator power density requirements and cooling system specifications.
- Offshore Wind:Salt-resistant encapsulation and redundant cooling loops protect multi-megawatt units in North Sea and Chinese eastern seaboard deployments. Orsted and Equinor procurement contracts specify 15-20 year design lifecycles with documented availability guarantees.
- Onshore Wind:Cost-optimized induction systems dominate installed base refurbishment cycles across lower wind speed corridors.
- Distributed Generation:Sub-megawatt permanent magnet units serve industrial microgrid and rural electrification projects with modular scaling.
- Utility Scale:Centralized procurement by state-owned developers in China and independent power producers in Europe drives volume concentration in direct-drive synchronous platforms.
Offshore wind commands premium pricing tiers; distributed generation shows the steepest expansion trajectory among application categories.
End User:
Procurement authority fragmentation between integrated turbine OEMs and direct utility sourcing reshapes contract structures and margin distribution.
- Energy Producers:State Grid Corporation of China and Iberdrola issue alternator-only RFPs to optimize component-level sourcing outside traditional turbine supply agreements.
- Project Developers:Equinor and Orsted engineering teams specify alternator performance envelopes separately from nacelle integration contracts.
- Government Agencies:India's CEA and Tamil Nadu state authorities enforce domestic content requirements through seabed lease auction terms.
- Research Institutions:Danish Technical University and Fraunhofer IWES validate high-temperature superconductor prototypes at demonstration sites.
Energy producers generate the largest order volumes; project developers are gaining procurement autonomy fastest.
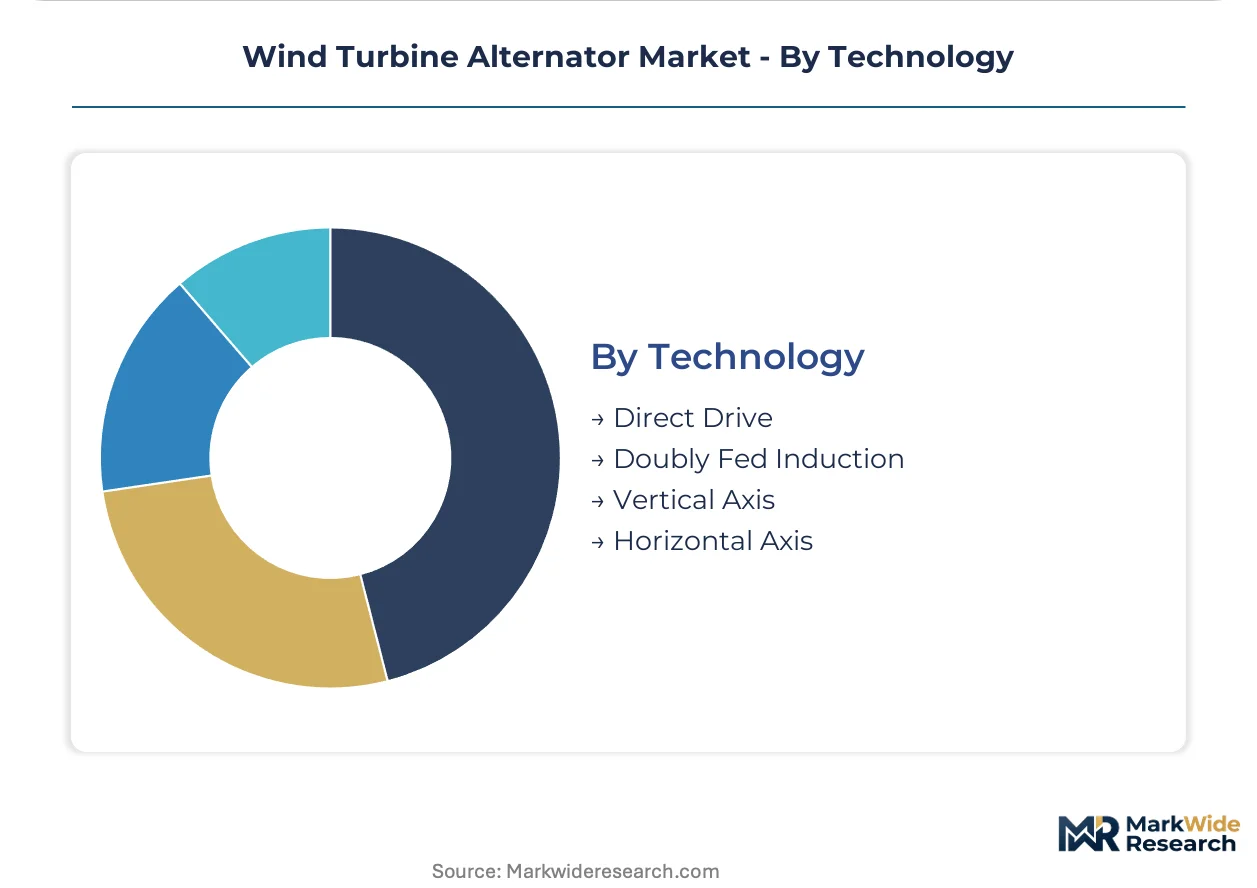
Technology:
Drivetrain topology selection determines rare-earth exposure, maintenance scheduling, and power electronics integration complexity.
- Direct Drive:Synchronous permanent magnet architectures eliminate gearbox failure modes entirely. Vestas and Siemens Gamesa deploy these systems across 8MW+ offshore platforms where accessibility constraints magnify maintenance cost premiums.
- Doubly Fed Induction:Partial-scale converters reduce power electronics costs for onshore installations with consistent wind profiles.
- Vertical Axis:Omnidirectional rotor acceptance suits distributed urban and rooftop applications with turbulent wind regimes.
- Horizontal Axis:Dominant configuration across utility-scale deployments with established supply chains and certification pathways.
Direct drive technology anchors offshore deployment; vertical axis systems are climbing the fastest on share in distributed applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics shape regional alternator procurement patterns. China maintains net export dominance through eastern seaboard manufacturing clusters. European Union markets rely on intra-regional sourcing for offshore installations while importing specialized magnet components.
China
Inner Mongolia and Jiangxi provinces concentrate rare-earth separation capacity for permanent magnet production. MIIT enforces GB efficiency tiers for domestic turbine electrical components. Manufacturing clusters along the Yangtze River Delta export direct-drive alternators to Southeast Asian wind farm developers.
Germany
KBA grid-code certification mandates synchronize alternator commissioning timelines across North Sea lease rounds. EU Green Deal efficiency standards tighten equipment qualification for utility-scale feed-in. Industrial corridors in Lower Saxony and Schleswig-Holstein host alternator testing facilities for offshore prototypes.
United States
Independent power producers issue direct RFPs for alternator-only packages outside traditional turbine supply agreements. FERC interconnection standards govern synchronization requirements for grid-connected equipment. Gulf Coast assembly plants serve emerging offshore developments in federal waters.
Denmark
Danish Technical University demonstration sites validate high-temperature superconductor prototypes at 10MW+ scales. National renewable portfolio standards accelerate fleet replacement cycles. Copenhagen-region engineering firms specify alternator performance envelopes separately from nacelle integration contracts.
India
Tamil Nadu and Gujarat state authorities auction seabed leases with domestic content requirements for alternator assembly. CEA technical standards govern grid synchronization for utility-scale installations. Port infrastructure at Mundra and Kattupalli supports offshore component import logistics.
Wind Turbine Alternator Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and captive supply arrangements. The vendor base separates into consolidated full-turbine OEMs and emerging Tier-2 alternator specialists. Three archetypes dominate: integrated turbine builders with captive magnet sourcing, independent alternator fabricators serving utility direct procurement, and rare-earth processors backward-integrating into component manufacturing. Competitive moves concentrate on strategic partnerships for magnet supply security and capacity expansion in offshore-certified production lines.
Within the integrated OEM tier, Siemens Gamesa Renewable Energy and Vestas Wind Systems exemplify full-turbine builders with established alternator portfolios. GE Vernova occupies a position bridging conventional induction systems and emerging direct-drive architectures. These three entities represent divergent technology bets across permanent magnet synchronous and doubly fed induction topologies.
| Leading Market Players |
|---|
| Siemens Gamesa Renewable Energy |
| Vestas Wind Systems |
| GE Vernova |
| Nordex |
| Goldwind |
| Envision Energy |
| Ming Yang Smart Energy |
| ENERCON |
| Doosan Heavy Industries & Construction |
| Others |
Value Network & Pricing Analysis
Multi-gigawatt manufacturing scale at Yangtze River Delta clusters compresses unit economics for permanent magnet alternators while simultaneously concentrating price-setting power among vertically integrated producers. This scale dynamic establishes floor prices that smaller fabricators cannot match without captive rare-earth sourcing or state-backed financing.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across offshore wind procurement, with pricing stratifying across premium, standard, and economy tiers based on magnet grade certification and cooling redundancy specifications. Cost compression in standard-tier induction systems intensifies because Chinese MIIT efficiency mandates force technology upgrades without corresponding price recovery mechanisms. State-owned developers in China exhibit lowest price sensitivity due to policy-driven procurement timelines, while independent power producers in Europe demonstrate highest sensitivity to magnet price volatility pass-through clauses.
Supply Chain Analysis
Strategic stockpiling of neodymium-dysprosium oxides dominates inventory strategy among European alternator manufacturers seeking buffer against Chinese export quota volatility. Raw material dependencies center on rare-earth oxides from Inner Mongolia and Jiangxi, copper windings from Chilean concentrate, and high-grade electrical steel from Japanese and South Korean mills. Single-source vulnerability concentrates in heavy rare-earth separation capacity, with distribution running through integrated turbine OEM assembly plants and direct utility procurement channels for offshore projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around KBA grid-code certification and EU Green Deal efficiency tiers constructs formidable defensive moats for established alternator suppliers. Switching costs escalate through 14-18 month recertification timelines that lock developers into proven synchronization platforms.
For Market Incumbents: Shield market position through captive magnet recycling partnerships with German hydrometallurgical facilities and capacity expansion in offshore-certified production lines at Danish demonstration sites. Siemens Gamesa and Vestas must deepen backward integration into rare-earth separation to offset Chinese supply concentration. Certification investment in high-temperature superconductor prototypes represents the priority defensive lever against magnet-free substitute technologies. For New Entrants and Emerging Players: Differentiate on magnet recycling yield rates and modular direct-drive architectures targeting India's Tamil Nadu and Gujarat offshore licensing rounds with domestic content compliance. The most penetrable white space sits in alternator-only procurement contracts unbundled from full-turbine agreements, particularly among North Sea developers optimizing component-level sourcing. Go-to-market execution should anchor on power electronics integration partnerships with established converter specialists. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among alternator specialists with long-term service contracts and documented availability guarantees across 15-20 year design lifecycles. Long-term viability over the projection horizon favors acquisition targets with proven KBA certification track records and Malaysian or Vietnamese magnet sourcing outside Chinese concentration. The critical inflection signal to monitor is REACH rare-earth recovery mandate enforcement tightening across German and Dutch waters.| Strategic Initiative | Industry Significance |
|---|---|
| Magnet Recycling Infrastructure Investment | Hydrometallurgical recovery facilities in Germany extract rare-earth elements at 95% purity, securing supply independence. |
| Direct-Drive Capacity Expansion | Offshore-certified production lines eliminate gearbox failure modes and reduce maintenance intervals in inaccessible installations. |
| High-Temperature Superconductor Prototyping | Danish Technical University demonstration sites validate 10MW+ units that eliminate rare-earth dependency entirely. |
| Captive Rare-Earth Sourcing Partnerships | Inner Mongolia and Australian processor agreements secure neodymium-dysprosium supply chains against export quota volatility. |
| Power Electronics Integration Development | Full-converter interfaces enable synchronous permanent magnet architectures to displace doubly fed induction systems. |
Research Methodology
The analysis maps permanent magnet, synchronous, induction, and gearless alternator topologies, each validated through turbine OEM engineering directors, offshore project developer procurement leads, rare-earth processor supply managers, and grid operator interconnection specialists. Primary interview intelligence triangulates against customs trade data, MIIT GB standard filings, KBA certification registries, and ECHA SCIP database disclosures. Bottom-up installation forecasts and top-down equipment spend estimates converge through iterative stakeholder cross-checking.
Consistency checks validate volume and value outputs against IEA renewable capacity projections, FERC interconnection queue data, and European offshore wind lease round announcements across the modeling period. Segmentation dimensions include drivetrain topology, deployment context, magnet grade specification, and regional regulatory framework. CAGRs derive from unit shipment trajectories and technology mix shifts, with magnet price volatility and grid-code certification timelines as industry-specific forecast inputs.
Material uncertainties — rare-earth export quota revisions, REACH substance restriction expansions, and superconductor technology maturation — sit outside the modeled envelope. Forecasts reflect assumptions around current magnet sourcing geography and efficiency mandate enforcement intensity. Revision becomes warranted when high-temperature superconductor field winding reliability crosses commercial deployment thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Boiler, Turbine, and Generator (BTG) Market
Generators
India Diesel Generator Market
Generators
Gas Generator Market
Generators
Wind Power Generators Market
Generators
Marine Gensets Market
Generators
South America Gas Generator Market
Generators
North America Portable Generators Market
Generators
Turbo Generator Market
Generators
Generator Sales Market
Generators
South America Diesel Generator Market
Generators
Gasoline Gensets Market
Generators
Saudi Arabia Diesel Generator Market
Generators
Generator Belt Market
Generators
Portable Inverter Generators Market
Generators
Digital Inverter Generator Market
Generators
Construction Generator Sets Market