
 Canada Digital X-Ray Devices Market | 2026-2036
Canada Digital X-Ray Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Digital X-Ray Devices Market Outlook
Health Canada's Medical Devices Regulations is repositioning compliance costs for new entrants. GE Healthcare leverages its installed base across Canadian hospital networks to sustain recurring service revenue. Siemens Healthineers anchors its position through R&D intensity in advanced detector technology. Fujifilm Holdings Corporation differentiates via specialized portable systems targeting remote and indigenous community clinics.
Canada digital X-ray devices comprise electronic imaging systems that replace analog film with digital detectors capturing X-ray photons and converting them to diagnostic images via flat panel or computed radiography sensors, with spatial resolution typically exceeding 2.5 line pairs per millimeter. These systems serve primarily to reduce radiation exposure, eliminate chemical processing, and enable immediate image distribution across hospital information networks. Portable X-Ray systems lead volume deployment as emergency departments and intensive care units prioritize bedside diagnostics, while Direct Radiography captures premium margins through superior dose efficiency and workflow speed. Flat Panel Technology dominates new capital purchases among imaging centers replacing legacy computed radiography rooms.
Health Canada enforces the Medical Devices Regulations under the Food and Drugs Act, classifying digital X-ray systems as Class II or III devices requiring quality management system certification and pre-market technical documentation review. The Canadian Standards Association maintains CSA Z114.4 for radiation safety, while provincial occupational health agencies mandate ALARA protocols and operator shielding standards that shape equipment specification requirements. Procurement committees must weigh total cost of ownership against detector lifespan and software upgrade paths when evaluating vendor proposals.
Market Dynamics
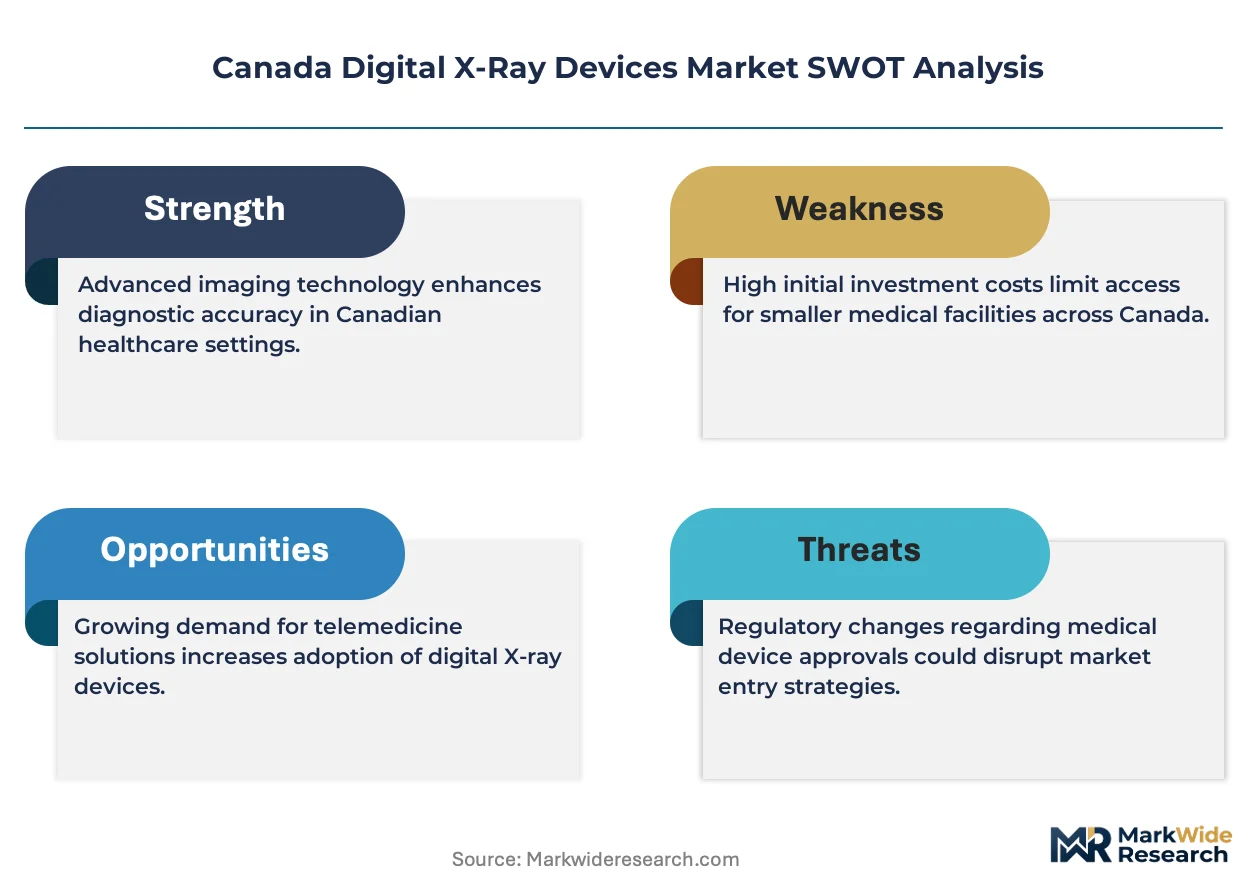
Provincial hospital networks in Ontario, Quebec, and British Columbia are consolidating radiology procurement under centralized tender frameworks. Health Canada's Medical Devices Regulations is compressing registration timelines while elevating quality management system requirements. This structural pressure favors vendors with established compliance infrastructure and service footprints across multiple provinces.
Growth Catalysts
- Class II Device Registration Pathways:Health Canada's streamlined pre-market technical documentation review is accelerating commercialization timelines for flat panel detector systems. Ontario's acute care procurement committees prioritize vendors with active device licenses.
- Remote Indigenous Community Deployment:Federal healthcare infrastructure programs are funding portable digital X-ray systems for northern clinics. Transportable computed radiography units address diagnostic gaps in fly-in communities.
- ALARA Protocol Mandates:Provincial occupational health agencies enforce radiation exposure minimization standards. Direct radiography systems with superior dose efficiency command preference in tender evaluations.
Market Restraints
- Detector Panel Supply Concentration:Amorphous silicon flat panel manufacturing concentrates among Asian component suppliers. Canadian system integrators face extended lead times for premium detector modules.
- Capital Equipment Replacement Cycles:Hospital capital budgets stretch computed radiography system lifespans beyond optimal detector degradation thresholds. Deferred upgrades compress addressable market volume.
- Interoperability Certification Costs:Provincial health information network integration requires DICOM conformance testing. Smaller regional vendors absorb disproportionate compliance overhead.
Strategic Opportunities
- Artificial Intelligence Convergence:Computer-aided detection algorithms are unifying with digital radiography workstations. Alberta's diagnostic imaging networks pilot AI-enhanced screening protocols.
- Mobile Imaging Service Models:Third-party radiology providers deploy truck-mounted digital X-ray units. Long-term care facilities in rural Quebec contract outsourced bedside imaging.
- Veterans Affairs Procurement Stream:Federal healthcare programs for military personnel maintain dedicated capital equipment budgets. Specialized trauma imaging requirements diverge from standard hospital specifications.
Industry Challenges
- Medical Physics Specialist Shortage:Provincial licensing bodies report insufficient qualified personnel for equipment acceptance testing. Extended commissioning timelines delay revenue recognition.
- Legacy PACS Integration Complexity:Hospital information networks operate heterogeneous archive systems. Vendor-neutral archive migration projects stall device deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Digital X-Ray Devices Market |
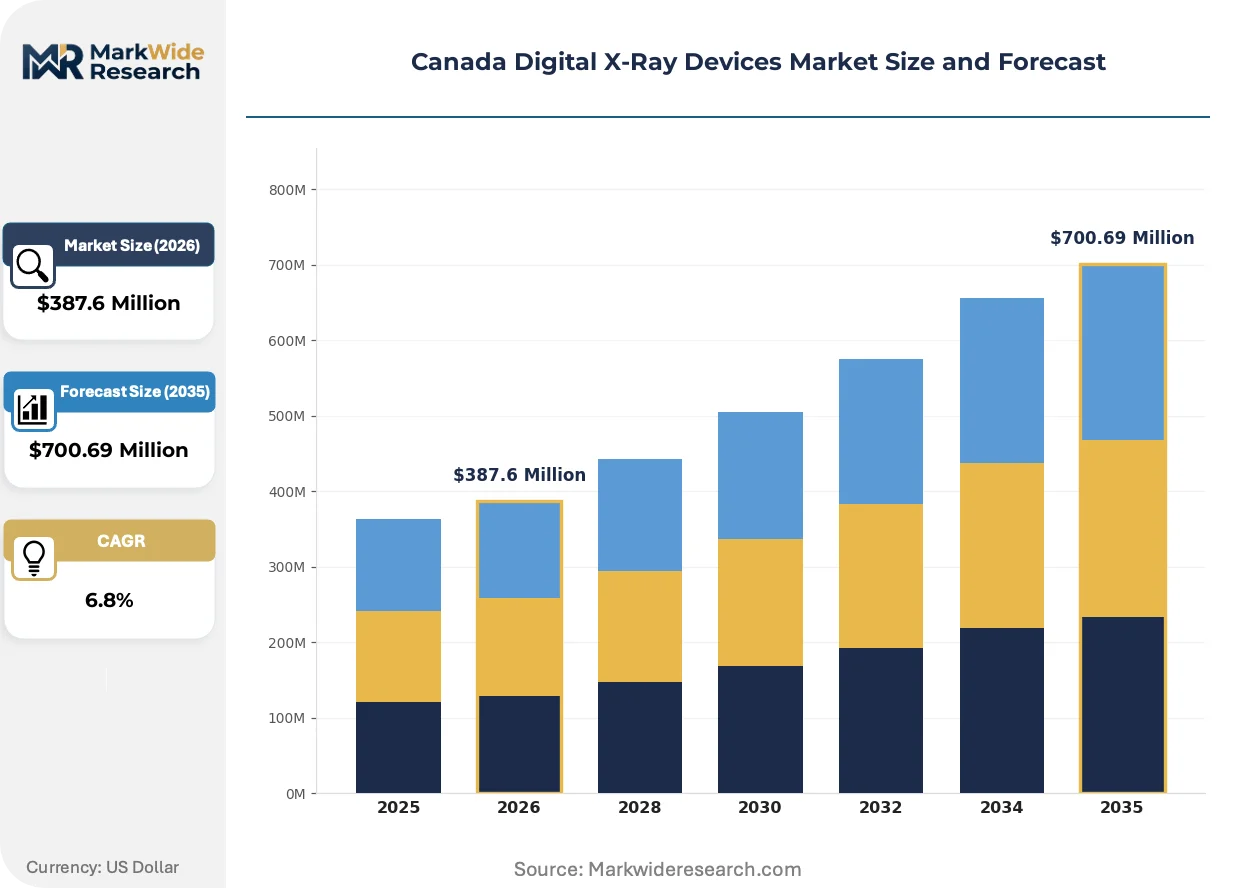
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable X-Ray, Fixed X-Ray, Retrofit Systems, Digital Detectors End User: Hospitals, Imaging Centers, Outpatient Clinics, Research Facilities Technology: Computed Radiography, Direct Radiography, Photostimulable Phosphor, Flat Panel Technology Application: General Radiography, Orthopedic Imaging, Dental Imaging, Cardiovascular Imaging |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips NV, Canon Medical Systems Corporation, Fujifilm Holdings Corporation, Carestream Health, Shimadzu Corporation, Mindray Medical International, Hologic Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Digital X-Ray Devices Market Strategic Shifts
Detector technology evolution and procurement centralization are compressing vendor margins while elevating service contract value. Canadian healthcare authorities prioritize dose optimization and network interoperability over hardware differentiation.
Wireless flat panel detectors are unifying emergency department and operating room imaging workflows. Ontario's Level 1 trauma centers adopt battery-powered portable units for intraoperative fluoroscopy substitution. This convergence is unifying capital planning across radiology and surgical services departments.
Health Canada's Medical Devices Regulations amendment tightens post-market surveillance for Class III digital radiography systems. Manufacturers must submit periodic safety updates and adverse event summaries. High-volume screening programs in breast imaging clinics face elevated documentation burdens.
Consolidated provincial procurement is displacing hospital-level vendor selection authority. Quebec's centralized health authority negotiates enterprise-wide service agreements spanning detector replacement and software maintenance. Community hospitals surrender negotiating leverage for standardized equipment configurations.
Canada Digital X-Ray Devices Market Segmentation
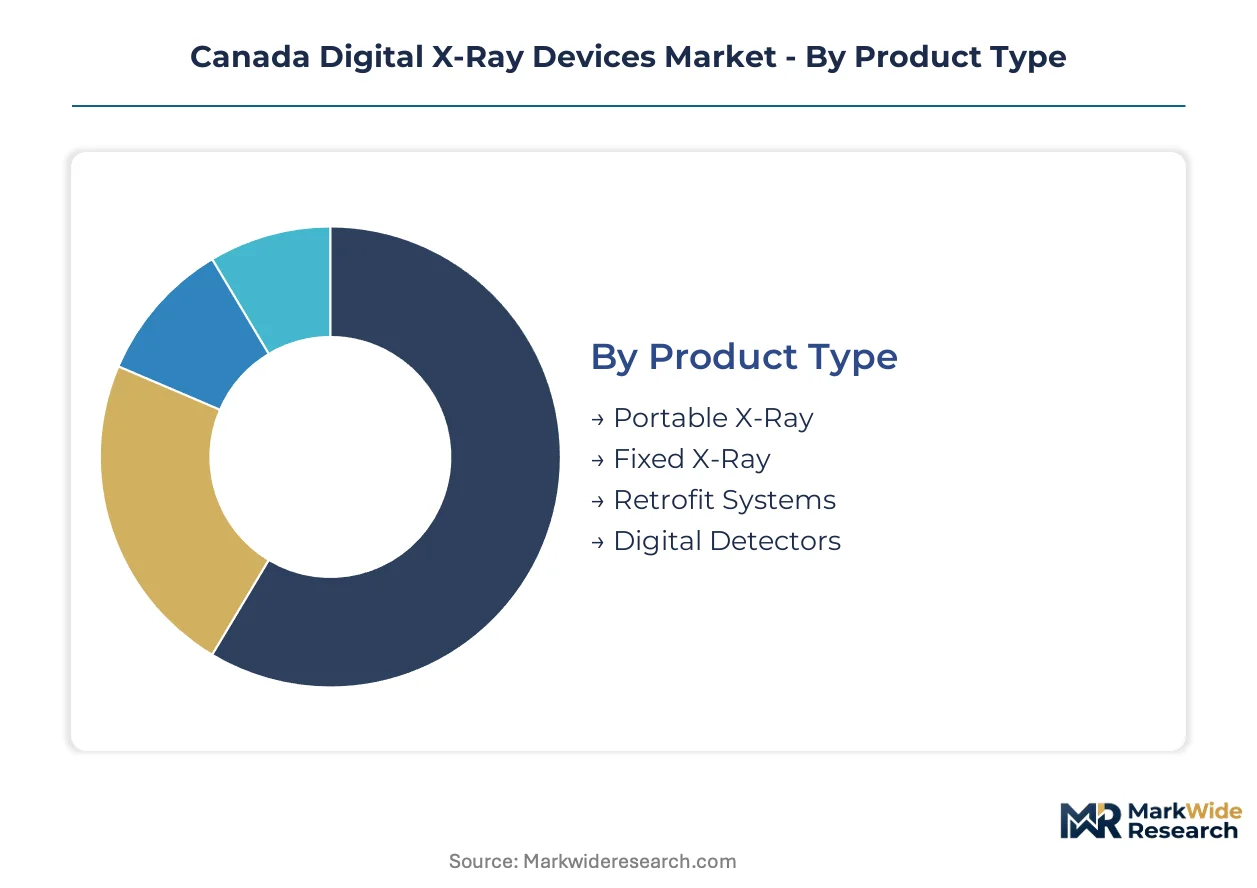
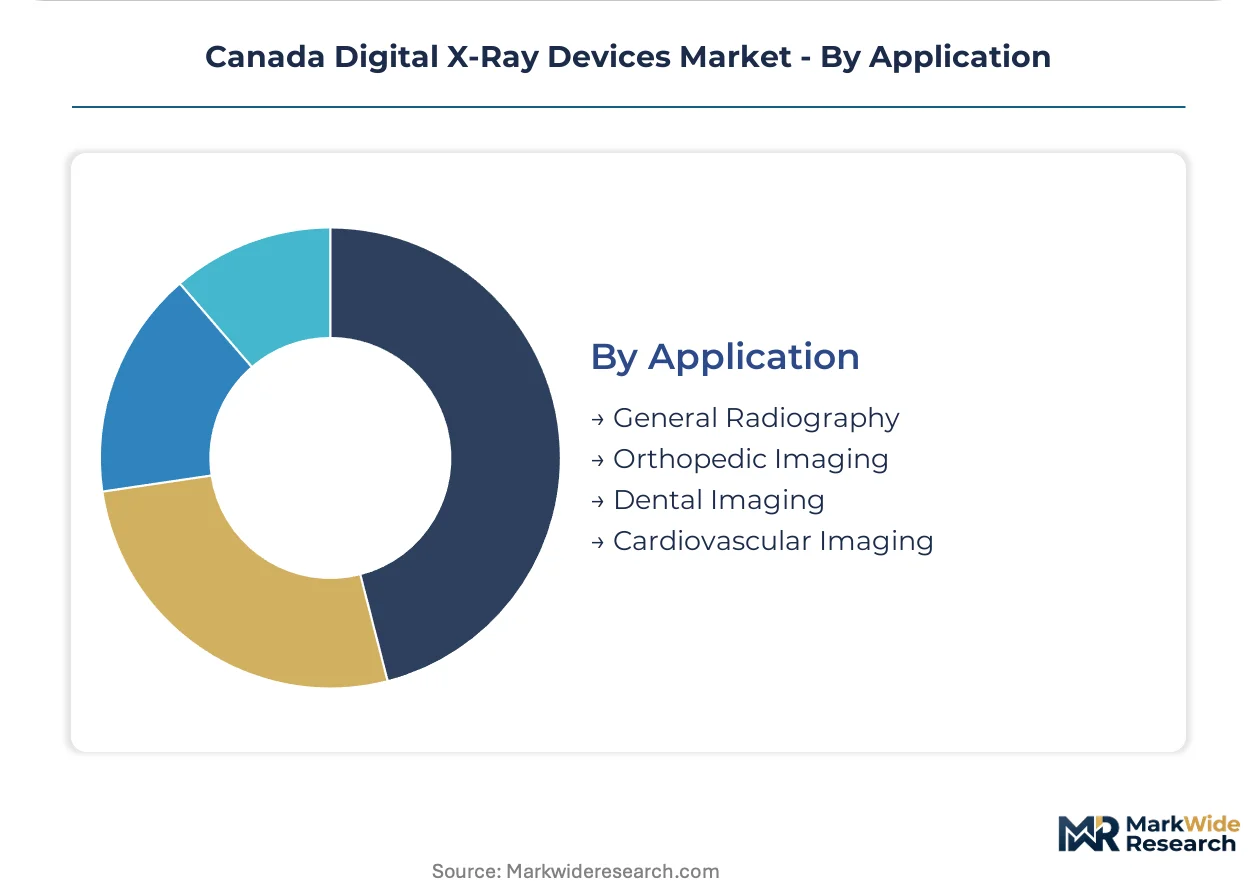
Canadian procurement committees evaluate digital X-ray investments through multiple technical and operational lenses. Understanding how demand fragments across product configurations, clinical settings, and imaging applications reveals where capital deployment concentrates and where upgrade cycles lag.
Product Type:
Capital intensity varies sharply across installation scenarios, with fixed-room systems demanding substantial construction integration while portable units minimize infrastructure requirements.
- Portable X-Ray:Battery-powered mobile units with wireless detector panels enable bedside imaging in intensive care units and emergency departments. Ontario's Level 1 trauma centers prioritize these systems for intraoperative workflow integration where surgical throughput depends on rapid image acquisition without patient transport.
- Fixed X-Ray:Permanent room installations with ceiling-suspended tube stands and bucky tables serve high-volume radiology departments. Quebec's centralized health authority negotiates enterprise service agreements spanning detector replacement cycles for these capital-intensive configurations.
- Retrofit Systems:Conversion kits upgrade analog film-based equipment to digital capture without full room replacement.
- Digital Detectors:Standalone flat panel or computed radiography cassettes integrate with existing mechanical frameworks.
Most installed capacity flows through Fixed X-Ray systems in hospital radiology departments. Expansion is steepest in Portable X-Ray as bedside diagnostics displace departmental throughput bottlenecks.
End User:
Procurement authority concentrates differently across customer types, with provincial networks controlling hospital purchasing while independent clinics retain vendor selection flexibility.
- Hospitals:Acute care facilities with 24-hour emergency services and surgical programs generate the highest imaging volumes. British Columbia's health authority consolidates tender frameworks across its regional hospital networks, standardizing detector specifications and service contract terms.
- Imaging Centers:Dedicated outpatient facilities optimize throughput per square meter with streamlined patient flows. Alberta's diagnostic imaging networks pilot AI-enhanced screening protocols in these high-efficiency environments where case volume justifies workstation automation.
- Outpatient Clinics:Community-based practices with limited capital budgets favor compact computed radiography solutions.
- Research Facilities:University-affiliated imaging departments prioritize experimental detector configurations and software customization.
Revenue concentration sits with Hospitals due to replacement scale and service contract value. Imaging Centers are gaining share fastest as provincial governments shift non-urgent diagnostics to ambulatory settings.
Technology:
Detector architecture determines dose efficiency, image acquisition speed, and total cost of ownership across replacement cycles.
- Computed Radiography:Photostimulable phosphor plates require mechanical scanning after exposure, extending workflow time compared to direct capture. Remote indigenous community clinics in northern Canada deploy transportable CR units where infrastructure limitations preclude fixed-room installation and technical support access is intermittent.
- Direct Radiography:Amorphous silicon or selenium flat panels convert X-ray photons to electrical signals without intermediate processing. Ontario's acute care procurement committees specify DR systems for ALARA compliance, where dose reduction mandates command tender evaluation priority.
- Photostimulable Phosphor:Storage phosphor technology dominates legacy installed base awaiting upgrade.
- Flat Panel Technology:Active matrix arrays with thin-film transistor backplanes anchor new capital purchases.
Deployment volume currently favors Computed Radiography in budget-constrained settings. Direct Radiography claims the steepest expansion trajectory as detector manufacturing scale reduces unit costs and dose regulations tighten.
Application:
Clinical use case shapes equipment specification requirements from detector size to specialized image processing algorithms.
- General Radiography:Chest and abdominal imaging constitutes the highest procedure volume across Canadian healthcare systems. Provincial occupational health agencies enforce radiation exposure documentation for these routine examinations, driving preference for systems with automated dose area product logging.
- Orthopedic Imaging:Long-bone and joint studies require specialized positioning aids and weight-bearing capabilities. Saskatchewan's regional health authorities prioritize retrofit solutions for existing trauma bays where musculoskeletal injury volume strains conventional radiography throughput.
- Dental Imaging:Intraoral and panoramic systems operate under separate regulatory classification with distinct installation requirements.
- Cardiovascular Imaging:Angiography and fluoroscopy integration demands higher frame rates and specialized detector formats.
Procedure volume concentrates in General Radiography across all customer segments. Orthopedic Imaging is climbing fastest as population aging accelerates joint replacement assessments and fracture management demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's digital X-ray infrastructure originated in Ontario's post-war hospital expansion, where Toronto's teaching hospitals pioneered radiology department standardization. Provincial health authorities subsequently scaled procurement networks across five major regions.
Ontario
Toronto's Level 1 trauma centers drive demand for wireless portable units enabling intraoperative imaging without patient transport. Health Canada's Medical Devices Regulations enforcement concentrates device registration reviews in Ottawa, compressing approval timelines for flat panel detector systems. The Greater Toronto Area hosts the densest concentration of imaging centers piloting AI-enhanced screening protocols.
Quebec
Montreal's centralized health authority negotiates enterprise-wide service agreements spanning detector replacement cycles across 34 hospitals. The province's ALARA protocol mandates command preference for direct radiography systems in tender evaluations. Quebec City's university-affiliated hospitals prioritize experimental detector configurations for research applications.
British Columbia
Vancouver's health authority consolidates tender frameworks across regional hospital networks, standardizing equipment specifications province-wide. Provincial occupational health agencies enforce radiation exposure documentation requirements that shape procurement committee decisions. The Lower Mainland concentrates outpatient imaging center expansion as government shifts non-urgent diagnostics to ambulatory settings.
Alberta
Calgary's diagnostic imaging networks deploy computer-aided detection algorithms in high-efficiency screening environments where case volume justifies workstation automation. The province's medical physics specialist shortage extends equipment commissioning timelines. Edmonton anchors prairie-region trauma imaging requirements with specialized capital equipment budgets.
Atlantic Canada
Halifax's regional health authorities face extended lead times for premium detector modules due to supply concentration among Asian component suppliers. Federal healthcare infrastructure programs fund portable systems for remote community clinics across Nova Scotia and New Brunswick. St. John's Memorial University hospital serves as the sole tertiary referral center for Newfoundland's fly-in communities.
Canada Digital X-Ray Devices Market Competitive Environment
The competitive structure tilts toward diversified medical technology conglomerates with established service footprints. Vendor concentration remains moderate, with top-tier players commanding hospital procurement committees through compliance infrastructure and multi-provincial support networks. Three archetypes dominate: integrated imaging system manufacturers, specialized portable equipment developers, and third-party radiology service providers. Consolidation proceeds through strategic partnerships for AI algorithm integration and geographic expansion via mobile imaging service models.
Among diversified healthcare technology conglomerates, GE Healthcare, Siemens Healthineers, and Fujifilm Holdings Corporation occupy positions reflecting distinct strategic emphases. GE Healthcare exemplifies the installed-base leverage archetype, sustaining recurring revenue through service contracts across Canadian hospital networks. Siemens Healthineers represents R&D-intensive positioning in advanced detector technology. Fujifilm Holdings Corporation anchors the specialized portable systems segment, targeting deployment scenarios in remote and indigenous community clinics where infrastructure limitations constrain conventional equipment installation.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips NV |
| Canon Medical Systems Corporation |
| Fujifilm Holdings Corporation |
| Carestream Health |
| Shimadzu Corporation |
| Mindray Medical International |
| Hologic Inc |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up regional service providers are consolidating mobile imaging fleets across Ontario and Quebec, concentrating purchasing power for detector replacement cycles while compressing margins for system integrators unable to match enterprise-scale service bundling.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement evaluations, with premium tiers commanding spreads for wireless flat panel configurations and AI-enhanced workstation integration. Price differentiation rests on Health Canada Class III certification status and detector dose efficiency ratings under ALARA protocols. Cost compression in standard-tier fixed-room systems is intensifying because provincial procurement committees weight total cost of ownership over upfront capital outlay. Community hospitals and outpatient clinics exhibit highest price sensitivity, while Level 1 trauma centers prioritize workflow speed over unit economics.
Supply Chain Analysis
Amorphous silicon flat panel supply rests on Japanese and South Korean specialty semiconductor foundries, with secondary sourcing from Taiwanese component assemblers. Canadian system integrators draw from concentrated Asian detector module production, xenon gas supply for high-voltage generators, and precision mechanical fabrication from German and Swiss suppliers. Single-source vulnerability in premium selenium detector substrates creates exposure to export licensing delays. Distribution runs through authorized dealer networks with provincial service certification requirements, limiting direct manufacturer-to-hospital transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada digital X-ray devices market functions as a stable compounder, with provincial healthcare infrastructure commitments providing predictable replacement demand regardless of macroeconomic volatility.
For Market Incumbents: Deepen service contract penetration across British Columbia's consolidated health authority networks before competitive rebidding cycles commence. Secure backward integration into detector refurbishment capabilities to defend margin position against third-party parts suppliers. Health Canada's tightening post-market surveillance documentation requirements favor vendors with established quality management infrastructure. For New Entrants and Emerging Players: Begin with transportable computed radiography deployments in Atlantic Canada's remote community clinics, where infrastructure constraints and intermittent technical support access create protected market space. Federal healthcare infrastructure programs for indigenous communities offer the most penetrable entry vector. Partner with established mobile imaging service operators to bypass capital-intensive direct sales channel buildout. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap regional service specialists with concentrated provincial footprints and aging installed bases ripe for detector refresh cycles. Long-term viability hinges on recurring revenue share from software maintenance and AI algorithm licensing rather than hardware shipment volume. Watch Alberta's diagnostic imaging network AI pilot expansion as signal for workstation automation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Class III Registration | Accelerates commercialization timelines for flat panel detector systems in Ontario's acute care procurement committees. |
| Provincial Health Authority Partnership | Locks in enterprise-wide service agreements spanning detector replacement cycles across Quebec's 34-hospital network. |
| AI Algorithm Companion Development | Captures incremental workstation licensing revenue as Alberta's screening networks pilot computer-aided detection protocols. |
| Mobile Imaging Service Expansion | Addresses diagnostic gaps in northern indigenous communities through truck-mounted unit deployment models. |
| Detector Refurbishment Capability Buildout | Reduces total cost of ownership for budget-constrained community hospitals extending computed radiography system lifespans. |
Study Parameters
Multiple input streams — hospital procurement committee interviews, biomedical engineer surveys, and GPO contract database analysis — were reconciled against secondary validation from Health Canada device registration filings, provincial tender documentation, and CSA standards revision records. Primary fieldwork engaged radiology department heads, medical physics specialists, and diagnostic imaging network administrators across Ontario, Quebec, and British Columbia. Bottom-up equipment shipment estimates and top-down healthcare capital expenditure allocations were triangulated to constrain forecast variance.
Data-stream reconciliation anchored the analytical framework across the projection horizon, modeling demand by product type, end user category, detector technology architecture, and clinical application. Segmentation incorporated provincial regulatory cluster differences and health authority procurement centralization patterns. CAGRs were derived from replacement cycle analysis and ALARA protocol enforcement trajectories, with cross-checks against federal healthcare infrastructure program disbursement schedules and provincial occupational health agency inspection intensity.
Several conditions sit outside the modeled scope, including potential Health Canada Medical Devices Regulations reclassification, abrupt detector substrate supply disruptions, and provincial election outcomes affecting healthcare capital budgets. Forecasts reflect assumptions regarding stable federal transfer payment flows and continued provincial procurement consolidation. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
IV Therapy and Vein Access Devices Market
Medical Devices
Medical Bionic Implant Market
Medical Devices
Digital Body Thermometer Market
Medical Devices
Walkers and Rollators Market
Medical Devices
Brazil Ultrasound Devices Market
Medical Devices
Global Ureteroscopes Market
Medical Devices
Next-Generation Neurofeedback Device Market
Medical Devices
Heel and Elbow Suspension Market
Medical Devices
US Medical Device Outsourcing Market
Medical Devices
Lower Limb Prosthetics Market
Medical Devices
Sweden Ophthalmic Devices Market
Medical Devices
Intradermal Injections Market
Medical Devices
Europe Surgical Visualization Products Market
Medical Devices
Flow Cytometry Products Market
Medical Devices
Asia Pacific Brachytherapy Devices Market
Medical Devices
Bone Densitometer Devices Market