
 Wearable ECG Sensor Market | 2026-2036
Wearable ECG Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable ECG Sensor Market Analytics
Cloud-based arrhythmia monitoring subscriptions is pivoting hardware vendors toward recurring revenue models. AliveCor leverages physician dashboard integrations to sustain clinical channel loyalty. Medtronic anchors enterprise contracts with health systems through its cardiac data infrastructure. Abbott differentiates via extended ambulatory monitoring workflows that reduce false-positive burdens.
A wearable ECG sensor integrates biopotential electrodes, analog front-end amplifiers, and wireless transceivers to capture cardiac electrical activity continuously outside clinical settings, typically sampling at 256–512 Hz with motion artifact rejection algorithms for ambulatory use. Patch sensors and medical monitors lead clinical-grade revenue pools where reimbursement codes attach, while smartwatches dominate consumer volumes through retail channels. Dry electrode technology occupies the fastest-growing position as skin-contact reliability improves without conductive gels.
FDA 510(k) clearances and EU MDR conformity assessments shape product design requirements and market access timelines for wearable ECG devices across North America and Europe. HIPAA data governance in the US and GDPR health-data provisions in the EU constrain cloud architecture choices and cross-border data routing. Stakeholders must monitor evolving reimbursement decisions from CMS and national health technology assessment bodies that determine whether wearable ECG outputs qualify for diagnostic billing.
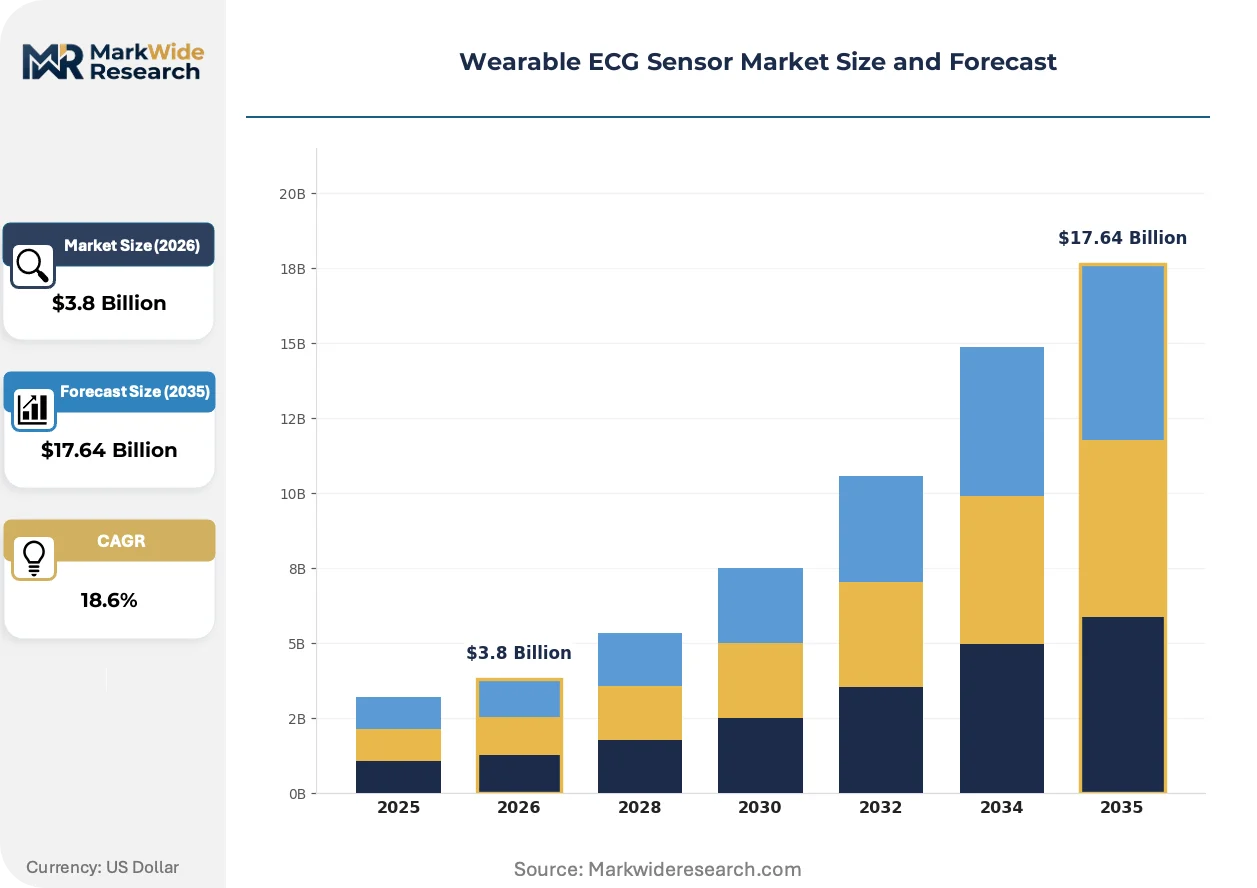
Market Dynamics
Cloud-based arrhythmia monitoring subscriptions are compressing hardware margins while expanding total addressable revenue pools through recurring physician dashboard integrations and health system enterprise contracts.
Growth Catalysts
- FDA Breakthrough Device Designation:The FDA's accelerated pathway compresses commercialization timelines for patch-based systems, enabling faster clinical adoption across US hospital networks.
- Dry Electrode Technology:Skin-contact reliability improvements without conductive gels are expanding ambulatory monitoring use cases beyond traditional clinical settings.
- Cardiology Clinic Chains:German healthcare providers are integrating wearable ECG data into electronic health records, creating institutional demand for interoperable systems.
Market Restraints
- GDPR Health-Data Provisions:Cross-border data routing constraints under EU regulations complicate cloud architecture choices for vendors serving European patients.
- Motion Artifact Rejection:Technical limitations in algorithm performance during high-activity states reduce diagnostic confidence for certain ambulatory use cases.
- Reimbursement Code Gaps:CMS and national health technology assessment bodies have not consistently classified wearable ECG outputs as billable diagnostic procedures.
Strategic Opportunities
- Extended Ambulatory Workflows:Multi-day monitoring protocols that reduce false-positive burdens address unmet clinical needs in arrhythmia detection.
- Smartwatch Consumer Channel:Retail distribution pathways for consumer-grade devices remain underpenetrated relative to clinical procurement volumes.
- EU MDR Conformity Assessments:The Medical Device Regulation's structured pathways create competitive differentiation for manufacturers achieving CE marking ahead of peers.
Industry Challenges
- HIPAA Data Governance:US healthcare data security requirements impose architectural constraints on cloud infrastructure design and vendor selection.
- Physician Workflow Integration:Electronic health record compatibility and dashboard usability determine clinical channel loyalty and sustained utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable ECG Sensor Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Medical Monitors, Patch Sensors Technology: Dry Electrode, Wet Electrode, Optical Sensor, Hybrid Sensor End User: Consumers, Healthcare Providers, Research Institutions, Fitness Professionals Delivery Mode: Bluetooth, Wi-Fi, Cellular, USB |
| Companies Covered | Apple, Medtronic, Fitbit, AliveCor, Samsung Electronics, Koninklijke Philips, iRhythm Technologies, Abbott, OMRON Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable ECG Sensor Market Evolving Landscape
Wearable ECG sensor architecture is converging around continuous monitoring capabilities that blur the boundary between consumer wellness and clinical-grade diagnostics.
Dry electrode materials are unifying skin-interface reliability with gel-free convenience, eliminating patient preparation friction. Cardiology clinics and remote patient monitoring programs are adopting these electrodes for 7-14 day ambulatory studies at accelerating rates. The technology is unifying previously separate consumer and clinical product categories into single-platform designs.
EU MDR conformity assessments are tightening clinical evidence requirements for wearable ECG devices seeking CE marking. Manufacturers must now submit expanded biocompatibility and electrical safety documentation. Patch-based systems targeting hospital procurement face the most significant timeline and cost adjustments.
Health system procurement committees are consolidating vendor relationships around integrated cardiac data infrastructure rather than standalone device purchases. Enterprise contracts now bundle hardware, cloud analytics, and physician dashboard access into multi-year agreements. This pattern is most visible in US hospital networks expanding remote patient monitoring programs.
Wearable ECG Sensor Market Segmentation
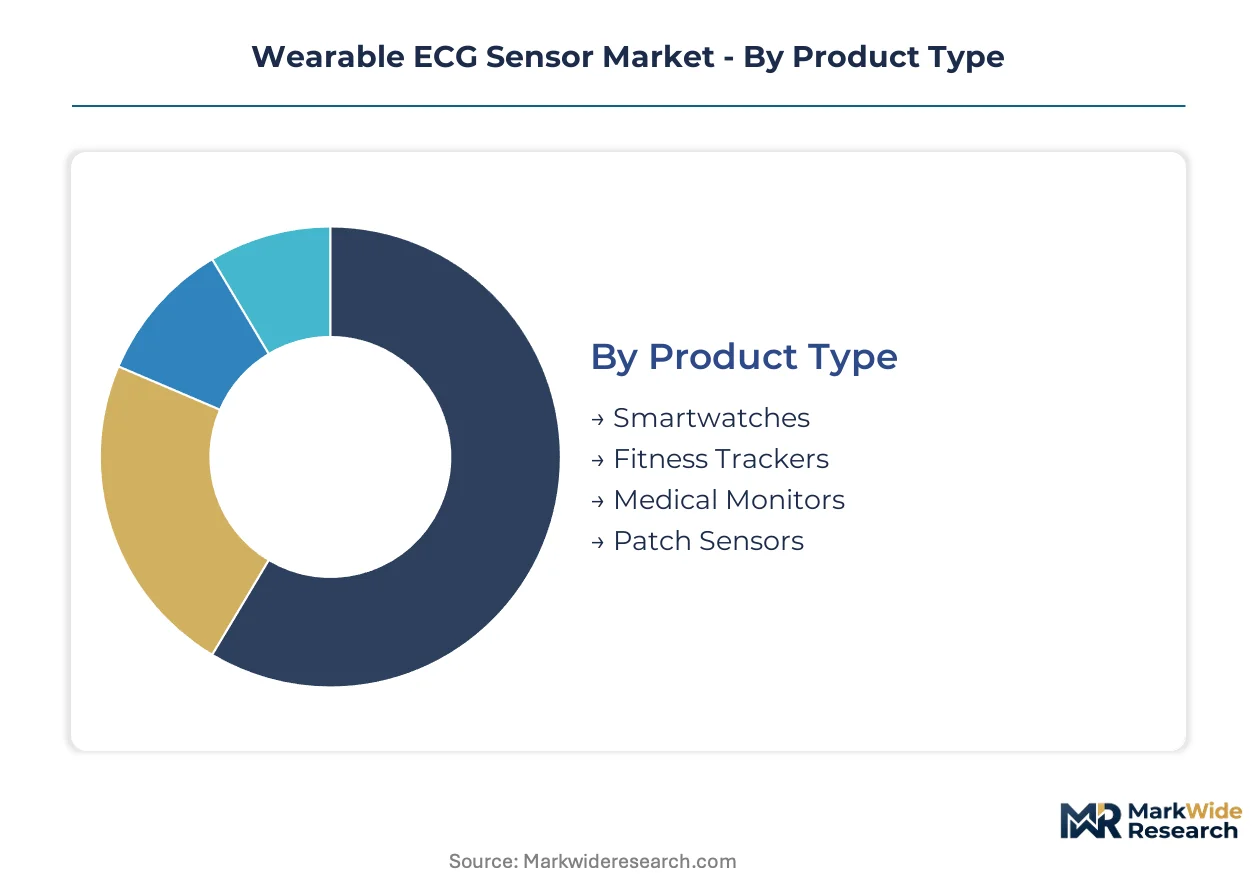
Wearable ECG sensor segmentation reveals divergent commercial models across clinical and consumer channels. Product architecture, electrode technology, and connectivity protocols each create distinct margin profiles and regulatory pathways that shape vendor strategic positioning.
Product Type:
Standardization dominates at the consumer tier while clinical applications demand extensive customization for workflow integration and reimbursement compliance.
- Patch Sensors:Adhesive-integrated electrodes with flexible substrate designs enable 7-14 day continuous monitoring without patient intervention. US hospital networks expanding remote patient monitoring programs anchor procurement volumes here, with FDA 510(k) clearance requirements filtering vendor participation.
- Smartwatches:Wrist-worn form factors with PPG-ECG hybrid architectures capture consumer volumes through retail channels. Germany's cardiology clinic chains increasingly validate these devices for preliminary screening, blurring wellness-clinical boundaries.
- Medical Monitors:Chest-worn or handheld devices with clinical-grade sampling rates target diagnostic workflows in cardiology practices.
- Fitness Trackers:Activity-optimized designs with reduced ECG fidelity serve wellness applications and athletic performance monitoring.
Most installed capacity flows through Patch Sensors. Expansion is steepest in Smartwatches.
Technology:
Cost tiers separate gel-dependent legacy systems from next-generation dry interfaces that eliminate consumable friction.
- Dry Electrode:Conductive polymer or metalized fabric interfaces achieve skin-contact stability without electrolytic gels. Ambulatory monitoring programs in German healthcare systems are accelerating procurement of these systems for extended wear protocols.
- Wet Electrode:Ag/AgCl gel-based interfaces maintain signal fidelity gold standards for short-duration diagnostic studies in clinical settings.
- Optical Sensor:Photoplethysmography-derived heart rate variability substitutes for electrical measurement in consumer wellness devices.
- Hybrid Sensor:Multi-modal architectures combining electrical and optical channels for artifact rejection in motion-intensive applications.
Dry Electrode systems command expanding share in new installations. Wet Electrode retains dominance in replacement cycles.
End User:
Application maturity separates established clinical reimbursement pathways from emerging direct-to-consumer revenue models.
- Healthcare Providers:Hospital systems and cardiology practices purchasing through group purchasing organizations with enterprise contract structures.
- Consumers:Individual purchasers through retail channels and direct-to-consumer telehealth platforms.
- Research Institutions:Academic medical centers and pharmaceutical trials requiring raw data access and protocol customization.
- Fitness Professionals:Sports medicine clinics and athletic training facilities optimizing performance and recovery monitoring.
Healthcare Providers absorb the majority of current procurement spend. Consumers are gaining share fastest.
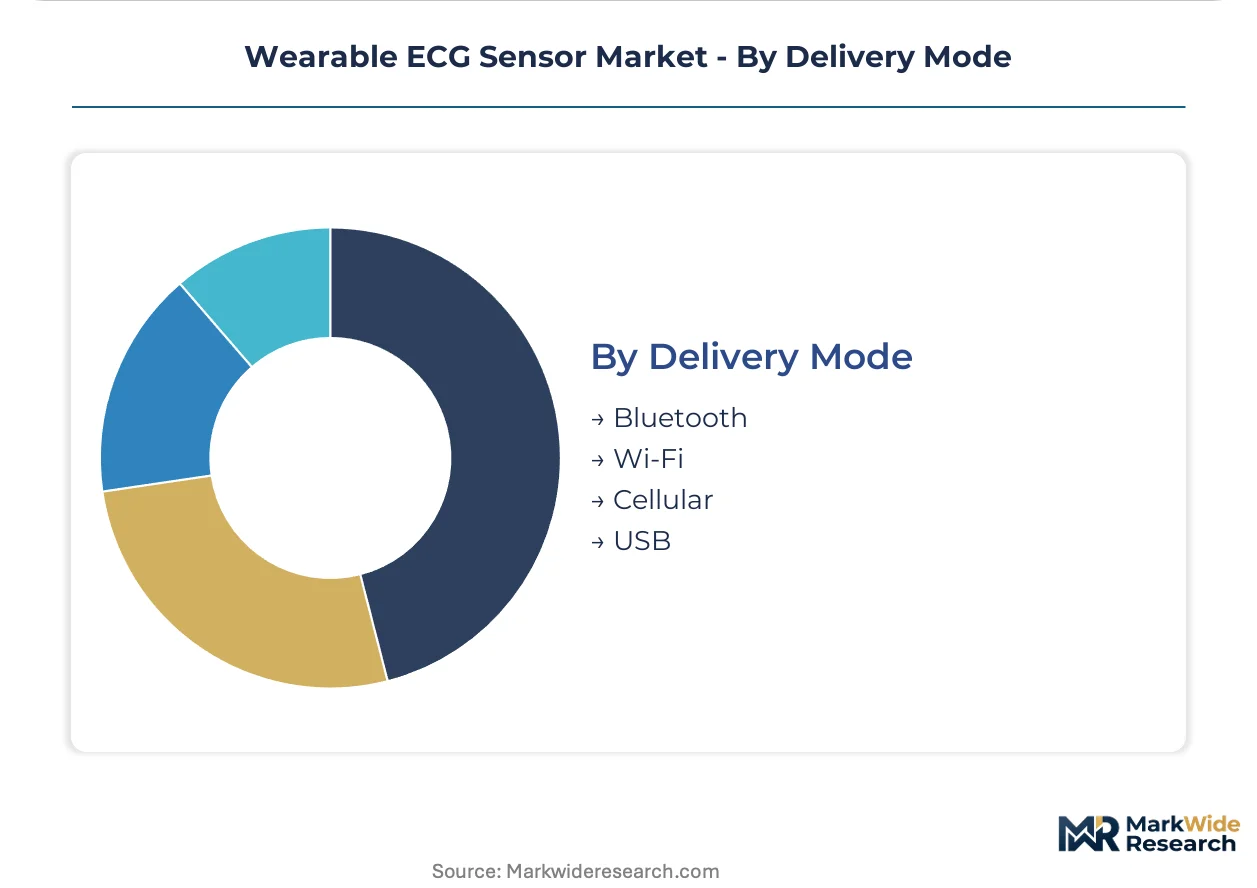
Delivery Mode:
Supply concentration in connectivity chipsets creates tiered performance-cost tradeoffs across use cases.
- Bluetooth:Low-energy protocols dominate smartphone-tethered consumer devices with 10-meter range constraints.
- Cellular:LTE-M and NB-IoT modules enable standalone operation for remote patient monitoring without patient smartphone dependency.
- Wi-Fi:Higher bandwidth supporting multi-sensor streaming in clinical hub configurations.
- USB:Wired connectivity for diagnostic-grade data transfer and device charging in stationary settings.
Bluetooth ships in greatest volume. Cellular is climbing the fastest as standalone clinical applications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's cardiology clinic chains integrate wearable ECG data into electronic health records faster than US hospital networks expand remote patient monitoring procurement, revealing divergent institutional adoption velocities across Atlantic markets.
United States
FDA breakthrough device designations compress commercialization timelines for patch-based systems while hospital procurement committees consolidate vendor relationships around integrated cardiac data infrastructure. HIPAA data governance constrains cloud architecture choices for vendors serving American patients. Boston and Minneapolis medical device clusters anchor enterprise contract negotiations with health systems.
Germany
Cardiology clinic chains drive institutional demand for interoperable systems that feed directly into electronic health records. EU MDR conformity assessments tighten clinical evidence requirements for CE marking, favoring manufacturers with expanded biocompatibility documentation. Baden-Württemberg and Bavaria host concentrated medical technology development centers advancing dry electrode reliability.
China
Domestic manufacturers scale production of consumer-grade smartwatch ECG modules for both local distribution and export markets. NMPA regulatory pathways increasingly align with international standards to accelerate market access for innovative devices. Shenzhen and Shanghai electronics manufacturing clusters integrate biopotential electrodes into wearable platforms at accelerating rates.
Japan
Aging demographics expand ambulatory monitoring demand through remote patient monitoring programs administered by regional healthcare cooperatives. PMDA review processes emphasize electrical safety documentation for extended-wear patch sensors. Tokyo and Osaka metropolitan areas concentrate physician dashboard integration development for cloud-based arrhythmia services.
United Kingdom
NHS long-term plan commitments fund wearable ECG deployment for atrial fibrillation screening in primary care networks. MHRA post-Brexit regulatory frameworks maintain alignment with EU MDR standards while streamlining conformity assessment timelines. Cambridge and Oxford medical technology corridors attract venture funding for next-generation dry electrode platforms.
Wearable ECG Sensor Market Competitive Landscape
Top-tier vendors anchor enterprise health system contracts, while mid-tier specialists compete on specific workflow integrations or electrode technology differentiation. The market structure concentrates around three strategic archetypes: diversified medical technology conglomerates with cardiac data infrastructure, pure-play wearable sensor developers with FDA-cleared algorithms, and consumer electronics giants leveraging retail distribution scale. Competitive moves center on physician dashboard integration capabilities and multi-year service bundling rather than hardware pricing alone.
Among diversified medical technology conglomerates, Medtronic and Abbott exemplify the enterprise-contract archetype through integrated cardiac data infrastructure offerings. AliveCor occupies a distinct position representing pure-play algorithm specialists with physician-facing dashboard platforms. Apple and Samsung Electronics anchor the consumer-electronics vector, leveraging smartphone ecosystem integration and retail channel density to capture wellness-oriented volumes.
| Leading Market Players |
|---|
| Apple |
| Medtronic |
| Fitbit |
| AliveCor |
| Samsung Electronics |
| Koninklijke Philips |
| iRhythm Technologies |
| Abbott |
| OMRON Corporation |
| Others |
Value Network & Pricing Analysis
EU MDR biocompatibility documentation requirements gate qualified supply for patch-based systems and command premium-tier pricing access for manufacturers with expanded clinical evidence packages. Cost compression in consumer-grade smartwatch modules intensifies margin pressure at the volume tier while clinical procurement committees absorb higher per-unit costs for enterprise-contracted cardiac data infrastructure.
Pricing Analysis
Capacity additions in China's Shenzhen electronics manufacturing clusters are reshaping price floors for consumer-grade ECG modules while FDA-cleared patch sensors maintain premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-contracted hospital systems from GPO-negotiated mid-tier procurement and direct-to-consumer retail channels. Pricing softness in Bluetooth-tethered devices reflects chipset commoditization, whereas cellular-enabled standalone monitors face limited price sensitivity from remote patient monitoring programs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Apple and Samsung Electronics while specialized distributors serve mid-tier clinical device manufacturers. Supply concentrates in China for flexible substrate fabrication, Taiwan for analog front-end chipsets, and Germany for medical-grade dry electrode polymers. Raw material dependencies include conductive polymer formulations, lithium-polymer cells, and low-energy Bluetooth SoCs. Single-source vulnerability in advanced biosensor foundry capacity exposes vendors to allocation risk during demand surges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in wearable ECG sensors rests on dry electrode cost-down curves and the shift toward recurring SaaS revenue from hardware-plus-subscription enterprise contracts. Cloud-based arrhythmia monitoring platforms capture pricing power that transactional device sales cannot match.
For Market Incumbents: Deepen physician dashboard integration capabilities to defend against pure-play algorithm specialists encroaching on clinical channel loyalty. Secure backward integration into dry electrode polymer supply to offset Ag/AgCl gel cost volatility and accelerate extended-wear protocol adoption across German cardiology clinic chains.
For New Entrants and Emerging Players: Capture the underpenetrated fitness professional segment with hybrid sensor architectures optimized for motion artifact rejection in athletic performance monitoring. Pursue direct-to-consumer telehealth platform partnerships as the fastest path to volume without health system procurement committee barriers.
For Investors and Strategic Acquirers: Roll-up economics work for pure-play wearable sensor developers with FDA-cleared algorithms because health system procurement committees increasingly consolidate vendor relationships around integrated cardiac data infrastructure rather than standalone hardware. Watch for inflection when CMS establishes consistent reimbursement codes for wearable ECG diagnostic outputs.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessments compress timeline advantage for prepared manufacturers against lagging peers. |
| Hospital System Partnership | Enterprise contracts with US hospital networks bundle hardware, cloud analytics, and physician dashboard access into multi-year agreements. |
| Software Companion Development | Physician-facing arrhythmia monitoring platforms convert transactional hardware sales into recurring subscription revenue pools. |
| Reimbursement Strategy | CMS diagnostic billing code qualification determines whether wearable ECG outputs capture clinical procurement budgets. |
| Geographic Expansion | German cardiology clinic chains integrate wearable data into electronic health records faster than other European markets. |
Research Methodology
Coverage spans the United States, Germany, China, Japan, and the United Kingdom, with primary inputs from each market cluster. The research combines interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists with secondary validation from FDA 510(k) filings, EU MDR conformity assessment databases, hospital procurement records, and CMS reimbursement decisions. Bottom-up demand modeling triangulates against top-down market sizing across product type, electrode technology, and end-user segments.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. The analytical framework models patch sensors, smartwatches, medical monitors, and fitness trackers by dry electrode, wet electrode, optical, and hybrid technology tiers, further segmented by healthcare provider, consumer, research institution, and fitness professional end users. CAGRs derive from installed base expansion rates, replacement cycle compression, and attach rates for cloud-based monitoring subscriptions. Forecast inputs include health system remote patient monitoring program expansion trajectories and EU MDR timeline impacts on CE marking velocity.
Underlying measurement precision varies by segment; patch sensors and medical monitors carry tighter precision than fitness trackers due to established reimbursement code attachment and clinical validation requirements. Forecasts reflect assumptions about regulatory pathway efficiency, cloud architecture compliance costs, and physician workflow integration adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Electronic Drug Delivery Systems Market
Medical Devices
Ambulatory Aids Market
Medical Devices
US SNF Based Dialysis Market
Medical Devices
Mobile Operating Rooms Market
Medical Devices
Medical Cyclotron Market
Medical Devices
Brachytherapy Market
Medical Devices
Pneumology Digital Stethoscope Market
Medical Devices
Incontinence Devices and Ostomy Market
Medical Devices
Europe Smart Bed Market
Medical Devices
North America Surgical Microscopes Market
Medical Devices
Global Diagnostic Catheter Market
Medical Devices
Continuous Bladder Irrigation Devices Market
Medical Devices
Temporary Cardiac Pacing Wires and Leads Market
Medical Devices
Global Asthma and Copd Devices Market
Medical Devices
Global Defibrillators Market
Medical Devices
Micro-Bypass Systems Market