
 Global Electromyography Devices Market | 2026-2036
Global Electromyography Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electromyography Devices Market Intelligence
A shift from single-vendor to multi-vendor procurement is recalibrating purchasing decisions within diagnostic laboratories and specialty centers. Medtronic plc leverages its vast distribution network to supply large hospital systems with integrated device portfolios. In contrast, Delsys Inc. specializes in high-performance surface EMG technology for sports science research. Cadwell Industries, Inc. focuses on neurodiagnostic systems tailored for clinical neurology departments.
Electromyography devices are medical instruments designed to measure and record the electrical activity produced by skeletal muscles, known as myoelectric signals. These systems use electrodes and high-gain amplifiers to detect minute voltage changes, aiding in the diagnosis of neuromuscular disorders like amyotrophic lateral sclerosis. While needle EMG remains the clinical standard for deep muscle analysis, non-invasive surface EMG is expanding rapidly in sports science and rehabilitation. Diagnostic laboratories and physiotherapy centers constitute the primary end-user base, with research institutes driving demand for advanced wireless systems.
Market access is governed by stringent medical device regulations, including FDA 510(k) clearance in the United States and CE marking under the Medical Device Regulation (MDR) in Europe. China's National Medical Products Administration (NMPA) also enforces distinct approval pathways, influencing product design. These frameworks mandate specific safety and performance standards for market entry. Navigating these diverse regulatory landscapes while advancing AI-powered signal analysis will define future market leaders.
Market Dynamics
The decentralization of neuromuscular diagnostics is the central force shaping the electromyography devices market. This shift is driven by the proliferation of portable and wireless systems, moving diagnostic capabilities from centralized hospital labs into specialized clinics, sports facilities, and remote care settings.
Growth Catalysts
- Expanding Clinical Applications:The use of EMG is growing beyond traditional neurology into sports medicine for injury prevention and performance optimization, as well as in ergonomic assessments within occupational health programs.
- Demographic Pressures:Aging populations in countries like Japan and Germany increase the prevalence of neuromuscular and degenerative diseases, spurring public health investment in advanced diagnostic tools like EMG.
- Technological Miniaturization:Advances in wireless sensor technology and low-power electronics enable the development of wearable, non-invasive surface EMG systems, improving patient comfort and facilitating long-term monitoring.
Market Restraints
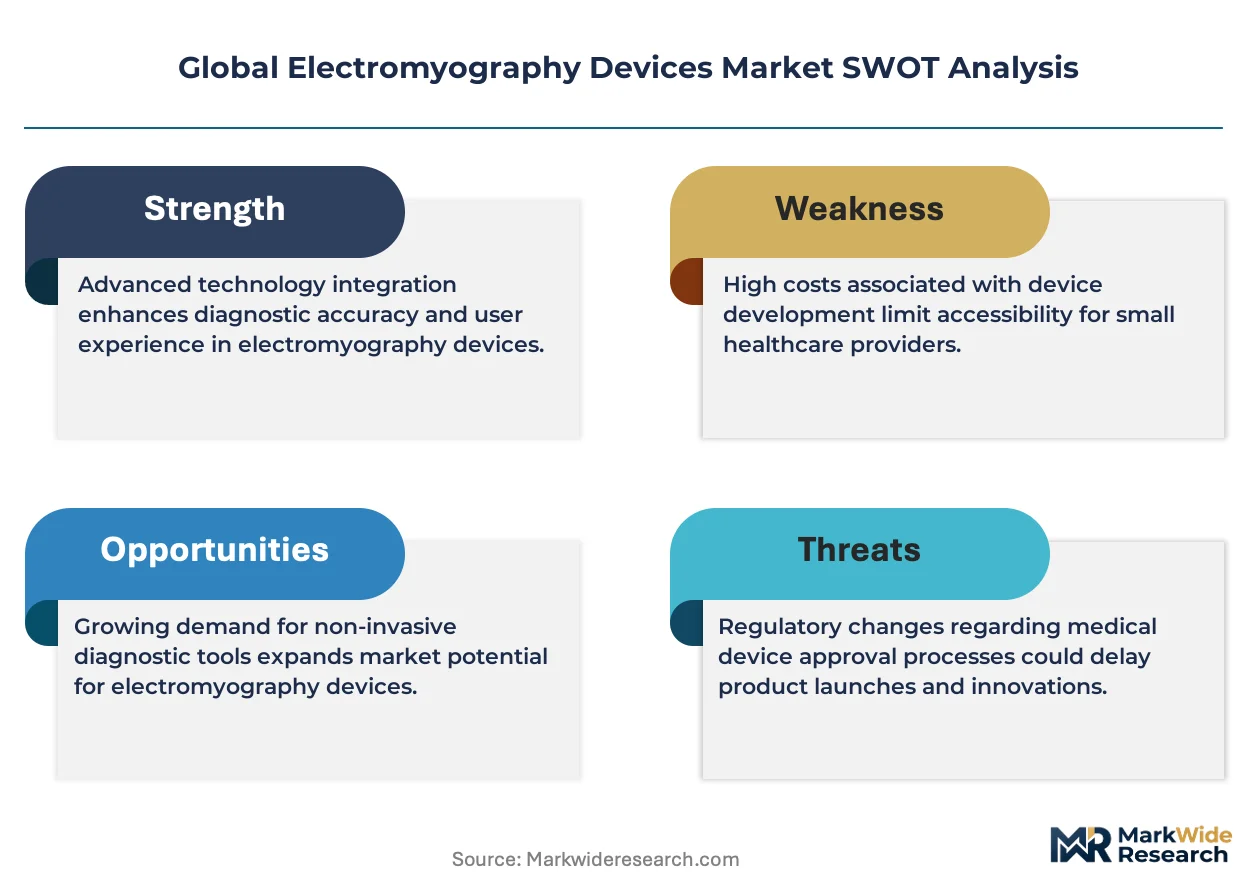
- High System Costs:The significant capital investment required for high-channel, research-grade EMG systems remains a barrier for smaller physiotherapy centers and independent diagnostic laboratories.
- Clinical Preference for Needle EMG:For definitive diagnosis of deep muscle pathologies, needle EMG remains the clinical gold standard, which can limit the adoption of surface EMG for certain core diagnostic procedures.
- Reimbursement Disparities:Inconsistent reimbursement policies for EMG procedures across different healthcare systems and private insurers can create economic uncertainty for providers and constrain investment.
Strategic Opportunities
- Telehealth Integration:Integrating portable EMG devices with telehealth platforms creates opportunities for remote patient monitoring and rehabilitation, particularly for post-stroke or post-surgery recovery programs.
- Emerging Market Penetration:Healthcare infrastructure development in Brazil and India presents significant growth potential for mid-range EMG systems tailored for general hospitals and new specialty clinics.
- AI-Powered Analytics:Developing artificial intelligence and machine learning algorithms to automate signal analysis and pattern recognition can simplify interpretation and support clinical decision-making.
Industry Challenges
- Data Standardization:A lack of universally accepted protocols for surface EMG data acquisition and processing hinders the comparability of research findings and the creation of large-scale clinical databases.
- Skilled Operator Scarcity:Effective use of advanced EMG systems and accurate interpretation of their outputs require specialized training, creating a skills gap for technicians and clinicians in some regions.
- System Interoperability:Integrating new wireless EMG devices with legacy hospital information systems and electronic health records (EHR) presents a significant technical and administrative challenge for healthcare providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electromyography Devices Market |
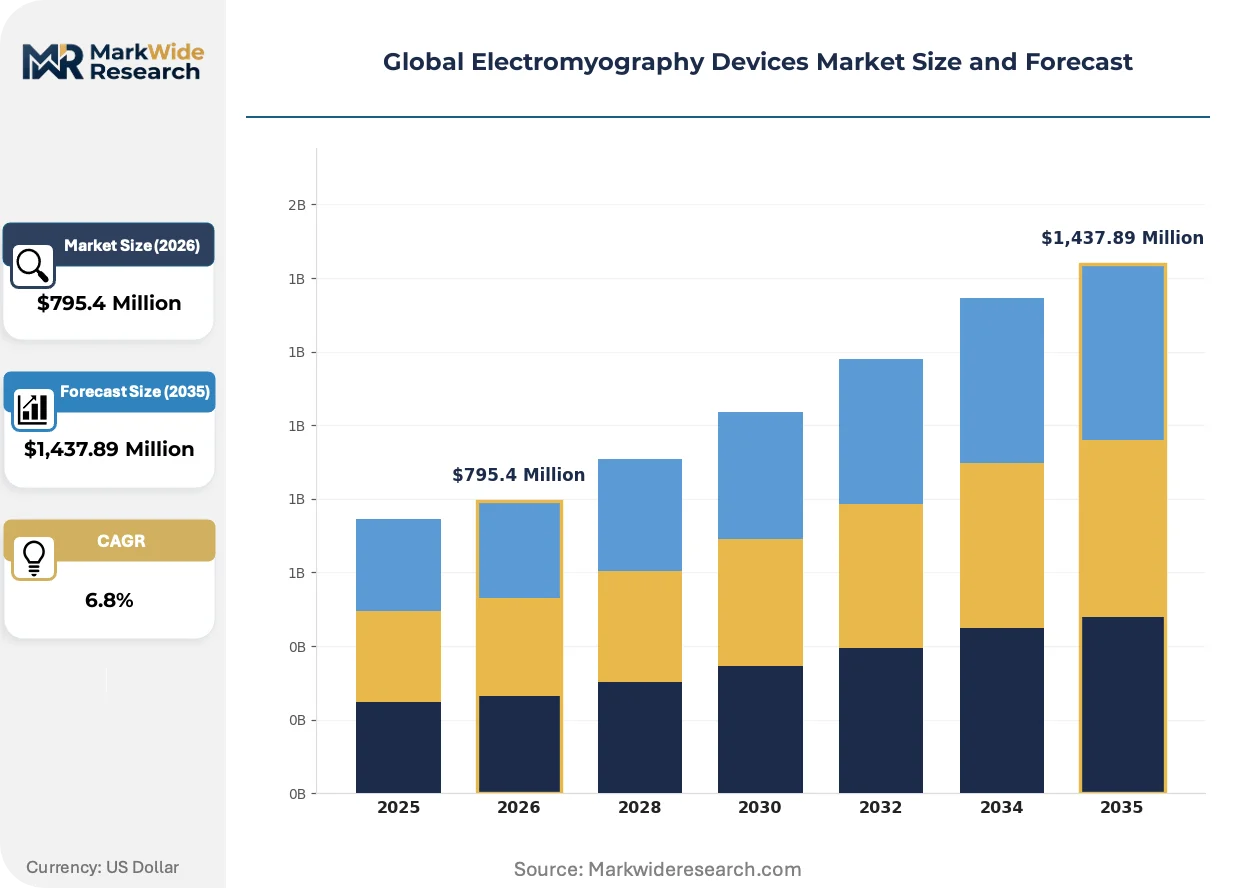
| Market Size in 2026 | $795.4 Million |
| Market Size in 2035 | $1,437.89 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Needle EMG, Surface EMG, Wireless EMG, Portable EMG, Ambulatory EMG Application: Neuromuscular Disorder Diagnosis, Rehabilitation, Sports Science, Ergonomics, Biofeedback End User: Diagnostic Laboratories, Research Institutes, Physiotherapy Centers, Sports Clinics, Specialty Centers Deployment: On-Premise, Cloud-Based, Hybrid, Remote Monitoring |
| Companies Covered | Cadwell Industries, Inc., Delsys Inc., Natus Medical Incorporated, Neurosoft Ltd., Noraxon U.S.A. Inc., Medtronic plc, Compumedics Limited, ADInstruments, Nihon Kohden Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electromyography Devices Market Strategic Shifts & Innovations
Device intelligence and enhanced connectivity are transforming electromyography from a purely diagnostic tool into an integrated component of continuous monitoring and therapeutic feedback loops. This evolution is driven by innovations in sensor design, regulatory frameworks mandating greater clinical evidence, and new service-oriented business models.
High-density surface EMG (HD-sEMG) arrays provide detailed spatial mapping of myoelectric activity across a muscle's surface. Sports science research institutes and advanced rehabilitation centers are the primary adopters of this technology for complex kinesiological studies. This advancement is modularizing the diagnostic process, allowing clinicians to use customized sensor grids tailored to specific muscle groups or research protocols.
The European Union's Medical Device Regulation (MDR) establishes more stringent requirements for clinical evidence and post-market surveillance. This policy increases the compliance burden for manufacturers seeking CE marking, particularly for software-driven and AI-enabled diagnostic systems. EMG systems classified as Class IIa are most affected, compelling vendors to invest heavily in updating technical files and quality management processes to maintain market access.
A transition toward subscription-based access for advanced EMG analysis software is altering purchasing patterns. This model lowers the initial capital barrier for smaller physiotherapy practices and university research labs, displacing the traditional one-time hardware sale. The trend is most prominent in North America and Western Europe, where robust cloud infrastructure facilitates the delivery of software-as-a-service (SaaS) platforms.
Global Electromyography Devices Market Segmentation
Understanding the distinct segments within the electromyography devices market provides clarity on specialized product development and targeted end-user engagement. This granular view highlights where technological innovation meets specific clinical and research demands, guiding strategic investment decisions for manufacturers.
Product Type:
The product type dimension delineates EMG systems by their core functional design and signal acquisition methodology.
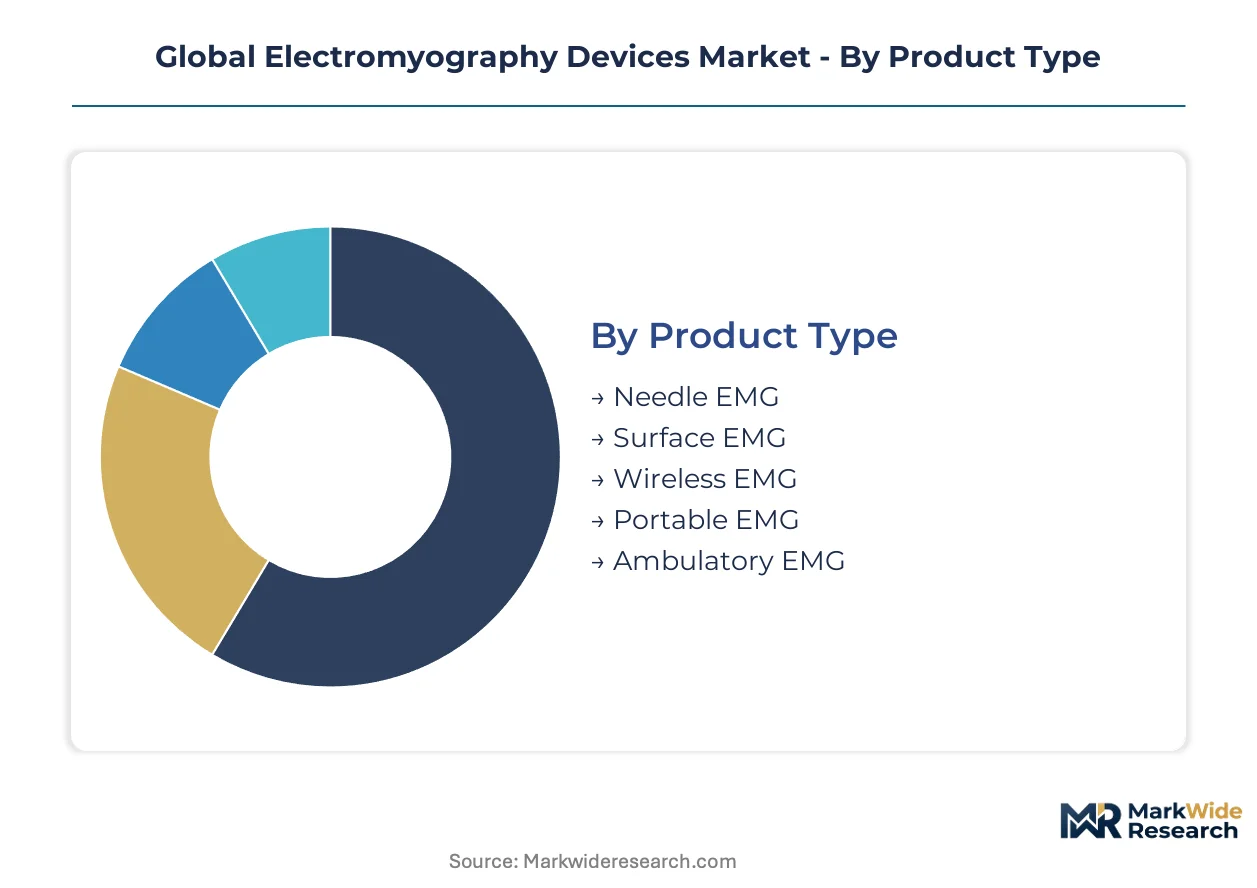
- Needle EMG:This invasive technique involves inserting fine needles into muscle tissue to record electrical activity, delivering precise data for diagnosing deep neuromuscular pathologies. Clinicians widely use needle EMG for definitive diagnosis of conditions like myasthenia gravis, particularly in hospitals across Germany and the United States.
- Surface EMG:Non-invasive surface electrodes detect electrical signals from muscles, commonly employed in rehabilitation and sports science for biofeedback and movement analysis. Demand for surface EMG is expanding within specialized sports clinics and physiotherapy centers seeking performance optimization tools.
- Wireless EMG:These systems transmit data without physical cables, enhancing patient mobility and comfort during assessments. Wireless EMG systems facilitate dynamic movement analysis in sports facilities and research settings.
- Portable EMG:Compact and lightweight devices allow for flexible use in various clinical and field settings, supporting decentralized diagnostic capabilities. Portable EMG systems are gaining traction in remote care and smaller specialty centers.
- Ambulatory EMG:Devices designed for continuous, long-term monitoring of muscle activity outside of a clinical environment, aiding in the assessment of chronic conditions. Ambulatory EMG provides valuable data for post-stroke rehabilitation programs.
Needle EMG leads on scale; Surface EMG leads on momentum.
Application:
Application segments illustrate the diverse clinical and research areas where electromyography devices provide critical insights.
- Neuromuscular Disorder Diagnosis:This primary application uses EMG to identify and characterize disorders affecting nerves and muscles, such as amyotrophic lateral sclerosis and carpal tunnel syndrome. Diagnostic laboratories rely heavily on EMG for precise disease identification.
- Rehabilitation:EMG devices assist in monitoring muscle recovery, guiding therapeutic exercises, and providing biofeedback for patients undergoing physical therapy after injury or surgery. Physiotherapy centers frequently integrate EMG for patient progress tracking.
- Sports Science:EMG technology analyzes muscle activation patterns during athletic performance, aiding in injury prevention, performance enhancement, and training optimization. High-performance sports academies use EMG for detailed biomechanical analysis.
- Ergonomics:EMG assesses muscle load and fatigue in occupational settings, helping to design safer workstations and prevent work-related musculoskeletal disorders. Corporate health programs increasingly utilize EMG for workplace assessments.
- Biofeedback:Patients learn to control physiological responses by receiving real-time information about their muscle activity, often used for pain management and muscle re-education. Biofeedback applications extend to specialized pain clinics.
Neuromuscular Disorder Diagnosis drives the largest volume; Sports Science demonstrates significant expansion.
End User:
The end-user segment highlights the primary types of facilities and institutions that procure and utilize EMG devices.
- Diagnostic Laboratories:These facilities conduct a wide range of neurological and muscular assessments, forming a core demand base for high-precision EMG systems. Centralized diagnostic labs in the United States maintain extensive EMG equipment.
- Research Institutes:Academic and private research entities utilize advanced EMG systems for studies in neuroscience, biomechanics, and rehabilitation, often requiring high-channel and specialized configurations. Universities in Europe drive demand for cutting-edge wireless EMG technology.
- Physiotherapy Centers:These centers employ EMG for patient assessment, biofeedback, and guiding rehabilitation exercises, especially for muscle re-education and recovery. Smaller physiotherapy clinics seek cost-effective portable EMG solutions.
- Sports Clinics:Specialized clinics focus on athletic performance analysis, injury diagnosis, and rehabilitation for athletes, integrating EMG for objective muscle function evaluation. Professional sports teams invest in advanced EMG for athlete monitoring.
- Specialty Centers:This category includes pain clinics, occupational health centers, and other niche medical facilities that use EMG for specific diagnostic or therapeutic purposes. Neurological specialty clinics require tailored EMG solutions.
Diagnostic Laboratories anchor the primary demand; Research Institutes represent a critical innovation hub.
Deployment:
Deployment models describe how EMG software and data management systems are structured and accessed by end-users.
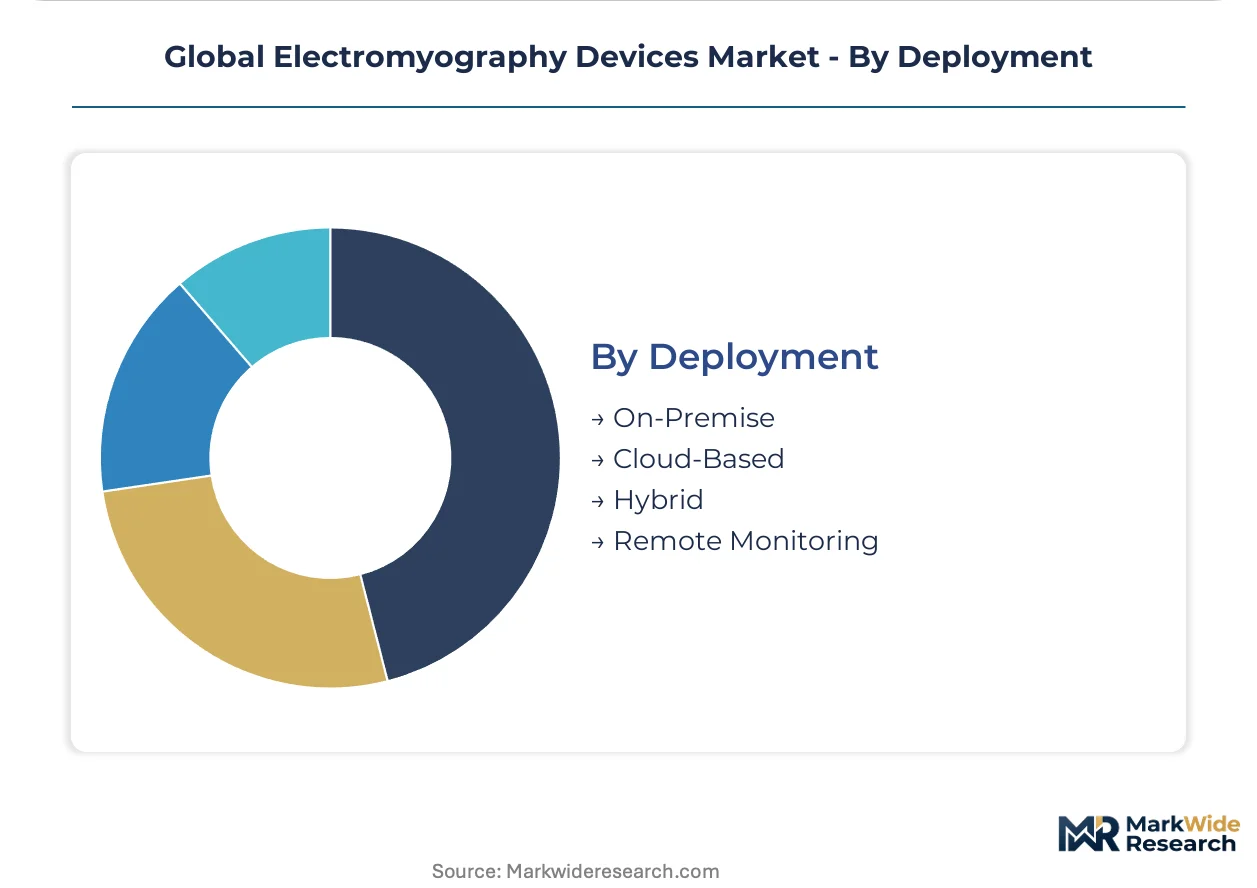
- On-Premise:Software and data are hosted and managed directly on the end-user's local servers and infrastructure, offering full control over data security. Large hospital systems often prefer on-premise solutions for their established IT environments.
- Cloud-Based:EMG data and analysis software are accessed via internet servers, offering scalability, remote access, and reduced IT overhead for users. Smaller clinics and remote care providers increasingly adopt cloud-based platforms for flexibility.
- Hybrid:This model combines elements of both on-premise and cloud-based solutions, allowing for a balance of local control and remote accessibility. Hybrid deployments suit organizations with specific data residency requirements.
- Remote Monitoring:Systems designed to continuously track EMG signals from patients outside traditional clinical settings, often integrating with telehealth platforms. Remote monitoring facilitates post-discharge patient management.
On-Premise solutions maintain a foundational presence; Cloud-Based models are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's advanced medical technology cluster drives significant innovation and demand within the electromyography devices market. Healthcare infrastructure maturity and specific demographic trends influence regional procurement patterns across the globe. Regulatory frameworks also shape product development and market access strategies for manufacturers.
United States
Demand for advanced neuromuscular diagnostic tools and sports science applications propels the market in the United States. FDA 510(k) clearance mandates rigorous safety and performance standards for market entry. Boston's biotech hub drives advanced neurodiagnostic research, fostering continuous innovation in EMG systems.
Germany
An aging population increases the prevalence of neuromuscular and degenerative diseases, spurring public health investment in EMG devices. CE marking under the Medical Device Regulation (MDR) sets stringent requirements for product approval. Munich's medical device manufacturers develop high-precision EMG systems for clinical neurology departments.
Japan
Demographic pressures and a focus on post-stroke rehabilitation programs contribute to the market's expansion in Japan. PMDA standards govern medical device approvals, ensuring product quality and efficacy. Tokyo's research institutes pioneer advanced wireless EMG applications for long-term patient monitoring.
India
Healthcare infrastructure development and the growth of specialty clinics present significant opportunities for mid-range EMG systems. CDSCO approval pathways influence product design for local market needs. Bengaluru's emerging medical technology sector increasingly adopts portable EMG solutions for diagnostic laboratories.
Brazil
Emerging market penetration and an expanding network of general hospitals are driving demand for accessible EMG technology. ANVISA regulations guide the market entry process for medical devices. São Paulo's growing hospital networks integrate portable EMG devices for decentralized diagnostic capabilities.
Global Electromyography Devices Market Key Industry Players
Global majors compete with regional champions across product portfolio and distribution reach within the electromyography devices market. The competitive structure features a mix of integrated device providers and specialized technology innovators. Strategic archetypes include comprehensive solution providers, high-performance niche players, and cost-effective system developers. Companies actively pursue strategic partnerships and geographic expansion to solidify their market positions.
Specialists in integrated solutions and high-performance technology shape the upper tiers of the market. Medtronic plc represents a global leader offering vast distribution networks and integrated device portfolios for large hospital systems. Delsys Inc. exemplifies a high-performance niche player, specializing in advanced surface EMG technology for sports science research. Cadwell Industries, Inc. occupies a position as a provider of neurodiagnostic systems tailored for clinical neurology departments.
| Leading Market Players |
|---|
| Cadwell Industries, Inc. |
| Delsys Inc. |
| Natus Medical Incorporated |
| Neurosoft Ltd. |
| Noraxon U.S.A. Inc. |
| Medtronic plc |
| Compumedics Limited |
| ADInstruments |
| Nihon Kohden Corporation |
| Others |
Cost & Logistics Intelligence
Private-equity-backed specialists in electromyography devices often drive supply consolidation, which in turn influences pricing strategies for advanced diagnostic systems. This dynamic shapes market access and competitive intensity.
Pricing Analysis
Input costs for high-precision sensors and advanced electronics are frequently passed through to end-users in the electromyography market. Pricing stratifies across premium, standard, and economy tiers, reflecting device capabilities and after-sales support. Reimbursement disparities across European and US healthcare systems create pricing pressure for providers. Smaller physiotherapy centers exhibit high price sensitivity, while large hospital systems prioritize comprehensive device portfolios.
Supply Chain Analysis
Workforce availability in specialized electronics manufacturing clusters in Germany and the United States influences the electromyography device supply chain. Production relies on microcontrollers and high-gain amplifiers sourced globally, with China serving as a key manufacturing hub for electronic components. Single-source vulnerability for advanced sensor components presents a structural risk. Distribution runs through direct sales teams for major hospital systems and regional channel partners for smaller specialty clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electromyography devices market functions as a stable compounder, driven by the consistent expansion of clinical applications beyond traditional neurology. This sustained demand underpins long-term investment viability.
For Market Incumbents: Anticipate continued pressure from emerging AI-driven diagnostic software by investing heavily in proprietary signal analysis algorithms. Secure FDA 510(k) and CE MDR approvals for next-generation wireless EMG systems to maintain market access. Deepen vertical integration into specialized sensor manufacturing to control component supply and costs. Strengthen distribution networks within advanced healthcare infrastructures in Germany and the United States.
For New Entrants and Emerging Players: Begin with developing cost-effective portable EMG solutions tailored for emerging markets like India and Brazil. Target smaller physiotherapy centers with subscription-based access models for advanced analysis software. Focus on AI-powered analytics to simplify interpretation, addressing the skilled operator scarcity. Leverage telehealth integration for remote patient monitoring in post-rehabilitation programs.
For Investors and Strategic Acquirers: Large medical technology conglomerates are the most active acquirers in this space, seeking to expand their integrated device portfolios. The market offers long-term viability over the next decade due to aging populations and expanding clinical applications. Target acquisition profiles include niche specialists in high-density surface EMG or AI-powered signal analysis. Regulatory clarity for AI-enabled medical devices represents a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance | Enables market entry and widespread adoption of new EMG devices in the United States. |
| Hospital System Integration | Secures large-volume contracts and streamlines device adoption within established healthcare networks. |
| AI-Powered Software Development | Automates signal analysis, reducing interpretation time and improving diagnostic accuracy for clinicians. |
| MDR CE Marking | Ensures compliance with stringent European medical device regulations for market access. |
| Telehealth Platform Partnership | Expands remote monitoring capabilities for post-rehabilitation and chronic condition management. |
Research Approach
Multiple input streams — primary interviews with neurologists, physiotherapists, and procurement managers, alongside secondary validation from medical device registries and academic journals — were reconciled to construct the market estimates. This approach integrated insights from key industry stakeholders with publicly available data. Bottom-up analysis of product segments was triangulated with top-down market sizing for comprehensive validation.
Historical market data was cross-referenced with expert panel input to project market trajectories across the analysis window. The analytical framework segmented the market by product type, application, end-user, and deployment model. Compound annual growth rates were derived from observed historical trends and projected future demand. Prevalence rates of neuromuscular disorders and healthcare expenditure growth served as critical forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen regulatory shifts or rapid technological obsolescence beyond current projections. Forecasts reflect assumptions about healthcare policy stability and sustained R&D investment. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Electric Breast Pumps Market
Medical Devices
Europe Foot Orthotic Insoles Market
Medical Devices
Global Walking Assist Devices Market
Medical Devices
Global Endovascular Aneurysm Repair Devices Market
Medical Devices
Auto Keratometer Market
Medical Devices
Global Cranial and Facial Implants Market
Medical Devices
Global Microscopy Device Market
Medical Devices
Global Disposable Medical Sensors Market
Medical Devices
Global Wearable Pregnancy Devices Market
Medical Devices
Wireless Handheld Ultrasound Devices Market
Medical Devices
Global Pediatric Medical Devices Market
Medical Devices
Global Gamma Probe Device Market
Medical Devices
Platelet Concentration Systems Market
Medical Devices
Polyp Trap Devices Market
Medical Devices
Low Flux Single-Use Dialyzers Market
Medical Devices
Global Intraoral Cameras Market