
 Microwave Ablation Devices Market | 2026-2036
Microwave Ablation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
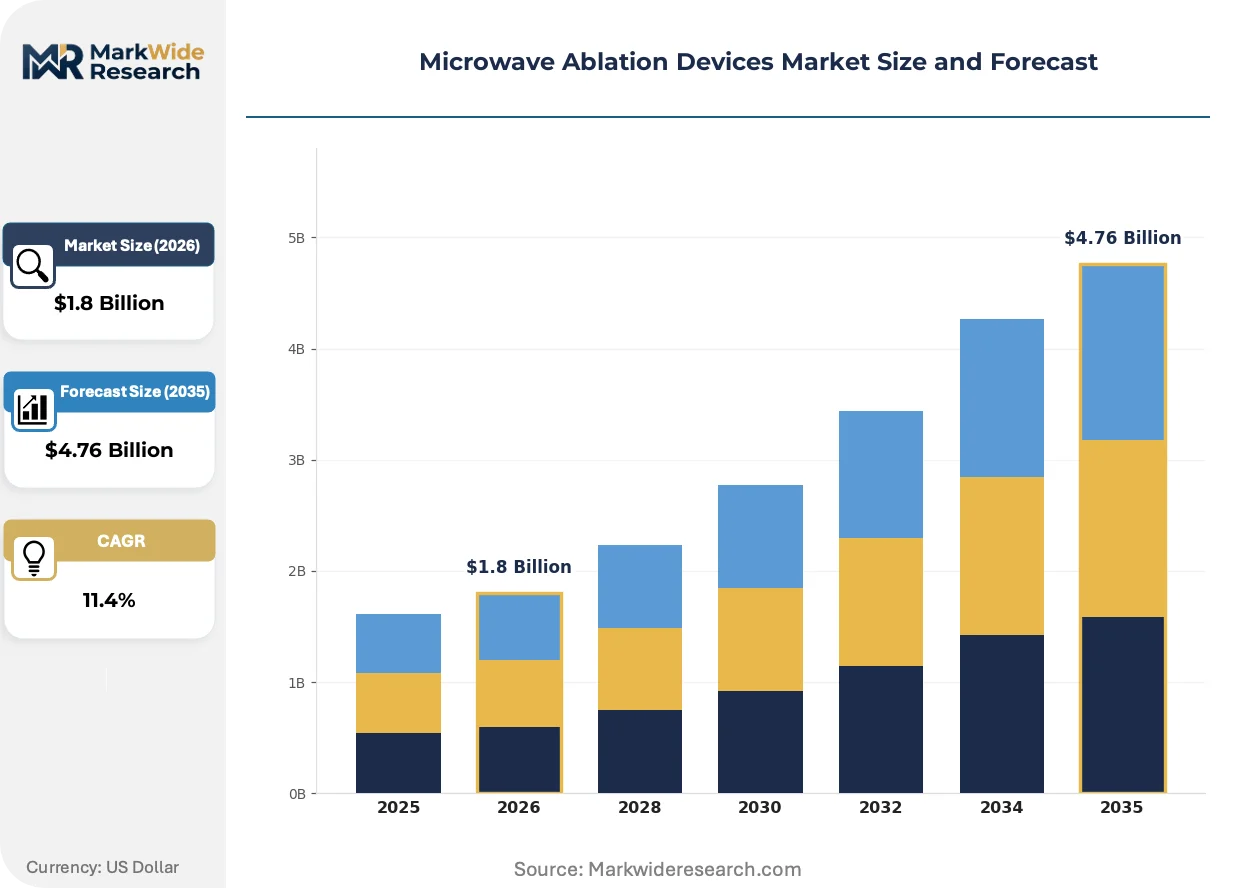
Microwave Ablation Devices Market Outlook
The microwave ablation devices market is pivoting on a widening gap between premium integrated systems and commoditized single-use antennas. Medtronic leverages its capital equipment footprint to bundle generators with proprietary consumables. Emblation Ltd. specializes in compact, portable generators for outpatient settings. Johnson & Johnson Services, Inc. sustains institutional loyalty through deep training ecosystems and clinical validation programs.
Microwave ablation devices generate electromagnetic energy at frequencies between 915 MHz and 2.45 GHz to induce thermal coagulation in targeted tissue, with generator output typically ranging from 20 to 100 watts depending on lesion size and tissue impedance. These systems serve interventional radiologists and surgeons seeking minimally destructive alternatives to resection across liver, lung, renal, and bone malignancies. Microwave generators command the largest installed base but face margin compression as dual-frequency and multi-frequency systems capture premium positioning through broader tissue applicability. Antennas and catheters generate recurring revenue streams that exceed hardware profitability over a system's lifecycle. Oncology dominates procedural volume while cardiology ablation applications remain nascent due to competing radiofrequency and cryoablation modalities.
FDA 510(k) clearance requirements govern device safety and electromagnetic compatibility in the United States, while the EU MDR mandates clinical evidence and post-market surveillance for CE marking in European markets. China's NMPA enforces GB standards for electromagnetic emissions and biocompatibility testing, creating layered compliance burdens for multinational manufacturers. Stakeholders must monitor evolving MDR technical documentation requirements and NMPA localization mandates to preserve market access across major jurisdictions.
Market Dynamics
The microwave ablation devices market is bifurcating between capital-intensive integrated suites and modular portable systems, with procurement officers at academic medical centers now weighting total cost of ownership against per-procedure economics in vendor selection.
Growth Catalysts
- Interventional Radiology Expansion:Oncology departments at tertiary hospitals in the United States, Germany, and China are building dedicated ablation programs, creating pull for generator-antenna bundles.
- EU MDR Compliance Pathways:Tightened clinical evidence requirements for CE marking are advantaging manufacturers with robust post-market surveillance infrastructure over smaller entrants.
- Dual-Frequency Generator Adoption:Systems operating at both 915 MHz and 2.45 GHz are capturing preference for their broader tissue applicability across hepatic and pulmonary lesions.
Market Restraints
- Input Cost Volatility:Specialized coaxial cable and ceramic antenna substrates face price pressure from concentrated suppliers in East Asian manufacturing clusters.
- Technical Limitation:Microwave energy propagation in high-impedance tissues such as bone and desiccated lung remains unpredictable, restricting reliable lesion control.
- Regulatory Friction:China's NMPA localization mandates for electromagnetic compatibility testing create timeline delays and duplicate certification costs for multinational manufacturers.
Strategic Opportunities
- Outpatient Migration:Ambulatory surgical centers in the United States are adopting compact, portable generators for same-day tumor ablation procedures.
- Cardiology Adjacency:Atrial fibrillation treatment represents an emerging application where microwave modalities compete with incumbent radiofrequency and cryoablation systems.
- Training Ecosystem Monetization:Deep clinical validation programs and proctoring networks create institutional loyalty and recurring service revenue beyond hardware sales.
Industry Challenges
- Interventional Radiologist Pipeline:The specialized skill set for image-guided thermal ablation creates talent scarcity that limits procedural volume expansion.
- Legacy System Integration:New generators must interface with existing imaging suites from multiple vendors, complicating electromagnetic compatibility certification.
- Post-Market Surveillance Burden:EU MDR requirements for systematic clinical follow-up strain quality assurance resources at mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microwave Ablation Devices Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cooling Systems, Microwave Generators, Catheters, Antennas Application: Oncology, Cardiology, Gynecology, Urology End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Research Institutions Technology: Single-Frequency, Dual-Frequency, Multi-Frequency, Continuous Wave |
| Companies Covered | Johnson & Johnson Services, Inc., MedWaves, Inc., Medtronic, HUBER+SUHNER, Varian Medical Systems, Inc., AngioDynamics, Emblation Ltd., Mermaid Medical, Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microwave Ablation Devices Market Strategic Shifts
Real-time temperature monitoring and energy delivery algorithms are displacing fixed-power protocols, enabling more predictable ablation zones and reducing procedure times. Three developments are restructuring competitive positioning.
Multipolar antenna arrays with synchronous energy delivery is integrating phased-field control to shape thermal lesions around vascular structures. Interventional radiologists at high-volume centers are adopting these systems for perivascular tumors where heat sink effects previously compromised outcomes. The technology is integrating predictive thermal modeling software that compresses the learning curve for complex anatomical targets.
China's NMPA has intensified GB standard enforcement for electromagnetic emissions and biocompatibility testing, extending approval timelines for imported devices. Manufacturers with established in-country testing partnerships are securing market access advantages. Dual-track regulatory strategies now dominate, with separate dossier preparation for NMPA versus FDA 510(k) pathways.
Hospital procurement committees are unbundling service contracts from capital equipment purchases, demanding itemized pricing for training, maintenance, and software upgrades. This shift is most visible in German university hospitals where public tender rules mandate transparent lifecycle costing. Vendors are responding with modular subscription tiers for algorithm updates and remote technical support.
Microwave Ablation Devices Market Segmentation
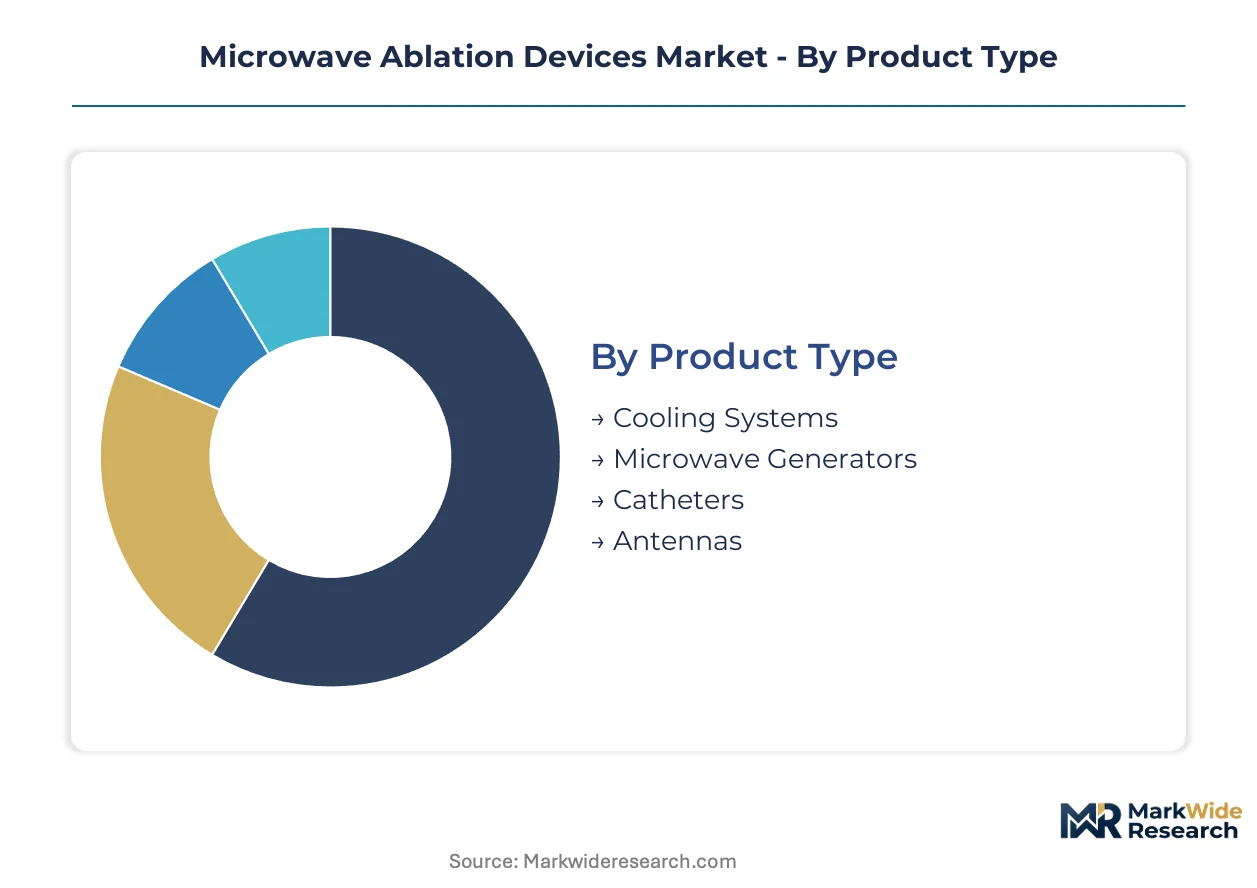
Microwave ablation devices fragment across hardware categories, clinical applications, and frequency technologies. Procurement patterns differ sharply between capital-intensive hospital systems and outpatient settings seeking portable solutions.
Product Type:
Volume deployment concentrates in consumable components with recurring revenue models, while premium positioning attaches to integrated generator systems with proprietary antenna compatibility.
- Microwave Generators:These units deliver electromagnetic energy at 915 MHz or 2.45 GHz with output ranging 20-100 watts. Demand clusters at academic medical centers in the United States, Germany, and China building interventional radiology capacity, though margin compression intensifies as dual-frequency systems capture preference.
- Antennas:Single-use coaxial devices with ceramic substrates and active cooling channels generate the highest recurring revenue streams across a system's lifecycle. Procurement officers at German university hospitals now unbundle antenna contracts from generator purchases, demanding transparent per-procedure economics.
- Catheters:Flexible delivery systems for percutaneous access.
- Cooling Systems:Circulating pumps and temperature management modules.
Mature deployment sits with microwave generators. Newer deployment is concentrated in specialized antenna arrays with synchronous energy delivery.
Application:
Oncology commands procedural volume through established reimbursement pathways, while cardiology represents an emerging frontier competing against entrenched radiofrequency modalities.
- Oncology:Hepatic, pulmonary, renal, and bone tumor ablation drives the majority of installed base expansion. Tertiary hospitals in the United States and China are building dedicated ablation programs, with interventional radiologists favoring microwave over radiofrequency for larger lesion volumes and reduced heat sink effects near vasculature.
- Cardiology:Atrial fibrillation treatment via pulmonary vein isolation remains nascent. Competing cryoablation and radiofrequency systems dominate electrophysiology labs, though microwave modalities offer theoretical advantages in lesion durability.
- Urology:Renal mass and prostate applications.
- Gynecology:Uterine fibroid and adenomyosis procedures.
Established reimbursement sits with oncology. Steepest expansion trajectory is emerging in cardiology as electrophysiologists evaluate microwave durability data.
End User:
Capital procurement authority differs across facility types, with hospital systems prioritizing total cost of ownership and ambulatory centers optimizing per-procedure throughput.
- Hospitals:Academic medical centers and tertiary facilities command the largest generator installed base. FDA 510(k) clearance and EU MDR compliance requirements advantage manufacturers with robust post-market surveillance infrastructure in these high-volume settings.
- Ambulatory Surgical Centers:Compact, portable generators from specialized vendors are gaining traction for same-day tumor ablation. United States outpatient migration is accelerating as payors shift site-of-service incentives.
- Specialty Clinics:Focused interventional radiology practices.
- Research Institutions:Preclinical and clinical trial deployment.
Hardware concentration sits with hospitals. Fastest volume gains are appearing in ambulatory surgical centers.
Technology:
Frequency versatility determines tissue applicability, with single-frequency legacy systems facing displacement from multi-frequency platforms.
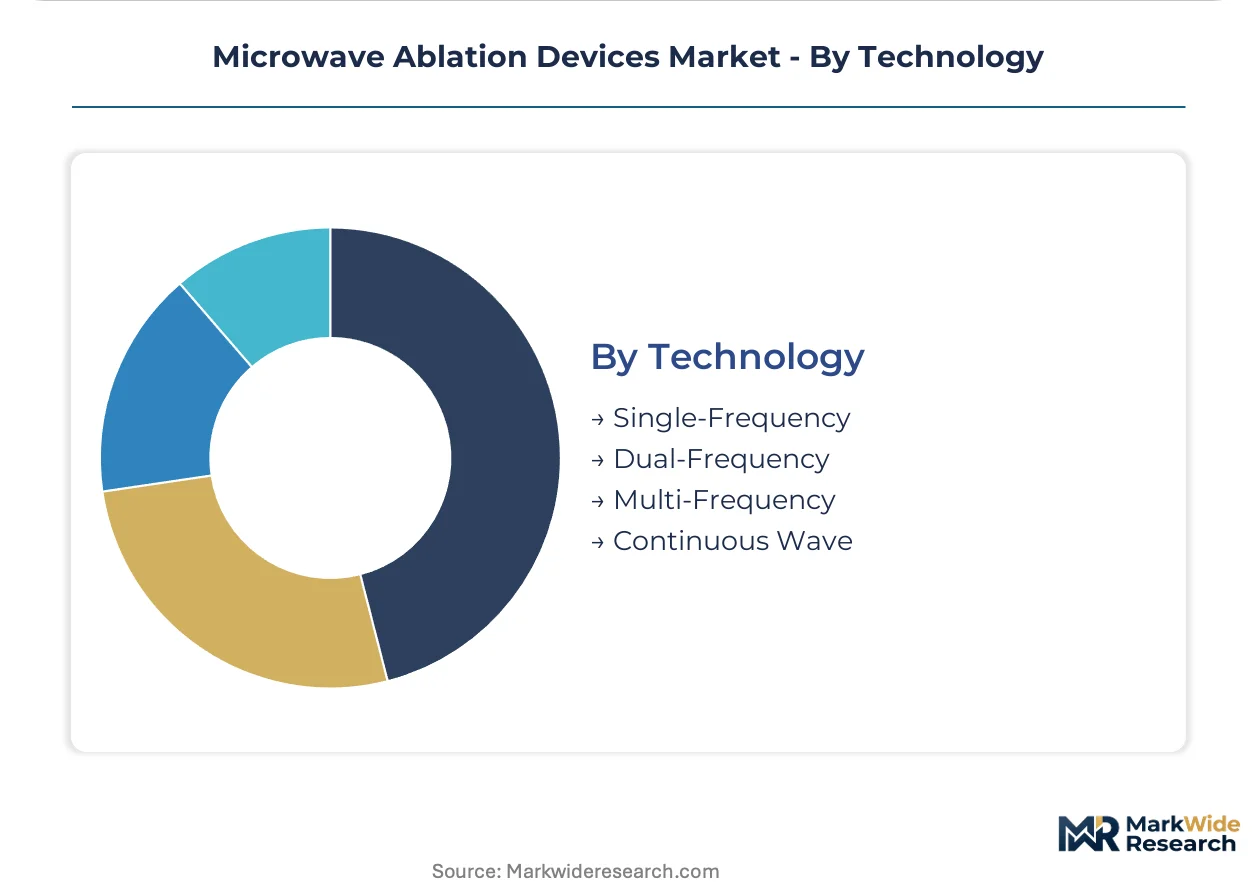
- Dual-Frequency:Systems operating at both 915 MHz and 2.45 GHz are capturing preference for broader tissue applicability across hepatic and pulmonary lesions. China's NMPA GB standard enforcement for electromagnetic compatibility testing creates timeline advantages for manufacturers with established in-country validation partnerships.
- Multi-Frequency:Advanced platforms with predictive thermal modeling software enable real-time lesion shaping around vascular structures. High-volume interventional radiology centers are adopting these systems for perivascular tumors where heat sink effects previously compromised outcomes.
- Single-Frequency:Legacy 915 MHz or 2.45 GHz only systems.
- Continuous Wave:Uninterrupted energy delivery protocols.
Installed base concentration sits with single-frequency systems. Technology migration is accelerating toward dual-frequency and multi-frequency platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors the most concentrated cluster of microwave ablation device development, with Medtronic's headquarters driving interventional radiology procurement standards across United States hospital systems.
United States
Tertiary hospitals in Texas and California are expanding dedicated ablation programs for hepatic and pulmonary malignancies. FDA 510(k) clearance pathways govern electromagnetic compatibility and biocompatility testing for all new device submissions. The Minneapolis medical technology corridor concentrates generator manufacturing and clinical training infrastructure.
Germany
University hospitals in Bavaria and North Rhine-Westphalia are unbundling service contracts from capital equipment purchases under public tender rules. EU MDR clinical evidence requirements advantage manufacturers with established post-market surveillance systems. The Munich-Stuttgart medical device belt hosts specialized testing laboratories for electromagnetic emissions validation.
China
Beijing and Shanghai tertiary centers are building interventional radiology capacity for liver and lung tumor ablation. NMPA GB standard enforcement for electromagnetic compatibility testing extends approval timelines for imported devices. The Yangtze River Delta region concentrates domestic antenna substrate manufacturing and in-country validation partnerships.
Japan
Metropolitan Tokyo hospitals are adopting dual-frequency systems for broader tissue applicability across hepatic lesions. PMDA pharmaceutical and medical device regulations mandate rigorous clinical evidence for thermal ablation technologies. The Osaka-Kobe medical technology corridor specializes in ceramic antenna component fabrication.
United Kingdom
London academic medical centers are evaluating portable generators for ambulatory surgical center migration. MHRA post-Brexit regulatory frameworks maintain alignment with EU MDR technical documentation standards. The Cambridge-Oxford health technology cluster drives early-stage thermal modeling software development.
Microwave Ablation Devices Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the microwave ablation devices market. Integrated system vendors with captive generator manufacturing face margin pressure from modular portable specialists. Three archetypes dominate: diversified medical technology conglomerates with deep training ecosystems, interventional radiology-focused device specialists, and compact outpatient system innovators. Competitive moves concentrate on dual-frequency technology licensing and unbundled service contract architectures.
Among diversified medical technology conglomerates, Johnson & Johnson Services, Inc. and Medtronic occupy positions defined by institutional loyalty programs and capital equipment bundling strategies. MedWaves, Inc. represents the interventional radiology specialist archetype with focused therapeutic device portfolios. Emblation Ltd. anchors the compact portable generator segment for ambulatory settings. Terumo Corporation exemplifies Asia-Pacific-based diversification across cardiovascular and interventional oncology modalities.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| MedWaves, Inc. |
| Medtronic |
| HUBER+SUHNER |
| Varian Medical Systems, Inc. |
| AngioDynamics |
| Emblation Ltd. |
| Mermaid Medical |
| Terumo Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive manufacturing of ceramic antenna substrates and specialized coaxial cable anchors both cost position and procurement leverage for microwave ablation device producers. This integration choice separates premium integrated system vendors from modular portable specialists competing on per-procedure economics.
Pricing Analysis
Value-based pricing anchored to clinical throughput and lesion predictability dominates procurement decisions at academic medical centers. Three-tier pricing structure across premium dual-frequency systems, standard single-frequency generators, and economy portable units reflects certification tier and after-sales service bundling. Cost compression in the antenna consumable tier is intensifying because procurement officers at German university hospitals now unbundle per-procedure contracts from capital equipment purchases. Ambulatory surgical centers exhibit highest price sensitivity; tertiary hospitals with dedicated ablation programs demonstrate lowest sensitivity due to reimbursement stability.
Supply Chain Analysis
Specialized coaxial cable supply rests on concentrated Japanese and South Korean specialty component producers. Ceramic antenna substrates draw from domestic Chinese manufacturing clusters in the Yangtze River Delta and precision fabricators in Japan's Osaka-Kobe corridor. Single-source vulnerability in high-purity dielectric materials creates exposure to logistics chokepoints through East Asian port congestion. Distribution runs through hospital procurement committees at academic medical centers and specialized interventional radiology distributors serving outpatient settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The microwave ablation devices market functions as a vertical-integration race where control over antenna substrate manufacturing and generator firmware development determines margin capture. Players are pursuing backward integration into ceramic component fabrication to secure supply and pricing power.
For Market Incumbents: Lock in institutional loyalty through captive training ecosystems and predictive thermal modeling software subscriptions that raise switching costs. Defend against portable generator entrants by bundling algorithm updates with generator service contracts. Deepen backward integration into ceramic antenna substrate production to offset input cost volatility from East Asian suppliers. For New Entrants and Emerging Players: Direct-to-clinician digital education platforms offer low-friction entry for compact portable systems targeting ambulatory surgical centers. White-space opportunity concentrates in United States outpatient migration where site-of-service incentives favor same-day tumor ablation. Target cardiology electrophysiology labs with microwave durability data for atrial fibrillation applications underserved by incumbent radiofrequency vendors. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified medical technology conglomerates seeking interventional radiology footprint. Long-term viability favors manufacturers with established NMPA validation partnerships and EU MDR post-market surveillance infrastructure. Monitor FDA 510(k) clearance timelines for dual-frequency systems as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Frequency Generator Development | Broadens tissue applicability across hepatic and pulmonary lesions for academic medical centers. |
| Antenna Substrate Backward Integration | Captive ceramic manufacturing reduces exposure to East Asian supply concentration and price volatility. |
| NMPA In-Country Validation Partnership | Accelerates China market access against competitors facing extended GB standard approval timelines. |
| Unbundled Service Contract Architecture | Meets German public tender transparency requirements while capturing recurring software revenue streams. |
| Cardiology Clinical Validation Program | Builds electrophysiologist adoption pathway for microwave modalities competing with radiofrequency systems. |
Study Parameters
Independent corroboration across interventional radiologists, hospital purchasing committees, biomedical engineers, and GPO contracts managers underwrites the qualitative findings. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation, NMPA approval databases, and hospital procurement records established the evidentiary base. Bottom-up antenna and generator shipment analysis triangulates against top-down ablation procedure volume estimates from Medicare claims and tertiary hospital utilization data.
Rate-of-change decomposition across product type, application, end user, technology, and regional regulatory clusters structured the analytical framework. CAGRs were derived from segmented volume and value modeling throughout the forecast period. Industry-specific inputs included interventional radiology fellowship graduation rates, NMPA localization mandate implementation timelines, and EU MDR post-market surveillance cost burdens.
Inputs from FDA 510(k) clearance databases and EU MDR notified body technical documentation were available through the study window; gaps in real-time China NMPA approval timelines introduce uncertainty bands around Asia-Pacific penetration assumptions. Forecasts reflect documented assumptions regarding reimbursement stability and interventional radiologist pipeline expansion. A small set of triggers—including NMPA electromagnetic compatibility enforcement shifts and cardiology microwave durability trial readouts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Image Guided Surgery Devices Market
Medical Devices
Global Scleral Lens Market
Medical Devices
Global Anastomosis Devices Market
Medical Devices
United States Respiratory Devices Market
Medical Devices
Pelvic Floor Stimulators Market
Medical Devices
Robotic Catheterization Systems Market
Medical Devices
Italy Respiratory Devices Market
Medical Devices
Japan Respiratory Devices Market
Medical Devices
3D Surgical Microscope Systems Market
Medical Devices
Prefilled Syringe Contract Manufacturing Market
Medical Devices
Arthroscopy Market
Medical Devices
Transradial Access Devices Market
Medical Devices
Gracey Curette Market
Medical Devices
Thoracolumbar Stabilization Devices Market
Medical Devices
Active Wheelchair Market
Medical Devices
Global Embolic Protection Device Market