
 India Biopsy Devices Market | 2026-2036
India Biopsy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
India Biopsy Devices Market Insights
Mumbai-based medical device manufacturing clusters is realigning production toward precision biopsy instrumentation for oncology workflows. Hologic Inc leverages its integrated women's health portfolio to sustain leadership in breast biopsy systems across Indian metro hospitals. Becton Dickinson and Co anchors its position through deep distribution into government procurement channels, while Medtronic Plc competes on advanced navigation-enabled platforms for neuro and thoracic applications.
Biopsy devices comprise instruments engineered to extract cellular or tissue specimens from living patients for histopathological, cytological, or molecular analysis, typically featuring gauge-optimized needles, vacuum-assisted suction mechanisms, or endoscopic forceps with specimen retrieval chambers. These systems serve the critical function of enabling definitive disease diagnosis while minimizing patient trauma and procedural risk. Needle biopsy instruments dominate procedural volumes in Indian oncology settings due to lower cost and outpatient compatibility, whereas vacuum-assisted biopsy configurations capture premium margins in breast care centers demanding larger contiguous tissue samples. Endoscopic biopsy modalities are expanding fastest among diagnostic laboratories adopting integrated gastrointestinal screening protocols.
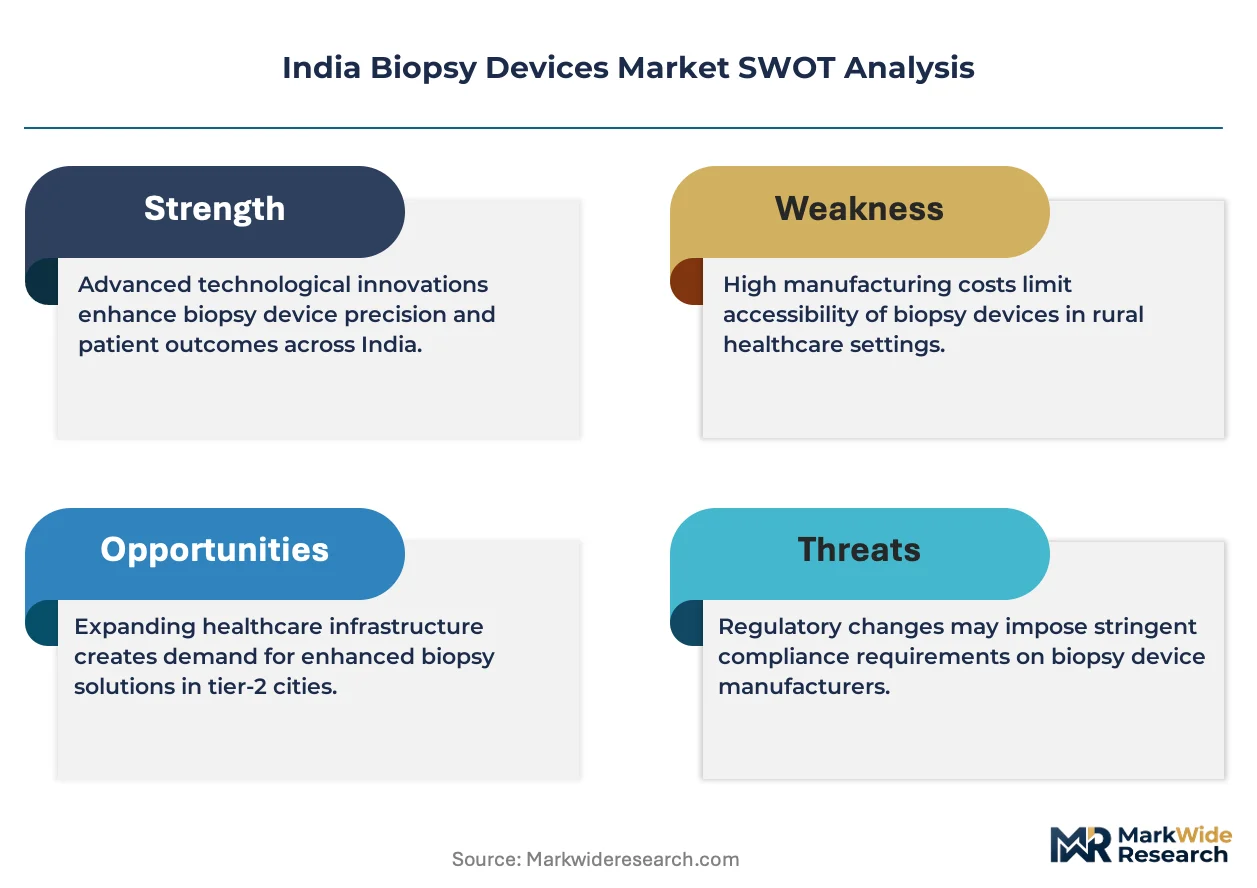
CDSCO regulates device licensing under the Medical Device Rules, while BIS mandates electrical safety and material biocompatibility standards for imported and domestically manufactured instruments. The PLI scheme for medical devices is reshaping capital allocation toward local production of core biopsy needles and guidance systems. Stakeholders must monitor how CDSCO's risk-based classification updates affect registration timelines for novel image-guided platforms entering the Indian market.
Market Dynamics
The PLI scheme for medical devices is redirecting capital toward domestic manufacturing of biopsy needles and guidance systems, compressing import dependence while reshaping supplier economics for Indian hospitals and diagnostic chains.
Growth Catalysts
- CDSCO risk-based classification:Streamlined licensing pathways for Class B and C biopsy devices are shortening registration timelines for novel image-guided platforms entering Indian tertiary care centers.
- Diagnostic laboratory consolidation:Large pathology chains in Maharashtra and Karnataka are standardizing on vacuum-assisted biopsy configurations to support molecular profiling workflows.
- Minimally invasive technique diffusion:Outpatient-compatible needle biopsy instruments are penetrating Tier-2 oncology centers previously limited to surgical excision.
Market Restraints
- Stainless steel and nitinol input volatility:Gauge-optimized needle manufacturing faces margin pressure from specialty alloy price swings tied to global commodity cycles.
- Import concentration for precision components:Vacuum-assisted suction mechanisms and navigation sensors remain dominated by German and Japanese suppliers, exposing Indian assemblers to forex and logistics risk.
- CDSCO technical documentation depth:Novel image-guided platforms require extensive clinical evidence packages that extend registration timelines beyond domestic capital patience.
Strategic Opportunities
- Tamil Nadu and Telangana diagnostic infrastructure:Greenfield cancer care investments in Chennai and Hyderabad offer first-mover positioning for integrated biopsy system vendors.
- Robotic navigation convergence:Fusion of electromagnetic tracking with CT-ultrasound registration is opening thoracic and renal biopsy applications previously restricted to surgical referral.
- BIS certification acceleration:Domestic manufacturers leveraging PLI incentives can capture institutional procurement preference through Make in India compliance thresholds.
Industry Challenges
- Interventional radiology specialist scarcity:Image-guided biopsy deployment outpaces trained operator availability in government hospital networks.
- CDSCO-BIS dual compliance synchronization:Electrical safety and material biocompatibility testing sequences create timeline misalignment for product launch planning.
- Legacy surgical pathology workflow integration:Digital specimen tracking and automated processing systems require reconfiguration of established histopathology laboratory layouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Biopsy Devices Market |
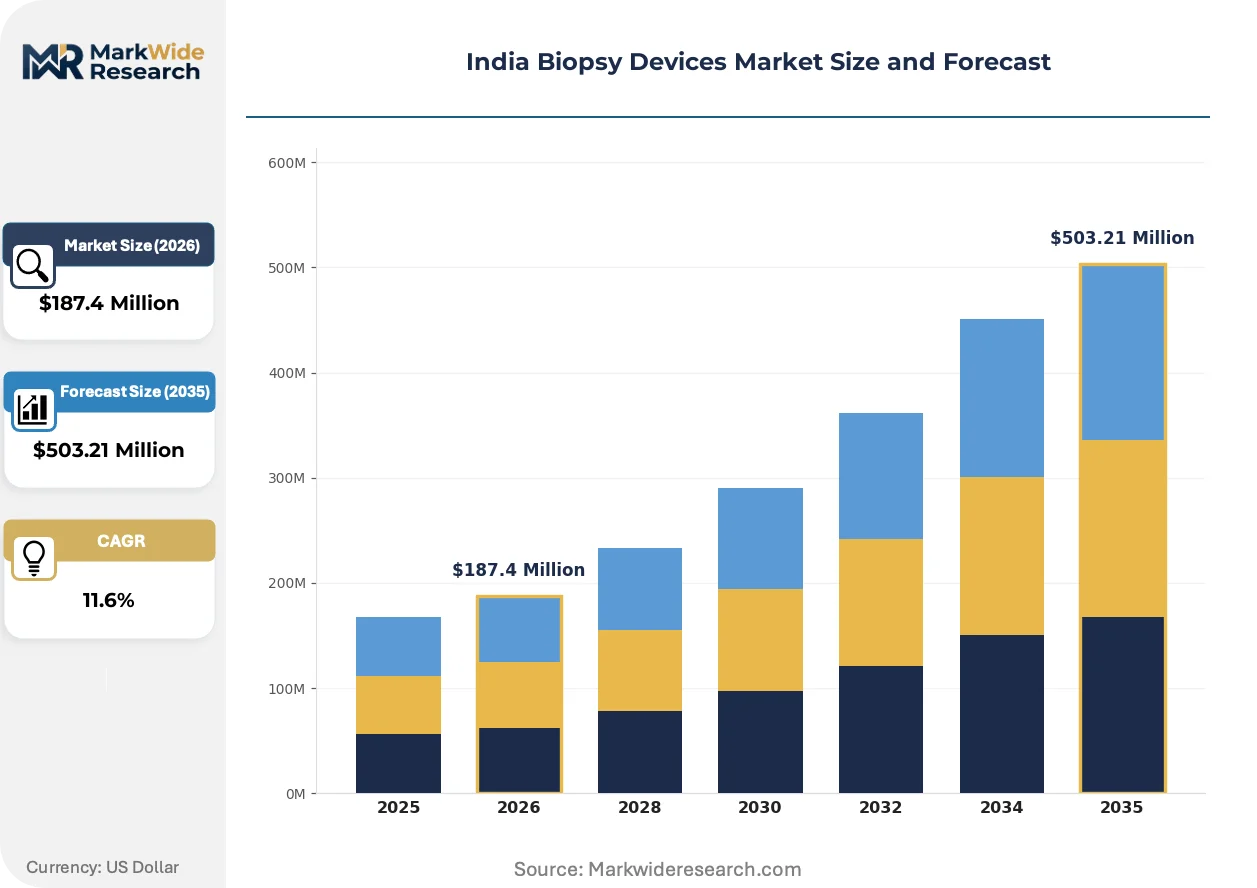
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Needle Biopsy, Endoscopic Biopsy, Surgical Biopsy, Vacuum-assisted Biopsy Procedure Type: Percutaneous, Open Surgical, Laparoscopic, Transbronchial End User: Hospitals, Diagnostic Laboratories, Academic Institutes, Research Centers Application: Cancer Diagnosis, Infectious Disease Detection, Genetic Testing, Inflammatory Conditions |
| Companies Covered | Hologic Inc, Argon Medical Devices Inc, Becton Dickinson and Co, Edges Medicare Pvt. Ltd, Medtronic Plc, Cardinal Health Inc, Boston Scientific Corp, Advin Health Care, B. Braun SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Biopsy Devices Market Trends and Innovations
Navigation-enabled platforms are redefining procedural precision expectations across Indian oncology settings, while regulatory frameworks and procurement behaviors undergo parallel transformation.
Electromagnetic tracking biopsy systems is overtaking mechanical freehand techniques in thoracic and abdominal applications. Tertiary cancer centers in Delhi and Mumbai are adopting these platforms at accelerating pace to reduce repeat sampling rates. The technology is overtaking conventional CT-guided approaches by enabling real-time needle tip visualization without continuous radiation exposure.
BIS electrical safety amendments under the Medical Device Rules are mandating updated insulation testing for imported biopsy generators. Domestic manufacturers must recertify existing product lines or risk exclusion from government tender eligibility. Breast care centers and interventional suites represent the most affected segments, with procurement teams prioritizing pre-certified alternatives to avoid installation delays.
Leasing arrangements for capital-intensive navigation platforms are displacing outright purchase in private hospital chains. Diagnostic laboratories in Karnataka and Maharashtra are shifting toward per-procedure service contracts that bundle maintenance and software updates. This restructuring is most visible among mid-tier oncology centers seeking access to advanced biopsy capabilities without balance sheet strain.
India Biopsy Devices Market Segmentation
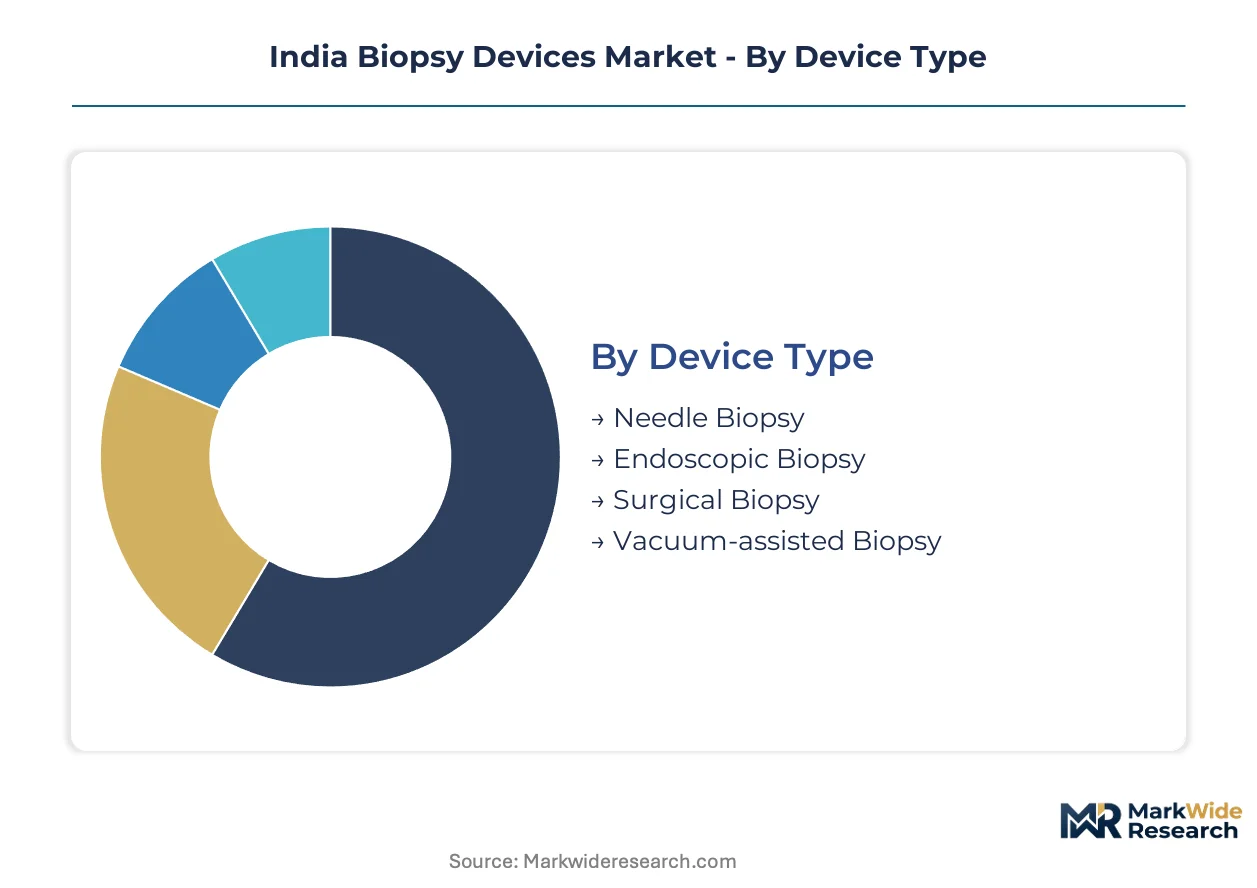
Biopsy device segmentation in India reflects divergent procurement priorities across public and private healthcare tiers, with cost sensitivity, procedural throughput, and diagnostic sophistication driving distinct purchasing behaviors.
Device Type:
Cost tier separates institutional buyers, with premium configurations targeting metropolitan cancer centers while basic instruments penetrate government hospital networks.
- Needle Biopsy:Gauge-optimized instruments ranging from 14G to 22G enable percutaneous tissue extraction with minimal trauma. Maharashtra and Karnataka diagnostic laboratories favor these systems for outpatient oncology workflows, constrained by stainless steel input price volatility.
- Vacuum-assisted Biopsy:Suction-integrated mechanisms retrieve larger contiguous tissue specimens for molecular profiling. Breast care centers in Mumbai and Delhi deploy these configurations despite premium pricing, driven by CDSCO's streamlined Class C licensing pathways.
- Endoscopic Biopsy:Forceps-based retrieval systems integrated with gastrointestinal screening protocols.
- Surgical Biopsy:Excisional and incisional instruments for definitive tissue diagnosis in complex cases.
Needle biopsy leads volumes today; vacuum-assisted configurations are gaining share fastest.
Procedure Type:
Application complexity dictates equipment investment, with image-guided methods commanding capital budgets while conventional techniques sustain high-throughput screening.
- Percutaneous:CT- or ultrasound-guided needle insertion through intact skin enables targeted organ sampling without surgical exposure. Tier-2 oncology centers in Tamil Nadu and Telangana adopt these techniques, expanding beyond traditional surgical referral patterns.
- Transbronchial:Bronchoscope-mediated lung tissue retrieval addresses thoracic diagnostic demand. Tertiary centers in Delhi deploy navigation-enabled platforms to reduce pneumothorax complications, though interventional pulmonologist scarcity limits diffusion.
- Open Surgical:Direct tissue excision under visualization for definitive diagnosis.
- Laparoscopic:Minimally invasive abdominal sampling through trocar access.
Percutaneous methods dominate procedural counts; transbronchial applications are climbing the fastest.
End User:
Customer type determines procurement channel, with government tenders favoring domestic BIS-certified suppliers while private chains negotiate bundled service contracts.
- Hospitals:Tertiary cancer centers and general medical facilities requiring integrated biopsy capabilities. Government hospital networks in Maharashtra concentrate demand for cost-optimized needle systems, constrained by interventional radiology specialist shortages.
- Diagnostic Laboratories:Dedicated pathology chains and imaging centers performing high-volume outpatient procedures. Large laboratory consolidations in Karnataka standardize on vacuum-assisted platforms to support molecular diagnostics pipelines.
- Academic Institutes:Teaching hospitals combining patient care with training missions.
- Research Centers:Specialized facilities conducting translational and clinical trial specimen collection.
Hospitals anchor current procurement volumes; diagnostic laboratories show steepest expansion trajectory.
Application:
Clinical urgency shapes reimbursement and investment priority, with oncology commanding premium technology allocation while infectious disease detection emphasizes throughput economics.
- Cancer Diagnosis:Histopathological confirmation and molecular subtyping for treatment selection. Mumbai and Delhi metropolitan clusters drive demand for navigation-enabled platforms, supported by PLI scheme domestic manufacturing incentives.
- Genetic Testing:Specimen collection for hereditary disease screening and pharmacogenomic analysis. Precision medicine programs in Hyderabad and Chennai create specialized demand for high-yield tissue retrieval systems.
- Infectious Disease Detection:Microbiological and histological confirmation of pathogenic conditions.
- Inflammatory Conditions:Tissue diagnosis for autoimmune and idiopathic disease processes.
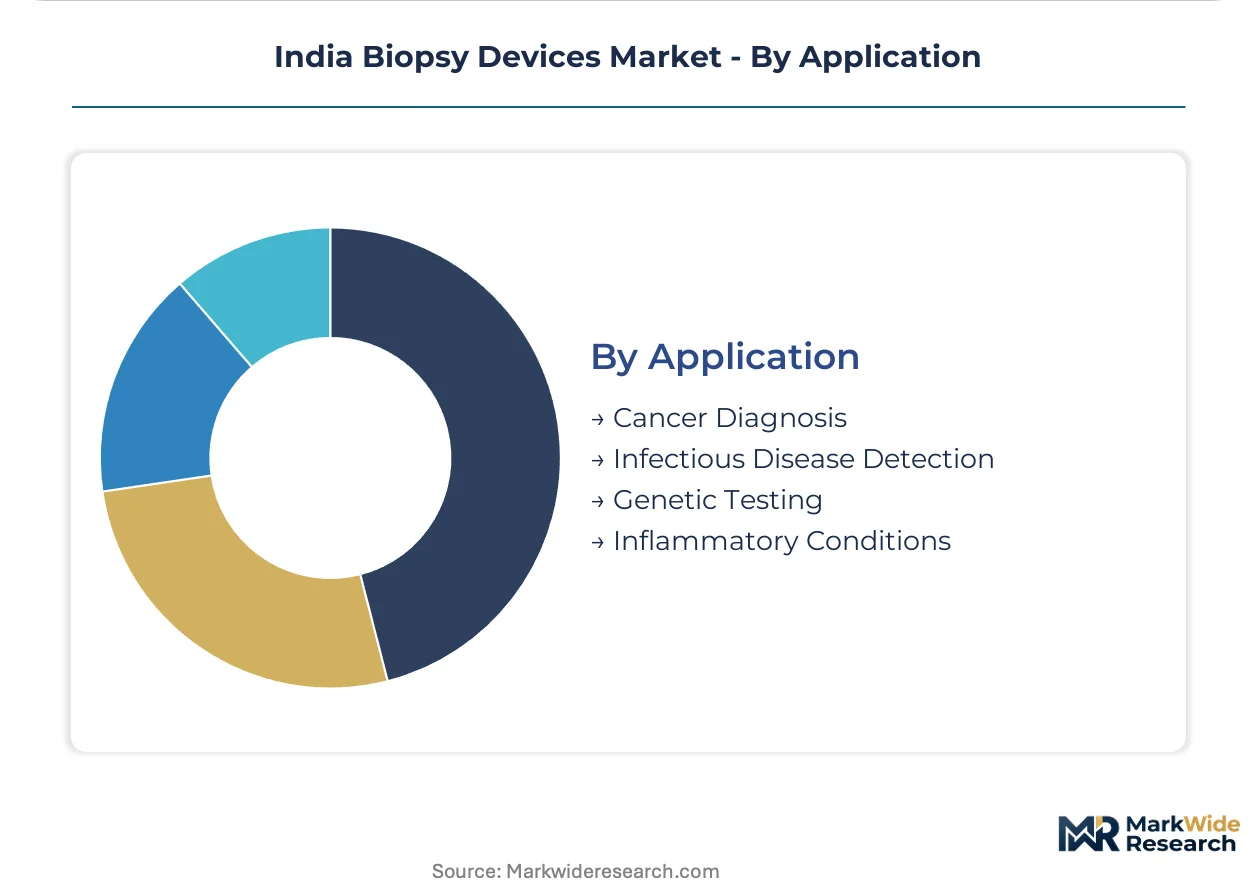
Cancer diagnosis commands dominant equipment allocation; genetic testing applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CDSCO's risk-based classification creates compliance-cost arbitrage that draws manufacturing investment toward states with established medical device clusters and streamlined BIS certification pathways.
Maharashtra
Mumbai and Pune host India's densest concentration of tertiary cancer centers, driving demand for vacuum-assisted biopsy platforms. The state's Medical Device Park in Solapur leverages PLI scheme incentives to attract needle assembly operations. Domestic manufacturers in the Mumbai-Ahmednagar corridor are scaling gauge-optimized instrument production for government hospital tenders.
Karnataka
Bengaluru's diagnostic laboratory chains are standardizing on integrated biopsy systems for molecular profiling workflows. CDSCO's regional office expedites Class C device registrations for companies locating technical documentation teams in the city. The Electronics City medical device cluster is attracting component suppliers for navigation-enabled platforms targeting neuro and thoracic applications.
Tamil Nadu
Chennai's greenfield cancer care investments create first-mover positioning for electromagnetic tracking biopsy vendors. The state's medical device policy offers capital subsidies that compress payback periods for precision instrument manufacturing. Sriperumbudur industrial belt is emerging as an assembly hub for cost-optimized needle systems serving Tier-2 oncology centers.
Telangana
Hyderabad's precision medicine programs generate specialized demand for high-yield tissue retrieval systems. The state's life sciences corridor provides shared testing infrastructure that reduces BIS electrical safety certification costs for domestic entrants. Genome Valley-based contract manufacturers are backward integrating into specialty alloy needle sourcing to mitigate import dependence.
Delhi-NCR
Government hospital networks in the capital concentrate demand for cost-optimized needle biopsy instruments constrained by interventional radiology specialist shortages. CDSCO headquarters proximity enables direct regulatory engagement for novel image-guided platform sponsors. Faridabad and Noida manufacturing zones are repurposing automotive component expertise toward precision biopsy instrumentation.
India Biopsy Devices Market Competitive Landscape
United States-based multinationals anchor the premium instrumentation tier; German and Japanese component specialists hold critical positions in vacuum-assisted suction mechanisms and navigation sensors. The supplier base organizes into three archetypes: integrated women's health portfolio owners, deep government procurement channel operators, and advanced navigation platform developers. Competitive maneuvering concentrates on PLI scheme qualification for domestic manufacturing and bundled per-procedure service contracts displacing outright capital purchases.
Among United States-based portfolio owners, Hologic Inc and Becton Dickinson and Co exemplify archetypes differentiated by channel strategy. Hologic Inc occupies a position aligned with metropolitan breast care center standardization, while Becton Dickinson and Co anchors government procurement preference through Make in India compliance thresholds. Medtronic Plc represents the navigation-enabled platform tier, sitting within the advanced thoracic and neuro application segment where electromagnetic tracking convergence opens procedural expansion.
| Leading Market Players |
|---|
| Hologic Inc |
| Argon Medical Devices Inc |
| Becton Dickinson and Co |
| Edges Medicare Pvt. Ltd |
| Medtronic Plc |
| Cardinal Health Inc |
| Boston Scientific Corp |
| Advin Health Care |
| B. Braun SE |
| Others |
Pricing and Supply Chain Analysis
Captive needle assembly operations within Maharashtra's Medical Device Park anchor both supply security and pricing leverage for domestic manufacturers qualifying under PLI scheme incentives. This backward integration into gauge-optimized instrument production compresses import dependence while enabling competitive positioning against German and Japanese component suppliers in government tender channels.
Pricing Analysis
Distributor margins on vacuum-assisted biopsy systems absorb 18-25% of landed cost before reaching breast care centers in Mumbai and Delhi. Three-tier pricing structure across premium navigation-enabled platforms, standard vacuum-assisted configurations, and economy needle systems stratifies procurement by hospital tier. Cost compression in the economy segment intensifies as stainless steel input volatility squeezes domestic assemblers. Government hospital networks exhibit highest price sensitivity; metropolitan diagnostic chains prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Direct-to-hospital channels handle premium navigation platform demand from tertiary cancer centers in Delhi and Mumbai. Component sourcing draws from Germany for vacuum-assisted suction mechanisms, Japan for navigation sensors, and China for specialty alloy feedstock. Single-source vulnerability in electromagnetic tracking modules exposes Indian assemblers to logistics chokepoints. Distribution runs through government procurement portals for public hospital networks and GPO contracts for private chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on PLI scheme-enabled domestic manufacturing cost-downs and diagnostic laboratory consolidation shifting procurement toward bundled service contracts.
For Market Incumbents: Deploy PLI qualification as a defensive moat by accelerating Solapur facility investments ahead of CDSCO risk-based classification updates. Lock in government procurement preference through BIS certification depth while countering emerging domestic entrants with per-procedure leasing bundles that reduce capital barriers for mid-tier oncology centers. For New Entrants and Emerging Players: Enter via Tamil Nadu and Telangana greenfield cancer care investments where first-mover positioning in electromagnetic tracking systems remains uncontested. Target Tier-2 oncology centers in Chennai and Hyderabad with cost-optimized needle platforms compatible with existing CT-ultrasound infrastructure. Pursue diagnostic laboratory service contracts that bundle maintenance and software updates to displace outright capital purchases. For Investors and Strategic Acquirers: Roll-up economics work for domestic needle assembly specialists because PLI scheme incentives compress payback periods while CDSCO registration timelines create barriers to rapid competitor entry. Long-term viability centers on captive supply of specialty alloys and navigation sensor backward integration. Watch BIS electrical safety amendment implementation velocity as inflection indicator for procurement preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Class C Registration Acceleration | Streamlined licensing for vacuum-assisted platforms reduces time-to-revenue in Maharashtra diagnostic chains. |
| PLI Scheme Manufacturing Qualification | Domestic needle assembly in Solapur Medical Device Park captures government tender preference thresholds. |
| Per-Procedure Leasing Contracts | Service bundling shifts private hospital chains from capital purchase to operational expenditure models. |
| Electromagnetic Tracking Integration | Real-time needle visualization without continuous radiation exposure differentiates thoracic applications. |
| Diagnostic Laboratory Partnership | Standardized vacuum-assisted configurations in Karnataka pathology chains support molecular profiling pipelines. |
Research Methodology
Bottom-up hospital and diagnostic laboratory procurement modeling reconciled against top-down medical device import tracking forms the analytical core of this study. Primary interviews with interventional radiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from CDSCO registration databases, BIS certification records, PLI scheme beneficiary disclosures, and hospital procurement portals. Triangulation across these sources ensures segment-level volume and value estimates reflect actual institutional purchasing behavior.
Input-output matrices map gauge-optimized needle demand, vacuum-assisted system deployment, and navigation platform adoption across procedure type, end-user tier, and application segments over the projection horizon. CAGRs derive from procedure volume elasticity to cancer incidence trends, diagnostic laboratory consolidation rates, and technology substitution patterns in image-guided biopsy. Industry-specific forecast inputs include interventional radiologist supply growth and CDSCO risk-based classification implementation timelines.
The model holds under stable PLI scheme incentive continuity and CDSCO registration pathway predictability; deviation in specialty alloy price volatility or BIS-CDSCO compliance synchronization delays would shift volume trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Laparoscopic and Open Hernia Mesh Repair Surgery Market
Medical Devices
Brazil Artificial Organs and Bionic Implants Market
Medical Devices
Temporary Cardiac Pacing Wires and Leads Market
Medical Devices
Neuromodulation Devices Market
Medical Devices
Gel Implants Market
Medical Devices
Global Anesthesia Video Laryngoscope Market
Medical Devices
Anesthesia Laryngeal Masks Market
Medical Devices
Personal-Use Facial and Skin Therapy Devices Market
Medical Devices
ECG Patch and Holter Monitor Market
Medical Devices
Human Anatomical Models Market
Medical Devices
Tattoo Removal Lasers Market
Medical Devices
Global Urinary Incontinence Treatment Devices Market
Medical Devices
Bone Fixation Plates Market
Medical Devices
Bone Conduction Hearing Devices Market
Medical Devices
Pharma Robots Market
Medical Devices
Breast Biopsy Marker Market