
 Intravaginal Device Market | 2026-2036
Intravaginal Device Market Size, Share, and Industry Trends Forecast 2026-2036
Intravaginal Device Market Insights
Silicone elastomer is decoupling from legacy latex formulations across intravaginal device portfolios, cutting allergen liability and extending product lifecycles for reusable contraceptive rings. CooperSurgical Inc. leverages its vertically integrated manufacturing in Trumbull, Connecticut to control raw material sourcing for pessary and diaphragm lines. Bayer AG anchors European supply through its Kiel facility, where polymer compounding and finished-device molding occur under one roof. Hologic competes in the diagnostic segment with molecular collection devices that integrate specimen stability chemistry directly into intravaginal sampling platforms.
An intravaginal device is a medically engineered insert designed for placement within the vaginal canal to deliver therapeutic agents, provide physical contraceptive barriers, support pelvic organ prolapse, or collect diagnostic specimens; most commercial variants employ medical-grade silicone, thermoplastic elastomer, or hydrogel matrices shaped to conform to vaginal anatomy while maintaining positional stability during ambulation. Contraceptive devices retain the largest revenue share due to decades of clinical validation and established reimbursement codes across public health systems, though delivery devices for localized hormone administration are gaining fastest as pharmaceutical partners seek to bypass hepatic first-pass metabolism. Diagnostic devices occupy a narrower but higher-margin niche, with specimen collection platforms commanding premium pricing when paired with PCR or next-generation sequencing workflows in gynecological clinics.
FDA 510(k) clearance pathways and EU MDR conformity assessments govern market entry, with the latter requiring updated clinical evaluation reports and post-market surveillance systems that have extended approval timelines by twelve to eighteen months for medium-risk vaginal devices. BIS certification in India and CDSCO import licensing add compliance layers for manufacturers targeting Asia-Pacific expansion through contract manufacturing partnerships. Stakeholders must monitor how FDA draft guidance on women's health trial design and EU MDR notified body capacity constraints reshape competitive access timelines and localization requirements.
Market Dynamics
The EU Medical Device Regulation is compressing competitive timelines for intravaginal device manufacturers, forcing material upgrades to silicone and hydrogel formulations while extending conformity assessment periods by twelve to eighteen months for Class IIa and IIb products.
Growth Catalysts
- EU MDR material mandates:Biocompatibility requirements for Class IIb vaginal devices are accelerating silicone elastomer adoption across contraceptive and therapeutic portfolios, cutting allergen liability for reusable ring formats.
- German gynecological clinic expansion:Outpatient procedural volume growth in Munich and Berlin procurement networks is sustaining demand for pessary and diagnostic collection devices.
- Localized hormone delivery:Pharmaceutical partnerships targeting hepatic bypass are pulling investment into intravaginal rings with sustained-release polymer matrices.
Market Restraints
- Notified body capacity constraints:EU MDR designation bottlenecks for vaginal device categories are extending time-to-market for medium-risk products beyond historical 510(k) baselines.
- Medical-grade silicone supply concentration:Polymer compounding capabilities for implantable-grade elastomers cluster in Connecticut and Kiel, creating geographic single-source exposure.
- Reusable device liability exposure:Extended product lifecycles for contraceptive rings amplify sterilization validation and post-market surveillance cost burdens.
Strategic Opportunities
- India CDSCO pathway acceleration:Import licensing and BIS certification harmonization for contract manufacturing partnerships opens Asia-Pacific volume expansion for Western device portfolios.
- PCR-integrated specimen collection:Molecular diagnostic workflows in gynecological clinics create premium pricing niches for intravaginal sampling platforms with built-in nucleic acid stabilization chemistry.
- France ANSM early engagement:Pre-submission consultation pathways for women's health devices offer faster conformity assessment routing than standard EU MDR notified body queues.
Industry Challenges
- Polymer science talent scarcity:Formulation chemistry expertise for hydrogel drug-device combination products concentrates in legacy pharmaceutical hubs, constraining R&D scaling.
- Legacy latex conversion capex:Manufacturing line retooling for silicone-exclusive production demands capital allocation that mid-tier manufacturers struggle to sequence alongside MDR compliance spending.
- Post-market surveillance system integration:EU MDR vigilance reporting requirements for vaginal devices force rebuilds of quality management infrastructure without grandfathering provisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intravaginal Device Market |
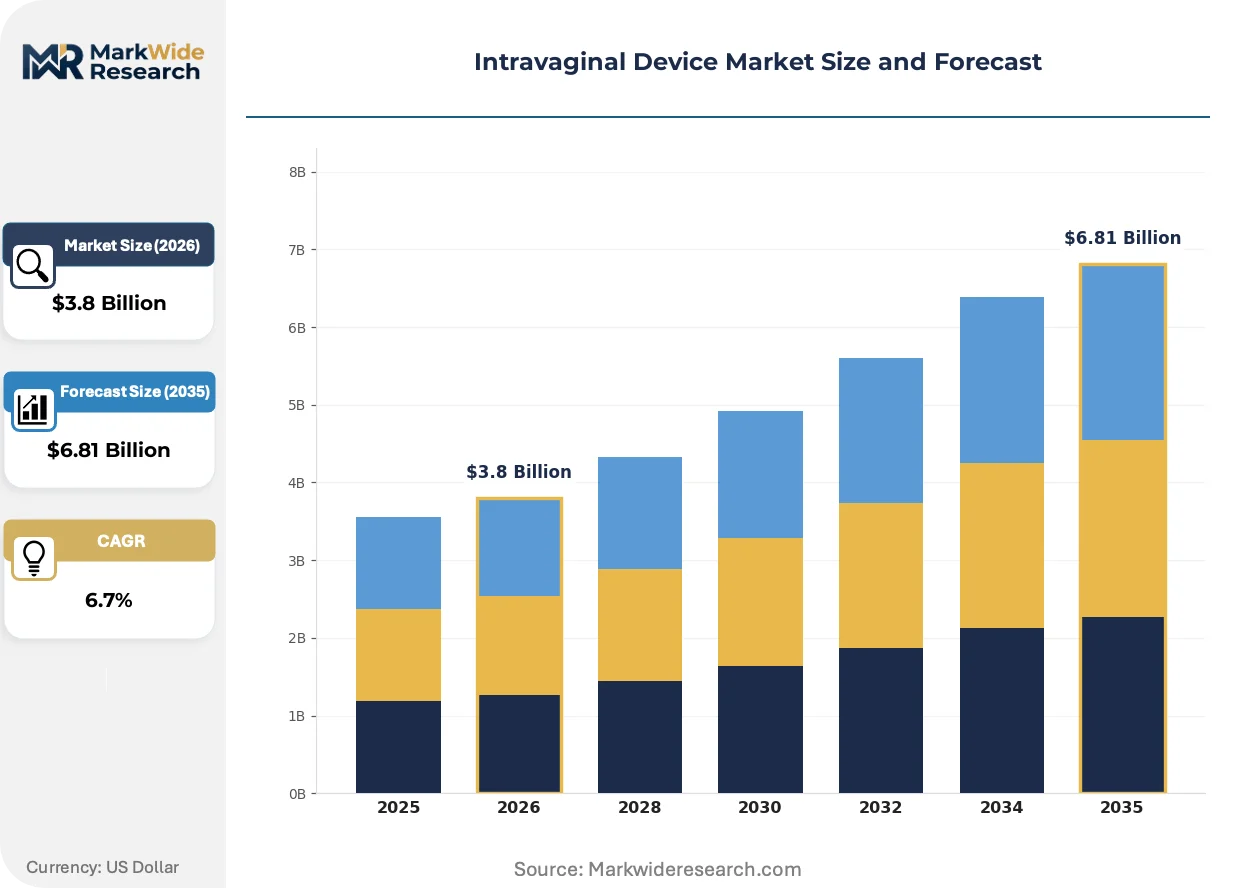
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contraceptive Devices, Therapeutic Devices, Diagnostic Devices, Delivery Devices Application: Birth Control, Hormonal Treatment, Infection Prevention, Disease Management Usage Type: Reusable Devices, Disposable Devices, Customizable Devices, Standard Devices End User: Hospitals, Gynecological Clinics, Outpatient Centers, Research Institutions |
| Companies Covered | CooperSurgical Inc., Bayer AG, Merck & Co Inc., AbbVie Inc., MedGyn Products Inc., Bioteque America Inc., Gyneas, Panpac Medical Corp., Hologic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intravaginal Device Market Trends and Innovations
Silicone-hydrogel composite matrices are redefining material performance thresholds across contraceptive and therapeutic device categories, compressing the gap between mechanical durability and biocompatibility that legacy latex formulations could not bridge.
Drug-eluting silicone elastomer is unifying hormone delivery and physical barrier functions within single-ring architectures. Gynecological clinics in France and Germany are standardizing procurement around these combination formats. The convergence is compressing separate device categories into unified therapeutic-contraceptive platforms that command reimbursement parity under women's health procedure codes.
EU MDR clinical evaluation report requirements are forcing retrospective data generation for legacy vaginal devices that predated stricter evidence standards. Manufacturers with pre-2021 product portfolios face portfolio triage decisions. The diagnostic segment is responding fastest, with specimen collection platforms accelerating prospective study investment to defend premium positioning in PCR-integrated workflows.
Direct-to-clinic contracting is displacing traditional distributor intermediaries for high-volume pessary and diaphragm procurement. Hospital purchasing consortia in Western Europe are consolidating vendor panels around manufacturers with vertically integrated polymer compounding. The shift concentrates procurement leverage in Germany and France while marginalizing smaller distributors without manufacturing partnerships.
Intravaginal Device Market Segmentation
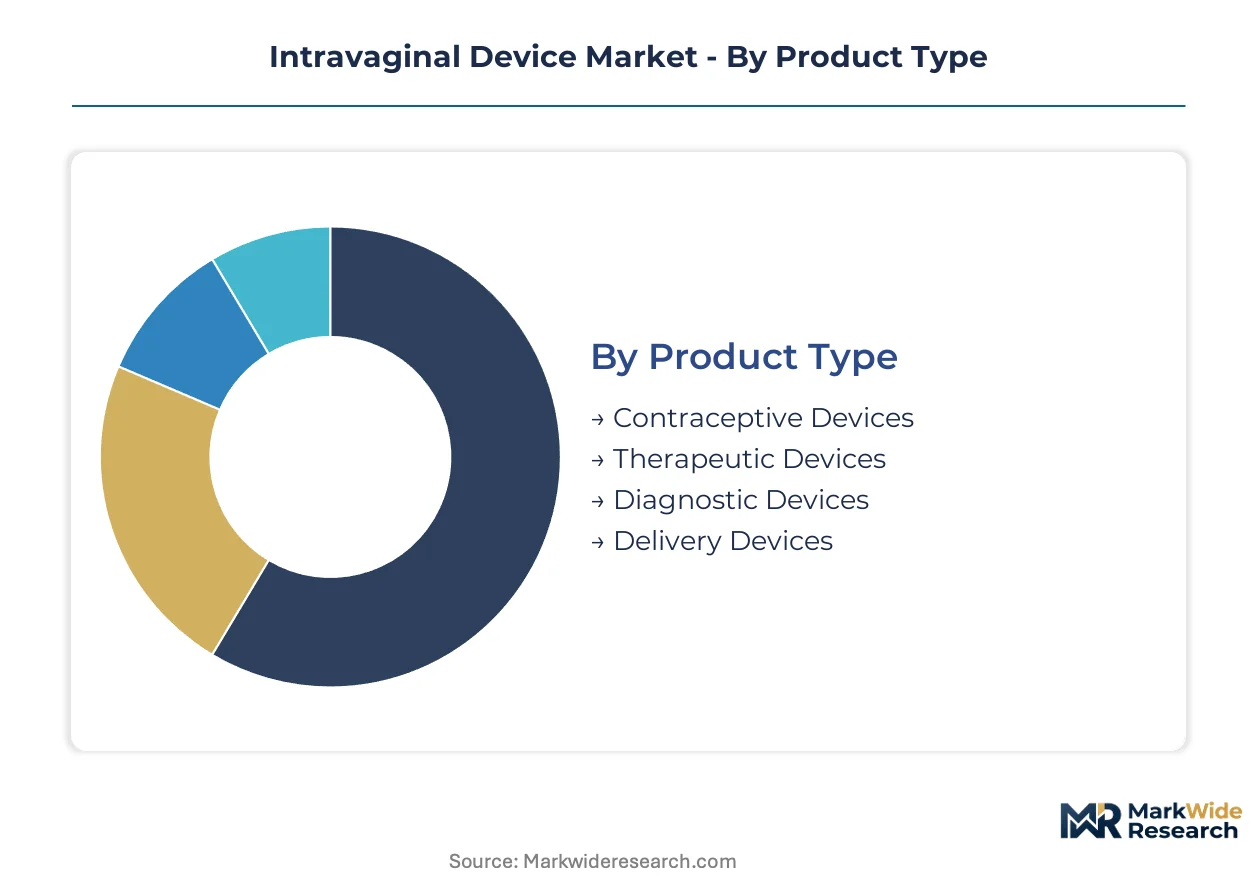
Material compliance costs and reimbursement pathway complexity create divergent margin profiles across intravaginal device categories. Procurement concentration in German and French gynecological networks favors manufacturers with vertically integrated polymer compounding and MDR-ready technical documentation.
Product Type:
Clinicians prioritize biocompatibility certification and reuse validation when selecting between contraceptive, therapeutic, and diagnostic formats.
- Contraceptive Devices:Silicone elastomer rings and diaphragms dominate procurement volumes in Western European public health systems. German clinic networks in Munich and Berlin sustain demand for reusable formats that minimize allergen liability under EU MDR biocompatibility mandates.
- Therapeutic Devices:Pessary systems for pelvic organ prolapse management utilize medical-grade silicone with Shore A durometer specifications calibrated for ambulatory retention. French ANSM early engagement pathways accelerate conformity assessment for manufacturers with Kiel-based polymer compounding capabilities.
- Diagnostic Devices:Specimen collection platforms integrate nucleic acid stabilization chemistry for PCR workflows in gynecological clinics.
- Delivery Devices:Hormone-eluting rings with sustained-release matrices bypass hepatic first-pass metabolism for localized therapeutic effect.
Contraceptive devices lead on scale; delivery devices lead on momentum.
Application:
Reimbursement parity under women's health procedure codes determines commercial viability across clinical use cases.
- Birth Control:Physical barrier and hormone-eluting formats command established procurement codes across European public health systems. Outpatient volume expansion in Berlin and Paris clinic networks sustains device utilization despite MDR-extended approval timelines.
- Hormonal Treatment:Menopausal symptom management and endometriosis therapy drive silicone-hydrogel composite development for sustained-release pharmacokinetics.
- Infection Prevention:pH-modulating and microbiome-supportive devices occupy emerging regulatory territory with evolving clinical evidence requirements.
- Disease Management:Drug-device combinations for localized oncology or infectious disease applications face stricter EU MDR Class IIb scrutiny.
Birth control applications anchor revenue concentration; hormonal treatment applications expand most quickly.
Usage Type:
Sterilization validation burdens and liability exposure differentiate total cost of ownership between reusable and disposable formats.
- Reusable Devices:Contraceptive rings and pessaries with extended lifecycles demand rigorous post-market surveillance systems under EU MDR vigilance requirements. German procurement consortia favor these formats for cost efficiency in high-volume outpatient settings.
- Disposable Devices:Single-use diagnostic collection platforms eliminate sterilization overhead while commanding premium pricing in PCR-integrated workflows.
- Customizable Devices:Patient-specific sizing and drug-loading configurations require flexible manufacturing infrastructure.
- Standard Devices:Off-the-shelf formats prioritize manufacturing scale and distributor inventory efficiency.
Reusable devices dominate procurement volume; disposable devices capture the steepest margin expansion.
End User:
Procurement authority consolidation and technical specification complexity shape vendor selection across care settings.
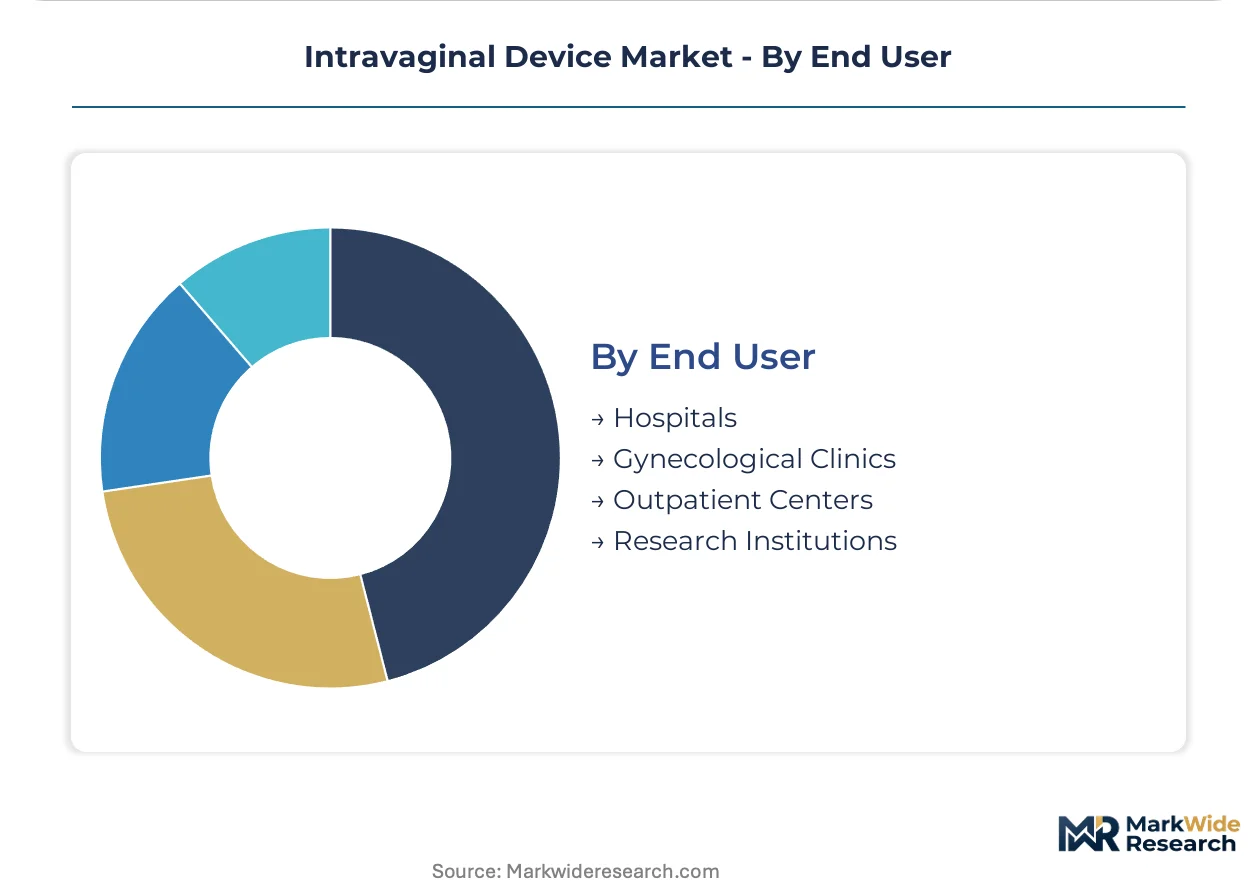
- Hospitals:Integrated health systems in France and Germany centralize purchasing around manufacturers with captive silicone compounding and MDR-ready quality management systems.
- Gynecological Clinics:Munich and Berlin outpatient networks drive pessary and diagnostic device demand through direct-to-clinic contracting that marginalizes traditional distributors.
- Outpatient Centers:Ambulatory procedural volume growth sustains contraceptive device utilization with reimbursement parity under women's health codes.
- Research Institutions:Clinical trial endpoints for drug-device combination products generate prospective data investment for EU MDR clinical evaluation reports.
Gynecological clinics concentrate procurement leverage; research institutions drive evidence generation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kiel's polymer compounding corridor anchors European supply for medical-grade silicone elastomers, with vertically integrated manufacturers controlling raw material flows for intravaginal device production across multiple continents.
United States
FDA 510(k) clearance pathways sustain market entry for contraceptive rings and diagnostic collection platforms. Connecticut's manufacturing belt hosts captive silicone compounding operations that feed pessary and diaphragm production lines. Trumbull-based facilities leverage backward integration to manage material quality and shorten procurement cycles for domestic clinic networks.
Germany
Berlin and Munich outpatient centers drive procurement volume for reusable contraceptive devices under statutory health insurance reimbursement parity. EU MDR notified body assessments for Class IIb vaginal products extend approval timelines, favoring manufacturers with pre-existing technical documentation. Kiel's polymer science cluster concentrates implantable-grade elastomer formulation capabilities for regional device portfolios.
France
ANSM pre-submission consultations accelerate conformity assessment routing for women's health device manufacturers seeking faster EU MDR market access. Paris clinic procurement consortia consolidate vendor panels around suppliers with MDR-ready quality management systems. Lyon-based research institutions generate clinical evaluation report data for silicone-hydrogel composite formulations.
India
CDSCO import licensing and BIS certification requirements shape contract manufacturing partnerships for Western device portfolios targeting Asia-Pacific expansion. Maharashtra's medical device manufacturing zones attract toll compounding arrangements for silicone elastomer processing. Mumbai regulatory consultants navigate harmonization between domestic standards and EU MDR technical documentation requirements.
United Kingdom
MHRA post-Brexit regulatory divergence creates parallel conformity assessment pathways for vaginal devices previously covered by EU MDR mutual recognition. London gynecological clinic networks maintain procurement relationships with Continental manufacturers despite customs friction. Cambridge diagnostic technology clusters develop nucleic acid stabilization chemistry for specimen collection platforms.
Intravaginal Device Market Competitive Landscape
Global majors compete with regional champions across material science capabilities and regulatory compliance infrastructure. Market structure tilts toward consolidation among manufacturers with captive polymer compounding and vertically integrated molding operations. Three archetypes dominate: multinational pharmaceutical-device hybrids with hormone delivery expertise, specialized women's health device pure-plays with clinic direct-contracting capabilities, and diagnostic platform developers integrating specimen stability chemistry. Competitive moves concentrate on M&A to secure silicone supply security and strategic partnerships with gynecological clinic purchasing consortia.
Within the pharmaceutical-device hybrid tier, Bayer AG and Merck & Co Inc. occupy positions anchored by hormone-eluting ring development and European manufacturing scale. Among specialized device manufacturers, CooperSurgical Inc. exemplifies the vertically integrated archetype with domestic silicone compounding control, while Hologic represents the diagnostic platform specialization vector with molecular collection device integration. These three companies illustrate how competitive positioning separates material science control, pharmaceutical partnership depth, and diagnostic workflow integration as distinct strategic paths.
| Leading Market Players |
|---|
| CooperSurgical Inc. |
| Bayer AG |
| Merck & Co Inc. |
| AbbVie Inc. |
| MedGyn Products Inc. |
| Bioteque America Inc. |
| Gyneas |
| Panpac Medical Corp. |
| Hologic |
| Others |
Pricing and Supply Chain Analysis
Silicone-hydrogel composite formulation transitions are compressing unit economics for intravaginal device manufacturers while concentrating polymer compounding capabilities in Kiel and Connecticut corridors. This dual effect amplifies pricing power for backward-integrated producers and squeezes mid-tier competitors facing simultaneous MDR compliance capex and material upgrade costs.
Pricing Analysis
Medical-grade silicone elastomer cost pass-through dominates pricing structures for Class IIb vaginal devices, with EU MDR biocompatibility certification tiers separating premium silicone-hydrogel composites from standard elastomer formulations. Price differentiation hinges on implantable-grade material sourcing and notified body assessment depth. Pricing pressure stems from legacy latex conversion capex burdens that compound MDR compliance spending. German gynecological clinic consortia exhibit highest price sensitivity due to statutory health insurance reimbursement constraints, while PCR-integrated diagnostic platforms command lowest sensitivity through workflow premium capture.
Supply Chain Analysis
EU MDR notified body qualification gating concentrates implantable-grade silicone supply in Germany, the United States, and Switzerland, with polymer compounding capabilities clustering around Kiel and Trumbull manufacturing belts. Raw material dependencies center on medical-grade silicone elastomers, hydrogel monomers, and nucleic acid stabilization chemistries for diagnostic formats. Single-source vulnerability runs through Connecticut-based captive compounding operations that feed multiple device categories. Distribution runs through direct-to-clinic contracting channels that displace traditional distributor intermediaries in Western European procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in intravaginal devices rest on silicone material cost compression and diagnostic platform premium-tier shifts toward PCR-integrated workflows. Manufacturers capturing both dynamics through backward-integrated compounding and molecular collection chemistry integration will outpace competitors burdened by legacy latex conversion timelines.
For Market Incumbents: Acquire polymer compounding assets in the Kiel corridor to secure implantable-grade silicone supply security against emerging entrant toll-manufacturing challenges. Anchor defensive positioning through ANSM early engagement pathway pre-submissions that accelerate EU MDR conformity assessment timelines relative to standard notified body queues. Deepen clinic direct-contracting relationships in Berlin and Munich procurement networks to marginalize distributor-dependent competitors. For New Entrants and Emerging Players: CDSCO import licensing harmonization in India opens a window for Asia-Pacific volume expansion through contract manufacturing partnerships with Maharashtra-based toll compounders. Target diagnostic specimen collection platforms as the most penetrable segment, where nucleic acid stabilization chemistry integration commands premium positioning absent from saturated contraceptive device categories. Pursue GPO contracts manager relationships in German hospital purchasing consortia as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for specialized women's health device pure-plays because MDR compliance infrastructure costs disproportionately burden sub-scale manufacturers without captive polymer capabilities. Five-to-ten year viability hinges on consolidation of silicone supply security and clinic direct-contracting networks. Watch FDA draft guidance on women's health trial design as the signal for regulatory access timeline compression that would revalue MDR-ready technical documentation portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | ANSM pre-submission consultations compress EU MDR timelines for silicone-hydrogel composite devices. |
| Backward Integration into Polymer Compounding | Kiel and Connecticut captive facilities control medical-grade elastomer quality for implantable devices. |
| Hospital System Partnership | German clinic consortia consolidate vendor panels around MDR-ready manufacturers with direct contracting. |
| Software Companion Development | Post-market surveillance systems integrate EU MDR vigilance reporting for reusable device lifecycle tracking. |
| Reimbursement Strategy | Women's health procedure codes in France and Germany sustain procurement parity for therapeutic-contraceptive platforms. |
Research Methodology
Coverage spans Germany, France, the United States, India, and the United Kingdom, with primary inputs from each market informing demand calibration and regulatory pathway assessment. The analysis combines interviews with gynecological clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, EU MDR notified body assessment databases, CDSCO import licensing records, and hospital procurement contract disclosures. Bottom-up device shipment estimates and top-down healthcare expenditure triangulation anchor market sizing.
Rate-of-change decomposition separates volume expansion from value-per-unit shifts across the projection horizon. The analytical framework models segmentation dimensions including material type, device category, application indication, usage format, and end-user setting. CAGRs derive from fitted growth curves applied to procedural volume trajectories and reimbursement code utilization patterns. Forecast inputs incorporate EU MDR approval timeline extensions, German outpatient clinic expansion rates, and India CDSCO pathway harmonization progress.
Revisions become necessary when EU MDR notified body capacity constraints deepen beyond current assessment periods or when FDA draft guidance on women's health trial design finalizes with substantively modified evidence requirements. Forecasts reflect documented assumptions regarding silicone raw material supply stability and statutory health insurance reimbursement parity maintenance. A model refresh is warranted upon material change in polymer compounding geographic concentration or diagnostic platform PCR workflow standardization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Automatic Clotting Timer Systems Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Devices Market
Medical Devices
Global Smart Implantable Pumps Market
Medical Devices
Asia-Pacific Respiratory Devices Market
Medical Devices
Global Implantable Loop Recorder Market
Medical Devices
Middle East and Africa C-Arms Market
Medical Devices
Robot Assisted PCI Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
Annuloplasty Rings Market
Medical Devices
Foot and Ankle Allograft Market
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market
Medical Devices
Implantable Pulse Generator Market
Medical Devices
3D Printed Medical Devices Market
Medical Devices
Large Volume Nebulizers Market
Medical Devices
Europe Biopsy Devices Market
Medical Devices
Occlusion Microcatheter Market