
 Global Automatic Pill Dispenser Market | 2026-2036
Global Automatic Pill Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automatic Pill Dispenser Market Foresight
Multi-source component procurement is decoupling from legacy single-vendor dependencies as manufacturers diversify sensor and connectivity suppliers. Philips Healthcare leverages in-house electronics production to control quality across its smart dispenser lines. Baxter International sustains competitive positioning through specialized hospital-grade dispensing systems. Omnicell Inc. dominates automated medication management with extensive pharmacy channel control.
Automatic pill dispensers are electromechanical or connected devices programmed to release medications at preset intervals, incorporating sensors, locking mechanisms, and alert systems to ensure dosing accuracy and patient adherence. These systems serve primarily to reduce medication errors, improve therapeutic outcomes, and enable remote monitoring of patient compliance in both institutional and residential settings. Smart dispensers with Wi-Fi and Bluetooth connectivity represent the fastest-expanding technology segment as telemedicine integration accelerates. Multi dose dispensers command stronger margin pools due to higher complexity and chronic disease patient reliance, while single dose units occupy the entry-level tier in cost-sensitive channels.
FDA 510(k) clearance requirements and EMA Medical Device Regulation (MDR) compliance shape product development timelines and market access barriers for connected dispensing devices. The EU AI Act and FDA cybersecurity guidance are forcing manufacturers to embed data protection and algorithmic transparency into next-generation units. Stakeholders must monitor evolving reimbursement policies for remote patient monitoring devices across Medicare, NHS England, and Japan's MHLW to anticipate demand inflection points.
Market Dynamics
The automatic pill dispenser market is experiencing structural compression from telemedicine integration mandates and aging-in-place healthcare policies across OECD economies. Device manufacturers must now engineer for dual-use compliance across hospital discharge protocols and residential remote monitoring reimbursement codes simultaneously.
Growth Catalysts
- Japan's MHLW reimbursement expansion:Remote patient monitoring devices now qualify for long-term care insurance subsidies, accelerating home-based dispenser deployment among elderly populations managing polypharmacy regimens.
- Wi-Fi and Bluetooth sensor convergence:Low-power connectivity modules enable real-time adherence tracking that integrates directly with electronic health record systems, reducing nursing intervention costs.
- Chronic disease prevalence in Germany:Cardiovascular and diabetes patient volumes exceeding institutional capacity are forcing payers to subsidize automated dispensing for outpatient medication adherence programs.
Market Restraints
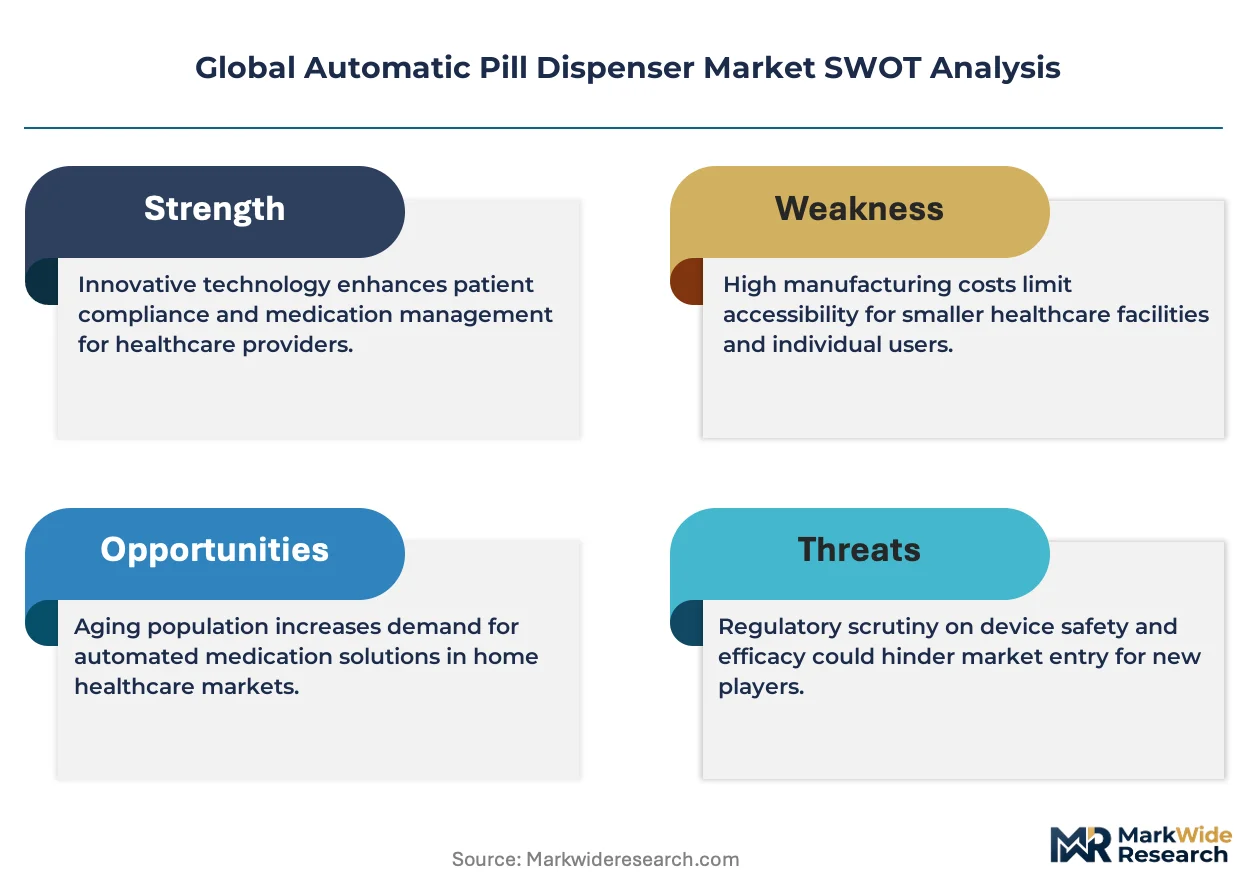
- Semiconductor supply concentration:Microcontroller and MEMS sensor fabrication clusters in Taiwan and South Korea create procurement vulnerability for dispenser manufacturers scaling connected device lines.
- FDA cybersecurity guidance compliance costs:Pre-market documentation requirements for software-as-medical-device classification extend development timelines and compress margins on mid-tier product lines.
- Manual pill organizers:Low-cost plastic compartment systems retain preference among price-sensitive caregivers and short-term therapy patients, capping premium dispenser penetration in emerging markets.
Strategic Opportunities
- India's PLI scheme for medical electronics:Production-linked incentives for domestic manufacturing of diagnostic and monitoring devices reduce landed costs for regional dispenser assembly.
- Behavioral health integration:Psychiatric medication adherence monitoring represents an underserved application where locking mechanisms and tamper-evident dosing align with controlled substance protocols.
- EU AI Act algorithmic transparency requirements:Early compliance with explainable dosing recommendation engines creates differentiation for manufacturers targeting NHS England and German statutory health insurance tenders.
Industry Challenges
- Embedded systems engineering talent scarcity:Firmware development for real-time clock accuracy and motor control precision requires specialized skills concentrated in medical device hubs.
- EMA MDR technical documentation burden:Clinical evidence requirements for connected dispensers classified as Class IIa devices demand substantial post-market surveillance infrastructure investment.
- Legacy pharmacy management system interoperability:Proprietary communication protocols in institutional medication dispensing cabinets create integration friction for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automatic Pill Dispenser Market |
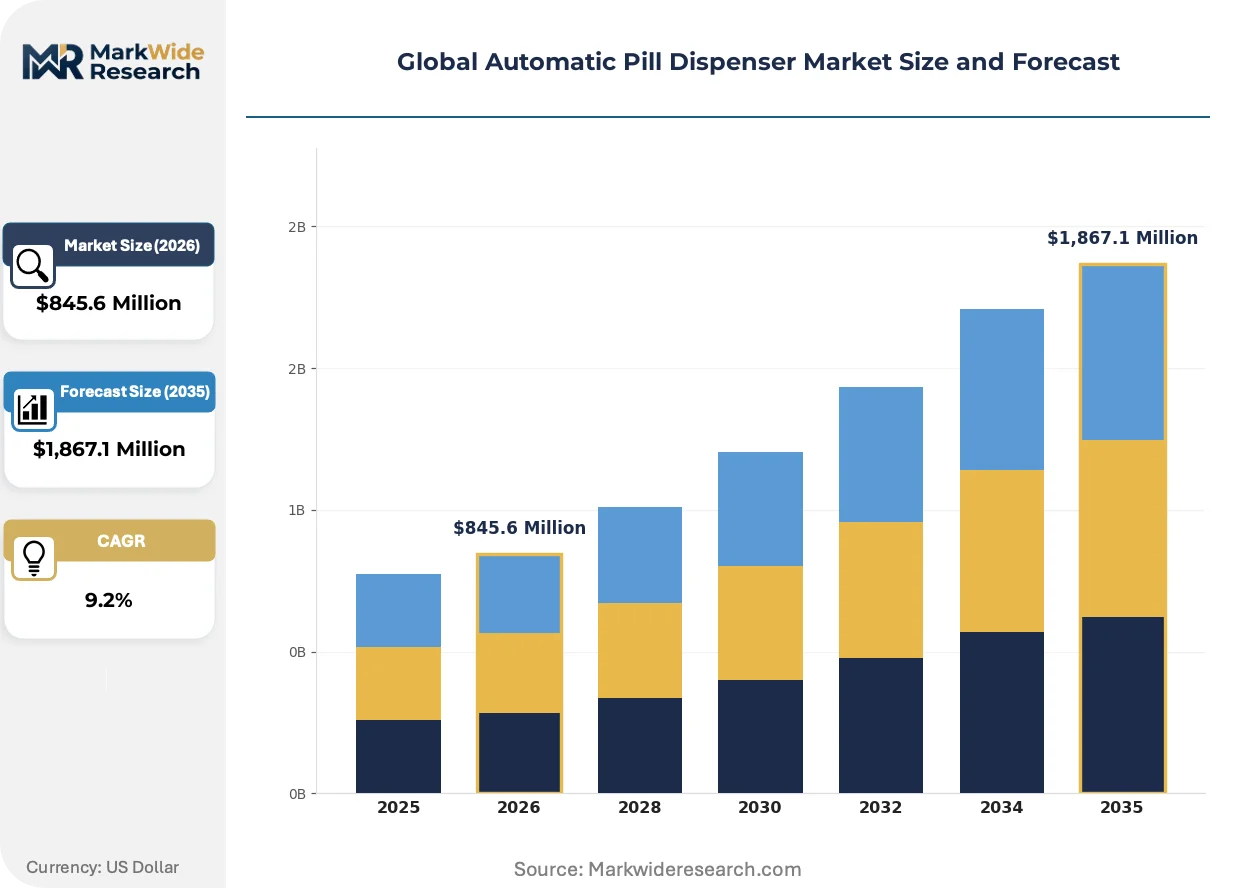
| Market Size in 2026 | $845.6 Million |
| Market Size in 2035 | $1,867.1 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Dose Dispenser, Multi Dose Dispenser, Smart Dispenser, Portable Dispenser, Timed Dispenser Technology: Bluetooth Enabled, Wi-Fi Enabled, RFID Based, Infrared Sensor, Mechanical, Voice Activated Application: Home Care, Assisted Living Facilities, Long-Term Care Centers, Telemedicine, Medication Management Services End User: Geriatric Patients, Chronic Disease Patients, Pharmacy Providers, Healthcare Institutions, Caregivers |
| Companies Covered | Omnicell Inc., Becton, Dickinson and Company, Philips Healthcare, McKesson Corporation, Capsa Healthcare, Hero Health Inc., Baxter International Inc., Cerner Corporation, Swisslog Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automatic Pill Dispenser Market Shifts & Advancements
Connectivity architectures and regulatory data governance are restructuring how medication adherence systems are designed, procured, and reimbursed across care settings.
Computer vision-based pill recognition is absorbing quality assurance functions previously requiring manual pharmacist verification. Hospital discharge planners in the United States are specifying camera-equipped dispensers for high-risk polypharmacy patients. This technology compression is reducing callback rates and enabling remote visual confirmation of correct medication selection without human intermediation.
EMA Medical Device Regulation cybersecurity annexes are mandating secure-by-design architectures for connected dispensers handling patient-identifiable data. Manufacturers must now embed hardware security modules and encrypted boot processes from initial prototyping stages. German notified bodies are enforcing these requirements most stringently, causing product registration delays for devices lacking pre-certified components.
Subscription-based device provisioning is replacing outright purchase models in US Medicare Advantage plans. Payers bundle dispenser hardware with remote monitoring services and medication adherence coaching, shifting revenue recognition from equipment margin to recurring per-member-per-month fees. This restructuring concentrates purchasing authority with integrated delivery networks rather than individual patients or retail pharmacies.
Global Automatic Pill Dispenser Market Segmentation
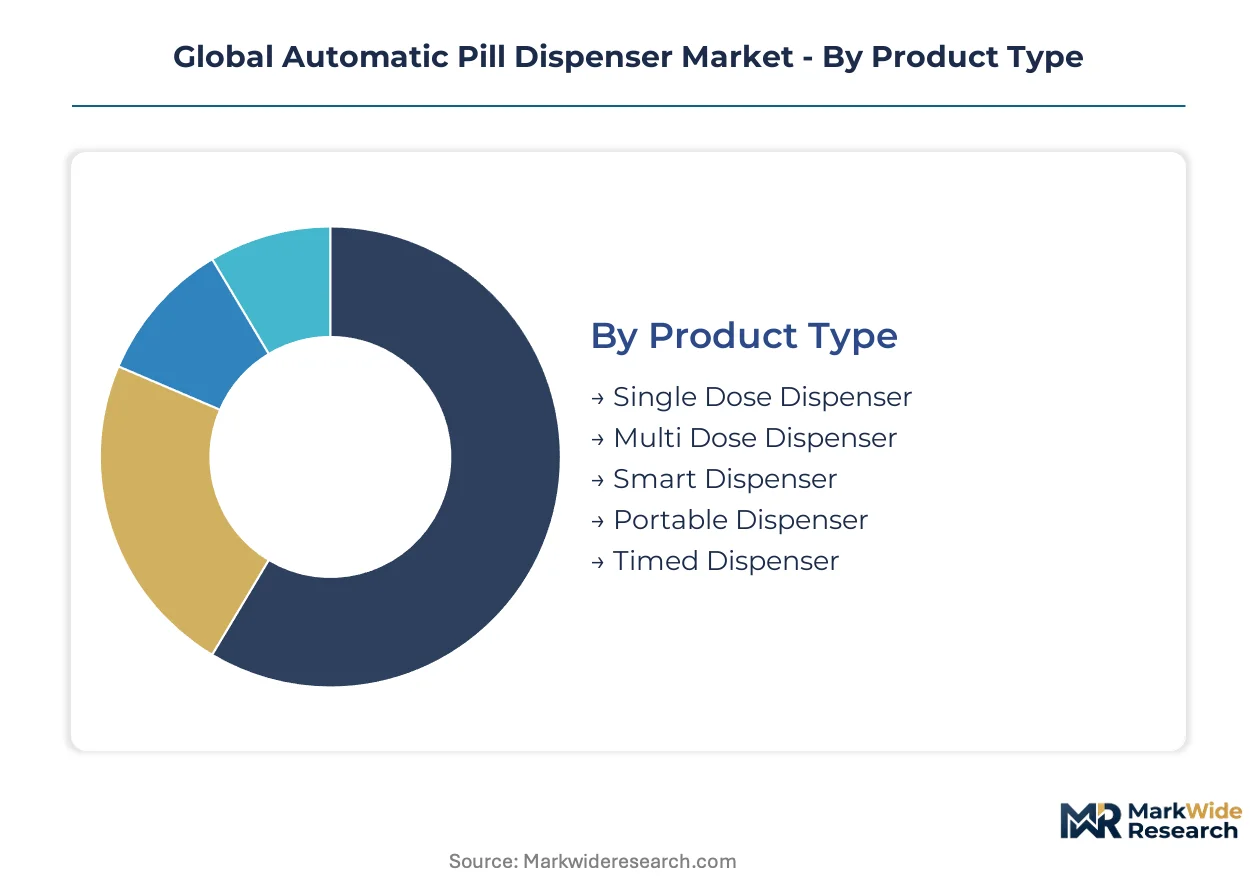
Automatic pill dispenser segmentation reveals divergent buyer priorities across clinical sophistication, connectivity requirements, and reimbursement pathways. Product architecture and technology choices determine whether devices qualify for remote patient monitoring subsidies or remain consumer-paid retail purchases.
Product Type:
Buyers in this category stratify sharply by therapy complexity and reimbursement eligibility, with institutional procurement favoring multi-dose systems while retail channels push single-dose units.
- Multi Dose Dispenser:Electromechanical systems manage 28-30 day medication regimens through rotating carousel mechanisms and programmable alarm protocols. Germany's statutory health insurance funds now subsidize these units for cardiovascular patients discharged to home care, creating volume concentration in chronic disease management programs.
- Smart Dispenser:Connected devices integrate Wi-Fi, Bluetooth, and cloud dashboards for real-time adherence monitoring and caregiver alerts. Japan's MHLW reimbursement expansion for remote patient monitoring devices accelerates deployment among elderly populations managing polypharmacy, with telemedicine integration becoming a mandatory specification.
- Single Dose Dispenser:Basic compartment-based systems serve short-term antibiotic courses and post-surgical pain management where cost sensitivity dominates.
- Portable Dispenser:Pocket-sized units with vibration alerts target working-age chronic disease patients requiring medication access during travel and employment.
- Timed Dispenser:Clockwork or battery-driven mechanisms without connectivity serve price-conscious caregivers in emerging markets where smartphone penetration lags.
Multi dose dispensers lead volumes today; smart dispensers are gaining share fastest.
Technology:
Technology selection locks manufacturers into specific regulatory pathways and supply chain dependencies, with wireless modules requiring FDA cybersecurity documentation and MEMS sensors concentrating in East Asian fabrication clusters.
- Wi-Fi Enabled:High-bandwidth connectivity enables continuous cloud synchronization, video verification, and EHR integration for hospital-at-home programs. United States Medicare Advantage plans increasingly mandate Wi-Fi capability for remote patient monitoring reimbursement, concentrating demand in integrated delivery network procurement.
- Bluetooth Enabled:Low-energy protocols pair with smartphone applications for medication logging and family caregiver notifications. Battery efficiency makes these modules dominant in portable dispenser designs where power constraints override bandwidth requirements.
- RFID Based:Radio-frequency identification authenticates medication blister packs and tracks inventory depletion through pharmacy management systems.
- Infrared Sensor:Beam-interruption detection confirms pill retrieval without mechanical contact, reducing wear in high-frequency dispensing cycles.
- Mechanical:Spring-loaded and gravity-fed mechanisms without electronics avoid software-as-medical-device classification and associated FDA pre-market timelines.
- Voice Activated:Speaker-dependent recognition enables hands-free operation for visually impaired users and arthritis patients with limited manual dexterity.
Bluetooth modules dominate unit shipments currently; Wi-Fi configurations show the steepest expansion trajectory.
Application:
Application segmentation tracks the migration of medication management from institutional settings toward reimbursed home-based care, with each setting imposing distinct device specifications and liability frameworks.
- Home Care:Residential deployment of connected dispensers enables aging-in-place policies while reducing nursing home admission costs. Japan and Germany lead policy-driven procurement here, with long-term care insurance subsidies covering device rental and monitoring service fees.
- Telemedicine:Virtual care platforms require dispensers with video verification and real-time adherence dashboards to satisfy clinical oversight requirements without physical patient contact.
- Assisted Living Facilities:Semi-independent residents use dispenser systems that balance autonomy with staff notification protocols for missed doses.
- Long-Term Care Centers:Institutional medication carts and centralized dispensing cabinets integrate with electronic MAR systems for regulatory compliance.
- Medication Management Services:Third-party adherence coaching programs bundle dispenser hardware with pharmacist outreach and insurance reporting.
Home care applications anchor current volumes; telemedicine integration is climbing the fastest.
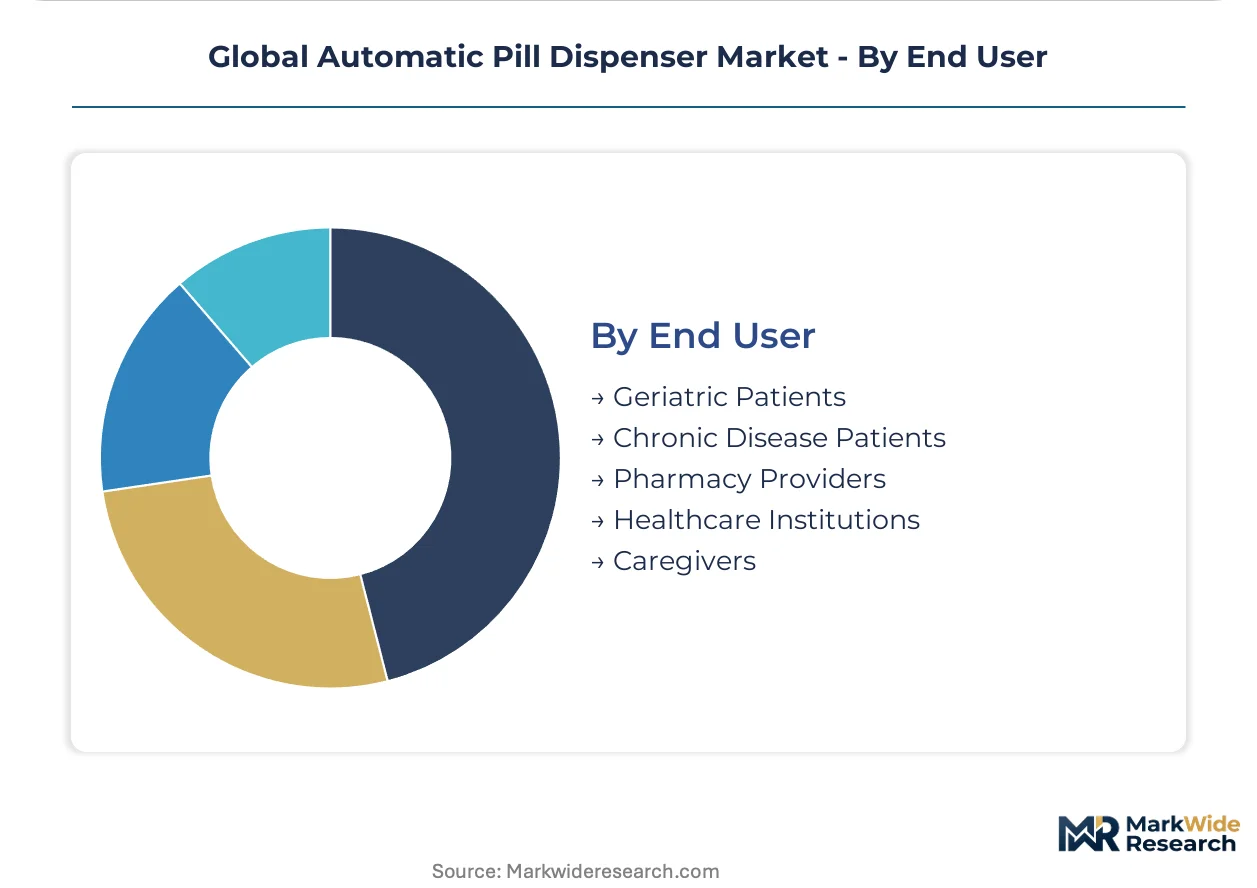
End User:
End user categories reflect divergent purchasing authority, with patients and caregivers making retail decisions while pharmacy providers and healthcare institutions control reimbursed procurement channels.
- Geriatric Patients:Adults over 65 managing multiple chronic conditions drive demand for high-capacity dispensers with simplified interfaces and loud auditory alerts. Japan's demographic profile concentrates global volume for this segment.
- Chronic Disease Patients:Diabetes, hypertension, and heart failure populations require adherence monitoring to prevent acute events and hospitalization, with United States payers increasingly tying reimbursement to documented compliance metrics.
- Pharmacy Providers:Retail and specialty pharmacies deploy dispenser programs to differentiate from mail-order competition and capture medication therapy management revenue.
- Healthcare Institutions:Hospital discharge planners specify dispensers for high-risk polypharmacy patients to reduce readmission penalties.
- Caregivers:Family members purchase entry-level units to manage medication oversight for relatives with early-stage cognitive impairment.
Geriatric patients represent the largest addressable population; chronic disease patients show the most rapid eligibility expansion through reimbursement policy changes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Minneapolis-Saint Paul medical device cluster anchors North American dispenser engineering, with FDA 510(k) clearance pathways and Medicare reimbursement codes shaping product specifications for hospital-at-home deployment.
United States
Medicare Advantage plans bundle dispenser hardware with remote monitoring services, concentrating purchasing authority with integrated delivery networks. FDA cybersecurity guidance for software-as-medical-device classification extends pre-market timelines. The Minneapolis-Saint Paul corridor hosts embedded systems engineering talent for real-time clock and motor control firmware.
Germany
Statutory health insurance funds subsidize multi-dose dispensers for cardiovascular patients discharged to home care, creating volume concentration in chronic disease management. EMA Medical Device Regulation Class IIa technical documentation requirements demand substantial post-market surveillance infrastructure. Stuttgart and Munich host precision manufacturing clusters for electromechanical carousel mechanisms.
Japan
MHLW reimbursement expansion for remote patient monitoring devices accelerates deployment among elderly populations managing polypharmacy regimens. METI production-linked incentives support domestic medical electronics assembly. The Kanto region around Tokyo concentrates telemedicine platform integration and cloud dashboard development.
India
Production-linked incentive schemes for medical electronics reduce landed costs for regional dispenser assembly targeting price-sensitive retail channels. CDSCO medical device rules classify connected dispensers under import licensing requirements. Bangalore and Hyderabad clusters supply firmware engineering for low-power Bluetooth module integration.
United Kingdom
NHS England tenders for medication adherence monitoring specify algorithmic transparency requirements under EU AI Act alignment. MHRA post-Brexit device registration creates parallel compliance pathways. The Cambridge-London corridor concentrates computer vision engineering for pill recognition quality assurance.
Global Automatic Pill Dispenser Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue behavioral health integration and subscription service models. The market structure concentrates around three strategic archetypes: integrated healthcare technology conglomerates with in-house electronics production, specialized hospital-grade dispensing system manufacturers, and automated medication management platform operators with pharmacy channel control. Dominant competitive moves include backward integration into sensor and connectivity component supply, plus strategic partnerships with telemedicine platforms for EHR integration.
Within the integrated technology tier, Philips Healthcare exemplifies captive electronics production for quality control across smart dispenser lines. Baxter International occupies a position among specialized hospital-grade system fabricators. Omnicell Inc. anchors the automated medication management archetype with extensive pharmacy channel presence.
| Leading Market Players |
|---|
| Omnicell Inc. |
| Becton, Dickinson and Company |
| Philips Healthcare |
| McKesson Corporation |
| Capsa Healthcare |
| Hero Health Inc. |
| Baxter International Inc. |
| Cerner Corporation |
| Swisslog Healthcare |
| Others |
Supply & Pricing Matrix
EMA Medical Device Regulation cybersecurity annexes gate qualified component supply and premium-tier pricing access, as manufacturers embedding hardware security modules from prototyping stages command reimbursement-eligible positioning in German statutory health insurance tenders while uncertified competitors face margin compression in retail channels.
Pricing Analysis
Input-cost pass-through from MEMS sensor and microcontroller procurement in Taiwan and South Korea intensifies pricing pressure on mid-tier connected dispenser lines. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared Wi-Fi units with EHR integration from Bluetooth-enabled standard tiers and mechanical economy units. Price differentiation hinges on cybersecurity certification grade and telemedicine platform interoperability. Cost compression in standard tiers reflects semiconductor supply concentration, while premium pricing holds firm among integrated delivery networks with Medicare Advantage remote monitoring mandates. Retail caregivers and short-term therapy patients exhibit highest price sensitivity; hospital discharge planners show lowest sensitivity due to readmission penalty avoidance.
Supply Chain Analysis
Dual-sourcing requirements from Omnicell and Philips Healthcare mandate multi-supplier qualification for low-power Bluetooth and Wi-Fi connectivity modules, reducing single-fabrication vulnerability. Component supply concentrates in Taiwan, South Korea, and China for microcontroller and sensor fabrication. Raw material dependencies span medical-grade plastics, lithium-ion cells for portable units, and precision stepper motors for carousel mechanisms. Single-source vulnerability in East Asian semiconductor fabrication clusters threatens scaling timelines for connected device lines. Distribution runs through pharmacy benefit managers and integrated delivery networks in reimbursed channels, with retail e-commerce serving price-sensitive consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automatic pill dispenser demand compounds through regulatory milestones, with Japan's MHLW reimbursement expansion for remote patient monitoring devices creating policy-driven procurement inflections that reward early compliance investment.
For Market Incumbents: Deepen backward integration into sensor and connectivity component supply to secure qualification for German EMA MDR Class IIa technical documentation pathways. Lock in multi-year pharmacy channel control agreements before emerging entrants achieve EHR interoperability certification. Defend against subscription-based service providers by captive production of cloud dashboard infrastructure. For New Entrants and Emerging Players: Psychiatric medication adherence monitoring represents an underserved buyer archetype where locking mechanisms and tamper-evident dosing align with controlled substance protocols and existing regulatory gaps. Behavioral health integration offers the most penetrable application segment given incumbent focus on geriatric polypharmacy. Pursue partnership-based go-to-market angles with telemedicine platforms seeking differentiated medication management capabilities. For Investors and Strategic Acquirers: Roll-up economics work for automated medication management platform operators because pharmacy channel control and EHR integration capabilities concentrate value capture in a fragmented vendor landscape. Five-to-ten year viability favors acquirers of firms with FDA 510(k) clearance and active NHS England tender participation. Watch for MHLW reimbursement code expansions beyond long-term care insurance as the signal indicating accelerated home-based deployment.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Cybersecurity Submission | Pre-market documentation for software-as-medical-device classification satisfies Medicare Advantage remote monitoring mandates. |
| CE Marking Pathway under EMA MDR | Class IIa technical documentation enables German statutory health insurance subsidy eligibility for cardiovascular patients. |
| Hospital System Partnership | Discharge planner specifications for high-risk polypharmacy patients reduce readmission penalties in US integrated delivery networks. |
| Software Companion Development | Telemedicine platform integration with real-time adherence dashboards satisfies Japan MHLW virtual care oversight requirements. |
| Reimbursement Strategy | Per-member-per-month service bundling shifts revenue from equipment margin to recurring fees in Medicare Advantage plans. |
Research Methodology
Bottom-up home care and telemedicine deployment modeling reconciled against top-down sensor and connectivity module production tracking forms the analytical core. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and pharmacy benefit directors combined with secondary validation against FDA 510(k) filings, EMA MDR technical documentation databases, CMS Medicare remote monitoring reimbursement codes, and Japan MHLW long-term care insurance subsidy records. Triangulation across stakeholder inputs and regulatory filings ensures segment-level precision.
Historical trendline analysis of Wi-Fi and Bluetooth module shipments into medical device applications anchors the projection framework. Segmentation dimensions span product type, connectivity technology, application setting, and end-user category across the analysis window. CAGR derivation incorporates chronic disease prevalence trajectories, aging-in-place policy adoption curves, and reimbursement code expansion timelines. Forecast inputs include semiconductor supply capacity constraints and EMA MDR notified body processing backlogs.
Underlying measurement precision varies by segment; smart dispenser and Wi-Fi-enabled categories carry tighter precision than mechanical timed dispenser estimates due to component supply transparency. Forecasts reflect assumptions regarding MHLW reimbursement continuity, FDA cybersecurity guidance stability, and Taiwan semiconductor fabrication capacity. Deviation in East Asian supply chain disruption severity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Knotless Suture Anchors Market
Medical Devices
Global Cranial Implants Market
Medical Devices
North America General Surgical Devices Market
Medical Devices
Vascular Closure Device (VCD) Market
Medical Devices
Ambulatory Aids Market
Medical Devices
Therapeutic Contact Lenses Market
Medical Devices
North America IVD Regulatory Affairs Outsourcing Market
Medical Devices
Cervical Fusion Market
Medical Devices
Compression Therapy Devices Market
Medical Devices
Medical Pendant Market
Medical Devices
Europe Electroencephalography Devices Market
Medical Devices
Global Electroceuticals Market
Medical Devices
Global Foley Catheters Market
Medical Devices
Micro-Bypass Systems Market
Medical Devices
Anterior Cervical Plating Market
Medical Devices
Phakic Intraocular Lenses (IOL) Market