
 Disposable EEG Electrode Market | 2026-2036
Disposable EEG Electrode Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable EEG Electrode Market Intelligence
Silver-silver chloride is broadening its share of disposable EEG electrode formulations as manufacturers abandon traditional pure silver coatings to reduce raw material costs. Ambu A/S leverages vertical integration across polymer substrate and gel formulation production to protect margin structure. Natus Medical Incorporated anchors North American hospital supply contracts through dedicated neurology distributor networks. Koninklijke Philips N.V. competes by bundling disposable electrodes with its diagnostic monitoring systems, creating captive demand for consumables.
A disposable EEG electrode is a single-use conductive sensor, typically comprising an Ag/AgCl sensing element, a hydrogel or conductive paste interface, and an adhesive backing, designed to detect and transmit microvolt-level cortical electrical signals to amplification and recording equipment. Its primary purpose is to enable non-invasive electroencephalography for neurological diagnosis, intraoperative monitoring, and sleep assessment while eliminating cross-contamination risks inherent to reusable alternatives. Wet electrodes retain dominant share in clinical diagnostics due to established signal fidelity, though dry electrodes are gaining fastest in home healthcare where patient self-application eliminates gel handling complexity. Compressed electrodes occupy a narrow but defensible niche in ambulatory services where transport durability outweighs comfort optimization.
The FDA enforces biocompatibility and electrical safety standards under 21 CFR Part 820 quality system regulations, while ISO 10993 governs cytotoxicity and skin-sensitization testing for adhesive and conductive materials. The EU Medical Device Regulation requires notified body certification for electrodes marketed in Europe, extending compliance timelines for non-European manufacturers. Stakeholders must monitor evolving MDR classification debates and FDA guidance on novel dry-electrode substrates to anticipate registration requirements that could reshape competitive access.
Market Dynamics
Material transitions toward skin-safe conductive polymers are compressing legacy silver supply chains while FDA biocompatibility enforcement under ISO 10993 accelerates formulation turnover across disposable EEG electrode manufacturing.
Growth Catalysts
- ISO 10993 biocompatibility mandates:The FDA's renewed enforcement is forcing manufacturers to abandon allergenic adhesives, opening procurement windows for compliant suppliers.
- Epilepsy monitoring unit standardization:German university hospital networks are mandating single-use protocols across sleep disorder and seizure diagnosis wards.
- Conductive polymer substrate advances:Skin-safe hydrogel formulations are displacing traditional conductive pastes in ambulatory monitoring applications.
Market Restraints
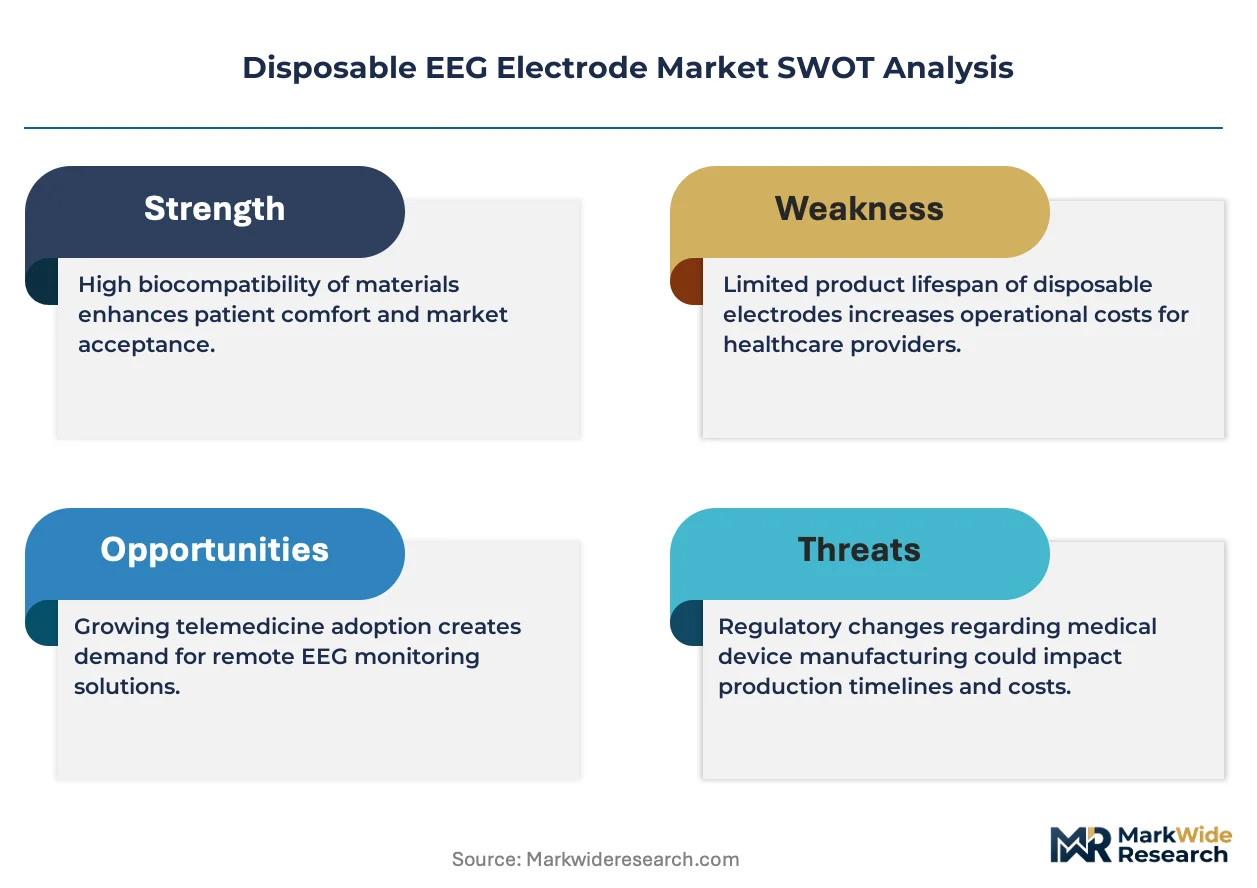
- Silver price volatility:Raw material cost swings for Ag/AgCl coatings compress margin structures for non-integrated manufacturers.
- EU MDR certification timelines:Extended notified body review periods for electrodes create nine-to-eighteen-month market access delays.
- Reusable electrode refurbishment:Sterilization-as-a-service models in cost-constrained health systems threaten single-use volume in price-sensitive segments.
Strategic Opportunities
- Home healthcare self-application:Dry electrode formats eliminate gel handling complexity for patient-operated sleep monitoring devices.
- India diagnostic infrastructure expansion:Government hospital electrification programs are creating first-time EEG procurement demand in tier-two cities.
- bundled consumable contracts:Diagnostic system manufacturers are locking electrode supply into multi-year monitoring equipment leases.
Industry Challenges
- Biocompatibility testing capacity:ISO 10993 cytotoxicity assay bottlenecks are extending product development cycles for novel adhesive substrates.
- Legacy amplifier compatibility:Dry electrode impedance mismatches with existing hospital EEG systems force costly interface redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable EEG Electrode Market |
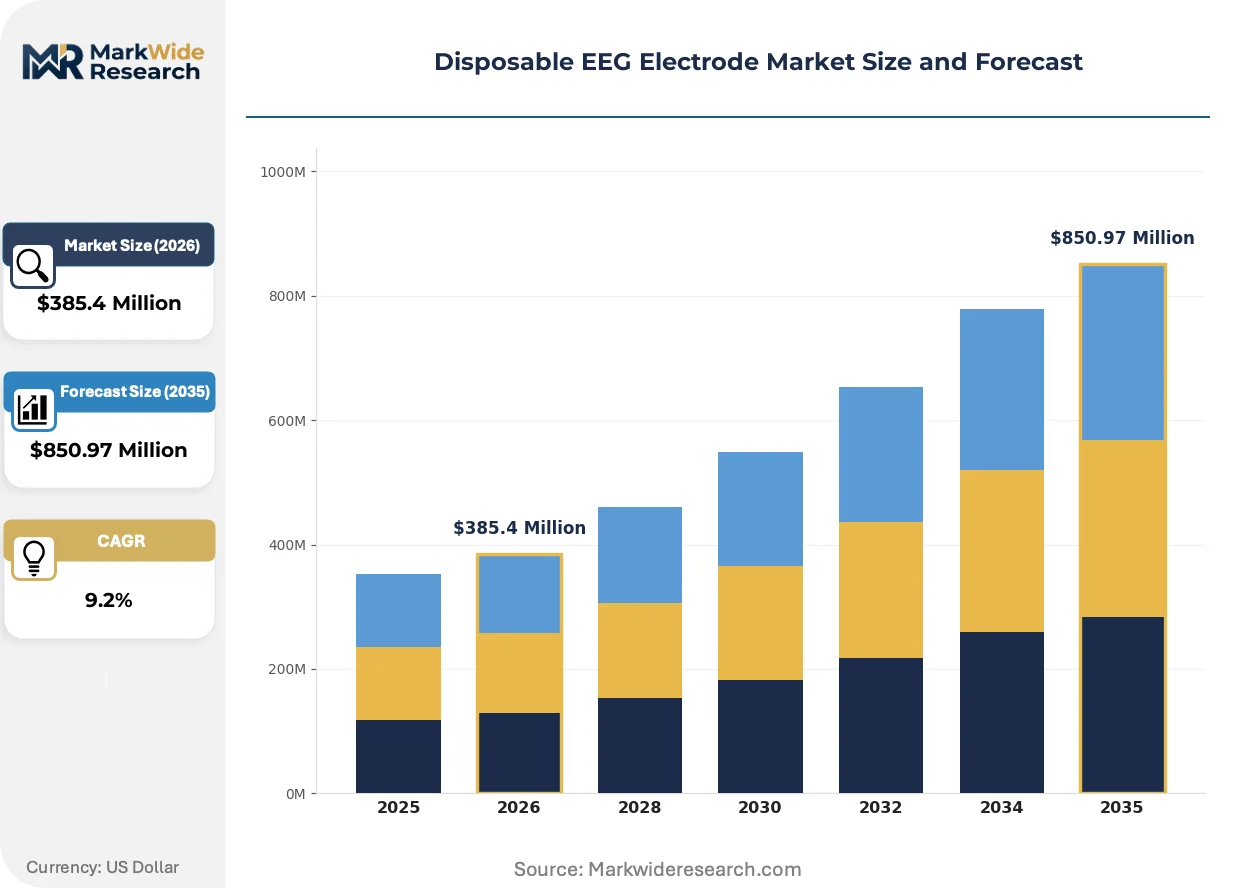
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $850.97 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Electrodes, Dry Electrodes, Compressed Electrodes, Textile Electrodes Application: Clinical Diagnostics, Neurological Research, Sleep Studies, Home Healthcare End User: Hospitals, Research Laboratories, Home Users, Ambulatory Services Distribution Channel: Online Retail, Medical Supply Distributors, Direct Sales, Others |
| Companies Covered | Medtronic plc, Natus Medical Incorporated, Ambu A/S, CONMED Corporation, Brain Scientific, Inc., 3M Health Care, Koninklijke Philips N.V., Rhythmlink International, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable EEG Electrode Market Strategic Shifts & Innovations
Formulation chemistry and procurement contracting are converging to reshape competitive positioning, with material science breakthroughs and regulatory enforcement timelines determining which manufacturers capture hospital network standardization decisions.
Polymer-based conductive hydrogels are integrating micro-structured skin-contact layers to match wet-electrode signal fidelity without gel application. Sleep disorder clinics in the United States are piloting these formats for home-based polysomnography. The technology is integrating patient self-application workflows that eliminate technician labor from diagnostic protocols.
EU Medical Device Regulation classification debates are forcing electrodes above certain risk thresholds into stricter notified body review pathways. German manufacturers with existing MDR certifications are capturing share from suppliers still navigating technical documentation gaps. Ambulatory service providers are consolidating procurement around pre-certified suppliers to avoid supply interruption.
Hospital group purchasing organizations are consolidating disposable electrode contracts into multi-year single-source agreements with price-volume ladders. Independent neurology distributors are losing shelf space to direct manufacturer relationships with integrated delivery networks. This concentration is most visible in Germany, where university hospital procurement alliances now cover sixty-plus facilities under unified technical specifications.
Disposable EEG Electrode Market Segmentation
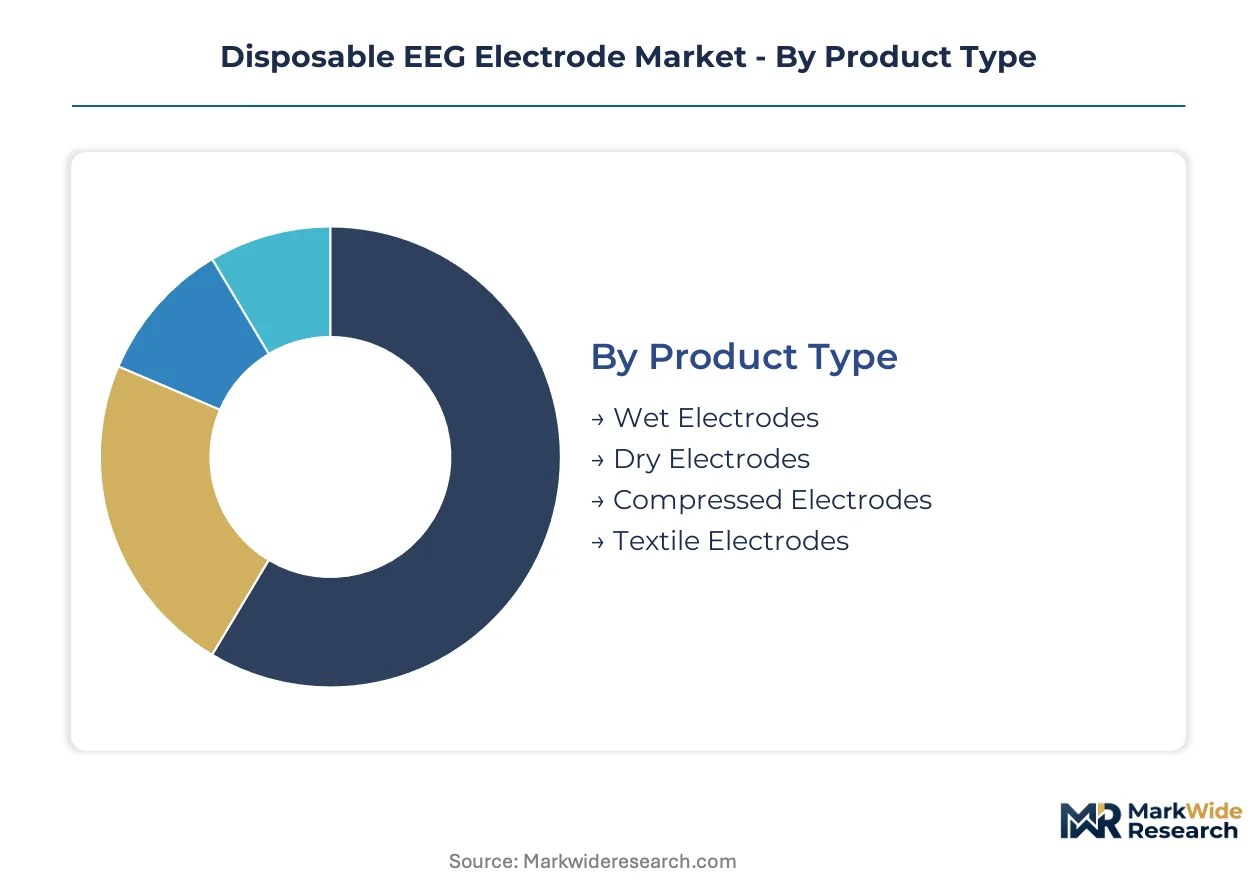
Disposable EEG electrode procurement varies sharply by clinical setting and patient acuity. Signal fidelity requirements, application complexity, and infection control protocols determine which electrode formats capture volume in each segment tier.
Product Type:
Capital intensity concentrates in hydrogel formulation infrastructure and precision coating equipment for wet electrodes, while dry electrode manufacturing demands semiconductor-grade microfabrication cleanrooms.
- Wet Electrodes:Ag/AgCl sensing elements paired with conductive hydrogel interfaces deliver microvolt-level signal fidelity required for epilepsy diagnosis and intraoperative monitoring. German university hospital networks are standardizing these across neurology wards as single-use protocols replace reusable alternatives.
- Dry Electrodes:Polymer substrates with micro-structured skin-contact layers eliminate gel handling for patient self-application. Sleep disorder clinics in the United States are piloting these for home-based polysomnography where technician labor reduction drives procurement decisions.
- Compressed Electrodes:Rigid conductive cores with adhesive backing prioritize transport durability over comfort optimization.
- Textile Electrodes:Conductive fabric weaves integrate into wearable headbands for extended ambulatory monitoring.
Most installed capacity flows through wet electrodes. Expansion is steepest in dry electrodes.
Application:
Regulatory burden scales with patient risk classification, concentrating compliance investment in clinical diagnostics while home healthcare navigates lighter oversight.
- Clinical Diagnostics:FDA 21 CFR Part 820 quality system regulations and ISO 10993 biocompatibility mandates govern cortical electrical signal detection for seizure disorders and brain injury assessment. Wet electrode dominance persists here due to amplifier compatibility and established reimbursement codes.
- Sleep Studies:Polysomnography protocols demand multi-channel EEG alongside respiratory monitoring. Ambulatory service providers are consolidating procurement around MDR-certified suppliers to avoid supply interruption from extended notified body review timelines.
- Neurological Research:Academic laboratories prioritize signal density and experimental flexibility over standardization.
- Home Healthcare:Patient-operated devices favor dry electrode formats that eliminate gel handling complexity and technician dependency.
Revenue concentration sits with clinical diagnostics. Volume growth is climbing the fastest in home healthcare.
End User:
Procurement authority determines contract structure, with hospital group purchasing organizations extracting multi-year single-source agreements while research laboratories retain spot-buying flexibility.
- Hospitals:Integrated delivery networks in Germany now cover sixty-plus facilities under unified technical specifications for disposable EEG electrodes. Direct manufacturer relationships are displacing independent neurology distributors as contracts consolidate into price-volume ladders.
- Ambulatory Services:Transport durability requirements favor compressed electrode formats for mobile epilepsy monitoring and sleep disorder assessment outside fixed clinical infrastructure.
- Research Laboratories:Academic procurement prioritizes experimental flexibility and multi-modal compatibility over standardization.
- Home Users:Direct-to-patient distribution channels are emerging for sleep monitoring devices with self-application dry electrode systems.
Contract value aggregates in hospitals. Account expansion is gaining share fastest in ambulatory services.
Distribution Channel:
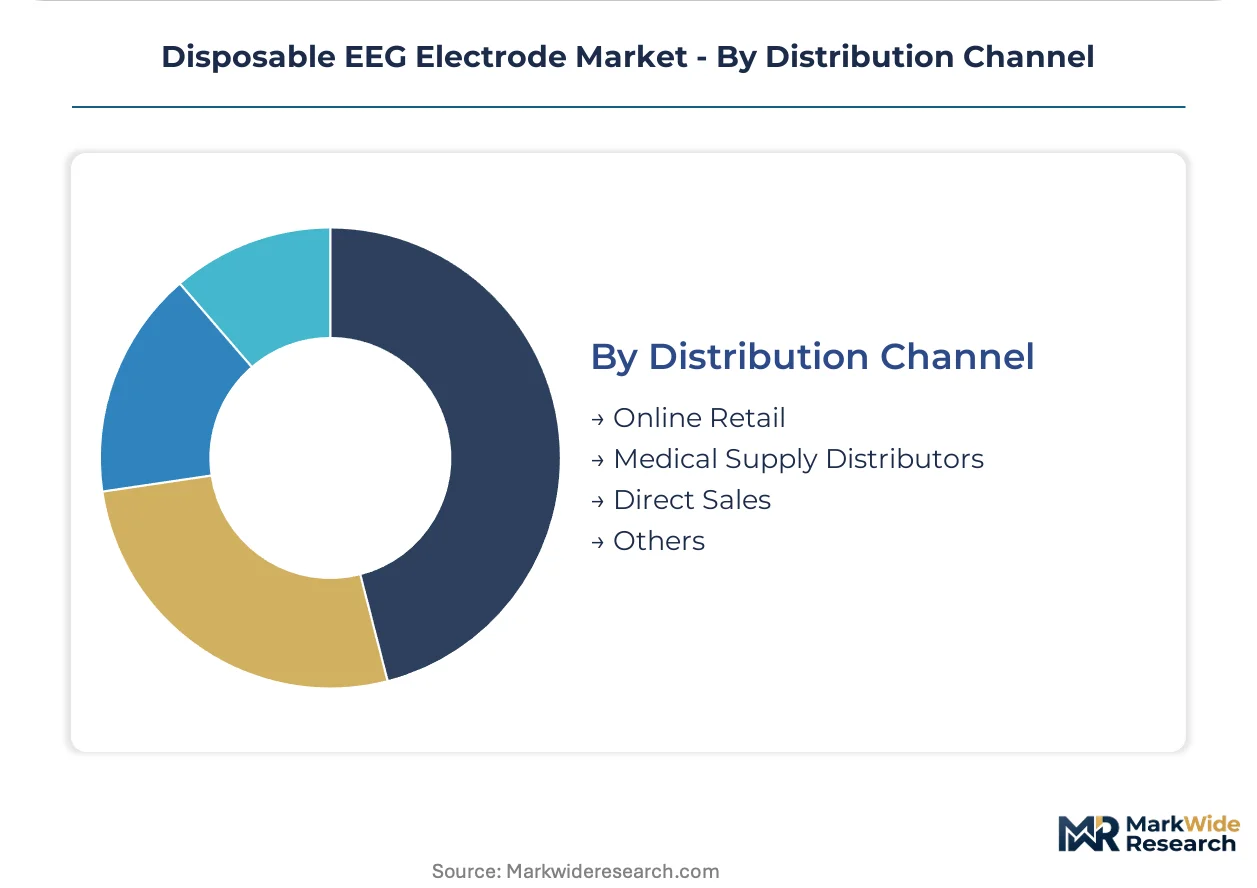
Channel economics reflect customer scale and technical support requirements, with direct sales capturing integrated delivery networks while online retail serves fragmented home users.
- Medical Supply Distributors:Dedicated neurology distributor networks anchor North American hospital supply contracts through technical specification expertise and inventory management services.
- Direct Sales:Diagnostic system manufacturers are locking electrode supply into multi-year monitoring equipment leases, creating captive demand for bundled consumables.
- Online Retail:E-commerce platforms serve home healthcare patients and small research laboratories with standardized product configurations.
- Others:Group purchasing organizations and procurement alliances intermediate for large hospital networks.
Order volume flows predominantly through medical supply distributors. Channel shift is accelerating most quickly in direct sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German university hospital networks anchor procurement standardization for single-use EEG electrodes across epilepsy and sleep disorder units. Material transitions toward ISO 10993-compliant conductive polymers are reshaping supplier access in multiple jurisdictions.
United States
FDA 21 CFR Part 820 quality system regulations govern biocompatibility enforcement for adhesive and conductive materials in clinical diagnostics. The agency's renewed emphasis on ISO 10993 cytotoxicity testing is accelerating formulation turnover among domestic manufacturers. Sleep disorder clinics in the United States are piloting dry electrode formats for home-based polysomnography.
Germany
University hospital procurement alliances now cover sixty-plus facilities under unified technical specifications for disposable EEG electrodes. EU Medical Device Regulation notified body certification requirements are extending compliance timelines for non-European manufacturers. The country's diagnostic equipment manufacturers are bundling disposable electrodes with monitoring systems to create captive consumable demand.
India
Government hospital electrification programs are creating first-time EEG procurement demand in tier-two cities. CDSCO medical device registration requirements are tightening market access for imported electrodes. Maharashtra and Karnataka are emerging as concentration points for diagnostic infrastructure expansion.
Japan
PMDA pharmaceutical and medical device regulations enforce electrical safety standards for cortical signal detection equipment. METI industrial policy is supporting conductive polymer research for skin-safe sensor applications. The Kanto region around Tokyo maintains concentration in neurology research equipment distribution.
China
NMPA medical device registration is requiring extended clinical evaluation for novel dry-electrode substrates entering the domestic market. Government hospital procurement centralization is consolidating supplier relationships in tier-one cities. The Yangtze River Delta region hosts manufacturing capacity for hydrogel formulation components.
Disposable EEG Electrode Market Key Industry Players
Strategic partnerships dominate the current landscape as diagnostic system manufacturers lock electrode supply into multi-year monitoring equipment leases. The vendor base organizes around three tiers: integrated medical technology conglomerates with captive consumable strategies, specialized neurology equipment suppliers with dedicated distributor networks, and regional manufacturers competing on material cost. Two competitive vectors are reshaping positioning: backward integration into polymer substrate production to protect margin structures, and direct contracting with integrated delivery networks to displace independent distributors.
Among European-based manufacturers, Ambu A/S exemplifies the vertically integrated archetype through in-house control of polymer substrate and gel formulation production. Natus Medical Incorporated anchors the North American specialist tier through dedicated neurology distributor networks. Koninklijke Philips N.V. represents the integrated conglomerate model by bundling disposable electrodes with diagnostic monitoring systems to generate recurring consumable revenue streams.
| Leading Market Players |
|---|
| Medtronic plc |
| Natus Medical Incorporated |
| Ambu A/S |
| CONMED Corporation |
| Brain Scientific, Inc. |
| 3M Health Care |
| Koninklijke Philips N.V. |
| Rhythmlink International |
| GE Healthcare |
| Others |
Cost & Logistics Intelligence
German university hospital procurement alliances mandating ISO 10993-compliant single-use protocols are compressing supplier margins while forcing material transitions toward skin-safe conductive polymers. This demand-side specification tightening feeds directly into raw material cost pass-through dynamics and distribution network reconfiguration.
Pricing Analysis
Silver price volatility in Ag/AgCl coatings passes through unevenly across manufacturer tiers, with backward-integrated producers absorbing shocks better than non-integrated competitors. Three-tier pricing structure across premium, standard, and economy levels separates MDR-certified European suppliers from emerging Asian manufacturers and commodity spot buyers. Pricing pressure stems from reusable electrode refurbishment services gaining traction in cost-constrained health systems. Ambulatory service providers exhibit highest price sensitivity due to thin procedure margins, while integrated delivery networks leverage volume scale for preferential contracting.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and China form hub-and-spoke patterns serving hospital networks and ambulatory operators. Manufacturing concentration centers on Denmark for vertically integrated polymer substrate production, the United States for hydrogel formulation expertise, and China for adhesive backing components. Raw material dependencies include silver chloride precursors, medical-grade acrylic adhesives, and conductive polymer resins. Single-source vulnerability in silver supply chains from concentrated mining jurisdictions creates structural risk. Distribution runs through dedicated neurology distributor networks in North America and direct manufacturer relationships with integrated delivery networks in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The disposable EEG electrode market compounds returns through regulatory ratchets, with FDA's renewed ISO 10993 enforcement creating recurring compliance investment cycles that favor prepared incumbents.
For Market Incumbents: Lock in multi-year bundled consumable contracts with diagnostic system leases before MDR certification gaps eliminate non-European competitors. Secure backward integration into hydrogel formulation production to defend margin structure against silver price volatility. Prioritize direct relationships with German university hospital procurement alliances covering sixty-plus facilities under unified technical specifications. For New Entrants and Emerging Players: E-commerce platforms serving home healthcare patients offer lowest barrier entry for dry electrode formats eliminating gel handling complexity. Target tier-two Indian cities where government hospital electrification programs create first-time EEG procurement demand without entrenched supplier relationships. Pursue white-label manufacturing partnerships with established diagnostic equipment brands seeking MDR-compliant electrode sourcing. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing existing EU MDR certifications and captive polymer substrate production. Five-to-ten year viability hinges on positioning ahead of dry electrode impedance standardization resolving legacy amplifier compatibility barriers. Monitor FDA guidance timelines on novel dry-electrode substrates as inflection signal for competitive access reshuffling.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Accelerates market access for German manufacturers while excluding non-compliant competitors from hospital procurement. |
| Backward Integration into Polymer Substrates | Protects Ambu A/S margin structure against silver price volatility through captive hydrogel formulation production. |
| Direct Hospital System Partnerships | Displaces independent neurology distributors as Natus Medical anchors North American supply contracts. |
| Dry Electrode R&D Scale-Up | Captures home healthcare expansion as sleep disorder clinics pilot patient self-application formats. |
| India Distribution Network Buildout | Positions suppliers for government hospital electrification programs in Maharashtra and Karnataka diagnostic corridors. |
Research Approach
Bottom-up hospital procurement modeling reconciled against top-down raw material tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and neurology distributor principals combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contract registries, and silver commodity price indices. Triangulation across these sources ensures segment-level volume estimates align with supply-side capacity assessments.
Historical trendline analysis of electrode shipment patterns and installed EEG system bases informs the projection framework across the analysis window. Segmentation dimensions modeled include product type tier, application setting, end-user category, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves incorporating MDR compliance timelines and dry electrode technology diffusion parameters. Forecast inputs include silver price scenario modeling and hospital standardization protocol adoption rates.
The model assumes a particular technology adoption path; alternative pathways for dry electrode impedance standardization would alter the outlook. Forecasts reflect documented assumptions regarding MDR certification completion rates and FDA enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Vertebral Compression Fracture Devices Market
Medical Devices
Smart Stairlift Market
Medical Devices
Global Neurovascular Thrombectomy Devices Market
Medical Devices
Brachytherapy Afterloaders Market
Medical Devices
Europe Breast Implant Market
Medical Devices
Digital Vision Lenses Market
Medical Devices
Global Aneurysm Clips Market
Medical Devices
Absorbable Antibacterial Envelope Market
Medical Devices
Craniomaxillofacial Implants Market
Medical Devices
Digital Blood Pressure Monitors Market
Medical Devices
India Diabetes Devices Market
Medical Devices
Global Breast Implants Market
Medical Devices
Neurovascular Access Catheters Market
Medical Devices
Global Photomedicine Market
Medical Devices
Corneal Cross Linking Devices Market
Medical Devices
Europe Surgical Microscopes Market