
 Intrathecal Pumps Market | 2026-2036
Intrathecal Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Intrathecal Pumps Market Intelligence
The EU Medical Device Regulation is broadening compliance requirements for implantable drug delivery systems across European pain management facilities. Medtronic plc sustains technology leadership in programmable pump architectures with deep R&D investment in battery longevity. Flowonix Medical Inc. specializes in catheter-compatible systems for targeted spasticity therapy. B. Braun Melsungen AG anchors European manufacturing scale with vertically integrated component production.
Intrathecal pumps are implantable or external devices that deliver medication directly into the cerebrospinal fluid via a catheter, typically operating at infusion rates measured in microliters per hour for precise dosing control. These systems serve patients with refractory chronic pain, severe spasticity, or cancer-related discomfort who have failed oral or systemic analgesic regimens. Programmable pumps capture the dominant share of product type revenue due to their titratable dosing flexibility and physician-adjustable protocols. Chronic pain management leads therapy area demand while spasticity treatment represents the fastest-growing application segment driven by cerebral palsy and multiple sclerosis patient populations.
FDA premarket notification and EU MDR conformity assessment shape product development timelines and clinical evidence requirements for intrathecal pump manufacturers. ISO 14708 active implantable medical device standards govern electromagnetic compatibility and electrical safety testing protocols. Health Canada and Japan's PMDA maintain aligned but distinct review pathways that influence regional launch sequencing. Stakeholders must monitor evolving cybersecurity guidance for connected drug delivery systems and prepare for outcome-based reimbursement pilots in major markets.
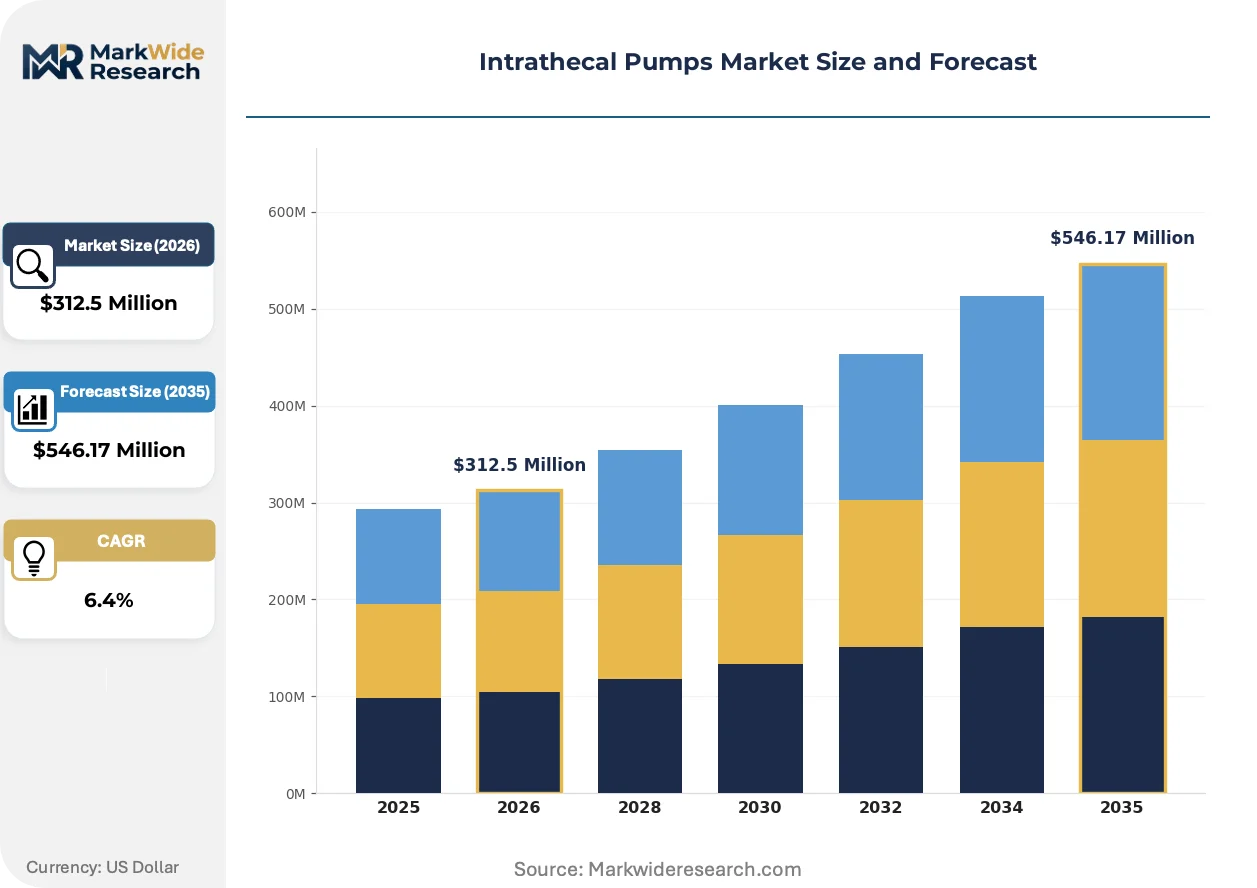
Market Dynamics
Implantable drug delivery systems face mounting pressure from the EU Medical Device Regulation's expanded clinical evidence requirements, forcing manufacturers to restructure development timelines and safety documentation protocols for programmable pump architectures.
Growth Catalysts
- EU MDR Conformity Assessment:The regulation's stricter post-market surveillance mandates are elevating quality standards across European pain management facilities, creating competitive separation for compliant manufacturers.
- Chronic Pain Prevalence:Aging demographics in the United States, Germany, and Japan are expanding the addressable patient pool for refractory pain therapy beyond oral analgesic failure thresholds.
- Targeted Spasticity Therapy:Cerebral palsy and multiple sclerosis patient populations are driving catheter-compatible system adoption in specialized neurology centers.
Market Restraints
- Premium Component Concentration:Battery cell and precision catheter supply chains concentrate among limited Asian suppliers, exposing manufacturers to input volatility and qualification delays.
- FDA Premarket Pathway Friction:The notification process for novel programmable architectures extends development cycles by 18-24 months compared to predicate device routes.
- Oral Analgesic Substitution:Extended-release opioid formulations and non-opioid alternatives retain first-line status in many reimbursement frameworks, constraining implantable system access.
Strategic Opportunities
- Underpenetrated Japanese Market:PMDA alignment with ISO 14708 standards is accelerating review timelines for foreign manufacturers with existing CE marking.
- Outcome-Based Reimbursement Pilots:German statutory health insurance experiments with therapy-response-linked payment models are creating preference for titratable programmable systems.
- Cybersecurity-Integrated Platforms:Connected drug delivery systems incorporating encrypted telemetry protocols are expanding into hospital-integrated pain management workflows.
Industry Challenges
- Active Implantable Device Engineering Talent:Electromagnetic compatibility and electrical safety specialization scarcity constrains R&D team scaling for ISO 14708 compliance.
- Legacy System Integration Complexity:New programmable pumps must interface with established electronic health record architectures and catheter inventory systems in major medical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intrathecal Pumps Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Programmable Pumps, Fixed-Rate Pumps, Refillable Pumps, Implantable Pumps, External Pumps Therapy Area: Chronic Pain Management, Spasticity Treatment, Cancer Pain Relief, Severe Muscle Spasms, Postoperative Pain End User: Specialty Clinics, Rehabilitation Centers, Pain Management Facilities, Neurosurgical Units Delivery Technology: Battery-Powered Systems, Peristaltic Pumps, Electromechanical Pumps, Hydraulic Mechanisms |
| Companies Covered | Tricumed Medizintechnik GmbH, Boston Scientific Corp., Medtronic plc, Baxter International Inc., Smiths Medical, Flowonix Medical Inc., Teleflex Inc., B. Braun Melsungen AG, Johnson & Johnson (Codman & Shurtleff), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intrathecal Pumps Market Strategic Shifts & Innovations
Battery longevity engineering and encrypted connectivity protocols are redefining competitive differentiation in implantable drug delivery, with regulatory frameworks simultaneously tightening evidence requirements and opening reimbursement experimentation pathways.
Closed-loop sensing technology is expanding into intrathecal pump architectures, enabling real-time cerebrospinal fluid pressure monitoring and automated dose adjustment. Academic medical centers in the United States and Germany are piloting these systems for complex spasticity cases. The technology is expanding into premium-tier product positioning while compressing differentiation timelines for battery-only programmable platforms.
EU MDR technical documentation requirements are mandating systematic clinical evaluation reports across all implantable device classes. Manufacturers must now demonstrate equivalence or conduct new investigations for software updates affecting dosing algorithms. Programmable pump portfolios face the heaviest documentation burden, with notified bodies extending review queues for novel catheter-pump combinations.
Hospital procurement committees are consolidating vendor relationships for implantable pain management systems, favoring suppliers with comprehensive service infrastructure. Group purchasing organizations in the United States are displacing individual facility negotiations with multi-hospital contract structures. This concentration is most visible in integrated delivery networks across Texas, Florida, and California, where standardization incentives override individual physician preference.
Intrathecal Pumps Market Segmentation
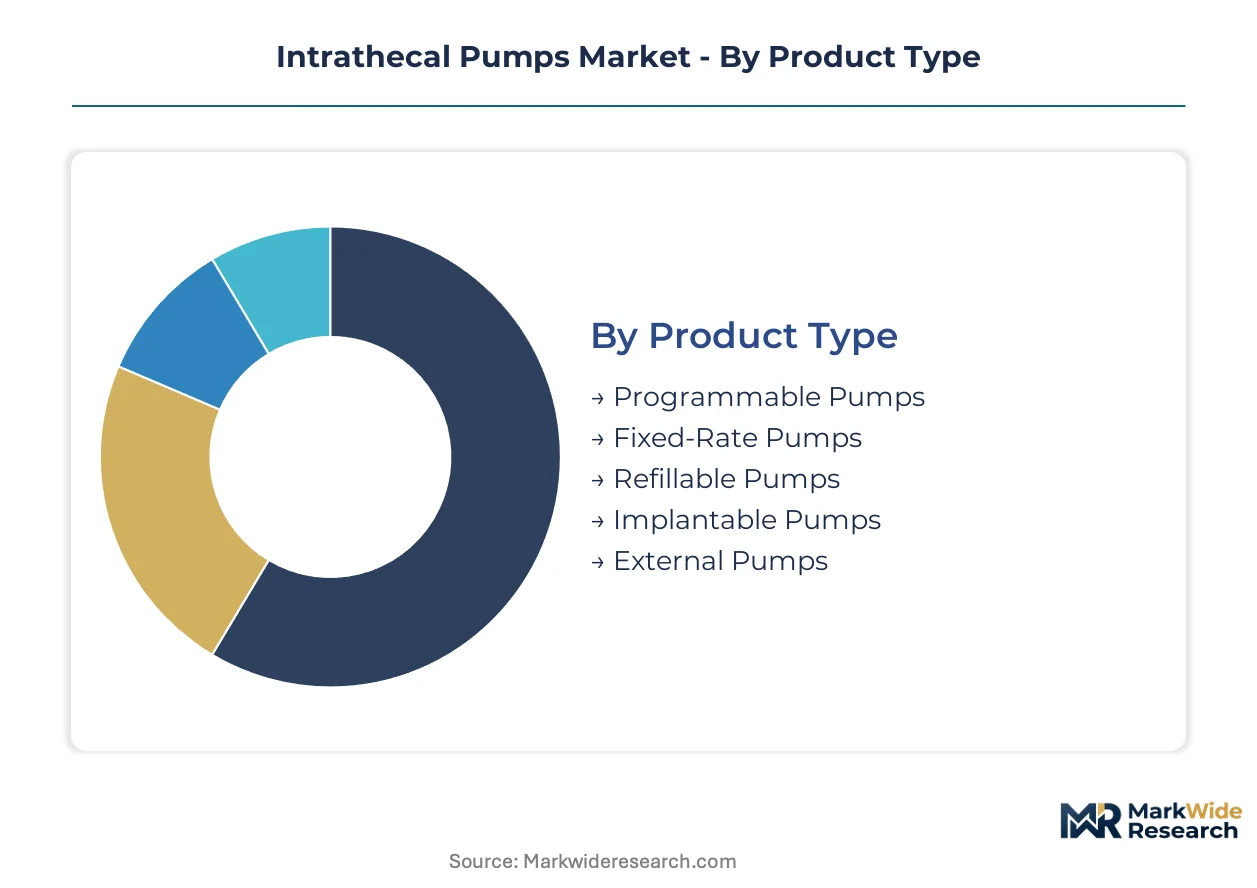
Intrathecal pump procurement decisions pivot on therapy specificity, reimbursement compatibility, and facility infrastructure capacity. Manufacturers must align product architectures with distinct clinical workflows across pain management facilities and neurosurgical units.
Product Type:
Physician preference for dosing flexibility drives category selection, with programmable architectures commanding premium positioning in academic medical centers.
- Programmable Pumps:Electronically controlled systems enable microliter-per-hour titration and remote protocol adjustments via telemetry. Pain management facilities in the United States prioritize these for complex spasticity cases requiring frequent dose optimization.
- Fixed-Rate Pumps:Mechanical reservoirs deliver constant infusion without electronic components, reducing battery dependency and cybersecurity exposure. German statutory health insurance reimbursement frameworks favor these for stable chronic pain patients with predictable analgesic requirements.
- Refillable Pumps:Percutaneous reservoir access extends device longevity through outpatient maintenance protocols.
- Implantable Pumps:Fully internalized systems with subcutaneous placement minimize infection risk in long-term therapy.
- External Pumps:Catheter-connected portable units serve bridging therapy and palliative care transitions.
Volume sits with programmable systems; growth tilts toward refillable architectures as battery longevity constraints reshape total cost-of-ownership calculations.
Therapy Area:
Patient population severity and reimbursement authorization complexity segment demand across neurological and oncological indications.
- Chronic Pain Management:Refractory non-malignant pain patients who have exhausted oral opioid escalations and interventional procedures. United States Medicare coverage determinations for implantable systems concentrate demand in accredited pain management facilities with comprehensive implant programs.
- Spasticity Treatment:Cerebral palsy and multiple sclerosis populations requiring intrathecal baclofen delivery. Japanese neurology centers are expanding catheter-compatible system adoption as PMDA review timelines accelerate for CE-marked devices.
- Cancer Pain Relief:Malignancy-associated discomfort in patients with systemic analgesic intolerance or dose-limiting side effects.
- Severe Muscle Spasms:Traumatic brain injury and spinal cord injury sequelae requiring targeted antispasmodic delivery.
- Postoperative Pain:Temporary intrathecal analgesia for major thoracic and abdominal procedures.
Chronic pain captures installed base dominance; spasticity therapy is climbing the fastest as pediatric cerebral palsy protocols mature.
End User:
Facility credentialing requirements and implant volume thresholds determine vendor contract eligibility and service infrastructure investments.
- Specialty Clinics:Ambulatory settings with interventional pain physicians performing pump implants and refill procedures. Texas and Florida integrated delivery networks are consolidating purchasing through multi-clinic contracts.
- Rehabilitation Centers:Inpatient and outpatient facilities managing spasticity therapy titration and functional outcome measurement.
- Pain Management Facilities:Hospital-based and independent centers with comprehensive implantable device programs.
- Neurosurgical Units:Operating room infrastructure for initial catheter placement and revision surgeries.
Procurement authority concentrates in pain management facilities; expansion tilts toward rehabilitation centers as outcome-based reimbursement pilots proliferate.
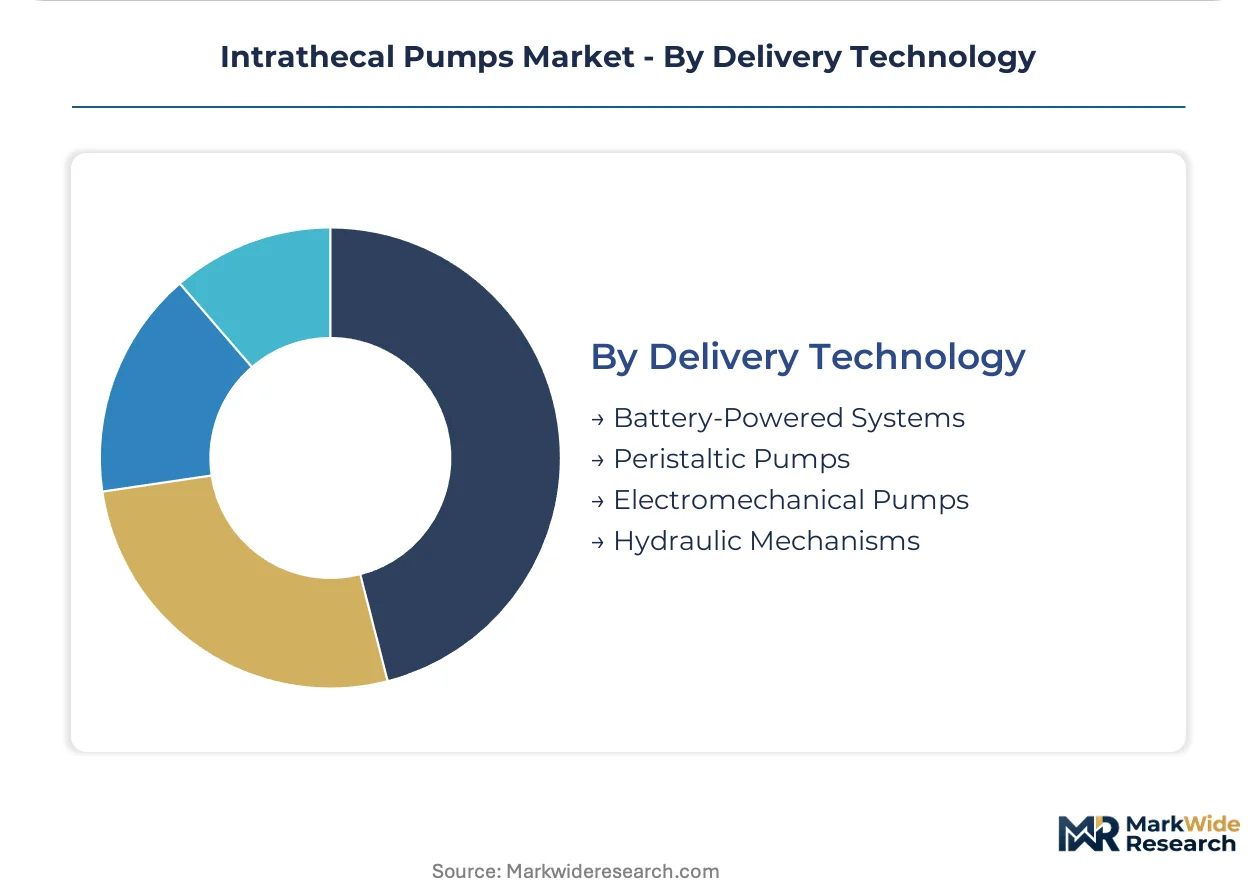
Delivery Technology:
Power source reliability and dose precision specifications differentiate competitive positioning in FDA and EU MDR approval pathways.
- Battery-Powered Systems:Lithium-based cells supporting multi-year operational life with telemetry connectivity. ISO 14708 electromagnetic compatibility testing requirements extend development timelines for novel battery architectures.
- Peristaltic Pumps:Roller mechanism displacement eliminates valve-dependent failure modes. German manufacturers emphasize these for EU MDR technical documentation simplicity.
- Electromechanical Pumps:Motor-driven piston systems enabling high-precision flow control.
- Hydraulic Mechanisms:Pressure-driven reservoirs without electronic components for MRI-conditional applications.
Revenue concentrates in battery-powered platforms; design activity tilts toward electromechanical alternatives as closed-loop sensing integration advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American intrathecal pump manufacturing, with the Twin Cities metro housing concentrated R&D infrastructure for programmable drug delivery systems.
United States
Medicare coverage determinations for implantable pain management systems concentrate demand in accredited facilities across Texas, Florida, and California. FDA premarket notification pathways for novel programmable architectures extend development timelines by 18-24 months. The Greater Boston corridor hosts specialized neurology centers piloting closed-loop sensing integration for complex spasticity cases.
Germany
Statutory health insurance experiments with outcome-based reimbursement models create preference for titratable programmable systems in Baden-Württemberg and Bavaria. EU MDR conformity assessment mandates systematic clinical evaluation reports for all implantable device classes. The Rhine-Ruhr industrial basin anchors European manufacturing scale for precision catheter components.
Japan
PMDA alignment with ISO 14708 standards accelerates review timelines for foreign manufacturers with existing CE marking. Aging demographics in the Kanto region expand the addressable patient pool for refractory pain therapy. Tokyo-based neurology centers are expanding catheter-compatible system adoption for cerebral palsy and multiple sclerosis populations.
United Kingdom
NHS England specialized commissioning frameworks concentrate implantable device procurement in designated pain management centers across London and the Midlands. MHRA post-Brexit regulatory pathways maintain alignment with EU MDR technical documentation requirements. The Oxford-Cambridge arc hosts academic medical centers advancing battery longevity engineering research.
Switzerland
Swissmedic maintains distinct but harmonized review pathways for active implantable medical devices, influencing regional launch sequencing for programmable pump manufacturers. Zurich and Basel clusters concentrate precision engineering talent for electromagnetic compatibility specialization. Cantonal hospital procurement committees favor suppliers with comprehensive service infrastructure for long-term intrathecal therapy.
Intrathecal Pumps Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology sophistication and regulatory compliance depth. The vendor base stratifies between diversified medical device conglomerates with full-stack capabilities and specialized pump manufacturers with targeted therapy expertise. Three archetypes dominate: programmable platform specialists, catheter-integrated system providers, and vertically integrated European manufacturers. Competitive moves concentrate on M&A for regulatory dossier acquisition and strategic partnerships for closed-loop sensing development.
Within the diversified conglomerate tier, Medtronic plc and Boston Scientific Corp. occupy positions spanning multiple implantable drug delivery segments. Tricumed Medizintechnik GmbH exemplifies the specialized European manufacturer archetype with concentrated expertise in precision infusion mechanisms. Flowonix Medical Inc. represents the targeted therapy specialist model focused on catheter-compatible architectures for neurological applications.
| Leading Market Players |
|---|
| Tricumed Medizintechnik GmbH |
| Boston Scientific Corp. |
| Medtronic plc |
| Baxter International Inc. |
| Smiths Medical |
| Flowonix Medical Inc. |
| Teleflex Inc. |
| B. Braun Melsungen AG |
| Johnson & Johnson (Codman & Shurtleff) |
| Others |
Cost & Logistics Intelligence
Lithium battery cell costs cascade through programmable pump architectures, compressing margins at the premium tier while fixed-rate mechanical systems gain price competitiveness in German statutory reimbursement frameworks. Precision catheter supply constraints in Asian manufacturing clusters amplify input volatility, forcing European manufacturers toward captive component production or long-term qualification partnerships.
Pricing Analysis
Value-based pricing anchored to therapy response outcomes dominates programmable pump procurement in United States academic medical centers, where reimbursement authorization ties to documented pain reduction metrics. Three-tier pricing structure across premium programmable, standard refillable, and economy fixed-rate levels segments buyer access, with FDA premarket notification burden and EU MDR conformity assessment costs driving premium tier elevation. Cost compression in the standard tier intensifies because Health Canada and Japan PMDA alignment pressures are accelerating foreign manufacturer entry. Hospital purchasing committees exhibit lowest price sensitivity for closed-loop sensing platforms, while independent specialty clinics in Texas and Florida integrated delivery networks demonstrate highest sensitivity to total cost-of-ownership calculations.
Supply Chain Analysis
Electromagnetic compatibility engineering talent scarcity in the Minneapolis-Twin Cities corridor and Rhine-Ruhr industrial basin constrains R&D team scaling for ISO 14708 compliance, tethering battery-powered system development to established manufacturing geographies. Component supply draws from South Korean lithium cell producers, German precision catheter manufacturers, and Swiss electromagnetic shielding specialists. Single-source vulnerability in programmable pump microcontroller architectures poses structural risk given FDA cybersecurity guidance evolution. Distribution runs through hospital procurement committees and group purchasing organizations, with multi-hospital contract structures displacing individual facility negotiations across United States integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU MDR expanded clinical evidence requirements force subscale manufacturers toward regulatory dossier acquisition or exit.
For Market Incumbents: Hedge against fixed-rate pump commoditization by deepening backward integration into precision catheter production and securing exclusive hospital system partnerships for closed-loop sensing pilot programs. Battery longevity R&D investment and encrypted telemetry protocol development defend premium positioning against emerging cybersecurity-integrated platform entrants. CE marking pathway acceleration for software-updatable dosing algorithms maintains competitive separation from predicate device-dependent competitors. For New Entrants and Emerging Players: Begin with catheter-compatible system specialization for cerebral palsy and multiple sclerosis populations in Japanese neurology centers, where PMDA review timeline acceleration for existing CE-marked devices creates regulatory arbitrage. Target rehabilitation center expansion as outcome-based reimbursement pilots proliferate, offering functional outcome measurement bundling that incumbent service infrastructure struggles to match. Direct-to-specialist-neurologist go-to-market models bypass hospital procurement committee concentration. For Investors and Strategic Acquirers: FDA premarket approval pathway conversion for novel programmable architectures is the leading indicator that regulatory dossier depth is separating viable acquisition targets from stranded assets. Five-to-ten year viability favors manufacturers with vertically integrated European manufacturing scale and active ISO 14708 notified body relationships. Watch for German statutory health insurance outcome-based reimbursement pilot expansion as the inflection signal for titratable system preference acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment acceleration unlocks Japanese PMDA review timeline advantages for foreign manufacturers. |
| Hospital System Partnership | Multi-hospital contract structures in Texas and Florida integrated delivery networks displace fragmented individual facility negotiations. |
| Software Companion Development | Encrypted telemetry protocols for connected drug delivery systems address evolving FDA cybersecurity guidance requirements. |
| Reimbursement Strategy | Outcome-based pilot alignment with German statutory health insurance experiments creates preference for titratable programmable platforms. |
| Backward Integration | In-house precision catheter production mitigates South Korean and German component supply concentration risks. |
Research Approach
Independent corroboration across pain management facility procurement managers, biomedical engineers specializing in active implantable devices, GPO contracts managers, and EU MDR notified body technical reviewers underwrites the qualitative findings. Primary interviews with hospital purchasing committee members and rehabilitation center clinical directors combined with secondary validation from FDA 510(k) filings, EU MDR clinical evaluation report databases, and Japanese PMDA review pathway documentation established segment-level demand quantification. Bottom-up installed base modeling and top-down therapy-area penetration analysis triangulated volume estimates across the projection horizon.
Historical reference periods anchored the forecast window to pre-COVID baseline procedural volumes and post-EU MDR implementation regulatory throughput rates. Segmentation modeling incorporated product type programmable versus fixed-rate architecture, therapy area chronic pain versus spasticity indication, end user pain management facility versus rehabilitation center, and delivery technology battery-powered versus electromechanical mechanism. CAGRs derived from procedure volume growth rates and device replacement cycle analysis, with reimbursement authorization timeline assumptions and cybersecurity regulatory evolution as industry-specific forecast inputs.
Underlying measurement precision varies by segment; programmable pump revenue and United States Medicare-covered procedure volumes carry tighter precision than emerging market penetration and closed-loop sensing pilot adoption. Forecasts reflect assumptions regarding EU MDR notified body capacity, PMDA review timeline acceleration, and outcome-based reimbursement pilot expansion that specific regulatory delays or reimbursement framework reversals could revise. A small set of triggers including FDA cybersecurity guidance finalization and German statutory health insurance pilot outcome publication warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Italy Contraceptive Devices Market
Medical Devices
Australia Artificial Organs and Bionic Implants Market
Medical Devices
China Ultrasound Devices Market
Medical Devices
Transcutaneous Oximetry Systems Market
Medical Devices
Cardioscope Market
Medical Devices
North America Biopsy Devices Market
Medical Devices
Brazil Medical Devices Market
Medical Devices
DLIF and XLIF Implants Market
Medical Devices
Global Prosthetics Market
Medical Devices
Dynamic Spinal Tethering Systems Market
Medical Devices
Global Spinal Cord Stimulation Devices Market
Medical Devices
Europe Organ-On-Chip Market
Medical Devices
On-Body Drug Delivery Devices Market
Medical Devices
US Medical Device Outsourcing Market
Medical Devices
Global Smart Contact Lenses Market
Medical Devices
Global Cerebrospinal Fluid Management Devices Market