
 Contact and Intraocular Lenses Market | 2026-2036
Contact and Intraocular Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Contact and Intraocular Lenses Market Analysis
Ophthalmic surgeon training capacity is collapsing in several developed markets, creating procedural bottlenecks that constrain intraocular lens implant volumes even as patient need expands. Alcon Inc. leverages its vertically integrated cataract surgical ecosystem to sustain instrument-and-lens bundling that locks hospital purchasing committees. Johnson & Johnson Vision Care, Inc. anchors daily disposable contact lens supply through automated manufacturing scale that few rivals can replicate. Bausch + Lomb Corporation competes across both contact and intraocular segments, navigating channel conflicts between retail optometry and hospital procurement.
Contact and intraocular lenses are medical devices designed to correct refractive errors, replace natural crystalline lenses after cataract extraction, or modify corneal optics through direct ocular surface interaction; silicone hydrogel formulations now dominate soft contact lens portfolios due to oxygen permeability coefficients exceeding 100 Dk/t, while acrylic hydrophobic and hydrophilic materials compete in posterior chamber intraocular lens platforms engineered for capsular bag fixation. Soft lenses occupy the highest volume tier in contact lens consumption, though scleral lenses command premium positioning for irregular cornea management. Healthcare providers represent the decisive demand node for intraocular lenses, where surgeon preference and facility contract terms shape brand selection more than patient-directed choice.
FDA premarket notification pathways and ISO 11979 biocompatibility standards govern intraocular lens commercialization in the United States, while the EU Medical Device Regulation imposes enhanced clinical evidence requirements that extend CE marking timelines for novel optical designs. Japan's PMDA maintains distinct pharmaceutical affairs classification for contact lens care solutions that constrains bundling strategies. Stakeholders must monitor how FDA draft guidance on accommodating intraocular lenses reshapes premium category definitions and reimbursement negotiations with Medicare Administrative Contractors.
Market Dynamics
Silicone hydrogel oxygen permeability thresholds above 100 Dk/t are extending daily wear parameters while compressing conventional hydrogel market positions, forcing material science investments across lens portfolios.
Growth Catalysts
- Presbyopic Demographics:Aging populations in Japan, Germany, and the United States are expanding the addressable patient pool requiring multifocal and toric corrections.
- EU Medical Device Regulation:Enhanced clinical evidence requirements for CE marking are accelerating consolidation toward manufacturers with robust trial infrastructure.
- Cataract Surgical Volume:Premium intraocular lens adoption in hospital outpatient departments is elevating per-procedure value capture.
Market Restraints
- Acrylic Monomer Volatility:Hydrophobic and hydrophilic intraocular lens raw material costs fluctuate with petroleum feedstock pricing.
- Surgeon Training Bottlenecks:Ophthalmic surgical fellowship capacity constraints in the United States and United Kingdom limit procedural throughput regardless of patient need.
- Refractive Surgery Substitution:Laser vision correction platforms compete for younger myopic candidates before presbyopia onset.
Strategic Opportunities
- Accommodating Intraocular Lenses:FDA draft guidance reshaping premium category definitions creates reimbursement negotiation leverage with Medicare Administrative Contractors.
- Scleral Lens Specialization:Irregular cornea management applications including keratoconus and post-graft ectasia remain underpenetrated relative to soft lens saturation.
- Automated Manufacturing Scale:Daily disposable contact lens production lines reward capital-intensive entrants with throughput advantages.
Industry Challenges
- ISO 11979 Biocompatibility Certification:Extended testing timelines for novel optical designs delay commercialization and compress development ROI windows.
- Channel Conflict Navigation:Manufacturers competing across both retail optometry and hospital procurement face pricing transparency demands from divergent buyer types.
- Capsular Bag Fixation Engineering:Posterior chamber intraocular lens designs must balance haptic flexibility against posterior capsule opacification resistance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contact and Intraocular Lenses Market |
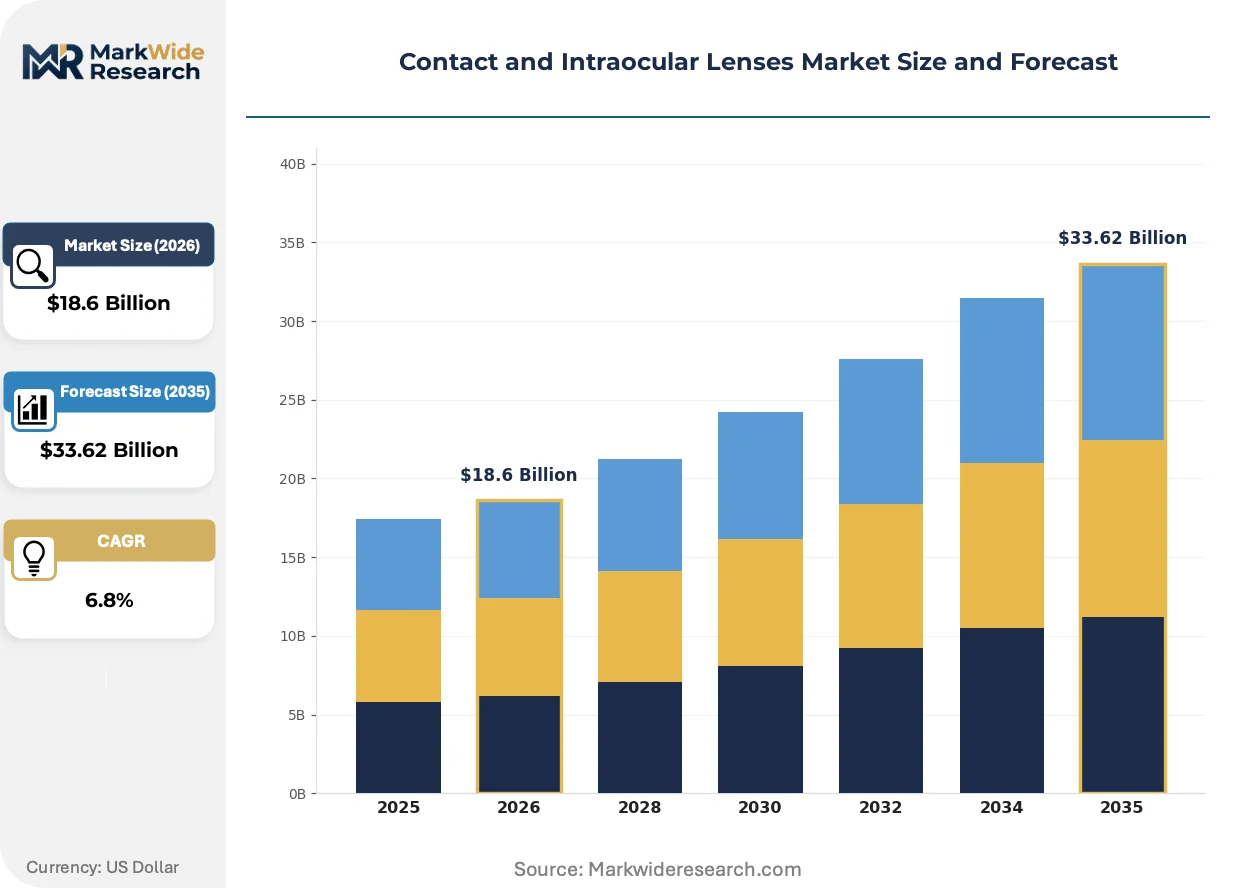
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $33.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Lenses, Rigid Gas Permeable, Scleral Lenses, Toric Lenses Application: Corrective, Cosmetic, Therapeutic, Specialty End User: Consumer, Healthcare Providers, Clinics, Hospitals Material: Hydrogel, Silicone Hydrogel, Poly-Methyl Methacrylate, PC |
| Companies Covered | Johnson & Johnson Vision Care, Inc., Alcon Inc., Bausch + Lomb Corporation, The Cooper Companies, Inc., Carl Zeiss Meditec AG, HOYA Corporation, EssilorLuxottica SA, STAAR Surgical Company, Rayner Intraocular Lenses Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contact and Intraocular Lenses Market Emerging Trajectories
Material science advances and regulatory evidence requirements are segmenting competitive capabilities, separating capital-intensive platform players from specialized technology licensors.
Extended wear silicone hydrogel formulations are bifurcating the soft contact lens category into high-Dk/t daily disposables versus conventional replacement schedules. Ambulatory surgical centers in the United States are adopting these materials for post-refractive surgery bandage lens applications. The technology is compressing mid-tier hydrogel margins while rewarding oxygen permeability leaders with hospital contract bundling opportunities.
Japan's PMDA maintains distinct pharmaceutical affairs classification for contact lens care solutions, constraining bundling strategies that pair lenses with disinfection chemistries. This regulatory friction forces manufacturers to pursue separate marketing authorizations for device-solution combinations. Daily disposable manufacturers face particular pressure as solution sales cannot subsidize lens pricing in this jurisdiction.
Hospital purchasing committees are consolidating intraocular lens procurement through instrument-and-lens bundling agreements that privilege vertically integrated cataract surgical ecosystems. Independent ambulatory surgery centers respond by forming group purchasing organizations to match contract terms. The United States exhibits the most pronounced concentration, where facility contract terms override individual surgeon brand preference in three-quarters of implant decisions.
Contact and Intraocular Lenses Market Segmentation
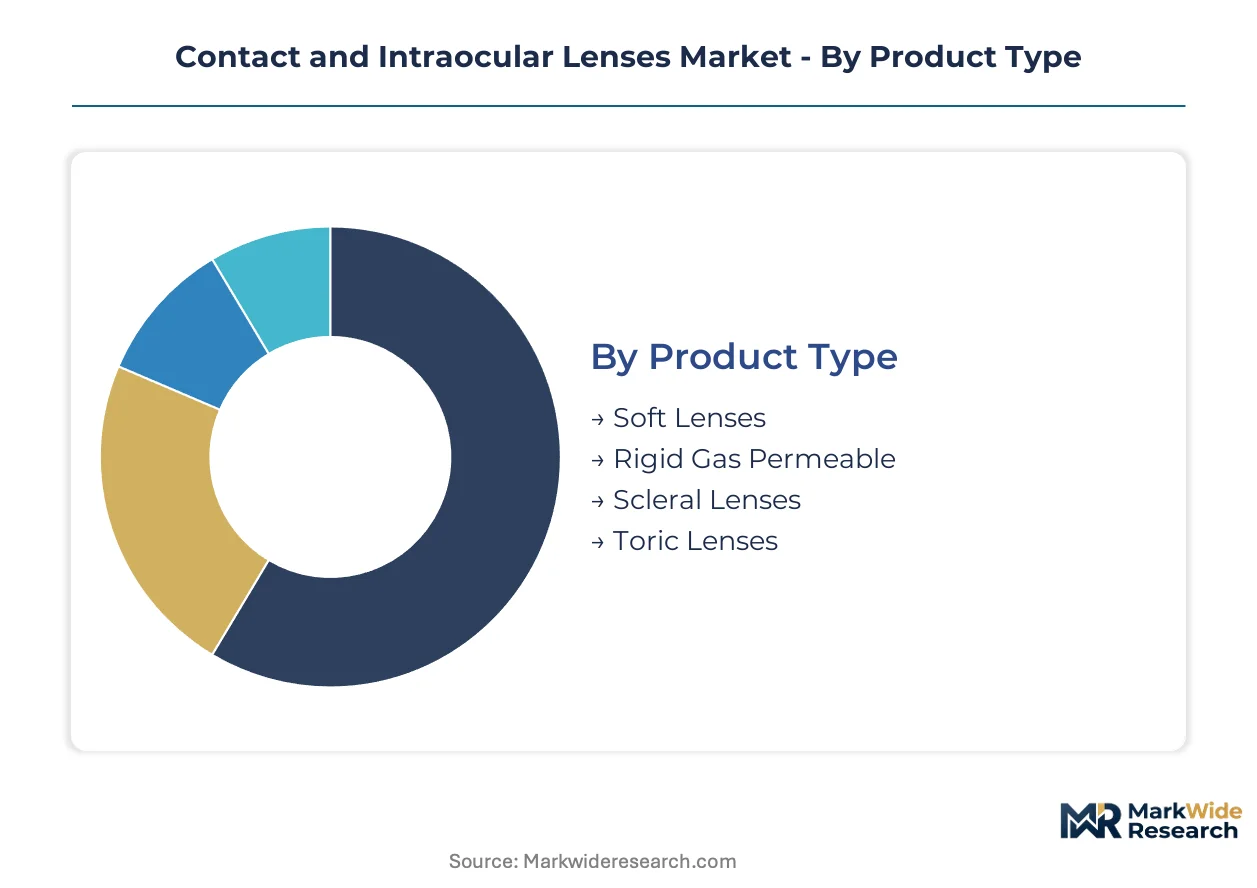
Segmentation in the contact and intraocular lenses market reveals how substitution pressures from refractive surgery and material science advances reshape competitive boundaries. Manufacturers must align R&D portfolios with the specific performance thresholds that separate commodity hydrogel positions from premium silicone hydrogel and specialty scleral niches.
Product Type:
Laser vision correction platforms pose the most acute substitution threat to standard spherical soft lenses among younger myopic populations, while irregular cornea conditions protect scleral and toric categories from surgical displacement.
- Soft Lenses:Silicone hydrogel formulations with oxygen permeability exceeding 100 Dk/t now dominate daily disposable and extended-wear schedules. United States retail optometry channels concentrate demand for monthly replacement modalities, though presbyopic demographics in Germany and Japan are accelerating multifocal soft lens adoption.
- Toric Lenses:Cylindrical correction designs address astigmatism through stabilization zones and prism ballast geometries. Hospital outpatient departments in the United States favor toric intraocular lens platforms for cataract procedures, where rotational stability directly determines visual outcomes.
- Scleral Lenses:Large-diameter rigid designs vault over the cornea to manage keratoconus and post-graft ectasia. Specialty contact lens practices retain pricing power in this underpenetrated segment.
- Rigid Gas Permeable:Fluorosilicone acrylate materials persist in orthokeratology and high-prescription corrections where soft lens optics prove inadequate. Manufacturing scale constraints limit volume expansion.
Soft lenses retain volume leadership across all geographies; scleral lenses hold the steepest expansion curve as irregular cornea diagnoses climb.
Application:
Cost tier stratification separates premium therapeutic indications from mass-market corrective volumes, with reimbursement differentials determining manufacturer margin exposure.
- Corrective:Myopia, hyperopia, and presbyopia corrections constitute the foundational revenue base. Silicone hydrogel daily disposables command the highest per-unit pricing in this category.
- Therapeutic:Bandage lens applications for corneal abrasions and post-refractive surgery healing require FDA 510(k) clearance with specific wear-time claims. Ambulatory surgical centers in the United States represent the concentrated demand node.
- Specialty:Prosthetic lenses for iris defects and cosmetic opaque designs serve ocular trauma and congenital anomaly populations. Low volumes sustain premium pricing.
- Cosmetic:Plano and prescription colored lenses face regulatory scrutiny under FDA medical device classification rather than cosmetic oversight. Distribution concentrates through online retail channels with limited professional fitting.
Corrective applications dominate absolute unit shipments; therapeutic indications are climbing fastest as post-surgical protocols standardize.
End User:
Customer type fragmentation creates channel conflict, with hospital procurement committees and retail optometry practices demanding incompatible contract structures and pricing transparency.
- Healthcare Providers:Ophthalmology practices and optometry clinics drive toric and multifocal fitting decisions through professional recommendation authority. United States Medicare reimbursement codes shape intraocular lens selection.
- Hospitals:Integrated delivery networks consolidate intraocular lens procurement through instrument-and-lens bundling agreements. Surgeon preference yields to facility contract terms in three-quarters of implant decisions.
- Consumer:Direct-to-patient channels for daily disposable lenses bypass professional fitting in some jurisdictions, triggering regulatory enforcement in Japan and the United States.
- Clinics:Independent ambulatory surgery centers form group purchasing organizations to match hospital contract leverage on intraocular lens pricing.
Healthcare providers anchor professional fitting volumes; hospitals capture the steepest value-per-procedure trajectory through premium intraocular lens adoption.
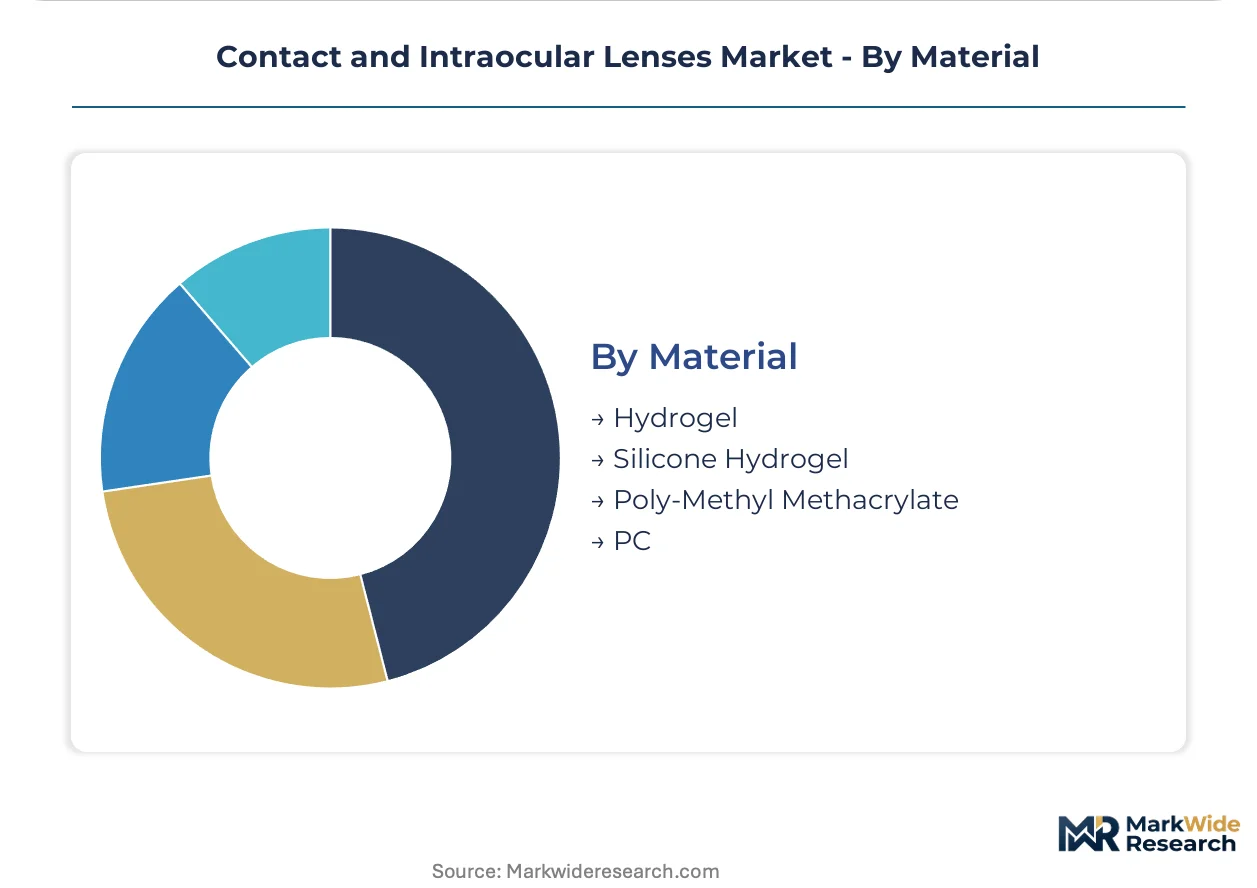
Material:
Supply concentration in silicone hydrogel monomer production is displacing conventional hydrogel positions, with petroleum feedstock volatility affecting acrylic intraocular lens cost structures.
- Silicone Hydrogel:Copolymer architectures combining silicone rubber with hydrophilic monomers achieve oxygen permeability coefficients above 100 Dk/t. Daily disposable production lines in the United States reward automated manufacturing scale.
- Hydrogel:Conventional poly-HEMA formulations retain share in emerging markets where extended wear parameters face less regulatory scrutiny. Margin compression accelerates as silicone hydrogel prices converge.
- Poly-Methyl Methacrylate:Rigid lens materials persist in scleral and specialty applications requiring dimensional stability. Limited new product development constrains growth.
- PC:Phosphorylcholine surface modifications reduce protein deposition and inflammatory response. Niche positioning in sensitive-eye segments.
Silicone hydrogel commands the dominant share of new product launches; PC surface technologies are expanding most quickly in allergy-prone patient populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket notification pathways anchor the United States as the decisive geography for premium intraocular lens commercialization, while Japan's PMDA and the EU Medical Device Regulation shape distinct compliance burdens across developed markets.
United States
Medicare reimbursement codes for toric and multifocal intraocular lenses drive hospital outpatient department adoption. FDA draft guidance on accommodating intraocular lenses reshapes premium category definitions for Medicare Administrative Contractors. The Rochester cluster in New York and the Research Triangle in North Carolina concentrate ophthalmic device manufacturing and surgeon training infrastructure.
Germany
Presbyopic demographics expand demand for multifocal corrections in Europe's largest aging population. The EU Medical Device Regulation imposes enhanced clinical evidence requirements that extend CE marking timelines for novel optical designs. The Mannheim-Heidelberg corridor hosts concentrated intraocular lens R&D and specialized ophthalmology clinic networks.
Japan
PMDA maintains distinct pharmaceutical affairs classification for contact lens care solutions that constrains bundling strategies. Silicone hydrogel daily disposable adoption accelerates among urban presbyopic populations. The Tokyo-Osaka corridor dominates both domestic manufacturing and specialized contact lens fitting practice density.
United Kingdom
Ophthalmic surgical fellowship capacity constraints limit procedural throughput regardless of patient need expansion. NHS procurement frameworks consolidate intraocular lens purchasing through instrument-and-lens bundling agreements. London and Manchester anchor specialized cornea and refractive surgery centers with concentrated scleral lens fitting expertise.
India
CDSCO medical device regulations govern contact lens and intraocular lens importation and local manufacturing licensing. Cost-sensitive demand for conventional hydrogel lenses persists alongside premium silicone hydrogel growth in metro centers. Mumbai and Bengaluru concentrate private ophthalmology hospital chains and domestic lens distribution networks.
Contact and Intraocular Lenses Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the contact and intraocular lenses market. Vertically integrated cataract surgical ecosystems compete against automated manufacturing scale players in daily disposable contact lenses. Three archetypes dominate: ophthalmic surgical platform bundlers, high-throughput disposable lens manufacturers, and dual-segment navigators managing retail-hospital channel conflicts. Consolidation through instrument-and-lens bundling agreements and automated production line expansion represent the dominant competitive moves.
Among United States-based healthcare conglomerates, Johnson & Johnson Vision Care, Inc. and Alcon Inc. occupy positions at opposite ends of the integration spectrum—one exemplifying automated manufacturing scale in daily disposables, the other representing surgical platform bundling. Bausch + Lomb Corporation anchors the dual-segment archetype, navigating channel conflicts between retail optometry and hospital procurement. These three structures illustrate how capital intensity and regulatory compliance capabilities separate sustainable positions from marginal competitors.
| Leading Market Players |
|---|
| Johnson & Johnson Vision Care, Inc. |
| Alcon Inc. |
| Bausch + Lomb Corporation |
| The Cooper Companies, Inc. |
| Carl Zeiss Meditec AG |
| HOYA Corporation |
| EssilorLuxottica SA |
| STAAR Surgical Company |
| Rayner Intraocular Lenses Limited |
| Others |
Supply Flow & Price Mechanics
Instrument-and-lens bundling agreements lock hospital purchasing committees into multi-year cataract surgical platform contracts that secure supply access while compressing price visibility for standalone intraocular lens competitors. Daily disposable contact lens manufacturers offset raw material volatility through automated production scale that fixes per-unit cost structures across extended procurement windows.
Pricing Analysis
United States hospital outpatient departments command 40-60% premiums over German ambulatory surgery centers for equivalent toric intraocular lens platforms, reflecting Medicare reimbursement code differentials and facility contract consolidation. Three-tier pricing structure across premium silicone hydrogel, standard hydrogel, and economy conventional lenses separates oxygen permeability tiers rather than brand positioning. Cost compression in conventional hydrogel segments is intensifying because silicone hydrogel manufacturing scale is converging price points downward. Retail optometry channels exhibit highest price sensitivity due to direct patient out-of-pocket exposure, while integrated delivery networks leverage volume aggregation for least sensitivity.
Supply Chain Analysis
Just-in-time inventory strategies dominate daily disposable contact lens production, with automated lines in the United States and Ireland maintaining sub-30-day raw material cycles to minimize silicone hydrogel monomer price exposure. Hydrophobic acrylic intraocular lens supply concentrates in the United States, Germany, and Japan, with each hub serving distinct regulatory certification clusters. Manufacturing rests on petroleum-derived monomer feedstocks, precision-molded optic polishing equipment, and sterilization validation infrastructure. Single-source vulnerability concentrates in silicone hydrogel monomer production, where three chemical suppliers serve the entire ophthalmic device sector. Distribution runs through hospital procurement committees for intraocular lenses and retail optometry chains for contact lenses, with limited direct-to-patient penetration due to fitting requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The contact and intraocular lenses market is recovering from surgeon training capacity constraints that suppressed procedural volumes through the early 2020s, with cyclical expansion now tied to presbyopic demographic waves in developed economies.
For Market Incumbents: Shield premium intraocular lens positioning by deepening backward integration into silicone hydrogel monomer production, locking in cost advantages against commodity hydrogel price convergence. Secure hospital system exclusivity through expanded instrument-and-lens bundling that raises switching costs for ambulatory surgery center competitors. Refractive surgery substitution for younger myopic populations threatens soft lens volume growth, requiring defensive multifocal portfolio investment. For New Entrants and Emerging Players: Lead with scleral lens specialization for keratoconus and post-graft ectasia management, where irregular cornea diagnosis rates are climbing fastest relative to fitting capacity. Target independent ambulatory surgery centers in the United States that lack group purchasing organization leverage against integrated delivery network contract terms. Pursue direct-to-specialist education models that bypass hospital procurement committee gatekeeping. For Investors and Strategic Acquirers: Capital is best deployed toward automated daily disposable manufacturing platforms with FDA 510(k) clearance runway and established Medicare Administrative Contractor reimbursement codes. Long-term viability across the 5-10 year window hinges on EU MDR compliance infrastructure and PMDA Japan marketing authorization capabilities. Monitor FDA draft guidance finalization on accommodating intraocular lenses as the signal for premium category reimbursement inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Extended-Wear Silicone Hydrogel | Clears pathway for Medicare reimbursement codes that drive hospital outpatient department adoption. |
| CE Marking Pathway Under EU MDR | Extended clinical evidence requirements favor manufacturers with robust trial infrastructure in Germany. |
| Hospital System Partnership for Bundled Procurement | Locks in instrument-and-lens agreements that override individual surgeon brand preference. |
| Software Companion Development for Accommodating IOLs | Supports FDA premium category definitions that reshape Medicare Administrative Contractor negotiations. |
| Reimbursement Strategy for Toric and Multifocal Platforms | Aligns product positioning with Medicare codes that determine per-procedure value capture. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with ophthalmic surgeons, hospital purchasing committee members, contact lens fitting optometrists, and biomedical engineers at intraocular lens manufacturing facilities. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR CE marking registries, CMS Medicare reimbursement code filings, and ISO 11979 biocompatibility certification records. Bottom-up unit demand modeling across silicone hydrogel, conventional hydrogel, and scleral lens categories was triangulated against top-down manufacturer revenue disclosures.
Across the analysis window, volume and value outputs reflect segmented modeling by product type, application, end user, material composition, and geographic regulatory cluster. CAGRs were derived from procedure volume trajectories, demographic presbyopia incidence curves, and premium intraocular lens adoption elasticity estimates. Forecast inputs incorporated ophthalmic surgical fellowship capacity constraints, refractive surgery platform substitution rates, and petroleum feedstock price volatility assumptions for acrylic monomer cost structures.
Underlying assumptions cover stable Medicare reimbursement code structures and EU MDR compliance timelines, with deviation risk concentrated in FDA draft guidance finalization schedules and surgeon training program expansion rates. Revision becomes warranted when accommodating intraocular lens reimbursement thresholds cross established premium category boundaries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Flow Cytometry Products Market
Medical Devices
Global Assistive Listening Device Market
Medical Devices
Ultrasonic Aspirator Market
Medical Devices
Drainage Catheters Market
Medical Devices
Global Abdominal Surgical Robot Market
Medical Devices
Middle East and Africa Surgical Equipment Market
Medical Devices
Canada Digital X-Ray Devices Market
Medical Devices
General Surgery Devices Market
Medical Devices
Indonesia Devices Market
Medical Devices
Global Voice Prosthesis Devices Market
Medical Devices
Digital Intraoral Sensors and Consumables Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
Global Blood Banking Devices Market
Medical Devices
Europe Ablation Technologies Market
Medical Devices
Patient Lift Slings Market
Medical Devices
Flexible Spinal Implants Market