
 Electrosurgery Accessories Market | 2026-2036
Electrosurgery Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Electrosurgery Accessories Market Analysis
Aftermarket service revenue for electrosurgical generator maintenance and electrode refurbishment is rewriting margin allocation across the value chain. Medtronic leverages its hospital contracting networks to sustain recurring revenue streams from disposable accessories. Erbe Elektromedizin GmbH anchors its position through deep specialization in bipolar technology and integrated system architectures. Johnson & Johnson competes via broad portfolio breadth spanning generators, forceps, and advanced energy platforms.
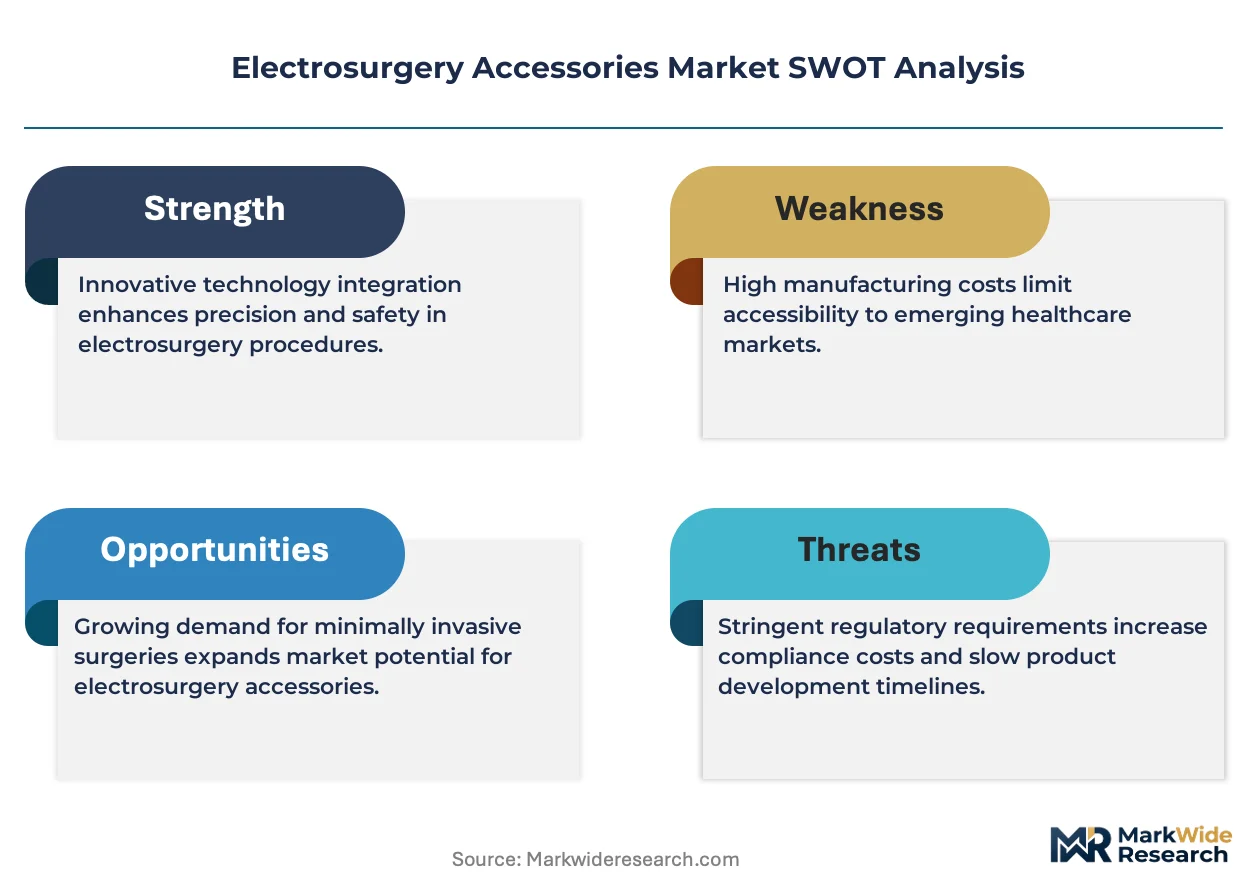
Electrosurgery accessories comprise consumable and reusable instruments that conduct high-frequency electrical current for tissue cutting and coagulation during surgical procedures, typically manufactured from conductive alloys with insulation ratings exceeding 5000 volts to ensure patient safety and surgeon precision. Electrosurgical generators and bipolar forceps command the largest installed base and replacement volume, while radiofrequency-based accessories lead technology adoption due to established clinical protocols and broad surgical applicability; microwave and ultrasonic modalities represent faster-growing niches where premium pricing reflects specialized tissue interaction profiles.
FDA 510(k) clearance requirements and EU MDR conformity assessments shape product development cycles, testing protocols, and market entry timelines for electrosurgery accessories across both jurisdictions. ISO 13485 quality management standards and IEC 60601 electrical safety specifications further constrain design choices and manufacturing documentation. Stakeholders must monitor evolving reimbursement codes for outpatient electrosurgical procedures and anticipate how ambulatory surgical center accreditation standards will reshape purchasing criteria for generator and electrode bundles.
Market Dynamics
Electrosurgery accessories face structural compression from ambulatory surgical center purchasing consolidation, where bundled generator-electrode contracts concentrate procurement power among fewer buyers and force manufacturers to absorb margin pressure through volume commitments.
Growth Catalysts
- Outpatient procedural migration:Ambulatory surgical centers in the United States are expanding electrosurgical service lines as CMS reimbursement codes favor same-day discharge protocols.
- EU MDR harmonization:Streamlined conformity assessment pathways under the Medical Device Regulation are accelerating cross-border market access for bipolar forceps manufacturers.
- Radiofrequency protocol standardization:Established clinical training curricula at American medical schools entrench radiofrequency-based accessories as default energy modalities in general surgery residencies.
Market Restraints
- Precious metal input volatility:Tungsten and silver alloy prices for electrode manufacturing fluctuate with mining supply disruptions in Chile and Peru.
- Generator OEM lock-in:Proprietary connector architectures from dominant equipment manufacturers create switching costs that fragment the replacement electrode aftermarket.
- Thermal spread limitations:Monopolar accessories face substitution pressure from advanced bipolar systems in precision neurosurgical applications.
Strategic Opportunities
- Refurbishment service models:Third-party reprocessing of bipolar forceps in Germany bypasses single-use premium pricing and captures ASC cost-conscious demand.
- Ultrasonic energy convergence:Hybrid platforms combining radiofrequency and ultrasonic modalities open gynecological and urological procedure expansion.
- Indian manufacturing zones:Special Economic Zones near Chennai and Hyderabad offer tariff advantages for export-oriented electrosurgical instrument production.
Industry Challenges
- Biocompatibility documentation:ISO 10993 testing requirements for novel polymer insulation layers extend FDA 510(k) submission preparation by eight to fourteen months.
- Legacy generator integration:Backward compatibility engineering for fifteen-year-old installed bases consumes R&D resources without corresponding revenue uplift.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrosurgery Accessories Market |
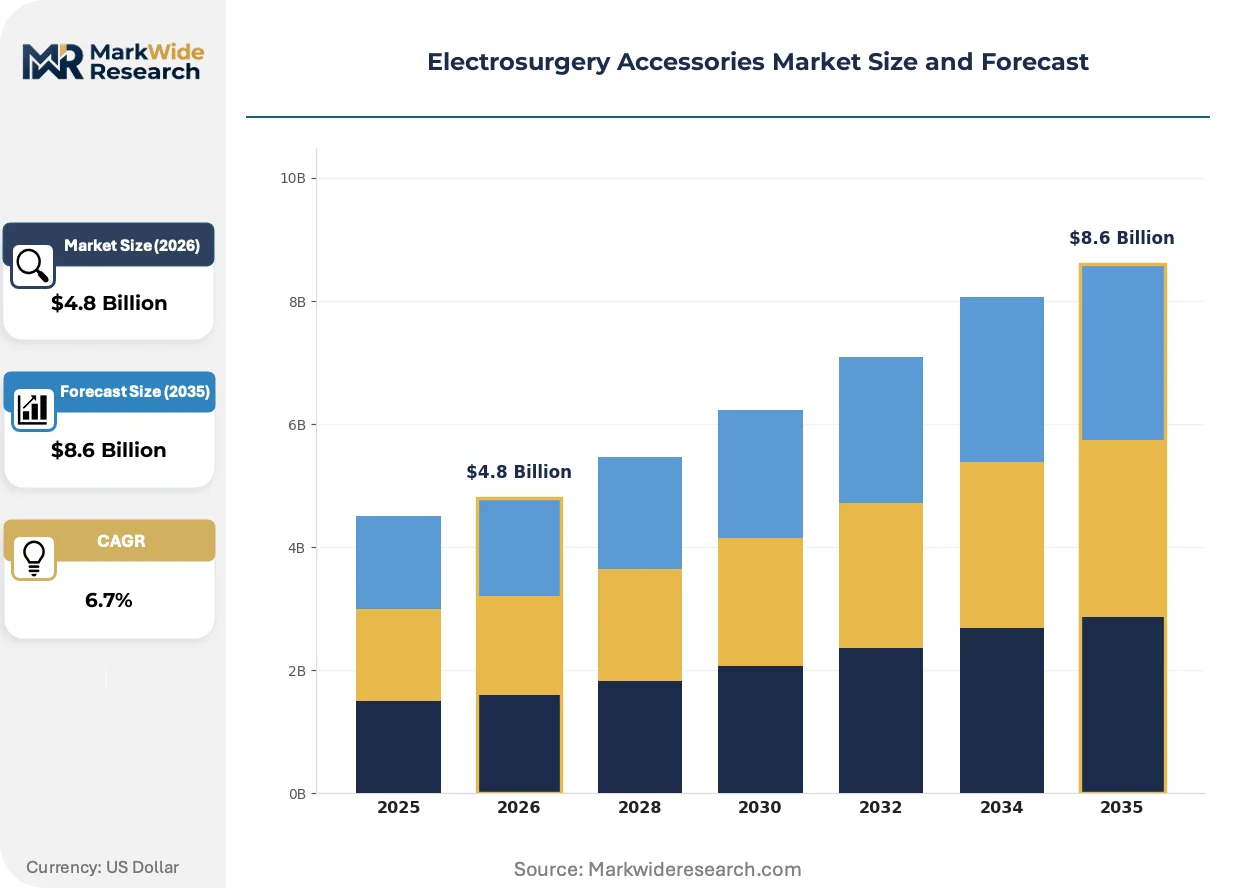
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrosurgical Generators, Electrosurgical Bipolar Forceps, Cutting Electrodes, Coagulation Electrodes End User: Hospitals, Ambulatory Surgical Centers, Clinics, Medical Research Facilities Application: General Surgery, Gynecological Surgery, Urological Surgery, Plastic Surgery Technology: Radiofrequency, Microwave, Laser, Ultrasonic |
| Companies Covered | B. Braun Melsungen AG, Erbe Elektromedizin GmbH, Medtronic, KLS Martin Group, Integra Lifesciences Holdings Corporation, Olympus Corporation, Johnson & Johnson, Bowa-Electronic GmbH & Co. Kg, Conmed Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrosurgery Accessories Market Emerging Trajectories
Active electrode monitoring technology and single-use instrument reprocessing protocols are compressing traditional replacement cycles while forcing manufacturers to defend position through software-integrated generator platforms rather than commodity hardware.
Smart bipolar forceps with embedded impedance sensors are collapsing the distinction between cutting and coagulation settings by enabling real-time tissue feedback loops. Academic medical centers in Boston and Heidelberg are piloting these systems in oncologic resections. The technology is collapsing training curves for junior surgeons and reducing thermal injury litigation exposure.
EU MDR Article 10 post-market surveillance requirements are mandating systematic clinical follow-up data collection for Class IIa electrosurgical accessories. Manufacturers must now maintain vigilance systems that track device performance across ten-year lifecycles. German notified bodies are interpreting these provisions most strictly, delaying certificates for bipolar instrument families.
Hospital purchasing cooperatives are consolidating electrosurgical accessory sourcing through prime vendor agreements that bundle electrodes with generators, drapes, and sutures. Independent distributors in the American Midwest are losing access to IDN accounts as these contracts centralize. The shift is most visible in Texas and Florida health systems where Catholic and for-profit chains dominate bed capacity.
Electrosurgery Accessories Market Segmentation
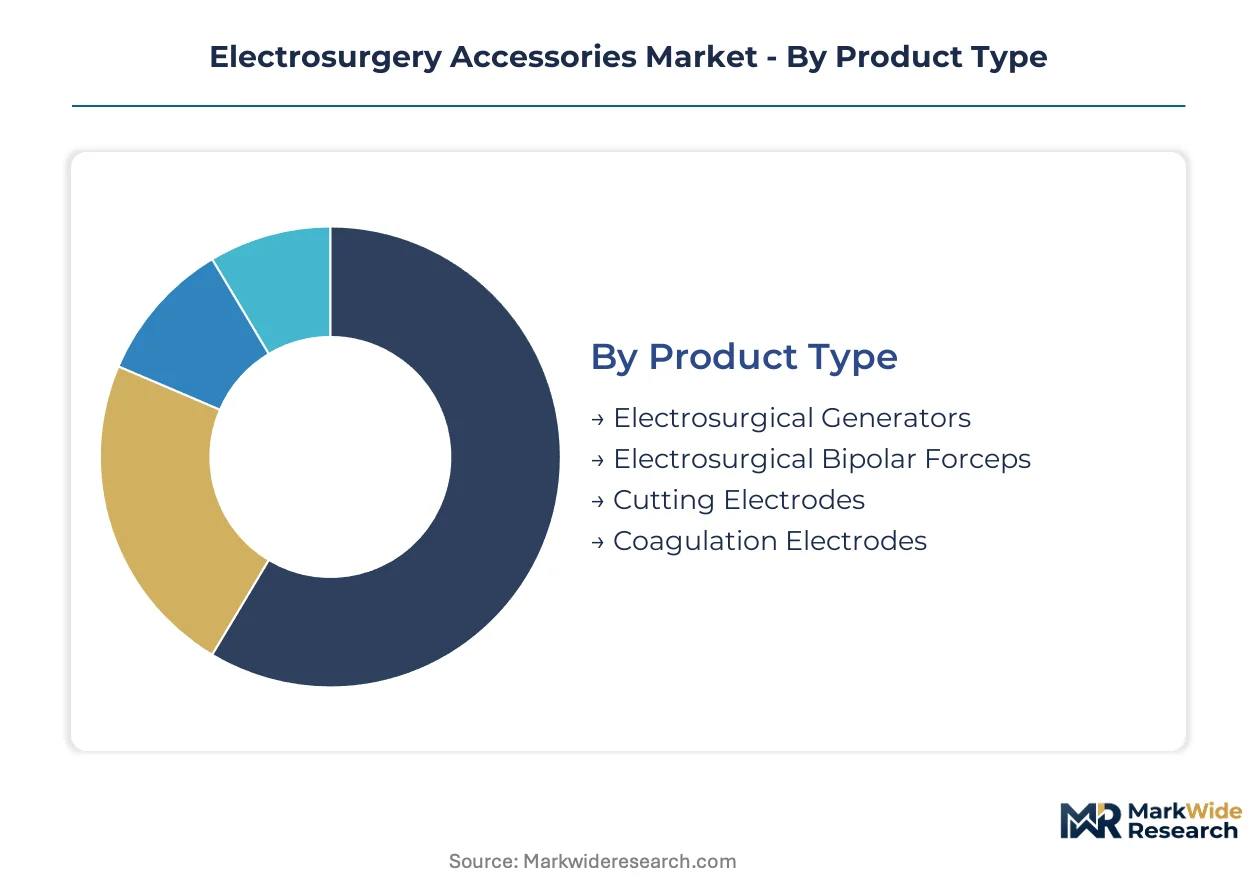
Segmentation in electrosurgery accessories reveals how procurement cycles, clinical workflows, and technology substitution patterns create distinct commercial rhythms across product categories. Understanding these temporal and structural differences enables manufacturers to align inventory, service, and R&D investments with actual replacement velocities.
Product Type:
Replacement cycles range from daily disposable electrodes to capital-intensive generators with decade-long amortization schedules.
- Electrosurgical Generators:Capital equipment with 7-12 year depreciation cycles. Demand concentrates in German university hospitals upgrading legacy analog units to software-integrated platforms with impedance feedback capabilities.
- Electrosurgical Bipolar Forceps:Semi-reusable instruments requiring 50-200 cycle refurbishment. Ambulatory surgical centers in the United States are accelerating adoption as outpatient procedural volumes shift toward same-day discharge protocols.
- Cutting Electrodes:Single-use tungsten alloy tips with standardized connectors. Procurement runs through generator OEM bundled contracts that fragment aftermarket competition.
- Coagulation Electrodes:Ball and needle configurations for hemostasis. Silver alloy variants face input cost volatility from Chilean mining supply disruptions.
Electrosurgical generators dominate installed base. Electrosurgical bipolar forceps is where expansion concentrates.
End User:
Procurement authority and volume scale diverge sharply between centralized hospital systems and fragmented clinic networks.
- Hospitals:Integrated delivery networks with capital budgets and prime vendor agreements. German tertiary centers anchor demand for advanced bipolar platforms with embedded sensors.
- Ambulatory Surgical Centers:Cost-conscious purchasers favoring reprocessing-compatible forceps and generator rental models. United States CMS reimbursement codes favoring same-day discharge are expanding site-of-service migration.
- Clinics:Low-volume purchasers dependent on distributor markup tiers.
- Medical Research Facilities:Niche demand for experimental energy modalities and prototype testing.
Hospitals retain capital expenditure authority. Ambulatory surgical centers are gaining share fastest in procedure volume.
Application:
Clinical specialization drives energy modality preferences and instrument specification requirements.
- General Surgery:High-volume abdominal procedures using standardized radiofrequency protocols. American medical school curricula entrench this modality as default training.
- Gynecological Surgery:Laparoscopic hysterectomies and endometrial ablations. Hybrid radiofrequency-ultrasonic platforms are opening procedure expansion.
- Urological Surgery:Transurethral resections with precise thermal control requirements. Microwave modalities compete for tissue vaporization applications.
- Plastic Surgery:Low-thermal-spread demands favoring fine-tip bipolar instruments.
General surgery commands procedure volume. Gynecological surgery is climbing the fastest in technology upgrade intensity.
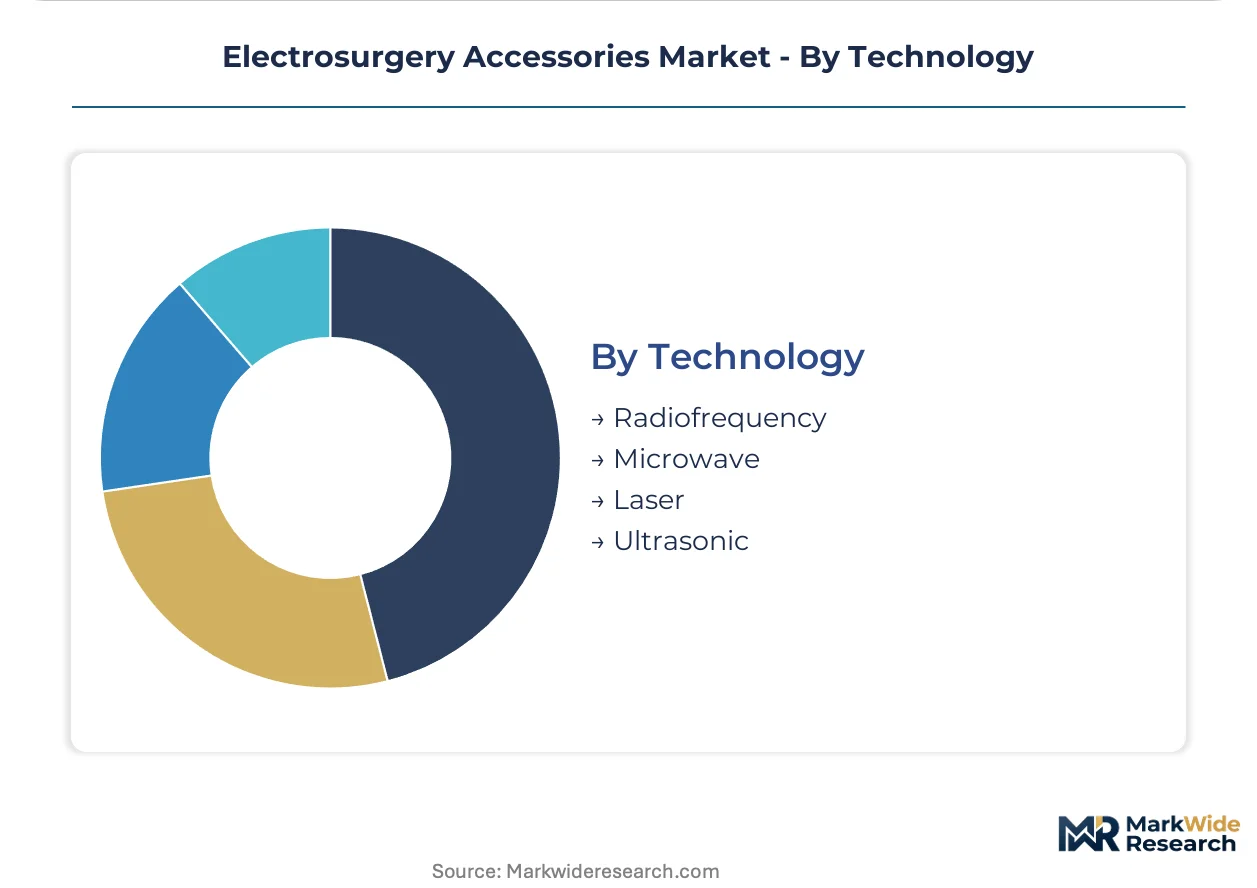
Technology:
Established radiofrequency protocols face displacement pressure from advanced energy platforms with superior tissue interaction profiles.
- Radiofrequency:Dominant modality with standardized training infrastructure and broad surgical applicability. IEC 60601 electrical safety specifications constrain design evolution.
- Microwave:Faster tissue heating with reduced thermal spread. Niche adoption in hepatic and urological ablation procedures commands premium pricing.
- Laser:Precision cutting in ophthalmic and dermatological applications with specialized safety protocols.
- Ultrasonic:Mechanical vibration cutting with simultaneous coagulation. Boston and Heidelberg academic centers pilot hybrid radiofrequency-ultrasonic systems in oncologic resections.
Radiofrequency anchors clinical training and installed base. Ultrasonic is gaining share fastest in premium procedure segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. German university hospitals absorb premium pricing for sensor-integrated platforms. Indian procurement offices at district hospitals reject equivalent specifications on cost grounds.
United States
Ambulatory surgical centers in Texas and Florida drive forceps volume as Catholic and for-profit chains consolidate bed capacity. CMS reimbursement codes favoring same-day discharge accelerate site-of-service migration. Boston academic medical centers pilot smart bipolar systems with embedded impedance sensors in oncologic resections.
Germany
Tübingen and Heidelberg anchor electrosurgery innovation clusters where Erbe Elektromedizin and KLS Martin maintain dense R&D presences. EU MDR Article 10 post-market surveillance requirements delay certificates for bipolar instrument families as German notified bodies interpret provisions strictly. Bavarian university hospitals upgrade legacy analog generators to software-integrated platforms.
India
Special Economic Zones near Chennai and Hyderabad attract export-oriented instrument production with tariff advantages. CDSCO regulatory pathways for Class IIa devices extend timelines for foreign manufacturers seeking import licenses. Maharashtra's Mumbai-Pune corridor hosts contract manufacturers serving Middle Eastern and African export markets.
Japan
PMDA quality management inspections enforce ISO 13485 documentation standards that filter out smaller foreign entrants. Tokyo and Osaka metropolitan hospitals maintain long depreciation cycles on electrosurgical generators, slowing replacement demand. METI industrial policy supports domestic precision alloy suppliers for electrode manufacturing.
China
NMPA medical device registration requirements for imported electrosurgical accessories intensify documentation burdens for European and American suppliers. Yangtze River Delta hospitals in Shanghai and Jiangsu province concentrate demand for radiofrequency-based systems. Domestic manufacturers in Shenzhen capture mid-tier generator segments through cost-engineered platforms.
Electrosurgery Accessories Market Vendor Landscape
Capability concentration sits with specialized German manufacturers; scale advantage sits with diversified American health conglomerates. The market structures around three tiers: integrated energy platform vendors, standalone accessory specialists, and regional contract manufacturers. Competitive moves center on generator-electrode bundling contracts and third-party reprocessing service expansion.
Among German-based specialists, Erbe Elektromedizin GmbH, KLS Martin Group, and Bowa-Electronic GmbH & Co. Kg exemplify the deep specialization archetype in bipolar technology and integrated system architectures. Medtronic and Johnson & Johnson occupy positions as diversified health conglomerates leveraging hospital contracting networks for recurring accessory revenue. Olympus Corporation represents the endoscopic-integrated energy platform segment where surgical visualization and electrosurgical delivery converge.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Erbe Elektromedizin GmbH |
| Medtronic |
| KLS Martin Group |
| Integra Lifesciences Holdings Corporation |
| Olympus Corporation |
| Johnson & Johnson |
| Bowa-Electronic GmbH & Co. Kg |
| Conmed Corporation |
| Others |
Supply Flow & Price Mechanics
Tübingen's electrosurgery manufacturing cluster concentrates precision instrument capacity, translating into asymmetric pricing power for German specialists serving American hospital systems. Bavarian producers leverage ISO 13485 certification density to command premium positioning against Asian contract manufacturers.
Pricing Analysis
Long-term generator-electrode bundled contracts dominate procurement, locking ambulatory surgical centers into multi-year volume commitments with Medtronic and Johnson & Johnson. Price differentiation hinges on FDA 510(k) clearance tier and after-sales service bundling. Cost compression in the mid-tier is intensifying as Indian contract manufacturers capture standard electrode segments. Ambulatory surgical centers exhibit highest price sensitivity; German university hospitals absorb premium sensor-integrated platforms without volume negotiation.
Supply Chain Analysis
Extended payment terms from American hospital purchasing cooperatives are squeezing working capital for European component suppliers. Manufacturing concentrates in Germany, the United States, and India. Tungsten and silver alloy electrodes draw from Chilean and Peruvian mining supply. Single-source vulnerability persists in precision polymer insulation from Japanese specialty chemical producers. Distribution runs through hospital prime vendor agreements and independent distributors serving clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR Article 10 post-market surveillance mandates are accelerating competitive disruption, forcing manufacturers to rebuild clinical evidence portfolios or exit Class IIa segments entirely.
For Market Incumbents: Insulate installed base revenue through backward integration into electrode refurbishment services, capturing ambulatory surgical center cost-conscious demand. Prioritize CE marking pathway acceleration with German notified bodies to preempt certificate delays for bipolar instrument families. Vertical integration into impedance sensor firmware development defends against ultrasonic modality substitution.
For New Entrants and Emerging Players: Establish a beachhead in Indian Special Economic Zone manufacturing for export-oriented standard electrode production. Target reprocessing-compatible bipolar forceps for American ambulatory surgical centers, where prime vendor agreement exclusion creates white-space access. Lead with generator rental-plus-service bundling to bypass OEM lock-in switching costs.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because generator-electrode bundling contracts concentrate procurement power among fewer buyers, advantaging scaled platform vendors over standalone accessory specialists. Monitor FDA 510(k) clearance velocity for smart bipolar systems as inflection indicator for technology substitution timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessments from German notified bodies gate European market access for bipolar forceps families. |
| Hospital System Partnership | Prime vendor agreements with Texas and Florida Catholic chains consolidate procurement authority for bundled generator-electrode contracts. |
| Software Companion Development | Impedance feedback algorithms embedded in smart bipolar forceps collapse training curves and reduce thermal injury litigation exposure. |
| Reimbursement Strategy | CMS code alignment for same-day discharge protocols accelerates ambulatory surgical center site-of-service migration. |
| FDA Submission | 510(k) clearance for active electrode monitoring technology compresses replacement cycles and defends aftermarket position. |
Methodological Framework
The analysis maps electrosurgical generators, bipolar forceps, cutting electrodes, and coagulation electrodes, each validated through hospital purchasing committee interviews, biomedical engineering directors, GPO contracts managers, and regulatory affairs leads at German manufacturers. Primary fieldwork combined with FDA 510(k) filings, EU MDR certificate databases, CMS reimbursement code updates, and hospital procurement transaction records. Bottom-up segment sizing triangulated against top-down equipment installed base estimates.
Assumptions held fixed include EU MDR enforcement intensity, CMS outpatient reimbursement parity, and radiofrequency protocol dominance in American surgical training curricula. Segmentation modeled across product type, end user procurement authority, application specialty, and energy modality technology. CAGRs derived from replacement cycle velocity analysis and procedural volume migration patterns. Forecast inputs incorporated tungsten price volatility indices and ambulatory surgical center accreditation expansion trajectories.
Sensitivities concentrate around EU MDR certificate delay severity, Chilean mining supply disruptions, and ultrasonic modality adoption acceleration in gynecological surgery. Forecasts reflect these documented assumptions. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Low Flux Single-Use Dialyzers Market
Medical Devices
Ultrasound Transducers Market
Medical Devices
Artificial Disc Replacement Market
Medical Devices
Digital Flexible Ureteroscopes Market
Medical Devices
Electric Massage Equipment Market
Medical Devices
Global Oxygen Cylinders and Concentrators Market
Medical Devices
Global Medical Device Contract Manufacturing Market
Medical Devices
Double-Lumen Biliary Catheters Market
Medical Devices
Global Digital Pathology Systems Market
Medical Devices
Interlaminar Device Market
Medical Devices
Skin Revitalizing Handheld Devices Market
Medical Devices
Sputum Ejection Machine Market
Medical Devices
Global Endovascular Aneurysm Repair Devices Market
Medical Devices
Embolic Protection Systems Market
Medical Devices
Telehealth Device Market
Medical Devices
Bone Power Tools Market