
 Carotid Artery Stents Market | 2026-2036
Carotid Artery Stents Market Size, Share, and Industry Trends Forecast 2026-2036
Carotid Artery Stents Market Intelligence
Hospital procurement consolidation is restructuring purchasing power across major health systems and shifting contract leverage toward integrated delivery networks. Boston Scientific Corporation leverages its broad interventional portfolio to sustain multi-year supply agreements with these consolidated buyers. Medtronic anchors its position through deep catheter and stent integration, while Abbott Laboratories differentiates via proprietary delivery system designs that reduce procedural complexity.
Carotid artery stents are cylindrical metallic or polymeric scaffolds deployed via catheter-based delivery to maintain luminal patency in the carotid bifurcation, typically manufactured from nitinol or cobalt-chromium alloys with strut thicknesses ranging from 0.003 to 0.006 inches to balance radial force and vessel conformability. Self-expanding stents dominate procedural volume due to superior conformability in tortuous anatomy, while drug-eluting stents command premium positioning where restenosis risk warrants pharmacological intervention. Coated stent technology occupies the fastest-growing technology segment as manufacturers integrate anti-thrombogenic surface treatments without systemic drug exposure.
FDA premarket approval pathways and the EU MDR framework impose escalating clinical evidence requirements that extend development timelines and elevate capital barriers for new market entrants. Japan's PMDA maintains distinct technical documentation standards that shape product registration strategies for manufacturers targeting the world's third-largest procedural market. Stakeholders must monitor evolving reimbursement thresholds for transcarotid artery revascularization versus transfemoral approaches, as coverage decisions will redirect volume across delivery method segments and reshape competitive positioning without regard to product specifications alone.
Market Dynamics
Hospital procurement consolidation is concentrating purchasing power within integrated delivery networks, forcing manufacturers to restructure pricing and contract terms around multi-year supply commitments rather than transactional volume discounts.
Growth Catalysts
- Aging demographics in procedural markets:Japan's super-aged population and Germany's demographic profile sustain elevated carotid artery disease prevalence that drives stent utilization in tertiary care centers.
- Transcarotid artery revascularization reimbursement:Expanded coverage decisions for TCAR procedures in United States Medicare frameworks redirect volume toward specialized stent configurations designed for direct cervical access.
- EU MDR clinical evidence requirements:Elevated standards for post-market surveillance and clinical performance documentation favor established manufacturers with robust trial infrastructure, consolidating competitive positioning.
Market Restraints
- Nitinol raw material concentration:Superelastic alloy supply chains concentrate in specialized metallurgical facilities, exposing stent manufacturers to input cost volatility and long-lead procurement cycles.
- FDA premarket approval timelines:Extended PMA pathway durations for novel stent designs delay commercialization by 18-36 months, compressing effective patent life and elevating capital recovery thresholds.
- Best medical therapy substitution:Intensive pharmacological management protocols in asymptomatic patient cohorts displace prophylactic stenting in select risk profiles, constraining addressable procedure volume.
Strategic Opportunities
- Coated stent technology expansion:Anti-thrombogenic surface treatments without systemic drug exposure capture fastest-growing segment positioning as physicians seek restenosis reduction without dual antiplatelet burden.
- Japan PMDA regulatory harmonization:Streamlined technical documentation pathways for devices with prior FDA approval reduce registration friction in the world's third-largest procedural market.
- Integrated delivery network direct contracting:Bypassing traditional distributor markups through direct hospital system agreements preserves margin structure while securing multi-year volume commitments.
Industry Challenges
- Interventional neuroradiologist training pipelines:Procedural complexity and specialized skill requirements create workforce bottlenecks that constrain volume expansion even where device availability exists.
- EU MDR notified body capacity:Certification backlog delays product recertification timelines, forcing inventory management adjustments and temporary market access suspensions for legacy device families.
- Real-world evidence generation infrastructure:Post-market clinical follow-up requirements demand substantial data collection investments that strain mid-tier manufacturer operational resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carotid Artery Stents Market |
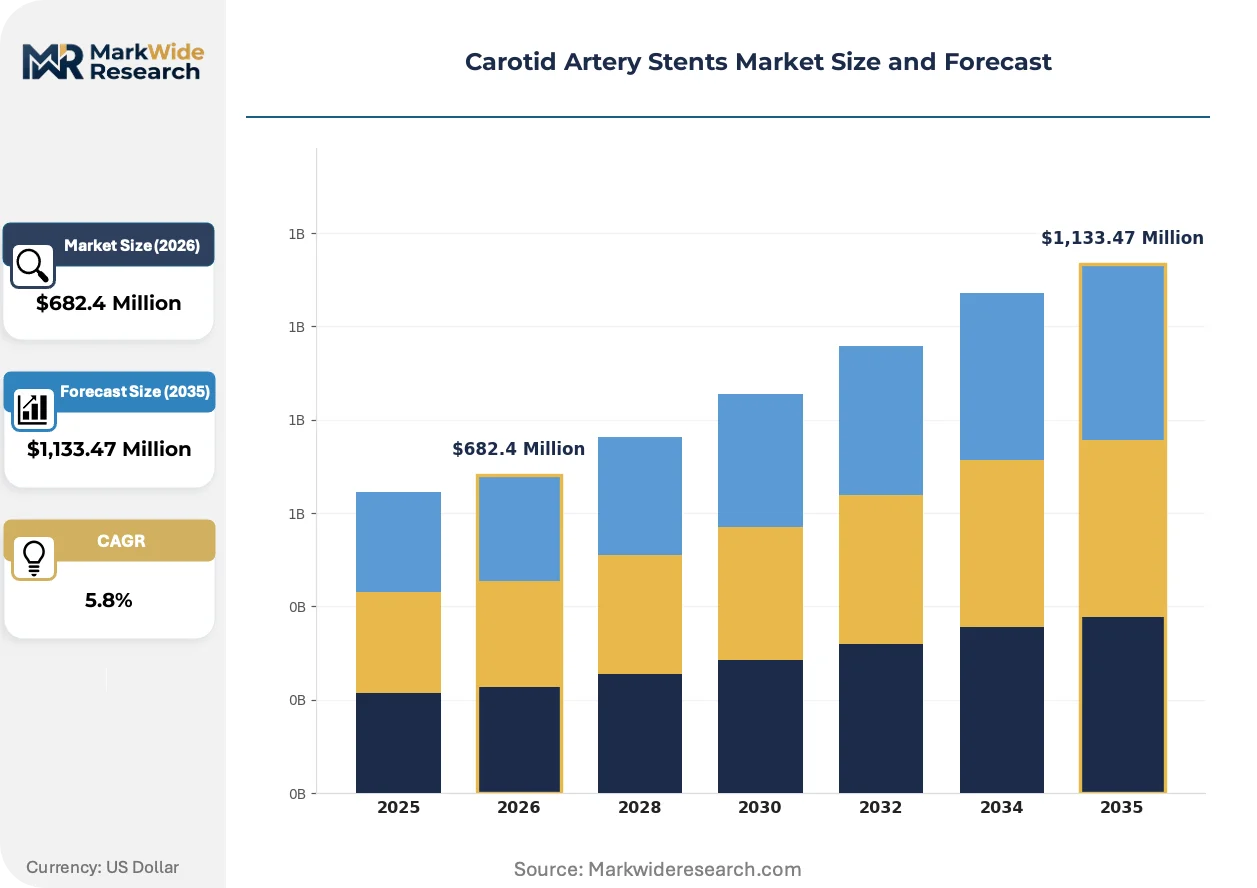
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $1,133.47 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon-Expandable Stents, Self-Expanding Stents, Covered Stents, Drug-Eluting Stents End User: Hospitals, Outpatient Clinics, Cardiology Centers, Surgical Centers Technology: Coated Stents, Metallic Stents, Hybrid Stents, Bioabsorbable Stents Delivery Method: Catheter-Based Delivery, Open Surgery, Percutaneous Intervention, Robotic-Assisted Delivery |
| Companies Covered | Boston Scientific Corporation, Cordis, Medtronic, Silk Road Medical Inc., Abbott Laboratories, Terumo Europe NV, InspireMD Inc., Balton, MicroPort Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carotid Artery Stents Market Strategic Shifts & Innovations
Device architecture and surface engineering are converging to reduce procedural complexity while regulatory frameworks on both sides of the Atlantic impose steeper evidence thresholds for market access.
Self-expanding nitinol stent platforms with closed-cell geometries are modularizing to accommodate physician preference for rapid exchange delivery systems and integrated embolic protection. Vascular surgeons in high-volume United States stroke centers are adopting these configurations at accelerating rates. This modularization is compressing development cycles for next-generation devices by enabling platform extensions rather than ground-up redesigns.
EU MDR post-market surveillance requirements are mandating systematic clinical follow-up registries that extend evidence obligations through product lifecycle. Manufacturers must now maintain active implant tracking infrastructure that was previously voluntary. The burden falls most heavily on cobalt-chromium alloy stent portfolios where long-term durability data remains undercollected.
Integrated delivery networks are consolidating purchasing decisions at system level rather than individual hospital cath lab autonomy. United States health systems with 15-plus hospital footprints now centralize interventional cardiology and vascular surgery procurement through value analysis committees. This concentration is visible most acutely in the Southeast and Midwest regions where regional system mergers have accelerated since 2022.
Carotid Artery Stents Market Segmentation
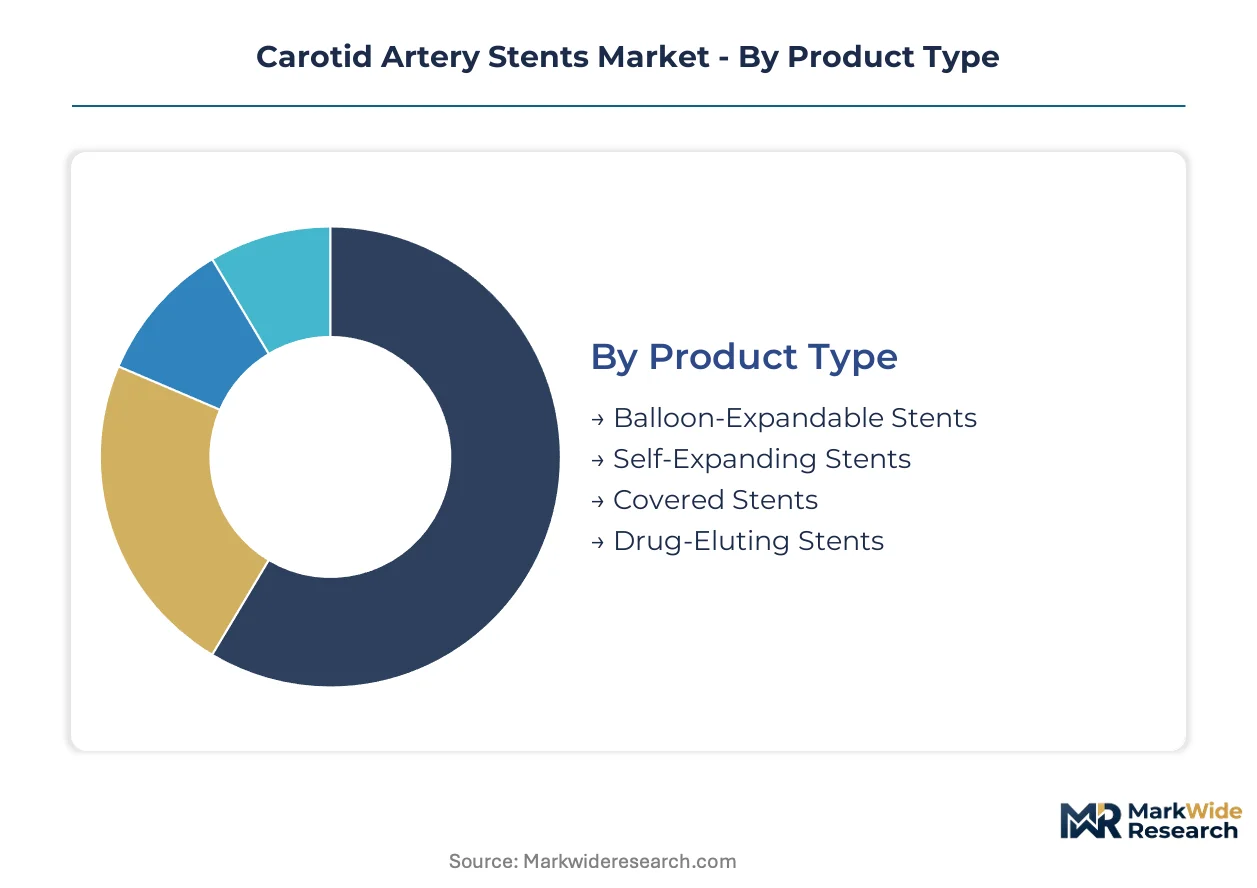
Carotid artery stent segmentation reveals how procedural complexity, reimbursement pathways, and anatomical constraints fragment demand across distinct technical configurations. Each category reflects divergent clinical priorities: radial force requirements, access site preferences, and antiplatelet management protocols.
Product Type:
Physician training backgrounds and lesion characteristics determine stent platform selection, with vascular surgeons and interventional neuroradiologists diverging on conformability versus precision deployment priorities.
- Self-Expanding Stents:Manufactured from superelastic nitinol alloys with closed-cell geometries, these devices deploy via sheath retraction without balloon inflation. Demand concentrates in United States tertiary stroke centers where tortuous carotid bifurcation anatomy requires superior vessel wall conformability. The transcarotid artery revascularization surge favors these platforms for direct cervical access procedures.
- Drug-Eluting Stents:Polymer matrices encapsulate antiproliferative agents on metallic scaffolds to inhibit neointimal hyperplasia. Japan's super-aged patient cohorts with high restenosis risk drive utilization in Tokyo and Osaka academic medical centers where dual antiplatelet compliance can be monitored.
- Balloon-Expandable Stents:Cobalt-chromium platforms deliver precise diameter control via inflation-mediated deployment. Reserved for calcified lesions requiring high radial force.
- Covered Stents:Expanded polytetrafluoroethylene membranes encapsulate metallic frameworks to exclude embolic debris. Deployed in complex lesions with ulcerated plaque characteristics.
Self-expanding stents lead volumes today; drug-eluting platforms are gaining share fastest.
End User:
Reimbursement differentials and capital equipment requirements stratify purchasing authority across facility types, with integrated delivery networks centralizing procurement for hospital-based interventions.
- Hospitals:Comprehensive stroke centers with 24/7 neurointerventional coverage dominate complex carotid interventions. United States Medicare reimbursement frameworks favor inpatient settings for TCAR procedures, concentrating volume in Southeast and Midwest health systems with consolidated cath lab networks.
- Cardiology Centers:Specialized facilities with dedicated vascular surgery programs offer streamlined preoperative workup and postoperative surveillance. Germany's outpatient cardiology infrastructure supports same-day discharge protocols that reduce systemic cost burden.
- Outpatient Clinics:Limited to diagnostic angiography and medical management; stent deployment requires hospital transfer capabilities.
- Surgical Centers:Ambulatory settings capture select low-risk transfemoral cases where overnight observation protocols apply.
Hospitals capture the majority of procedural revenue; cardiology centers are expanding capacity most aggressively.
Technology:
Surface engineering investments and biocompatibility research are redirecting R&D expenditure toward configurations that minimize thrombogenicity without systemic pharmacological burden.
- Coated Stents:Anti-thrombogenic surface treatments—heparin bonding, phosphorylcholine layers, or nitric oxide-releasing polymers—reduce platelet adhesion without drug elution. United States physicians in high-volume stroke centers prefer these for patients with bleeding risk contraindicating extended dual antiplatelet therapy.
- Metallic Stents:Bare nitinol or cobalt-chromium scaffolds without surface modification remain the cost-efficient default for standard-risk anatomies. Germany's statutory health insurance reimbursement thresholds favor these platforms in budget-constrained hospital procurement.
- Hybrid Stents:Combine metallic structural elements with selective surface modifications in modular architectures.
- Bioabsorbable Stents:Magnesium or polymeric scaffolds designed for complete resorption after luminal remodeling; limited commercial availability pending long-term durability data.
Metallic stents dominate installed base; coated platforms are climbing the fastest.
Delivery Method:
Access site selection imposes distinct stent design requirements on delivery system flexibility, sheath diameter, and embolic protection integration.
- Catheter-Based Delivery:Transfemoral or transradial approaches utilizing 6-8 French delivery sheaths with integrated embolic protection devices. Japan's PMDA technical documentation standards have shaped catheter design specifications for the Asian procedural market, with Tokyo manufacturers pioneering low-profile systems.
- Percutaneous Intervention:Minimally invasive access with ultrasound-guided puncture and closure device deployment. United States TCAR reimbursement expansion is redirecting volume toward direct cervical access that bypasses aortic arch navigation.
- Open Surgery:Surgical cutdown with direct carotid exposure for stent placement; reserved for anatomical failures of endovascular approaches.
- Robotic-Assisted Delivery:Telemanipulation platforms for remote catheter control; investigational status with limited commercial penetration.
Catheter-based delivery maintains volume leadership; percutaneous intervention is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Interventional neuroradiologist density in tertiary stroke centers anchors procedural volume distribution across major markets. Training pipeline capacity and reimbursement clarity determine where stent utilization expands fastest.
United States
Medicare coverage expansion for transcarotid artery revascularization procedures redirects volume toward specialized stent configurations. The FDA maintains stringent premarket approval pathways that extend development timelines for novel device designs. Southeast and Midwest health systems with consolidated 15-plus hospital footprints now centralize procurement through value analysis committees.
Germany
Statutory health insurance reimbursement thresholds favor cost-efficient bare metal stent platforms in budget-constrained hospital procurement. The EU MDR framework imposes escalating clinical evidence requirements that favor established manufacturers with robust trial infrastructure. Bavaria and North Rhine-Westphalia host the highest concentration of comprehensive stroke centers performing carotid interventions.
Japan
Super-aged demographics sustain elevated carotid artery disease prevalence that drives stent utilization in Tokyo and Osaka academic medical centers. PMDA maintains distinct technical documentation standards that shape product registration strategies for manufacturers. Kanto and Kansai regions concentrate the nation's interventional neuroradiologist workforce and tertiary care capacity.
United Kingdom
NICE technology appraisal processes influence stent adoption thresholds across NHS trusts. MHRA post-Brexit regulatory pathways diverge from EU MDR timelines, creating parallel compliance obligations for manufacturers. London and Southeast England concentrate specialized stroke services with 24/7 neurointerventional coverage.
China
NMPA innovation pathway accelerates review for domestically manufactured stent platforms with demonstrated clinical equivalence. Volume-based procurement reforms compress pricing for metallic stent categories while encouraging coated technology differentiation. Yangtze River Delta and Pearl River Delta clusters drive domestic manufacturing scale and catheter-based delivery system innovation.
Carotid Artery Stents Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidated purchasing power within integrated delivery networks forces manufacturers to restructure pricing around multi-year supply commitments. Three archetypes dominate: broad interventional portfolio holders, integrated catheter-stent platform developers, and proprietary delivery system innovators. Competitive moves center on direct hospital system contracting and modular platform extensions that compress development cycles.
Among diversified medical technology conglomerates, Boston Scientific Corporation and Medtronic exemplify portfolio breadth strategies, while Abbott Laboratories occupies a position emphasizing proprietary delivery system architectures. These three anchors represent distinct approaches to sustaining contract leverage with consolidated buyers.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Cordis |
| Medtronic |
| Silk Road Medical Inc. |
| Abbott Laboratories |
| Terumo Europe NV |
| InspireMD Inc. |
| Balton |
| MicroPort Scientific Corporation |
| Others |
Cost & Logistics Intelligence
Captive nitinol alloy production anchors supply positioning and pricing power for established stent manufacturers, with in-house metallurgical capabilities insulating against raw material volatility while enabling premium positioning for specialized geometries. Hospital procurement consolidation reinforces this dynamic by concentrating volume commitments around suppliers with demonstrated supply security.
Pricing Analysis
Capacity additions in China's NMPA-certified manufacturing facilities are reshaping price floors for bare metal stent categories. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA PMA status and dual antiplatelet burden reduction claims. Cost compression in metallic stent tiers is intensifying because volume-based procurement reforms in Asia redirect margin pressure upstream. Integrated delivery networks exhibit lowest price sensitivity; outpatient surgical centers face acute budget constraints.
Supply Chain Analysis
Nitinol supply rests on specialized metallurgical facilities in the United States, Germany, and Japan with superelastic alloy drawing capabilities. Raw material inputs draw from nickel-titanium ingot producers, precision laser-cutting equipment, and surface coating chemical suppliers. Single-source vulnerability concentrates in superelastic wire drawing capacity for sub-0.004 inch strut specifications. Distribution runs through GPO contracts and direct hospital system agreements with limited distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carotid artery stents market operates as a regulatory compounder where EU MDR post-market surveillance mandates accelerate replacement cycles for legacy device families and sustain demand for clinical evidence infrastructure.
For Market Incumbents: Deploy modular platform extensions to compress development cycles for next-generation delivery systems. Deepen catheter-stent integration to defend against pure-play specialists with proprietary embolic protection configurations. Capture multi-year IDN commitments before reimbursement thresholds harden for transcarotid approaches. For New Entrants and Emerging Players: Enter via coated stent technology segments where anti-thrombogenic surface treatments command premium positioning without systemic drug exposure. Target Japan's PMDA harmonization pathway for streamlined registration of FDA-cleared devices. Pursue direct contracting with regional stroke center networks bypassing established GPO relationships. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier manufacturers with EU MDR trial infrastructure because notified body capacity constraints prevent rapid competitive replication. Five-to-ten year viability hinges on post-market surveillance data ownership. Watch TCAR reimbursement expansion rates as volume inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements favor manufacturers with established PMCF registries. |
| Hospital System Partnership | Direct IDN agreements bypass distributor markups and secure multi-year volume commitments. |
| Reimbursement Strategy | Medicare coverage expansion for TCAR procedures redirects demand toward cervical access configurations. |
| Software Companion Development | Integrated imaging and planning tools reduce procedural complexity in tortuous anatomy cases. |
| Regulatory Harmonization | PMDA streamlined pathways for FDA-approved devices reduce registration friction in Japan. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with vascular surgeons, interventional neuroradiologists, hospital purchasing committee members, and GPO contracts managers with secondary validation against FDA PMA filings, EU MDR notified body certificates, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up procedure volume estimates and top-down manufacturer revenue analysis provided triangulation anchors.
Comparable historical periods anchored the projection horizon to capture cyclical reimbursement and regulatory cadences across the modeling period. Segmentation dimensions modeled include stent platform type, surface technology category, delivery method configuration, and facility reimbursement tier. CAGRs derived from fitted growth curves applied to procedural volume trajectories, with nitinol raw material cost indices and interventionalist workforce pipeline data informing elasticity assumptions.
Inputs from regulatory filings and hospital procurement databases were available through the study window; gaps in real-world clinical outcome registries introduce uncertainty bands around restenosis rate assumptions. Forecasts reflect documented assumptions regarding reimbursement stability and MDR implementation timelines. A small set of triggers—TCAR coverage expansion velocity, notified body capacity constraints, and nitinol supply concentration events—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Inhaled Nitric Oxide (NO) Delivery Systems Market
Medical Devices
Handheld Red Light Therapy Device Market
Medical Devices
Radiolucent Wrist Fixator Market
Medical Devices
Inversion Table Market
Medical Devices
Global Hernia Repair Devices and Consumables Market
Medical Devices
Digital Vision Lenses Market
Medical Devices
Global Wearable Healthcare Devices Market
Medical Devices
Sweden Ophthalmic Devices Market
Medical Devices
Atrial Fibrillation Devices Market
Medical Devices
Insulin Storage Devices Market
Medical Devices
Global Auto-Injectors Market
Medical Devices
Vascular Boot Market
Medical Devices
Implantable Neurostimulators Market
Medical Devices
Autosamplers Market
Medical Devices
Below-The-Knee Implants Market
Medical Devices
Depression Devices Market