
 Healthcare Data Integration Market | 2026-2036
Healthcare Data Integration Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Data Integration Market Analytics
Subscription-based platform licensing and pay-per-integration pricing is reconfiguring capital requirements for healthcare IT vendors, allowing mid-tier health systems to access enterprise-grade data fabrics without heavy upfront infrastructure spend. Epic Systems leverages its dominant position in acute care EHR installations to anchor proprietary integration networks across US hospital networks. Oracle Health sustains competitive relevance through cloud-native infrastructure investments that extend interoperability tools beyond legacy Cerner footprints. Innovaccer specializes in FHIR-based data activation platforms that compete directly with incumbent middleware stacks by offering faster implementation timelines for clinically integrated networks.
Healthcare data integration encompasses the technical processes, protocols, and platform architectures that normalize, transform, and exchange structured and unstructured clinical, operational, and financial information across disparate health information systems, typically employing HL7 FHIR R4 APIs, XML-based messaging, and real-time event streaming at sub-second latency thresholds to enable care coordination, population health analytics, and regulatory reporting. Cloud-based Solutions now lead technology adoption as health systems migrate from on-premises data warehouses to elastic compute environments that reduce total cost of ownership for multi-source analytics. API architectures represent the fastest-growing technology segment, displacing legacy middleware in new procurements due to modular deployment and vendor-agnostic connectivity. Research and Development applications command premium pricing within the application dimension, driven by pharmaceutical and academic medical center demand for regulatory-grade data pipelines that support trial recruitment and real-world evidence generation.
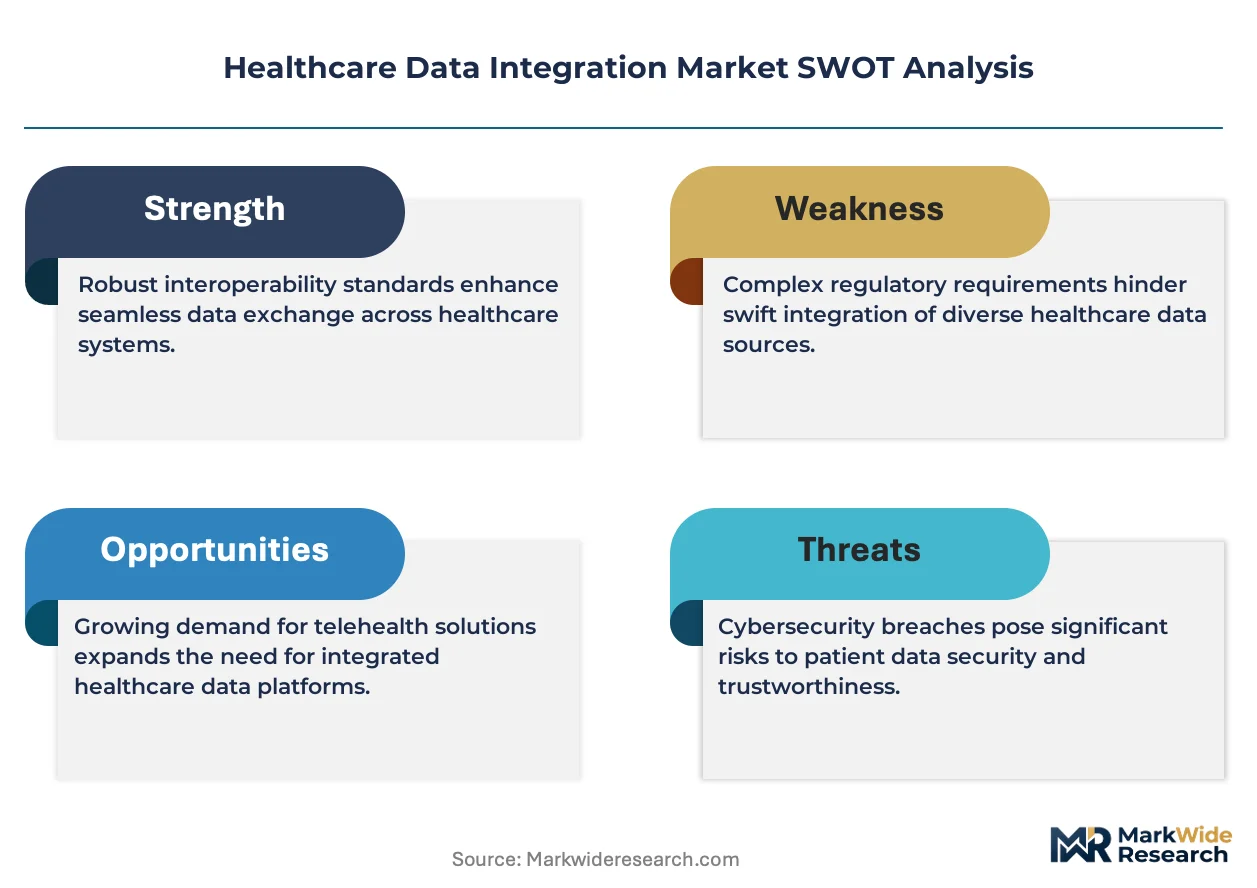
The Office of the National Coordinator for Health Information Technology enforces interoperability rules under the 21st Century Cures Act that mandate standardized API access, directly shaping vendor product roadmaps and creating compliance-driven replacement cycles for closed-system architectures. FDA guidance on real-world evidence data standards further tightens requirements for traceable, auditable data lineage in platforms serving life sciences customers. HIPAA security rule enforcement by the Department of Health and Human Services elevates procurement scrutiny around encryption protocols and access controls, particularly for hybrid cloud deployments spanning hospital and vendor environments. Stakeholders must monitor how pending federal rules on algorithmic transparency and artificial intelligence validation reshape data governance requirements for platforms supporting clinical decision support.
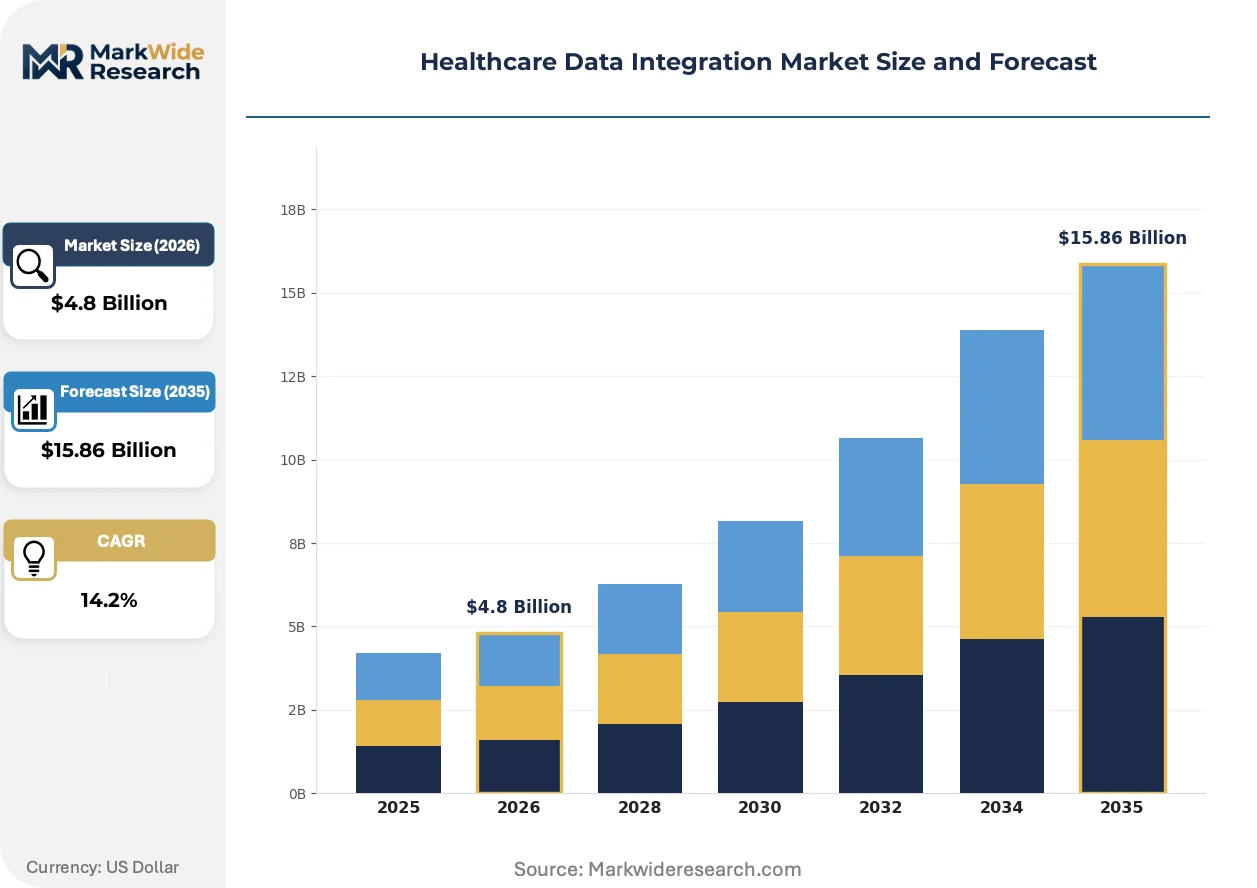
Market Dynamics
FHIR R4 API standardization is compressing procurement cycles and forcing legacy middleware vendors into accelerated replacement roadmaps as health systems demand sub-second latency for clinical data exchange.
Growth Catalysts
- US 21st Century Cures Act:ONC interoperability rules mandate standardized API access, creating compliance-driven replacement demand for closed-system architectures across acute care networks.
- Real-world evidence pipelines:Pharmaceutical sponsors and academic medical centers require regulatory-grade data lineage for trial recruitment, commanding premium platform pricing.
- Cloud infrastructure maturation:Elastic compute environments reduce total cost of ownership for multi-source analytics, enabling mid-tier health systems to deploy enterprise-grade data fabrics.
Market Restraints
- Legacy system entrenchment:Proprietary EHR networks anchor hospital data flows, creating switching costs that delay API-first platform adoption despite regulatory pressure.
- Hybrid cloud security complexity:HIPAA security rule enforcement elevates procurement scrutiny around encryption protocols for deployments spanning hospital and vendor environments.
- Specialized talent scarcity:Health informaticists with dual expertise in clinical workflows and FHIR implementation command compensation premiums that inflate implementation timelines.
Strategic Opportunities
- Clinically integrated networks:Faster implementation timelines for data activation platforms create white space against incumbent middleware stacks in regional hospital alliances.
- AI governance preparation:Pending federal rules on algorithmic transparency reshape data governance requirements, positioning platforms with built-in audit trails for clinical decision support contracts.
- Subscription pricing penetration:Pay-per-integration models allow smaller health systems to access capabilities previously reserved for capital-rich IDNs, expanding addressable market.
Industry Challenges
- Unstructured data normalization:Clinical notes, imaging metadata, and operational logs require specialized NLP pipelines that extend implementation timelines and inflate professional services costs.
- Cross-vendor certification lag:Multiple proprietary interpretations of FHIR R4 create integration testing burdens that delay production deployment despite standardization mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Data Integration Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: API, Middleware, Cloud-based Solutions, On-premises Solutions Application: Clinical Data Management, Patient Care Management, Research and Development, Financial Management End User: Hospitals, Clinics, Laboratories, Payors Deployment Model: Private Cloud, Public Cloud, Hybrid Cloud, On-premises |
| Companies Covered | InterSystems, Redox, Innovaccer, Oracle Health, Cerner, Epic Systems, Allscripts Healthcare Solutions, Optum, Health Catalyst, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Data Integration Market Evolving Landscape
Healthcare data integration is experiencing architectural compression as real-time event streaming displaces batch processing, regulatory mandates force API modularity, and buyer procurement models favor operational expenditure over capital deployment.
Real-time event streaming architectures are migrating from niche pilot deployments to standard procurement specifications for enterprise data fabrics. Large integrated delivery networks now require sub-second latency for clinical decision support triggers. This compression is migrating from technical differentiator to table-stakes requirement, forcing legacy middleware vendors into expensive platform rebuilds or partnership strategies.
US ONC enforcement of information blocking provisions under the 21st Century Cures Act is reshaping vendor product roadmaps toward open API architectures. Closed-system EHR extensions face compliance-driven replacement cycles as health systems preempt penalty exposure. Acute care networks with concentrated proprietary installations are most affected, accelerating RFP activity for vendor-agnostic connectivity layers.
Buyer preference for subscription-based platform licensing is restructuring vendor cash flow patterns and implementation risk allocation. Health systems increasingly demand outcome-aligned pricing tied to documented workflow efficiency gains or administrative burden reduction. This shift is most visible in North American markets where federal incentive programs have conditioned CFOs to favor operational expenditure treatment for health IT investments.
Healthcare Data Integration Market Segmentation
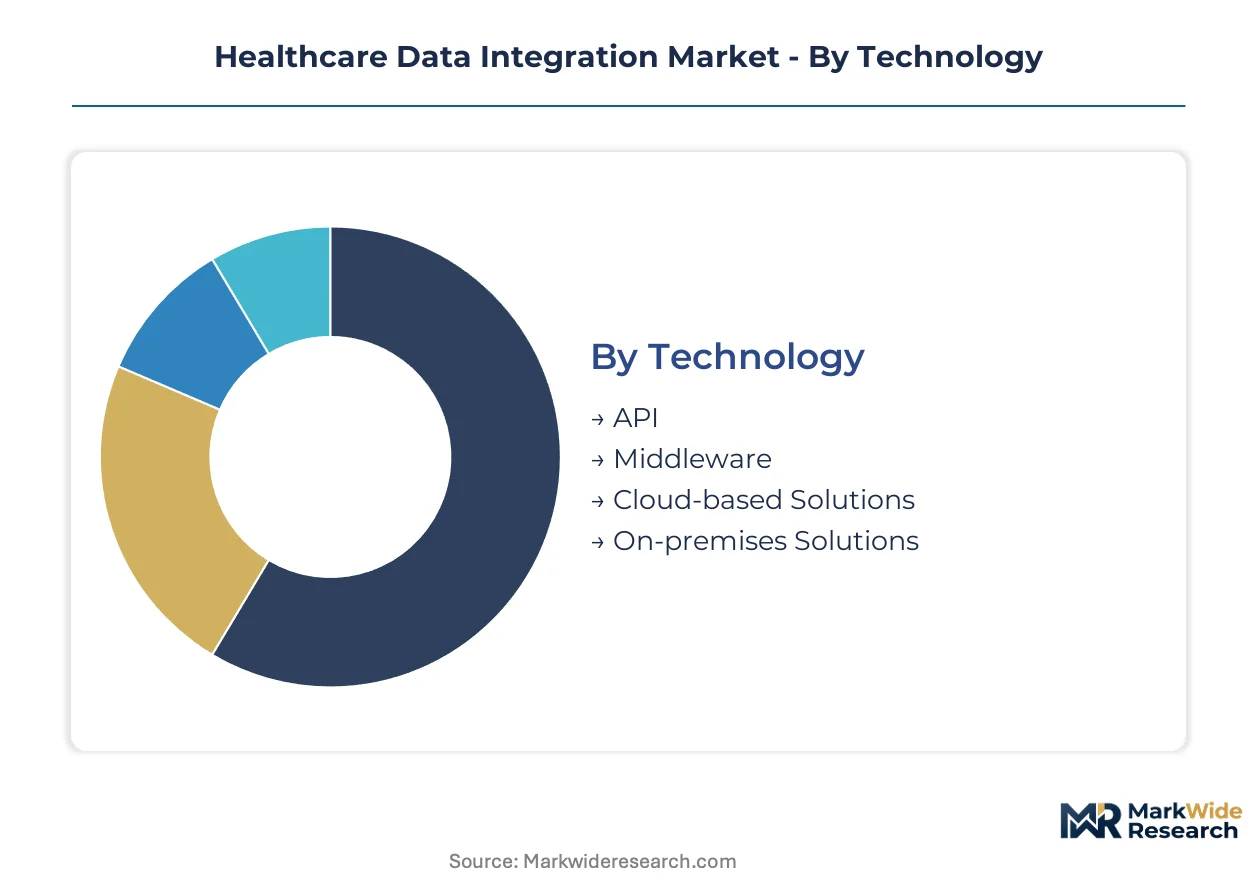
Healthcare data integration platforms fragment across technology architectures, clinical applications, and deployment topologies that determine interoperability depth and total cost of ownership. Understanding segment boundaries clarifies procurement trade-offs between latency performance, regulatory compliance, and capital efficiency for health system technology committees.
Technology:
Technology selection governs implementation timelines and vendor lock-in exposure for health system IT departments evaluating connectivity infrastructure.
- API:RESTful and FHIR R4 interfaces enable modular, vendor-agnostic data exchange with sub-second latency for clinical decision support triggers. Demand concentrates in US acute care networks modernizing under ONC interoperability mandates, where compliance deadlines accelerate replacement of proprietary interfaces.
- Cloud-based Solutions:Elastic compute environments with managed Kubernetes orchestration reduce infrastructure overhead for multi-source analytics pipelines. US health systems with mature cloud procurement policies favor these platforms for population health management workloads requiring variable compute scaling.
- Middleware:Legacy message brokers and enterprise service buses persist in entrenched EHR ecosystems where migration costs delay API-first transitions. These installations anchor data flows in hospital networks with concentrated proprietary EHR footprints.
- On-premises Solutions:Dedicated hardware deployments within hospital data centers address strict data residency requirements for certain regulated workloads. Academic medical centers with research data governance committees often mandate these configurations for genomic and trial-related datasets.
API holds installed capacity. Cloud-based Solutions is rotating up the share rankings.
Application:
Application segmentation tracks how clinical and operational use cases command differentiated platform capabilities and pricing tiers.
- Clinical Data Management:Real-time normalization of structured and unstructured clinical information across EHR, lab, and imaging systems. Pharmaceutical sponsors and academic medical centers require regulatory-grade data lineage, commanding premium platform pricing for trial recruitment and real-world evidence generation.
- Research and Development:Regulatory-grade data pipelines supporting FDA submission requirements for real-world evidence studies. Life sciences customers pay substantial premiums for platforms with auditable traceability and ISO 27001 certification.
- Patient Care Management:Care coordination workflows spanning inpatient, ambulatory, and remote monitoring settings. Clinically integrated networks deploy these capabilities to reduce readmission penalties and capture value-based contract incentives.
- Financial Management:Revenue cycle integration between clinical documentation and claims processing systems. Health systems prioritize these deployments to reduce administrative burden and accelerate accounts receivable cycles.
Clinical Data Management dominates current procurement volumes. Research and Development is climbing the fastest as pharmaceutical data strategies mature.
End User:
End user categories reflect organizational scale constraints and regulatory exposure that shape platform requirements and sales cycles.
- Hospitals:Large integrated delivery networks with complex multi-vendor EHR environments require enterprise-grade data fabrics. These buyers command the longest sales cycles but generate the highest contract values through multi-year platform commitments.
- Payors:Insurance organizations aggregating claims and clinical data for risk adjustment and care gap analytics. Medicare Advantage plans expanding supplemental benefit programs drive recent procurement acceleration in this segment.
- Clinics:Ambulatory practices with limited IT staff favor pre-configured integration templates and managed services. Subscription pricing models have expanded addressable market reach to smaller physician groups previously excluded from enterprise platform access.
- Laboratories:Diagnostic service providers exchanging results with ordering systems and public health reporting infrastructure. Regional laboratory networks upgrading from HL7 v2 to FHIR interfaces represent concentrated replacement demand.
Hospitals retain the deepest installed base. Payors is gaining share fastest as value-based contracting expands.
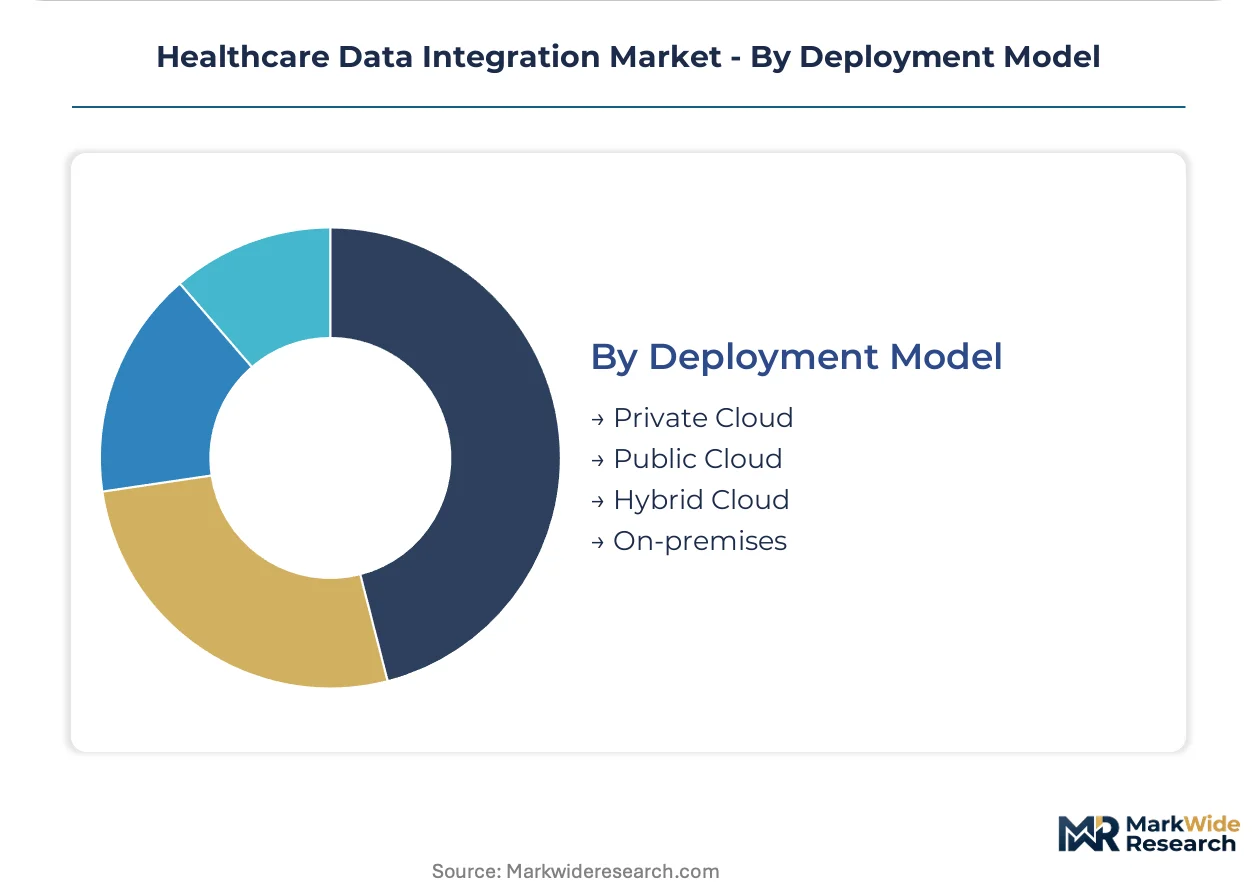
Deployment Model:
Deployment topology determines security architecture complexity and operational expenditure treatment for health system finance committees.
- Hybrid Cloud:Workload distribution across on-premises and public cloud environments balancing latency-sensitive clinical applications with elastic analytics. HIPAA security rule enforcement elevates procurement scrutiny around encryption protocols for these spanning deployments.
- Private Cloud:Dedicated infrastructure within health system-controlled data centers or single-tenant hosted environments. Organizations with strict data governance policies or state-level privacy regulations beyond HIPAA often mandate this configuration.
- Public Cloud:Multi-tenant services from hyperscale providers offering the lowest compute unit economics. Mid-tier health systems without dedicated security operations centers favor managed security responsibilities shifting to cloud vendors.
- On-premises:Fully captive infrastructure with no external data transmission for highest-sensitivity workloads. Certain psychiatric and substance use treatment facilities require these deployments under federal confidentiality regulations exceeding standard HIPAA protections.
Hybrid Cloud carries the largest committed pipeline. Private Cloud is rotating up the share rankings among risk-averse buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal incentive programs and interoperability mandates in the United States accelerate vendor investment in API-first architectures, while mature cloud infrastructure across North America and Europe creates favorable deployment conditions for enterprise data fabrics.
United States
Acute care networks with concentrated EHR installations drive replacement demand for vendor-agnostic connectivity layers. The Office of the National Coordinator for Health Information Technology enforces information blocking provisions under the 21st Century Cures Act, reshaping vendor roadmaps toward open API architectures. Large integrated delivery networks in the Northeast and California require sub-second latency for clinical decision support triggers.
Germany
Academic medical centers with research data governance committees mandate strict data residency configurations for genomic and trial-related datasets. The country's national health informatics regulator aligns with EU-wide interoperability frameworks while maintaining stringent localization requirements. Berlin and Munich anchor concentrated procurement activity for regulatory-grade data lineage platforms serving pharmaceutical sponsors.
United Kingdom
National Health Service trusts migrating from legacy messaging infrastructure generate concentrated replacement demand for FHIR R4 implementations. NHS Digital interoperability standards accelerate procurement cycles for cloud-native data fabrics. London and the Greater Manchester health system cluster represent the deepest committed pipeline for hybrid cloud deployments.
Canada
Provincial health authorities with strict privacy regulations beyond standard protections favor private cloud configurations for highest-sensitivity workloads. Health Canada guidance on real-world evidence data standards tightens requirements for traceable, auditable data lineage. Ontario and British Columbia health networks lead procurement of subscription-based platform licensing to reduce capital expenditure treatment.
Australia
Medicare Advantage-like expansion of supplemental benefit programs drives procurement acceleration among regional payors aggregating claims and clinical data. The Therapeutic Goods Administration maintains alignment with FDA guidance on regulatory-grade data pipelines. Sydney and Melbourne health system clusters concentrate demand for elastic compute environments supporting population health analytics.
Healthcare Data Integration Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered vendor landscape where EHR incumbents anchor proprietary networks while cloud-native specialists capture replacement cycles. The market structure concentrates around three strategic archetypes: dominant EHR platforms extending integration layers, cloud infrastructure providers offering interoperability tools, and FHIR-native specialists targeting faster implementation timelines. M&A activity targets middleware capabilities, while strategic partnerships accelerate API certification programs.
Within the EHR-anchored tier, Epic Systems and Oracle Health occupy positions representing contrasting approaches to platform extension—proprietary network density versus cloud-native infrastructure investment. Innovaccer exemplifies the specialist archetype competing directly with incumbent middleware through modular deployment positioning. These three entities collectively illustrate the competitive tension between closed-system entrenchment and regulatory-driven openness reshaping vendor market share dynamics.
| Leading Market Players |
|---|
| InterSystems |
| Redox |
| Innovaccer |
| Oracle Health |
| Cerner |
| Epic Systems |
| Allscripts Healthcare Solutions |
| Optum |
| Health Catalyst |
| Others |
Value Network & Pricing Analysis
Specialized FHIR implementation talent concentrates in the United States and India, anchoring professional services margins for integration platform vendors while downstream buyers in mid-tier health systems capture pricing leverage through subscription-based procurement models.
Pricing Analysis
Certification level creates the primary spread between platform tiers, with ISO 27001 and HIPAA-compliant deployments commanding substantial premiums over standard configurations. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by implementation timeline, data lineage depth, and managed services bundling. Cost compression in the standard tier intensifies because cloud-native entrants are displacing legacy middleware incumbents with faster deployment models. Mid-tier health systems exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers with research funding show lowest sensitivity given regulatory-grade data requirements.
Supply Chain Analysis
Upstream cloud infrastructure feeds from hyperscale providers concentrated in the United States, Ireland, and Singapore, with compute and storage resources forming the foundational cost stack for platform delivery. Specialized health informaticists, FHIR-certified engineers, and NLP pipeline developers constitute critical human capital inputs alongside managed Kubernetes orchestration and API gateway technologies. Single-source vulnerability runs through concentrated EHR vendor control of proprietary data formats, creating integration friction despite standardization mandates. Distribution runs through direct enterprise sales teams supplemented by channel partners serving regional health system alliances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The healthcare data integration market is cycling through a compliance-driven replacement wave as the 21st Century Cures Act enforcement deadlines compress procurement timelines for closed-system architectures.
For Market Incumbents: Harden API certification programs against emerging FHIR-native specialists by accelerating interoperability testing partnerships with regional hospital networks. Defensive consolidation through targeted middleware capability acquisitions will protect installed base erosion as cloud-native entrants capture replacement cycles with faster implementation timelines.
For New Entrants and Emerging Players: Pursue clinically integrated networks in secondary US metropolitan markets where Epic and Cerner concentration creates integration backlogs and buyer frustration with proprietary timelines. Ambulatory payor analytics represents the most penetrable application segment given Medicare Advantage expansion and limited incumbent specialization.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed middleware vendors facing compressed growth as API-first architectures displace legacy message brokers. Five-to-ten year viability hinges on successful platform rebuilds or strategic exits to cloud infrastructure providers. Monitor ONC information blocking penalty enforcement as the key inflection signal for accelerated replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| FHIR R4 API Certification Program | Accelerates vendor-agnostic connectivity for health systems facing ONC compliance deadlines. |
| Cloud-Native Platform Migration | Reduces total cost of ownership for mid-tier hospitals through elastic compute scaling. |
| Real-World Evidence Pipeline Partnership | Captures premium pricing from pharmaceutical sponsors requiring FDA-grade data lineage. |
| AI Governance Audit Trail Development | Positions platforms for pending federal algorithmic transparency mandates in clinical decision support. |
| Subscription Pricing Model Expansion | Expands addressable market to capital-constrained physician groups and regional clinics. |
Research Methodology
Operator-level perspectives from health system CIOs, FHIR implementation specialists, hospital procurement committees, and pharmaceutical data strategy leads anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against CMS Medicare reimbursement databases, ONC interoperability compliance filings, GPO contract repositories, and hyperscaler healthcare vertical capex disclosures. Bottom-up segmentation modeling triangulated with top-down market sizing across technology architecture, clinical application, and deployment topology dimensions.
Scenario-bracketing framed the analytical approach, with baseline, upside, and downside cases developed across the projection horizon. Segmentation dimensions modeled include API versus middleware versus cloud-native technology, clinical data management versus research and development versus patient care management applications, and hybrid versus private versus public cloud deployment. CAGRs derived from fitted growth curves incorporating health system IT budget trajectories, regulatory deadline schedules, and pharmaceutical R&D data infrastructure spending patterns.
Sensitivities concentrate around ONC enforcement intensity, FHIR R4 implementation uniformity across vendors, and cloud security incident frequency affecting buyer confidence. Forecasts reflect assumptions about continued federal interoperability mandate pressure and stable health system capital allocation to IT modernization. Cross-checking against hospital procurement database benchmarks and pharmaceutical sponsor technology spending surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Data Democratization in Healthcare Market
Health Data Management
Wireless Healthcare Asset Management Market
Health Data Management
Global Healthcare Data Storage Market
Health Data Management
Data Monetization in Healthcare Market
Health Data Management
Healthcare Data Monetization Solutions Market
Health Data Management
Medical Record Management System Market
Health Data Management
Master Data Management in Healthcare Market
Health Data Management
Health Care Quality Management Software Market
Health Data Management
Patient Data Management Software Market
Health Data Management
Global Big Data Analytics in Healthcare Market
Health Data Management
Americas Healthcare Archiving and Ediscovery Market
Health Data Management
Population Health Management (PHM) Market
Health Data Management
Global Healthcare Financial Analytics Market
Health Data Management
Clinical Data Management Systems (CDMS) Market
Health Data Management
Healthcare Analytics Market
Health Data Management
Global Healthcare Fraud Analytics Market