
 Contrast Media Consumables Market | 2026-2036
Contrast Media Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Contrast Media Consumables Market Analytics
Market Context
A shift from single-source to multi-source procurement of contrast media consumables is restructuring supply relationships across hospital systems. GE HealthCare leverages its installed base of imaging equipment to sustain bundled consumable contracts. Bracco Imaging competes through specialized manufacturing of iodinated agents for CT protocols. Fresenius Kabi anchors its position in generic injectable contrast through European manufacturing scale.
Technical Definition and Segment Structure
Contrast media consumables encompass sterile, single-use devices and formulations engineered to enhance tissue differentiation during radiologic imaging, with iodine concentrations ranging from 140 to 400 mgI/mL for CT agents and gadolinium chelates at 0.5 mmol/mL for MRI applications. CT contrast agents dominate current volume demand due to the proliferation of multi-detector scanner installations, while MRI contrast agents command premium positioning amid gadolinium safety debates. Intravenous delivery mode leads procedural utilization, though intra-arterial routes retain critical importance in interventional cardiology suites where precision dosing determines diagnostic yield.
Regulatory Framework
The FDA oversees premarket approval of new contrast formulations and post-market surveillance of gadolinium retention, while the EMA's PRAC has mandated enhanced labeling for macrocyclic agents across European markets. ISO 13485 quality management standards govern manufacturing consistency for disposable injection systems, creating compliance barriers for emerging suppliers. Stakeholders must monitor evolving pharmacovigilance requirements that could reshape agent selection protocols and trigger reformulation investments across the supply base.
Market Dynamics
The FDA's gadolinium retention warnings have triggered a wholesale reconfiguration of MRI contrast selection protocols, forcing hospital pharmacy committees to revalidate agent safety profiles and rebalance procurement portfolios between macrocyclic and linear chelates.
Growth Catalysts
- Multi-detector CT proliferation:Hospital radiology departments in the United States are expanding scanner installations, driving procedural volume for iodinated agents.
- Single-use delivery mandates:Infection control protocols are accelerating conversion from reusable to disposable contrast injection systems across European interventional suites.
- Gadolinium safety scrutiny:The FDA's updated pharmacovigilance requirements are compressing switching cycles as facilities preemptively migrate to macrocyclic formulations.
Market Restraints
- Iodine raw material concentration:Chilean and Japanese suppliers dominate iodine extraction, creating vulnerability to geopolitical disruption and input cost volatility.
- Gadolinium mining bottlenecks:Rare earth processing capacity concentrates in Chinese refining complexes, exposing downstream formulators to supply rationing.
- EMA labeling mandates:Enhanced macrocyclic agent documentation requirements are extending regulatory approval timelines and elevating compliance expenditure.
Strategic Opportunities
- Indian diagnostic expansion:Private hospital chains in Mumbai and Delhi are installing imaging capacity at rates outpacing mature market replacement cycles.
- Contrast-enhanced ultrasound:Microbubble formulations for liver and cardiac imaging represent an underpenetrated modality with lower nephrotoxicity liability.
- Integrated device-formulation bundles:OEMs are capturing pharmacy committee decisions by packaging proprietary injectors with multi-year agent supply commitments.
Industry Challenges
- ISO 13485 certification timelines:Disposable injection system manufacturers face 18-24 month quality management audits, constraining new entrant velocity.
- Legacy PACS integration:Automated contrast documentation modules require costly middleware development to interface with decade-old radiology information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contrast Media Consumables Market |
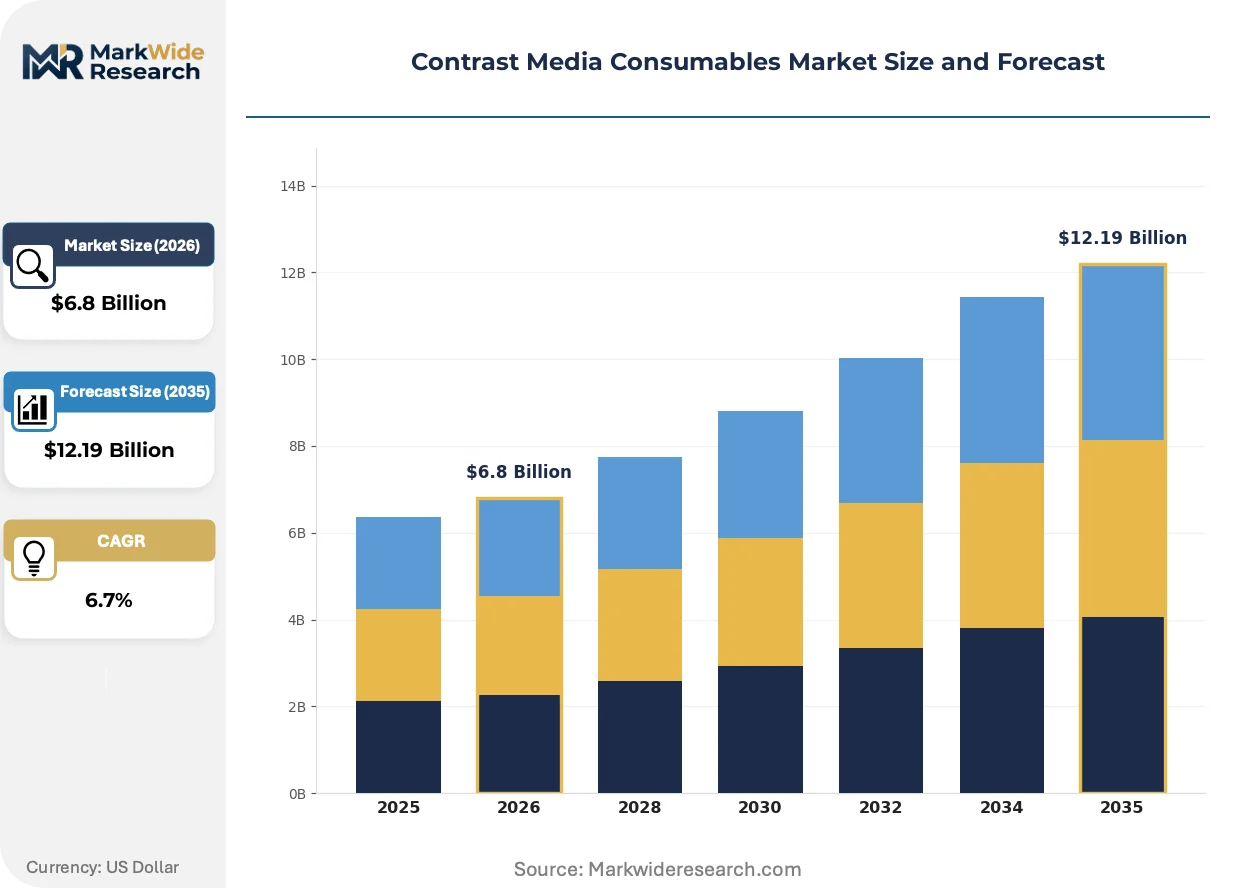
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Contrast Agents, MRI Contrast Agents, Ultrasound Contrast Agents, Other Agents Delivery Mode: Intravenous, Oral, Intra-arterial, Other Routes End User: Hospitals, Diagnostic Imaging Centers, Research Institutes, Private Clinics Application: Oncology Imaging, Cardiovascular Imaging, Neurology Imaging, Gastrointestinal Imaging |
| Companies Covered | Bayer AG, GE HealthCare, Bracco Imaging S.p.A., Guerbet, Lantheus Medical Imaging, Fresenius Kabi, J.B. Chemicals & Pharmaceuticals, Unijules Life Sciences, Beijing Beilu Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contrast Media Consumables Market Evolving Landscape
Agent formulation, delivery hardware, and procurement governance are converging into unified decision frameworks that reshape competitive positioning. Three developments dominate the analytical window.
Closed-loop contrast management systems are unifying dose tracking, patient-specific protocol selection, and waste reduction into single-platform architectures. Academic medical centers in Germany and the United States are piloting these integrated suites. The technology is unifying previously separate capital and consumable procurement decisions into bundled evaluation criteria.
The EMA's PRAC mandate for enhanced macrocyclic labeling has triggered reformulation investments across European manufacturing facilities. Industrial consequence includes accelerated phase-out of linear gadolinium agents in high-volume MRI centers. Cardiac and neurological imaging protocols in France and Italy are most affected, with hospital pharmacies pre-emptively restricting linear agent formulary placement.
Centralized pharmacy committee governance is displacing decentralized radiology department purchasing across integrated US health networks. The shift compresses supplier access points from dozens of individual departments to single system-level contracts. This consolidation is most visible in the Northeast and Midwest, where Catholic health systems and for-profit chains have completed multi-hospital integration.
Contrast Media Consumables Market Segmentation
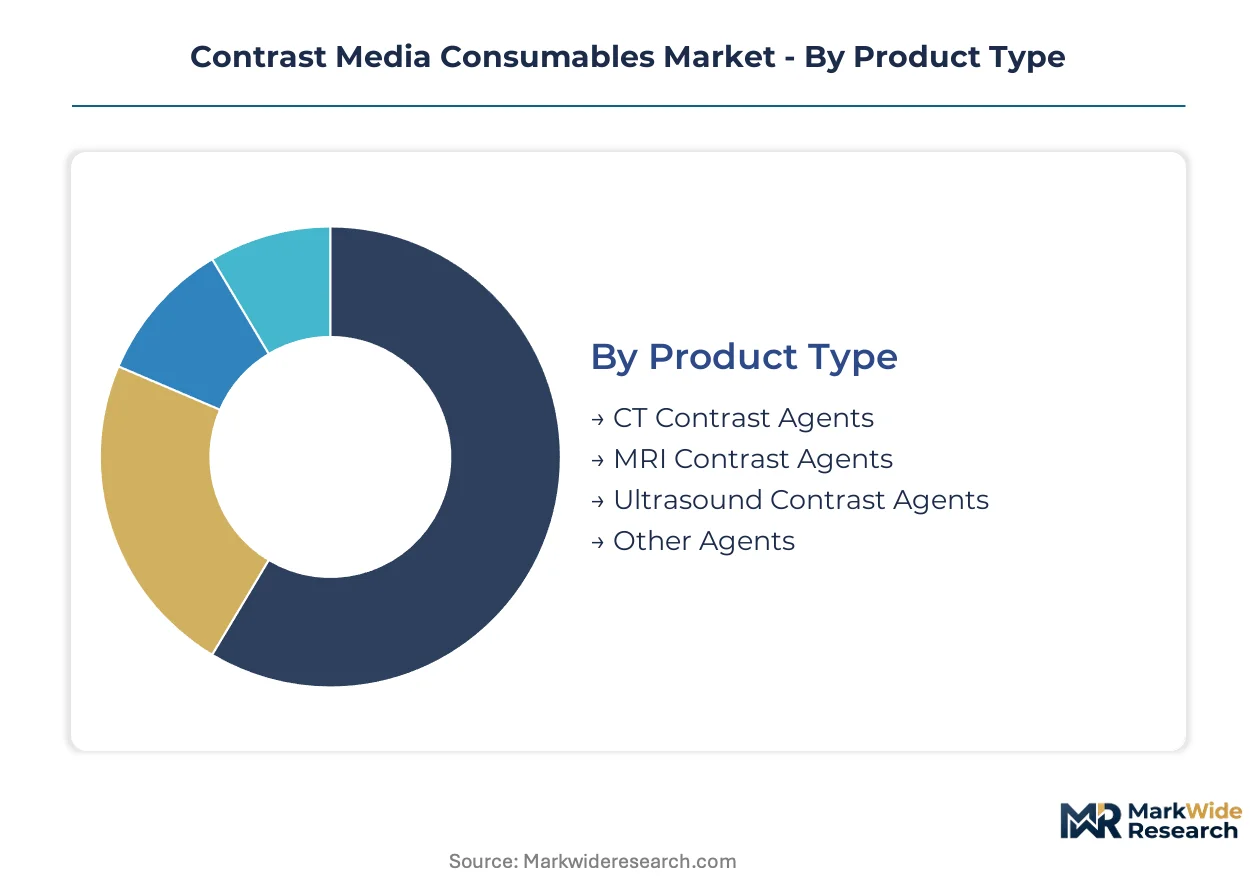
Contrast media consumables fragment across four distinct dimensions that reshape procurement priorities. Product type determines formulation chemistry and regulatory pathway. Delivery mode governs infection control protocols and device compatibility. End user concentration dictates contract scale and pricing leverage. Application specialization drives protocol standardization and agent selection criteria.
Product Type:
Procurement committees differentiate agents primarily by imaging modality installed base and safety profile revalidation burden.
- CT Contrast Agents:Iodinated formulations span 140-400 mgI/mL concentrations optimized for multi-detector scanner protocols. United States hospital radiology departments concentrate procurement volume here, driven by emergency department throughput requirements and trauma imaging standardization.
- MRI Contrast Agents:Gadolinium chelates at 0.5 mmol/mL face macrocyclic versus linear selection pressure from FDA pharmacovigilance mandates. German academic medical centers are preemptively restricting linear agent formulary placement ahead of EMA labeling enforcement.
- Ultrasound Contrast Agents:Microbubble formulations for liver and cardiac imaging carry lower nephrotoxicity liability than iodinated or gadolinium alternatives.
- Other Agents:Barium suspensions and specialized gastrointestinal formulations serve niche fluoroscopy protocols.
Volume sits with CT Contrast Agents; growth tilts toward MRI Contrast Agents amid safety-driven formulation switching.
Delivery Mode:
Route selection hinges on procedural precision requirements and disposable versus reusable device economics.
- Intravenous:Peripheral and central line administration dominates CT and MRI protocol utilization. European infection control mandates are accelerating conversion from reusable power injectors to single-use delivery systems in high-volume centers.
- Intra-arterial:Selective catheter delivery enables precision dosing in interventional cardiology suites where diagnostic yield depends on contrast timing. French and Italian cardiac catheterization laboratories maintain specialized procurement for these high-acuity procedures.
- Oral:Enteric formulations serve gastrointestinal and pelvic CT protocols requiring bowel opacification.
- Other Routes:Intrathecal and intra-cavitary administration support specialized neuroradiology and hysterosalpingography applications.
Intravenous captures procedural volume; intra-arterial commands premium positioning through precision requirements.
End User:
Customer scale and governance structure determine contract negotiation dynamics and supplier access points.
- Hospitals:Integrated health networks in the United States Northeast and Midwest are consolidating contrast purchasing under centralized pharmacy committees, compressing supplier relationships from departmental to system-wide contracts.
- Diagnostic Imaging Centers:Independent outpatient facilities in India—particularly Mumbai and Delhi private chains—are installing capacity faster than mature market replacement cycles, creating volume concentration outside traditional hospital procurement.
- Private Clinics:Smaller-scale operators rely on distributor relationships and group purchasing organization affiliation for supply security.
- Research Institutes:Academic medical centers in Germany pilot closed-loop contrast management systems that unify dose tracking with procurement optimization.
Hospitals anchor contract value; diagnostic imaging centers are expanding most quickly in emerging markets.
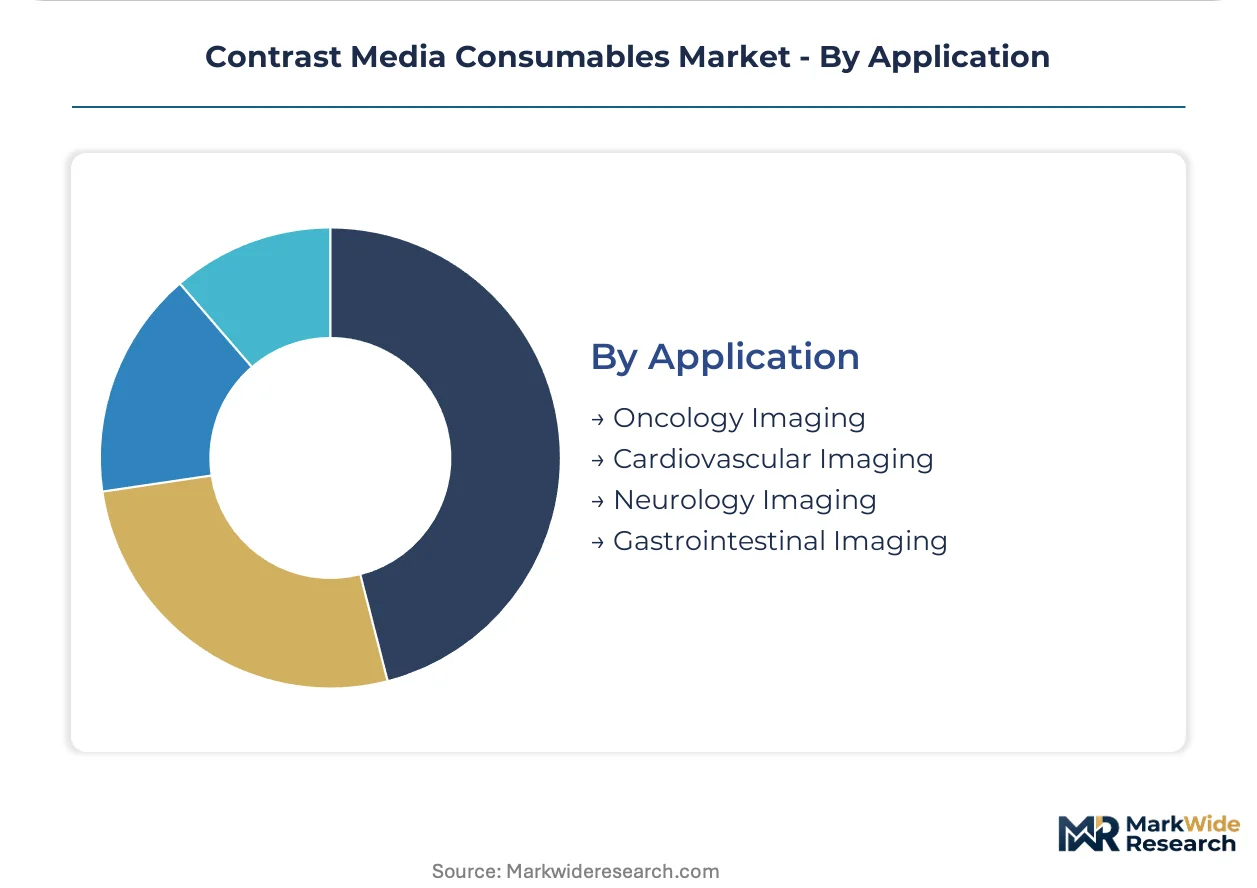
Application:
Clinical indication dictates agent selection criteria, protocol standardization, and outcome measurement frameworks.
- Oncology Imaging:Staging and treatment response assessment drives repeat scanning frequency. Macrocyclic gadolinium retention concerns are forcing protocol revalidation across United States cancer centers.
- Cardiovascular Imaging:Coronary CT angiography and cardiac MRI stress protocols demand precise timing and dose optimization. Intra-arterial delivery retains critical importance here.
- Neurology Imaging:Blood-brain barrier permeability assessment requires high-relaxivity gadolinium formulations with established safety documentation.
- Gastrointestinal Imaging:CT enterography and hepatobiliary MRI rely on oral and intravenous agent combinations with specialized timing protocols.
Oncology Imaging generates scan frequency; cardiovascular imaging demands the tightest delivery precision.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chilean iodine extraction and Chinese rare earth refining anchor raw material security for contrast media formulation, while downstream demand concentrates in health systems with centralized procurement governance.
United States
Integrated health networks in the Northeast and Midwest are consolidating contrast purchasing under centralized pharmacy committees. The FDA's updated gadolinium retention guidance is forcing hospital formularies to revalidate MRI agent safety profiles. Academic medical centers in Boston and Philadelphia pilot closed-loop contrast management systems that unify dose tracking with procurement optimization.
Germany
Academic medical centers in Berlin and Munich drive adoption of macrocyclic gadolinium formulations ahead of EMA labeling enforcement. The EMA's PRAC mandate for enhanced macrocyclic agent documentation is extending regulatory approval timelines. Industrial concentration in Baden-Württemberg supports ISO 13485-certified manufacturing of disposable injection systems for European export.
India
Private hospital chains in Mumbai and Delhi are installing imaging capacity at rates outpacing mature market replacement cycles. The CDSCO maintains premarket approval authority over new contrast formulations entering the domestic market. Manufacturing clusters in Gujarat and Maharashtra supply generic iodinated agents to diagnostic imaging centers across South Asia.
China
Rare earth processing capacity for gadolinium chelates concentrates in refining complexes supplying downstream formulators. The NMPA oversees premarket approval of new contrast media and post-market surveillance of agent safety. Beijing-based pharmaceutical manufacturers are expanding production of iodinated CT agents for domestic hospital procurement.
France
Cardiac catheterization laboratories in Paris and Lyon maintain specialized procurement for intra-arterial contrast delivery systems. ANSM enforces pharmacovigilance requirements that reshape agent selection protocols in high-volume MRI centers. Hospital pharmacies in Île-de-France are preemptively restricting linear gadolinium agent formulary placement.
Contrast Media Consumables Market Competitive Landscape
Strategic partnerships dominate the current landscape as suppliers seek to bundle proprietary injectors with multi-year agent supply commitments. The vendor base clusters around three tiers: diversified healthcare conglomerates with imaging equipment installed bases, specialized pharmaceutical manufacturers with formulation chemistry depth, and generic injectable specialists leveraging manufacturing scale. Archetypes include integrated device-formulation bundlers, iodinated agent specialists, and rare earth supply chain integrators. Competitive moves center on M&A for technology access and capacity expansion in ISO 13485-certified facilities.
Among diversified healthcare conglomerates, Bayer AG and GE HealthCare occupy positions that exemplify the integrated device-formulation bundler archetype. Bracco Imaging S.p.A. represents the specialized pharmaceutical manufacturer tier with concentrated expertise in iodinated agent formulation. Fresenius Kabi anchors the generic injectable specialist segment through European manufacturing scale.
| Leading Market Players |
|---|
| Bayer AG |
| GE HealthCare |
| Bracco Imaging S.p.A. |
| Guerbet |
| Lantheus Medical Imaging |
| Fresenius Kabi |
| J.B. Chemicals & Pharmaceuticals |
| Unijules Life Sciences |
| Beijing Beilu Pharmaceutical |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up diagnostic imaging specialists have consolidated procurement leverage across United States health networks, compressing supplier margins while simultaneously demanding extended warranty coverage on disposable injection systems. This ownership pattern tightens pricing discipline among formulators who must absorb service-bundling costs or forfeit centralized pharmacy committee contracts.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium injector-agent packages from unbundled economy alternatives in committee evaluations. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification grade and installed-base compatibility depth. Cost compression in the standard tier is intensifying because European infection control mandates accelerate single-use conversion without proportional volume growth. Diagnostic imaging centers in India exhibit highest price sensitivity due to capital-constrained expansion timelines, while German academic medical centers prioritize safety documentation over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Chilean iodine extraction and Chinese rare earth refining complexes that feed downstream formulators. Iodine draw from Atacama Desert brine operations, gadolinium from Inner Mongolia processing facilities, and sterile packaging substrates from German polymer specialists anchor manufacturing cost structures. Tariff exposure on refined rare earth compounds threatens margin stability for macrocyclic agent producers. Distribution runs through health system GPO contracts in the United States and specialized medical distributors in European interventional suites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a formulation-transition phase as macrocyclic gadolinium chelates displace linear alternatives under FDA pharmacovigilance pressure. Closed-loop contrast management platforms are simultaneously replacing standalone injector hardware in academic procurement cycles.
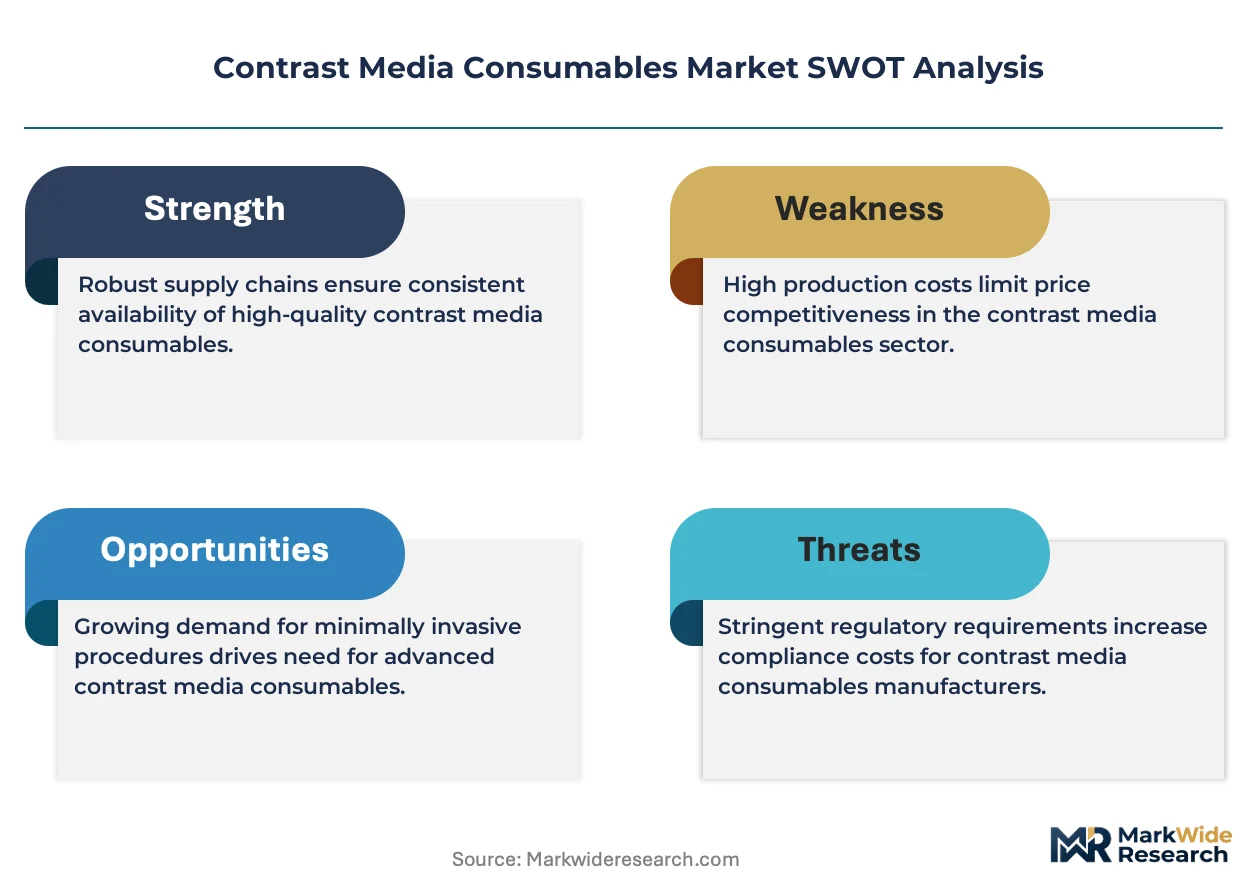
For Market Incumbents: Deepen backward integration into iodine extraction partnerships or captive rare earth offtake agreements to insulate against supply rationing. Expand ISO 13485-certified manufacturing capacity in Baden-Württemberg to capture European single-use mandate volume. Lock in multi-year bundled contracts with Catholic health systems before centralized pharmacy committees complete vendor consolidation. For New Entrants and Emerging Players: The price-point gap between premium GE-Bracco bundles and economy generic injectables creates entry space for mid-tier specialists with focused MRI agent portfolios. Target diagnostic imaging center chains in Mumbai and Delhi with localized manufacturing partnerships and CDSCO-fast-tracked registrations. Lead with contrast-enhanced ultrasound microbubbles as a nephrotoxicity-differentiated wedge into cardiac imaging protocols. For Investors and Strategic Acquirers: EMA PRAC labeling enforcement acceleration is the leading indicator that macrocyclic formulation capacity will command scarcity premiums over the next decade. Acquire generic injectable specialists with European manufacturing footprints and existing gadolinium chelate production lines. Monitor FDA adverse event reporting system trends for linear agent restriction signals that would trigger hospital formulary purge cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Macrocyclic Agent Reformulation Investment | EMA PRAC mandates in Berlin and Munich facilities preempt linear agent obsolescence. |
| ISO 13485 Manufacturing Scale-Up | Baden-Württemberg certification expansion captures European single-use conversion demand. |
| Closed-Loop System Hospital Partnership | Boston and Philadelphia academic pilots unify dose tracking with procurement optimization. |
| Indian Diagnostic Center Distribution Agreement | Mumbai and Delhi private chains outpace mature market installation rates. |
| Gadolinium Supply Chain Backward Integration | Inner Mongolia rare earth offtake secures macrocyclic production against Chinese export rationing. |
Research Methodology
Multi-period observation of FDA adverse event reporting trends and EMA PRAC labeling timelines anchored the trend analysis, supplemented by interviews with hospital pharmacy committee chairs, interventional radiology department heads, GPO contracts managers, and contrast media manufacturing quality directors. Secondary validation drew from FDA 510(k) filings, EMA EPAR documentation, CDSCO approval registers, hospital procurement database extracts, and ISO 13485 certification registries. Bottom-up volume modeling across scanner installation rates and procedure frequency triangulated against top-down health system expenditure tracking.
Input-output matrix framing connected iodine extraction volumes and gadolinium refining capacity to downstream formulation output across the projection horizon. Segmentation dimensions spanned imaging modality, delivery mode, end-user governance structure, and regional regulatory cluster. CAGRs were derived from procedure volume elasticity to scanner installation cycles and agent switching cost amortization patterns. Forecast inputs incorporated pharmacovigilance enforcement intensity indices and infection control mandate adoption curves.
Inputs from EMA and FDA regulatory disclosure systems were available through the study window; gaps in real-time hospital formulary restriction data introduce uncertainty bands around agent switching velocity assumptions. Deviation in Chinese rare earth export licensing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Cryotubes Market
Medical Supplies
Global Hospital Linen Supply and Management Services Market
Medical Supplies
Bile Collection Bags Market
Medical Supplies
Global Dental Sterilization Market
Medical Supplies
Nitrile Gloves Market
Medical Supplies
Global Enema Based Products Market
Medical Supplies
US Hospital Consumables Market
Medical Supplies
Medical Swabs Market
Medical Supplies
Venipuncture Needles and Syringes Market
Medical Supplies
Amniotic Membrane Market
Medical Supplies
GCC Syringes and Needles Market
Medical Supplies
Global Unna Boot Market
Medical Supplies
Petri Dishes Market
Medical Supplies
Flexible Packaging for Healthcare Market
Medical Supplies
External Nasal Dilator and Nasal Strip Market
Medical Supplies
Ultrasound Conductivity Gels Market