
 Bioactive Fillings Market | 2026-2036
Bioactive Fillings Market Size, Share, and Industry Trends Forecast 2026-2036
Bioactive Fillings Market Intelligence
Consolidation among dental service organizations and large hospital networks is recalibrating procurement relationships for bioactive filling manufacturers. This trend favors suppliers with significant scale and sophisticated logistics capabilities. Dentsply Sirona leverages its extensive distribution network to serve these centralized buyers. Separately, 3M differentiates through materials science innovation in resin-based composites, while Pulpdent Corporation specializes in moisture-friendly materials for specific clinical applications.
Bioactive fillings are dental and orthopedic restorative materials designed to interact with the biological environment, promoting natural tissue regeneration. These materials often contain calcium phosphate or glass ionomer components that release ions like calcium and phosphate to stimulate apatite formation. Glass ionomer and resin-based composites command significant volume among product types, valued for their handling properties and aesthetics. Demand from dental clinics for direct placement restorations constitutes the largest application segment.
Market access is governed by stringent medical device regulations, including the FDA's 510(k) clearance process in the United States and CE marking under the EU's Medical Device Regulation (MDR). ISO standards for biocompatibility, such as ISO 10993, further define material safety and testing protocols for all manufacturers. Future competitive success hinges on demonstrating long-term clinical efficacy and navigating evolving regulatory requirements for materials with regenerative claims.
Market Dynamics
The convergence of stringent medical device regulations and patient demand for minimally invasive procedures is the central force shaping the bioactive fillings market. This dual pressure accelerates innovation in materials that offer both clinical efficacy and demonstrable regenerative properties.
Growth Catalysts
- Minimally Invasive Dentistry:Patient demand for procedures preserving tooth structure drives adoption of materials that remineralize dentin, reducing the need for extensive cavity preparation.
- Advanced Material Science:Innovations in moisture-friendly glass ionomers and composites improve clinical handling, expanding their use in challenging direct restoration scenarios.
- Favorable Demographics:Aging populations in developed nations like Germany create sustained demand for advanced restorative solutions to manage conditions like root caries.
Market Restraints
- Higher Material Cost:The premium price of bioactive fillings versus traditional amalgam limits adoption in public healthcare systems and cost-sensitive dental clinics.
- Limited Long-Term Evidence:A scarcity of multi-year clinical studies for some newer formulations creates adoption hesitancy among practitioners awaiting robust efficacy data.
- Regulatory Compliance Burden:Navigating the EU's MDR and the FDA's 510(k) process adds significant cost and time to product development cycles.
Strategic Opportunities
- Emerging Market Expansion:Untapped demand in countries like Brazil and India with rising dental care spending presents a significant growth avenue for manufacturers.
- Pediatric Dentistry Applications:Developing formulations specifically for primary teeth offers a new segment, leveraging bioactive properties for caries prevention and simplified application.
- Digital Dentistry Integration:Combining bioactive materials with CAD/CAM systems for indirect restorations creates an opportunity for high-value, single-visit regenerative treatments.
Industry Challenges
- Practitioner Education:The unique handling properties of some bioactive materials require specialized dentist training, which can slow widespread clinical adoption.
- Post-Market Surveillance:Fulfilling the rigorous clinical follow-up and data reporting mandated by the EU's MDR is a significant operational burden.
- Raw Material Sourcing:Securing a stable supply of high-purity components like specialty glass fillers is critical for maintaining consistent product quality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioactive Fillings Market |
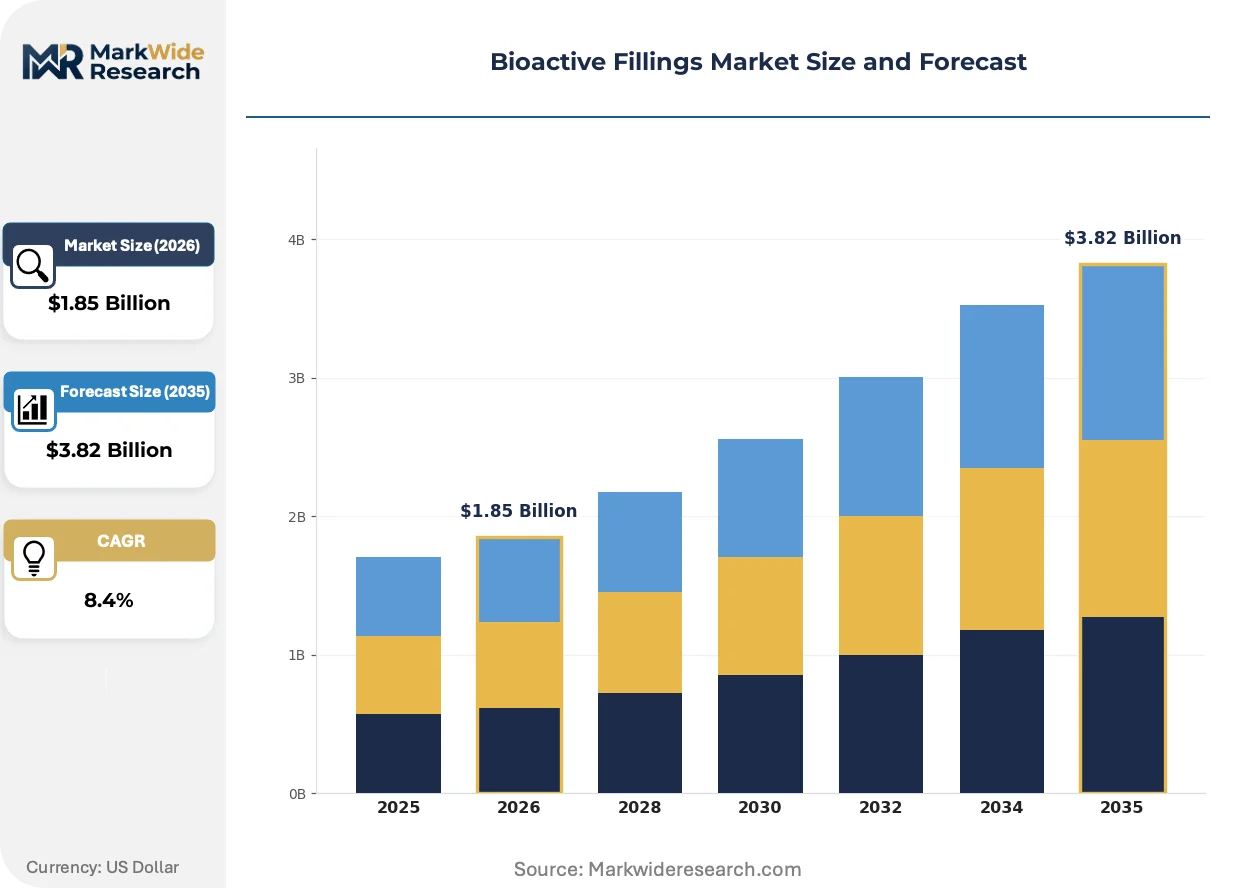
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Ionomer, Calcium Phosphate, Resin-Based, Composite, Polyacid-Modified Application: Dental Restorations, Orthopedic Reconstruction, Bone Grafting, Craniofacial Repair End User: Dental Clinics, Orthopedic Centers, Ambulatory Surgery Centers, Specialized Research Institutes Delivery Mode: Direct Placement, Indirect Application, Injectable Formulations, Pre-Mixed Cartridges |
| Companies Covered | DePuy Synthes, Septodont Inc., Zimmer Biomet, Medtronic, Kerr Corporation, Coltene Whaledent, 3M, Dentsply Sirona, Pulpdent Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioactive Fillings Market Strategic Shifts & Innovations
Materials science advancements are fundamentally redefining the role of dental fillings from passive fillers to active therapeutic agents. This evolution prioritizes long-term tissue regeneration and biocompatibility, pushing innovation beyond conventional restorative metrics.
Self-adhesive, dual-cure bioactive materials simplify the restorative workflow by eliminating separate etching and bonding steps. General dental practitioners seeking greater efficiency are adopting these products for direct restorations. This simplification is electrifying the direct restoration segment by reducing chair time and making advanced materials more accessible outside specialist clinics.
The European Union's Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence on products claiming therapeutic or regenerative benefits. This forces manufacturers to invest in comprehensive, long-term clinical trials to validate material performance and biocompatibility claims. Resin-based composite and glass ionomer manufacturers are most affected, now building robust data packages for CE marking.
Centralized purchasing by large dental service organizations (DSOs) is altering traditional procurement models. This shift favors manufacturers with scaled logistics and enterprise-level contracts over those reliant on direct sales to individual clinics. The trend is most visible in the United States, where DSO consolidation is reshaping supplier relationships and pricing negotiations.
Bioactive Fillings Market Segmentation
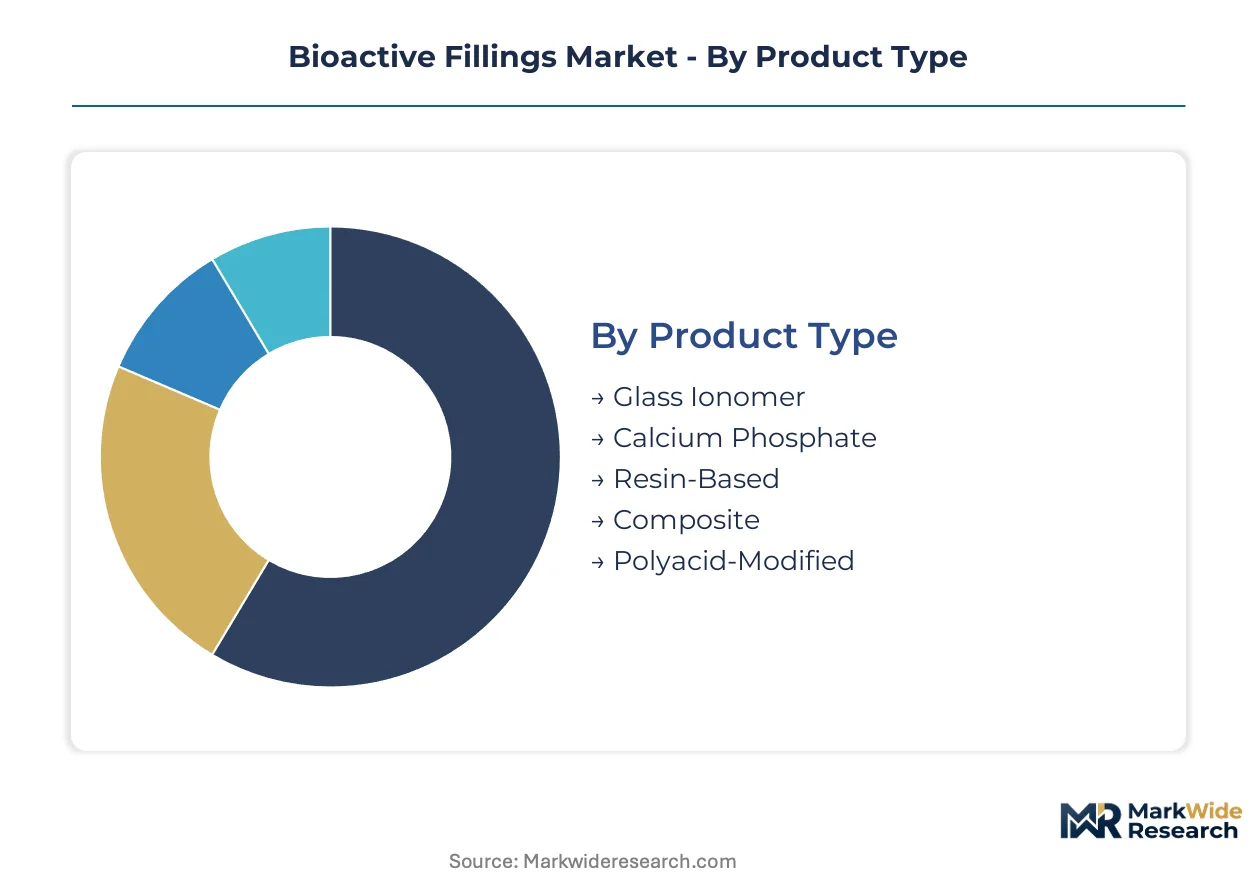
The Bioactive Fillings Market differentiates across distinct material compositions, clinical applications, and end-user requirements. Understanding these segments clarifies demand patterns and highlights areas of innovation in restorative and regenerative dentistry. Each segment reflects unique material science challenges and specific regulatory pathways.
Product Type:
Buyers in this category differentiate based on material properties and clinical handling characteristics crucial for long-term patient outcomes.
- Glass Ionomer:These materials release fluoride ions and chemically bond to tooth structure, offering remineralization benefits and moisture tolerance. Demand concentrates in pediatric dentistry and geriatric care in countries like Germany, where caries management is a priority.
- Resin-Based:These composites offer superior aesthetics and strength, often incorporating bioactive fillers for ion release and tissue interaction. Demand is high for direct restorations in private dental clinics across the United States, driven by patient aesthetic preferences.
- Calcium Phosphate:These materials mimic natural bone and tooth minerals, promoting apatite formation and tissue integration.
- Composite:These materials combine resin matrices with various fillers, balancing mechanical properties with aesthetic requirements for restorative procedures.
- Polyacid-Modified:These materials offer a hybrid approach, combining properties of glass ionomers and resin composites for specific clinical scenarios.
Volume sits with Glass Ionomer; growth tilts toward Resin-Based.
Application:
Application focuses on treatment area and desired regenerative outcome for both dental and orthopedic fields.
- Dental Restorations:This segment involves filling cavities and repairing damaged tooth structure, constituting the largest end-use for bioactive materials. Demand from general dental practitioners for direct placement procedures drives significant volume globally, including in emerging markets like Brazil.
- Orthopedic Reconstruction:Bioactive materials support bone regeneration and repair in various orthopedic procedures, including fracture healing and joint reconstruction. Demand is increasing in specialized orthopedic centers in developed healthcare markets due to an aging population.
- Bone Grafting:These materials serve as scaffolds to stimulate new bone formation in areas requiring structural support or defect repair.
- Craniofacial Repair:Bioactive fillings facilitate the reconstruction of bone defects in the skull and face, often after trauma or surgical intervention.
Demand for Dental Restorations remains consistent, while Orthopedic Reconstruction is expanding most quickly.
End User:
End user segmentation reflects the scale and specialization of healthcare providers procuring bioactive filling materials.
- Dental Clinics:These facilities, ranging from solo practices to large dental service organizations, represent the primary purchasers of bioactive fillings for routine restorative procedures. Procurement relationships are recalibrating with centralized purchasing by DSOs in the United States.
- Orthopedic Centers:Specialized hospitals and clinics focusing on musculoskeletal conditions utilize bioactive materials for bone repair and regeneration. Demand for advanced restorative solutions in these centers is driven by complex surgical needs.
- Ambulatory Surgery Centers:These outpatient facilities perform various surgical procedures, including some dental and orthopedic interventions, requiring efficient material delivery.
- Specialized Research Institutes:Academic and private research entities use bioactive materials for developing new applications and testing advanced formulations.
The largest segment, Dental Clinics, drives consistent procurement, while Orthopedic Centers show significant potential.
Delivery Mode:
Delivery mode differentiates by clinical workflow efficiency and material handling properties during application.
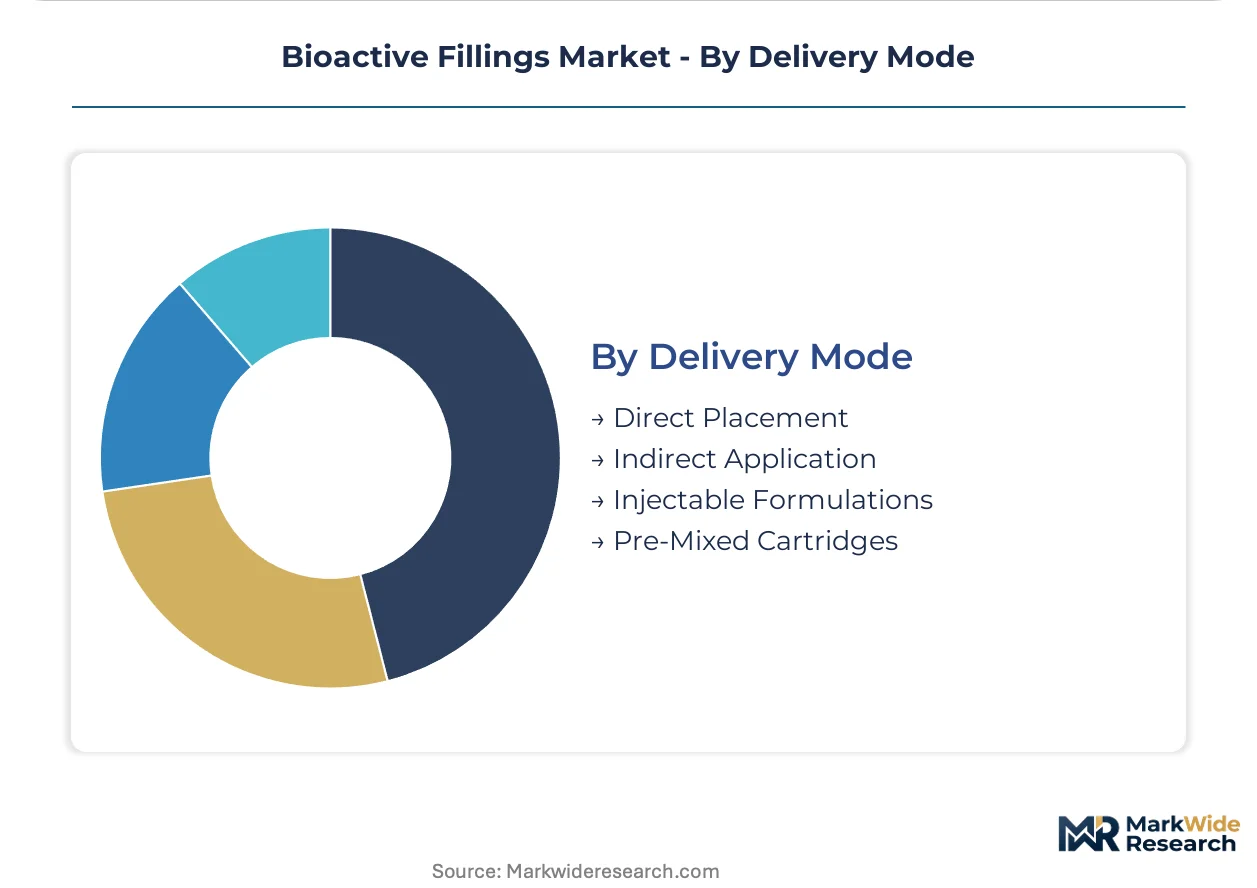
- Direct Placement:Materials applied directly into the cavity or defect during a single clinical visit, simplifying the restorative process. This mode is favored by general dental practitioners seeking to reduce chair time and improve workflow in clinics globally.
- Pre-Mixed Cartridges:Pre-dosed and encapsulated materials ensure consistent mixing and easy extrusion, minimizing preparation errors and waste. This delivery method is gaining traction in busy dental practices across Europe due to its convenience and reliability.
- Indirect Application:Materials used in laboratory settings to fabricate restorations that are later cemented into place, offering precise control over contours.
- Injectable Formulations:Viscous or flowable materials delivered via syringe, suitable for minimally invasive procedures and filling irregular defects.
Efficiency gains in Direct Placement are influencing adoption, with Pre-Mixed Cartridges seeing notable uptake.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for bioactive fillings concentrates in developed healthcare markets prioritizing advanced dental technologies. The United States and Germany exhibit strong adoption due to patient preferences and established dental infrastructure. Emerging economies like Brazil and India also present significant growth opportunities.
United States
Patient demand for aesthetic and advanced restorative solutions drives the market in the United States. The FDA's 510(k) clearance process rigorously regulates new product introductions. California's MedTech hubs, particularly around San Francisco, foster significant innovation in dental material development.
Germany
Germany's aging population and focus on root caries management sustain demand for advanced restorative solutions. The EU's Medical Device Regulation (MDR) sets high standards for clinical evidence and product safety. Munich's advanced dental research centers actively contribute to material efficacy studies.
Brazil
Rising dental care spending and increasing access to general dental practitioners boost demand in Brazil. ANVISA, the national health surveillance agency, regulates medical device approvals and market access. São Paulo's large dental schools heavily influence material adoption trends and practitioner training.
India
Untapped market potential and a growing middle class seeking better dental care drive demand across India. The Central Drugs Standard Control Organization (CDSCO) oversees medical device regulations. Bangalore's burgeoning healthcare technology sector attracts investment in local manufacturing capabilities for dental materials.
Japan
Japan's high standards for dental care and emphasis on long-term biocompatibility fuel product adoption. The Pharmaceuticals and Medical Devices Agency (PMDA) rigorously approves new dental materials. Tokyo's leading research institutions advance new bioactive material formulations and clinical applications.
Bioactive Fillings Market Key Industry Players
Developed market producers anchor one tier; emerging market specialists hold another. The bioactive fillings market exhibits a tiered structure, with global players alongside specialized regional manufacturers. Large multinational corporations, niche material science innovators, and regional distributors form distinct competitive archetypes. Manufacturers pursue strategic partnerships for market access and invest in portfolio diversification to address varied clinical needs.
Among global material science innovators, Dentsply Sirona exemplifies companies leveraging extensive distribution networks to serve centralized buyers across various geographies. 3M represents firms differentiating through advanced materials science, particularly in resin-based composites with enhanced properties. Pulpdent Corporation anchors the segment specializing in moisture-friendly materials, catering to specific clinical applications requiring unique handling characteristics. These entities collectively highlight diverse approaches to market penetration, product development, and customer engagement within the bioactive fillings sector, emphasizing innovation and logistical strength.
| Leading Market Players |
|---|
| DePuy Synthes |
| Septodont Inc. |
| Zimmer Biomet |
| Medtronic |
| Kerr Corporation |
| Coltene Whaledent |
| 3M |
| Dentsply Sirona |
| Pulpdent Corporation |
| Others |
Cost & Logistics Intelligence
Advanced material science innovation, particularly in resin-based composites, simultaneously reshapes cost economics and supply concentration by demanding specialized chemical precursors and manufacturing processes. This technological shift influences both the final product pricing and the geographic sourcing of critical components for bioactive fillings.
Pricing Analysis
Volume-driven glass ionomer products operate on tighter margins compared to premium resin-based composites. The dominant pricing structure remains per-unit transactional, influenced by material composition and clinical claims. Price differentiation stems from the level of biocompatibility certification (e.g., CE marking, FDA 510(k) clearance) and brand reputation. Pricing pressure stems from public healthcare systems and cost-sensitive dental clinics seeking more affordable alternatives. Dental clinics, especially those in public health systems, are most price-sensitive, while specialized orthopedic centers prioritize validated performance over cost.
Supply Chain Analysis
Domestic-content mandates for medical devices are reshaping sourcing strategies, particularly for specialized raw materials. Geographic supply concentration for key components, such as specialty glass fillers and calcium phosphate, draws from specialized manufacturers in Germany and China. Raw material dependencies include high-purity glass particles and specific resin monomers. Supply chain risk centers on commodity price volatility for these specialized chemical inputs. Distribution runs through a dual model of direct sales to large dental service organizations (DSOs) and regional distributors serving individual dental clinics and orthopedic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a supply-constrained story, with specialized raw material sourcing for advanced bioactive components forming a critical capacity bottleneck propping pricing.
For Market Incumbents:
Extend clinical evidence for existing product lines, focusing on multi-year efficacy studies to counter practitioner hesitancy. Consolidate market share through strategic acquisitions of niche material science innovators specializing in regenerative claims. Invest in robust regulatory affairs teams to navigate evolving EU MDR requirements, mitigating the threat of market access delays. Control distribution channels by establishing direct supply agreements with large dental service organizations, leveraging logistical scale as a competitive lever.
For New Entrants and Emerging Players:
A price-point gap exists between premium, highly specialized bioactive materials and more traditional, cost-effective options. Target pediatric dentistry applications, where simplified application and caries prevention offer a clear white-space opportunity. Focus on developing moisture-friendly glass ionomer formulations for easier clinical handling in general dental practices. A direct-to-practitioner education model, emphasizing clinical benefits and simplified workflows, offers a penetrable go-to-market angle.
For Investors and Strategic Acquirers:
Exit pathways concentrate in specialized material science firms with proprietary regenerative technologies or strong regulatory approvals. The bioactive fillings market offers long-term viability over a 5-10 year window, driven by aging populations and demand for minimally invasive dentistry. Target acquisition candidates with strong intellectual property in calcium phosphate or advanced resin-based composites. Watch for significant advancements in digital dentistry integration as a key inflection indicator for high-value indirect restoration opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Clinical Evidence Base | Validates long-term material efficacy, reducing practitioner adoption hesitancy across developed markets. |
| Invest in Specialized Raw Material Sourcing | Secures supply of high-purity components, ensuring consistent product quality and manufacturing stability. |
| Target Pediatric Dentistry Formulations | Addresses a specific demographic need, leveraging bioactive properties for primary teeth applications. |
| Acquire Niche Material Science Innovators | Integrates advanced regenerative technologies and intellectual property into existing product portfolios. |
| Strengthen Regulatory Affairs Capabilities | Ensures compliance with stringent global medical device regulations, facilitating market access and product longevity. |
Research Approach
Independent corroboration across industry white papers, scientific publications, and regulatory body databases underwrites the qualitative findings within this study. The analysis combines primary interviews with dental practitioners, materials scientists, regulatory affairs specialists, and procurement managers from dental service organizations. Secondary validation draws from FDA 510(k) clearances, EU MDR documentation, ISO standards, and dental association publications to ensure a robust bottom-up and top-down triangulation.
The forecast framework anchored the analysis window by establishing comparable historical reference periods for market trends and growth drivers. Segmentation dimensions modeled include product type, application, end-user, delivery mode, and material biocompatibility, providing granular insights across the projection horizon. Compound annual growth rates were derived through a proprietary analytical model, incorporating dental procedure volumes and regulatory approval timelines as key industry-specific forecast inputs throughout the forecast period.
Inputs from published scientific literature and regulatory filings were available through the study window; gaps in long-term clinical efficacy data for newer formulations introduce uncertainty bands. Forecasts reflect assumptions concerning future regulatory changes and material science breakthroughs. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Soft Tissue Market
Medical Devices
Peripheral Embolization Device Market
Medical Devices
Europe Sperm Separation Devices Market
Medical Devices
Medical Device Tester Market
Medical Devices
Global Laparoscopy Devices Market
Medical Devices
Global Vaginal Speculum Market
Medical Devices
Repetitive Transcranial Magnetic Stimulation Market
Medical Devices
Novel Vaccine Delivery Systems Market
Medical Devices
North America Refractive Surgery Devices Market
Medical Devices
Canada Ultrasound Devices Market
Medical Devices
Nano Healthcare Technology Market
Medical Devices
Surgical Devices Market
Medical Devices
Global Implantable Cardioverter Defibrillators (ICD) Market
Medical Devices
Spinal Implant Market
Medical Devices
In Vitro Fertilization Monitoring System Market
Medical Devices
Directed Energy Based Surgical Systems Market