
 Dravet Syndrome Treatment Market | 2026-2036
Dravet Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Dravet Syndrome Treatment Market Analysis
Specialized pediatric epilepsy centers is unwinding the traditional hospital-centric treatment model as families seek comprehensive care coordination. Biocodex leverages its European distribution network to sustain access across rare-disease pharmacy channels. Jazz Pharmaceuticals anchors its position through deep R&D investment in cannabinoid formulations. Stoke Therapeutics differentiates with antisense oligonucleotide technology targeting the underlying SCN1A genetic mechanism.
Dravet syndrome treatment encompasses pharmacological and emerging genetic interventions designed to reduce seizure frequency and severity in patients with SCN1A mutations, with anticonvulsants such as stiripentol, clobazam, and valproate forming the current standard of care backbone. The primary purpose is to modulate neuronal excitability and improve developmental outcomes in a patient population resistant to conventional monotherapy. Cannabinoids, particularly purified cannabidiol formulations, command premium positioning due to FDA orphan exclusivity and restricted payer formularies. Novel drug delivery systems, including sustained-release platforms, represent the fastest-expanding technology tier as developers target adherence gaps in pediatric populations. Oral administration routes maintain volume dominance, though intravenous formulations retain critical share in acute rescue settings.
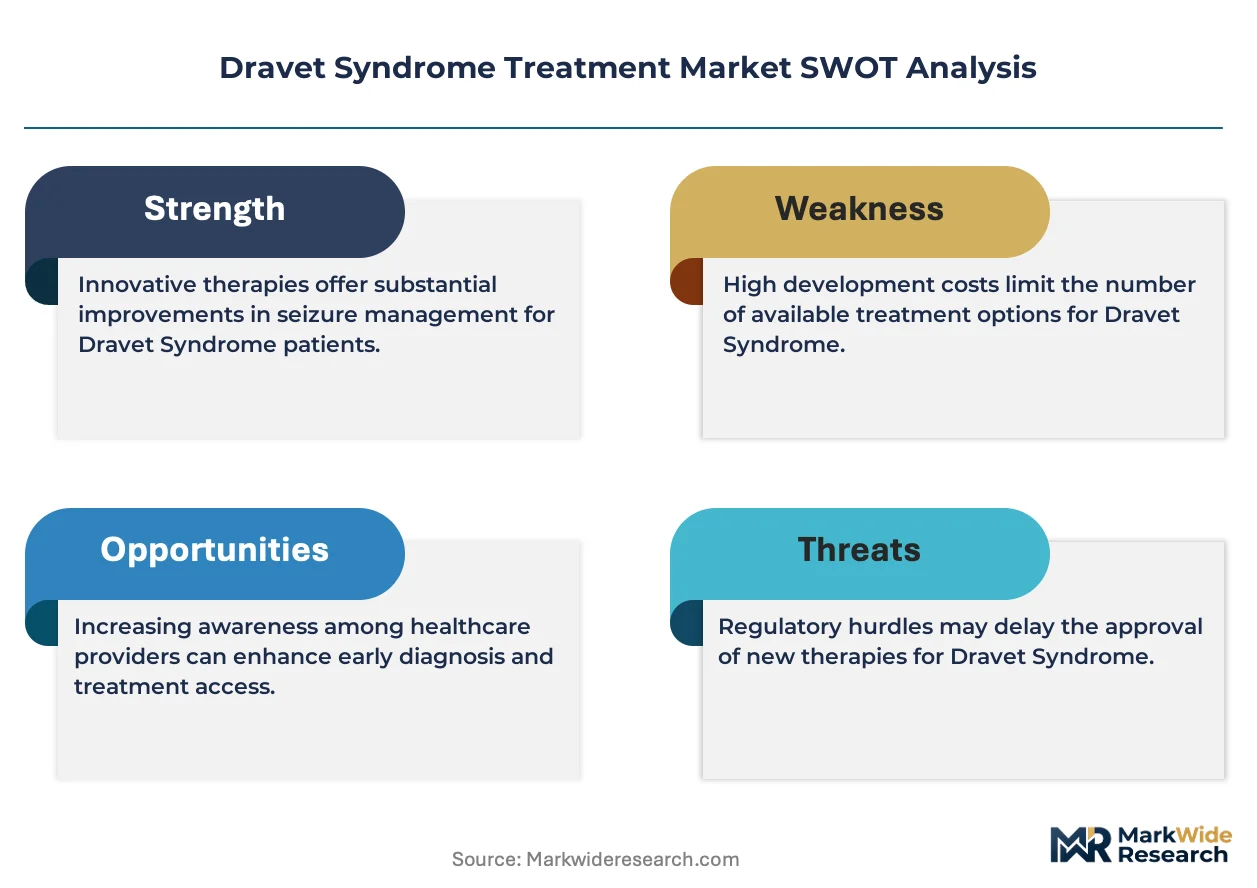
FDA orphan drug designation and breakthrough therapy pathways accelerate commercial timelines for developers targeting this ultra-rare indication, while EMA's pediatric regulation mandates juvenile toxicity studies that reshape early-phase trial design. State-level Medicaid expansion in the US and national health technology assessments in Europe create divergent reimbursement landscapes that manufacturers must navigate simultaneously. Stakeholders should monitor gene therapy regulatory precedents and payer readiness for one-time curative modalities versus chronic maintenance protocols.
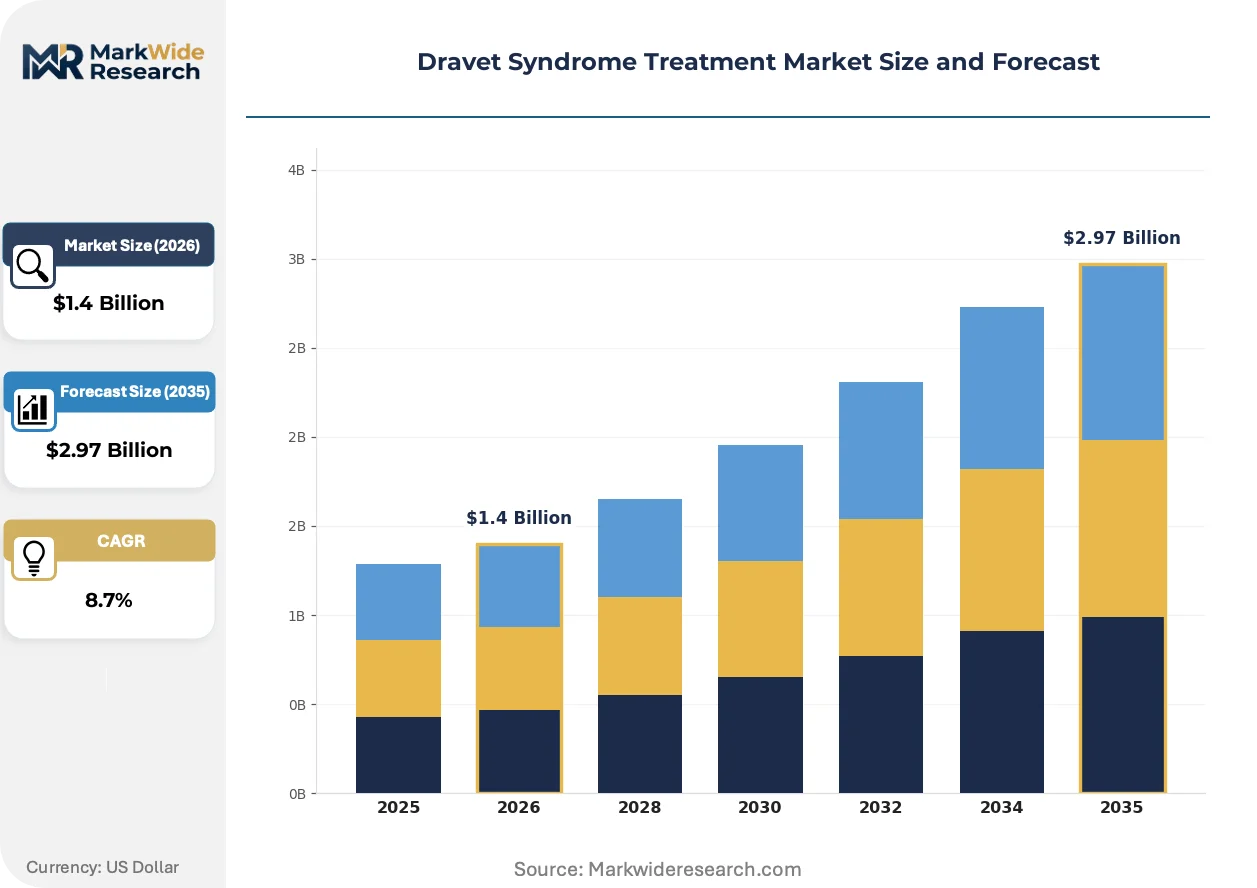
Market Dynamics
Gene therapy pipelines targeting SCN1A haploinsufficiency are compressing development timelines and forcing incumbents to reposition chronic maintenance portfolios against potential curative alternatives.
Growth Catalysts
- FDA orphan drug exclusivity:Seven-year market protection and tax credits incentivize developers to pursue pediatric epilepsy indications despite small addressable populations.
- EMA pediatric investigation plans:Mandatory juvenile study requirements accelerate age-appropriate formulation development across European trial networks.
- Caregiver advocacy mobilization:Dravet Syndrome Foundation chapters in the United States compress diagnostic delays and drive earlier specialist referrals.
Market Restraints
- Single-source API concentration:Stiripentol active pharmaceutical ingredient production concentrates among European contract manufacturers, exposing supply chains to geopolitical friction.
- Medicaid formulary heterogeneity:US state-level prior authorization requirements create access friction for cannabinoid-based therapies despite federal approval.
- Gene therapy manufacturing bottlenecks:Viral vector production capacity constraints delay antisense oligonucleotide program timelines.
Strategic Opportunities
- Subcutaneous depot formulations:Sustained-release cannabinoid delivery platforms address adherence gaps in pediatric populations resistant to frequent oral dosing.
- Companion diagnostic integration:SCN1A variant identification protocols expand addressable patient pools through neonatal screening program adoption.
- Japan's orphan drug framework:PMDA priority review vouchers and extended exclusivity periods attract Western developers to Asia-Pacific registration strategies.
Industry Challenges
- Pediatric trial recruitment scarcity:Ultra-rare incidence rates force sponsors to maintain multi-year enrollment windows across dispersed academic medical centers.
- Reimbursement evidence standards:Payer demands for quality-of-life endpoints beyond seizure frequency complicate health technology assessment submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dravet Syndrome Treatment Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anticonvulsants, Cannabinoids, Steroids, Other Therapies Administration Route: Oral, Injectable, Intravenous, Transdermal End User: Hospitals, Clinics, Homecare, Research Centers Delivery Technology: Standard Delivery, Sustained Release, Novel Drug Delivery, Others |
| Companies Covered | Biocodex, Jazz Pharmaceuticals, UCB, Stoke Therapeutics, Epygenix Therapeutics, Ovid Therapeutics, PTC Therapeutics, Takeda Pharmaceutical Company Limited, Lundbeck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dravet Syndrome Treatment Market Emerging Trajectories
Antisense oligonucleotide platforms and cannabinoid formulation science are converging to redefine therapeutic paradigms, while regulatory frameworks adapt to evaluate one-time genetic interventions against chronic pharmacological maintenance.
MicroRNA-targeting oligonucleotides restore SCN1A expression in inhibitory interneurons by blocking translation-suppressing sequences. Academic medical centers in Boston and San Francisco are advancing first-in-human protocols with unprecedented speed. This modality is miniaturizing the treatment burden from lifelong polypharmacy to episodic intrathecal administration.
EMA's updated guideline on clinical investigation of medicinal products for epilepsy mandates seizure diary digitization and patient-reported outcome integration. Developers must now deploy electronic data capture platforms from Phase II forward. European trial sponsors are absorbing substantial protocol amendment costs to comply.
Caregiver purchasing committees now dominate cannabinoid therapy selection, displacing traditional physician-driven prescribing patterns. Specialty pharmacy distribution channels capture margin through risk evaluation and mitigation strategy administration. This concentration is most visible in California and New York, where integrated epilepsy centers coordinate insurance navigation services.
Dravet Syndrome Treatment Market Segmentation
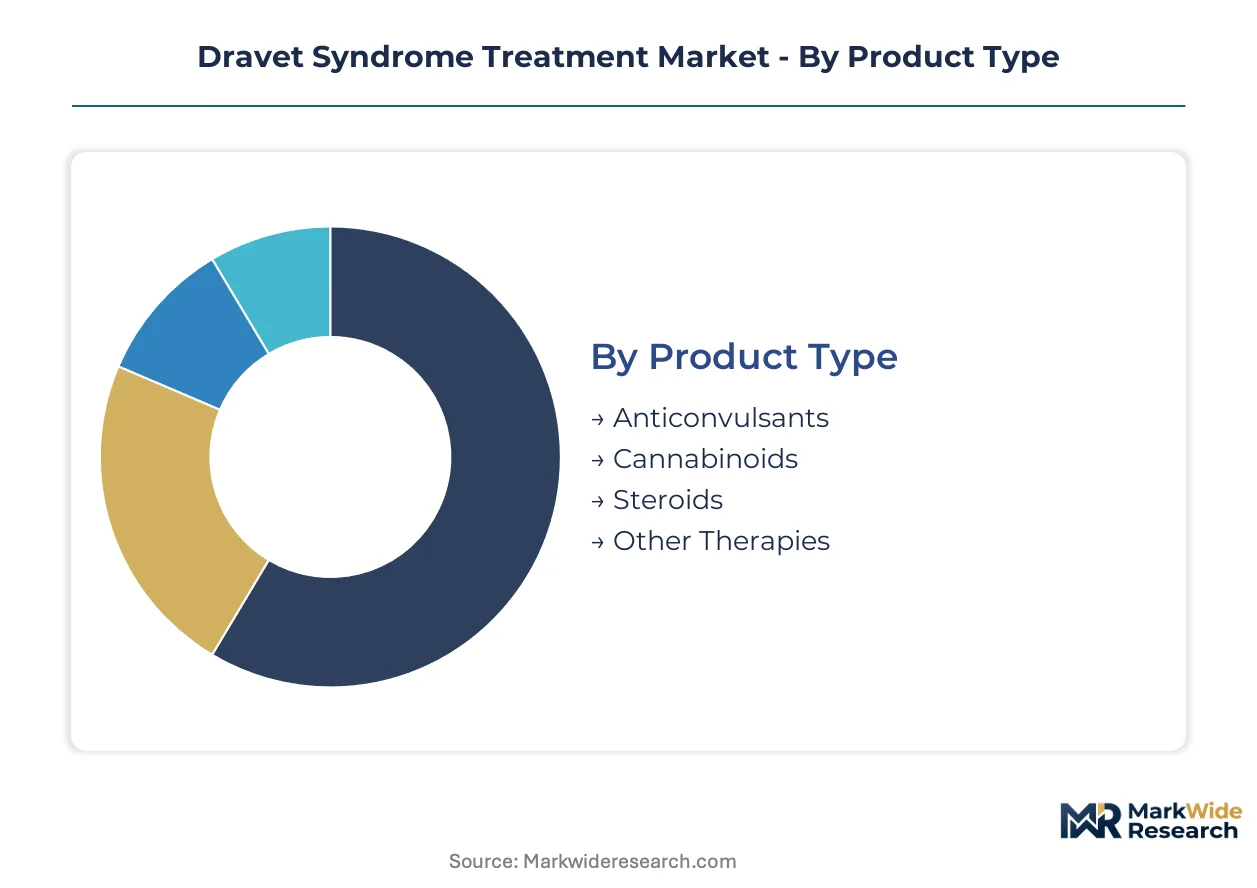
Treatment segmentation in Dravet syndrome reflects divergent commercial strategies across chronic maintenance versus curative modalities. Product and technology categories concentrate demand in distinct geographies based on regulatory approval status and reimbursement infrastructure maturity.
Product Type:
Anticonvulsants dominate domestic prescription volumes in established Western markets, while cannabinoid uptake concentrates in US states with streamlined Medicaid pathways.
- Anticonvulsants:Stiripentol, clobazam, and valproate combinations form the pharmacological backbone with decades of clinical validation. European pharmacy channels sustain the deepest penetration, though US academic medical centers drive protocol refinements through the NIH-funded rare diseases consortium.
- Cannabinoids:Purified cannabidiol formulations operate under FDA orphan exclusivity with restricted distribution through specialty pharmacy networks. California and New York integrated epilepsy centers coordinate insurance navigation services that accelerate patient access.
- Steroids:Rescue protocols in acute seizure clusters.
- Other Therapies:Adjunctive interventions including ketogenic diet support and vagus nerve stimulation.
Anticonvulsants command the established base. The steepest expansion runs through cannabinoids.
Administration Route:
Route selection tracks patient age and seizure acuity, with pediatric adherence challenges driving formulation innovation across cost tiers.
- Oral:Volume-dominant across maintenance protocols with liquid and sprinkle formulations addressing swallowing difficulties in developmentally delayed children. European EMA pediatric investigation plans mandate age-appropriate taste masking and dosing flexibility.
- Intravenous:Critical share in acute rescue settings where rapid bioavailability determines clinical outcomes. US hospital formularies maintain standby inventory for status epilepticus protocols.
- Injectable:Subcutaneous depot formulations emerging for sustained-release cannabinoid platforms.
- Transdermal:Patch-based delivery in early clinical validation for patients with feeding tube dependence.
Oral formulations anchor volume economics. Injectable platforms are climbing the fastest as developers target adherence gaps.
End User:
Care site selection reflects diagnostic complexity and therapy intensity, with specialized pediatric epilepsy centers displacing general hospital neurology departments.
- Hospitals:Academic medical centers with Level 4 epilepsy monitoring units capture the most complex cases requiring surgical evaluation and intravenous rescue protocols. Boston Children's Hospital and UCSF Benioff Children's Hospitals anchor referral networks.
- Clinics:Dedicated pediatric neurology clinics unwind hospital-centric models through comprehensive care coordination. The Dravet Syndrome Foundation chapters compress diagnostic delays by routing families to these specialized sites.
- Homecare:Caregiver-administered rescue medications and daily maintenance protocols.
- Research Centers:Gene therapy trial sites with SCN1A natural history registries.
Hospitals retain the highest-acuity base. Clinics are gaining share fastest as families seek coordinated care outside institutional settings.
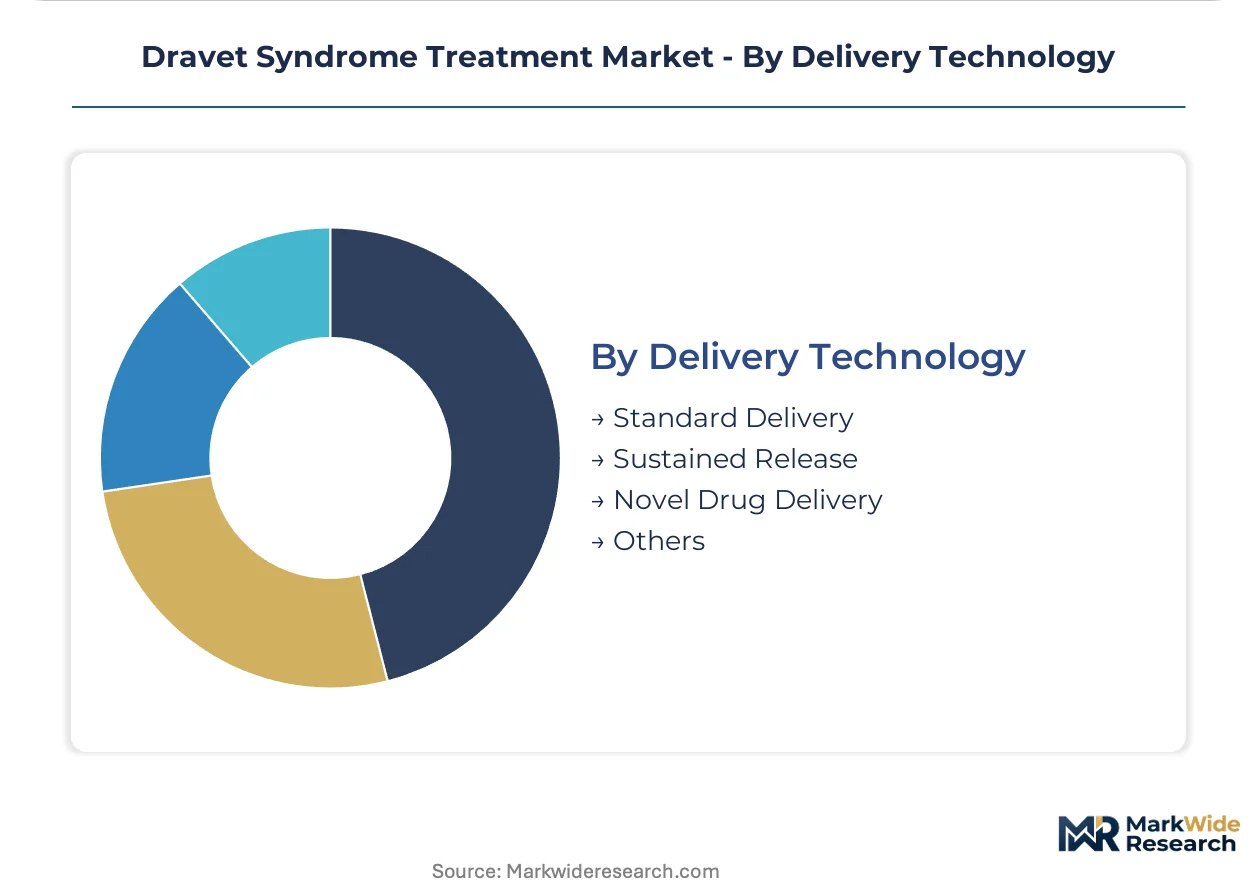
Delivery Technology:
Technology tier selection separates premium-positioned novel platforms from commoditized standard formulations, with manufacturing complexity driving margin stratification.
- Sustained Release:Subcutaneous depot and implantable formulations address the adherence burden of twice-daily oral dosing in pediatric populations. Developers target this tier for cannabinoid platform extensions with FDA breakthrough therapy designations.
- Novel Drug Delivery:Intranasal rescue sprays and intrathecal antisense oligonucleotide administration represent the frontier. Stoke Therapeutics advances episodic dosing that compresses treatment burden from lifelong polypharmacy.
- Standard Delivery:Immediate-release oral tablets and solutions with established bioequivalence profiles.
- Others:Emerging platforms including transdermal microneedle arrays and implantable pumps.
Standard delivery commands the installed base. Novel drug delivery systems show the steepest expansion trajectory as gene therapy pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European API manufacturers export stiripentol active pharmaceutical ingredients to US specialty pharmacy distributors, anchoring transatlantic trade flows in this ultra-rare disease category.
United States
Caregiver advocacy networks and Level 4 epilepsy monitoring units at Boston Children's Hospital and UCSF drive diagnostic acceleration. FDA orphan drug exclusivity grants seven-year market protection for cannabinoid formulations. California and New York integrated epilepsy centers coordinate insurance navigation services that compress time-to-treatment initiation.
Germany
EMA pediatric investigation plans mandate juvenile toxicity studies that reshape early-phase trial protocols for developers targeting European approval. The country's national pharmaceutical regulator enforces stringent pharmacovigilance requirements for anticonvulsant combinations. Heidelberg and Munich academic medical centers anchor multi-center natural history registries for SCN1A variants.
Japan
PMDA priority review vouchers and extended exclusivity periods attract Western developers pursuing Asia-Pacific registration strategies. METI orphan drug frameworks subsidize pediatric formulation development costs. Tokyo and Osaka university hospitals host gene therapy trial sites with established antisense oligonucleotide administration capabilities.
United Kingdom
NICE health technology assessments create divergent reimbursement landscapes that manufacturers must navigate alongside US Medicaid formularies. The MHRA post-Brexit regulatory pathway accelerates access schemes for ultra-rare indications. London and Cambridge research clusters advance microRNA-targeting platforms through academic-industry partnerships.
Switzerland
Swissmedic streamlined approval processes for orphan indications attract developers seeking European market entry points. The country's pharmaceutical manufacturing base concentrates high-value API production for anticonvulsant backbones. Basel and Zurich house specialized rare-disease pharmacy distribution networks serving cross-border patient populations.
Dravet Syndrome Treatment Market Vendor Landscape
Listed leaders compete with private specialists across cannabinoid formulation and genetic intervention vectors. The vendor base stratifies into three tiers: established pharmaceutical conglomerates with orphan drug portfolios, mid-cap neurology-focused developers, and emerging gene therapy platforms. Archetypes include chronic maintenance incumbents defending polypharmacy positions, curative modality pioneers compressing treatment burdens, and specialty pharmacy intermediaries capturing distribution margin. Dominant competitive moves include strategic partnerships for viral vector manufacturing capacity and portfolio diversification into sustained-release delivery platforms.
Within the chronic maintenance tier, Jazz Pharmaceuticals and UCB occupy positions anchored by deep commercial infrastructure in epilepsy indications. Stoke Therapeutics exemplifies the curative modality archetype through antisense oligonucleotide technology targeting underlying SCN1A genetic mechanisms. Biocodex represents European distribution specialists sustaining access across rare-disease pharmacy channels through established contract manufacturing relationships.
| Leading Market Players |
|---|
| Biocodex |
| Jazz Pharmaceuticals |
| UCB |
| Stoke Therapeutics |
| Epygenix Therapeutics |
| Ovid Therapeutics |
| PTC Therapeutics |
| Takeda Pharmaceutical Company Limited |
| Lundbeck |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between European API manufacturers and US specialty pharmacy distributors lock in stiripentol supply access while anchoring price visibility across the forecast period. These contractual structures insulate orphan drug developers from spot market volatility in active pharmaceutical ingredient procurement.
Pricing Analysis
Current-generation anticonvulsant pricing sits at a substantial discount to next-generation cannabinoid formulations, which command premium positioning through FDA orphan exclusivity and restricted payer formularies. Price differentiation rests on regulatory designation tier and distribution channel control, with specialty pharmacy networks capturing margin through risk evaluation and mitigation strategy administration. Cost compression in the anticonvulsant backbone is intensifying as generic valproate alternatives expand, while cannabinoid tiers maintain pricing power through restricted distribution. Pediatric neurology clinics demonstrate highest price sensitivity due to Medicaid formulary heterogeneity, whereas integrated epilepsy centers in California and New York show lowest sensitivity through coordinated insurance navigation services.
Supply Chain Analysis
Inbound logistics costs from European contract manufacturers to US distributors have stabilized following pandemic-era container congestion, though Rotterdam-to-New York trade lanes retain vulnerability to seasonal port bottlenecks. API production concentrates in France, Germany, and Switzerland, with stiripentol active pharmaceutical ingredient manufacturing anchored in European chemical processing hubs. Raw material dependencies span sodium channel modulator precursors, cannabidiol hemp biomass, and viral vector production reagents. Single-source vulnerability in viral vector capacity constrains antisense oligonucleotide program timelines. Distribution runs through specialty pharmacy networks with cold chain requirements for biologic formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy pipelines targeting SCN1A haploinsufficiency constitute an existential substitution threat that chronic maintenance incumbents must navigate through strategic repositioning.
For Market Incumbents: Consolidate manufacturing relationships with European API suppliers to secure stiripentol active pharmaceutical ingredient continuity against geopolitical friction. Deepen backward integration into cannabinoid formulation science to defend margin position against antisense oligonucleotide episodic dosing alternatives. Prioritize sustained-release platform development to address adherence gaps that gene therapy entrants exploit. For New Entrants and Emerging Players: Caregiver insurance navigation services represent a service-layer gap where incumbents under-serve, creating white-space for specialized patient access platforms. Target Medicaid expansion states with streamlined prior authorization pathways as the most penetrable geography. Pursue companion diagnostic integration with neonatal screening programs as the primary go-to-market angle. For Investors and Strategic Acquirers: Antisense oligonucleotide platform developers with intrathecal administration capabilities offer the most compelling acquisition target archetype for long-term viability across the 5-10 year window. Payer readiness for one-time curative modalities versus chronic maintenance protocols serves as the critical signal to watch for inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Regulatory Approval Pathway | FDA breakthrough therapy designation accelerates SCN1A-targeting antisense oligonucleotide commercial timelines. |
| Companion Diagnostic Development | SCN1A variant identification protocols expand addressable patient pools through neonatal screening adoption. |
| Sustained-Release Formulation Scale-Up | Subcutaneous depot platforms address pediatric adherence gaps that drive caregiver therapy switching. |
| Specialty Pharmacy Network Partnership | Risk evaluation and mitigation strategy administration capabilities capture distribution margin in restricted cannabinoid channels. |
| Asia-Pacific Registration Strategy | PMDA priority review vouchers attract Western developers to Japanese orphan drug frameworks. |
Methodological Framework
Operator-level perspectives from drug development executives, regulatory affairs leads, formulary directors, and payer access specialists anchored the qualitative base for this analysis. Primary interviews across these stakeholder categories combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population modeling and top-down revenue triangulation ensured cross-verification of market sizing assumptions.
Sensitivity analysis across treatment line, dosage form, administration route, and regional regulatory cluster dimensions informed the analytical framework over the projection horizon. CAGRs derived from epidemiological prevalence projections, pricing trajectory assumptions, and penetration rate modeling for novel modalities. Forecast inputs incorporated gene therapy pipeline maturation timelines and payer readiness evolution for curative versus maintenance paradigms.
Forecasts assume regulatory continuity in FDA orphan drug exclusivity and EMA pediatric investigation plan regimes; material policy shifts would require re-modeling. Specific risk factors include gene therapy manufacturing bottlenecks, Medicaid formulary heterogeneity, and viral vector production capacity constraints that could compress development timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Hemophilia Market
Specialty Medicine
Neuromuscular Disorders Treatment Market
Specialty Medicine
HTLV-1 Associated Myelopathy (HAM) Market
Specialty Medicine
Biliary Atresia Treatment Market
Specialty Medicine
Systemic Lupus Erythematosus (SLE) Market
Specialty Medicine
Soft Tissue Sarcoma Market
Specialty Medicine
Bartonellosis Therapeutics Market
Specialty Medicine
Diffuse Large B-Cell Lymphoma Therapeutics Market
Specialty Medicine
Global Sarcopenia Treatment Market
Specialty Medicine
Glucagon Therapy Market
Specialty Medicine
Congenital Neutropenia Treatment Market
Specialty Medicine
Eosinophilic Esophagitis Market
Specialty Medicine
Lamellar Ichthyosis Treatment Market
Specialty Medicine
Middle East and Africa Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Sports Medicine Market
Specialty Medicine
Global Cancer Biological Therapy Market