
 Global Vascular Access Devices Market | 2026-2036
Global Vascular Access Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vascular Access Devices Market Foresight
Asset-light leasing models for infusion pump and catheter systems is tilting procurement economics toward providers with lower capital deployment capacity. Becton Dickinson and Company leverages integrated manufacturing scale across peripheral and central venous catheter lines. Terumo Corporation anchors its position through heparin-bonded surface technologies that reduce thrombotic complications. Medtronic competes via deep channel relationships with integrated delivery networks in North America.
Vascular access devices are sterile, biocompatible tubes—typically constructed from polyurethane, silicone, or fluorinated ethylene propylene—engineered for percutaneous insertion into veins to enable fluid administration, blood withdrawal, or hemodynamic monitoring. Peripheral catheters dominate procedure volume due to their deployment in short-term medication delivery, while antimicrobial-coated central venous catheters command premium positioning because hospital-acquired infection protocols elevate coated product specifications. Ultrasound-guided insertion technology is displacing landmark-based placement in emergency and critical care settings, reshaping training requirements and device bundling.
FDA 510(k) clearance pathways, EU MDR technical documentation requirements, and Japan PMDA quality management system inspections collectively elevate compliance costs and extend time-to-market for new catheter platforms. These frameworks compress the viable competitive set to manufacturers with dedicated regulatory affairs infrastructure and clinical evidence generation capabilities. Stakeholders must monitor how antimicrobial resistance surveillance data from CDC and ECDC influences coating efficacy claims and reimbursement thresholds for premium device tiers.
Market Dynamics
Ultrasound-guided insertion protocols are compressing training timelines for vascular access specialists while simultaneously elevating device bundling requirements for manufacturers.
Growth Catalysts
- EU MDR antimicrobial efficacy mandates:Hospital-acquired infection surveillance from ECDC is elevating coated catheter specifications across European oncology wards.
- Silicone elastomer advances:New polymer formulations extend dwell times for peripherally inserted central catheters in long-term infusion therapy.
- Ambulatory infusion center expansion:United States, Germany, and Japan are scaling outpatient networks that favor disposable catheter systems over capital-intensive alternatives.
Market Restraints
- Polyurethane feedstock volatility:Medical-grade polymer supply concentrates among Asian chemical manufacturers, exposing device makers to input cost swings.
- FDA 510(k) pathway friction:Predicate device requirements and clinical data expectations extend clearance timelines for novel catheter platforms.
- Peripheral catheter commoditization:Standard uncoated devices face substitution pressure from low-cost Asian producers in price-sensitive procurement environments.
Strategic Opportunities
- India's oncology infrastructure buildout:CDSCO regulatory harmonization and private hospital chain expansion create addressable white space for mid-tier device portfolios.
- Closed-system transfer device convergence:Integration of needle-free connectors with antimicrobial catheters addresses hazardous drug exposure protocols in chemotherapy administration.
- Japan PMDA quality management incentives:Streamlined inspection pathways for manufacturers with ISO 13485 certification accelerate market entry for compliant suppliers.
Industry Challenges
- Ultrasound competency gaps:Emergency departments and critical care units face shortages of clinicians trained in real-time vascular visualization techniques.
- EU MDR technical documentation burden:Clinical evidence generation requirements for legacy catheter lines strain regulatory affairs bandwidth at mid-sized manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vascular Access Devices Market |
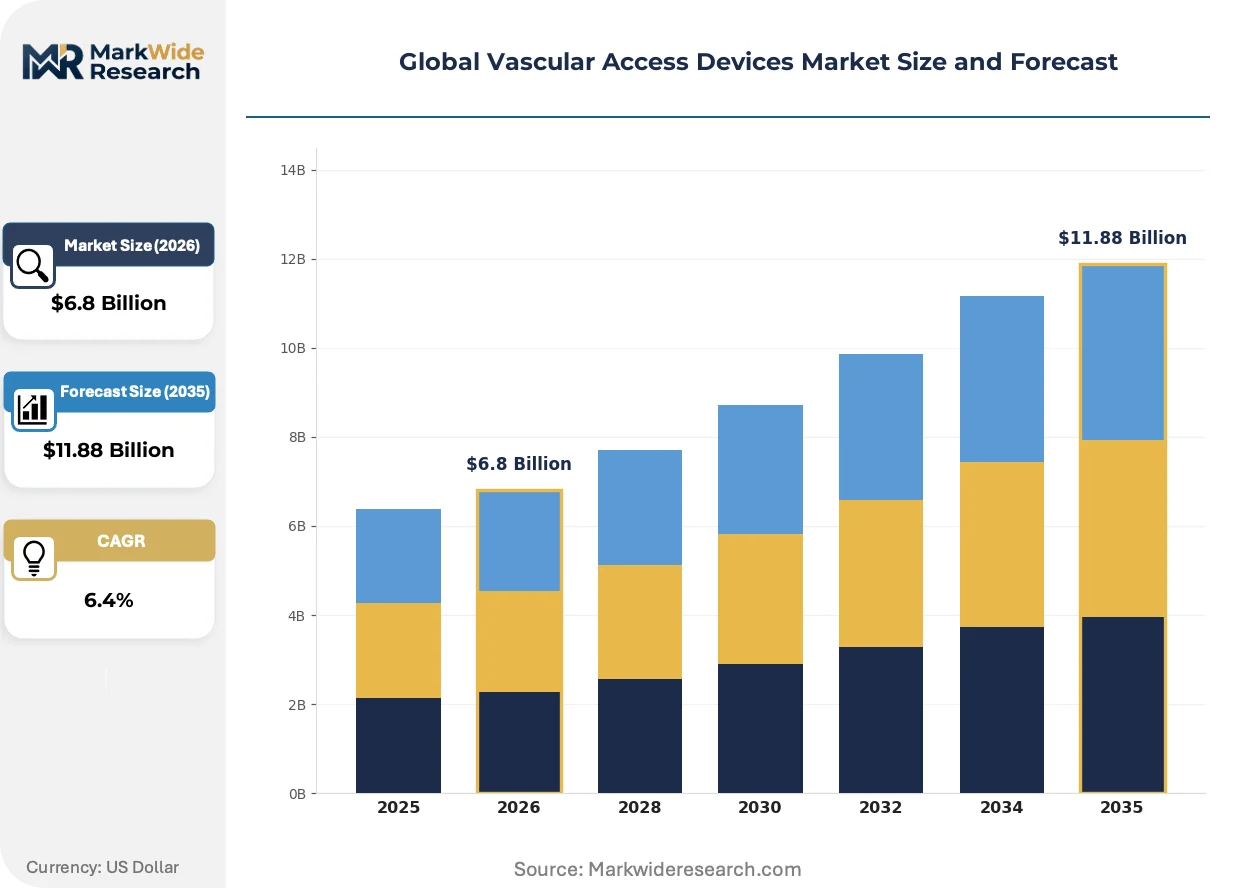
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peripheral Catheters, Central Venous Catheters, Implantable Ports, Dialysis Catheters, Introducer Sheaths Technology: Ultrasound Guidance, Power Injection, Antimicrobial Coating, Heparin Bonding, Flexible Materials Application: Drug Delivery, Hemodialysis, Blood Sampling, Parenteral Nutrition, Chemotherapy End User: Hospitals, Ambulatory Surgical Centers, Home Healthcare Providers, Specialty Clinics, Blood Banks |
| Companies Covered | Becton Dickinson and Company, Teleflex Incorporated, ICU Medical, Inc., B. Braun SE, Medtronic, Cook Medical, AngioDynamics, Inc., Terumo Corporation, Nipro Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vascular Access Devices Market Shifts & Advancements
Device manufacturers are engineering surface modifications and smart connector systems that transform catheter performance from passive tubing to active therapeutic interfaces.
Antimicrobial silver-ion and chlorhexidine coatings are rendering obsolete unprotected polyurethane central lines in intensive care settings. Hospital infection control committees in the United States and Germany now specify coated devices for patients with anticipated dwell times exceeding 48 hours. This specification shift compresses margins for manufacturers lacking bonded-surface capabilities.
Japan PMDA quality management system inspections are tightening documentation requirements for sterile barrier validation and pyrogen testing. Manufacturers must demonstrate continuous process verification across multiple production lots to maintain marketing authorization. European and North American suppliers with established quality infrastructure are capturing share from regional competitors facing compliance gaps.
Leasing-based procurement for infusion pump and catheter systems is displacing capital purchase models among United States ambulatory surgery centers and German outpatient oncology clinics. Third-party equipment financiers are bundling disposable catheter supply contracts with hardware placement agreements. This channel evolution concentrates purchasing influence among integrated delivery networks with centralized supply chain authority.
Global Vascular Access Devices Market Segmentation
Catheter selection criteria vary sharply across clinical settings. Device specifications, insertion protocols, and reimbursement pathways fragment procurement decisions into distinct technical and economic tiers that manufacturers must address separately.
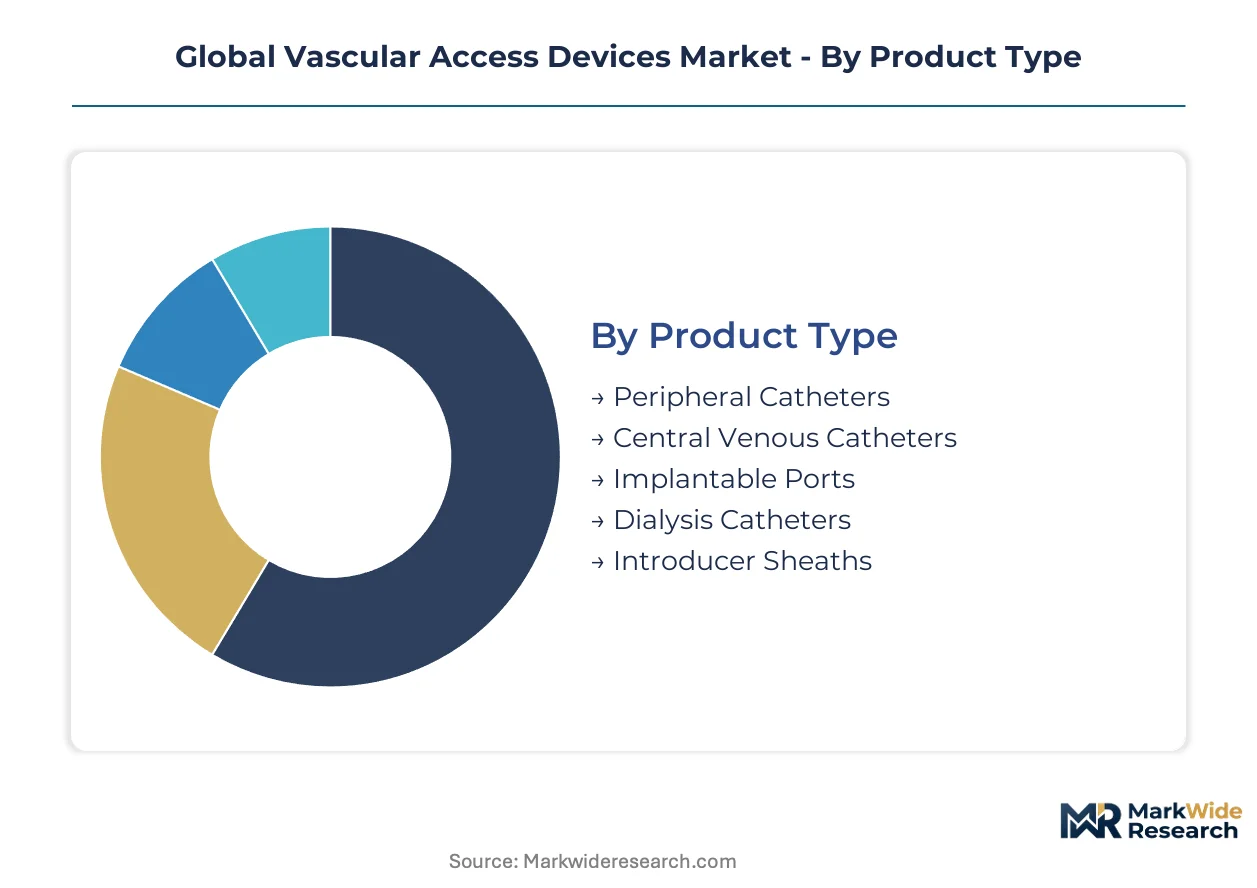
Product Type:
Cost tier differentiation separates commodity peripheral lines from premium central systems with integrated safety features.
- Peripheral Catheters:Short polyurethane or Teflon cannulas designed for superficial vein access and intermittent medication delivery. Demand concentrates in United States emergency departments where rapid turnover protocols favor single-use disposables over sterilization overhead.
- Central Venous Catheters:Multi-lumen silicone or polyurethane tubes engineered for extended dwell in vena cava or subclavian placement. German intensive care units specify antimicrobial-coated variants under ECDC hospital-acquired infection surveillance mandates, elevating coated product specifications.
- Implantable Ports:Subcutaneous reservoir systems connected to central veins for long-term intermittent access.
- Dialysis Catheters:High-flow dual-lumen devices optimized for hemodialysis exchange rates.
- Introducer Sheaths:Vascular entry conduits facilitating catheter exchange without repeated venipuncture.
Peripheral catheters command the established base. The steepest expansion runs through central venous catheters with bonded antimicrobial surfaces.
Technology:
Application requirements determine which performance layers providers will pay premium pricing to secure.
- Ultrasound Guidance:Real-time vascular visualization systems reducing landmark-based placement complications. United States academic medical centers embed probe systems into emergency department capital budgets, compressing training timelines for vascular access specialists.
- Antimicrobial Coating:Silver-ion, chlorhexidine, or antibiotic-impregnated surfaces suppressing biofilm formation. Japan PMDA quality management inspections now require continuous process verification for coating validation, favoring manufacturers with established sterile barrier infrastructure.
- Power Injection:Pressure-rated catheter construction enabling contrast-enhanced CT protocols.
- Heparin Bonding:Covalently attached anticoagulant surfaces reducing thrombotic occlusion rates.
- Flexible Materials:Advanced polymer formulations improving patient comfort during extended dwell.
Antimicrobial coating commands the established base. The steepest expansion runs through ultrasound guidance systems bundled with training protocols.
Application:
Volume concentration tracks the shift from inpatient administration toward outpatient infusion networks.
- Chemotherapy:Extended-dwell central access for cytotoxic agent administration with hazardous drug exposure controls. United States ambulatory oncology clinics specify closed-system transfer device integration, bundling needle-free connectors with antimicrobial catheters.
- Drug Delivery:General medication administration spanning antibiotics to analgesics across care settings. Home healthcare providers in Germany favor peripherally inserted central catheters with silicone elastomer advances that extend dwell times without replacement.
- Hemodialysis:Recurrent vascular access for renal replacement therapy.
- Blood Sampling:Diagnostic phlebotomy and hemodynamic monitoring.
- Parenteral Nutrition:Central venous delivery of complete nutritional formulations.
Drug delivery commands the established base. The steepest expansion runs through chemotherapy administration in scaled ambulatory networks.
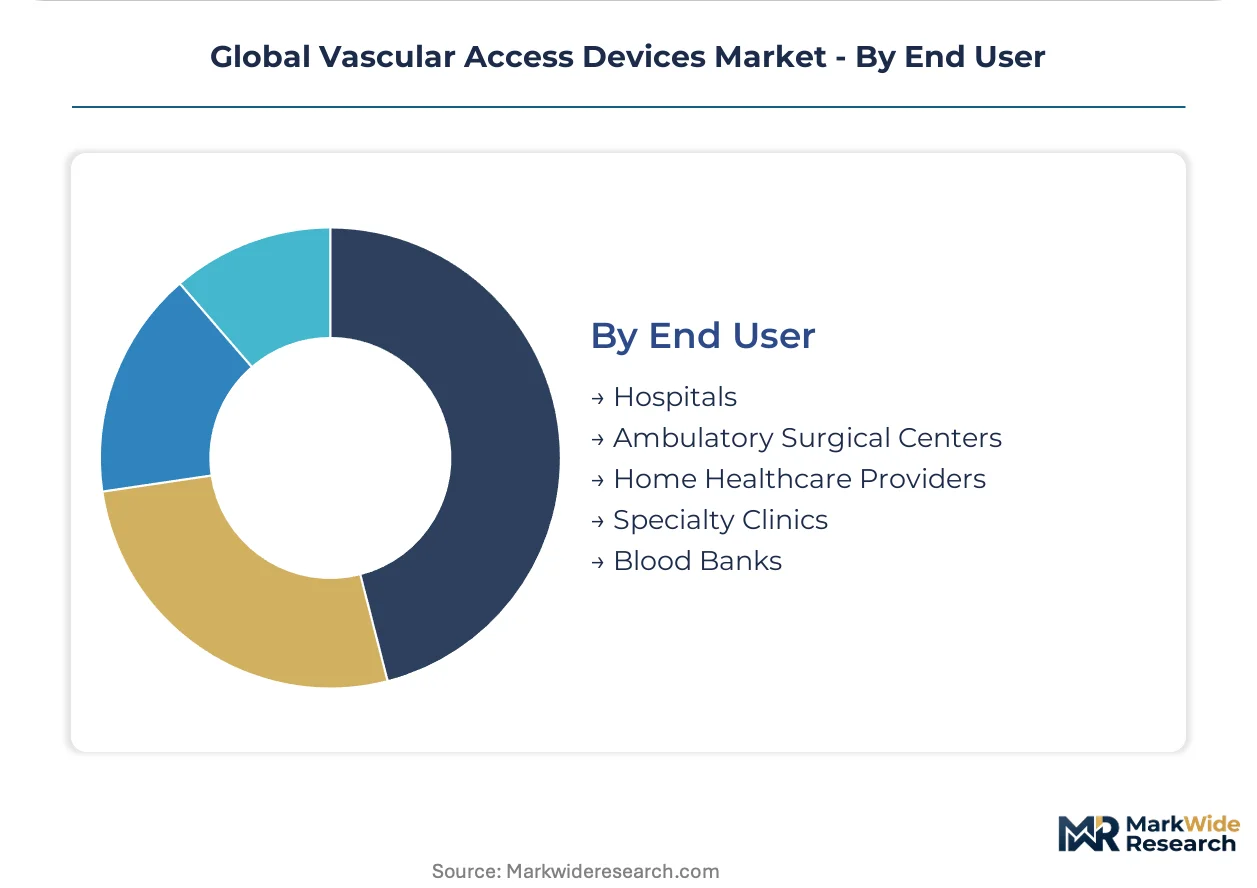
End User:
Customer type determines procurement authority concentration and capital versus operational expenditure preferences.
- Hospitals:Integrated inpatient facilities with infection control committees specifying coated devices for anticipated dwells exceeding 48 hours. FDA 510(k) clearance pathways and EU MDR technical documentation requirements compress viable supplier sets to manufacturers with dedicated regulatory infrastructure.
- Ambulatory Surgical Centers:Outpatient procedure facilities favoring leasing-based procurement for infusion pump and catheter systems. Third-party equipment financiers in the United States bundle disposable supply contracts with hardware placement agreements.
- Home Healthcare Providers:Residential care services managing long-term vascular access.
- Specialty Clinics:Focused oncology, dialysis, or infusion centers with concentrated procedure volumes.
- Blood Banks:Collection and processing facilities requiring large-bore apheresis access.
Hospitals command the established base. The steepest expansion runs through ambulatory surgical centers with centralized supply chain authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ambulatory infusion center networks in the United States, Germany, and Japan concentrate procurement authority for vascular access devices, while emerging markets in India and Brazil expand hospital infrastructure that absorbs mid-tier catheter portfolios.
United States
Leasing-based procurement models favor asset-light providers scaling outpatient oncology networks. FDA 510(k) clearance pathways compress viable supplier sets to manufacturers with dedicated regulatory infrastructure. Texas and Florida ambulatory surgery centers bundle disposable catheter contracts with third-party equipment financiers.
Germany
ECDC hospital-acquired infection surveillance mandates elevate antimicrobial-coated catheter specifications in intensive care units. EU MDR technical documentation requirements strain mid-sized manufacturers lacking clinical evidence generation capabilities. Bavarian medical device clusters concentrate coating validation expertise for premium product tiers.
Japan
PMDA quality management system inspections tighten sterile barrier validation requirements for silicone elastomer formulations. METI incentives for ISO 13485-certified manufacturers accelerate market entry for compliant foreign suppliers. Kanto region academic medical centers embed ultrasound-guided insertion systems into emergency department capital budgets.
India
Private hospital chain expansion and CDSCO regulatory harmonization create addressable white space for mid-tier device portfolios. Central government oncology infrastructure buildout concentrates demand in Maharashtra and Karnataka metropolitan corridors. Mumbai and Bangalore medical device distributors consolidate procurement influence for peripheral catheter volumes.
Brazil
ANVISA regulatory pathways for imported medical devices channel foreign manufacturer partnerships through São Paulo-based distributors. Public health system expansion in dialysis and chemotherapy administration absorbs central venous catheter volumes. Minas Gerais and Rio de Janeiro hospital networks specify coated devices under national infection control protocols.
Global Vascular Access Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidated supply relationships with integrated delivery networks in North America and Western Europe favor manufacturers with dedicated regulatory affairs infrastructure. Three archetypes dominate: diversified medical technology conglomerates with catheter line integration, regional specialists with coating or material expertise, and emerging Asian producers competing on cost-positioned peripheral lines. Competitive moves concentrate on antimicrobial surface technology licensing and ambulatory care channel partnerships.
Among diversified medical technology conglomerates, Becton Dickinson and Company and Medtronic occupy positions reflecting integrated manufacturing scale and deep channel relationships with United States integrated delivery networks. Terumo Corporation exemplifies the regional specialist archetype through its positioning in surface modification technologies. These three anchors represent distinct competitive vectors: conglomerate-scale bundling, coating specialization, and established quality infrastructure compliance.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Teleflex Incorporated |
| ICU Medical, Inc. |
| B. Braun SE |
| Medtronic |
| Cook Medical |
| AngioDynamics, Inc. |
| Terumo Corporation |
| Nipro Corporation |
| Others |
Supply & Pricing Matrix
Jiangsu province chemical manufacturing clusters anchor polyurethane feedstock capacity for medical-grade catheter production, translating upstream polymer availability into tiered pricing leverage for device manufacturers serving European and North American hospital systems.
Pricing Analysis
Cost-plus contracts with medical-grade polymer indexation dominate procurement between Asian chemical suppliers and catheter manufacturers. Pricing stratifies across premium antimicrobial-coated central lines, standard silicone peripherally inserted central catheters, and economy polyurethane peripheral cannulas. Cost compression in the economy tier is intensifying because low-cost Asian producers are expanding uncoated peripheral catheter volumes. Ambulatory surgery centers exhibit the highest price sensitivity due to leasing-based procurement models, while German intensive care units demonstrate the lowest sensitivity under ECDC infection control mandates.
Supply Chain Analysis
Upstream medical-grade polyurethane and silicone elastomer production concentrates in China, South Korea, and Japan. Device manufacturing draws from polymer feedstock, antimicrobial coating agents, and sterile barrier packaging materials. Single-source vulnerability runs through concentrated Asian chemical manufacturers for medical-grade thermoplastic polyurethane. Distribution runs through third-party equipment financiers bundling disposable catheter contracts with infusion pump placements in United States outpatient networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR antimicrobial efficacy mandates and Japan PMDA quality management tightening constitute a dual regulatory inflection that rewards manufacturers with pre-positioned compliance infrastructure.
For Market Incumbents: Build regulatory moats through dedicated EU MDR technical documentation capabilities and ISO 13485-certified sterile barrier validation infrastructure. Becton Dickinson and Terumo Corporation already anchor positions through bonded-surface technologies and heparin-coating expertise. Capacity addition in Bavarian medical device clusters addresses coating validation bottlenecks. Channel control through integrated delivery network partnerships in North America defends against emerging Asian cost competitors.
For New Entrants and Emerging Players: Build out mid-tier antimicrobial catheter portfolios targeting India's CDSCO-harmonized private hospital expansion in Maharashtra and Karnataka metropolitan corridors. The most penetrable geography sits in Brazil's ANVISA-regulated public health system dialysis and chemotherapy buildout. A go-to-market angle through São Paulo-based distributor partnerships channels foreign manufacturer access without direct regulatory infrastructure investment.
For Investors and Strategic Acquirers: Long-term, this sits as a compliance-premium play because regulatory barriers are compressing viable competitive sets to manufacturers with clinical evidence generation capabilities. Acquisition targets should surface among regional coating specialists with EU MDR-ready documentation packages. The signal to watch is CDC and ECDC antimicrobial resistance surveillance data revising reimbursement thresholds for premium device tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market entry for novel catheter platforms with predicate device pathways. |
| CE Marking Pathway | Unlocks European oncology ward procurement under ECDC infection surveillance mandates. |
| Hospital System Partnership | Secures volume commitments through GPO contracts with United States integrated delivery networks. |
| Software Companion Development | Enables ultrasound-guided insertion training protocols bundled with device placements. |
| Reimbursement Strategy | Aligns antimicrobial coating premiums with CMS and German DRG payment structures. |
Research Methodology
A spread of perspectives from vascular access specialists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, EU MDR technical documentation filings, hospital procurement contract registries, and Japanese PMDA quality management inspection records. Bottom-up catheter volume modeling triangulated with top-down market sizing across product type, technology layer, application setting, and end-user facility tier.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include catheter construction material, antimicrobial coating technology, insertion protocol complexity, and regional regulatory cluster. CAGRs were derived through regression analysis of historical procedure volumes and elasticity-adjusted price evolution. Industry-specific forecast inputs incorporated ECDC hospital-acquired infection surveillance trends and ambulatory infusion center expansion trajectories in the United States, Germany, and Japan.
Stress conditions across polyurethane feedstock price volatility, FDA 510(k) clearance timeline extension, and EU MDR recertification backlog were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about antimicrobial coating efficacy persistence and reimbursement threshold stability. Cross-checking against CDC bloodstream infection surveillance benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bionic Devices Market
Medical Devices
Global Mucosal Atomization Devices Market
Medical Devices
Veterinary Anesthesia Equipment Market
Medical Devices
North America Cataract Surgery Devices Market
Medical Devices
Global Medical Radiation Shielding Market
Medical Devices
Gastroretentive Drug Delivery Systems Market
Medical Devices
Implantable Pump Catheter Market
Medical Devices
Global Veress Needle Market
Medical Devices
Phoropters Market
Medical Devices
Asia-Pacific Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Low Flux Single-Use Dialyzers Market
Medical Devices
Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
South Africa Anti-Blue Ray Myopia Lenses Market
Medical Devices
Embolization Plugs Market
Medical Devices
Aortic Cannula Systems Market
Medical Devices
Global Insufflation Devices Market