
 Prefilled Syringes Market | 2026-2036
Prefilled Syringes Market Size, Share, and Industry Trends Forecast 2026-2036
Prefilled Syringes Market Analysis
Prefilled syringes are rotating toward high-barrier, ready-to-use formats as biologics manufacturers demand container closure integrity that matches the sensitivity of monoclonal antibody and cell therapy payloads. BD leverages backward integration into glass barrel forming and needle assembly to control quality at source. Gerresheimer AG differentiates through its pharmaceutical glass expertise and dedicated drug containment solutions. SCHOTT Pharma anchors European supply with its FIOLAX borosilicate glass platform, sustaining long-term contracts with top-20 pharma companies.
Prefilled syringes are single-dose injection systems pre-filled with medication by the manufacturer, typically constructed from borosilicate glass or cyclic olefin polymer with elastomeric plunger stoppers and rigid needle shields, designed to eliminate dosing errors and reduce preparation time in clinical settings. Glass syringes dominate oncology and autoimmune therapy areas where inert material contact surfaces prevent protein aggregation, while plastic formats are gaining traction in diabetes care for their break-resistance during patient self-administration. Home care end users represent the fastest-expanding segment as payors push for reduced hospitalization days and patients manage chronic conditions outside institutional settings.
The FDA enforces design controls and human factors requirements under 21 CFR Part 820 for combination product submissions, while the EU MDR mandates notified body oversight of syringe device classifications and post-market surveillance. ISO 11040 series standards govern dimensional interchangeability and functional testing, creating compliance thresholds that filter out smaller component suppliers. Stakeholders must monitor how FDA draft guidance on leachable and extractable studies reshapes elastomer selection and whether EU F-Gas Regulation constraints affect silicone oil alternatives for plunger lubrication.
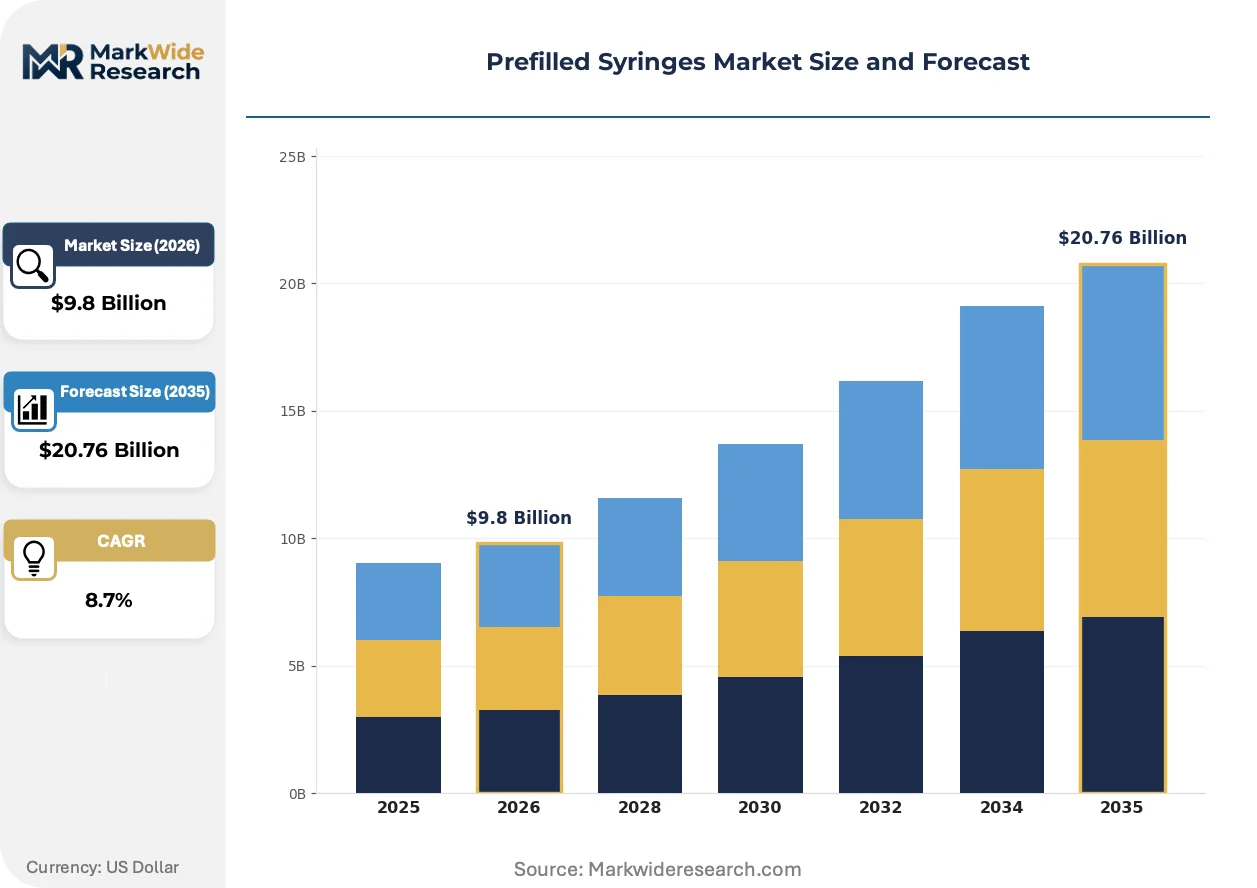
Market Dynamics
Biologics manufacturers are consolidating procurement around suppliers capable of integrated drug-device combination submissions, compressing vendor lists and elevating technical qualification barriers for component specialists.
Growth Catalysts
- EU MDR traceability mandates:Strengthened material documentation requirements accelerate replacement of legacy syringe formats with serialized, ready-to-use systems across European pharmaceutical packaging.
- Home-based injection therapies:Payers in the United States and Japan are expanding reimbursement for self-administered biologics, driving demand for patient-centric prefilled designs with ergonomic plunger systems.
- Cyclic olefin polymer (COP) barrier technology:Advanced resin formulations with low extractable profiles enable prefilled containment of sensitive cell therapies previously restricted to glass vials.
Market Restraints
- Borosilicate glass supply concentration:German and Japanese glass tubing suppliers control critical FIOLAX and equivalent feedstock, creating vulnerability to energy cost shocks or export licensing delays.
- Silicone oil lubrication dependency:Plunger functional requirements currently rely on dimethicone coatings facing scrutiny under EU F-Gas Regulation constraints on fluorinated compound alternatives.
- ISO 11040-4 functional testing costs:Dimensional interchangeability and glide force validation protocols impose capital-intensive metrology requirements that filter smaller molders from qualified supplier pools.
Strategic Opportunities
- Indian chronic disease management scale-up:CDSCO streamlined medical device registration pathways and government diabetes intervention programs create entry points for cost-optimized plastic prefilled formats.
- Connected injection ecosystems:Integration of NFC-enabled adherence sensors with prefilled syringe platforms enables pharmaceutical differentiation in value-based contracting with US payors.
- Cell therapy cold-chain formats:Cryogenic-compatible COP syringes with elastomer formulations rated to minus 80 degrees Celsius address emerging autologous therapy logistics requirements.
Industry Challenges
- Human factors engineering talent scarcity:Combination product submissions under FDA 21 CFR Part 820 require specialized usability study design capabilities that outpace current training pipeline output.
- Elastomer formulation IP thickets:Proprietary plunger stopper compositions and coating chemistries create licensing complexity for syringe assemblers seeking second-source qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prefilled Syringes Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.76 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Plastic, Biodegradable, Metal Therapy Area: Oncology, Autoimmune, Diabetes, Infectious Diseases End User: Hospitals, Home Care, Clinics, Research Institutions Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Sales |
| Companies Covered | BD, Gerresheimer AG, SCHOTT Pharma, West Pharmaceutical Services, Nipro Corporation, Stevanato Group, Terumo Corporation, Baxter, AptarGroup, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prefilled Syringes Market Emerging Trajectories
Container closure integrity specifications are tightening faster than material science can adapt, forcing concurrent evolution in barrier polymers, plunger coatings, and automated inspection systems.
Ready-to-use sterile syringes with integrated needle safety systems are displacing conventional staked-needle formats in oncology and autoimmune therapy segments. Hospital pharmacy buyers in Germany and the United States are specifying these systems to eliminate compounding steps and reduce needlestick injury liability. The shift is compressing demand for separate needle-attachment accessories and reshaping supplier R&D allocation toward closed-system designs.
The FDA's draft guidance on leachable and extractable studies for container closure systems is elevating analytical chemistry requirements for elastomer and adhesive selections. Pharmaceutical sponsors must now submit comprehensive migration profiles across accelerated aging conditions, extending qualification timelines by 12-18 months. Small-molecule injectable developers are responding by front-loading material compatibility studies earlier in formulation development cycles.
Self-administration training burden is shifting procurement criteria toward intuitive device design over unit cost minimization. Rheumatology and endocrinology practices in Japan are specifying prefilled syringes with audible dose-completion indicators and ergonomic thumb rests, displacing basic designs in formulary evaluations. This behavioral pivot rewards device differentiation and compresses price elasticity for undifferentiated commodity formats.
Prefilled Syringes Market Segmentation
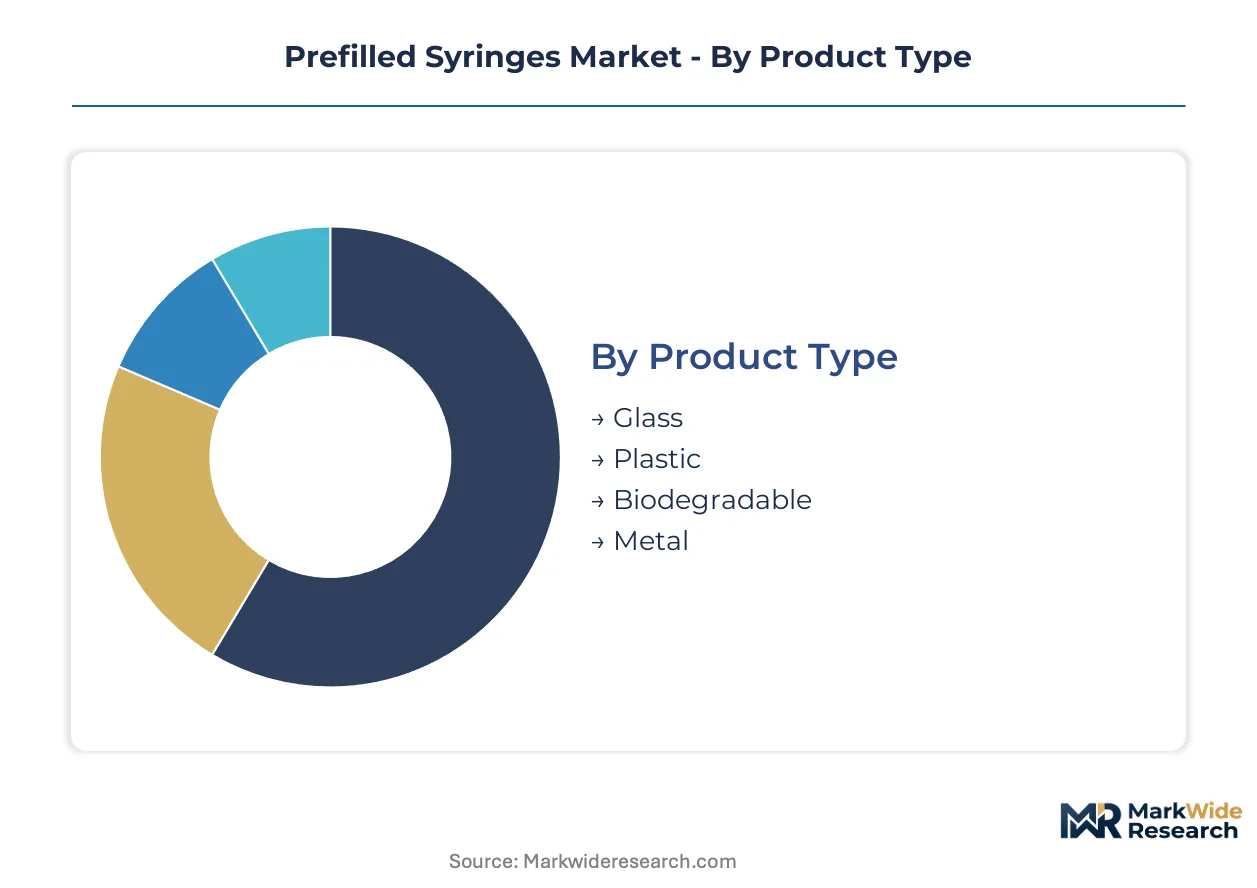
Segmentation in prefilled syringes reveals how material selection, clinical setting, and distribution economics create distinct competitive arenas. Each dimension carries different margin profiles and regulatory qualification barriers that reshape supplier positioning.
Product Type:
Glass syringes command premium margins in biologics containment where protein stability requirements justify higher unit costs, while plastic formats compete on scale economics in high-volume chronic disease management.
- Glass:Borosilicate glass barrels with FIOLAX or equivalent tubing provide inert contact surfaces that prevent monoclonal antibody aggregation. Oncology and autoimmune therapy manufacturers in Germany and the United States specify glass for parenteral biologics requiring extended shelf stability.
- Plastic:Cyclic olefin polymer (COP) and cyclic olefin copolymer (COC) resins deliver break-resistant containment for patient self-administration. Diabetes care programs in Japan are scaling COP adoption as payors expand home-based injection reimbursement.
- Biodegradable:Polylactic acid and starch-based polymers address single-use plastic reduction mandates under EU packaging regulations.
- Metal:Stainless steel barrel formats serve specialized industrial and veterinary applications requiring extreme durability.
The dominant share belongs to Glass, while Plastic is closing the gap fastest.
Therapy Area:
Volume concentration varies sharply across indications, with diabetes and oncology generating fundamentally different procurement rhythms and technical specifications.
- Oncology:Cytotoxic drug containment demands high-barrier glass with specialized elastomer formulations to prevent vapor permeation. Hospital pharmacy buyers in the United States specify ready-to-use formats to eliminate compounding exposure risks.
- Autoimmune:Rheumatology and dermatology practices require ergonomic plunger systems for patient self-injection. Japanese clinics prioritize audible dose-completion indicators in formulary evaluations.
- Diabetes:Insulin delivery systems favor plastic formats with integrated needle safety mechanisms for daily patient handling.
- Infectious Diseases:Vaccine prefilled formats emphasize cold-chain compatibility and multi-dose presentation efficiency.
Oncology retains the largest revenue pool, though Autoimmune applications are expanding most quickly as self-administered biologics proliferate.
End User:
Procurement authority and technical qualification requirements diverge significantly between institutional and non-institutional settings.
- Hospitals:Central pharmacy operations drive consolidated purchasing of ready-to-use sterile syringes with integrated safety systems. German hospital networks specify closed-system designs to reduce needlestick liability.
- Home Care:Patient-directed administration creates demand for intuitive device design over unit cost minimization. US payor reimbursement expansion for self-injected biologics is accelerating this segment's climb.
- Clinics:Outpatient infusion centers balance throughput efficiency with storage space constraints.
- Research Institutions:Clinical trial supply chains require serialized, temperature-monitored formats with comprehensive documentation packages.
Hospitals still capture the majority of unit volume, yet Home Care is gaining share fastest as chronic disease management decentralizes.
Distribution Channel:
Channel economics reflect diverging service intensity requirements and inventory risk allocation between manufacturers and intermediaries.
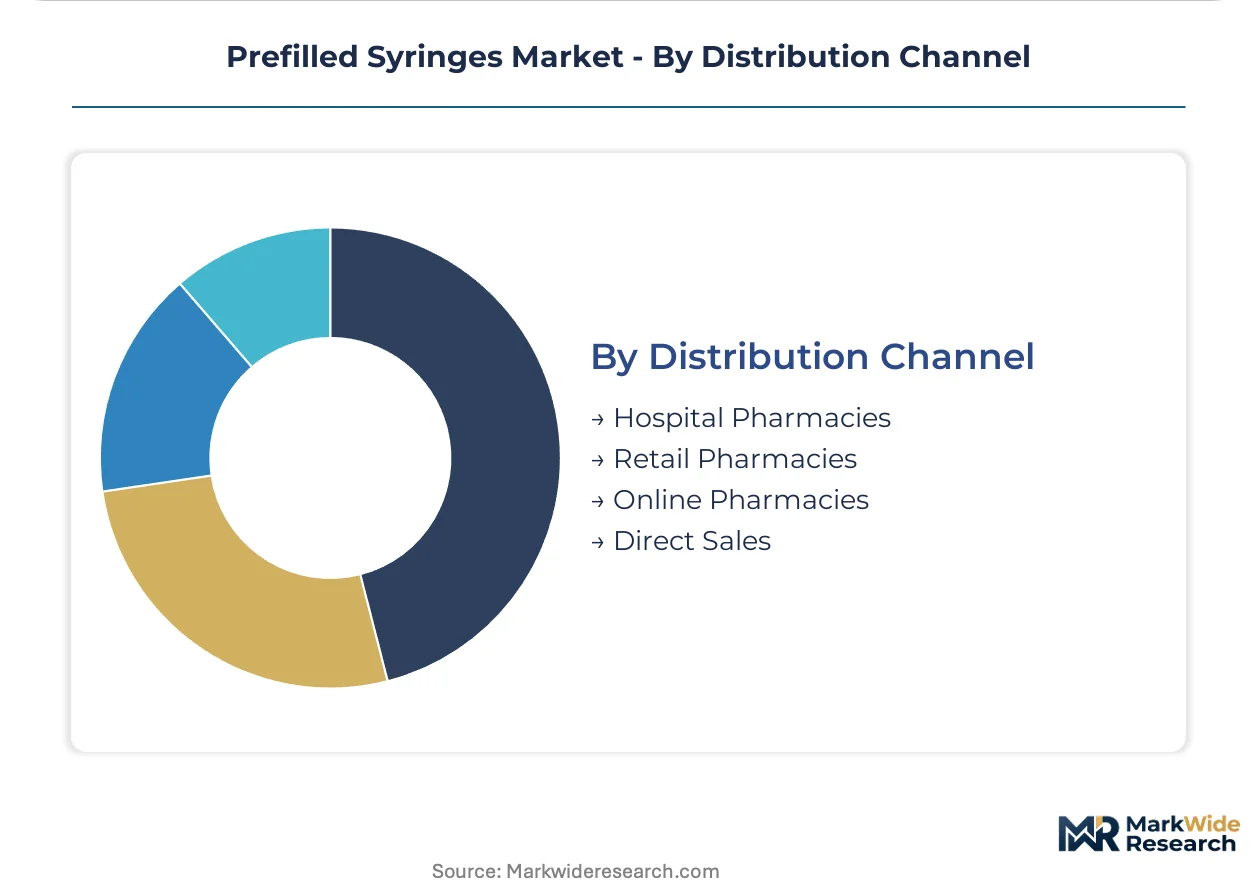
- Hospital Pharmacies:Direct contracting with integrated delivery networks concentrates volume among suppliers capable of consolidated just-in-time fulfillment. US health systems are tightening vendor lists to reduce qualification overhead.
- Retail Pharmacies:Dispensing of self-administered therapies creates demand for patient-centric packaging with storage condition labeling.
- Online Pharmacies:Direct-to-patient distribution models require cold-chain validated shipping configurations and tamper-evident seals.
- Direct Sales:Large pharmaceutical sponsors procure through dedicated supply agreements with backward-integrated component manufacturers.
Hospital Pharmacies maintain the deepest market penetration, while Online Pharmacies are climbing the fastest as digital health infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in prefilled syringes tilt toward manufacturing surplus in Germany and Japan against import dependency in the United States and India. Glass tubing feedstock flows from European and Japanese suppliers anchor regional production capabilities. Finished syringe trade routes concentrate through Rotterdam, Singapore, and Los Angeles distribution hubs serving pharmaceutical fill-finish networks.
United States
FDA combination product regulations and Medicare reimbursement expansion for home-based biologics drive procurement of patient-centric designs. The 21 CFR Part 820 quality system requirements filter supplier qualification to integrated device manufacturers. Boston and San Francisco biotech clusters source ready-to-use formats for clinical trial supply chains.
Germany
EU MDR traceability mandates accelerate replacement of legacy syringe formats with serialized systems across pharmaceutical packaging. FIOLAX borosilicate glass production in Mainz and Mitterteich sustains backward-integrated supply for European biologics manufacturers. The country's notified body infrastructure dominates CE marking oversight for syringe device classifications.
Japan
PMDA ergonomic requirements and aging population demographics expand self-injection reimbursement for rheumatology and diabetes therapies. METI industrial policy supports domestic COP resin formulation development for break-resistant patient formats. Osaka and Tokyo medical device clusters concentrate fill-finish capacity for Asia-Pacific distribution.
India
CDSCO streamlined medical device registration and government diabetes intervention programs create entry points for cost-optimized plastic formats. Import substitution policies encourage domestic molding capacity for insulin delivery systems. Gujarat and Maharashtra pharmaceutical zones attract contract manufacturing investment for export-oriented syringe assembly.
China
NMPA medical device classification reforms and biologics manufacturing scale-up drive demand for high-barrier containment systems. Domestic glass tubing suppliers in Shandong and Jiangsu challenge European feedstock dominance for standard therapeutic applications. Yangtze River Delta clusters integrate prefilled formats into mAb production workflows.
Prefilled Syringes Market Vendor Landscape
Concentration sits with backward-integrated glass specialists and diversified medical device conglomerates that control critical feedstock and assembly automation. Three archetypes dominate: borosilicate glass tubing manufacturers with captive syringe operations, full-service drug containment solution providers, and diversified medical technology multinationals with combination product expertise. Competitive moves center on capacity expansion in COP resin formulations and strategic partnerships for integrated drug-device submission capabilities.
Among diversified medical technology groups, BD exemplifies backward integration into glass barrel forming and needle assembly for quality control at source. Gerresheimer AG represents pharmaceutical glass expertise through dedicated drug containment solutions. SCHOTT Pharma anchors European supply with borosilicate glass platforms sustaining long-term contracts with top-tier pharmaceutical sponsors.
| Leading Market Players |
|---|
| BD |
| Gerresheimer AG |
| SCHOTT Pharma |
| West Pharmaceutical Services |
| Nipro Corporation |
| Stevanato Group |
| Terumo Corporation |
| Baxter |
| AptarGroup |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between biologics manufacturers and borosilicate glass tubing suppliers lock in both FIOLAX feedstock access and multi-year price visibility, insulating qualified vendors from spot market volatility while compressing margins for non-integrated assemblers. These contracts concentrate procurement power among backward-integrated players in Germany and Japan, forcing smaller molders to absorb residual price uncertainty in plastic formats.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with glass syringes for monoclonal antibody containment commanding ISO 11040-4 certification premiums while plastic COP formats compete on volume scale in diabetes care. Price differentiation hinges on elastomer formulation complexity and EU MDR traceability documentation depth. Cost compression in standard-tier plastic syringes is intensifying as Indian domestic molding capacity expands. Hospital pharmacy buyers exhibit lowest price sensitivity, prioritizing ready-to-use sterile formats with integrated needle safety over unit cost.
Supply Chain Analysis
Just-in-time fulfillment preferences among US health systems and German hospital networks contrast with strategic stockpiling of FIOLAX glass tubing by backward-integrated manufacturers to hedge against energy cost shocks. Geographic supply concentration centers on Germany, Japan, and China for borosilicate glass feedstock, with COP resin formulation anchored in Japanese and US chemical clusters. Raw material dependencies include dimethicone lubricants facing EU F-Gas Regulation scrutiny, elastomer stopper compounds, and serialized labeling substrates. Single-source vulnerability persists for pharmaceutical-grade glass tubing. Distribution runs through Rotterdam, Singapore, and Los Angeles hubs serving pharmaceutical fill-finish networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The prefilled syringes market sits at an inflection point where EU MDR traceability mandates and FDA leachable-extractable guidance are simultaneously elevating technical barriers and consolidating procurement around integrated suppliers capable of combination product submissions.
For Market Incumbents: Shield market position through captive supply of FIOLAX-equivalent glass tubing and needle assembly automation, while accelerating COP resin formulation R&D to offset silicone oil dependency risks under EU F-Gas constraints. Defensive consolidation of elastomer stopper IP through licensing partnerships will block second-source qualification attempts by emerging assemblers. For New Entrants and Emerging Players: Differentiate on cryogenic-compatible COP formats for cell therapy cold-chain logistics, where incumbent glass dominance weakens at minus 80 degrees Celsius operational requirements. White-space concentration in Indian diabetes intervention programs and connected injection ecosystems with NFC adherence sensors offers penetrable entry points. Pursue CDSCO registration pathway partnerships with Gujarat-based contract manufacturers to establish cost-optimized production footprints. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with validated COP barrier technology and existing FDA 510(k) submission track records, positioned for acquisition by diversified medical device conglomerates seeking combination product capabilities. Long-term viability favors suppliers with dual glass-plastic material expertise spanning biologics and chronic disease management segments. Monitor FDA draft guidance finalization on leachable-extractable studies as the critical signal for accelerated elastomer supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass Tubing | Captive FIOLAX supply secures qualification priority with top-20 pharmaceutical sponsors under EU MDR. |
| COP Resin Formulation Expansion | Advanced barrier polymers address cell therapy containment requirements previously restricted to glass vials. |
| Integrated Drug-Device Submission Partnerships | Combined 21 CFR Part 820 compliance accelerates biologics manufacturer vendor consolidation decisions. |
| Connected Injection Ecosystem Development | NFC-enabled adherence sensors enable pharmaceutical differentiation in US payor value-based contracting. |
| Cryogenic-Compatible Elastomer Qualification | Minus 80 degrees Celsius plunger formulations unlock autologous therapy logistics revenue streams. |
Methodological Framework
A spread of perspectives from biologics manufacturing executives, regulatory affairs specialists, hospital pharmacy procurement directors, and GPO contracts managers converged on the working assumptions underlying this analysis. Primary field engagement combined with secondary validation from FDA 510(k) filings, EMA CE marking databases, ISO 11040 standard documentation, and hospital procurement contract records. Bottom-up demand modeling across therapy areas and top-down supply capacity assessments were triangulated to establish market sizing boundaries.
Segmentation dimensions modeled include material type, therapy area, end-user setting, and distribution channel across the projection horizon. Analytical framework development incorporated patient population growth trajectories, reimbursement policy shifts, and regulatory timeline assumptions. CAGRs were derived from weighted scenario analysis of biologics pipeline expansion and chronic disease management decentralization trends. Industry-specific forecast inputs captured elastomer formulation qualification timelines and CDSCO registration pathway velocity.
Forecasts assume regulatory continuity in FDA 21 CFR Part 820 enforcement, EU MDR traceability implementation, and PMDA ergonomic requirements; material policy shifts in F-Gas Regulation scope or silicone oil alternatives would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spinal Thoracolumbar Implants Market
Medical Devices
Anti-Aging Devices Market
Medical Devices
Global Doppler Ultrasound Systems Market
Medical Devices
India Minimally Invasive Surgery Devices Market
Medical Devices
Brain-On-Chip Model Market
Medical Devices
Additional Defibrillator Accessories (AED) Market
Medical Devices
Gutta Percha Obturator Market
Medical Devices
Pectus Bar Market
Medical Devices
Europe Organ-On-Chip Market
Medical Devices
C-Arms Devices Market
Medical Devices
Single Use Contact Lenses Market
Medical Devices
Global Medical Injection Molding Market
Medical Devices
Low Flux Single-Use Dialyzers Market
Medical Devices
LASIK Eye Surgery Devices Market
Medical Devices
Global Vaginal Sling Market
Medical Devices
Global Hi-Tech Medical Devices Market