
 South America Fetal and Neonatal Monitoring Market | 2026-2036
South America Fetal and Neonatal Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
South America Fetal and Neonatal Monitoring Market Analytics
Buyer consolidation among Brazil's public hospital networks is restructuring procurement dynamics across the South America fetal and neonatal monitoring landscape. GE Healthcare leverages its installed base of maternal-fetal monitors to sustain service contract renewals in São Paulo's state hospital system. Philips Healthcare anchors its position through localized technical training programs that bind maternity centers to its digital sensor ecosystems.
Fetal and neonatal monitoring encompasses electronic systems that track maternal uterine activity, fetal heart rate, and neonatal vital signs through transducer-based signal acquisition, with typical monitoring frequencies spanning 1-20 Hz for cardiotocography and pulse oximetry wavelengths near 660-940 nm for oxygen saturation assessment. These devices serve the clinical imperative of detecting fetal hypoxia, uterine hyperstimulation, and neonatal respiratory compromise before irreversible injury occurs. Ultrasound devices and fetal monitors occupy the dominant hardware positions, while software solutions represent the fastest-expanding margin pool as hospitals integrate AI-assisted interpretation of cardiotocographic patterns. Wireless monitoring technology differentiates premium offerings, though portable devices compete aggressively for clinic-based point-of-care deployments across mid-tier municipalities.
ANVISA governs medical device registration and post-market surveillance for fetal monitors in Brazil, while Argentina's national pharmaceutical regulator enforces comparable safety standards for neonatal intensive care equipment importation. Both frameworks mandate clinical evidence packages that extend product commercialization timelines but elevate barrier-to-entry protection for established suppliers. Stakeholders must monitor how pending harmonization between Mercosur medical device technical regulations reshapes cross-border certification burdens and distributor qualification requirements.
Market Dynamics
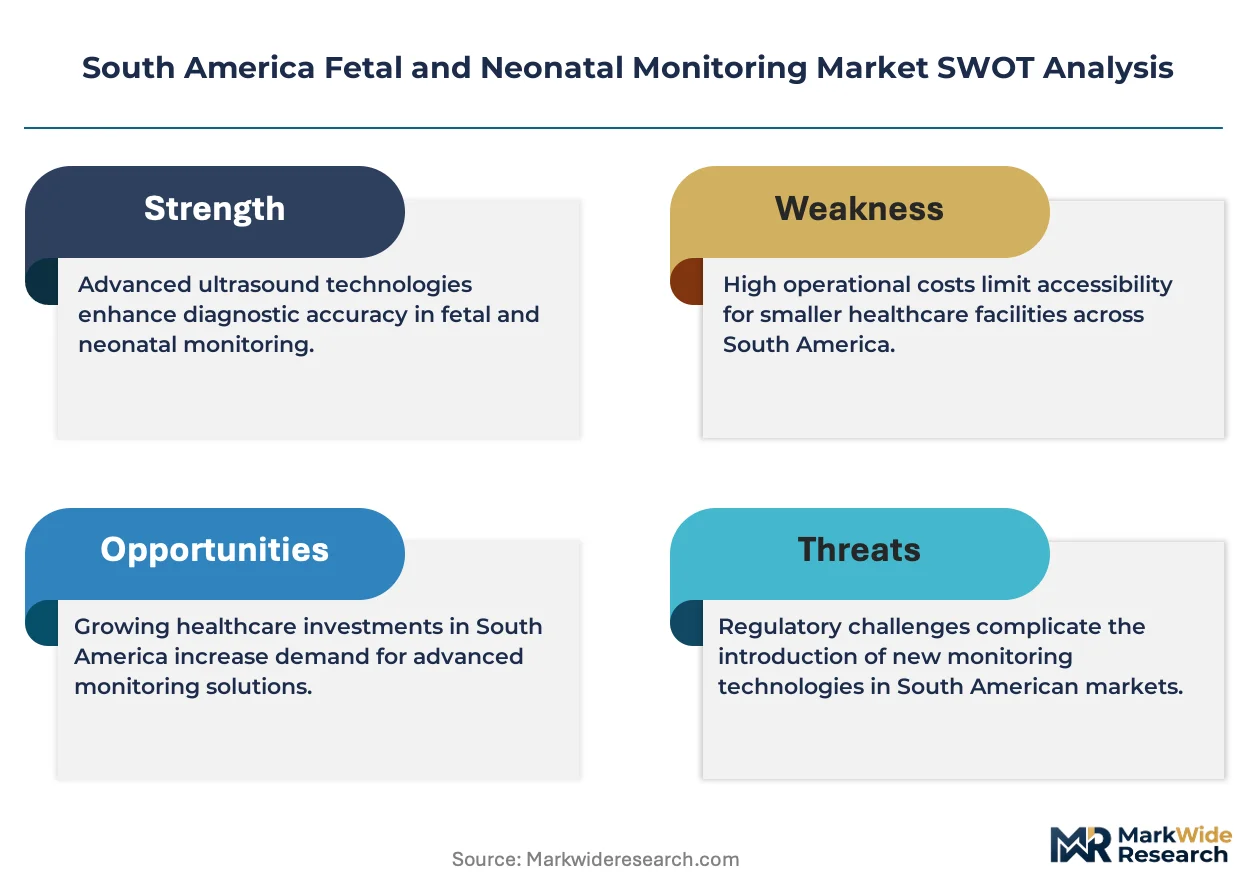
Hospital procurement network consolidation across Brazil and Argentina is compressing vendor margins while elevating technical service capabilities as the primary competitive differentiator in maternal-fetal monitoring equipment sourcing.
Growth Catalysts
- ANVISA registration pathway modernization:Brazil's medical device regulator has streamlined digital prenatal technology approvals, reducing commercialization timelines for wireless monitoring systems and accelerating hospital adoption cycles.
- Tertiary maternity center infrastructure replacement:Brazil's southeastern hospital corridor is executing systematic upgrade programs for cardiotocography suites, driven by equipment obsolescence and clinical quality mandates.
- Wireless telemetry integration:Cordless fetal monitoring transducers are displacing wired legacy systems in high-acuity labor and delivery units, enabling ambulatory patient monitoring during active labor.
Market Restraints
- Import dependency for sensor components:South American manufacturers rely on Asian suppliers for pulse oximetry emitters and ultrasound transducers, exposing procurement costs to currency volatility and logistics disruption.
- Clinical evidence package requirements:ANVISA and Argentina's national pharmaceutical regulator mandate extensive safety documentation that extends product registration timelines beyond eighteen months for novel monitoring modalities.
- Disposable electrode cost structure:Recurring expenditure on single-use fetal scalp electrodes and maternal abdominal transducers creates operational budget pressure for public hospital networks with constrained capital allocation.
Strategic Opportunities
- Mid-tier municipality clinic penetration:Portable fetal monitoring devices face limited competition in Brazil's interior states and Argentine provincial health systems where infrastructure investment lags coastal corridors.
- AI-assisted cardiotocography interpretation:Machine learning pattern recognition for fetal heart rate variability analysis is converging with cloud-based data platforms to create subscription revenue streams beyond hardware sales.
- Mercosur regulatory harmonization:Pending technical regulation alignment will enable single certification pathways across Brazil, Argentina, Paraguay, and Uruguay, reducing cross-border distributor qualification burdens.
Industry Challenges
- Biomedical engineering specialist scarcity:Maintenance and calibration of digital sensor ecosystems requires technicians with combined ultrasound and networking expertise that training institutions in the region produce insufficiently.
- Legacy system integration complexity:Hospital information system interoperability with proprietary fetal monitor data protocols demands custom interface development that prolongs deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Fetal and Neonatal Monitoring Market |
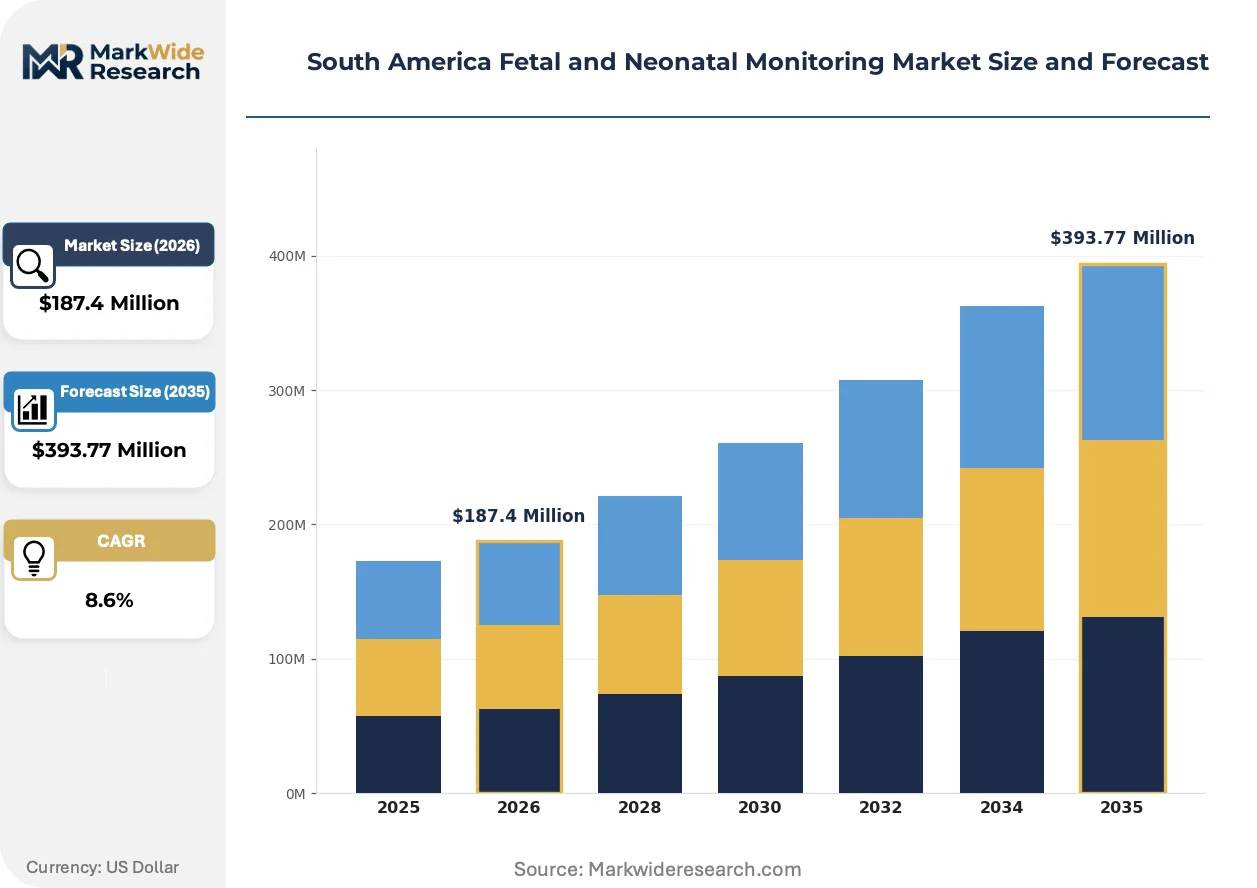
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound Devices, Fetal Monitors, ECG Monitors, Temperature Monitors Technology: Wireless Monitoring, Portable Devices, Digital Sensors, Software Solutions End User: Hospitals, Clinics, Home Care, Maternity Centers Application: Prenatal Monitoring, Labor Monitoring, Postnatal Care, Emergency Care |
| Companies Covered | GE Healthcare, Philips Healthcare, Medtronic, Nihon Kohden Corporation, Drägerwerk AG & Co. KGaA, Siemens Healthineers, Natus Medical Incorporated, Cardinal Health, Becton Dickinson, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Fetal and Neonatal Monitoring Market Evolving Landscape
Digital sensor miniaturization and cloud-native software architectures are restructuring how maternal-fetal data flows from bedside acquisition to centralized clinical decision support, compressing the traditional hardware-software boundary.
Artificial intelligence pattern recognition for cardiotocographic trace interpretation is automating preliminary assessment of fetal heart rate variability, deceleration classification, and uterine contraction analysis. Tertiary maternity centers in São Paulo and Buenos Aires are piloting these systems to reduce interpreter fatigue during extended labor monitoring. The technology is automating routine screening functions while preserving clinician oversight for abnormal pattern flagging, effectively redistributing specialist attention toward high-risk cases.
ANVISA's updated software-as-a-medical-device guidance is reclassifying AI-enabled monitoring analytics as regulated products requiring standalone clinical validation. Manufacturers must now submit algorithm performance datasets and update protocols for post-deployment modifications. Brazilian hospital procurement networks are responding by requiring documented regulatory clearance for integrated software modules prior to contract award.
Consolidated purchasing decisions by Brazil's state hospital systems are displacing fragmented municipal procurement, concentrating annual contract volumes with suppliers capable of multi-site service coverage. São Paulo's state health secretariat now coordinates fetal monitor standardization across forty-seven maternity facilities, replacing individual hospital vendor selection. This concentration is most visible in southeastern Brazil where tertiary center networks dominate regional birth volume and equipment replacement cycles.
South America Fetal and Neonatal Monitoring Market Segmentation
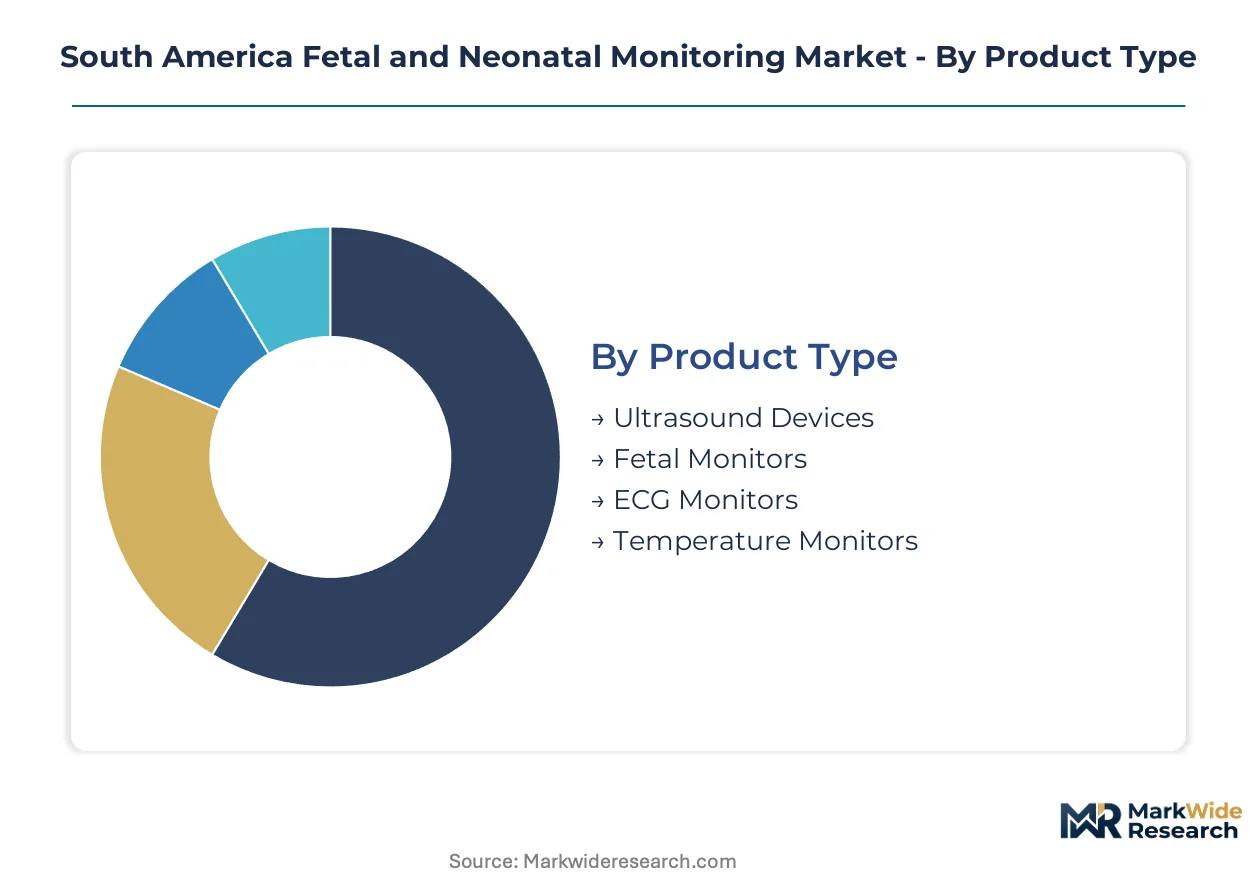
Product differentiation in South America's fetal and neonatal monitoring market determines procurement pathways, service contract structures, and technology migration timelines across public and private healthcare networks. Understanding segment boundaries illuminates where vendor consolidation concentrates and where specialized entrants retain footholds.
Product Type:
Supply concentration among multinational manufacturers tilts installed base composition toward systems with established service infrastructure across Brazil and Argentina's major maternity corridors.
- Ultrasound Devices:Doppler-based fetal imaging systems operating at 2-10 MHz frequencies dominate first-trimester screening and biometric assessment workflows. São Paulo's state hospital network drives replacement demand for portable ultrasound platforms with integrated biometric calculation packages.
- Fetal Monitors:Cardiotocography systems combining tocodynamometer and ultrasound transducer inputs constitute the core hardware investment in tertiary labor and delivery units. Brazil's southeastern hospital corridor executes systematic upgrade cycles for wireless telemetry-enabled suites.
- ECG Monitors:Neonatal electrocardiography systems with 3-lead and 12-lead configurations support cardiac surveillance in intensive care settings.
- Temperature Monitors:Continuous skin-surface and core temperature tracking devices serve thermoregulation management in premature infant care.
Fetal monitors absorb the bulk of installed capacity; ultrasound devices are expanding most quickly through point-of-care deployment in mid-tier municipalities.
Technology:
Cost tier differentiation separates premium wireless installations from economy portable configurations, with margin structure varying sharply across technology layers.
- Wireless Monitoring:Cordless transducer systems operating on proprietary 2.4 GHz or 5 GHz protocols eliminate cable constraints during ambulatory labor. Tertiary maternity centers in Brazil's southeastern corridor prioritize these platforms for patient mobility and infection control.
- Portable Devices:Battery-operated fetal monitors with integrated displays serve outreach programs and secondary clinic networks where fixed infrastructure investment is constrained.
- Digital Sensors:MEMS-based accelerometers and pressure transducers enable miniaturized signal acquisition with reduced calibration drift.
- Software Solutions:Cloud-native platforms for cardiotocography storage, remote consultation, and AI-assisted pattern interpretation represent the fastest-climbing margin pool as hospitals seek subscription revenue models beyond hardware procurement.
Wireless monitoring commands premium pricing in high-acuity settings; software solutions are gaining share fastest through recurring revenue conversion.
End User:
Volume concentration in hospital procurement networks shapes vendor qualification requirements and service coverage expectations across the customer base.
- Hospitals:Tertiary and secondary acute care facilities with dedicated maternity and neonatal intensive care units generate the dominant equipment demand. Brazil's consolidated state hospital procurement systems concentrate annual contract volumes with suppliers capable of multi-site technical service coverage.
- Clinics:Outpatient prenatal care facilities and smaller maternity units in Brazil's interior states and Argentine provinces operate with constrained capital budgets.
- Home Care:Remote fetal monitoring services for high-risk pregnancies represent an emerging delivery channel with limited current infrastructure penetration.
- Maternity Centers:Standalone birth centers and private maternity facilities outside hospital systems pursue differentiated technology configurations emphasizing patient experience.
Hospitals absorb the bulk of installed capacity; clinics are expanding most quickly through portable device penetration in underserved geographies.
Application:
Maturity gradients across the clinical workflow separate established monitoring modalities from emerging technology insertion points.
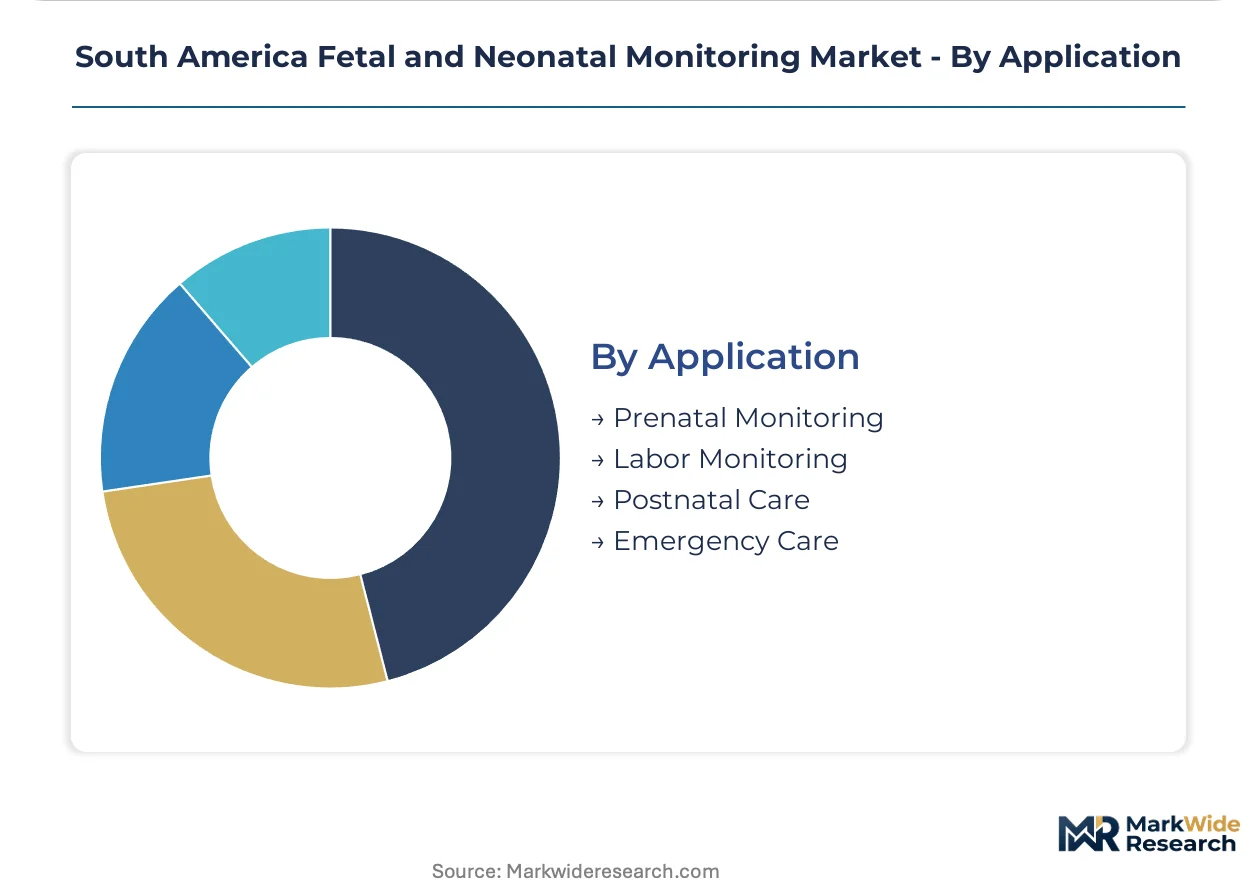
- Prenatal Monitoring:Routine fetal assessment through ultrasound biometry and Doppler flow studies occurs across outpatient and inpatient settings. ANVISA's streamlined digital prenatal technology approvals are compressing commercialization timelines for novel monitoring modalities entering this application.
- Labor Monitoring:Continuous cardiotocography during active labor and delivery represents the most intensive monitoring period with highest sensor density per patient. Wireless telemetry integration is displacing wired legacy systems in high-acuity labor units across São Paulo and Buenos Aires tertiary centers.
- Postnatal Care:Neonatal vital sign surveillance in nursery and intensive care settings extends monitoring into the immediate postpartum period.
- Emergency Care:Rapid fetal assessment in obstetric emergency departments and transport scenarios demands portable, rapid-deployment configurations.
Labor monitoring absorbs the bulk of installed capacity; prenatal monitoring is climbing the fastest through AI-assisted screening platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sensor component supply chains for pulse oximetry emitters and ultrasound transducers concentrate in East Asian manufacturing clusters, exposing South American procurement networks to currency volatility and logistics disruption. Brazil's southeastern hospital corridor absorbs the dominant share of regional equipment demand, while Argentine provincial systems and Andean markets operate with constrained capital allocation cycles.
Brazil
Tertiary maternity centers across São Paulo, Rio de Janeiro, and Minas Gerais drive replacement demand for wireless cardiotography suites. ANVISA's streamlined digital prenatal technology approvals compress commercialization timelines for novel monitoring modalities entering the market. São Paulo's state health secretariat coordinates standardized procurement across forty-seven maternity facilities, consolidating annual contract volumes with multi-site service providers.
Argentina
Provincial health systems in Buenos Aires, Córdoba, and Santa Fe maintain fragmented municipal procurement structures for neonatal intensive care equipment. The national pharmaceutical regulator enforces clinical evidence packages that extend product registration timelines beyond eighteen months for imported monitoring systems. Buenos Aires anchors demand concentration, with tertiary centers executing selective upgrade cycles for labor and delivery infrastructure.
Chile
Santiago's metropolitan hospital network generates concentrated demand for portable fetal monitoring devices serving outreach programs in underserved municipalities. The national medical device regulator maintains alignment with international standards that facilitate importation of European and North American monitoring platforms. Northern mining regions and southern territorial health services represent emerging deployment channels for point-of-care prenatal assessment.
Colombia
Bogotá and Medellín anchor procurement concentration for cardiotocography systems across public hospital networks and private maternity facilities. The national food and drug surveillance institute oversees medical device registration pathways that mandate local clinical validation studies for novel monitoring technologies. Caribbean and Pacific coastal provinces present underpenetrated opportunities for portable device deployment in clinic-based prenatal care.
Peru
Lima's metropolitan health system concentrates demand for neonatal vital sign surveillance equipment in public maternity hospitals. The national health authority's medical device regulatory framework requires import registration that extends commercialization timelines for wireless monitoring platforms. Andean highland regions and Amazonian territorial health services operate with infrastructure constraints that favor portable, battery-operated monitoring configurations.
South America Fetal and Neonatal Monitoring Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-enabled service models that convert hardware placements into recurring subscription revenue. The market structure consolidates around multinational manufacturers with established service infrastructure across Brazil and Argentina's major maternity corridors. Three archetypes dominate: integrated healthcare conglomerates leveraging installed base advantages, specialized maternal-fetal monitoring pure-plays, and diversified medical technology suppliers cross-selling from adjacent diagnostic portfolios. Competitive dynamics center on multi-site service coverage contracts and AI-assisted interpretation software integration rather than pure hardware differentiation.
Among diversified healthcare technology conglomerates, GE Healthcare and Philips Healthcare exemplify archetypes built on installed base leverage and localized technical training ecosystems. Siemens Healthineers occupies a position bridging diagnostic imaging heritage with maternal-fetal monitoring portfolio extension. These three anchors represent how scale-driven service infrastructure and regulatory navigation capabilities determine procurement network access across consolidated Brazilian state hospital systems and Argentine provincial health structures.
| Leading Market Players |
|---|
| GE Healthcare |
| Philips Healthcare |
| Medtronic |
| Nihon Kohden Corporation |
| Drägerwerk AG & Co. KGaA |
| Siemens Healthineers |
| Natus Medical Incorporated |
| Cardinal Health |
| Becton Dickinson |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between ANVISA-cleared wireless telemetry suites and uncertified portable alternatives manifests in both procurement premiums and supply chain qualification burdens across Brazilian and Argentine hospital networks. Three-tier pricing structure across premium, standard, and economy levels reflects service bundling intensity, with premium tiers incorporating multi-site technical coverage and AI software modules while economy configurations trade warranty depth for upfront capital relief.
Pricing Analysis
Warranty and service contract bundling separates premium fetal monitor procurement from unbundled equipment-only transactions common in mid-tier municipality clinics. Pricing stratifies across premium, standard, and economy tiers based on ANVISA registration tier and wireless telemetry capability, with premium installations commanding substantial service premiums. Cost compression in the standard tier is intensifying because consolidated state hospital procurement networks extract volume discounts. Public hospital networks exhibit highest price sensitivity due to constrained capital allocation cycles, while private maternity centers in São Paulo demonstrate lowest sensitivity to upfront hardware costs.
Supply Chain Analysis
Dual-sourcing requirements for pulse oximetry emitters and ultrasound transducers mandate multi-supplier qualification across East Asian manufacturing clusters in China, South Korea, and Taiwan. Raw material dependencies center on MEMS accelerometers, 660-940 nm LED emitters, and piezoelectric ceramic substrates. Single-source vulnerability concentrates in specialized ultrasound transducer fabrication, exposing Brazilian manufacturers to logistics disruption. Distribution runs through authorized distributor networks with ANVISA import registration credentials, concentrating downstream channel control with established multinational service infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over AI-assisted interpretation software and captive sensor calibration capabilities determines margin capture across hardware replacement cycles.
For Market Incumbents: To counter software-enabled entrant disruption, anchor installed base retention through backward integration into cloud-native data platforms and captive technical training academies in São Paulo. Prioritize multi-site service coverage contracts with consolidated state hospital procurement networks to elevate switching costs. Lock sensor calibration protocols into proprietary ecosystems that bind maternity centers to replacement part flows. For New Entrants and Emerging Players: Begin with portable fetal monitor deployment in Brazil's interior states and Argentine provincial health systems where infrastructure investment lags coastal corridors. Target clinic-based point-of-care prenatal monitoring in underserved geographies with battery-operated configurations priced below wireless telemetry suites. Pursue ANVISA registration pathway partnerships with established distributors to compress commercialization timelines. For Investors and Strategic Acquirers: Re-rating potential sits with software-pure-play specialists given ANVISA's reclassification of AI-enabled cardiotocography analytics as standalone regulated products. Long-term viability over a multi-year horizon favors acquisition targets with validated algorithm performance datasets and hospital system pilot deployments. Monitor ANVISA software-as-a-medical-device clearance velocity as the critical inflection indicator for subscription revenue conversion timelines.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Software-as-a-Medical-Device Registration | Secures standalone clearance for AI-assisted cardiotocography interpretation modules before hospital contract awards. |
| Hospital System Partnership | Locks multi-site service coverage with São Paulo's consolidated state procurement network across forty-seven maternity facilities. |
| Backward Integration into Sensor Calibration | Captures recurring revenue from proprietary transducer replacement flows and reduces third-party component dependency. |
| Technical Training Academy Deployment | Binds maternity centers to vendor ecosystems through localized biomedical engineering certification programs. |
| Cloud-Native Data Platform Launch | Enables subscription conversion from hardware sales through remote cardiotocography storage and AI pattern recognition. |
Research Methodology
Multi-period observation of ANVISA registration timelines, hospital procurement consolidation patterns, and wireless telemetry adoption rates anchored the trend analysis, supplemented by interviews with biomedical engineering directors, GPO contracts managers, and maternal-fetal medicine specialists across Brazil and Argentina. Secondary validation drew from ANVISA medical device registration databases, hospital procurement disclosure records, and Mercosur technical regulation harmonization documents. Bottom-up equipment shipment tracking and top-down healthcare expenditure modeling were triangulated to constrain volume estimates.
Segment-weighting across product type, technology tier, end-user concentration, and application maturity shaped the analytical framework over the projection horizon. Modeled dimensions included wireless versus portable configurations, tertiary versus clinic settings, and AI-enabled versus conventional interpretation workflows. CAGRs were derived from logistic diffusion curves fitted to replacement cycle data and procurement budget elasticity parameters specific to Brazilian state health secretariat allocation patterns.
Regulatory clearance delays, currency volatility in sensor component importation, and biomedical engineering specialist scarcity are the dominant revision risks to the forecast outlook. Deviation in ANVISA software-as-a-medical-device guidance implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Fetal Heart Rate Monitoring Devices Market
Patient Monitoring
Non-Invasive Respiratory Monitoring Market
Patient Monitoring
Monitoring Wristband Market
Patient Monitoring
Real Time Health Monitoring Devices Market
Patient Monitoring
Hemoglobin Monitor Market
Patient Monitoring
ICU ECG Patient Monitor Market
Patient Monitoring
ECG Monitoring System Market
Patient Monitoring
South America Hemodynamic Monitoring Market
Patient Monitoring
Germany Patient Care Monitoring Equipment Market
Patient Monitoring
Global Ambulatory Blood Pressure Monitoring (ABPM) Devices Market
Patient Monitoring
Contact-Free Sleep Monitoring Systems Market
Patient Monitoring
MRI Pulse Oximeters Market
Patient Monitoring
Coronary Pressure Monitors Market
Patient Monitoring
Global Cardiac Monitoring and Cardiac Rhythm Management Device Market
Patient Monitoring
South America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
North America Wearable Ambulatory Monitoring Devices Market