
 US Dialysis Market | 2026-2036
US Dialysis Market Size, Share, and Industry Trends Forecast 2026-2036
US Dialysis Market Analysis
CMS value-based care mandates for kidney disease treatment is restructuring how providers earn reimbursement across the care continuum. DaVita Inc. dominates large-scale in-center operations through captive clinic networks spanning metropolitan corridors. Fresenius Medical Care AG & Co. KGaA anchors integrated supply chains that span dialysis machines, concentrates, and direct patient services. Innovative Renal Care specializes in smaller-footprint facilities targeting underserved rural counties.
Dialysis constitutes an extracorporeal blood purification process utilizing semipermeable membranes to remove urea, creatinine, and excess electrolytes when native kidney function declines below fifteen percent of normal capacity. Hemodialysis commands the largest installed base of treatment stations while peritoneal dialysis represents the fastest-expanding modality as home training protocols mature and catheter biocompatibility improves. Portable dialysis technology attracts venture-stage engineering investment though regulatory clearance timelines constrain near-term commercial deployment.
FDA device clearance pathways govern machine safety and dialysate composition standards while CMS reimbursement rules determine provider revenue per treatment session and site-of-service differentials. State-level certificate-of-need regulations in New York and Illinois restrict new clinic construction, entrenching incumbents. Stakeholders must monitor Medicare Advantage penetration rates and home dialysis mandatory payment model adjustments to align capital deployment with evolving site-of-care economics.
Market Dynamics
CMS reimbursement rate compression is forcing providers to restructure site-of-service economics, accelerating capital migration from in-center facilities toward home-based delivery infrastructure.
Growth Catalysts
- Home Dialysis Mandates:CMS mandatory payment models incentivize nephrologists to shift patients toward peritoneal dialysis and home hemodialysis modalities, reducing facility overhead per treatment.
- Texas and Florida Demand Concentration:Chronic kidney disease prevalence among Medicare beneficiaries in these states exceeds national averages, concentrating new clinic development in Houston, Dallas, Miami, and Tampa corridors.
- Portable Device Engineering:Wearable and miniaturized dialysis systems are attracting venture funding, with prototypes targeting FDA breakthrough device designation pathways for accelerated clearance.
Market Restraints
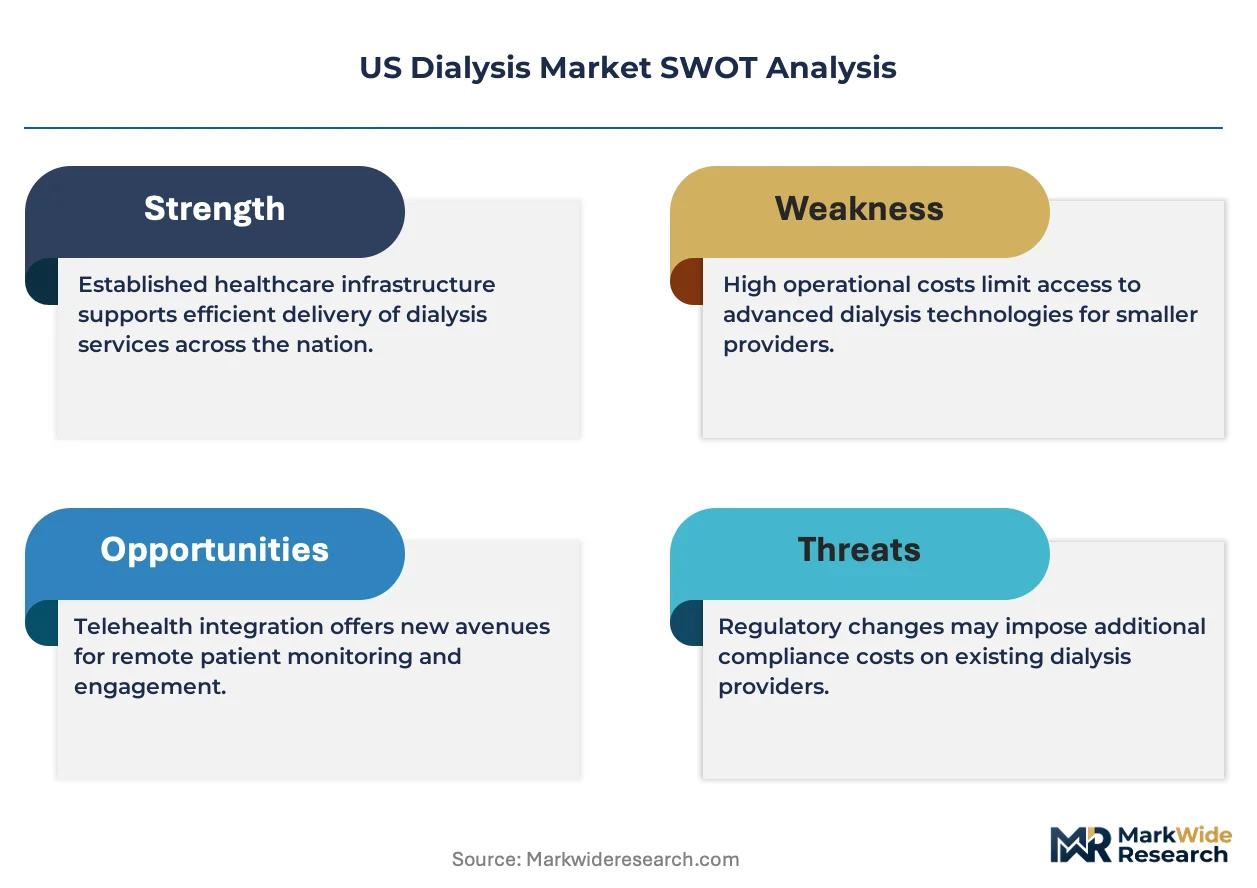
- Certificate-of-Need Barriers:New York and Illinois regulations restrict de novo clinic construction, entrenching incumbent operators and blocking competitive entry in high-density metropolitan markets.
- Biocompatibility Limitations:Current peritoneal dialysis catheters trigger fibrotic encapsulation in 15-30% of patients within two years, forcing modality switches and elevating total cost of care.
- Water Purification Infrastructure:Hemodialysis requires medical-grade ultrapure water systems; rural counties face capital barriers to installing compliant reverse osmosis and deionization equipment.
Strategic Opportunities
- Rural County Underservice:Smaller-footprint clinic models can penetrate counties with zero or single-provider dialysis access, particularly in Appalachian and Mississippi Delta regions.
- Medicare Advantage Penetration:MA plan growth creates carve-out opportunities for risk-bearing kidney care entities to capture capitated payments across the care continuum.
- Telehealth-Integrated Home Training:Remote monitoring platforms combined with video-based patient education protocols can reduce home dialysis training dropout rates and extend therapy persistence.
Industry Challenges
- Nephrology Workforce Scarcity:Fellowship-trained kidney specialists cluster in urban academic centers, leaving rural facilities dependent on locum tenens coverage and telemedicine nephrology.
- Facility Retrofit Costs:Converting in-center stations to accommodate portable or nocturnal dialysis equipment requires plumbing, electrical, and HVAC modifications that strain capital reserves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Dialysis Market |
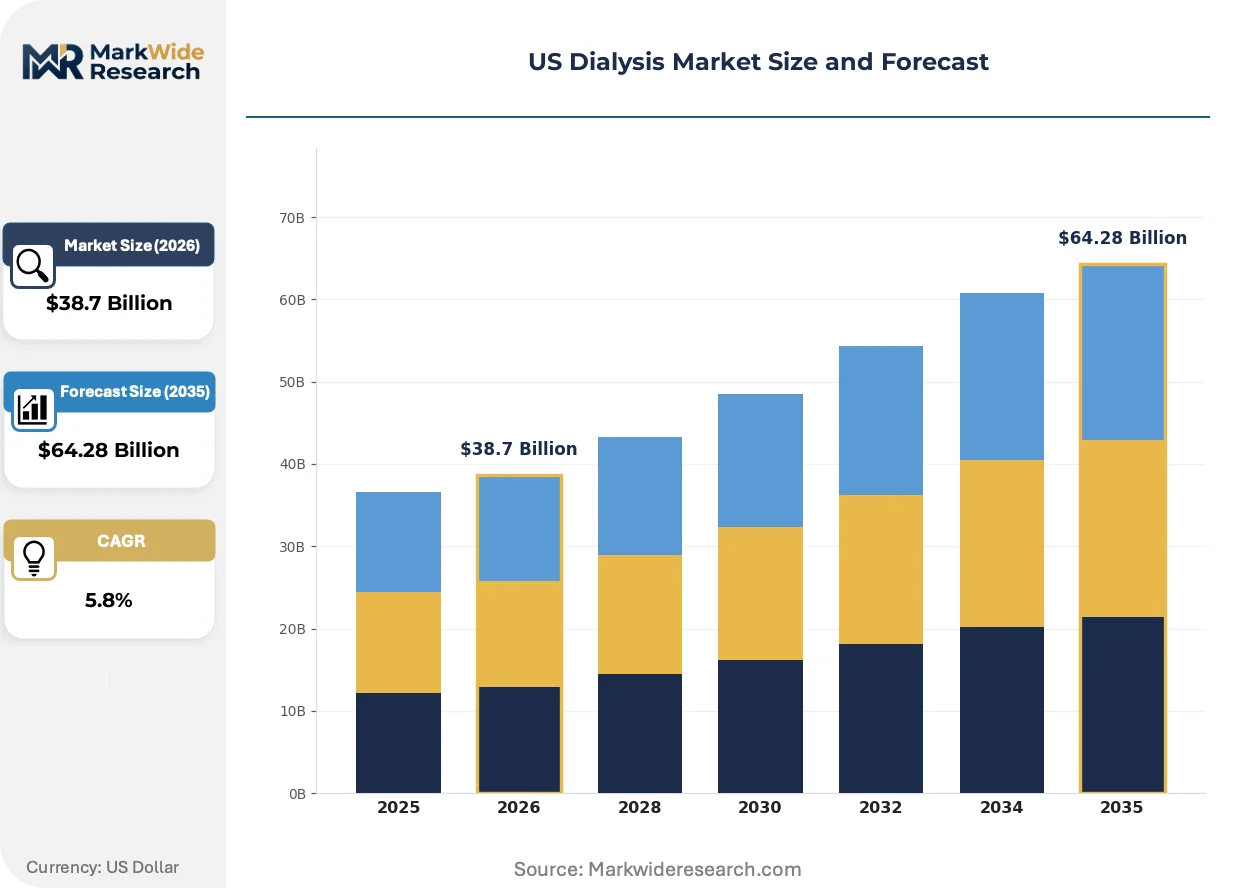
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemodialysis, Peritoneal Dialysis, Dialysis Accessories, Dialysis Machines End User: Hospitals, Dialysis Centers, Home Care Settings, Clinics Technology: Conventional Dialysis, Portable Dialysis, Automated Peritoneal Dialysis, Continuous Renal Replacement Therapy Service Type: In-Center Services, Home Services, Support Services, Training Services |
| Companies Covered | Dialysis Clinic, Inc., Innovative Renal Care, Fresenius Medical Care AG & Co. KGaA, Northwest Kidney Centers, Centers for Dialysis Care, DaVita Inc., Satellite Healthcare, Rogosin Institute, U.S. Renal Care Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Dialysis Market Emerging Trajectories
Device miniaturization and reimbursement redesign are converging to displace the traditional thrice-weekly clinic model, with engineering investment flowing toward patient-operated systems and remote clinical oversight platforms.
Sorbent-based dialysis technology is expanding into home care settings by eliminating the need for continuous water supply and drain connections. Medicare Advantage plans in Florida and Texas are piloting coverage for these systems to reduce transportation burdens. The technology is expanding into rural markets previously deemed unserviceable due to infrastructure constraints, compressing the addressable geography for traditional clinic operators.
CMS Transitional Drug Add-on Payment Adjustment policies are restructuring how oral-only kidney disease medications factor into bundled reimbursement calculations. Dialysis facilities now face margin pressure to integrate pharmacy services or forfeit revenue capture on phosphate binders and calcimimetics. Large multi-site operators in California and Ohio are responding by acquiring specialty pharmacies or forming exclusive distribution agreements.
Patient self-cannulation training protocols are displacing traditional staff-dependent vascular access management in home hemodialysis programs. Frequent dialysis schedules enabled by personal devices are reducing intradialytic hypotension episodes and hospitalization rates. This behavioral shift is most visible in Pacific Northwest markets where integrated delivery networks have invested in comprehensive home therapy support infrastructure.
US Dialysis Market Segmentation
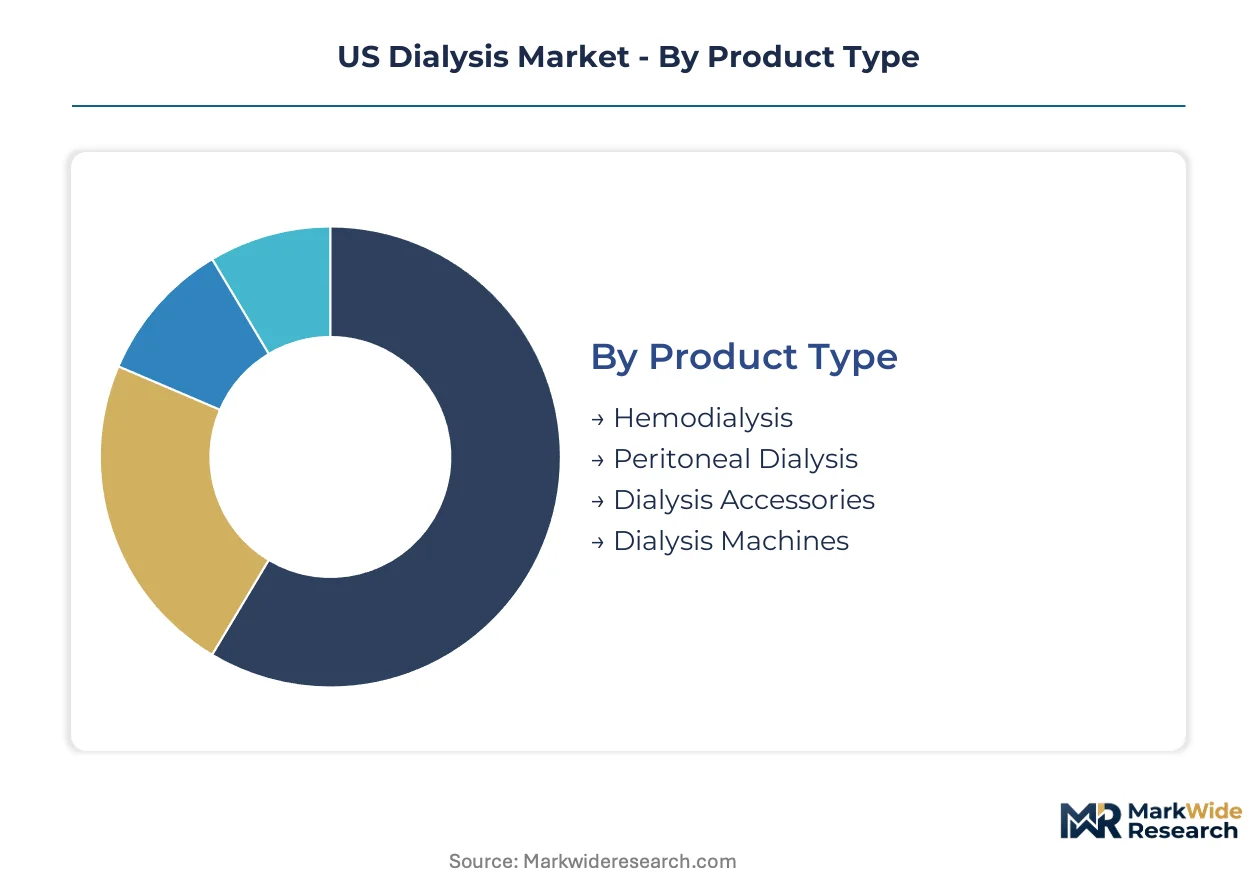
Dialysis market segmentation reveals how reimbursement redesign and site-of-care economics are fragmenting traditional treatment models. Product and service configurations now diverge sharply between institutional settings and patient-operated home systems.
Product Type:
Standalone devices dominate capital expenditure while embedded consumables drive recurring revenue streams.
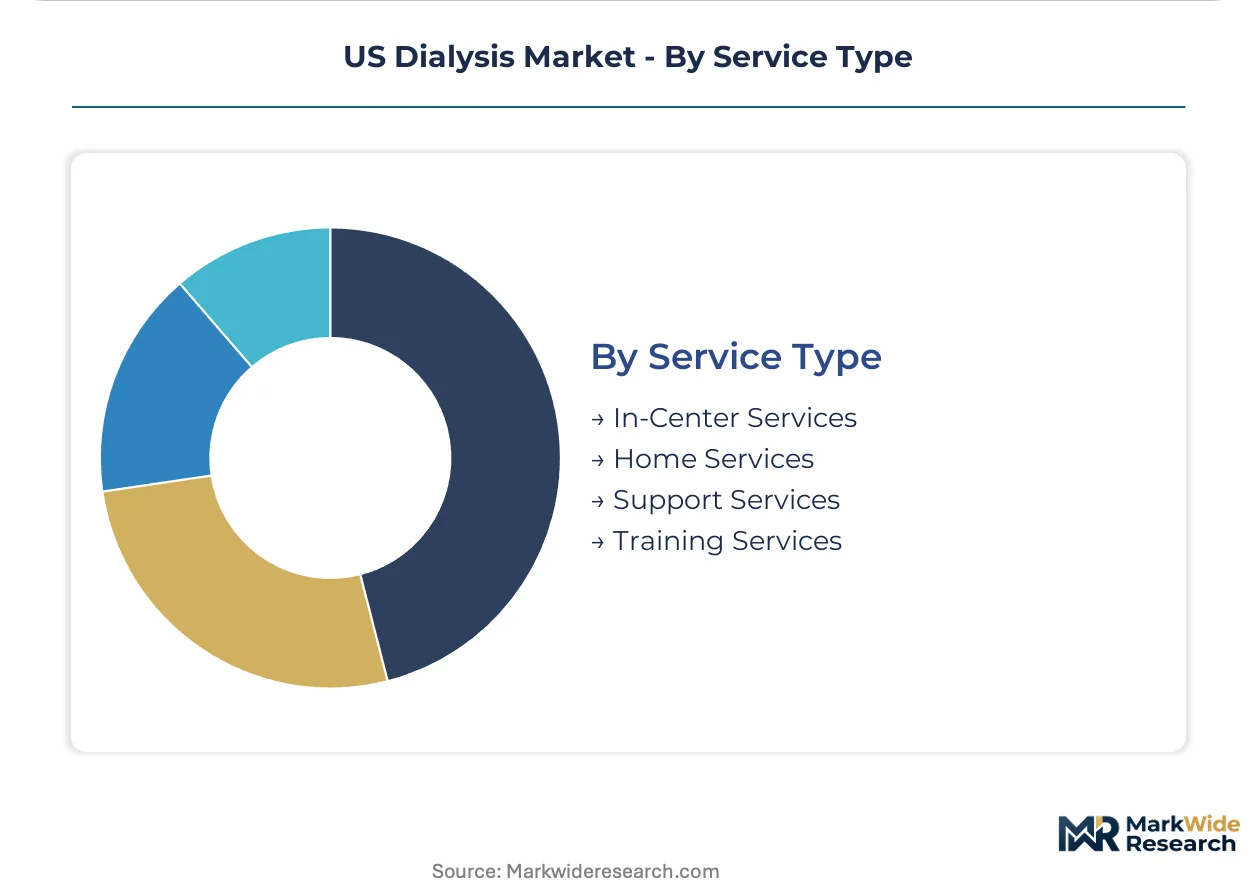
- Hemodialysis:Blood purification through external filtration circuits using dialyzers and concentrate solutions. Texas and Florida Medicare corridors concentrate installed base expansion as chronic kidney disease prevalence exceeds national benchmarks.
- Peritoneal Dialysis:Intraperitoneal fluid exchange via indwelling catheters enables patient-managed home therapy. Home training protocol maturation and CMS mandatory payment model incentives are accelerating modality migration in Pacific Northwest integrated delivery networks.
- Dialysis Accessories:Bloodlines, fistula needles, and catheter sets constitute high-velocity consumable demand.
- Dialysis Machines:Stationary and portable hardware platforms anchor provider capital budgets.
Volume placements concentrate in Hemodialysis; the faster expansion belongs to Peritoneal Dialysis.
End User:
Customer economics split between facility-dependent reimbursement and capitated home care risk models.
- Hospitals:Acute inpatient dialysis for hemodynamically unstable patients requiring intensive monitoring. Urban academic medical centers in Houston and Dallas maintain the highest treatment densities due to referral network concentration.
- Dialysis Centers:Freestanding outpatient facilities delivering thrice-weekly scheduled sessions. DaVita and Fresenius captive networks span metropolitan corridors where certificate-of-need regulations in New York and Illinois protect incumbent positions.
- Home Care Settings:Patient-managed therapy with remote clinical oversight.
- Clinics:Smaller-footprint facilities targeting underserved rural counties.
Patient volume aggregates in Dialysis Centers; Home Care Settings are climbing the fastest.
Technology:
Engineering maturity separates established platforms from venture-stage miniaturization efforts.
- Conventional Dialysis:Established three-times-weekly intermittent therapy protocols with fixed-station equipment. CMS reimbursement rate compression is forcing providers to extract operational efficiency from legacy infrastructure.
- Portable Dialysis:Wearable and miniaturized systems under FDA breakthrough device pathway review. Venture funding concentrates on prototypes targeting elimination of continuous water supply requirements.
- Automated Peritoneal Dialysis:Cycler-mediated overnight fluid exchanges.
- Continuous Renal Replacement Therapy:Slow, continuous filtration for ICU hemodynamic stability.
Installed base dominance rests with Conventional Dialysis; Portable Dialysis shows the steepest expansion trajectory.
Service Type:
Revenue model fragmentation follows site-of-care migration and workforce availability constraints.
- In-Center Services:Staff-assisted treatment delivery at fixed facilities with full clinical support. Nephrology workforce scarcity in rural Appalachian and Mississippi Delta regions limits geographic penetration.
- Home Services:Remote monitoring and periodic nursing visits for patient-managed therapy. Medicare Advantage plans in Florida and Texas are piloting coverage for sorbent-based systems to reduce transportation burdens.
- Support Services:Vascular access maintenance and infection prevention protocols.
- Training Services:Patient self-cannulation and equipment operation education.
Revenue concentration persists in In-Center Services; Home Services are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors the largest concentration of dialysis capacity in the United States, with metropolitan corridors in Texas and Florida driving the majority of new clinic development as chronic kidney disease prevalence among Medicare beneficiaries exceeds national benchmarks in these states.
Texas
Houston and Dallas corridors concentrate the highest density of freestanding dialysis centers in the nation, with chronic kidney disease prevalence among Medicare beneficiaries running substantially above national averages. CMS mandatory payment models incentivize nephrologists to shift patients toward home-based modalities, reducing facility overhead per treatment. DaVita and Fresenius captive networks span metropolitan corridors where certificate-of-need regulations do not restrict new clinic construction.
Florida
Miami and Tampa metropolitan areas exhibit dialysis demand concentration rivaling Texas, driven by aging Medicare beneficiary demographics and elevated diabetes prevalence. Medicare Advantage plans in Florida are piloting coverage for sorbent-based home dialysis systems to reduce transportation burdens on patients. Large multi-site operators are responding to CMS reimbursement rate compression by extracting operational efficiency from legacy infrastructure across South Florida corridors.
California
Los Angeles and San Francisco Bay Area dialysis markets face margin pressure from CMS Transitional Drug Add-on Payment Adjustment policies restructuring bundled reimbursement calculations. Large multi-site operators in California are acquiring specialty pharmacies or forming exclusive distribution agreements to capture revenue on phosphate binders and calcimimetics. Pacific Northwest integrated delivery networks have invested in comprehensive home therapy support infrastructure extending into Northern California.
New York
New York City metropolitan dialysis markets operate under strict certificate-of-need regulations that restrict de novo clinic construction and entrench incumbent operator positions. State-level CON barriers block competitive entry in high-density metropolitan markets, protecting established provider networks. Urban academic medical centers in Manhattan maintain high treatment densities due to referral network concentration for acute inpatient dialysis.
Illinois
Chicago metropolitan dialysis capacity faces similar certificate-of-need restrictions as New York, limiting new facility development and preserving incumbent market structures. State regulations protect established operators while concentrating patient volume in existing freestanding outpatient facilities. Rural counties in downstate Illinois present penetration opportunities for smaller-footprint clinic models targeting underserved areas with zero or single-provider dialysis access.
US Dialysis Market Vendor Landscape
Premium-margin players sit above commodity-margin players across site-of-service economics, with integrated supply chain operators commanding superior reimbursement capture compared to standalone facility operators. The vendor base clusters around three strategic archetypes: large-scale in-center network operators, integrated device-and-service conglomerates, and smaller-footprint rural specialists. Consolidation pressure from CMS reimbursement rate compression is driving M&A activity among mid-scale regional operators, while technology licensing partnerships proliferate between device manufacturers and home care service providers.
Within the large-scale network tier, DaVita Inc. and Fresenius Medical Care AG & Co. KGaA occupy positions exemplifying divergent strategic approaches to vertical integration. Among mid-scale specialists, Innovative Renal Care represents the smaller-footprint facility archetype targeting underserved rural counties. These three entities anchor the competitive structure, with DaVita exemplifying metropolitan corridor concentration, Fresenius representing integrated supply chain control, and Innovative Renal Care occupying the rural penetration vector.
| Leading Market Players |
|---|
| Dialysis Clinic, Inc. |
| Innovative Renal Care |
| Fresenius Medical Care AG & Co. KGaA |
| Northwest Kidney Centers |
| Centers for Dialysis Care |
| DaVita Inc. |
| Satellite Healthcare |
| Rogosin Institute |
| U.S. Renal Care Inc. |
| Others |
Supply Flow & Price Mechanics
Medicare Advantage plan procurement concentration anchors pricing power in the US dialysis market, with capitated reimbursement models compressing margins for facility-dependent operators while rewarding integrated care platforms. CMS bundled payment structures tether provider revenue to patient throughput and outcome metrics, forcing price discipline across site-of-service tiers.
Pricing Analysis
Value-based reimbursement anchors pricing structures, with CMS ESRD Prospective Payment System tying facility compensation to treatment frequency and quality benchmarks. Price differentiation separates metropolitan corridor incumbents from rural specialists, with certificate-of-need protections in New York and Illinois sustaining premium capture. Cost compression in in-center services is intensifying because home dialysis mandates reduce facility overhead per session. Independent dialysis centers exhibit highest price sensitivity, while integrated supply chain operators demonstrate lowest sensitivity due to captive consumable revenue.
Supply Chain Analysis
FDA 510(k) clearance and ISO 13485 certification gating concentrate device manufacturing among established medtech conglomerates with quality management infrastructure. Dialyzer membrane production draws from Germany, Japan, and Mexico, with concentrate solution formulation resting on US domestic mixing facilities. Supply chain risk centers on single-source vulnerability for high-flux membrane polymers. Distribution runs through GPO contracts with hospital systems and direct-to-facility logistics networks serving DaVita and Fresenius captive clinic footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US dialysis market functions as a vertical-integration race, with upstream control over dialyzer manufacturing and downstream capture of pharmacy services determining margin sustainability. Players are pursuing captive supply of consumables to defend against CMS reimbursement compression.
For Market Incumbents: Hedge against home dialysis displacement by acquiring specialty pharmacy capabilities to capture oral medication revenue under TDAPA restructuring. Consolidate rural county positions through smaller-footprint clinic deployment before mid-scale regional operators achieve scale. Defend metropolitan corridor density against sorbent-based portable device entrants by embedding telehealth-integrated training protocols that reduce home therapy dropout rates. For New Entrants and Emerging Players: Enter via Appalachian and Mississippi Delta counties with zero or single-provider access, where nephrology workforce scarcity has blocked incumbent penetration. Target sorbent-based home dialysis system distribution partnerships with Medicare Advantage plans in Florida and Texas pilot programs. Pursue FDA breakthrough device designation pathways for wearable systems to compress regulatory timelines against established device platforms. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale regional operators in certificate-of-need restricted states, where regulatory barriers protect cash flow stability despite reimbursement headwinds. Long-term viability hinges on home dialysis modality share trajectory and Medicare Advantage penetration rates across the Southeast. Watch CMS mandatory payment model adjustment timing as inflection indicator for capital deployment pacing.| Strategic Initiative | Industry Significance |
|---|---|
| Specialty Pharmacy Acquisition | Captures phosphate binder and calcimimetic revenue under TDAPA restructuring in California and Ohio corridors. |
| Sorbent-Based System Deployment | Eliminates water infrastructure requirements, expanding addressable geography into rural Appalachian counties. |
| Telehealth-Integrated Home Training | Reduces patient dropout rates through remote monitoring platforms in Pacific Northwest integrated delivery networks. |
| Smaller-Footprint Rural Clinic Buildout | Penetrates underserved Mississippi Delta regions where locum tenens coverage dominates nephrology access. |
| FDA Breakthrough Device Pathway | Accelerates wearable dialysis system clearance timelines against conventional 510(k) review cycles. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted among nephrology practice administrators, dialysis facility operations directors, Medicare Advantage plan formulary managers, and GPO contract specialists. CMS Medicare cost reports, FDA 510(k) device clearance databases, state certificate-of-need filings, and hospital procurement records provided validation layers. Bottom-up treatment volume modeling triangulated against top-down reimbursement flow analysis.
Data-stream reconciliation across the analysis window combined installed base enumeration with site-of-service migration tracking. Segmentation dimensions spanned modality type, care setting, technology maturity tier, and regional regulatory cluster. CAGRs derived from treatment volume trajectories and per-session revenue compression curves, with home dialysis penetration rates and Medicare Advantage plan growth curves serving as primary demand-side inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt CMS reimbursement rulemaking or accelerated FDA portable device clearances. Model assumptions reflect current regulatory frameworks and prevailing site-of-care economics. A model refresh is warranted upon material change in mandatory payment model implementation timelines or breakthrough device designation grant rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Blood Dialyzer Market
Nephrology
Hemodialyzer Market
Nephrology
Ketoanalogue for Kidney Disease Market
Nephrology
Aldosterone-Renin Screening Market
Nephrology
Global Dialyzer Market
Nephrology
Global Renal Medical Devices and Services Market
Nephrology
US Dialysis Centers Market
Nephrology
Drug-Induced Nephrotoxicity Treatment Market
Nephrology
Global Hepatorenal Syndrome Treatment Market
Nephrology
Renal Insufficiency Treatment Market
Nephrology
Lupus Nephritis Treatment Market
Nephrology
Global Diabetic Nephropathy Market
Nephrology
Plasmapheresis Market
Nephrology
South Africa Hemodialysis and Peritoneal Dialysis Market
Nephrology
Dialysis Service Market
Nephrology
Renal Artery Stenosis Treatment Market