
 Handheld Ultrasound Devices Market | 2026-2036
Handheld Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld Ultrasound Devices Market Foresight
The gap between premium cart-based systems and pocket-sized probes is expanding in concrete terms: image resolution, AI-assisted interpretation, and wireless connectivity now define the premium tier, while basic B-mode imaging occupies the commodity layer. Butterfly Network leverages semiconductor-based single-probe architecture to compress cost structures. GE Healthcare sustains institutional channel dominance through backward integration into hospital IT ecosystems. Philips differentiates via AI-embedded software that automates measurement protocols.
Handheld ultrasound devices are compact, battery-powered transducer systems operating at 2-15 MHz frequencies, designed for real-time anatomical imaging through piezoelectric crystal arrays or CMUT technology; they enable diagnostic visualization at the point of care without dedicated exam rooms. The convex segment leads in abdominal and obstetric applications where deep penetration matters, while the wireless technology layer captures the fastest expansion as Bluetooth 5 and 5G-enabled probes eliminate tethered workflows. Emergency services and clinics now represent the densest margin pools, as these settings prioritize speed over the comprehensive imaging suites hospitals require.
FDA 510(k) premarket notification and EU MDR conformity assessment shape product development timelines and clinical evidence requirements for manufacturers seeking market access. ISO 13485 quality management and IEC 60601-1-2 electromagnetic compatibility standards further constrain design choices for wireless-capable units. Stakeholders must monitor how national reimbursement codes for point-of-care ultrasound evolve, as coverage decisions will determine whether handheld systems displace traditional cart-based modalities or merely supplement them.
Market Dynamics
Point-of-care imaging demand is fragmenting procurement authority from centralized radiology departments to individual clinical units, rewiring how handheld ultrasound vendors must configure sales channels and service models.
Growth Catalysts
- Emergency medicine workflows:Bedside diagnostic capability reduces time-to-treatment for trauma and cardiac cases, pulling device deployment into ambulances and triage bays.
- FDA 510(k) pathway streamlining:Predicate device routes for wireless probe systems compress premarket review timelines relative to de novo submissions.
- CMUT semiconductor fabrication:Capacitive micromachined ultrasonic transducers enable single-probe multi-frequency operation without mechanical switching.
Market Restraints
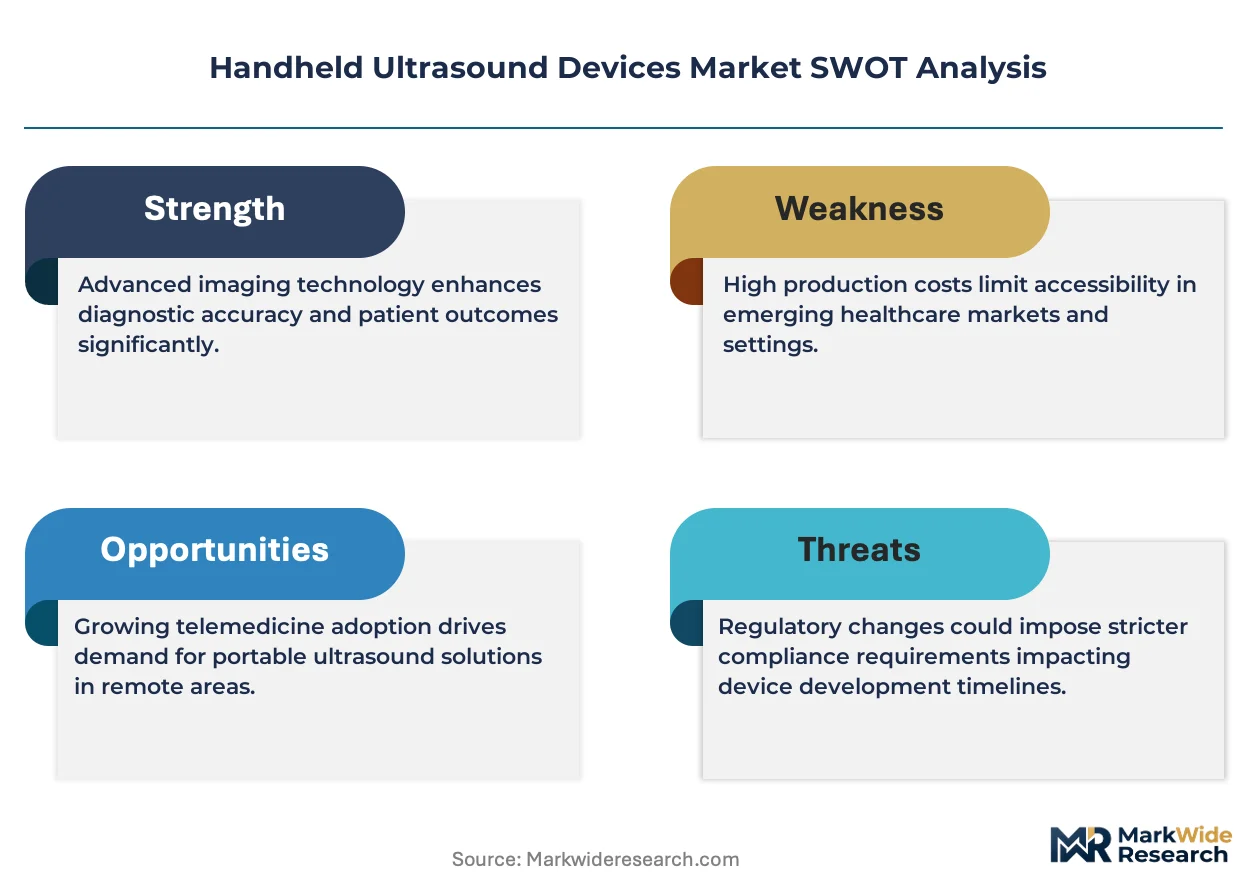
- Piezoelectric crystal supply concentration:High-purity lead zirconate titanate sourcing clusters in East Asian specialty chemical processors, exposing manufacturers to input volatility.
- EU MDR clinical evidence escalation:Class IIa device conformity assessments now require expanded post-market surveillance data, extending certification cycles.
- Cart-based system residual performance:Premium hospital imaging suites retain superior Doppler sensitivity and probe selection for complex cases.
Strategic Opportunities
- Rural China primary care networks:Township health centers lack radiology infrastructure, creating first-mover advantage for portable diagnostic deployment.
- 5G-enabled teleradiology integration:Real-time image transmission to urban specialists expands diagnostic reach without on-site expertise.
- India PLI scheme for medical electronics:Production-linked incentives for domestic manufacturing reduce landed cost for price-sensitive segments.
Industry Challenges
- Point-of-care ultrasound training standardization:Emergency physicians and nurse practitioners require competency frameworks that vary across hospital credentialing committees.
- Legacy PACS integration complexity:Wireless probes must interface with proprietary hospital IT architectures that prioritize cart-based system data formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld Ultrasound Devices Market |
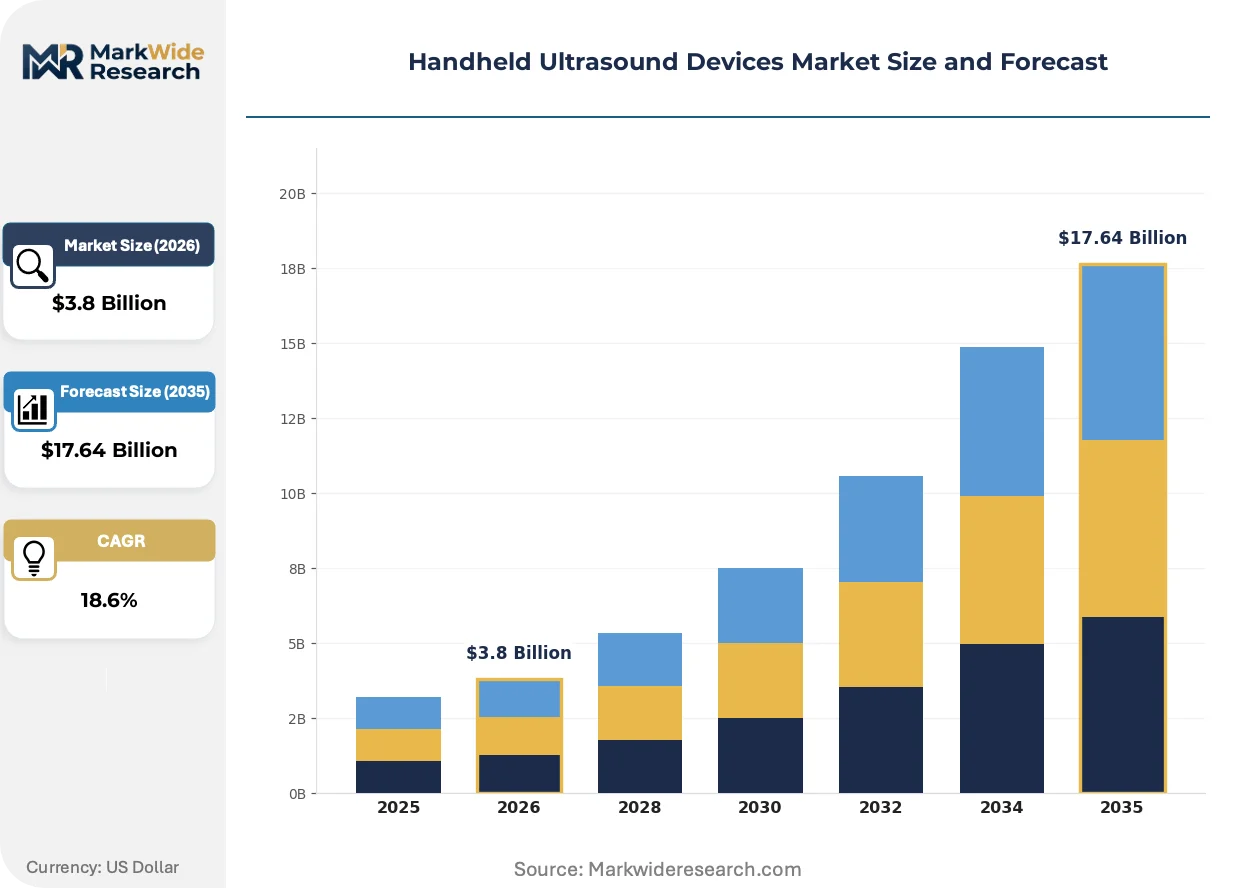
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Convex, Linear, Phased Array, 3D Ultrasound Technology: Digital, Analog, Wireless, Hybrid End User: Clinics, Hospitals, Emergency Services, Home Care Application: Obstetrics, Cardiology, Musculoskeletal, Abdominal |
| Companies Covered | Clarius, Canon Medical Systems, GE Healthcare, Konica Minolta, Healcerion, Philips, Butterfly Network, Mindray, Fujifilm SonoSite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld Ultrasound Devices Market Shifts & Advancements
Artificial intelligence is embedding directly into probe hardware, compressing the interpretation gap between acquisition and diagnosis while shifting competitive advantage toward software-native vendors.
CMUT-on-CMOS fabrication is integrating capacitive transducer arrays with standard semiconductor processes, collapsing transducer manufacturing costs while enabling software-defined frequency switching. Emergency departments in Germany and the United States are piloting these probes for rapid cardiac assessment. The technology is integrating AI-based automated ejection fraction calculation directly at the point of capture, reducing reliance on offline specialist review.
EU MDR Article 10 post-market clinical follow-up requirements are mandating systematic real-world evidence collection for wireless ultrasound devices, elevating documentation burdens for smaller manufacturers. This regulatory shift favors firms with established quality management systems and dedicated clinical affairs teams. The wireless probe segment is responding by consolidating supplier bases to reduce audit complexity.
Hospital procurement committees are unbundling device acquisition from software subscription and training packages, treating AI modules as separate line items with distinct renewal cycles. This purchasing pattern disrupts traditional bundled pricing models and pressures vendors to demonstrate standalone software value. The shift is most visible in United States health systems where value analysis committees scrutinize technology purchases against specific outcome metrics.
Handheld Ultrasound Devices Market Segmentation
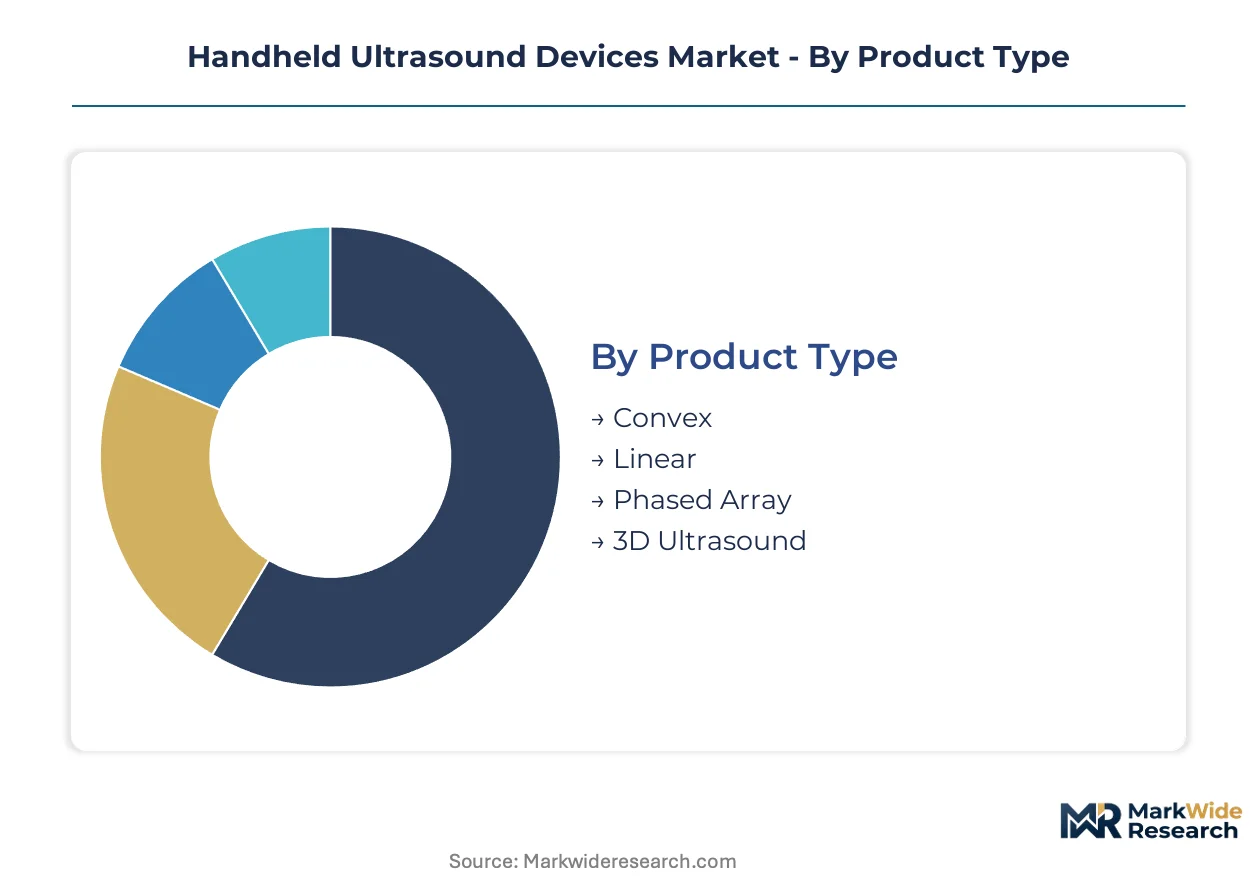
Segmentation in handheld ultrasound devices reveals how probe architecture and connectivity choices determine deployment settings. Upgrade cycles vary dramatically across clinical environments, from emergency departments replacing probes every 18 months to home care settings extending use beyond five years.
Product Type:
Replacement cycles in probe design track directly with frequency versatility and penetration depth requirements across anatomical targets.
- Convex:Curved array transducers operating at 2-5 MHz penetrate 15-20 cm for abdominal and obstetric imaging. Demand concentrates in China's township health centers where deep tissue visualization replaces absent cart-based systems. The convex architecture dominates maternal-fetal assessments in decentralized primary care networks.
- Linear:High-frequency 7-15 MHz arrays deliver superficial resolution for vascular access and musculoskeletal evaluation. Emergency departments in Germany and the United States deploy these for rapid central line placement and fracture assessment, prioritizing speed over comprehensive imaging suites.
- Phased Array:Sector-scanning probes optimized for cardiac imaging through intercostal windows.
- 3D Ultrasound:Volumetric acquisition probes with mechanical or matrix array steering.
Convex probes sit at the top of the volume ranking, with linear arrays climbing the fastest as point-of-care emergency protocols expand.
Technology:
Cost tier differentiation separates semiconductor-based architectures from legacy piezoelectric systems, with wireless commanding premium positioning.
- Wireless:Bluetooth 5 and 5G-enabled probes eliminate tethered workflows through integrated battery and transmission modules. Emergency services in the United States pilot these for ambulance-based trauma triage, cutting time-to-diagnosis for penetrating chest injuries. The wireless layer captures the steepest expansion trajectory as hospital IT departments relax security protocols for encrypted personal area networks.
- Digital:Beamforming processors integrated directly into probe handles enable software-defined frequency switching without mechanical components.
- Analog:Traditional cable-connected systems with external processing units.
- Hybrid:Architectures combining on-probe digitization with tethered power delivery.
Wireless technology leads margin capture, with hybrid systems gaining share fastest among budget-constrained clinics.
End User:
Customer type determines procurement authority, training investment, and software subscription tolerance across institutional and individual purchasers.
- Emergency Services:Pre-hospital and triage settings prioritize acquisition speed over image archive integration. Ambulance services in Germany deploy single-probe systems for field cardiac assessment, with crews trained to transmit clips to receiving hospitals. Reimbursement codes for point-of-care ultrasound in emergency medicine remain under negotiation with CMS and private payers.
- Hospitals:Radiology departments and clinical units with PACS integration requirements.
- Clinics:Outpatient settings with limited capital equipment budgets.
- Home Care:Patient-operated or visiting nurse-deployed systems for chronic monitoring.
Emergency services command the highest per-unit software spending, with clinics expanding volume fastest through government procurement programs.
Application:
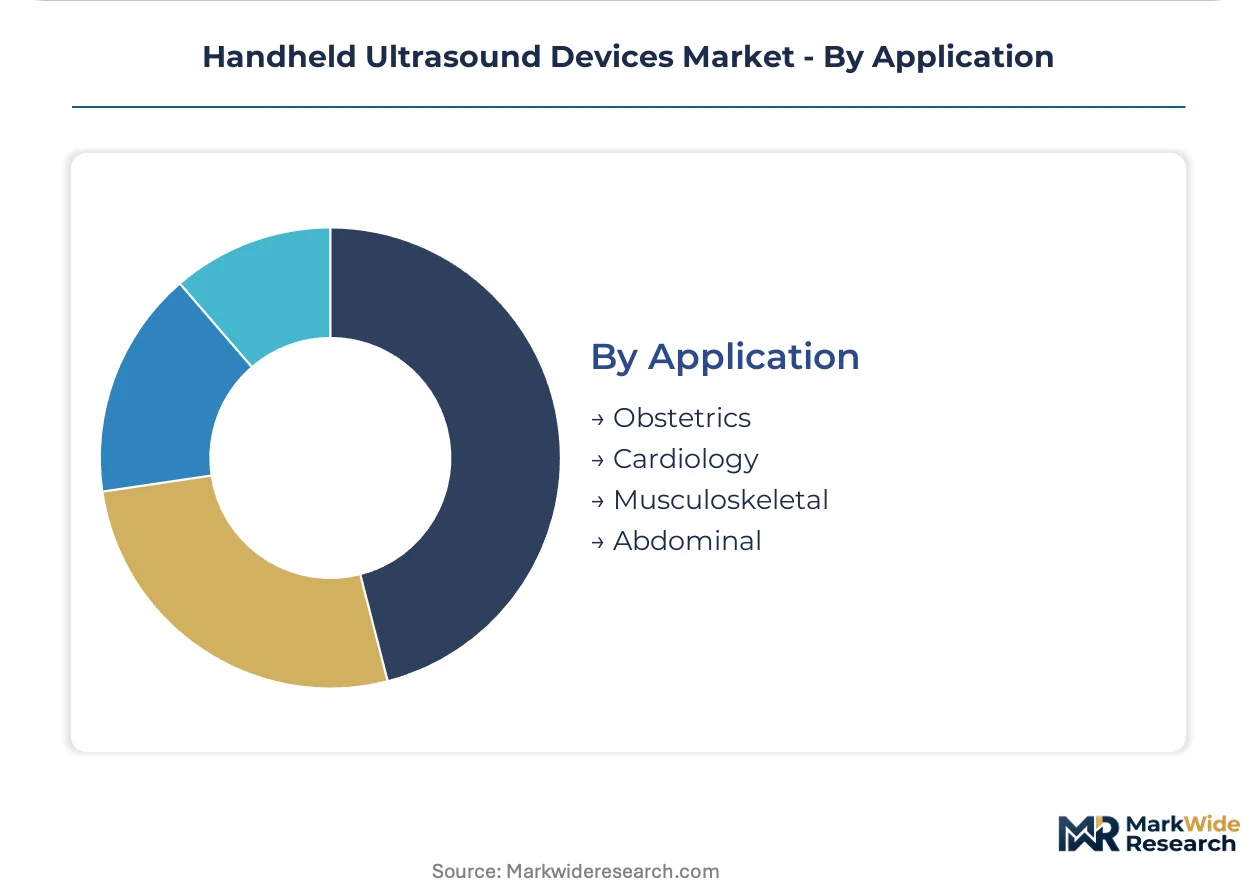
Application focus drives probe frequency selection and AI module configuration, with cardiology and obstetrics anchoring distinct technology development paths.
- Cardiology:Echocardiography applications demand phased array geometry and automated ejection fraction calculation. Emergency physicians in the United States use handheld systems to exclude pericardial effusion in hypotensive patients, reducing CT utilization. FDA 510(k) clearances for cardiac AI algorithms are accelerating predicate-based submissions.
- Obstetrics:Fetal biometry and placental assessment protocols.
- Musculoskeletal:Tendon, ligament, and joint surface evaluation.
- Abdominal:Solid organ and fluid assessment in trauma and chronic disease monitoring.
Cardiology applications generate the highest software attach rates, with musculoskeletal evaluation climbing fastest as sports medicine adopts point-of-care protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Emergency medicine specialists in the United States, Germany, and China anchor the geographic demand for handheld ultrasound devices, with health system decentralization and point-of-care protocols concentrating procurement authority in these markets.
United States
Ambulance services and emergency departments drive demand for wireless probe systems that transmit trauma imaging to receiving hospitals. FDA 510(k) premarket notification pathways compress clearance timelines for predicate-based wireless submissions. Boston and Minneapolis medical device clusters host development teams refining CMUT-on-CMOS architectures for single-probe cardiac assessment.
Germany
Pre-hospital emergency physicians deploy handheld systems for field cardiac triage, with reimbursement negotiations underway between statutory health insurers and device manufacturers. EU MDR conformity assessment requirements under Article 10 mandate expanded post-market surveillance for Class IIa wireless probes. Erlangen and Hamburg host radiology equipment engineering centers optimizing probe integration with hospital PACS networks.
China
Township health centers lacking radiology infrastructure create volume demand for convex probes in maternal-fetal and abdominal applications. NMPA regulatory pathways for wireless medical devices require electromagnetic compatibility testing under GB standards. Shenzhen and Beijing semiconductor fabrication clusters supply CMUT wafers for domestic probe manufacturers targeting primary care networks.
India
Primary health centers in rural districts seek portable diagnostic capability where cart-based systems remain uneconomical. The PLI scheme for medical electronics offers production-linked incentives for domestic manufacturing of wireless ultrasound components. Bangalore and Hyderabad medical technology clusters assemble probes for price-sensitive clinic segments.
Japan
Emergency medicine departments in Tokyo and Osaka evaluate handheld systems for rapid musculoskeletal assessment in aging populations. PMDA consultation pathways for software-as-a-medical-device regulate AI-embedded measurement modules. Nagoya industrial corridors host precision machining suppliers for probe housing and transducer assembly.
Handheld Ultrasound Devices Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across semiconductor fabrication and software development boundaries. The vendor base separates into three tiers: institutional imaging conglomerates with captive hospital IT integration, semiconductor-native entrants with single-probe architectures, and regional assemblers serving price-sensitive primary care networks. Dominant competitive moves include backward integration into CMUT wafer production and strategic partnerships with 5G infrastructure providers for teleradiology-enabled probes.
Within the semiconductor-native tier, Butterfly Network exemplifies single-probe multi-frequency architectures that collapse mechanical switching costs. GE Healthcare and Philips occupy positions anchoring institutional channel dominance through software-embedded AI modules and PACS integration capability. These three companies represent the strategic archetypes reshaping procurement authority from radiology departments toward individual clinical units.
| Leading Market Players |
|---|
| Clarius |
| Canon Medical Systems |
| GE Healthcare |
| Konica Minolta |
| Healcerion |
| Philips |
| Butterfly Network |
| Mindray |
| Fujifilm SonoSite |
| Others |
Supply & Pricing Matrix
Hospital value analysis committees unbundling software subscriptions from device hardware force vendors to demonstrate standalone AI module value, compressing bundled pricing premiums and accelerating cost transparency across procurement tiers.
Pricing Analysis
Bundled-versus-unbundled service splits now dominate purchasing negotiations, with three-tier pricing structure across premium, standard, and economy levels separating AI-embedded wireless systems from basic B-mode probes and refurbished analog units. Price differentiation rests on FDA 510(k) clearance tier and ISO 13485 certification status alongside software subscription attach rates. Pricing pressure stems from government procurement programs in price-sensitive primary care networks. Clinics and township health centers exhibit highest price sensitivity; emergency services tolerate premium positioning for speed-to-diagnosis.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Seoul, and Austin anchor hub-and-spoke fulfillment patterns for wireless probe assembly. High-purity lead zirconate titanate sourcing clusters in China and Japan, while CMUT semiconductor fabrication draws from Taiwan and South Korea. Single-source vulnerability concentrates in specialty chemical processors for piezoelectric crystals. Distribution runs through institutional GPO contracts in the United States and direct government procurement channels in China and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CMUT-on-CMOS fabrication cost curves and AI-embedded premium tier expansion frame this market as a margin-expansion story, with semiconductor-native architectures capturing software-defined value previously locked in mechanical probe switching.
For Market Incumbents: Anchor institutional channel dominance through backward integration into hospital IT ecosystems and PACS interoperability certification. Semiconductor-native entrants with single-probe architectures threaten premium tier positioning; incumbents must accelerate CMUT wafer captive supply and AI module R&D to defend software attach rates. For New Entrants and Emerging Players: Direct-to-clinic digital sales channels bypass radiology department procurement gatekeepers, enabling rapid penetration of township health centers in China and primary care networks in India. White-space concentrates in rural diagnostic deployment and 5G-enabled teleradiology integration; pursue software-first positioning with subscription revenue models. For Investors and Strategic Acquirers: Asymmetric upside sits with semiconductor fabrication specialists possessing CMUT-on-CMOS process expertise and clinical affairs teams navigating EU MDR post-market surveillance. Long-term viability favors firms with quality management infrastructure spanning Class IIa device conformity. Watch NMPA and FDA predicate clearance velocity as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 compliance accelerates wireless probe market access across German and French health systems. |
| Hospital System Partnership | PACS integration agreements with United States IDNs secure recurring software subscription revenue streams. |
| Software Companion Development | AI-embedded ejection fraction modules differentiate cardiac applications from commodity B-mode imaging. |
| Reimbursement Strategy | CMS point-of-care ultrasound code negotiations determine emergency services adoption velocity. |
| Backward Integration | Captive CMUT wafer production insulates margin from East Asian specialty chemical processor volatility. |
Research Methodology
Coverage spans the United States, Germany, China, India, and Japan, with primary inputs from each market combining structured interviews with emergency medicine clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers alongside secondary validation from FDA 510(k) filings, EU MDR conformity assessment databases, NMPA registration records, CMS reimbursement code proceedings, and hospital procurement databases. Bottom-up probe shipment analysis triangulates against top-down health system capital expenditure tracking.
Granularity-level modeling extends to product type, technology layer, end-user category, and application focus across the projection horizon. Convex, linear, phased array, and 3D probe architectures were modeled separately; wireless, digital, analog, and hybrid technology tiers tracked distinct cost curves. CAGRs derive from installed base expansion rates and replacement cycle compression in emergency settings. Forecast inputs include CMUT fabrication yield improvements and AI algorithm regulatory clearance velocity.
The model assumes a particular technology adoption path; alternative pathways for CMUT-on-CMOS versus piezoelectric crystal retention would alter the outlook. Forecasts reflect documented assumptions regarding reimbursement code expansion and 5G infrastructure deployment. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Electrotherapy Devices Market
Medical Devices
Asthma Spacers Market
Medical Devices
Canada Minimally Invasive Surgery Devices Market
Medical Devices
MRI Coils Market
Medical Devices
Europe Cardiac Rhythm Management Devices Market
Medical Devices
GCC and UAE Diabetes Devices Market
Medical Devices
Gutta Percha Obturator Market
Medical Devices
Global Automated External Defibrillators Market
Medical Devices
Steerable Needles Market
Medical Devices
Home Sleep Apnea Testing Devices Market
Medical Devices
Medical Devices Vigilance Market
Medical Devices
Nurse Call Systems Market
Medical Devices
Global Automated Dispensing Machines Market
Medical Devices
Implantable Drug Eluting Devices Market
Medical Devices
Global Insulin Pumps Market
Medical Devices
Endoscope Reprocessing Device Market