
 Hollow Glass Microspheres Market | 2026-2036
Hollow Glass Microspheres Market Size, Share, and Industry Trends Forecast 2026-2036
Hollow Glass Microspheres Market Intelligence
Specialized glass-forming chemist availability is bifurcating the competitive landscape between integrated producers and toll manufacturers. 3M Company leverages captive borosilicate formulation expertise to sustain premium positioning in aerospace-grade microspheres. Potters Industries LLC anchors North American supply through vertically controlled melting and spheroidization assets in Pennsylvania. Mo-Sci Corporation differentiates via pharmaceutical-grade surface chemistry for controlled-release applications.
Hollow glass microspheres are thin-walled, spherical silica-alumina particles typically 10 to 300 microns in diameter with densities ranging from 0.1 to 0.7 g/cm³, manufactured through flame spheroidization or sol-gel processes to deliver buoyancy, thermal insulation, and compressive strength in engineered composites. Fly ash based microspheres occupy the volume tier where construction companies source bulk material for lightweight concrete and thermal insulation boards. Ceramic based grades command margin concentration in oil well drilling where downhole pressure resistance determines procurement decisions. Polymer based variants represent the fastest-growing structural category as vehicle manufacturers integrate them into underbody shields and bumper systems.
EPA emissions standards and OSHA workplace exposure limits govern silica handling protocols across U.S. manufacturing facilities, while REACH registration requirements in Europe constrain raw material sourcing for non-compliant importers. China's GB standards for building materials and MEE environmental enforcement shape domestic production quotas and export availability. Stakeholders must monitor regulatory divergence between jurisdictions to determine where formulation investments and certification spending will yield durable market access.
Market Dynamics
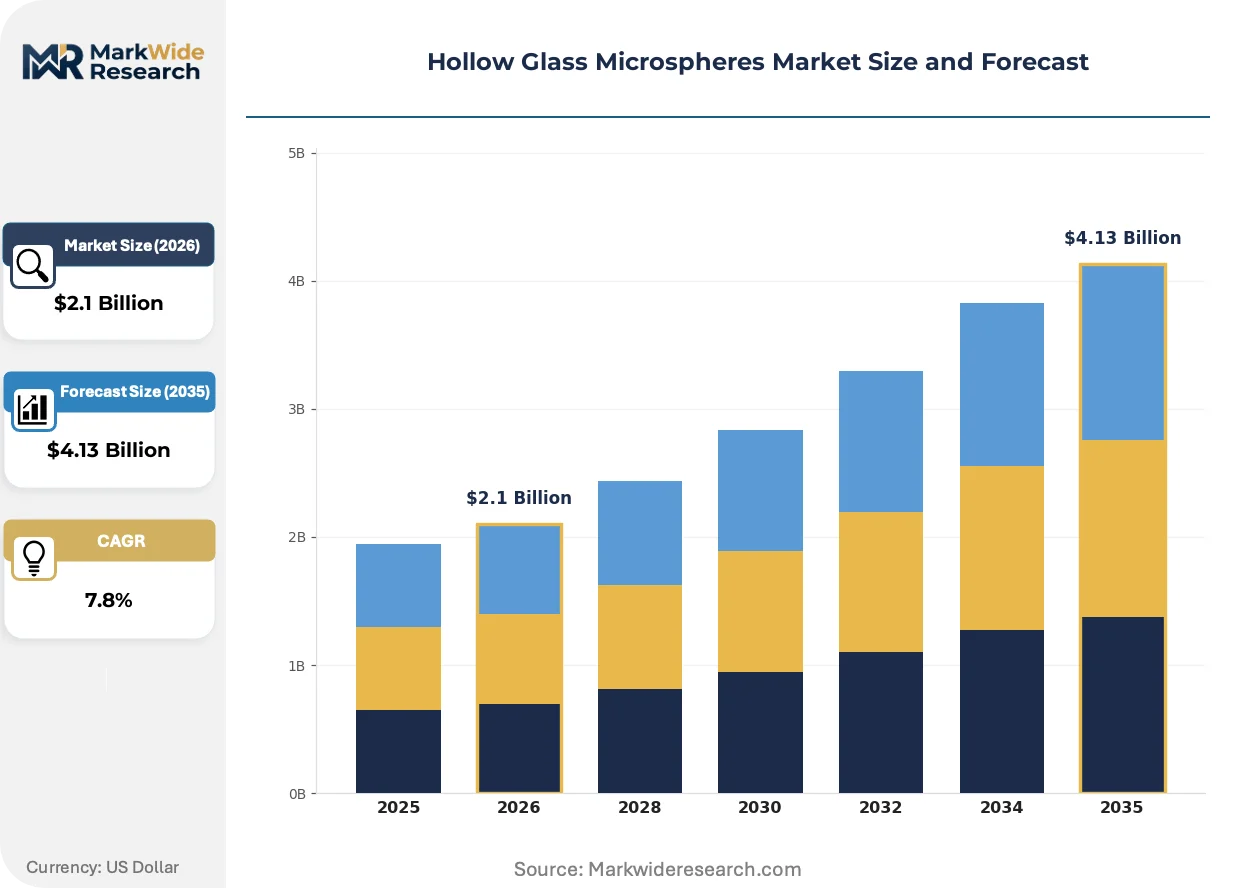
Automotive lightweighting mandates and construction thermal efficiency codes are compressing procurement cycles across hollow glass microsphere supply chains, forcing simultaneous reformulation investments in density reduction and compressive strength.
Growth Catalysts
- Automotive lightweighting mandates:Vehicle manufacturers in Germany and Japan specify hollow glass microspheres for structural composites to meet emissions thresholds. Density reduction targets of 15-20% in underbody applications accelerate procurement from tier-one suppliers.
- REACH compliance differentiation:ECHA registration requirements filter supplier bases in Europe, creating durable market access for compliant borosilicate formulators. Non-compliant importers face raw material sourcing constraints.
- Fly ash microsphere specification:Chinese construction companies source bulk material from domestic producers for high-rise residential thermal insulation. GB standards for building materials institutionalize procurement preferences.
Market Restraints
- Borosilicate raw material volatility:Specialty glass-forming chemist availability concentrates in Pennsylvania and Ohio melting corridors. Toll manufacturers face input cost instability when captive supply chains control spheroidization assets.
- Downhole pressure limitations:Ceramic based grades dominate oil well drilling above 10,000 psi. Hollow glass microspheres fracture under extreme downhole conditions, ceding margin concentration to zirconia and alumina alternatives.
- OSHA silica exposure protocols:Workplace handling requirements across U.S. manufacturing facilities mandate respiratory protection and dust suppression systems. Compliance capital expenditure deters small-batch producers from scaling flame spheroidization operations.
Strategic Opportunities
- Pharmaceutical-grade surface chemistry:Controlled-release applications in oncology and pain management require functionalized microspheres with precise dissolution profiles. Mo-Sci Corporation's expertise demonstrates white space for toll manufacturing partnerships.
- Polymer composite convergence:Thermoplastic integration with polypropylene and nylon matrices enables bumper systems and underbody shields. Vehicle manufacturers in Michigan and Stuttgart pilot structural validation programs.
- EU Green Deal material circularity:Recycled glass feedstock qualification under CSRD reporting frameworks creates premium positioning for closed-loop spheroidization operators. ESG-linked procurement contracts favor verified carbon footprint reductions.
Industry Challenges
- Flame spheroidization technician scarcity:Specialized furnace operation and temperature control expertise concentrates among legacy glass-ceramic workforces in Pennsylvania and Ohio. Training pipelines fail to replace retiring operators.
- Dual certification timelines:Aerospace-grade microspheres require simultaneous FAA material qualification and OEM process validation. Parallel approval tracks extend commercialization cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hollow Glass Microspheres Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fly Ash Based, Raw Material Based, Ceramic Based, Polymer Based Application: Lightweight Concrete, Automotive Components, Oil Well Drilling, Thermal Insulation, Coatings End User: Construction Companies, Vehicle Manufacturers, Drilling Contractors, Paint Producers Packaging Type: Fiber Drums, Bulk Bags, Cardboard Boxes, Plastic Containers |
| Companies Covered | 3M Company, Potters Industries LLC, Dennert Poraver GmbH, Trelleborg AB, Mo-Sci Corporation, Cospheric LLC, Chase Corporation, Sovitec, Matsumoto Yushi-Seiyaku Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hollow Glass Microspheres Market Strategic Shifts & Innovations
Sol-gel manufacturing precision and surface functionalization chemistry are compressing performance gaps between commodity fly ash grades and premium borosilicate formulations, reshaping competitive positioning across application tiers.
Sol-gel derived hollow glass microspheres achieve wall thickness uniformity below 2 microns, enabling compressive strength above 10,000 psi in sub-100 micron diameters. Oilfield services contractors in Texas and Alberta specify these grades for deepwater cementing applications. The technology is displacing flame-spheroidized alternatives in pressure-critical downhole environments where batch-to-batch consistency determines procurement decisions.
EPA emissions thresholds for manufacturing facilities tighten particulate matter and NOx limits annually, requiring scrubber retrofits and continuous emissions monitoring systems. Glass melting operations in Ohio and Pennsylvania face capital allocation decisions between compliance investment and capacity relocation. Smaller spheroidization plants respond by consolidating into shared emissions treatment cooperatives.
Buyers in automotive and aerospace segments now require lot-level thermal conductivity certification with third-party validation, replacing historical supplier self-certification. Tier-one composite laminators in Stuttgart and Nagoya insert independent testing clauses into multi-year supply agreements. This specification tightening concentrates procurement among integrated producers with captive analytical laboratories.
Hollow Glass Microspheres Market Segmentation
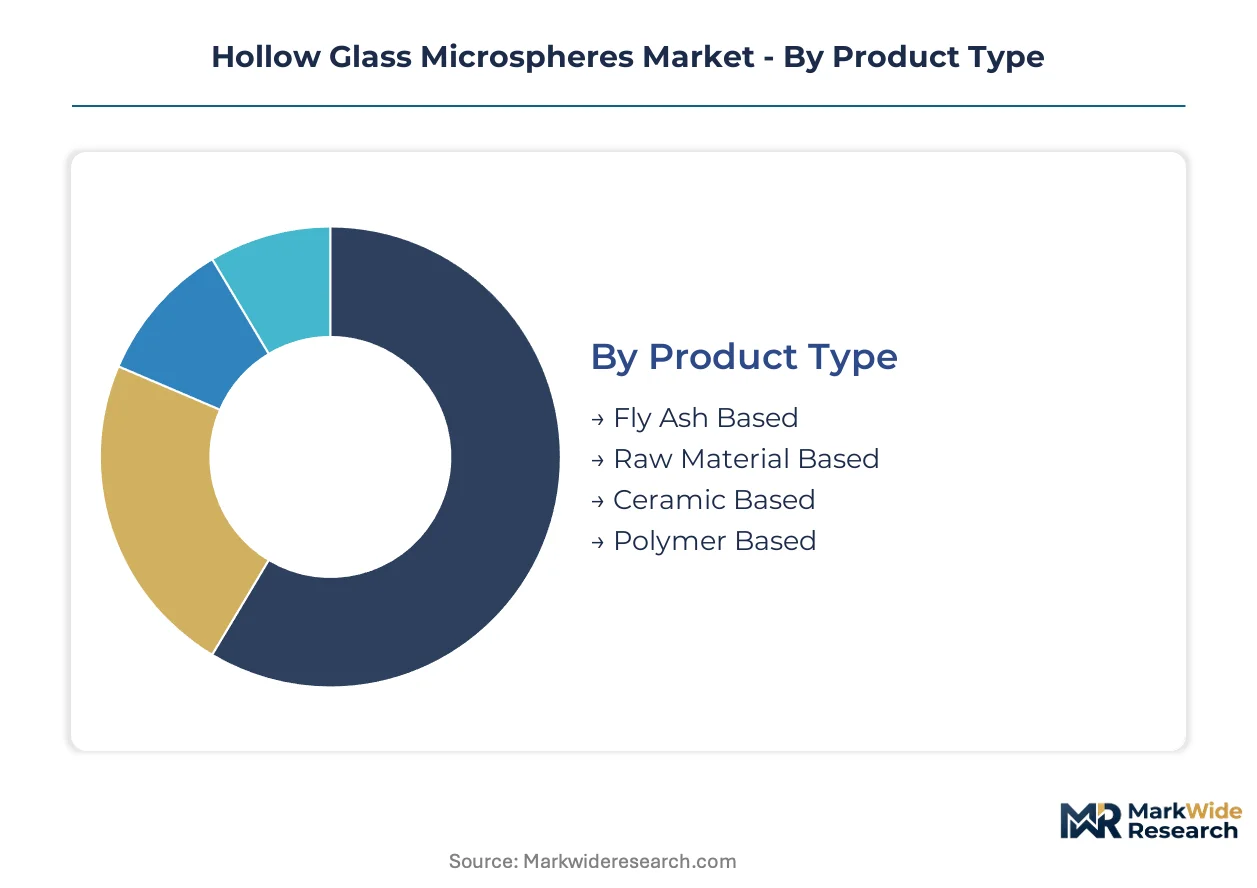
Hollow glass microspheres fragment across four distinct category axes, with product chemistry and application performance requirements driving the sharpest procurement bifurcations. Substitution pressures from ceramic and polymer alternatives reshape competitive dynamics within each tier.
Product Type:
Substitution pressure from ceramic and polymer alternatives concentrates most intensely in high-pressure and high-temperature applications, forcing glass microsphere suppliers to defend density advantages while ceding ground on compressive strength.
- Fly Ash Based:Cenospheres recovered from coal combustion carry densities of 0.7-0.9 g/cm³ with alumina-silicate shells. Chinese construction companies in Shanghai and Shenzhen specify these for high-rise concrete thermal insulation where GB standards institutionalize bulk procurement preferences.
- Raw Material Based:Virgin borosilicate formulations achieve wall thickness below 2 microns through controlled flame spheroidization. Aerospace laminators in Stuttgart and Nagoya demand these for satellite composite structures where lot-level thermal conductivity certification is mandatory.
- Ceramic Based:Zirconia-alumina spheres withstand downhole pressures above 10,000 psi in Texas shale formations.
- Polymer Based:Thermoplastic microspheres integrate with polypropylene matrices for Michigan vehicle underbody shields.
Fly ash based microspheres anchor the volume base while polymer based variants gain share at the steepest rate.
Application:
Application tiering follows compressive strength thresholds, with density-critical uses commanding premium formulation investments and pressure-critical uses ceding to ceramic alternatives.
- Lightweight Concrete:Fly ash microspheres reduce structural concrete density by 15-25% while maintaining flexural strength above 4 MPa. Chinese residential tower developers in Guangzhou and Chengdu embed these in precast panels where MEE environmental enforcement constrains domestic production quotas.
- Automotive Components:Borosilicate grades at 0.3-0.4 g/cm³ enable bumper systems and underbody shields that trim vehicle mass. German OEMs in Wolfsburg and Munich validate thermoplastic integration programs with tier-one composite laminators.
- Oil Well Drilling:Deepwater cementing in the Gulf of Mexico specifies sol-gel derived spheres for consistent batch performance.
- Thermal Insulation:European building retrofits under EU Green Deal efficiency codes specify low-thermal-conductivity grades.
- Coatings:Marine and industrial paint formulators leverage buoyancy for sag-resistant spray applications.
Lightweight concrete dominates procurement tonnage while automotive components expand most quickly under emissions mandate pressure.
End User:
End-user concentration maps directly to regulatory enforcement intensity, with construction and automotive sectors facing the most stringent material certification requirements.
- Construction Companies:Chinese state-owned developers source fly ash microspheres through centralized procurement platforms. GB standards compliance determines supplier qualification for high-rise residential projects in tier-one cities.
- Vehicle Manufacturers:German and Japanese OEMs specify borosilicate grades through validated tier-one laminators. REACH registration and FAA material qualification create dual certification barriers for new entrants.
- Drilling Contractors:Oilfield services firms in Texas and Alberta select sol-gel grades for deepwater cementing consistency.
- Paint Producers:Industrial coating formulators specify buoyancy-modified grades for marine and infrastructure applications.
Construction companies anchor the volume base while vehicle manufacturers drive specification tightening fastest.
Packaging Type:
Packaging selection hinges on silica dust exposure protocols and bulk handling economics, with OSHA workplace limits forcing capital-intensive containment investments.
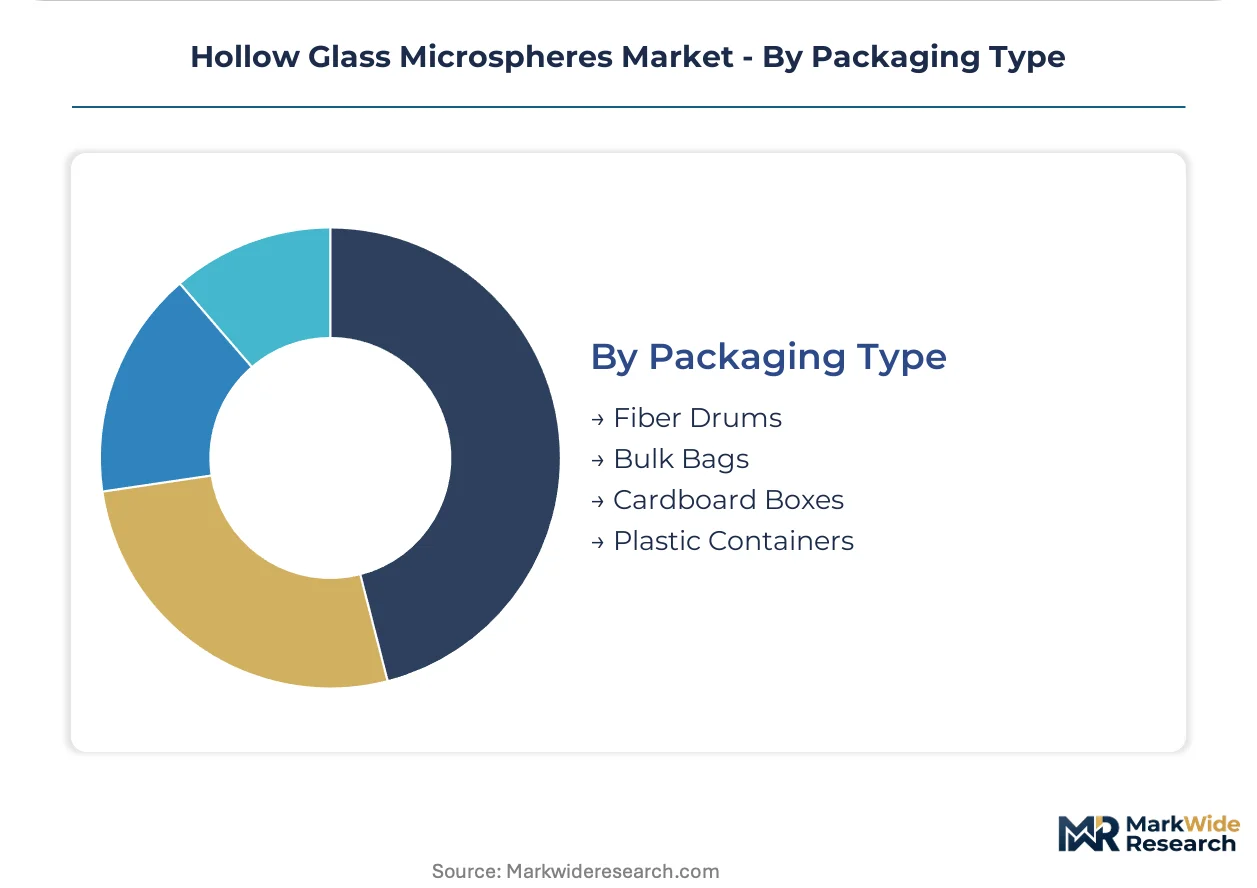
- Fiber Drums:UN-certified fiber drums with polyethylene liners satisfy aerospace-grade lot traceability requirements. Pennsylvania spheroidization plants ship borosilicate microspheres to Stuttgart laminators in sealed 200-liter drums with independent thermal conductivity certificates.
- Bulk Bags:FIBC containers with static-dissipative liners enable pneumatic unloading at Chinese concrete batching plants. Construction companies in Shanghai specify one-ton bulk bags for high-rise project economies.
- Cardboard Boxes:Multi-wall corrugated containers serve small-batch coating formulators with manual handling protocols.
- Plastic Containers:HDPE pails with gamma-sealed lids protect pharmaceutical-grade surface-functionalized grades.
Bulk bags anchor the volume base while fiber drums gain share fastest under certification and traceability requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes hollow glass microspheres primarily for construction thermal insulation, while Germany and Japan drive specification-grade demand through automotive lightweighting programs. This consumption-mix differential shapes regional supply chain investments and regulatory compliance priorities.
China
State-owned developers in Shanghai and Shenzhen embed fly ash microspheres in precast concrete panels for high-rise residential towers. MEE environmental enforcement constrains domestic production quotas and shapes export availability. Yangtze River Delta spheroidization plants supply bulk material to centralized procurement platforms serving tier-one city construction projects.
Germany
OEMs in Wolfsburg and Munich validate borosilicate grades for bumper systems and underbody shields to meet EU emissions thresholds. REACH registration requirements filter supplier bases, creating durable market access for compliant formulators. Stuttgart-based composite laminators demand lot-level thermal conductivity certification with third-party validation.
United States
Pennsylvania and Ohio melting corridors concentrate specialized glass-forming chemist availability for captive spheroidization operations. EPA emissions thresholds and OSHA silica exposure protocols mandate scrubber retrofits and respiratory protection systems. Oilfield services contractors in Texas specify sol-gel derived grades for deepwater cementing consistency.
Japan
Vehicle manufacturers in Nagoya integrate polymer-based microspheres into thermoplastic matrices for structural validation programs. METI industrial standards and JIS certification requirements govern material qualification timelines. Kansai-based tier-one suppliers pilot underbody shield applications with density reduction targets of 15-20%.
Canada
Alberta drilling contractors source ceramic-alternative grades for shale formation cementing where downhole pressure resistance determines procurement. Health Canada workplace exposure guidelines align with OSHA protocols for silica handling across manufacturing facilities. Ontario-based coating formulators specify buoyancy-modified grades for marine infrastructure applications.
Hollow Glass Microspheres Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with captive borosilicate formulation expertise and vertically controlled melting assets defining the upper stratum. The competitive landscape bifurcates between premium aerospace-grade suppliers and volume-oriented construction material producers. Two dominant archetypes emerge: integrated producers with in-house spheroidization capabilities and toll manufacturers dependent on external feedstock supply. Capacity consolidation and certification-driven portfolio diversification represent the primary competitive moves reshaping supplier positioning.
Among North American integrated producers, 3M Company and Potters Industries LLC exemplify the premium-tier archetype through captive supply chain control. Mo-Sci Corporation occupies a specialist position within the pharmaceutical-grade surface chemistry segment. Dennert Poraver GmbH represents the European volume-tier approach, while Trelleborg AB and Matsumoto Yushi-Seiyaku Co., Ltd. anchor regional supply positions in their respective home markets.
| Leading Market Players |
|---|
| 3M Company |
| Potters Industries LLC |
| Dennert Poraver GmbH |
| Trelleborg AB |
| Mo-Sci Corporation |
| Cospheric LLC |
| Chase Corporation |
| Sovitec |
| Matsumoto Yushi-Seiyaku Co., Ltd. |
| Others |
Cost & Logistics Intelligence
REACH registration requirements in Europe gate both supplier qualification and price differentiation simultaneously, filtering non-compliant importers from premium tiers while compressing margins for toll manufacturers dependent on external borosilicate feedstock. Buyers in Stuttgart and Nagoya now mandate lot-level thermal conductivity certification, forcing integrated producers to absorb analytical laboratory investments that spot-market suppliers cannot match.
Pricing Analysis
Long-term offtake agreements dominate procurement between Pennsylvania spheroidization plants and German automotive OEMs, locking in volume commitments that insulate integrated producers from spot-market volatility. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade borosilicate microspheres with FAA qualification from construction-grade fly ash cenospheres and commodity ceramic alternatives. Cost compression in the volume tier is intensifying because Chinese state-owned developers consolidate purchasing through centralized procurement platforms. Construction companies in Shanghai exhibit the highest price sensitivity, while aerospace laminators in Stuttgart prioritize certification reliability over unit cost.
Supply Chain Analysis
China, the United States, and Germany anchor hollow glass microsphere production, with Yangtze River Delta plants supplying bulk fly ash grades, Pennsylvania-Ohio melting corridors concentrating borosilicate expertise, and Stuttgart-area laminators demanding qualified aerospace material. Specialty glass-forming chemist availability draws from legacy glass-ceramic workforces in Pennsylvania and Ohio, while borosilicate raw material sourcing rests on captive spheroidization assets controlled by integrated producers. Single-source vulnerability concentrates in flame spheroidization technician expertise, where retiring operators outpace training pipelines. Distribution runs through tier-one composite laminators in Germany and Japan who validate material for downstream OEM integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for formulation support and application engineering expand faster than base material sales, creating recurring revenue layers that insulate suppliers from commodity pricing cycles in construction-grade segments.
For Market Incumbents: Shield premium positioning by deepening captive borosilicate formulation expertise and accelerating FAA material qualification timelines to outpace emerging sol-gel specialists. Ceramic alternatives threaten margin concentration in oil well drilling above 10,000 psi, demanding defensive R&D investment in compressive strength advancement. Backward integration into recycled glass feedstock qualification under CSRD frameworks captures ESG-linked procurement contracts from EU Green Deal retrofit programs. For New Entrants and Emerging Players: Toll manufacturing partnerships for pharmaceutical-grade surface chemistry represent the most penetrable white space, where Mo-Sci Corporation's expertise demonstrates unmet demand in controlled-release oncology applications. Sol-gel manufacturing precision for deepwater cementing consistency offers a second entry vector, with Texas and Alberta drilling contractors prioritizing batch-to-batch uniformity over brand heritage. Target independent analytical laboratory certification as the primary go-to-market angle, replacing historical supplier self-certification with third-party validation. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-optimized spheroidization assets in Pennsylvania and Ohio melting corridors. Long-term viability over the coming decade hinges on regulatory compliance differentiation rather than volume scale, favoring targets with captive REACH registration and FAA qualification pipelines. Watch ECHA enforcement intensity against non-compliant importers as the inflection indicator for premium-tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Glass Feedstock | CSRD reporting frameworks favor verified carbon footprint reductions in EU procurement. |
| Long-term Supply Agreement with Tier-One Laminators | Stuttgart and Nagoya composite validators lock in multi-year aerospace-grade material commitments. |
| Capacity Expansion in Captive Spheroidization Assets | Pennsylvania and Ohio melting corridors concentrate scarce glass-forming chemist expertise. |
| Joint Venture for Sol-Gel Manufacturing Scale-Up | Texas drilling contractors demand consistent batch performance for deepwater cementing applications. |
| Green Certification Program for Fly Ash Recovery | MEE environmental enforcement in China constrains domestic production quotas and shapes export availability. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with plant managers at spheroidization facilities, procurement leads at German automotive OEMs, technical R&D directors in glass-ceramic formulation, and oilfield services contractors in Texas, combined with secondary validation through customs and trade data, SEC 10-K filings from listed materials companies, ECHA REACH registration databases, and GB standards documentation for Chinese building materials. Bottom-up volume modeling triangulated against top-down market sizing across product chemistry tiers.
Across the analysis window, the forecasting framework modeled hollow glass microsphere demand through segmentation dimensions spanning product chemistry grade, end-use application intensity, regional regulatory cluster, and packaging format certification requirements. CAGRs were derived from regression analysis of historical procurement patterns and projected regulatory enforcement trajectories, incorporating automotive lightweighting mandate compliance timelines and EU Green Deal material circularity targets as industry-specific inputs.
Underlying assumptions cover sustained REACH registration enforcement intensity, EPA emissions threshold tightening, and MEE production quota constraints, with deviation risk concentrated in ceramic substitution rates for high-pressure oilfield applications and flame spheroidization technician availability. Recalibration cycles align with material shifts in regulatory enforcement intensity and automotive OEM validation program completions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals & Materials
Cellulose Esters and Ethers Market
Chemicals & Materials
Polyphosphate Market
Chemicals & Materials
Global Sodium Lauryl Sulfate Market
Chemicals & Materials
Global Palm Wax Market
Chemicals & Materials
Heat Resistant Sealant Market
Chemicals & Materials
Tungsten Disulphide Nanoparticles Market
Chemicals & Materials
Nomex Honeycomb Market
Chemicals & Materials
Halogen Biocides Market
Chemicals & Materials
North America Polyphenylene Sulfide Compounds Market
Chemicals & Materials
Bio-Fouling Prevention Coatings Market
Chemicals & Materials
Ethyl Cellulose Market
Chemicals & Materials
Roofing Adhesive Market
Chemicals & Materials
Europe and MENA Pulp Market
Chemicals & Materials
3D Printing Powder Market
Chemicals & Materials
Biorenewable Catalysts Market
Chemicals & Materials
Asia-Pacific Amino Acids Market