
 Recycled Glass Market | 2026-2036
Recycled Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Recycled Glass Market Analysis
Asset-light leasing models for optical sorting equipment is fragmenting competitive entry barriers in cullet processing. Strategic Materials Inc. leverages its North American collection network to sustain volume throughput across multiple glass grades. Owens-Illinois Inc. anchors container manufacturing demand through long-term supply agreements with municipal recyclers. Momentum Recycling LLC specializes in post-industrial flat glass recovery, occupying a niche with higher purity thresholds than consumer-stream cullet.
Recycled glass comprises post-consumer and post-industrial cullet processed to specified particle sizes and contamination levels for remelting or alternative applications. The material typically contains less than 0.5% ceramic, stone, and porcelain contaminants for container remelting, with stricter thresholds for optical and specialty glass. Container glass dominates volume flows due to established deposit-return infrastructure and closed-loop bottle-to-bottle pathways. Fiberglass manufacturing represents the fastest-growing application segment, as construction-grade cullet substitutes virgin raw materials in insulation and composite production. Glass powder for cement and concrete additives commands premium positioning where ASTM C1866 standards govern pozzolanic performance.
The EPA promotes glass recycling through national waste reduction benchmarks, while the EU Green Deal mandates minimum recycled content in packaging through delegated regulations. FDA food-contact rules and state-level bottle bill frameworks shape collection economics and processor certification requirements. Stakeholders must monitor how tightening contamination standards affect sorting technology investments and regional cullet price spreads.
Market Dynamics
Container manufacturers face mounting pressure to secure cullet supply chains as the EU Green Deal tightens post-consumer content mandates, forcing processors to invest in optical sorting infrastructure to meet contamination thresholds below 0.5% ceramic and stone.
Growth Catalysts
- Fiberglass insulation demand:Construction-grade cullet substitutes virgin raw materials in composite production, with Owens-Illinois and Momentum Recycling expanding flat glass recovery capacity for this segment.
- EU Green Deal packaging mandates:Delegated regulations impose minimum recycled content thresholds, compelling beverage producers to source bottle-to-bottle cullet through municipal collection networks.
- Dual-stream infrastructure expansion:Germany's deposit-return systems and color-separated collection create reliable supply chains that processors in France and Italy are now replicating.
Market Restraints
- Natural gas price volatility:Remelting cullet requires 30% less energy than virgin batch, but furnace operators remain exposed to European energy market fluctuations that compress operating margins.
- Contamination sorting capex:Laser and camera-based optical sorters cost $500,000 to $2 million per installation, creating capital barriers for mid-scale processors in Eastern Europe.
- Ceramic-laden single-stream feedstock:US municipalities running commingled collection produce cullet with 2-5% contamination, rendering material unsuitable for food-contact container remelting under FDA rules.
Strategic Opportunities
- Glass powder for cement additives:ASTM C1866-compliant pozzolanic material commands premium positioning in concrete production, with construction verticals in Spain and Portugal testing pilot volumes.
- Asset-light equipment leasing:Optical sorting vendors now offer per-ton processing contracts that lower entry barriers for regional cullet processors in Poland and Czechia.
- Post-industrial flat glass recovery:Solar panel and window manufacturing scrap yields higher-purity cullet than consumer streams, occupying a niche with stricter optical glass thresholds.
Industry Challenges
- Color-sorting technician shortage:Manual separation of amber, flint, and green glass requires trained operators, and vocational programs in Italy and Spain have not kept pace with processor expansion.
- Legacy furnace reconfiguration:Container glass plants designed for 30% cullet maximum face technical complexity retrofitting equipment to handle 70% post-consumer feedstock without quality degradation.
- Multi-jurisdiction certification timelines:Processors seeking FDA food-contact approval alongside EU EFSA compliance face 18-24 month documentation cycles that delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycled Glass Market |
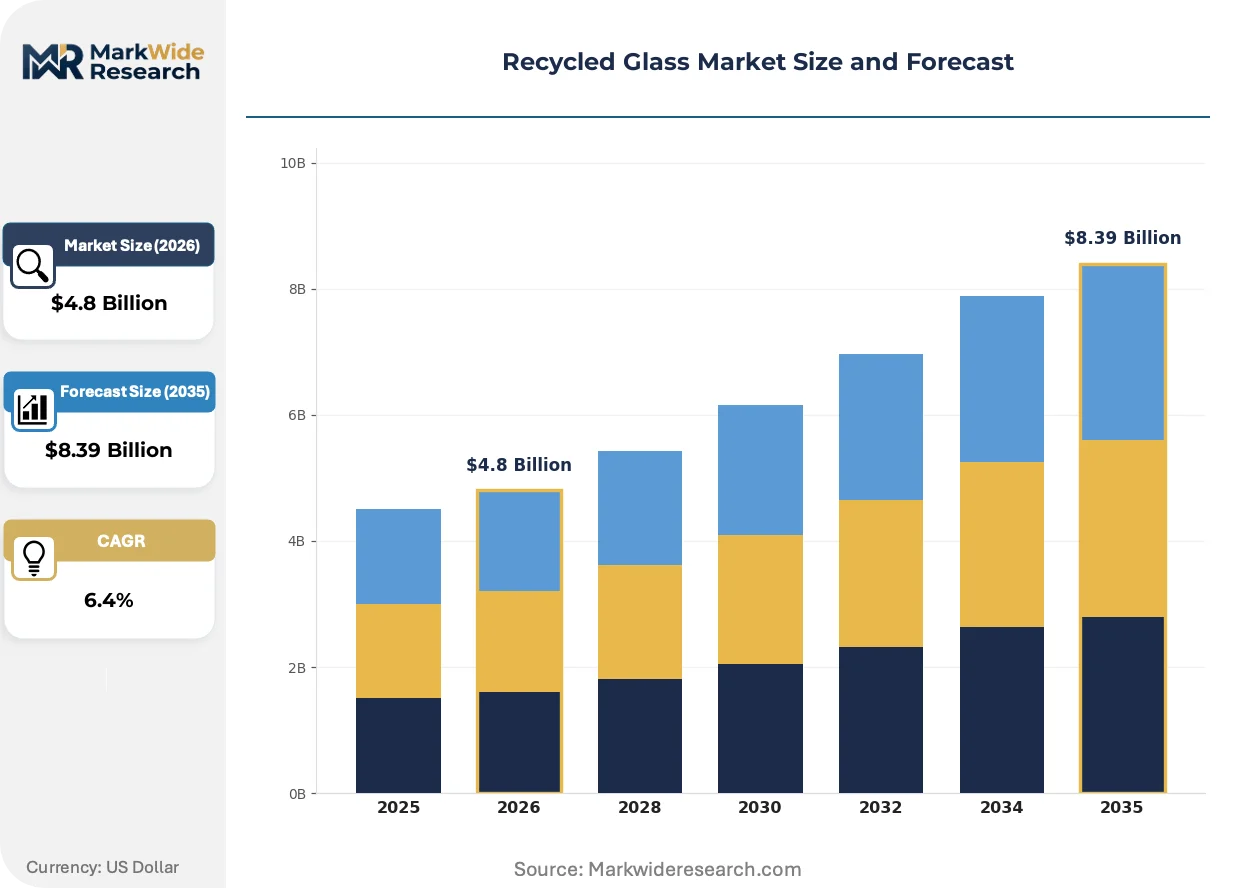
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Container Glass, Flat Glass, Fiberglass, Glass Powder Application: Construction, Beverage Packaging, Fiberglass Manufacturing, Decorative Items End User: Manufacturers, Architects, Construction Companies, Retailers Quality Grade: Food Grade, Industrial Grade, Construction Grade, Recycled Grade |
| Companies Covered | Strategic Materials Inc., Vetropack Holding, Owens-Illinois Inc., Ardagh Group, Momentum Recycling LLC, Sibelco, Glass Recycled Surfaces, URM/Berryman Glass Recycling, Dlubak Glass Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycled Glass Market Emerging Trajectories
Digital sorting technologies and policy-driven circular economy mandates are compressing traditional cullet supply chains, while procurement models shift from spot-market trading toward long-term offtake agreements tied to certified contamination thresholds.
AI-powered optical sorting is virtualizing quality control workflows that previously required manual inspection stations. Container manufacturers in Germany and France are adopting these systems at 15-20% annual replacement rates for legacy mechanical sorters. The technology is virtualizing processor labor structures, reducing headcount per ton while tightening ceramic detection to 0.1% thresholds.
REACH delegated acts on packaging waste are forcing producers to document recycled content through mass-balance accounting. Industrial consequence includes mandatory third-party verification of post-consumer cullet origin. Container glass producers in Belgium and Netherlands face the steepest compliance curves, with some redirecting procurement toward certified municipal streams rather than mixed post-industrial sources.
Long-term supply agreements now displace spot-market purchasing for high-purity cullet. Strategic Materials and Owens-Illinois have locked five- to seven-year contracts with municipal recyclers, freezing price volatility for container-grade material. This pattern is most visible in US states with bottle bill frameworks, where guaranteed volume flows justify processor investment in color-separated processing lines.
Recycled Glass Market Segmentation
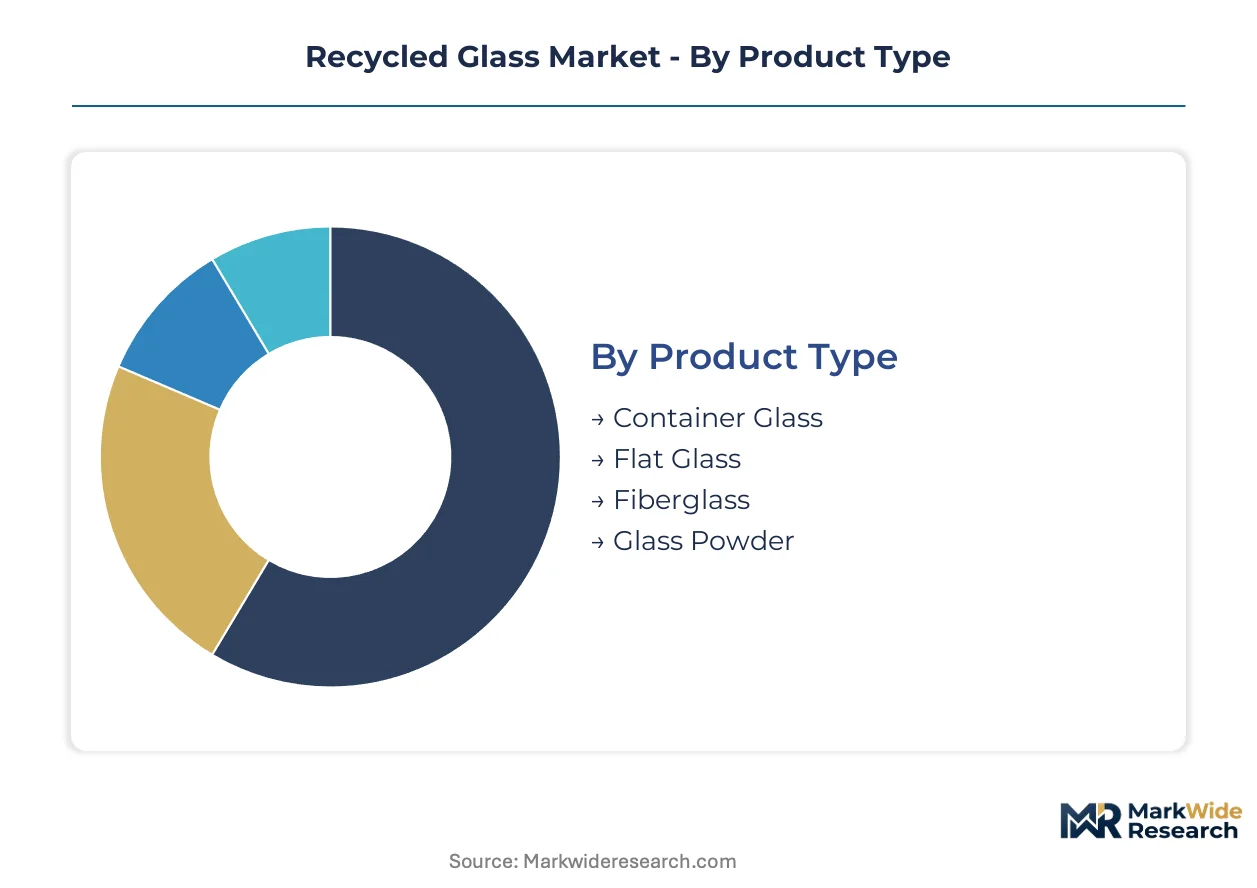
Segmentation in recycled glass markets determines pricing tiers, contamination thresholds, and furnace compatibility requirements. Each dimension creates distinct procurement channels and certification burdens that processors must navigate.
Product Type:
After-sales service intensity varies sharply across product types, with container glass demanding continuous color-sorting calibration and flat glass requiring purity verification protocols.
- Container Glass:Post-consumer cullet from beverage bottles contains amber, flint, and green streams requiring optical separation to below 0.5% ceramic contamination. Germany's dual-stream collection infrastructure supplies bottle-to-bottle manufacturers with color-separated feedstock meeting EU Green Deal mandates.
- Flat Glass:Post-industrial scrap from window and solar panel manufacturing yields higher-purity cullet than consumer streams. Momentum Recycling captures this niche in North America where optical glass manufacturers pay premiums for stricter thresholds.
- Fiberglass:Construction-grade cullet substitutes virgin raw materials in insulation and composite production, with Owens-Illinois expanding recovery capacity for this expanding segment.
- Glass Powder:ASTM C1866-compliant pozzolanic material for cement additives commands premium positioning where concrete producers test pilot volumes in Spain and Portugal.
Container glass holds the largest share; momentum sits with fiberglass as construction markets scale cullet substitution.
Application:
Cost tier differentiation separates commodity cullet from certified grades, with beverage packaging commanding the strictest contamination premiums.
- Construction:Glass powder and coarse cullet replace virgin aggregate in concrete and road base applications. Spain's pilot programs for ASTM C1866-compliant additives are expanding procurement volumes for certified processors.
- Beverage Packaging:Bottle-to-bottle remelting requires FDA food-contact approval and sub-0.5% ceramic thresholds. EU Green Deal delegated regulations now mandate minimum post-consumer content, forcing producers toward municipal collection networks with guaranteed supply agreements.
- Fiberglass Manufacturing:Insulation and composite producers accept higher contamination tolerance than container manufacturers, sourcing mixed-color cullet at discounted spreads.
- Decorative Items:Artisan glass and landscaping applications utilize unsorted mixed cullet with minimal processing investment.
Beverage packaging commands premium pricing; construction applications are climbing the fastest as cement substitution scales.
End User:
Customer type determines volume scale and contract structure, with manufacturers locking long-term offtake while retailers purchase spot quantities.
- Manufacturers:Container and fiberglass producers negotiate five- to seven-year supply agreements with municipal recyclers, freezing price volatility and justifying color-separated processing line investments.
- Architects:Specification of recycled content in green building certifications drives demand for documented post-consumer cullet with third-party verification.
- Construction Companies:Bulk procurement of construction-grade cullet for concrete additives and aggregate replacement, with volume discounts tied to ASTM compliance.
- Retailers:Small-lot purchasers of decorative cullet for landscaping and consumer products, operating on spot-market pricing with minimal certification requirements.
Manufacturers dominate procurement volumes; architects are gaining share fastest as green building standards tighten recycled content specifications.
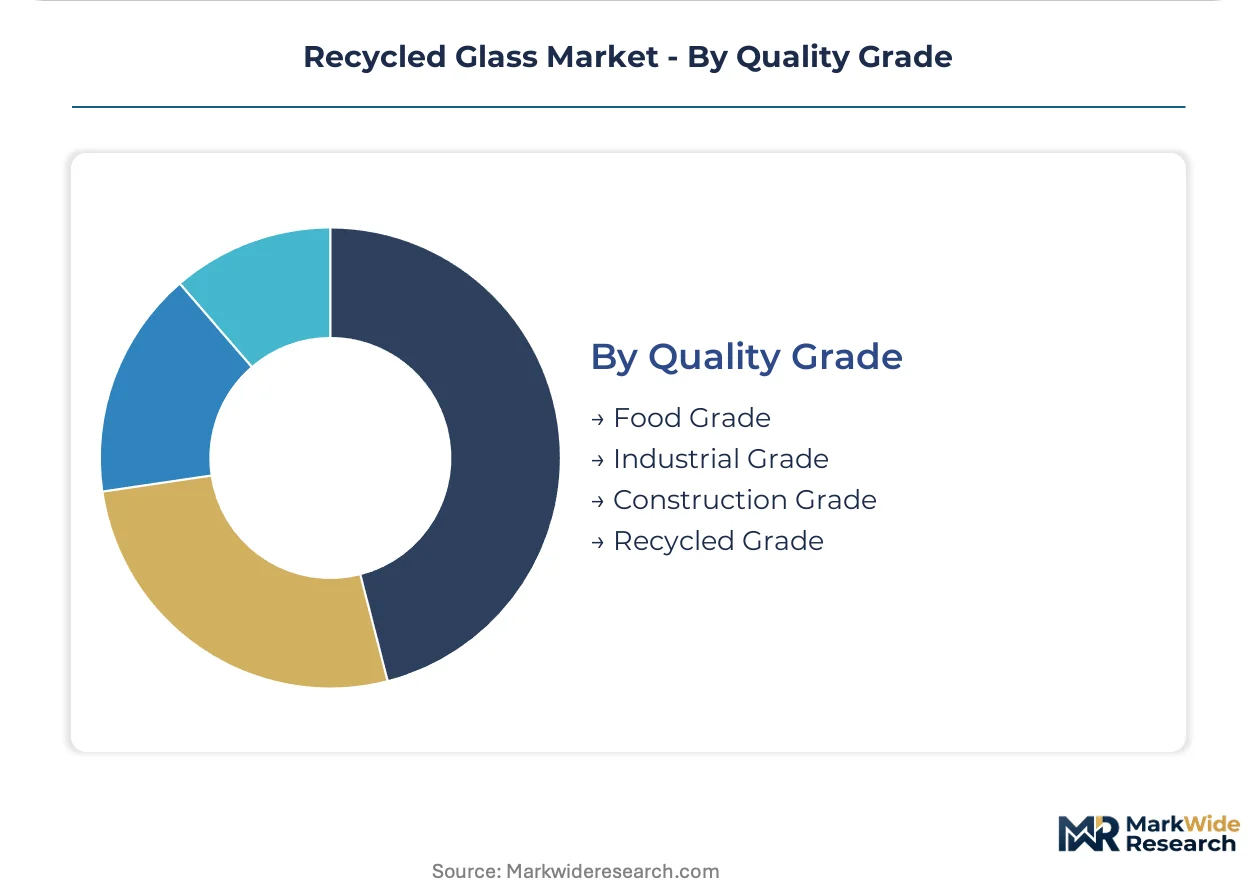
Quality Grade:
Margin stratification follows certification burden, with food-grade material requiring 18-24 month approval timelines that delay market entry.
- Food Grade:FDA food-contact and EU EFSA compliance mandates sub-0.5% ceramic, stone, and porcelain contamination. Multi-jurisdiction certification creates documentation cycles that freeze processor expansion timelines.
- Industrial Grade:Fiberglass and container manufacturing accept moderate contamination levels, with laser sorting infrastructure investments of $500,000 to $2 million per installation creating capital barriers in Eastern Europe.
- Construction Grade:Coarse cullet for aggregate and road base applications tolerates higher contamination, with ASTM C1866 governing only the powder segment for pozzolanic performance.
- Recycled Grade:Unsorted mixed cullet for decorative and fill applications, bypassing optical sorting entirely and trading at the deepest discounts to certified grades.
Food grade captures premium spreads; construction grade is expanding most quickly as infrastructure projects scale cullet substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Container manufacturers cluster near municipal collection networks with guaranteed cullet flows. Procurement patterns favor dual-stream infrastructure regions where color-separated feedstock meets EU Green Deal thresholds.
Germany
Dual-stream recycling infrastructure and packaging deposit laws create Europe's most reliable cullet supply chains. The EU Green Deal's circular economy requirements force producers to raise post-consumer content thresholds. Bavaria's glass processing clusters around Nuremberg supply container manufacturers with sub-0.5% contamination material.
United States
Beverage packaging demand concentrates in states with bottle bill frameworks guaranteeing volume flows. FDA food-contact rules and EPA waste reduction benchmarks shape collection economics and processor certification. Strategic Materials leverages its North American collection network across California and New York to sustain throughput across multiple glass grades.
France
Municipal recyclers face tightening contamination standards that drive optical sorting technology investments. REACH delegated acts on packaging waste mandate third-party verification of post-consumer cullet origin. The Paris basin and Lyon corridor host expanding processor capacity replicating Germany's color-separated collection models.
Spain
Construction-grade cullet demand accelerates as concrete producers test ASTM C1866-compliant glass powder additives. National waste frameworks align with EU circular economy targets. Catalonia's pilot programs for pozzolanic material are expanding procurement volumes for certified processors in Barcelona.
Italy
Container glass remelting depends on manual color-sorting operations facing technician shortages. EU EFSA compliance creates documentation cycles that freeze processor expansion timelines. Lombardy's glass manufacturing belt around Milan sources cullet through long-term municipal supply agreements.
Recycled Glass Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Consolidation pressures concentrate around optical sorting infrastructure investments of $500,000 to $2 million per installation. Three archetypes dominate: collection-network operators, container manufacturing integrators, and niche purity specialists. Competitive moves center on long-term offtake agreements and asset-light equipment leasing models that lower regional entry barriers.
Within the collection-network tier, Strategic Materials Inc. exemplifies volume-throughput positioning across North American municipal streams. Among container manufacturing integrators, Owens-Illinois Inc. anchors demand-side consolidation through multi-year supply agreements. Specialists in post-industrial flat glass recovery include Momentum Recycling LLC, occupying a niche with stricter purity thresholds than consumer-stream cullet.
| Leading Market Players |
|---|
| Strategic Materials Inc. |
| Vetropack Holding |
| Owens-Illinois Inc. |
| Ardagh Group |
| Momentum Recycling LLC |
| Sibelco |
| Glass Recycled Surfaces |
| URM/Berryman Glass Recycling |
| Dlubak Glass Company |
| Others |
Supply Flow & Price Mechanics
EU Green Deal delegated acts on packaging waste function as a regulatory chokepoint that simultaneously widens price spreads between certified and uncertified cullet grades and forces supply chain reconfiguration toward municipal collection networks with guaranteed volume flows.
Pricing Analysis
Cost-plus contracts indexed to natural gas benchmarks dominate container-grade cullet procurement, with Owens-Illinois and Strategic Materials locking five- to seven-year agreements that freeze volatility. Price differentiation hinges on certification grade and volume scale, with FDA food-contact material commanding substantial premiums over construction-grade alternatives. Cost compression in mixed-color streams is intensifying because single-stream municipalities produce feedstock with 2-5% contamination unsuitable for bottle-to-bottle remelting. Fiberglass manufacturers exhibit lowest price sensitivity due to higher contamination tolerance, while beverage packaging producers face acute cost pressure from mandated post-consumer content thresholds.
Supply Chain Analysis
Single-source vulnerability to Germany's dual-stream collection infrastructure dominates supply risk for EU container manufacturers dependent on Bavarian processing clusters around Nuremberg. Raw material flows draw from post-consumer municipal streams, post-industrial flat glass scrap, and construction demolition recovery. The supply chain rests on optical sorting equipment with $500,000 to $2 million installation costs creating capital barriers for Eastern European processors. Distribution runs through long-term offtake agreements displacing spot-market purchasing for high-purity material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment leasing and per-ton processing contracts represent a service-attach opportunity expanding faster than hardware sales, as optical sorting vendors shift from capital expenditure models toward recurring-revenue arrangements that lower regional entry barriers.
For Market Incumbents: Harden color-separated processing capacity in Germany and France against emerging asset-light competitors by securing exclusive municipal collection concessions. Backward integration into collection networks insulates volume throughput from new entrant leasing models. Investment in AI-powered optical sorting with 0.1% ceramic detection thresholds preserves premium positioning as EU contamination mandates tighten.
For New Entrants and Emerging Players: Poland and Czechia's underpenetrated optical sorting infrastructure offers white-space expansion where per-ton equipment leasing contracts bypass capital barriers. Post-industrial flat glass recovery from solar panel manufacturing yields higher-purity cullet than consumer streams with less competition from established municipal networks. Target glass powder for cement additives in Spain and Portugal where ASTM C1866 pilot programs are scaling procurement volumes.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors collection-network operators with locked municipal supply agreements over standalone processing assets. Five-to-ten year viability hinges on exposure to EU Green Deal compliance curves rather than spot-market commodity exposure. Monitor REACH delegated act implementation timelines as the inflection signal for certified cullet demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Optical Sorting Infrastructure Deployment | AI-powered ceramic detection to 0.1% thresholds meets EU Green Deal mandates for container manufacturers in Germany. |
| Backward Integration into Collection Networks | Exclusive municipal concessions lock volume throughput against asset-light leasing competitors in France and Italy. |
| Post-Industrial Flat Glass Recovery Expansion | Solar panel and window manufacturing scrap yields premium cullet for optical glass thresholds in North America. |
| Glass Powder Certification for Cement Additives | ASTM C1866-compliant pozzolanic material opens construction verticals in Spain and Portugal pilot programs. |
| Long-Term Offtake Agreement Structuring | Five- to seven-year contracts freeze price volatility and justify color-separated processing line investments. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with cullet processors, container manufacturing procurement leads, municipal recycling coordinators, and optical sorting equipment vendors; and secondary validation against EPA waste reduction benchmarks, EU Green Deal delegated regulations, FDA food-contact guidance documents, and ASTM C1866 standards. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, quality grade, and regional regulatory cluster dimensions.
Forecast inputs considered natural gas price trajectories, EU packaging waste mandate implementation schedules, and optical sorting technology replacement rates across the projection horizon. Segmentation dimensions modeled include container versus flat versus fiberglass product categories, beverage packaging versus construction versus decorative applications, and food-grade versus industrial-grade versus construction-grade quality tiers. CAGRs derived from regression analysis of historical cullet price spreads and processor capacity expansion patterns.
Practitioners should monitor EU Green Deal delegated act enforcement intensity and natural gas market volatility for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Technical Glass Market
Glass
Screen-Printing Glass Market
Glass
Glass Lens Market
Glass
Glass Mat Thermoplastic Market
Glass
Asia-Pacific Silica Sand Market
Glass
Porous Glass Market
Glass
Latin America Flat Glass Market
Glass
Mirrored Glass Market
Glass
Silica Sol Market
Glass
India Flat Glass Market
Glass
Glass Insulator Market
Glass
Global Energy Efficient Glass Market
Glass
Glazing Gel Market
Glass
Tempered Glass Market
Glass
Global Anti-Reflective Glass Market
Glass
Global Scratch Resistant Glass Market