
 Global Wind Turbine Composites Material Market | 2026-2036
Global Wind Turbine Composites Material Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wind Turbine Composites Material Market Intelligence
The capability gap between integrated carbon fiber producers and specialized resin formulators is unwinding the traditional supply structure. Toray Industries leverages its extensive carbon fiber production scale to secure large-volume contracts directly with major turbine manufacturers. In contrast, Gurit Holding specializes in providing core materials and structural engineering services for complex blade optimization projects. Hexcel Corporation competes by offering advanced prepregs and honeycomb materials for high-performance offshore applications.
Wind turbine composites are engineered materials, primarily fiber-reinforced polymers, used to construct lightweight, durable, and aerodynamically efficient turbine blades. These materials typically combine glass or carbon fibers within an epoxy resin matrix to achieve high tensile strength and fatigue resistance against extreme wind loads. Glass fiber remains the dominant material type due to its cost-effectiveness, while carbon fiber is becoming essential for blades longer than 80 meters. Turbine manufacturers, the primary end user type, drive procurement specifications for these advanced materials.
The EU's REACH regulation and Green Deal initiatives pressure manufacturers to develop recyclable, sustainable composite materials. In China, MEE directives and dual carbon goals incentivize larger, more efficient turbines, influencing material selection toward high-modulus carbon fiber. Navigating divergent regional standards for end-of-life blade management and material traceability remains a critical strategic challenge for suppliers.
Market Dynamics
The central structural force shaping the market is the bifurcation of material requirements, driven by the simultaneous need for cost-effective glass fiber in mainstream turbines and high-performance carbon fiber for next-generation, large-scale offshore blades exceeding 80 meters.
Growth Catalysts
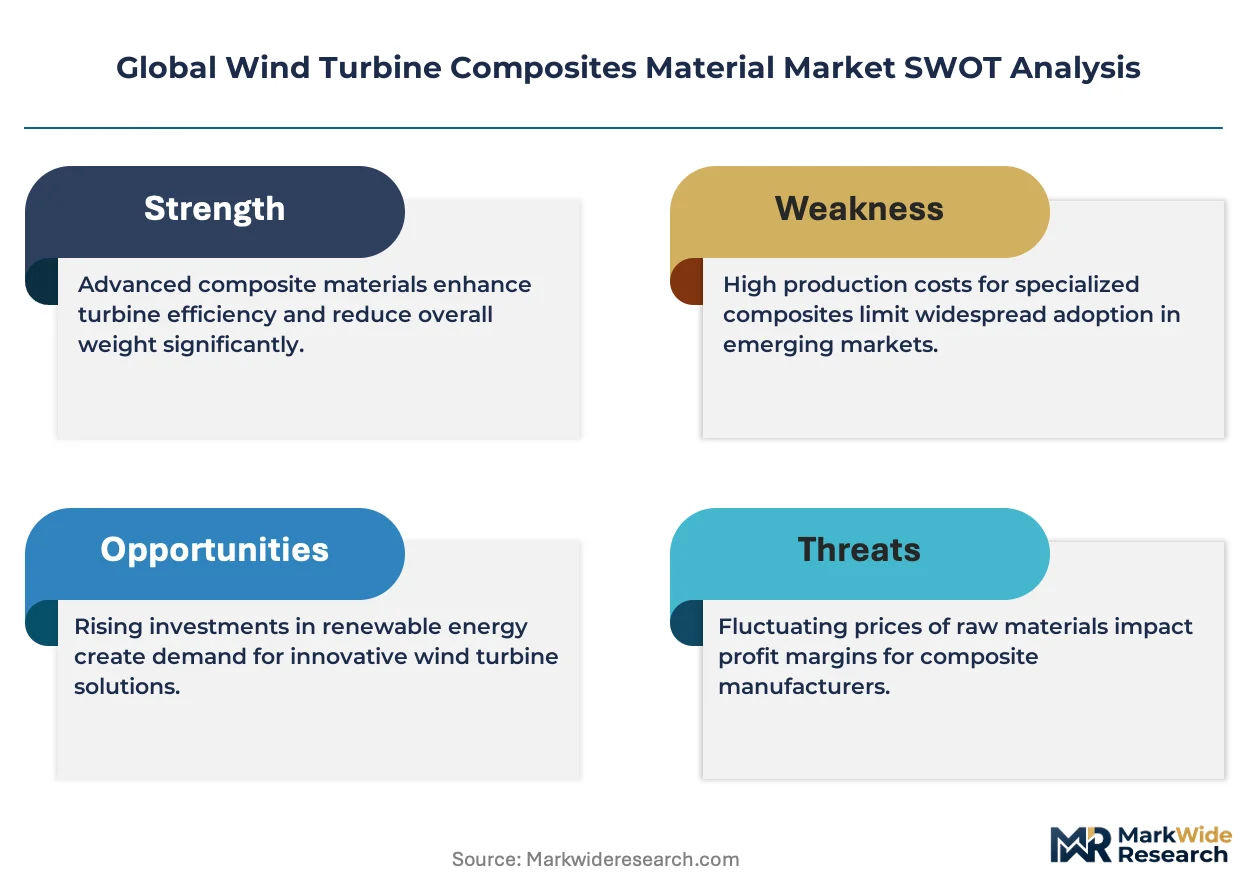
- Offshore Wind Expansion:Demand from large-scale offshore installations, particularly in the North Sea and coastal China, requires longer, more durable blades, driving consumption of high-modulus carbon fiber and advanced epoxy resins.
- Technological Advancements:The development of thermoplastic resins and automated fiber placement processes enhances blade manufacturing efficiency and improves material recyclability, aligning with performance and sustainability goals.
- Supportive Government Policies:China's dual carbon goals and the EU's Green Deal initiatives provide long-term policy support and incentives for wind energy capacity expansion, securing a stable demand pipeline for composite materials.
Market Restraints
- High Cost of Carbon Fiber:The significantly higher price of carbon fiber compared to glass fiber limits its widespread application to only the most demanding, large-scale turbine blades, constraining broader market penetration.
- Recycling Complexity:The prevalence of thermoset epoxy resins creates significant technical and economic challenges for end-of-life blade recycling, posing a major environmental and regulatory hurdle for the industry.
- Supply Chain Volatility:The supply of critical raw materials, including specific resins and fiber precursors, is subject to price fluctuations and geopolitical risks, impacting production costs and material availability for manufacturers.
Strategic Opportunities
- Bio-Based Composites:The commercialization of bio-derived epoxy resins and natural fibers like flax offers a pathway for suppliers to meet manufacturer demand for sustainable materials with a lower carbon footprint.
- Floating Offshore Wind Structures:Developing specialized, corrosion-resistant composites for floating turbine substructures and mooring systems represents a significant growth area as offshore projects move into deeper waters.
- Emerging Market Adaptation:Customizing composite formulations for specific climate conditions, such as high humidity in Southeast Asia or extreme cold in Nordic regions, opens new avenues for market entry and product differentiation.
Industry Challenges
- Divergent End-of-Life Regulations:Suppliers face complexity in navigating inconsistent national and regional regulations for blade disposal and recycling, increasing compliance costs and hindering the development of a global circular economy model.
- Lack of Material Standardization:The absence of universally accepted standards for testing and certifying new sustainable composite materials slows their adoption and creates uncertainty for turbine manufacturers.
- Skilled Labor Scarcity:A shortage of technicians proficient in advanced composite manufacturing techniques, such as automated fiber placement and infusion molding, can impede production scaling and quality control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wind Turbine Composites Material Market |
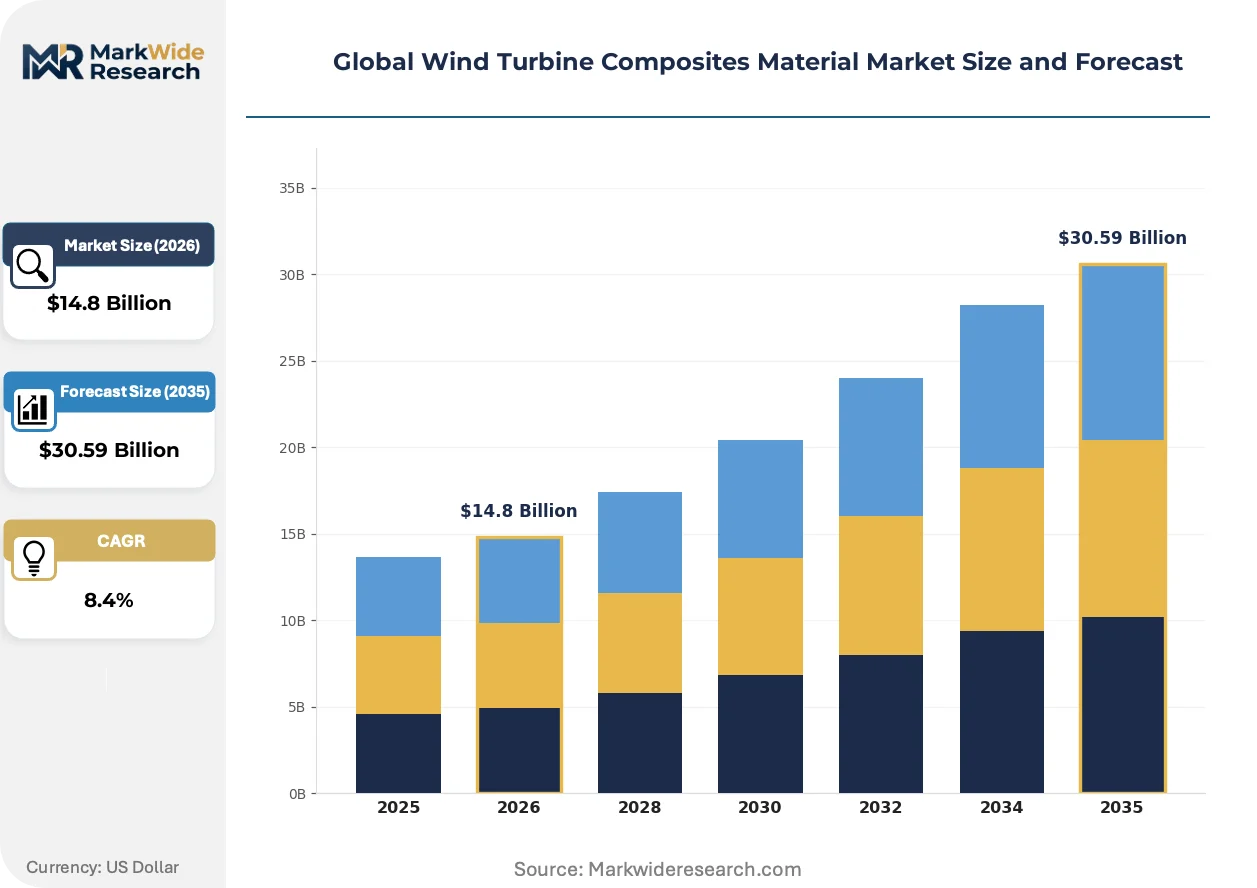
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Glass Fiber, Carbon Fiber, Aramid Fiber, Basalt Fiber, Hybrid Composites Blade Length: Below 40 Meters, 40-60 Meters, 60-80 Meters, Above 80 Meters Application Sector: Onshore Projects, Offshore Installations, Remote Location Facilities, Urban Development Plants End User Type: Turbine Manufacturers, Component Suppliers, Energy Developers, Engineering Consultancies |
| Companies Covered | Toray Industries, Hexcel Corporation, Teijin Limited, SGL Carbon, Gurit Holding, Owens Corning, Mitsubishi Chemical, Solvay, TPI Composites, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wind Turbine Composites Material Market Strategic Shifts & Innovations
The market is being reshaped by dual pressures to engineer materials for ever-larger turbine blades while simultaneously designing for full circularity. This forces a fundamental re-evaluation of material science, moving beyond performance-at-any-cost to a more holistic life-cycle approach.
Automated fiber placement (AFP) is a robotic manufacturing process that precisely lays down individual composite tows to build up a component. Major turbine manufacturers are adopting AFP for the production of spar caps and blade shells in turbines with rotor diameters exceeding 150 meters. This technology is displacing traditional, labor-intensive manual layup methods, which are less precise for the massive, structurally critical blades required for next-generation offshore wind farms.
China's MEE directives and dual carbon goals are creating a strong regulatory push for larger, more efficient wind turbines. These policies directly influence material selection, incentivizing the use of high-modulus carbon fiber to achieve the necessary stiffness and weight reduction for blades longer than 100 meters. As a result, composite suppliers targeting the Chinese market must now offer advanced carbon fiber prepregs and pultruded profiles to remain competitive.
Turbine original equipment manufacturers are shifting their material specification criteria to prioritize life-cycle performance and end-of-life recyclability over initial material cost alone. This change disrupts the traditional component-based procurement model, favoring suppliers who can provide integrated material systems with documented sustainability credentials. The trend is most pronounced in Europe, where EU circular economy directives are forcing blade designers to consider disposal and recycling from the outset.
Global Wind Turbine Composites Material Market Segmentation
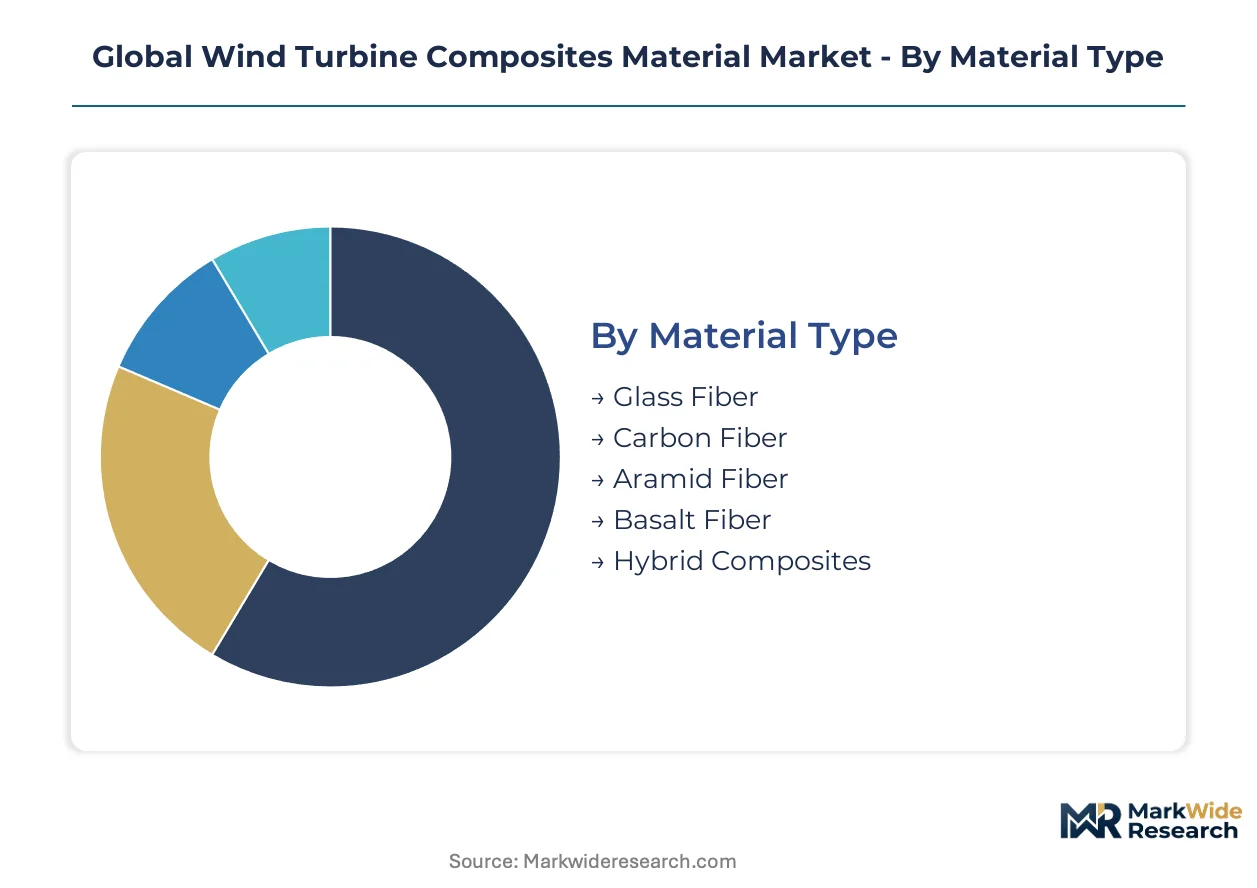
Understanding the segmentation within the global wind turbine composites material market reveals how material science adapts to diverse operational demands and regulatory pressures. Different blade lengths, installation environments, and end-user requirements dictate specific material formulations. This granular analysis highlights where innovation is most critical for performance and sustainability.
Material Type:
Substitution pressure profoundly influences material type selection, as cost-performance trade-offs drive shifts from traditional glass fiber to advanced carbon solutions.
- Glass Fiber:Comprises woven or non-woven strands embedded in a resin matrix, offering good strength-to-weight ratio and electrical insulation. Demand remains dominant for mainstream onshore turbines and blades up to 80 meters, driven by its cost-effectiveness and established manufacturing processes.
- Carbon Fiber:Features high stiffness, tensile strength, and fatigue resistance, typically used in prepreg or pultruded forms. Demand is essential for next-generation offshore blades exceeding 80 meters, particularly in regions like coastal China and the North Sea, where longer, lighter structures are critical.
- Aramid Fiber:Offers high impact resistance and vibration damping, finding niche applications in specific blade sections requiring enhanced toughness.
- Basalt Fiber:Possesses good thermal stability and chemical resistance, presenting an eco-friendly alternative with potential in certain composite structures.
- Hybrid Composites:Combine different fiber types, such as glass and carbon, to optimize properties and cost-performance balance for specific blade designs.
Glass Fiber anchors the volume base while Carbon Fiber gains share at the steepest rate.
Blade Length:
Blade length directly correlates with application scope and power output, dictating material requirements for stiffness and weight.
- Above 80 Meters:Requires high-modulus carbon fiber and advanced resin systems to manage extreme loads and minimize tip deflection. Demand concentrates in large-scale offshore wind farms in Europe and China, where longer blades maximize energy capture and reduce the levelized cost of energy.
- 60-80 Meters:Often employs a hybrid glass and carbon fiber construction, balancing cost with structural integrity for substantial power generation. This segment forms a significant portion of new onshore and nearshore installations globally, representing a sweet spot for many utility-scale projects.
- Below 40 Meters:Primarily utilizes glass fiber composites, serving smaller distributed wind energy systems and specialized applications.
- 40-60 Meters:Represents a mid-range segment, predominantly using glass fiber with some carbon reinforcement in critical areas for structural optimization.
The largest blade segments demand specialized materials, pushing innovation in composite engineering.
Application Sector:
Application sector delineates distinct operational environments, each imposing unique material performance and durability requirements.
- Offshore Installations:Demands composites with superior corrosion resistance, fatigue life, and structural integrity due to harsh marine environments and larger blade designs. Demand is driven by massive government investments in the North Sea and coastal China, requiring robust, long-lasting materials for deep-water turbines.
- Onshore Projects:Utilizes a broad range of composites, with glass fiber dominating due to its cost-effectiveness for blades up to 80 meters. This segment constitutes the largest volume, with growth in established markets like the US and emerging economies, focusing on optimized material-to-cost ratios.
- Remote Location Facilities:Requires durable, low-maintenance composites capable of withstanding extreme temperatures and logistical challenges in isolated areas.
- Urban Development Plants:Focuses on smaller, aesthetically integrated turbine designs, often prioritizing noise reduction and specific material certifications for urban environments.
Offshore installations drive material innovation, while onshore projects underpin foundational market volume.
End User Type:
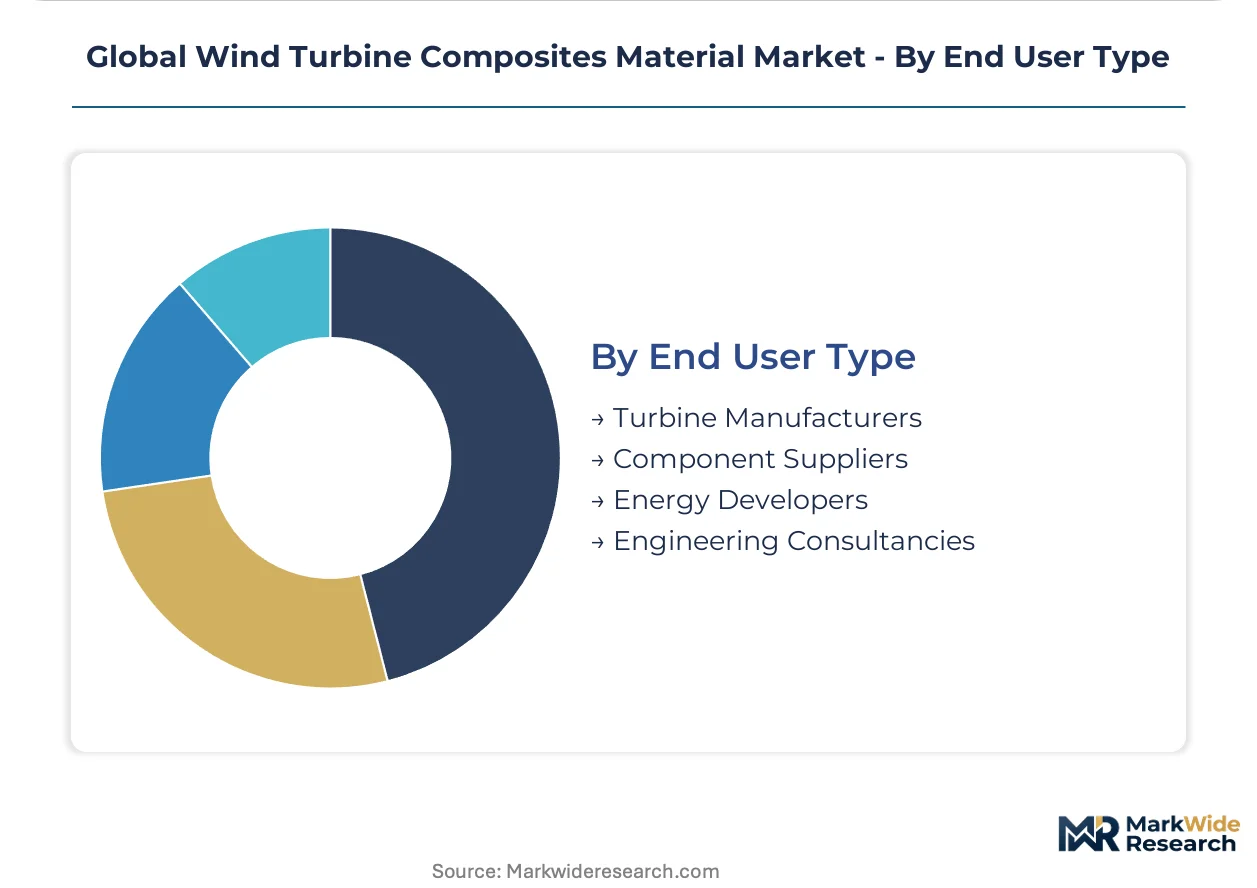
End user type influences procurement patterns and material specification, reflecting distinct roles within the wind energy value chain.
- Turbine Manufacturers:Serve as the primary specifiers and large-volume purchasers of composite materials, dictating precise performance and sustainability criteria for blade production. Demand concentrates among global giants like Vestas and Siemens Gamesa, who drive material innovation through their design and engineering departments.
- Component Suppliers:Focus on providing specialized composite parts, such as spar caps, leading edges, or root sections, often requiring specific material properties and manufacturing expertise. Demand is influenced by the subcontracting strategies of turbine manufacturers, requiring flexible and responsive material supply chains.
- Energy Developers:Primarily procure fully assembled turbines, influencing material choices indirectly through long-term performance and lifecycle cost requirements.
- Engineering Consultancies:Provide design and material selection advice to project developers and manufacturers, impacting specifications for advanced composite solutions.
Turbine manufacturers directly shape material demand, while component suppliers adapt to their evolving specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The demand elasticity for wind turbine composites varies significantly across regions, with buyers in some markets exhibiting less price sensitivity for advanced materials. Regions focused on large-scale offshore installations prioritize high-performance, durable composites for extreme conditions. Conversely, areas developing mainstream onshore projects often prioritize cost-effectiveness, favoring traditional glass fiber solutions.
China
China's ambitious wind energy targets drive demand for composites in massive coastal and inland wind farms, particularly for blades exceeding 100 meters. MEE directives and dual carbon goals incentivize the adoption of larger, more efficient turbines, pushing material selection towards high-modulus carbon fiber. The Yangtze River Delta region focuses on manufacturing advanced carbon fiber prepregs and pultruded profiles for these next-generation blades.
Germany
Germany's strong push for offshore wind expansion in the North Sea requires durable, high-modulus composites capable of withstanding harsh marine environments. The EU Green Deal and REACH regulations drive demand for recyclable and sustainable composite solutions, influencing material innovation. Northern Germany, particularly around Rostock and Bremerhaven, hosts key blade manufacturing and advanced material research centers.
United States
The United States sees significant growth in onshore wind, with increasing interest in larger blade designs and nascent offshore projects. The Investment Tax Credit (ITC) and Inflation Reduction Act (IRA) support wind energy development, fostering demand for advanced composites. Texas and Iowa, major wind energy states, see material suppliers establishing local production and service hubs to meet regional needs.
United Kingdom
The United Kingdom's ambitious offshore wind targets, particularly for deep-water floating turbines, necessitate specialized corrosion-resistant composites. The UK's Net Zero strategy and Contracts for Difference (CfD) scheme bolster offshore wind investment, requiring robust material solutions. The Humber region and Scotland are becoming hubs for offshore wind component manufacturing and composite material research.
Global Wind Turbine Composites Material Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the wind turbine composites market. This tiered structure reflects the diverse material requirements across blade lengths and applications. Strategic archetypes include large-scale carbon fiber producers, specialized resin formulators, and core material providers. Major players engage in strategic partnerships to integrate material systems and expand manufacturing capacity.
Within the high-performance material archetype, Toray Industries, a Japanese multinational corporation, exemplifies a leader leveraging extensive carbon fiber production scale. Hexcel Corporation, a US-based advanced composites company, occupies a position providing specialized prepregs and honeycomb materials for demanding applications. Gurit Holding AG, a Swiss company, anchors the market for core materials and structural engineering services, focusing on complex blade optimization projects.
| Leading Market Players |
|---|
| Toray Industries |
| Hexcel Corporation |
| Teijin Limited |
| SGL Carbon |
| Gurit Holding |
| Owens Corning |
| Mitsubishi Chemical |
| Solvay |
| TPI Composites |
| Others |
Cost & Logistics Intelligence
The extended lead times for specialized carbon fiber components significantly influence pricing power, especially for large offshore blade manufacturers, shaping the overall supply chain dynamics.
Pricing Analysis
After-sales service contracts for blade maintenance and repair drive lifetime value within the wind turbine composites market. Project-based pricing dominates for large-scale offshore installations, while per-unit transactional models prevail for mainstream onshore projects. Price differentiation stems from material performance specifications for blade length and specialized certifications. Pricing softness runs through the glass fiber segment due to high competition, making mainstream onshore projects highly price-sensitive. Turbine manufacturers procuring high-modulus carbon fiber for offshore blades exhibit lower price sensitivity.
Supply Chain Analysis
Port congestion in major shipping lanes, particularly those connecting Asian production hubs to European markets, elevates inbound logistics costs for composite materials. Supply concentration for carbon fiber rests in Japan and China, while glass fiber production spans China, the United States, and Europe. The industry relies on specialized epoxy resins and high-purity fiber precursors, creating a structural supply chain vulnerability to geopolitical risks impacting precursor availability. Downstream distribution primarily involves direct shipments from material producers to large turbine manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a strong substitution defense, as incumbents must navigate the increasing viability of alternative energy storage solutions that could reduce overall wind energy demand.
For Market Incumbents: Shield core market share by deepening vertical integration into advanced resin formulation and securing long-term carbon fiber supply contracts. Invest significantly in R&D for bio-based composites to counter regulatory pressure from EU circular economy directives. This counters the threat of material commoditization and strengthens control over critical material inputs.
For New Entrants and Emerging Players: Certification fast-tracks for novel recyclable thermoplastic composites offer a clear entry point into the European market. Target specialized niches like floating offshore wind substructures, which demand unique corrosion-resistant materials. Focus on providing integrated material systems with documented sustainability credentials to appeal to turbine manufacturers prioritizing life-cycle performance. This strategy allows penetration into high-value, underserviced segments.
For Investors and Strategic Acquirers: Long-term, this sits as a critical infrastructure enabler play because wind energy expansion is a global priority over the next 5-10 years. Acquire specialized resin formulators or advanced fiber pultruders with proprietary intellectual property in sustainable composites. Watch for significant capital expenditure announcements from major turbine manufacturers for new blade production facilities as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Bio-Based Resin R&D | Develops sustainable material alternatives to meet EU Green Deal directives for blade circularity. |
| Expand Carbon Fiber Production Capacity | Addresses growing demand for high-modulus carbon fiber in large offshore turbine blades. |
| Form Partnerships for Automated Fiber Placement | Accelerates adoption of efficient manufacturing processes for next-generation blade designs. |
| Develop Specialized Composites for Floating Offshore | Captures new market opportunities in deep-water wind energy projects requiring unique materials. |
| Secure Long-Term Supply Contracts for Precursors | Mitigates supply chain volatility and ensures material availability for critical production. |
Research Approach
Desk research of industry association reports, government energy agency publications, and corporate financial filings preceded structured interviews with turbine design engineers, material procurement leads, and composite manufacturers. This combined primary and secondary data approach ensured robust validation. Bottom-up data from material suppliers, cross-referenced with top-down market sizing from turbine OEMs, informed the overall market picture.
Variance decomposition across the analysis window isolated the impact of key market drivers and restraints on growth projections. The forecast modeled segmentation dimensions including material type, blade length, application sector, end-user type, and regional regulatory impacts. Compound annual growth rates stemmed from historical data and projected technology adoption. Key inputs included projected offshore wind capacity additions and carbon fiber price trajectory.
Decision-makers should treat outputs as directional under current government policy and raw material supply assumptions; material deviation warrants model refresh. Forecasts reflect these assumptions, with changes in government policy or raw material supply disruptions posing significant risk. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Composite Cans Market
Composite Materials
Composite Adhesives Market
Composite Materials
High-Temperature Composite Materials Market
Composite Materials
Global Carbon Fiber Reinforced Polymer Market
Composite Materials
GCC Decorative Laminates Market
Composite Materials
FRP Tanks Market
Composite Materials
Pressure Vessel Composite Materials Market
Composite Materials
Graphite Carbon Raiser Market
Composite Materials
Low Temperature Sealing Glass Composite Powder Market
Composite Materials
Wood Plastic Composite (WPC) Market
Composite Materials
Europe Marine Composites Market
Composite Materials
Synthetic Rope Market
Composite Materials
Tow Prepreg Market
Composite Materials
Marine Composites Market
Composite Materials
Global Carbon Graphite Bushings Market
Composite Materials
Reinforced Plastics Market