
 India Cooling Water Treatment Chemicals Market | 2026-2036
India Cooling Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
India Cooling Water Treatment Chemicals Market Foresight
Modular dosing systems bundled with real-time monitoring is shifting procurement patterns among large industrial buyers. Ecolab leverages its digital water-management platform to anchor premium service contracts across Indian steel complexes. Thermax Limited competes through captive manufacturing of chelating polymers at its Pune facility. Chembond Chemicals Limited specializes in acid corrosion inhibitors tailored for high-hardness groundwater regions.
India cooling water treatment chemicals comprise formulated blends of corrosion inhibitors, biocides, scale inhibitors, and pH adjusters designed to maintain thermal efficiency in recirculating water systems operating at 25-50°C with hardness levels exceeding 300 ppm as CaCO3. These chemicals prevent mineral deposition, microbial fouling, and electrochemical degradation on heat-exchange surfaces in continuous-process industries. Biocides command disproportionate margin pools due to rising bromine-based formulations replacing chlorination in coastal power plants. Scale inhibitors represent the fastest-growing product class as zero-liquid-disclosure mandates force higher cycle-of-concentration operation. Liquid formulations dominate volume offtake though powder concentrates gain traction in remote mining locations lacking bulk storage infrastructure.
BIS specification IS 10496 for cooling water quality and CEA technical standards for thermal power plant water consumption shape product registration requirements and formulation chemistry across Indian states. The country's national pharmaceutical regulator and FSSAI indirectly influence food-processing end users who must demonstrate potable-grade treatment chemical compliance. Solenis and Suez navigate this framework through local blending facilities that adapt imported active ingredients to regional hardness profiles. Stakeholders must monitor how state-level pollution control board enforcement of revised effluent norms alters biocide selection criteria and service contract structures.
Market Dynamics
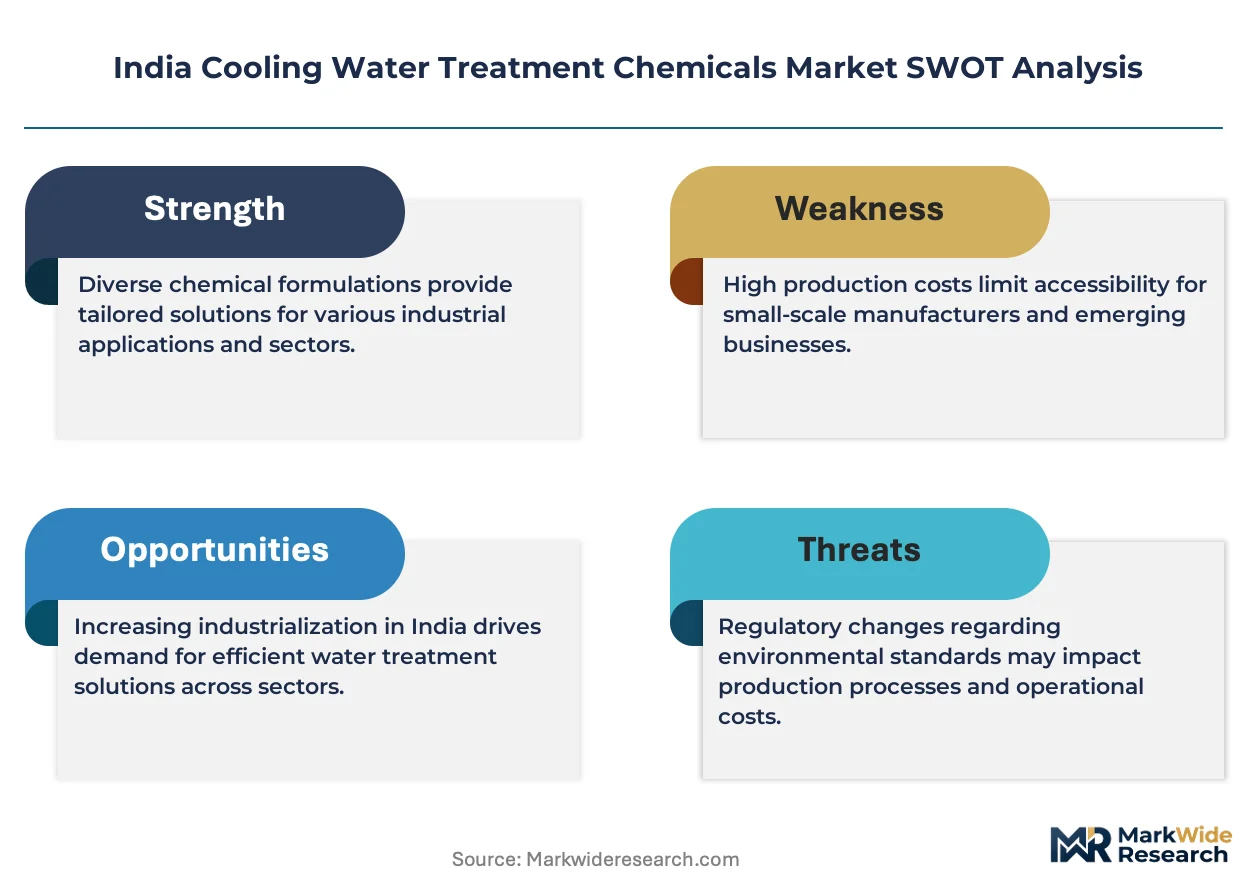
Zero-liquid-discharge mandates from state pollution control boards are compressing water-use cycles in coastal industrial clusters, forcing chemical suppliers to reformulate scale inhibitors for 8-10 concentration ratios previously unseen in Indian cooling systems.
Growth Catalysts
- CEA Water-Use Efficiency Norms:Mandatory consumption benchmarks for thermal power plants are expanding chemical treatment programs across Gujarat and Maharashtra facilities.
- Petrochemical Corridor Expansion:Refinery capacity additions in western India require continuous corrosion management for heat-exchange networks.
- Bromine-Based Biocide Transition:Coastal power stations are replacing chlorination regimes with alternative biocide formulations to meet stricter discharge limits.
Market Restraints
- Active Ingredient Import Dependency:Specialty biocide precursors and phosphonate intermediates concentrate in Chinese and European supply chains, exposing blenders to currency volatility and shipping disruptions.
- BIS Registration Timelines:IS 10496 compliance certification for new formulations stretches 18-24 months, freezing product pipelines for mid-size chemical suppliers.
- On-Site Electrochlorination:Capital-rich power utilities are installing in-house sodium hypochlorite generation, displacing bulk biocide offtake in the largest addressable segment.
Strategic Opportunities
- Remote Mining Locations:Powder concentrate formulations bypass bulk liquid storage limitations in Odisha and Jharkhand mineral processing sites lacking infrastructure.
- Digital-Physical Bundling:Real-time conductivity and ORP sensors paired with automated dosing pumps create recurring revenue streams beyond commodity chemical sales.
- PLI Scheme Alignment:Domestic manufacturing incentives for specialty chemicals support backward integration into chelating polymer production.
Industry Challenges
- Water Chemistry Expertise Gap:Field service engineers capable of interpreting Langelier saturation indices and stabilizing phosphate-polymer blends remain scarce outside Mumbai-Pune industrial belts.
- Legacy DCS Integration:Steel and cement plants operating 1990s-era distributed control systems face protocol mismatches when connecting modern IoT-enabled dosing skids.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Cooling Water Treatment Chemicals Market |
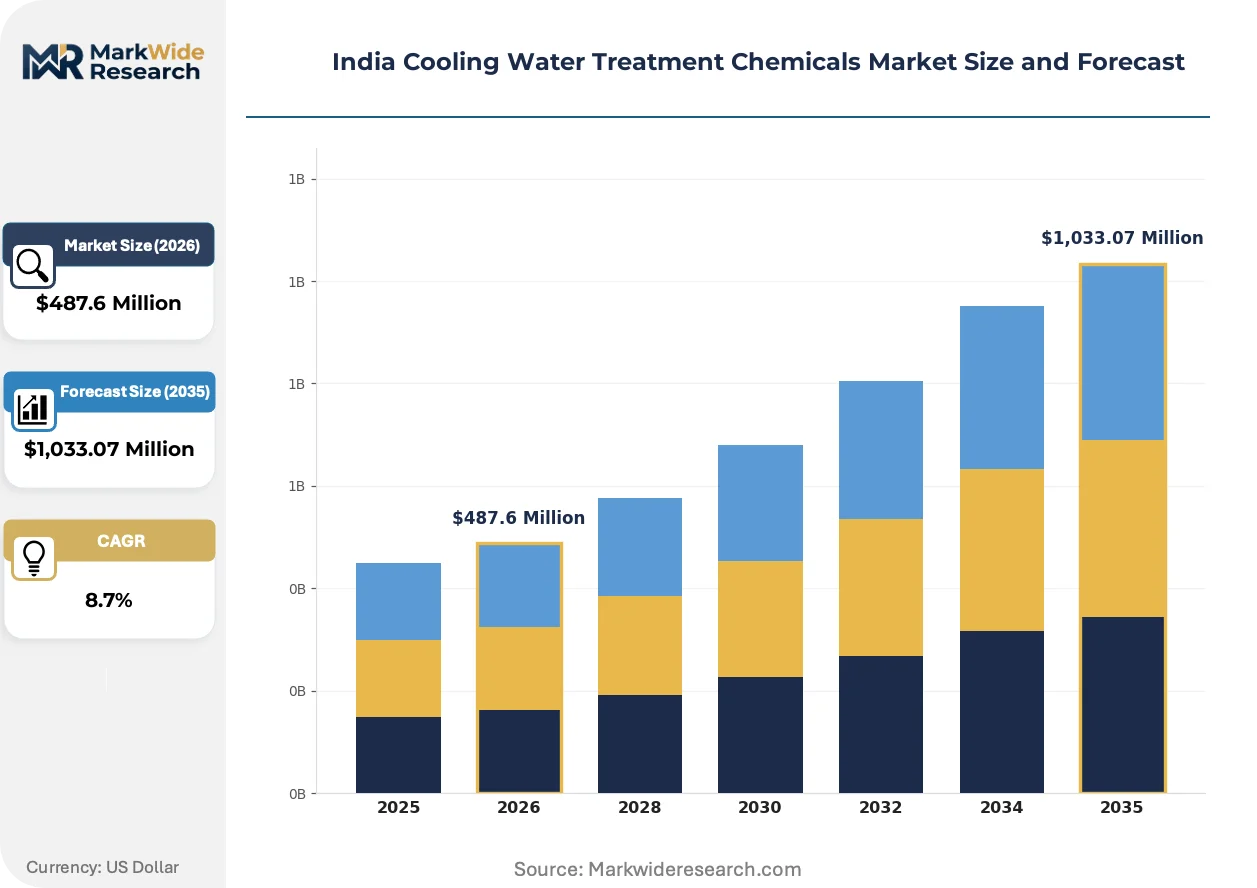
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corrosion Inhibitors, Biocides, Scale Inhibitors, pH Adjusters Application: Industrial Cooling Systems, HVAC Systems, Power Plants, Oil & Gas End User: Manufacturing, Energy, Food Processing, Chemical Form: Liquid, Powder, Solid, Tablet |
| Companies Covered | Ecolab, Kemira, Chembond Chemicals Limited, Chemtex Specialty Limited, Toray Industries, Thermax Limited, Solenis, Suez, Ion Exchange, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Cooling Water Treatment Chemicals Market Shifts & Advancements
Formulation chemistry and delivery mechanisms are diverging sharply between coastal high-salinity installations and inland high-hardness sites, fragmenting what was historically a standardized product category.
AI-driven predictive dosing algorithms are automating chemical feed-rate adjustments based on real-time heat-exchanger fouling indicators. NTPC and Tata Power pilot installations demonstrate 12-15% reduction in total chemical consumption. This compression of manual intervention is automating service contract structures toward remote-monitoring subscriptions.
BIS specification IS 10496 revisions are tightening conductivity and microbial count thresholds for cooling tower blowdown. Formulators must recalibrate polymer molecular weights and biocide release kinetics. Western Indian power clusters face the steepest compliance curves as state pollution control boards accelerate enforcement.
Steel complexes and refineries are unbundling chemical supply from technical service, awarding separate contracts to specialty blenders and third-party water-management consultants. This bifurcation fragments supplier relationships previously anchored by integrated service agreements. The pattern concentrates in Maharashtra and Gujarat where buyer sophistication exceeds national averages.
India Cooling Water Treatment Chemicals Market Segmentation
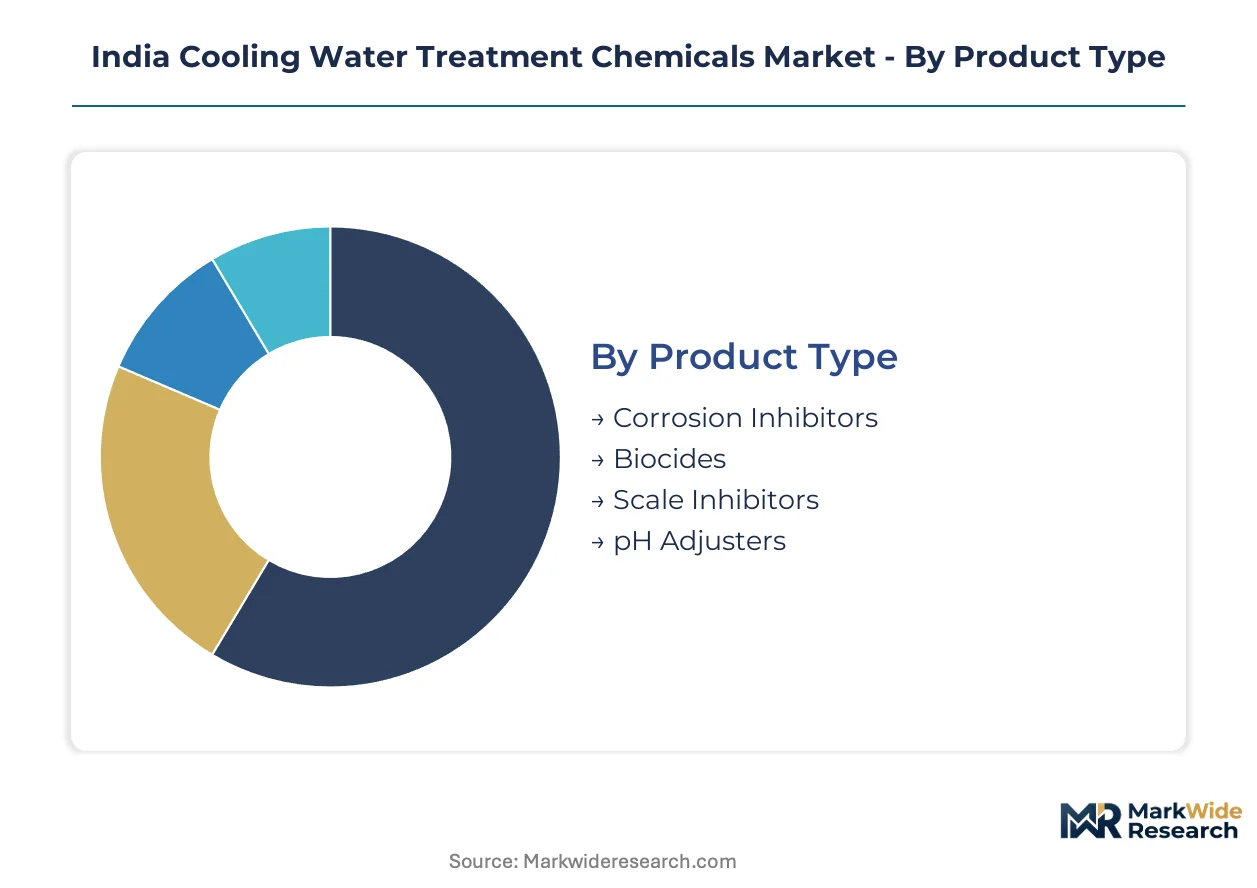
Cooling water treatment chemistry fragments across four distinct axes in India, each commanding different margin structures and technical service intensity. Product formulation determines raw material exposure, while application context dictates regulatory compliance burdens and cycle-of-concentration requirements.
Product Type:
Specialty chemical manufacturing concentrates disproportionately among phosphonate blenders and bromine compounders serving coastal power clusters.
- Biocides:Bromine-based formulations and isothiazolinone blends control microbial fouling in recirculating systems operating above 35°C. Coastal Gujarat power stations drive disproportionate offtake as chlorination faces discharge limit pressure under state pollution control board enforcement.
- Scale Inhibitors:Phosphonate polymers and polymaleic acid derivatives prevent calcium carbonate and calcium sulfate precipitation at concentration ratios exceeding 6:1. Zero-liquid-discharge mandates across Maharashtra refineries force reformulation for 8-10 cycle operation previously unseen in Indian practice.
- Corrosion Inhibitors:Azole-based film formers and orthophosphate blends protect carbon steel heat-exchange surfaces in high-hardness groundwater regions.
- pH Adjusters:Sulfuric acid and caustic soda solutions maintain alkalinity within 6.5-8.5 pH bands for polymer stability.
Today's leader: Biocides. Tomorrow's challenger: Scale inhibitors.
Application:
End-use concentration tilts toward continuous-process industries with 24-hour thermal load profiles and stringent efficiency mandates.
- Power Plants:Coal and combined-cycle facilities across Gujarat and Maharashtra deploy comprehensive treatment programs covering condenser circuits, auxiliary cooling, and ash handling systems. CEA water-use efficiency norms mandate specific consumption benchmarks that expand chemical treatment scope.
- Industrial Cooling Systems:Steel complexes and cement plants operate large recirculating networks with 10,000+ m³/hour circulation rates requiring automated dosing infrastructure.
- Oil & Gas:Refinery heat-exchange networks and downstream petrochemical crackers demand corrosion management compatible with hydrocarbon process streams.
- HVAC Systems:Commercial building cooling towers represent fragmented demand with lower technical service attachment rates.
Power plants anchor current volume; industrial cooling systems present the steepest expansion trajectory as steel capacity additions proceed.
End User:
Procurement sophistication varies sharply between central utility buyers and distributed manufacturing accounts.
- Energy:NTPC, Tata Power, and Adani Thermal anchor bulk offtake through framework agreements spanning 3-5 year horizons with integrated technical service.
- Manufacturing:Automotive and textile plants in Pune-Nashik belt represent mid-scale demand with growing digital monitoring adoption.
- Chemical:Fertilizer and specialty chemical producers in Gujarat require treatment chemistry compatible with ammonia and acid process environments.
- Food Processing:Dairy and beverage facilities face FSSAI indirect compliance requirements for potable-grade chemical certification.
Energy sector procurement dominates contract value; manufacturing accounts fragment across regional supplier relationships.
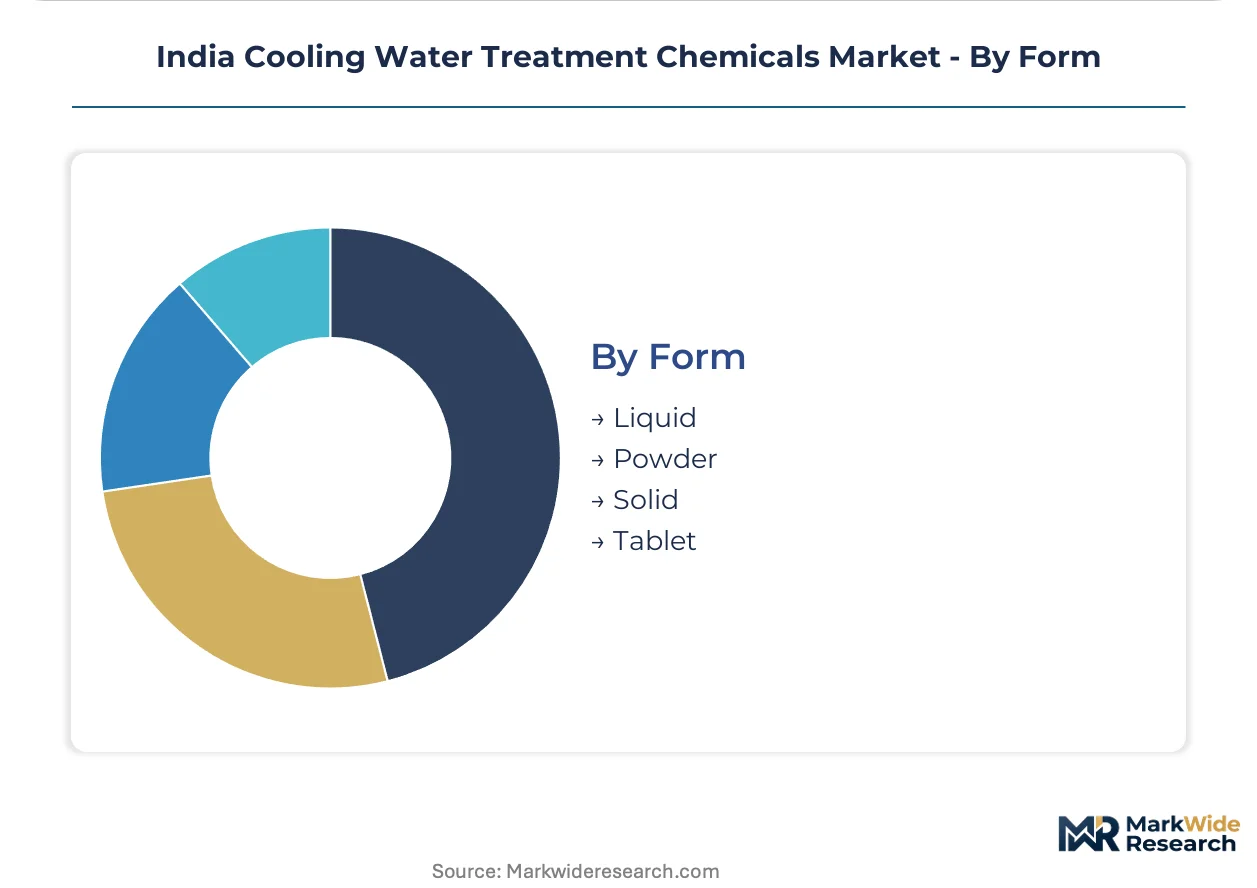
Form:
Physical delivery format determines logistics economics and storage infrastructure requirements across India's uneven industrial geography.
- Liquid:Bulk drum and tanker deliveries dominate volume offtake for coastal refineries and large power stations with dedicated chemical storage farms.
- Powder:Concentrated solid formulations bypass bulk liquid limitations at remote Odisha and Jharkhand mining locations lacking tankage infrastructure.
- Tablet:Slow-dissolving briquettes serve small HVAC and commercial applications with intermittent supervision.
- Solid:Block and briquette formats address specific cooling tower sump applications requiring extended release kinetics.
Liquid formulations command present volume; powder concentrates gain fastest as mining corridor demand matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial water treatment chemistry in India traces its commercial origins to the 1970s steel and fertilizer buildouts in West Bengal and Bihar, where early public-sector thermal plants imported phosphonate formulations to manage scaling in high-hardness river water.
Maharashtra
Mumbai-Pune industrial belt hosts India's densest concentration of automotive and specialty chemical manufacturing. CEA water-use efficiency norms drive treatment program upgrades at thermal facilities in Chandrapur and Nagpur. Refinery complexes in Raigad district deploy continuous corrosion management for heat-exchange networks processing high-sulfur crude.
Gujarat
Coastal power stations at Mundra and Hazira face steepest discharge limit pressure under state pollution control board enforcement. BIS specification IS 10496 compliance timelines stretch formulation registration for new biocide entrants. Dahej and Vadodara petrochemical corridors require treatment chemistry compatible with ammonia and acid process environments.
Karnataka
Bengaluru's precision manufacturing ecosystem generates mid-scale demand from semiconductor and aerospace component plants. State-level pollution control mandates accelerate digital monitoring adoption among IT park cooling tower operators. Mysuru and Mangaluru cement clusters operate large recirculating networks requiring automated dosing infrastructure.
Tamil Nadu
Ennore and Tuticorin thermal ports anchor bulk chemical offtake through NTPC and state utility framework agreements. Neyveli lignite complexes drive specialized scale inhibitor demand for high-alkalinity feedwater. Sriperumbudur automotive belt represents fragmented manufacturing accounts with growing service contract sophistication.
Telangana
Hyderabad's pharmaceutical and bulk drug manufacturing corridor faces FSSAI indirect compliance requirements for potable-grade chemical certification. Ramagundam power station expansion extends treatment program scope across auxiliary cooling and ash handling circuits. Warangal fertilizer plants require treatment chemistry stabilizing phosphate-polymer blends in high-hardness groundwater.
India Cooling Water Treatment Chemicals Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service integration intensity, with digital-physical bundling separating recurring-revenue specialists from drum-sale commodity blenders. The vendor base concentrates among three strategic archetypes: integrated water-management platforms, captive polymer manufacturers, and regional formulation specialists. Consolidation pressure intensifies as steel complexes and refineries unbundle chemical supply from technical service, fragmenting supplier relationships previously anchored by integrated agreements. Two dominant competitive moves reshape positioning: M&A targeting digital monitoring capabilities, and backward integration into chelating polymer production under PLI scheme incentives.
Within the integrated platform tier, Ecolab leverages its digital water-management platform to anchor premium service contracts across Indian steel complexes. Thermax Limited competes through captive manufacturing capabilities at its Pune facility, exemplifying the backward-integrated archetype. Chembond Chemicals Limited occupies a specialist position, with formulation expertise concentrated in acid corrosion inhibitors for high-hardness groundwater regions. These three players represent distinct strategic vectors—service-led, manufacturing-led, and application-led—each responding differently to procurement pattern shifts among large industrial buyers.
| Leading Market Players |
|---|
| Ecolab |
| Kemira |
| Chembond Chemicals Limited |
| Chemtex Specialty Limited |
| Toray Industries |
| Thermax Limited |
| Solenis |
| Suez |
| Ion Exchange |
| Others |
Supply & Pricing Matrix
Zero-liquid-discharge mandates from Maharashtra and Gujarat pollution control boards are forcing reformulation of scale inhibitors for 8-10 concentration ratios, compelling suppliers to absorb higher phosphonate polymer costs while buyers demand fixed-price multi-year contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates digital-physical bundled service contracts from commodity drum sales and unbranded local blends. Price differentiation rests on BIS IS 10496 certification status and real-time monitoring integration. Cost compression in the economy tier is intensifying because on-site electrochlorination systems displace bulk biocide offtake. Power utilities with framework agreements show least price sensitivity; remote mining accounts in Odisha and Jharkhand demonstrate highest.
Supply Chain Analysis
Direct-to-refinery channels handle bulk liquid deliveries for coastal installations, while distributor networks reach inland manufacturing clusters. Active ingredient supply concentrates in China for phosphonate intermediates and Europe for specialty biocide precursors. Raw material sourcing draws from bromine compounds, chelating polymers, and azole-based film formers. Single-source vulnerability concentrates in Chinese phosphonate supply chains exposed to currency volatility and shipping disruptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India cooling water treatment chemicals market functions as a stable compounder, with CEA water-use efficiency norms and state-level discharge mandates ensuring continuous program upgrades across thermal power and refining infrastructure.
For Market Incumbents: Anticipate procurement unbundling trends where steel complexes separate chemical supply from technical service contracts. Defensive positioning requires deepening captive manufacturing of chelating polymers at Pune-cluster facilities and securing BIS registration pipelines for reformulated biocide blends ahead of IS 10496 revisions. Threat concentration sits with digital-native entrants offering AI-driven predictive dosing without legacy DCS integration burdens.
For New Entrants and Emerging Players: The mid-tier price gap between Ecolab's premium service bundles and unbranded local commodity blends offers white-space entry. Target powder concentrate formulations for remote mining corridors in Odisha and Jharkhand lacking bulk liquid infrastructure. Penetrable segments include third-party water-management consulting services unbundled from chemical supply. Go-to-market leverage rests on PLI scheme alignment for domestic specialty chemical manufacturing.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional formulation specialists possessing BIS-registered product pipelines and established pollution control board relationships. Long-term viability frames around 5-10 year water stress intensification across western Indian industrial corridors. Acquisition target archetype: mid-size blenders with backward-integrated polymer production and digital monitoring capabilities. Signal to monitor: state pollution control board acceleration of effluent norm enforcement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chelating Polymers | Captive supply of phosphonate intermediates reduces exposure to Chinese import volatility for Maharashtra-based blenders. |
| Digital-Physical Bundling | Real-time ORP sensor integration with automated dosing pumps creates recurring revenue streams beyond commodity chemical sales. |
| PLI Scheme Alignment | Domestic manufacturing incentives support in-house production of specialty biocide formulations for coastal power clusters. |
| Regional Blending Facility Expansion | Local adaptation of imported active ingredients to Gujarat's high-salinity hardness profiles accelerates BIS compliance timelines. |
| Remote Mining Corridor Penetration | Powder concentrate formats bypass bulk liquid storage limitations at Odisha and Jharkhand mineral processing sites. |
Research Methodology
Direct dialogue with plant managers at thermal power facilities, procurement leads at downstream refineries, distribution channel partners, and technical R&D directors anchored qualitative foundations. Secondary validation drew from customs and trade data, CEA technical standards documentation, SEC filings of listed chemical suppliers, and state pollution control board enforcement records. Bottom-up volume modeling across product types, applications, and regional clusters triangulated against top-down macroeconomic indicators for the Indian industrial sector.
Segment-level projections across biocides, scale inhibitors, corrosion inhibitors, and pH adjusters were generated through the analysis window. Modeled dimensions included formulation chemistry, end-use industry concentration, physical delivery format, and state-level regulatory stringency. CAGRs were derived from regression analysis of historical offtake patterns against CEA water consumption benchmarks and refinery capacity expansion schedules. Forecast inputs incorporated BIS specification revision timelines and state pollution control board enforcement intensity differentials.
Caveats apply where BIS registration delays, active ingredient supply disruptions, or accelerated electrochlorination adoption could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and industrial water stress trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Mexico Water Treatment Chemicals Market
Water & Sludge Treatment
Hazardous Waste Treatment System Market
Water & Sludge Treatment
Slurry Heaters Market
Water & Sludge Treatment
Germany Water Treatment Chemicals Market
Water & Sludge Treatment
Ultrapure Water Market
Water & Sludge Treatment
Water Softening Systems Market
Water & Sludge Treatment
Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
South America Water Treatment Chemicals Market
Water & Sludge Treatment
Aquarium Water Treatment Market
Water & Sludge Treatment
Global Water Treatment Technology Market
Water & Sludge Treatment
Saudi Arabia Industrial Hazardous Waste Management Market
Water & Sludge Treatment
Water Gel Market
Water & Sludge Treatment
Industrial Water Treatment Chemicals Market
Water & Sludge Treatment
Water Treatment Polymers Market
Water & Sludge Treatment
Global Valves in Water and Wastewater Market
Water & Sludge Treatment
Wastewater Treatment Chemicals Market