
 Rubber Foam Materials Market | 2026-2036
Rubber Foam Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Foam Materials Market Analysis
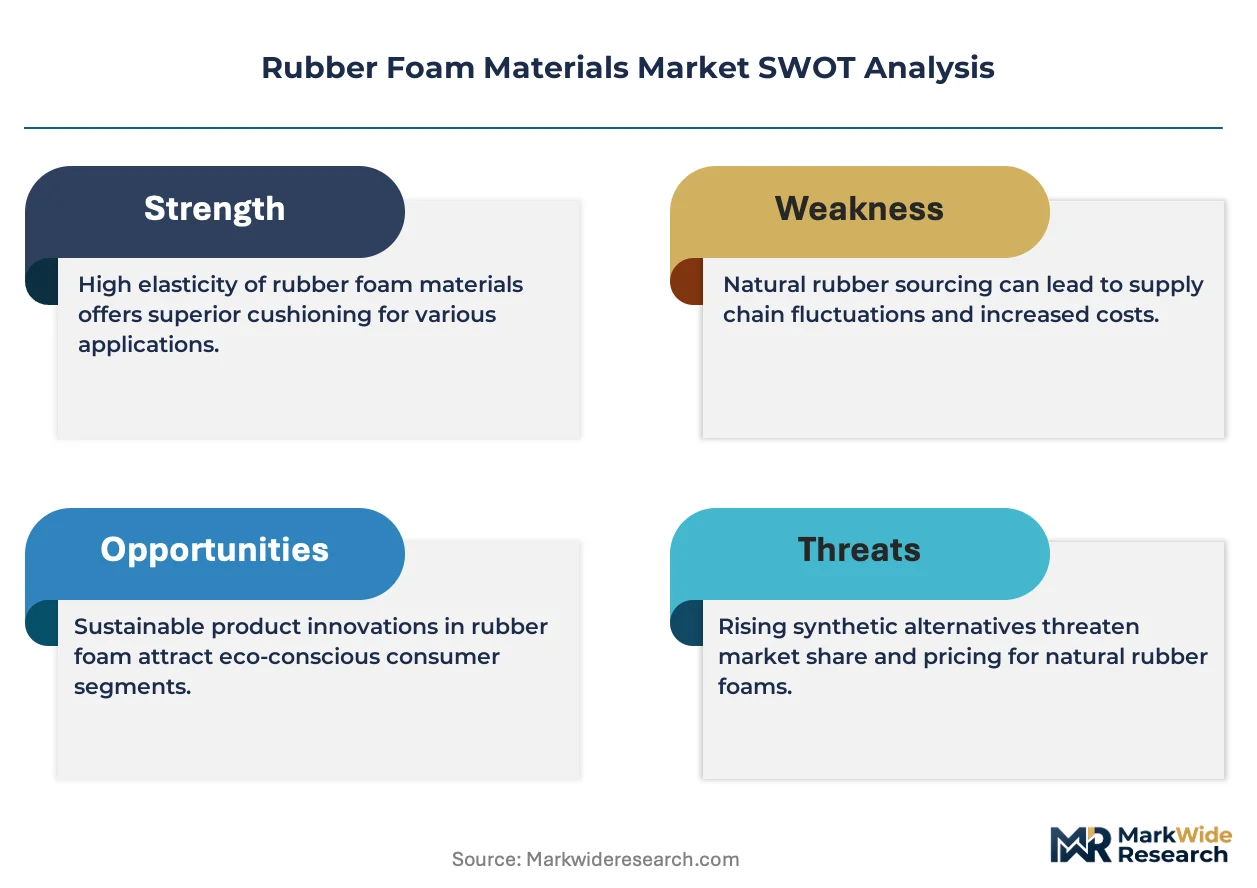
Closed-cell microstructure innovation is tilting rubber foam production toward thermal management grades for electric vehicle battery enclosures. Armacell leverages its European manufacturing base to supply halogen-free insulation systems for automotive OEMs. Saint-Gobain anchors its position through integrated melamine foam operations serving aerospace fire-blocking applications. Dow Chemical Company competes on polymer science breadth, extending ethylene-propylene formulations into high-temperature gasket segments.
Rubber foam materials are elastomeric cellular solids manufactured through chemical or physical blowing of synthetic rubber compounds, typically achieving densities from 30 to 300 kg per cubic meter depending on cell architecture and cure chemistry. Their primary industrial purpose spans thermal insulation, mechanical cushioning, and acoustic attenuation in environments requiring combined flexibility and environmental resistance. Closed cell foam commands the largest volume share due to its moisture-barrier performance in HVAC and refrigeration systems, while microcellular foam represents the fastest-expanding category as miniaturized sealing solutions penetrate medical device and consumer electronics assembly. High density grades concentrate margin pools in aerospace and defense applications where fire-smoke-toxicity certification creates supply scarcity.
EPA regulations in the United States restrict hydrofluorocarbon blowing agents, pushing manufacturers toward water-based or hydrocarbon expansion technologies. REACH in Europe and GB standards in China impose parallel constraints on residual monomer content and flame retardant chemistries, reshaping raw material sourcing across multinational supply chains. ECHA substance evaluation protocols now target specific isocyanate precursors common in polyurethane foam variants, elevating compliance costs for non-integrated compounders. Stakeholders must monitor evolving chemical hazard classifications across EPA, ECHA, and China's MEE to anticipate reformulation cycles and qualification timelines.
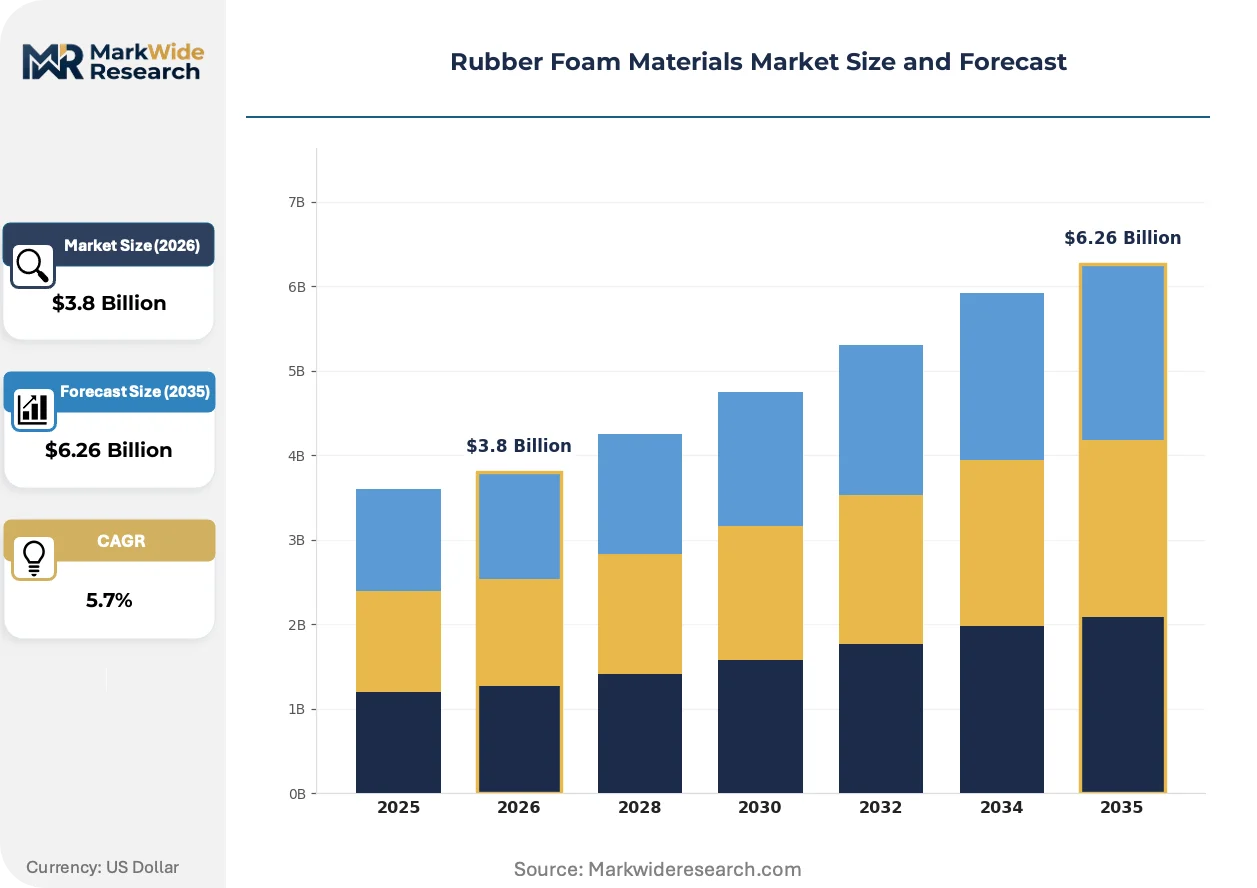
Market Dynamics
Closed-cell microstructure innovation is compressing thermal management grades toward electric vehicle battery enclosures, while REACH chemical safety rules and EPA hydrofluorocarbon restrictions simultaneously reshape formulation chemistry and blowing agent selection across multinational supply chains.
Growth Catalysts
- Electric vehicle battery insulation demand:Automotive OEMs in China and Germany are expanding lightweight cushioning programs for battery pack thermal isolation. This application segment concentrates procurement volume in high-density closed-cell grades.
- REACH volatile organic compound limits:ECHA substance evaluation protocols now target specific isocyanate precursors, accelerating qualification of halogen-free alternative chemistries among European compounders.
- Physical blowing agent substitution:Water-based and hydrocarbon expansion technologies are displacing restricted hydrofluorocarbon systems, creating equipment upgrade cycles at US and European production facilities.
Market Restraints
- Petrochemical feedstock volatility:Synthetic rubber compound costs fluctuate with ethylene-propylene and styrene-butadiene monomer pricing, compressing margin predictability for non-integrated foam producers.
- Specialty additive supply concentration:Flame retardant and curing agent production clusters in Northeast Asia, exposing Western compounders to logistics disruption and qualification timeline extension.
- Fire-smoke-toxicity certification scarcity:Aerospace and rail applications require limited-source testing protocols, creating bottlenecked supply for high-density grades serving these segments.
Strategic Opportunities
- Medical device miniaturization:Microcellular foam penetration into catheter sealing and diagnostic housing assembly represents underexploited volume potential in precision manufacturing.
- China dual carbon policy alignment:MEE enforcement of stricter GB standards on residual monomer content creates first-mover advantage for compounders with pre-qualified low-emission formulations.
- Consumer electronics thermal interface:Convergence of 5G base station deployment and handheld device waterproofing is opening gasket specification opportunities in assembly automation channels.
Industry Challenges
- Polymer science talent scarcity:Formulation chemistry expertise for blow ratio control and cell architecture optimization is concentrating at integrated material science programs in Germany and the United States.
- Multi-jurisdiction qualification burden:Simultaneous EPA, ECHA, and GB standard compliance requires parallel testing streams, extending product launch timelines by 18-24 months for new chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Foam Materials Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed Cell Foam, Open Cell Foam, Hybrid Foam, Microcellular Foam End User: Automotive Industry, Aerospace, Construction, Consumer Goods Application: Insulation, Cushioning, Vibration Damping, Soundproofing Grade: Low Density, Medium Density, High Density, Extra High Density |
| Companies Covered | Armacell, Saint-Gobain, BASF Corporation, Recticel, Covestro, Dow Chemical Company, Huntsman Corporation, INOAC Corporation, Rogers Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Foam Materials Market Emerging Trajectories
Process control systems and formulation analytics are digitizing production workflows, while regulatory pressure on blowing agents and residual content accelerates chemistry substitution cycles across automotive and construction end-uses.
Closed-cell density mapping through inline ultrasound is digitizing quality assurance protocols at extrusion lines serving HVAC and refrigeration OEMs. Tier-one suppliers in Germany and China are retrofitting legacy equipment with sensor arrays that correlate blow ratio to thermal conductivity in real time. This capability is compressing batch rejection rates and enabling just-in-time certification documentation for export shipments.
EPA restrictions on hydrofluorocarbon blowing agents under the AIM Act are forcing capital deployment into hydrocarbon and water-based expansion systems at US production facilities. The industrial consequence is elevated upfront equipment expenditure paired with reformulation cycles for existing product grades. Automotive thermal management applications in Michigan and South Carolina are responding fastest, driven by battery enclosure qualification deadlines from domestic OEMs.
Specification consolidation among tier-one automotive buyers is concentrating procurement decisions at fewer engineering teams, displacing fragmented distributor networks. Direct technical collaboration between compounders and OEM material scientists is replacing arm's-length spot purchasing. This pattern is most visible in Germany's Baden-Württemberg and Bavaria manufacturing clusters, where battery pack insulation programs require co-development agreements for thermal runaway containment validation.
Rubber Foam Materials Market Segmentation
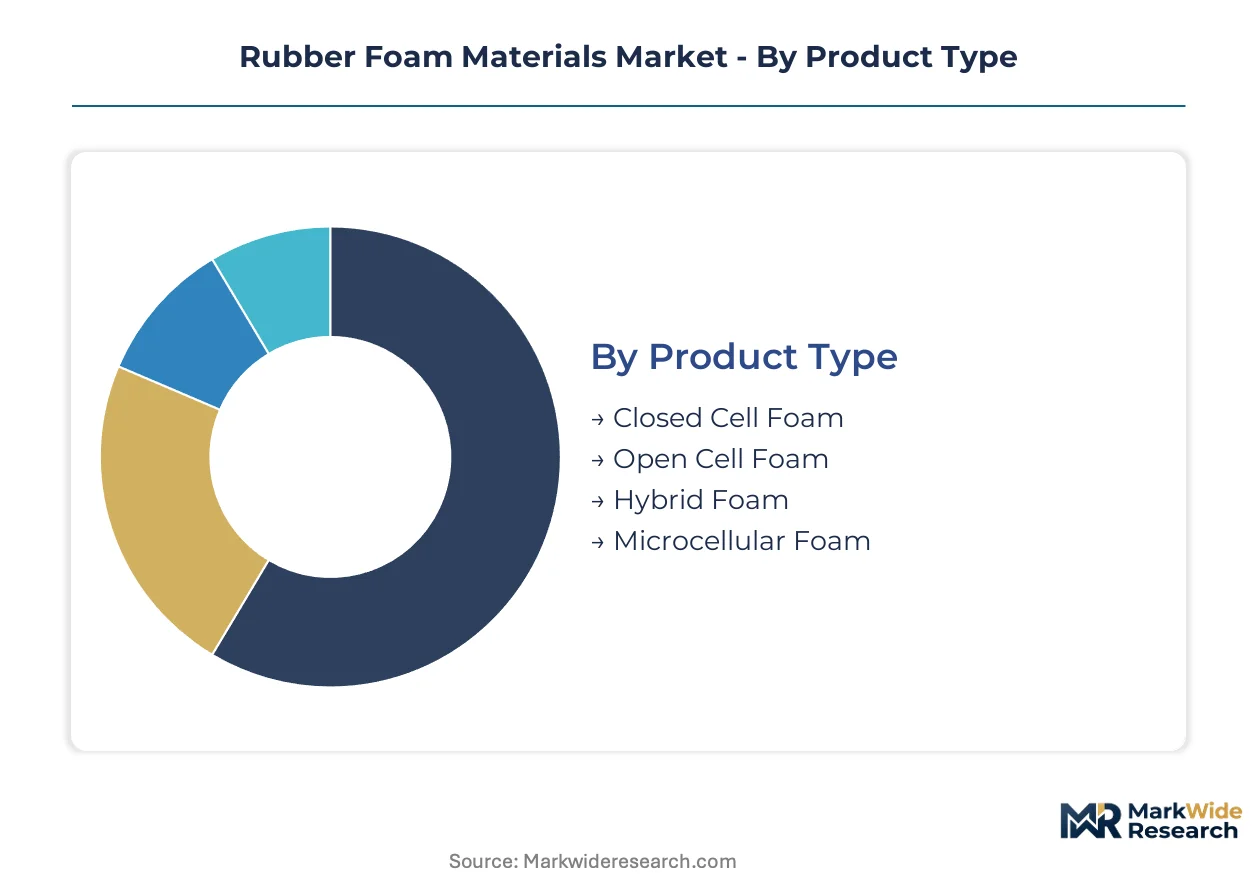
Rubber foam materials serve distinct performance requirements across thermal management, mechanical isolation, and acoustic control. Cell architecture, density grading, and end-use certification requirements create natural segmentation boundaries that determine formulation chemistry and manufacturing investment.
Product Type:
Use-case spectrum spans moisture-barrier HVAC systems through precision medical sealing, with cell structure governing permeability, compressibility, and thermal conductivity trade-offs.
- Closed Cell Foam:Impermeable bubble architecture formed by chemical or physical blowing during vulcanization creates the dominant volume category. Demand concentrates in refrigeration and electric vehicle battery pack insulation across Germany and China, where moisture resistance and thermal stability are non-negotiable. REACH volatile organic compound limits and EPA hydrofluorocarbon restrictions are accelerating reformulation toward water-based expansion systems.
- Microcellular Foam:Sub-millimeter cell structures manufactured through controlled gas saturation enable precision sealing in miniaturized assemblies. Procurement is concentrating in medical device catheter hubs and consumer electronics waterproofing gaskets, driven by assembly automation requirements for dimensional tolerance below 50 microns.
- Open Cell Foam:Interconnected pore networks prioritize acoustic absorption and breathable cushioning over moisture barriers. Applications cluster in furniture upholstery and HVAC air-handling systems.
- Hybrid Foam:Engineered gradient structures combining open and closed cell layers serve specialized acoustic-thermal dual-function requirements in rail and marine interiors.
The dominant share belongs to Closed Cell Foam, while Microcellular Foam is closing the gap fastest.
End User:
Customer procurement patterns diverge sharply between specification-driven OEMs and price-sensitive distributors, with certification burden and volume scale determining margin capture.
- Automotive Industry:Battery pack thermal isolation programs in China and Germany command premium pricing for halogen-free, fire-resistant grades. OEM material scientists now require direct co-development agreements rather than spot purchasing through distributor networks.
- Aerospace:Fire-smoke-toxicity certification under FAA and EASA protocols creates supply scarcity for high-density grades, with limited-source testing extending qualification timelines.
- Construction:Building envelope insulation and expansion joint sealing drive volume in water-based blown formulations compliant with evolving GB standards in China.
- Consumer Goods:Footwear midsoles and protective packaging represent price-competitive segments where Asian compounders dominate through scale manufacturing.
Automotive Industry captures the largest revenue pool, with Aerospace expanding most quickly on certification-scarcity pricing power.
Application:
Functional performance requirements dictate density selection, blowing agent chemistry, and additive packages across thermal, mechanical, and acoustic domains.
- Insulation:Thermal conductivity optimization through cell size control and gas retention properties dominates electric vehicle battery enclosure specifications. Michigan and South Carolina production facilities are retrofitting for hydrocarbon expansion systems under EPA AIM Act compliance deadlines.
- Vibration Damping:Loss factor engineering through polymer blend selection serves precision machinery and rail suspension systems requiring frequency-specific energy dissipation.
- Cushioning:Compression set resistance and rebound characteristics determine specification in seating and protective equipment across automotive and consumer segments.
- Soundproofing:Acoustic impedance matching through open cell or hybrid architectures targets HVAC ductwork and architectural assemblies.
Insulation holds the dominant position, while Vibration Damping is gaining share fastest on precision manufacturing expansion.
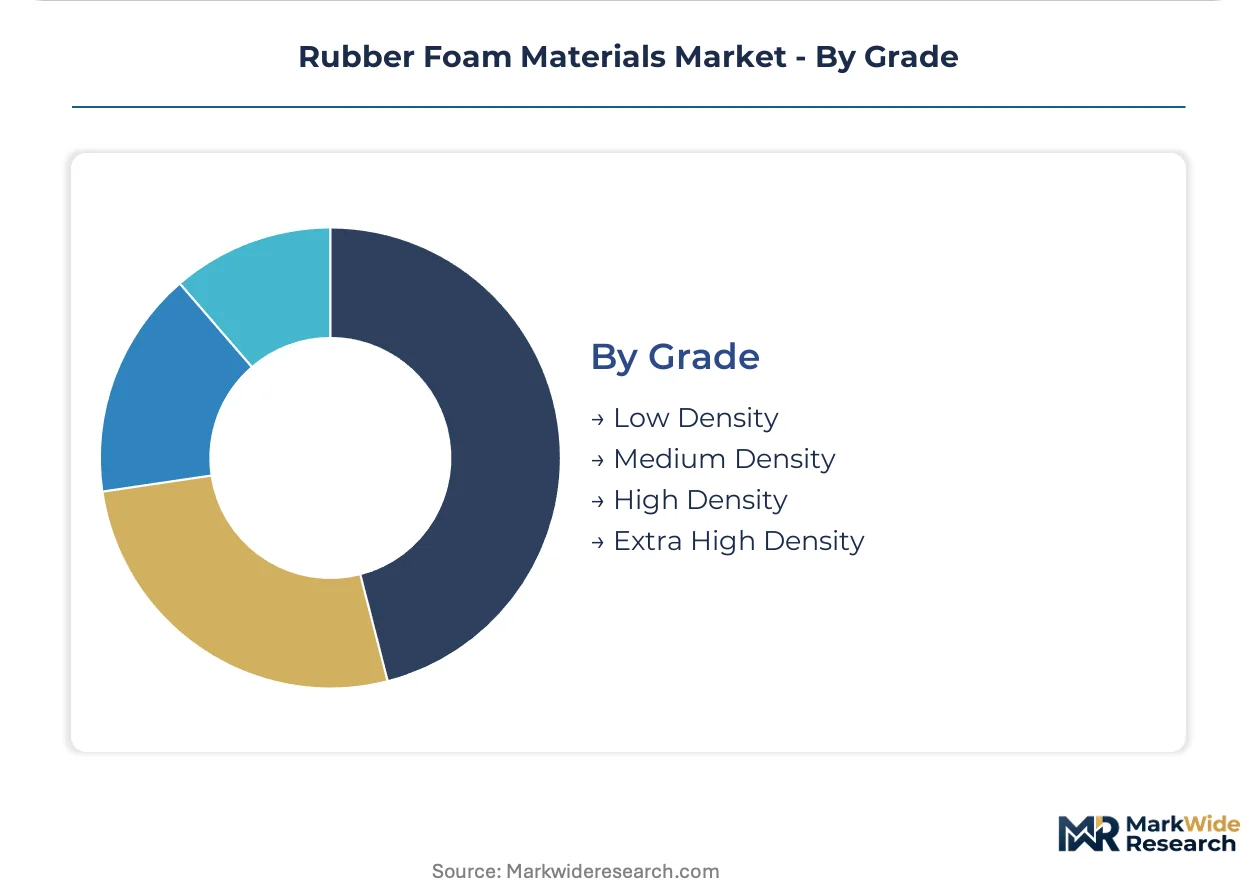
Grade:
Density tiers stratify by performance ceiling, with premium pricing concentrated at certification-intensive extremes and commodity competition dominating mid-range specifications.
- High Density:Aerospace fire-blocking and rail interior applications require 200-300 kg per cubic meter specifications with halogen-free flame retardant packages. ECHA substance evaluation protocols for isocyanate precursors are elevating compliance costs for non-integrated compounders serving this tier.
- Extra High Density:Specialized defense and subsea applications command the highest margins through limited qualified supplier pools and extended testing protocols.
- Medium Density:General industrial gasketing and HVAC applications face intense price competition from Asian manufacturers with captive petrochemical feedstock integration.
- Low Density:Packaging and disposable cushioning segments prioritize cost minimization over performance longevity, with water-based blown formulations displacing legacy chemistries.
High Density commands the premium tier, while Medium Density maintains volume leadership through construction and general industrial offtake.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German compounders export halogen-free insulation systems to automotive OEMs across China and the United States, establishing the primary trade-flow corridor for battery pack thermal management grades.
United States
EPA restrictions under the AIM Act are forcing hydrocarbon and water-based expansion system retrofits at Michigan and South Carolina production facilities. Domestic OEM battery enclosure qualification deadlines are compressing equipment upgrade timelines. Procurement concentration in the Midwest automotive corridor is displacing legacy distributor networks with direct compounder-OEM technical collaboration.
Germany
REACH volatile organic compound limits and ECHA isocyanate precursor evaluations are accelerating halogen-free chemistry qualification among Baden-Württemberg and Bavaria compounders. The country's national chemical regulator maintains substance evaluation protocols that elevate compliance costs for non-integrated producers. Battery pack insulation programs in Stuttgart and Munich manufacturing clusters now require co-development agreements rather than spot purchasing.
China
MEE enforcement of stricter GB standards on residual monomer content is reshaping formulation chemistry for electric vehicle battery applications. The dual carbon policy alignment creates first-mover advantage for compounders with pre-qualified low-emission formulations. Yangtze River Delta production facilities are retrofitting for water-based blown systems to serve domestic OEM thermal isolation programs.
Japan
METI industrial standards and JIS certification requirements govern microcellular foam specifications for medical device and consumer electronics assembly. Precision manufacturing demand in the Kanto region is concentrating procurement for catheter sealing and diagnostic housing applications. Tokyo-Osaka industrial corridors are digitizing quality assurance through inline ultrasound density mapping at extrusion lines.
South Korea
MFDS medical device regulations and national industrial policy support domestic foam compounders serving export markets. Seoul Capital Area manufacturing clusters are expanding capacity for 5G base station thermal interface gaskets. Busan-Ulsan petrochemical integration provides captive feedstock supply for medium-density construction and industrial grades.
Rubber Foam Materials Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where specification-driven OEM procurement is concentrating decisions at fewer engineering teams. The market exhibits moderate consolidation among integrated material science compounders with captive polymer research capabilities. Three archetypes dominate: European-based integrated chemical conglomerates with aerospace certification depth, Asian-scale manufacturers with petrochemical feedstock integration, and North American specialty compounders focused on automotive thermal management. Capacity expansion and strategic partnerships represent the dominant competitive moves, with direct technical collaboration replacing arm's-length distributor relationships.
Among the integrated chemical conglomerates, Armacell and Saint-Gobain exemplify the European archetype with established aerospace and automotive certification portfolios. Dow Chemical Company occupies a position within the North American specialty tier, leveraging polymer science breadth across high-temperature gasket segments. These three entities represent the channel-control end of the competitive spectrum, where direct OEM engagement and qualification depth create defensive positioning against price-competitive Asian-scale alternatives.
| Leading Market Players |
|---|
| Armacell |
| Saint-Gobain |
| BASF Corporation |
| Recticel |
| Covestro |
| Dow Chemical Company |
| Huntsman Corporation |
| INOAC Corporation |
| Rogers Corporation |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor's freight cost volatility compresses margin pools for non-integrated compounders while amplifying price differentiation between REACH-compliant European grades and standard Asian formulations. Battery pack insulation procurement from Stuttgart and Munich OEMs now commands premium positioning against commodity construction grades.
Pricing Analysis
Cost-plus contracts indexed to ethylene-propylene and styrene-butadiene monomer benchmarks dominate procurement for medium-density construction grades. Three-tier pricing structure across aerospace-certified, automotive-qualified, and general industrial tiers reflects flame-retardant package complexity and qualification depth. Pricing pressure stems from petrochemical feedstock volatility squeezing non-integrated producers. Construction distributors exhibit highest price sensitivity, while aerospace OEMs accept certification-scarcity premiums.
Supply Chain Analysis
Export-control restrictions on advanced blowing-agent technologies limit equipment flows from Germany and Japan to emerging production facilities. Raw material supply concentrates in South Korea, China, and Germany for specialty curing agents and halogen-free flame retardants. Synthetic rubber compound production rests on naphtha-cracker output from Busan-Ulsan and Yangtze River Delta petrochemical clusters. Single-source vulnerability concentrates in aerospace-certified additive packages. Distribution runs through direct compounder-OEM technical collaboration, displacing legacy distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemistry expertise for blow ratio control and cell architecture optimization is concentrating at integrated material science programs in Germany and the United States, creating defensive moats for incumbents with captive R&D infrastructure.
For Market Incumbents: Harden qualification depth against Asian-scale competitors by embedding fire-smoke-toxicity certification investment into Baden-Württemberg and Bavaria production assets. Deepen backward integration into specialty curing agent production to offset Northeast Asian supply concentration risk. Anchor direct OEM relationships through co-development agreements for battery pack thermal runaway containment validation. For New Entrants and Emerging Players: Microcellular foam applications in catheter sealing and diagnostic housing assembly represent the most penetrable entry point, given dimensional tolerance requirements below 50 microns that deter commodity producers. Consumer electronics waterproofing gaskets for 5G base station deployment offer secondary white-space access. Pursue assembly automation channel partnerships rather than spot distributor relationships. For Investors and Strategic Acquirers: Compounders with pre-qualified low-emission formulations aligned to China's MEE GB standard enforcement present the highest acquisition priority. Long-term viability hinges on regulatory qualification velocity rather than scale manufacturing. Monitor ECHA substance evaluation protocol expansion for isocyanate precursor restrictions as the inflection signal for chemistry substitution cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Additives | Captive curing agent production insulates against Northeast Asian logistics disruption. |
| Hydrocarbon Expansion System Retrofit | EPA AIM Act compliance at Michigan and South Carolina facilities locks in automotive qualification. |
| Direct OEM Technical Collaboration | Co-development agreements with Stuttgart battery pack engineers displace distributor networks. |
| Fire-Smoke-Toxicity Certification Investment | FAA and EASA protocol depth creates supply scarcity pricing power in aerospace segments. |
| Inline Ultrasound Quality Assurance Deployment | Real-time density mapping at extrusion lines compresses batch rejection rates for HVAC OEMs. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, and Cefic chemical industry reports. Interviews with plant managers at extrusion facilities, procurement leads at automotive Tier 1 suppliers, distribution channel partners, and technical R&D directors informed formulation chemistry and equipment investment patterns. Bottom-up volume modeling across cell architecture categories triangulates against top-down petrochemical feedstock consumption analysis.
Forecast inputs include electric vehicle battery pack insulation procurement timelines, REACH and EPA regulatory compliance deadlines, and hydrocarbon expansion system retrofit cycles. Segmentation modeling spans cell structure type, density grade tier, end-use industry vertical, and regional production hub qualification status. CAGRs derive from correlating historical monomer price elasticity with OEM specification consolidation trends.
Practitioners should monitor ECHA substance evaluation protocol expansion, MEE GB standard enforcement intensity, and domestic OEM battery enclosure qualification deadlines for early signals of chemistry substitution acceleration. Material shifts in blowing-agent regulatory classification or aerospace certification testing capacity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Global Medical Rubber and Balloon Products Consumption Market
Rubber
Polybutadiene Rubber (PBR) Market
Rubber
Rubber Block Market
Rubber
EPDM Market
Rubber
Polyacrylate Rubber Market
Rubber
Co-Extruded Rubber Profiles Market
Rubber
Rubber Wear Liners Market
Rubber
Fast Curing Nitrile Butadiene Rubber (NBR) Market
Rubber
Synthetic Rubber Market
Rubber
Acrylic Based Elastomers Market
Rubber
Rubber Rollers Market
Rubber
Global Rubber Process Oil Market
Rubber
Isoprene Rubber (IR) Latex Market
Rubber
Rubber Chemicals Market
Rubber
Tire Recycling Downstream Products Market
Rubber
Global Automotive Elastomers Market