
 Food Marking Inks Market | 2026-2036
Food Marking Inks Market Size, Share, and Industry Trends Forecast 2026-2036
Food Marking Inks Market Analytics
Subscription-based ink replenishment and predictive maintenance contracts is shifting how packaging converters procure marking systems. Sun Chemical leverages its vertical integration into pigment synthesis to secure supply continuity for food-grade formulations. Siegwerk Druckfarben AG & Co. KGaA anchors its position through specialized R&D centers in Europe focused on low-migration UV-curable recipes. Flint Group competes aggressively in solvent-based segments where beverage coding volume sustains margin pools.
Food marking inks are formulated colorant systems designed for application onto packaging substrates or direct food contact surfaces, with critical specifications including migration limits below 10 ppb for primary contact and curing energy thresholds of 80-200 W/cm for UV variants. Their primary purpose is to deliver legible, durable traceability codes, expiration dates, and batch identifiers across high-speed production lines. Water-based formulations dominate secondary packaging applications where porous board substrates absorb aqueous vehicles efficiently, while UV-curable inks command premium positioning in direct food contact where instant polymerization eliminates volatile organic compound release. Hot melt segments occupy niche thermal transfer roles in cold-chain dairy and frozen food logistics where wax-resin ribbons adhere to low-surface-energy films.
The FDA governs indirect food additive compliance through 21 CFR 175.105 for adhesives and coatings, while the EPA regulates volatile organic compound emissions from solvent-based ink operations under Clean Air Act Title V permitting. The European Food Safety Authority enforces migration testing protocols that shape formulation chemistry across EU member states. Stakeholders must monitor evolving dual carbon goals in China and the EU Green Deal's packaging waste directives, as these frameworks will redefine acceptable substrate-ink combinations and recyclability requirements.
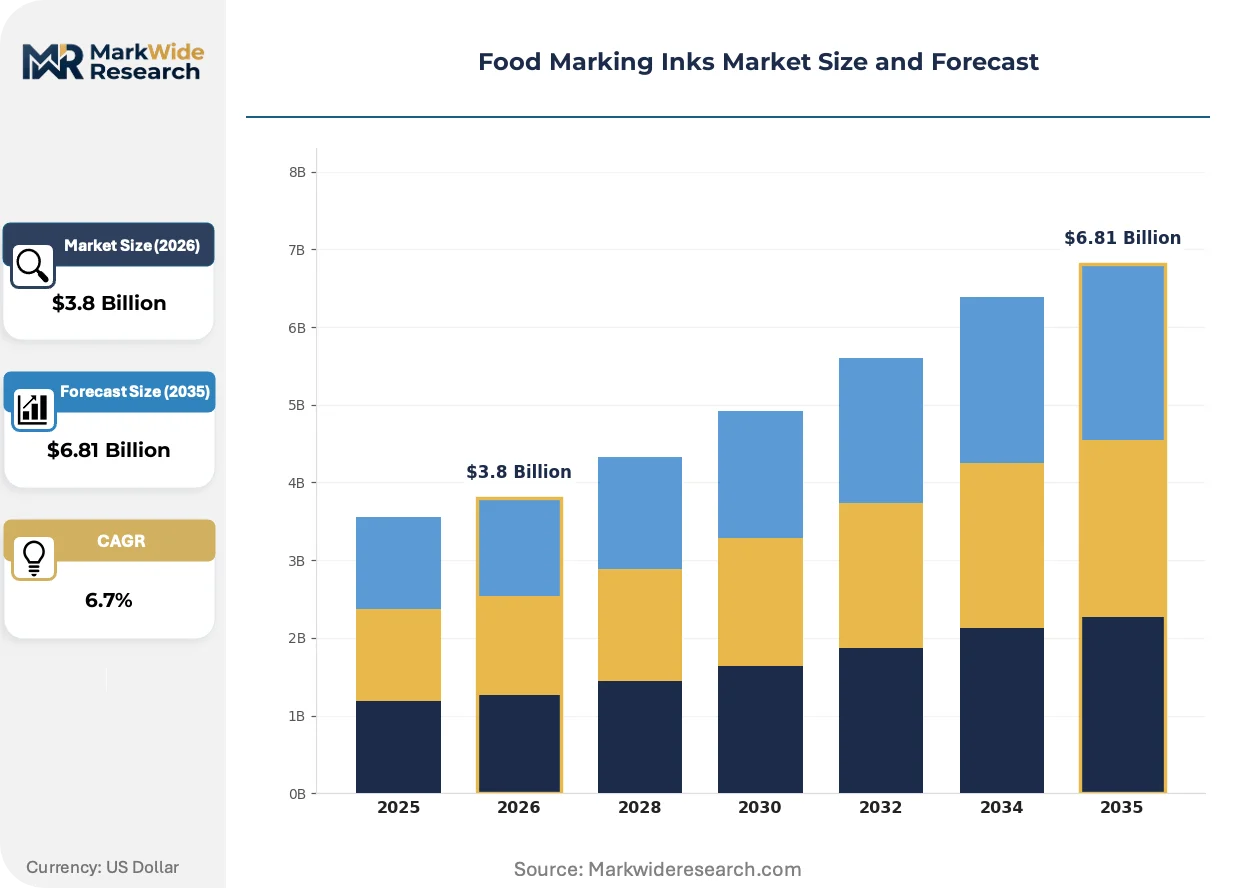
Market Dynamics
Migration limit tightening under EU REACH and FDA 21 CFR frameworks is forcing reformulation cycles that compress R&D timelines while expanding compliance costs for ink producers serving beverage and dairy packaging segments.
Growth Catalysts
- Direct food contact ink adoption:Beverage producers are migrating from label-based coding to direct substrate marking for aluminum cans and flexible pouches, eliminating secondary label materials.
- REACH Article 33 enforcement:ECHA's tightened SVHC disclosure thresholds above 0.1% w/w are accelerating replacement of legacy photoinitiators in UV-curable formulations across German and French packaging clusters.
- High-throughput coding demand:Central European dairy and meat processors are installing continuous inkjet systems requiring low-viscosity, fast-drying formulations compatible with 600+ bottles per minute line speeds.
Market Restraints
- Pigment supply concentration:Food-grade titanium dioxide and organic pigment synthesis concentrates among three German and Chinese chemical conglomerates, creating input cost volatility during energy price spikes.
- UV LED curing technical ceiling:Current 395 nm peak wavelength systems fail to polymerize certain cationic epoxy formulations, limiting substrate adhesion on low-surface-energy polypropylene films.
- Dual carbon compliance friction:China's MEE enforcement of provincial carbon intensity targets is disrupting solvent-based ink production in Shandong and Jiangsu provinces, forcing supply chain reconfiguration.
Strategic Opportunities
- India FSSAI compliance gap:Domestic Indian food processors remain underpenetrated by low-migration ink suppliers, creating first-mover advantage for formulations pre-certified to EU standards.
- Edible ink expansion:Confectionery and pharmaceutical tablet marking applications are converging with 3D food printing, requiring new regulatory pathways for direct consumption-grade colorants.
- Subscription replenishment models:Packaging converters are unbundling hardware from consumables, creating recurring revenue streams for ink suppliers who integrate IoT-enabled tank monitoring systems.
Industry Challenges
- Migration testing talent scarcity:Analytical chemists capable of executing EFSA-compliant simulant testing and specific migration limit verification command premium salaries in Basel and Frankfurt labor markets.
- Legacy CIJ system integration:Retrofitting twenty-year-old continuous inkjet printheads with new low-VOC formulations requires nozzle redesign, creating technical service bottlenecks at converter sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Marking Inks Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, UV-Curable, Hot Melt Ink Application: Direct Food Contact, Secondary Packaging, Coding, Labelling End User: Food Manufacturers, Beverage Producers, Packaging Companies, Retailers Distribution Channel: Online Sales, Direct Sales, Distributors, Retail Outlets |
| Companies Covered | Sun Chemical, Flint Group, Siegwerk Druckfarben AG & Co. KGaA, Sakata INX Corporation, Huber Group, T&K TOKA, Toyo Ink, Independent Ink, InkJet, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Marking Inks Market Evolving Landscape
Formulation chemistry is pivoting toward instant-cure systems that eliminate thermal drying stages, while digital printing integration and regulatory pre-certification are reshaping how ink suppliers engage packaging converters.
Photoinitiator-free UV LED curing is converging with cationic epoxy resin chemistry to enable direct food contact applications without migration-prone radical photoinitiators. Dairy processors in Bavaria and North Rhine-Westphalia are piloting these systems for yogurt cup coding. This convergence is compressing the regulatory approval timeline from thirty-six to eighteen months by eliminating separate photoinitiator toxicology dossiers.
EFSA's updated guidance on printing inks and varnishes published in 2023 mandates specific migration testing for all substances without established SMLs, effective across EU member states. Ink producers must now submit analytical data for each raw material above 10 ppb detection thresholds. Small and mid-sized Italian and Spanish converters are consolidating supplier relationships to three approved vendors to manage documentation burden.
Converter procurement departments are unbundling capital equipment from consumable supply, shifting toward full-cost-per-print contracts. This model displaces traditional hardware purchase plus spot ink ordering in German beverage coding segments. Equipment OEMs in Munich and Stuttgart are responding by acquiring ink formulation capabilities to capture recurring revenue streams previously lost to chemical suppliers.
Food Marking Inks Market Segmentation
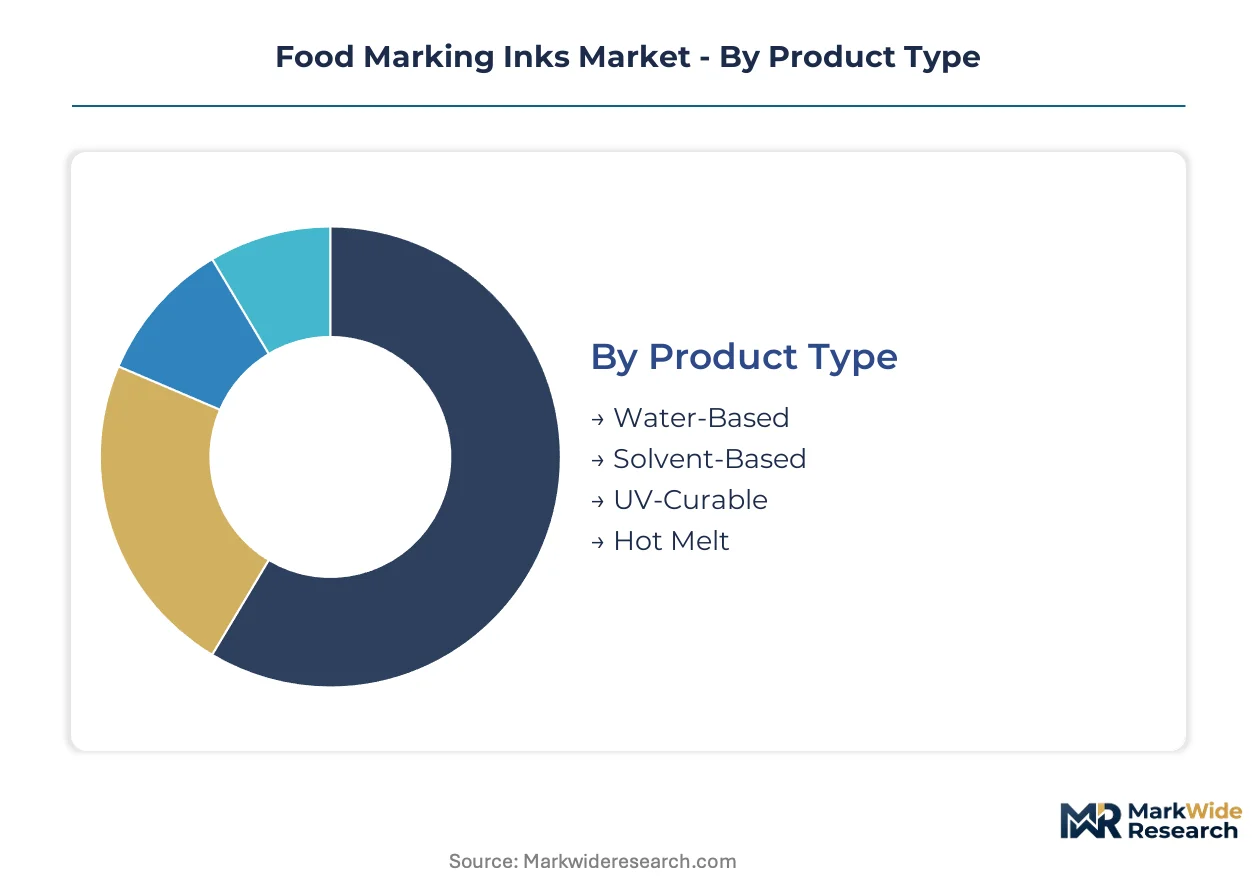
Food marking inks segment across formulation chemistry, regulatory contact class, and supply chain position. Each dimension shapes procurement patterns, compliance burden, and margin structure for ink suppliers and packaging converters.
Product Type:
Standardization dominates water and solvent formulations, while UV-curable recipes demand extensive customization for substrate-specific adhesion and migration profiles.
- Water-Based:Aqueous pigment dispersions with 20-40% solids content penetrate porous board substrates through capillary absorption. Dairy and bakery secondary packaging in Germany absorbs these formulations at high line speeds, though humidity sensitivity limits cold-chain deployment.
- Solvent-Based:Ethyl acetate and ethanol-based vehicles deliver aggressive substrate wetting on non-porous films. Beverage coding volume in aluminum can lines sustains this segment despite EPA Title V permitting costs and China's MEE carbon enforcement disrupting Shandong production.
- UV-Curable:Acrylate oligomer systems with radical or cationic photoinitiators polymerize instantly under 80-200 W/cm UV dosage. Premium positioning reflects EFSA-compliant low-migration formulations for direct food contact.
- Hot Melt:Wax-resin thermal transfer ribbons adhere to low-surface-energy polypropylene in frozen food logistics. Niche thermal transfer roles serve cold-chain dairy distribution.
Leading the category by volume: Water-Based. Expanding most quickly: UV-Curable.
Ink Application:
Regulatory contact classification determines formulation complexity, with direct food contact commanding 3-4x the R&D investment of secondary applications.
- Direct Food Contact:Formulations must demonstrate specific migration limits below 10 ppb through EFSA-compliant simulant testing. Bavarian dairy processors pilot photoinitiator-free cationic epoxy systems for yogurt cup coding, compressing approval timelines.
- Secondary Packaging:Outer case and corrugated board marking face reduced regulatory scrutiny. Water-based systems dominate this volume tier where absorption properties eliminate cure energy requirements.
- Coding:Continuous inkjet systems demand low-viscosity, fast-drying formulations compatible with 600+ bottles per minute throughput. Central European meat processors drive specification intensity.
- Labelling:Adhesive-backed substrate marking persists in premium beverage segments where aluminum can direct printing adoption remains incomplete.
Highest margin concentration: Direct Food Contact. Steepest adoption trajectory: Coding.
End User:
Procurement sophistication varies sharply, with beverage producers consolidating suppliers while retailers fragment demand across private-label specifications.
- Food Manufacturers:Meat, dairy, and bakery processors specify migration-compliant formulations for primary packaging. German packaging converters serve these accounts with pre-certified ink portfolios.
- Beverage Producers:Aluminum can and flexible pouch coding migration from label-based systems drives direct substrate marking volume. Technical service requirements intensify with line speed demands.
- Packaging Companies:Converter procurement departments unbundle hardware from consumables, shifting toward full-cost-per-print contracts with IoT-enabled tank monitoring.
- Retailers:Private-label specification power concentrates in Central European grocery chains, though technical input remains limited compared to processor-driven standards.
Specification authority concentrates with: Food Manufacturers. Procurement innovation originates from: Packaging Companies.
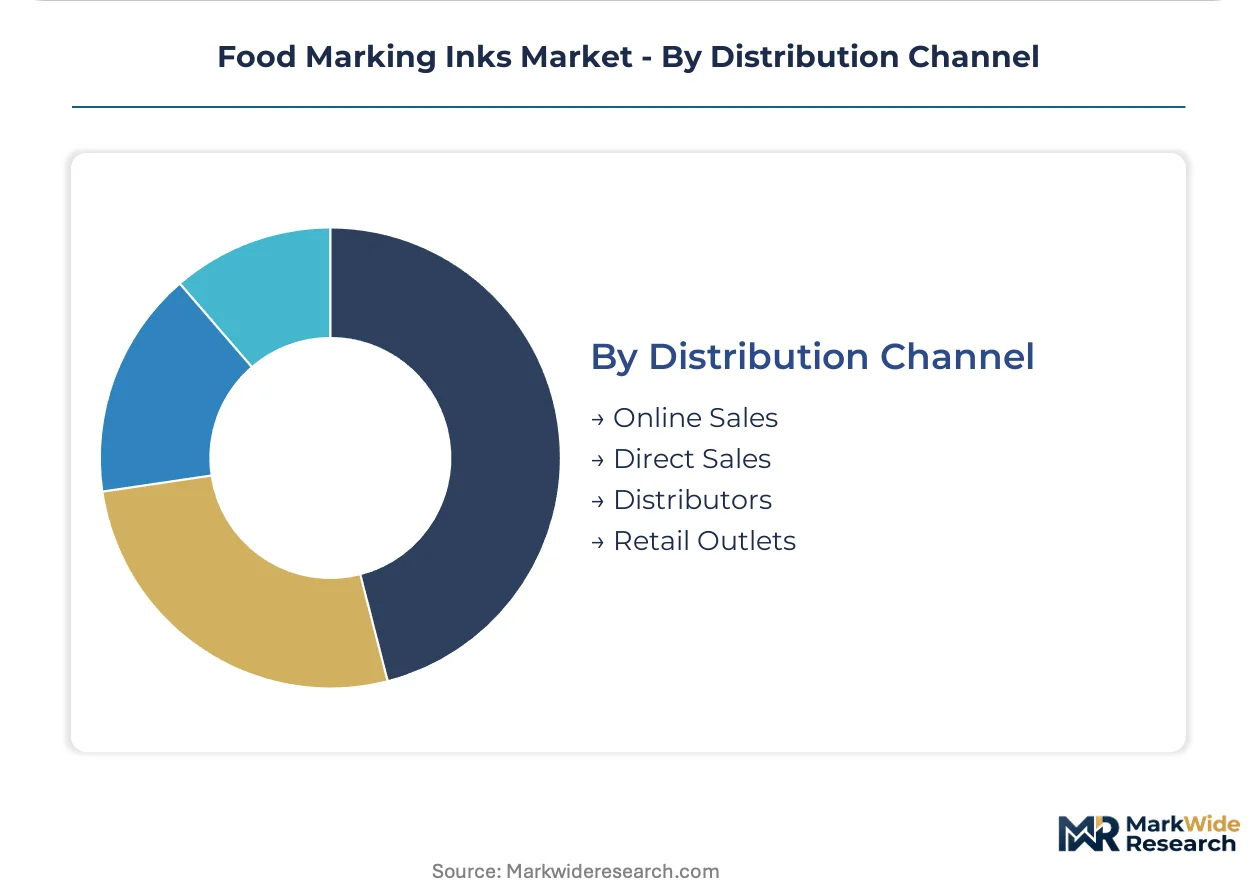
Distribution Channel:
Channel selection tracks account size and formulation complexity, with direct relationships dominating certified formulations and distributors serving spot demand.
- Direct Sales:Technical specification development, migration testing support, and custom formulation lock in strategic accounts. Sun Chemical and Siegwerk anchor major beverage and dairy relationships through captive technical service.
- Distributors:Regional chemical distributors serve mid-tier converters with standard water-based and solvent formulations, carrying inventory risk for spot replenishment.
- Online Sales:E-procurement platforms gain traction for standardized secondary packaging inks where specification burden remains minimal.
- Retail Outlets:Limited to small-scale maintenance supplies and emergency replenishment for legacy continuous inkjet systems.
Dominant channel by revenue: Direct Sales. Gaining operational share: Online Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany and China where pigment synthesis and formulation chemistry anchor supply chains, while consumption pulls toward beverage and dairy processing clusters in the United States and Central Europe.
United States
Beverage can coding volume sustains solvent-based ink demand across aluminum packaging lines. EPA Title V permitting under the Clean Air Act shapes facility siting decisions in Ohio and Texas chemical corridors. Chicago-area dairy processors pilot direct food contact UV formulations for high-throughput yogurt cup marking.
Germany
Packaging converters in Bavaria and North Rhine-Westphalia serve Central European food brands with EFSA-compliant low-migration systems. REACH Article 33 SVHC disclosure thresholds above 0.1% w/w accelerate photoinitiator replacement in UV-curable recipes. Stuttgart equipment OEMs acquire ink formulation capabilities to capture recurring service revenue.
China
Solvent-based ink production faces disruption from MEE enforcement of provincial carbon intensity targets in Shandong and Jiangsu. Domestic beverage brands expand aluminum can capacity, pulling imported low-migration formulations. Yangtze River Delta packaging clusters retrofit continuous inkjet systems for 600+ bottles per minute throughput.
India
Domestic food processors remain underpenetrated by low-migration ink suppliers despite FSSAI framework development. Dairy and bakery packaging growth in Maharashtra and Gujarat creates specification gaps. Mumbai-based converters seek EU-pre-certified formulations to shortcut compliance timelines for export-oriented accounts.
Japan
Confectionery and pharmaceutical tablet marking applications converge with precision inkjet requirements. METI guidance on food contact materials shapes domestic formulation standards. Osaka-Kobe industrial corridor hosts specialized R&D for edible ink colorants targeting 3D food printing integration.
Food Marking Inks Market Competitive Landscape
Capital-heavy pigment producers compete with asset-light formulation specialists across distinct margin tiers. Three German and Chinese chemical conglomerates control food-grade titanium dioxide and organic pigment synthesis, creating upstream concentration. Strategic archetypes include vertically integrated pigment-to-ink producers, specialized low-migration formulation labs, and regional solvent-based volume suppliers. Competitive moves center on captive technical service deployment and subscription-based consumables contracting.
Among Germany-based specialists, Siegwerk Druckfarben AG & Co. KGaA exemplifies the R&D-intensive archetype through its European low-migration centers. Sun Chemical anchors the integrated producer tier with captive pigment synthesis capabilities. Flint Group occupies a position in solvent-based segments where beverage coding volume sustains operational scale. These three represent distinct strategic postures rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Sun Chemical |
| Flint Group |
| Siegwerk Druckfarben AG & Co. KGaA |
| Sakata INX Corporation |
| Huber Group |
| T&K TOKA |
| Toyo Ink |
| Independent Ink |
| InkJet, Inc. |
| Others |
Value Network & Pricing Analysis
Backward integration into pigment synthesis anchors both supply security and pricing power for leading ink producers, with Sun Chemical's captive titanium dioxide production insulating formulation margins against energy-driven volatility in German and Chinese chemical corridors.
Pricing Analysis
Margin tightening in UV-curable formulations reflects REACH Article 33 compliance costs and photoinitiator replacement cycles. Three-tier pricing structure across premium low-migration, standard industrial-grade, and economy solvent-based levels separates EFSA-certified direct food contact recipes from secondary packaging alternatives. Beverage producers demonstrate lowest price sensitivity due to line-speed reliability requirements, while mid-tier converters in Southern Europe resist subscription models without guaranteed uptime clauses.
Supply Chain Analysis
EFSA pre-certification gating restricts supplier pools to three approved vendors for major Italian and Spanish converters managing documentation burden. Food-grade titanium dioxide and organic pigment synthesis concentrates in Germany and China, with formulation chemistry drawing from ethyl acetate, acrylate oligomers, and cationic epoxy resin feedstocks. Single-source vulnerability concentrates in Shandong province where MEE carbon enforcement disrupts solvent-based production. Distribution runs through direct technical service relationships for certified formulations, with regional distributors handling spot replenishment for standardized water-based grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
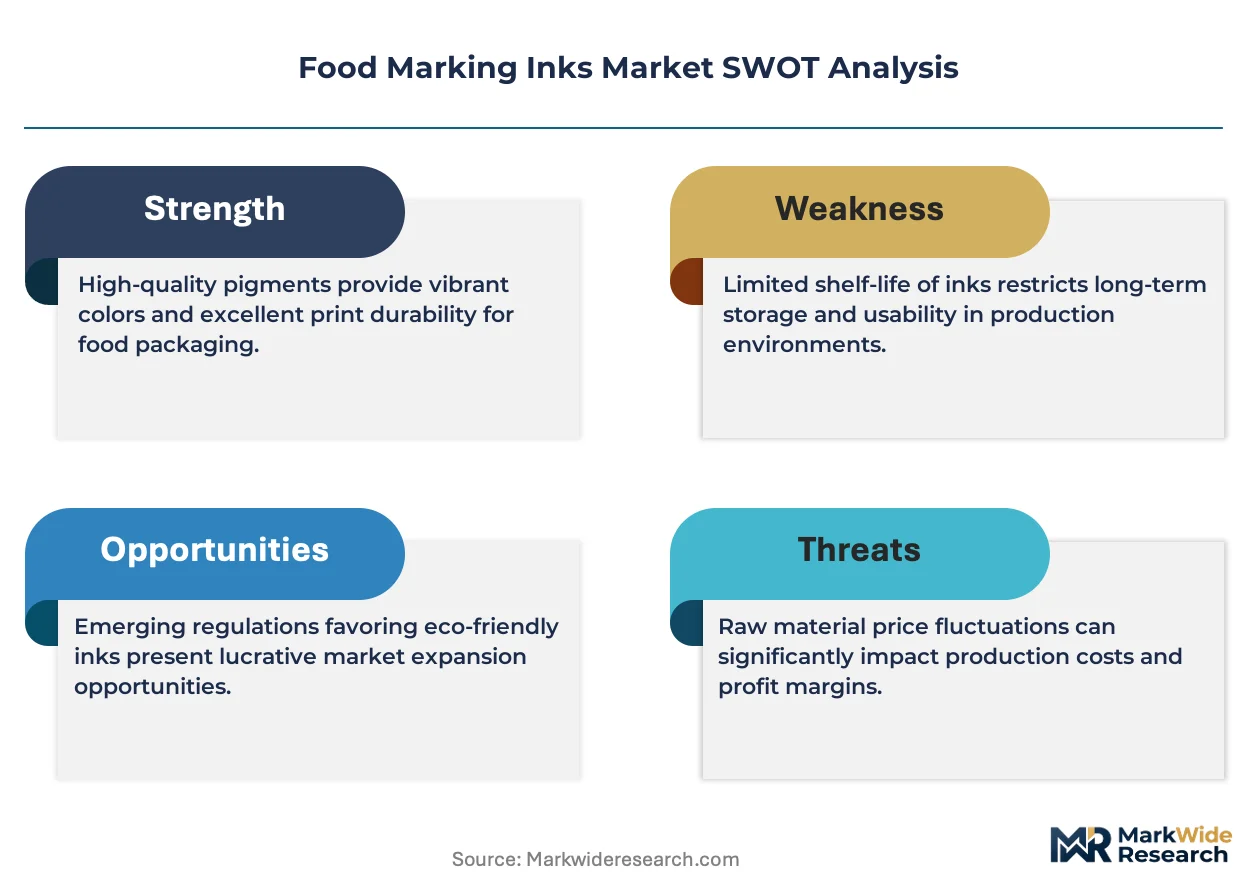
Consolidation pressure intensifies as EFSA's expanded migration testing mandates force smaller Italian and Spanish converters to collapse supplier relationships, eliminating formulation specialists lacking analytical chemistry capabilities.
For Market Incumbents: Deepen captive technical service deployment in Bavarian dairy clusters to lock in full-cost-per-print contracts before equipment OEMs acquire formulation capabilities. Invest in photoinitiator-free cationic epoxy R&D to compress regulatory approval timelines from thirty-six to eighteen months. Defend against Stuttgart-based equipment manufacturers by integrating IoT-enabled tank monitoring into subscription replenishment models. For New Entrants and Emerging Players: Enter via FSSAI compliance gap in Maharashtra and Gujarat dairy packaging, where domestic Indian processors seek EU-pre-certified formulations for export-oriented accounts. Target edible ink convergence with 3D food printing applications in Osaka-Kobe corridor. Pursue white-label formulation partnerships with Mumbai-based converters lacking in-house migration testing infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of specialized low-migration formulation labs by equipment OEMs seeking recurring consumables revenue. Long-term viability favors R&D-intensive archetypes with established EFSA dossier libraries over regional solvent-based volume suppliers exposed to China's dual carbon enforcement. Watch for inflection when UV LED curing technical ceiling resolves for cationic epoxy adhesion on polypropylene films.| Strategic Initiative | Industry Significance |
|---|---|
| Photoinitiator-Free UV Formulation Development | Eliminates separate toxicology dossiers, compressing EFSA approval timelines for Bavarian dairy processors. |
| IoT-Enabled Tank Monitoring Integration | Captures recurring revenue streams from packaging converters unbundling hardware from consumable procurement. |
| Backward Integration into Pigment Synthesis | Insulates margin position against energy price spikes concentrated among German and Chinese chemical conglomerates. |
| India FSSAI Pre-Certification Entry | Shortcuts compliance timelines for export-oriented dairy and bakery accounts in Maharashtra and Gujarat. |
| Equipment OEM Formulation Capability Acquisition | Enables full-cost-per-print contracting and displaces traditional chemical supplier relationships in German beverage coding. |
Research Methodology
Independent corroboration across ink formulation executives, packaging converter procurement leads, regulatory affairs specialists at EFSA-notified bodies, and continuous inkjet equipment OEMs underwrites the qualitative findings. Secondary validation draws from REACH SVHC candidate list updates, EFSA guidance documents on printing inks, customs data for titanium dioxide trade flows, and SEC filings of pigment-producing chemical conglomerates. Bottom-up volume estimates from formulation chemistry segments triangulate against top-down value projections anchored in procurement contract structures.
Comparable-period anchoring to historical regulatory implementation cycles shapes the projection horizon, with segmentation dimensions spanning formulation chemistry, regulatory contact class, and end-user procurement sophistication. CAGRs derive from line-speed capacity expansion in Central European dairy and meat processing, aluminum can coding migration trends, and subscription model penetration rates across German packaging converters. Industry-specific inputs include UV LED curing wavelength adoption curves and photoinitiator replacement cycle timing under REACH Article 33.
Revisions become necessary when EFSA publishes updated specific migration limit guidance, when China's MEE enforcement intensity shifts provincial carbon targets, or when UV LED technical specifications resolve cationic epoxy polymerization gaps. A model refresh is warranted upon material change in beverage producer direct substrate marking adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Ink Resins Market
Printing Inks
Non-Conductive Ink Market
Printing Inks
Global Flexographic Inks Market
Printing Inks
Water-Based Metal-Deco Beverage Can Inks Market
Printing Inks
Global Light Changing Packaging Inks Market
Printing Inks
Solvent-Based Inks Market
Printing Inks
Global Decorative Print Market
Printing Inks
Rapid Liquid Printing Market
Printing Inks
Global Digital Inks Market
Printing Inks
Brazil Commercial Printing Market
Printing Inks
UV Fluorescing Ink Market
Printing Inks
Textile Printing Ink Market
Printing Inks
Global Printing Blanket Market
Printing Inks
Global Printing Toners Market
Printing Inks
Returnable Glass Bottle Ink Market
Printing Inks
Thermochromic Ink Printing Market