
 Global Glycerol Monostearate (GMS) Powder Market | 2026-2036
Global Glycerol Monostearate (GMS) Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Global Glycerol Monostearate (GMS) Powder Market Foresight
A skilled process engineering labor pool is unwinding capacity bottlenecks across Southeast Asian GMS production hubs. Croda International Plc leverages backward integration into vegetable oil feedstocks to secure margin control. Lonza Group AG sustains pharmaceutical-grade certification intensity across European and North American facilities. Wilmar International Limited anchors regional supply through palm oil origination strength in Malaysia and Indonesia.
Glycerol monostearate powder is a glycerol ester of stearic acid, typically manufactured via direct esterification of glycerol with stearic acid or transesterification of fats, yielding a white to off-white powder with an HLB value near 3.8 that functions primarily as a lipophilic emulsifier and stabilizer in oil-in-water systems. Food Grade GMS dominates volume throughput due to baked goods and dairy applications, while Pharmaceutical Grade commands the deepest margin pools driven by excipient purity mandates. Cosmetic Grade is accelerating fastest as formulators replace synthetic surfactants with plant-derived alternatives in skin care and hair care products.
FDA food additive regulations under 21 CFR 184.1324 govern GMS use in U.S. food systems, while EFSA purity standards and REACH registration requirements shape European market access conditions. China's SAMR enforces GB standards for food-grade emulsifiers that increasingly align with CODEX specifications. Stakeholders must monitor evolving biobased certification schemes and feedstock traceability requirements that will determine supplier qualification thresholds.
Market Dynamics
EU Green Deal compliance mandates and REACH purity requirements are compressing supplier qualification thresholds while concentrating demand among certified manufacturers capable of pharmaceutical-grade output.
Growth Catalysts
- EFSA purity standards:Tightened emulsifier-grade specifications across European food systems are filtering out subscale producers and redirecting volume toward integrated refiners.
- Baked goods sector:Extended shelf-life demands in packaged bread and pastry applications are expanding Food Grade GMS incorporation rates in oil-in-water stabilizer systems.
- Malaysia-Indonesia palm oil origination:Feedstock proximity to Southeast Asian processing hubs is shortening supply chains and improving margin capture for regional manufacturers.
Market Restraints
- Palm oil price volatility:Crude palm oil futures swings directly compress GMS producer margins due to feedstock concentration in tropical monoculture supply.
- Stearic acid supply concentration:Hydrogenated tallow and vegetable-derived stearic acid production clusters in specific geographies create single-source vulnerability for non-integrated compounders.
- Pharmaceutical-grade certification timelines:FDA 21 CFR 184.1324 and EMA excipient qualification protocols extend facility validation cycles beyond 18 months.
Strategic Opportunities
- India FSSAI alignment:Domestic food processing capacity expansion under PLI scheme incentives is creating import substitution demand for locally manufactured emulsifier grades.
- Cosmetic surfactant replacement:Formulators in skin care and hair care are substituting synthetic ethoxylates with plant-derived GMS in clean-label positioning strategies.
- Biobased certification schemes:RSPO Mass Balance and analogous traceability frameworks are opening premium pricing tiers for verified sustainable feedstock sourcing.
Industry Challenges
- Process engineering talent scarcity:Skilled esterification and transesterification specialists are concentrated in established European and Southeast Asian production centers, limiting new facility ramp rates elsewhere.
- Dual-grade facility reconfiguration:Switching between Food Grade and Pharmaceutical Grade output requires complete CIP validation and analytical method transfers that idle capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Glycerol Monostearate (GMS) Powder Market |
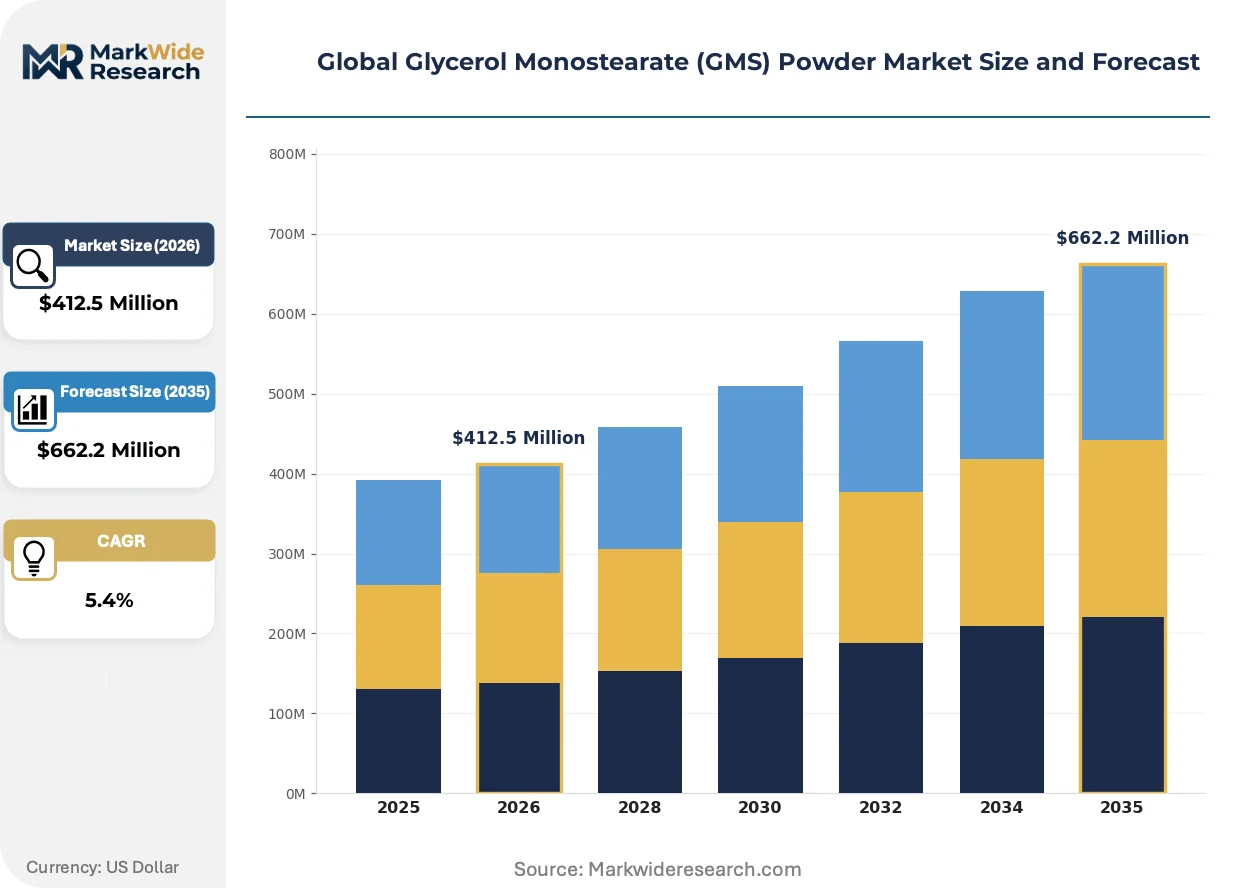
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Food Grade, Cosmetic Grade, Industrial Grade Application: Emulsifiers, Thickening Agents, Anti-caking Agents, Moisturizers, Lubricants End Use Industry: Personal Care, Pharmaceuticals, Food & Beverage, Animal Nutrition Packaging Type: Bag, Drum, Box, Bulk Container, Carton |
| Companies Covered | Croda International Plc, Lonza Group AG, Wilmar International Limited, Kao Corporation, Evonik Industries AG, BASF SE, Stepan Company, Oleon NV, Cargill, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Glycerol Monostearate (GMS) Powder Market Shifts & Advancements
Enzymatic esterification processes and precision hydrogenation technologies are displacing conventional chemical routes, while regulatory traceability mandates and buyer certification requirements are reshaping procurement qualification protocols.
Enzymatic glycerolysis using immobilized lipase catalysts is supplanting traditional sodium hydroxide-catalyzed transesterification in high-purity GMS manufacturing. European pharmaceutical excipient suppliers have adopted this biocatalytic route at commercial scale since 2022. The shift is compressing energy intensity per ton while enabling single-digit ppm residual fatty acid specifications that chemical processes struggle to achieve.
REACH registration dossier updates under the 2023-2025 substance evaluation work program are mandating enhanced toxicological data packages for glycerol fatty acid esters used in food contact applications. ECHA's systematic re-evaluation of emulsifier safety profiles is extending registration maintenance costs for importers. Small-volume traders without in-house regulatory affairs capabilities are exiting the European market, consolidating supply relationships with dossier-holding manufacturers.
Direct long-term contracting between food manufacturers and GMS producers is displacing spot market purchases through distributor intermediaries. Large baked goods and dairy processors in China are negotiating multi-year offtake agreements with Malaysian and Indonesian integrated refiners. This channel compression is most visible in coastal Chinese provinces where domestic food processing clusters have scaled to absorb container-direct shipments.
Global Glycerol Monostearate (GMS) Powder Market Segmentation
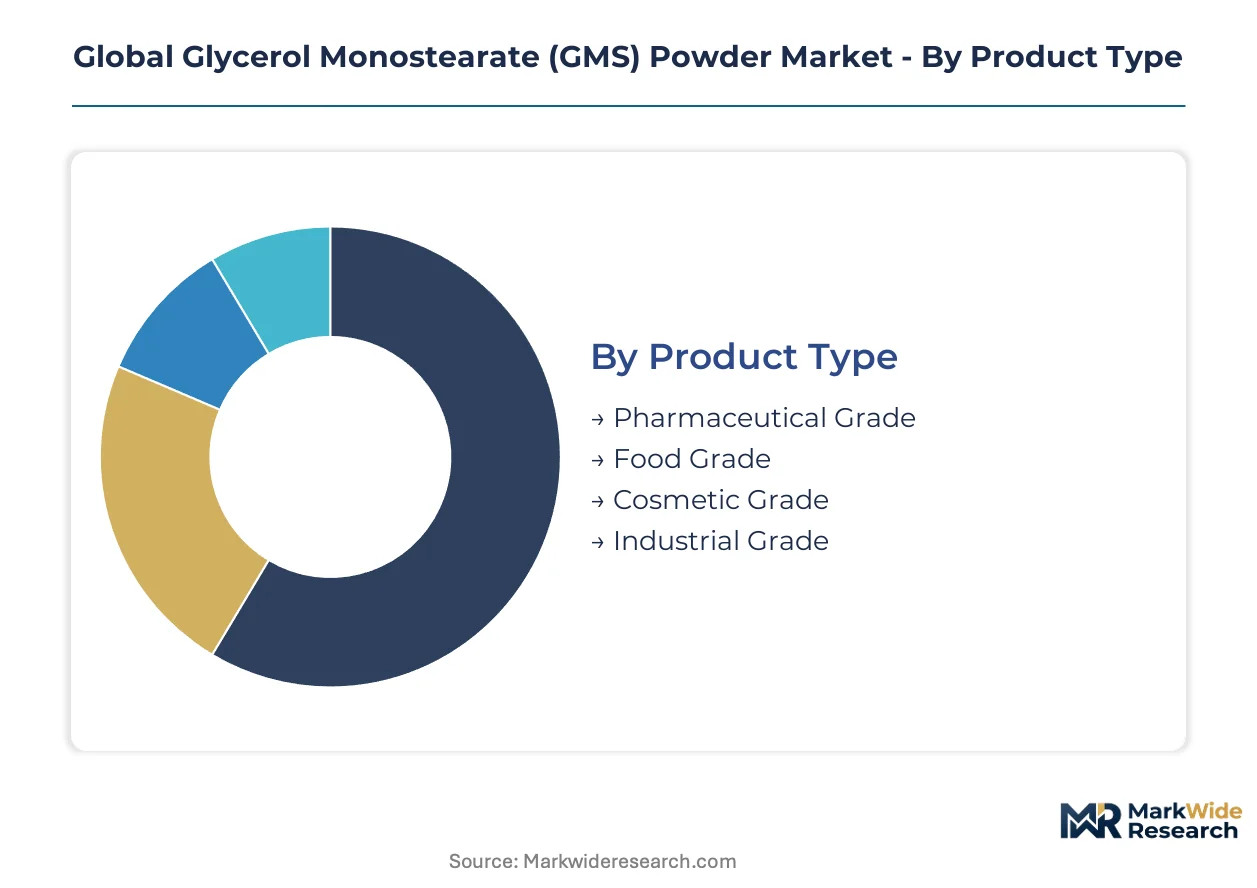
GMS powder segmentation reveals how purity thresholds and regulatory frameworks partition margin pools across grades. Manufacturers configure esterification capacity to capture value concentration in pharmaceutical and cosmetic applications while maintaining food-grade throughput for volume stability.
Product Type:
Margin pools concentrate in pharmaceutical-grade output where excipient certification commands premium pricing, while food-grade dominates tonnage throughput.
- Pharmaceutical Grade:Manufactured via enzymatic esterification to achieve single-digit ppm residual fatty acid specifications. FDA 21 CFR 184.1324 and EMA excipient qualification protocols restrict supply to validated facilities, concentrating demand in Germany, Switzerland, and Singapore.
- Cosmetic Grade:Accelerating substitution for synthetic ethoxylates in clean-label skin care formulations. RSPO Mass Balance certification opens premium tiers for Malaysian and Indonesian producers serving European personal care brands.
- Food Grade:Standard emulsifier-grade GMS for baked goods and dairy stabilization.
- Industrial Grade:Lower-purity material for polymer processing and metalworking lubricants.
Pharmaceutical Grade holds installed capacity. Cosmetic Grade is rotating up the share rankings.
Application:
Application segmentation tracks functional deployment across oil-in-water systems, with emulsifier demand anchored in food processing and thickening agents expanding in personal care.
- Emulsifiers:Primary function leveraging HLB 3.8 lipophilicity for oil-in-water stabilization. Extended shelf-life requirements in Chinese and Indian packaged bread applications are expanding incorporation rates.
- Thickening Agents:Texture modification in lotions and creams where GMS replaces carbomer and xanthan gum in natural-positioned formulations. European cosmetic formulators in France and Germany are standardizing this substitution.
- Anti-caking Agents:Powder flow control in seasonings and grated cheese.
- Moisturizers:Occlusive film-forming in leave-on skin products.
- Lubricants:Tablet compression aid and mold release in pharmaceutical tableting.
Emulsifiers anchor current volume. Thickening Agents are climbing the fastest as clean-label cosmetics expand.
End Use Industry:
End-use segmentation reflects divergent purity requirements and certification intensity across consumer-facing sectors.
- Personal Care:Surfactant replacement trend in skin and hair care, with formulators in Japan and South Korea adopting GMS for silicone-free conditioning systems.
- Pharmaceuticals:Excipient-grade supply governed by USP-NF and EP monographs, with validation cycles exceeding eighteen months.
- Food & Beverage:Dominant volume sector spanning bakery, dairy, and confectionery applications.
- Animal Nutrition:Feed pellet binding and fat encapsulation for ruminant and aquaculture diets.
Food & Beverage maintains capacity leadership. Personal Care is gaining share fastest on surfactant substitution momentum.
Packaging Type:
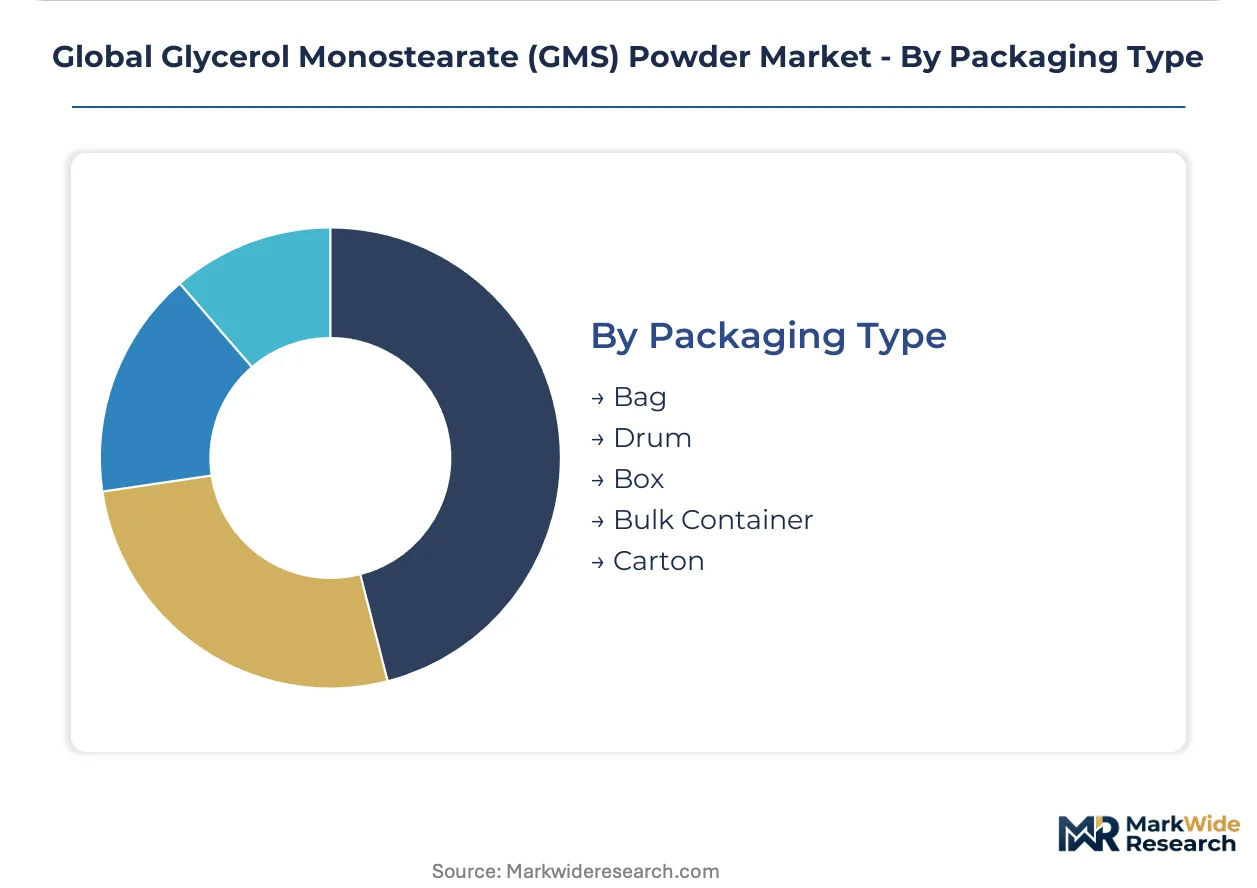
Packaging configuration aligns with customer scale and handling infrastructure, from manual bag breaking to automated bulk systems.
- Bag:Standard 25kg kraft multiwall units for mid-scale food processors and compounders.
- Drum:Steel and fiber drums for pharmaceutical and cosmetic manufacturers requiring contamination control.
- Box:Corrugated units for retail ingredient distribution.
- Bulk Container:Flexible intermediate bulk containers and tanker deliveries for integrated baked goods and dairy operations in coastal China.
- Carton:Shelf-ready packaging for specialty cosmetic ingredient distribution.
Bag and drum formats hold installed capacity. Bulk Container is rotating up the share rankings on direct mill-to-plant contracting expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and Switzerland outstrips Malaysian and Indonesian supply bases by double-digit margins, reflecting pharmaceutical-grade certification premiums against feedstock-integrated cost structures. This asymmetry shapes regional competitive positioning across the value chain.
China
Domestic food processing clusters in Shandong and Jiangsu provinces absorb container-direct shipments from Southeast Asian refiners. SAMR's GB standards alignment with CODEX specifications is tightening import qualification thresholds. Qingdao and Shanghai ports now handle bulk GMS deliveries under multi-year offtake agreements with Malaysian integrated producers.
Germany
Pharmaceutical excipient demand from Bavarian and North Rhine-Westphalian drug manufacturers sustains premium-grade capacity. EMA qualification protocols and REACH registration requirements filter supply to dossier-holding manufacturers. Frankfurt-Rhine-Main logistics corridors enable just-in-time delivery to validated tableting facilities.
United States
FDA 21 CFR 184.1324 compliance underpins food-grade incorporation in Midwestern baked goods operations. Extended shelf-life requirements in Illinois and Ohio bread processing plants are expanding emulsifier procurement volumes. New Jersey and Pennsylvania distribution hubs channel pharmaceutical-grade material to East Coast generic drug manufacturers.
Malaysia
RSPO Mass Balance certification opens premium pricing tiers for personal care brands in Europe and Japan. Port Klang and Pasir Gudang processing facilities leverage captive palm oil origination from Peninsular Malaysia estates. Wilmar International Limited anchors regional supply through upstream feedstock control.
India
FSSAI alignment under PLI scheme incentives is creating import substitution demand for locally manufactured food-grade emulsifiers. Maharashtra and Gujarat food processing corridors are scaling domestic compounder capacity. Mumbai and Ahmedabad logistics nodes are consolidating distribution for bakery and dairy sector procurement.
Global Glycerol Monostearate (GMS) Powder Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. European and Swiss manufacturers concentrate pharmaceutical-grade output with enzymatic process certification, while Southeast Asian integrated refiners capture feedstock-adjacent margin efficiency. The market organizes around three strategic archetypes: validated excipient specialists, palm oil-integrated mass producers, and diversified chemical conglomerates with emulsifier divisions. Competitive moves center on backward integration into vegetable oil feedstocks and facility validation for dual-grade pharmaceutical-food output.
Among European-based excipient specialists, Croda International Plc and Lonza Group AG occupy positions representing the technology-certified archetype, with regulatory dossier holdings across EMA and FDA jurisdictions. Wilmar International Limited exemplifies the feedstock-integrated model, anchoring Southeast Asian supply through Malaysian and Indonesian palm oil origination strength. These three entities collectively illustrate the competitive tension between certification premiums and cost leadership that defines regional market segmentation.
| Leading Market Players |
|---|
| Croda International Plc |
| Lonza Group AG |
| Wilmar International Limited |
| Kao Corporation |
| Evonik Industries AG |
| BASF SE |
| Stepan Company |
| Oleon NV |
| Cargill, Incorporated |
| Others |
Supply & Pricing Matrix
Eighteen-month pharmaceutical-grade certification timelines compress supplier pools and amplify pricing power for validated manufacturers in Germany and Switzerland against Malaysian feedstock-integrated competitors. This lead-time asymmetry concentrates premium capture among EMA-qualified facilities while standard-grade pricing tracks palm oil futures volatility.
Pricing Analysis
Configured-to-order pharmaceutical-grade GMS commands spreads exceeding standard food-grade material by certification intensity and excipient validation depth. Three-tier pricing structure across pharmaceutical, cosmetic, and food grades reflects purity thresholds and regulatory dossier maintenance costs. Pricing pressure stems from crude palm oil futures swings that transmit directly to non-integrated compounder margins. Food-grade buyers in Chinese baked goods operations exhibit highest price sensitivity, while pharmaceutical formulators prioritize supply security over unit cost.
Supply Chain Analysis
Container availability constraints on Southeast Asia-to-China trade lanes elevate inbound logistics costs for Malaysian and Indonesian refiners serving Shandong processing clusters. Supply concentrates in Malaysia, Indonesia, and Germany through palm oil origination strength and pharmaceutical-grade validation infrastructure. Feedstock dependence draws from crude palm oil, hydrogenated stearic acid, and immobilized lipase catalysts. Single-source vulnerability runs through stearic acid production clusters in specific geographies. Distribution runs through direct mill-to-plant contracting between integrated refiners and coastal Chinese food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. EMA and FDA validation cycles exceeding eighteen months create switching costs that protect incumbent position.
For Market Incumbents: Consolidate backward integration into vegetable oil feedstocks to defend margin position against palm oil price volatility. Expand dual-grade facility certification across European and Southeast Asian production hubs to capture pharmaceutical-grade premiums. Channel control through direct long-term contracting with Chinese dairy and baked goods processors locks out distributor-dependent competitors. For New Entrants and Emerging Players: Lead with cosmetic-grade enzymatic production targeting RSPO Mass Balance-certified supply to European personal care brands. White-space concentration sits in Indian domestic emulsifier manufacturing under FSSAI-aligned PLI scheme incentives. Go-to-market execution should anchor on clean-label surfactant replacement narratives in French and German formulator networks. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underoptimized emulsifier divisions lacking pharmaceutical-grade certification depth. Long-term viability over the coming decade rests on enzymatic process technology ownership and regulatory dossier maintenance capabilities. Signal to monitor: FDA 21 CFR 184.1324 enforcement intensity shifts that accelerate facility validation backlog.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palm Oil Feedstocks | Wilmar International Limited secures margin control through Peninsular Malaysia estate origination. |
| Pharmaceutical-Grade Facility Validation | Croda International Plc maintains EMA qualification protocols that filter supply to dossier-holding manufacturers. |
| Enzymatic Esterification Process Adoption | European excipient suppliers achieve single-digit ppm residual fatty acid specifications via immobilized lipase catalysts. |
| RSPO Mass Balance Certification | Malaysian producers unlock premium pricing tiers for verified sustainable feedstock sourcing to European brands. |
| Direct Long-Term Supply Contracting | Chinese baked goods processors in Shandong province negotiate container-direct multi-year offtake agreements. |
Research Methodology
Desk research of customs trade databases, SEC 10-K filings, and ECHA registration dossiers preceded structured interviews with plant managers at Southeast Asian refiners, procurement leads at Chinese dairy processors, distribution channel partners, and technical R&D directors. Primary fieldwork combined with secondary validation from FDA 21 CFR 184.1324 filings and SAMR GB standard documentation. Bottom-up capacity modeling and top-down demand estimation triangulated volume and value outputs.
Variance decomposition across pharmaceutical-grade, cosmetic-grade, and food-grade segments structured the analytical framework over the projection horizon. Modeling incorporated grade tier, end-use industry, packaging format, and regional production hub dimensions. CAGRs derived from elasticity-adjusted demand curves and capacity expansion timelines. Forecast inputs included palm oil futures trajectory assumptions and EMA excipient qualification protocol evolution.
Underlying assumptions cover sustained EFSA purity standard enforcement and PLI scheme incentive continuity in India, with deviation risk concentrated in crude palm oil supply disruptions and REACH registration maintenance cost escalation. Practitioners should keep alternative scenarios live as EU Green Deal compliance mandates and enzymatic process technology diffusion rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Mancozeb Market
Bulk Chemicals
N-Heptane Market
Bulk Chemicals
Naphthalene Market
Bulk Chemicals
Tertiary Butylhydroquinone Market
Bulk Chemicals
Europe Ammonium Nitrate Market
Bulk Chemicals
Alunite Market
Bulk Chemicals
Muconic Acid Market
Bulk Chemicals
Asia-Pacific Quicklime Market
Bulk Chemicals
Ethylene and Propylene Market
Bulk Chemicals
Europic Chloride Market
Bulk Chemicals
Ammonium Molybdate Market
Bulk Chemicals
Adipic Acid Market
Bulk Chemicals
Magnesium Sulfate Market
Bulk Chemicals
2-Ethylhexanoyl Chloride Market
Bulk Chemicals
Sodium Tungstate Dihydrate Market
Bulk Chemicals
Isovaleryl Chloride Market