
 Dimethyldichlorosilane Market | 2026-2036
Dimethyldichlorosilane Market Size, Share, and Industry Trends Forecast 2026-2036
Dimethyldichlorosilane Market Outlook
Modular supply contracts for chlorosilane intermediates is hardening buyer preferences toward bundled purity certification and logistics services. Dow Chemical Company leverages its integrated silicone feedstock network across North American production corridors. Wacker Chemie AG anchors European supply through its Burghausen manufacturing complex and captive siloxane downstream operations. Shin-Etsu Chemical Co., Ltd. dominates Asian chlorosilane output with vertical control from metallurgical silicon to finished silicone polymers.
Dimethyldichlorosilane (DMDCS) functions as a foundational organochlorosilane intermediate, typically manufactured via the direct process reaction of methyl chloride with silicon metal in the presence of copper catalyst at elevated temperatures, yielding a colorless liquid with a pungent odor that serves as the primary precursor for polydimethylsiloxane and other silicone polymers. The silicone production application segment leads value capture due to its irreplaceable role in elastomers, fluids, and resins across industrial and consumer formulations. The electronics end-user category registers the fastest structural expansion, driven by thermal management materials and conformal coatings in semiconductor fabrication. Liquid form formulations command premium positioning owing to handling efficiency and established bulk chemical infrastructure compatibility.
EPA oversight in the United States governs chlorosilane emissions and workplace exposure thresholds under Clean Air Act and OSHA frameworks, while REACH registration in Europe mandates comprehensive substance dossiers for DMDCS import and manufacture. China's MEE enforces increasingly stringent VOC and hazardous chemical storage protocols that elevate compliance costs for domestic and foreign producers alike. Stakeholders must monitor regulatory divergence between jurisdictions, as divergent purity and documentation requirements threaten to fragment supply chain interoperability and complicate cross-border qualification programs.
Market Dynamics
Integrated chlorosilane-silicone production corridors are consolidating procurement power among buyers who demand bundled purity certification and captive logistics services. This structural concentration is compressing margins for non-integrated intermediates suppliers while rewarding backward-linked producers.
Growth Catalysts
- Semiconductor packaging thermal management:Advanced conformal coatings and heat-dissipating materials in chip fabrication are drawing specialized silicone formulations that require high-purity DMDCS feedstock.
- REACH registration completion:Comprehensive substance dossiers under ECHA frameworks have stabilized European import pathways, reducing qualification friction for compliant suppliers.
- China's integrated chemical clusters:Domestic silicone capacity expansion around Yangtze River Delta manufacturing corridors is concentrating procurement decisions toward Asia-Pacific supply bases with captive metallurgical silicon sources.
Market Restraints
- Metallurgical silicon price volatility:Energy-intensive silicon metal production faces electricity cost swings that transmit directly into DMDCS manufacturing economics.
- Supply concentration in German and Japanese producers:Captive siloxane operations at Burghausen and Niigata facilities limit third-party spot market liquidity for independent buyers.
- Fluorosilicone substitution in aerospace seals:Perfluorinated elastomers are displacing conventional silicone in fuel-contact applications above 200°C operating thresholds.
Strategic Opportunities
- India specialty silicone formulation:PLI scheme incentives for electronics manufacturing are creating downstream demand for imported chlorosilane intermediates as domestic polymerization capacity scales.
- MEE hazardous chemical storage protocols:Stricter VOC containment mandates in China are elevating compliance costs for non-integrated traders, opening margin expansion for certified tank-farm operators.
- Bio-based siloxane feedstock development:Convergence of agricultural waste pyrolysis with direct process chemistry offers pathway to reduced-carbon silicone precursors.
Industry Challenges
- Process safety engineering expertise:Pyrophoric chlorosilane handling and copper catalyst management require specialized technicians that command premium compensation in tight labor markets.
- Cross-jurisdictional dossier harmonization:Divergent purity specifications between EPA Clean Air Act thresholds and REACH annex requirements complicate single-plant qualification for multi-region supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dimethyldichlorosilane Market |
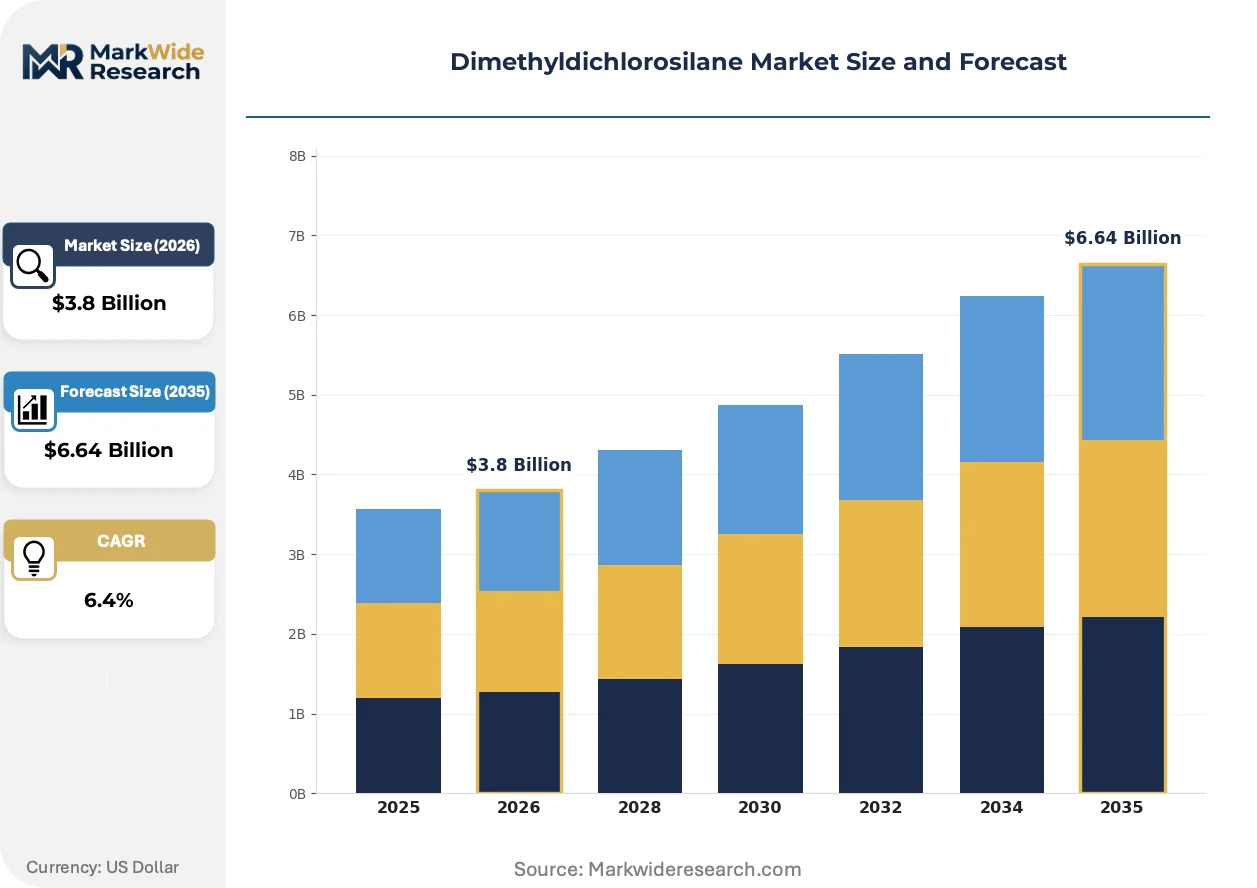
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Silicone Production, Coatings, Adhesives, Sealants Form: Liquid, Gas, Solid, Viscous End User: Chemical Manufacturers, Electronics, Automotive, Healthcare Technology: Synthesis, Polymerization, Catalysis, Extraction |
| Companies Covered | Evonik Industries AG, Elkem ASA, Dow Chemical Company, Merck KGaA, Momentive Performance Materials, Shin-Etsu Chemical Co., Ltd., Gelest Inc., China National Bluestar (Group) Co., Ltd., Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dimethyldichlorosilane Market Strategic Shifts
Digital process control systems are penetrating chlorosilane manufacturing floors, replacing manual sampling with real-time spectroscopic monitoring. This instrumentation shift is compressing batch-to-batch variation while elevating capital intensity for facility upgrades.
Continuous flow reactor technology is automating methyl chloride-silicon contact patterns that historically required batch vessel cycling. Shin-Etsu and Wacker pilot installations demonstrate 15-20% yield improvement over conventional stirred-tank designs. The technology is automating quality consistency benchmarks that previously demanded extensive downstream distillation.
EPA's evolving chlorosilane workplace exposure thresholds under revised OSHA frameworks are mandating closed-loop sampling infrastructure. Facilities without automated leak detection face accelerated compliance timelines through 2027. Electronics-grade silicone producers with existing cleanroom protocols are adapting fastest, leveraging containment expertise from semiconductor client specifications.
Specification-driven procurement contracts are displacing commodity spot purchasing among North American silicone formulators. Buyers now bundle purity certification, lot traceability, and dedicated tank-car logistics into multi-year supply agreements. This pattern is most visible in automotive thermal interface material supply chains, where Tesla and Rivian battery pack specifications propagate upstream to DMDCS sourcing criteria.
Dimethyldichlorosilane Market Segmentation
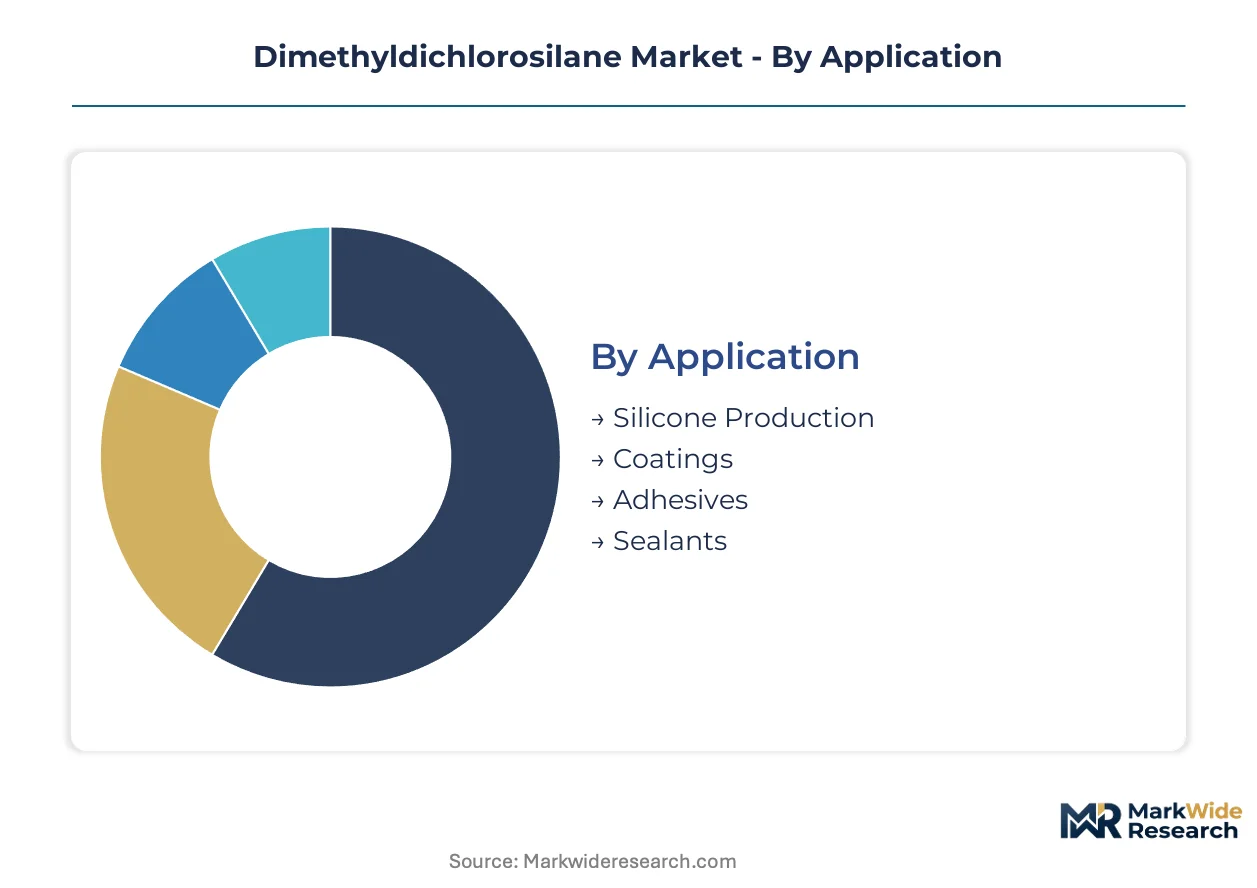
Dimethyldichlorosilane market dynamics diverge sharply across application chemistry and customer technical requirements. Segment-specific purity thresholds, handling protocols, and integration depth create distinct competitive arenas with uneven margin profiles.
Application:
Capital intensity concentrates in silicone production corridors where direct-process reactors and integrated distillation trains demand nine-figure facility investments.
- Silicone Production:Polydimethylsiloxane precursor manufacturing consumes over 90% of commercial DMDCS volume. Shin-Etsu's Niigata complex and Wacker's Burghausen facility anchor supply through captive siloxane polymerization, locking in long-term offtake contracts.
- Coatings:Conformal coating formulations for semiconductor packaging require electronics-grade purity specifications. Demand concentrates in China's Yangtze River Delta where domestic silicone capacity expansion is drawing procurement decisions toward Asia-Pacific supply bases with integrated metallurgical silicon sources.
- Adhesives:Industrial bonding applications leverage DMDCS-derived silane coupling agents for substrate adhesion enhancement.
- Sealants:Construction and automotive gasket formulations utilize chlorosilane intermediates for moisture-cure chemistry.
Most installed capacity flows through Silicone Production. Expansion is steepest in Coatings.
Form:
Handling economics and infrastructure compatibility drive procurement preferences toward specific physical states.
- Liquid:Standard commercial presentation as colorless, pungent liquid with established bulk chemical logistics compatibility. Tank-car and ISO-tank infrastructure across North American and European chemical corridors supports efficient multimodal distribution to silicone polymerization facilities.
- Gas:Vapor-phase handling for specialized chemical vapor deposition processes in semiconductor fabrication.
- Solid:Crystalline or adsorbed forms for laboratory-scale synthesis and specialty chemical applications.
- Viscous:Partially polymerized or oligomeric preparations for specific adhesive and sealant formulations.
Distribution infrastructure favors Liquid formulations. Technical applications are gaining share fastest in Gas phase handling.
End User:
Customer integration depth determines contract structure and technical service intensity.
- Chemical Manufacturers:Integrated silicone producers with captive chlorosilane synthesis represent the anchor demand segment. Dow Chemical's North American feedstock network and Shin-Etsu's vertical control from metallurgical silicon to finished polymers exemplify this category's procurement power.
- Electronics:Semiconductor packaging thermal management materials and conformal coatings are climbing the fastest as advanced node fabrication multiplies die-level protection requirements.
- Automotive:Battery pack thermal interface materials and gasketing applications propagate upstream purity specifications to DMDCS sourcing criteria.
- Healthcare:Medical-grade silicone formulations for implants and drug delivery systems demand traceable, low-metal-content feedstock with extensive documentation.
Contract volume concentrates with Chemical Manufacturers. Specification intensity is expanding most quickly in Electronics.
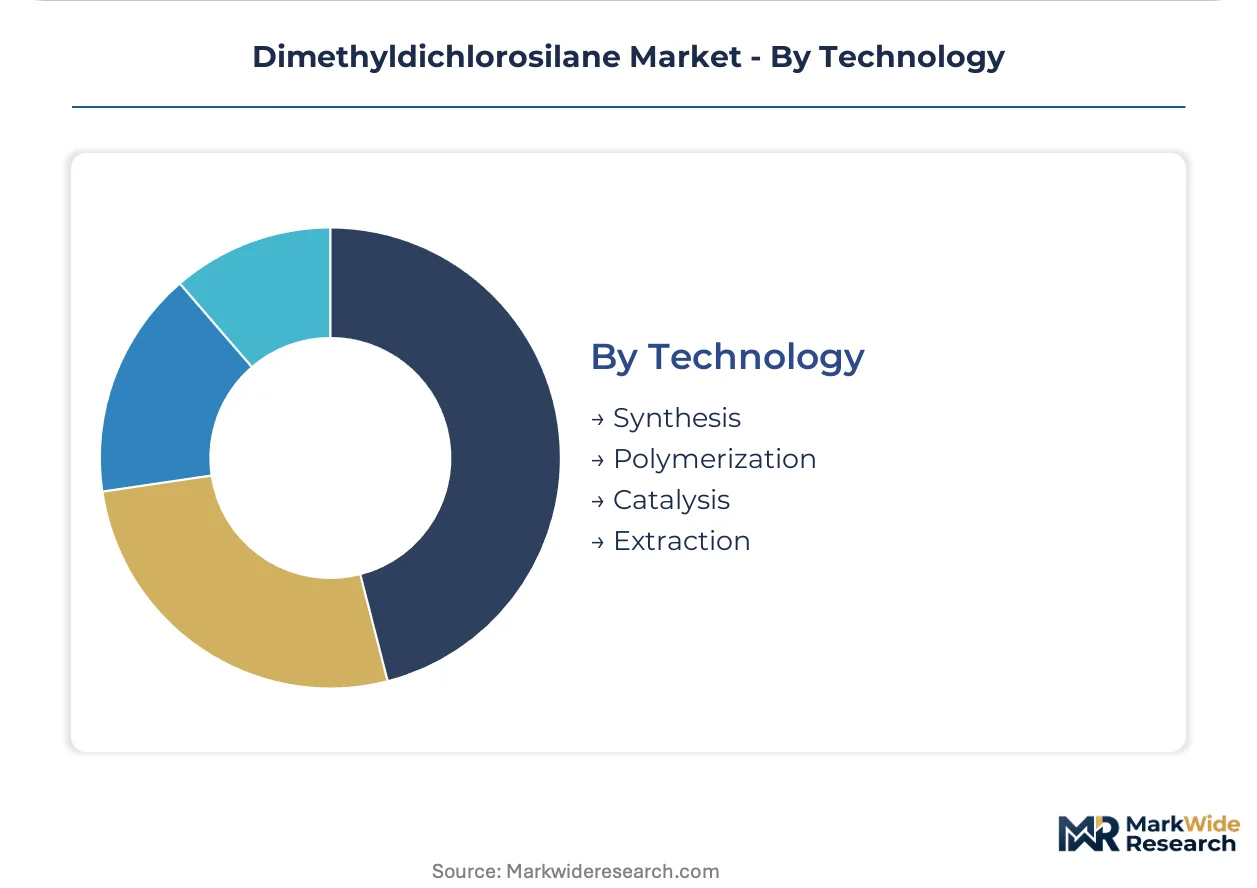
Technology:
Process selection governs yield efficiency, impurity profiles, and regulatory compliance architecture.
- Synthesis:Direct reaction of methyl chloride with silicon metal in copper-catalyzed fluidized bed reactors remains the dominant production pathway. Continuous flow reactor pilot installations at major producers demonstrate 15-20% yield improvement over conventional stirred-tank designs.
- Polymerization:Hydrolysis and condensation chemistry converting DMDCS to siloxane oligomers and polymers.
- Catalysis:Copper catalyst management and regeneration systems critical to process economics and product distribution.
- Extraction:Downstream distillation and purification trains separating methylchlorosilane product mixtures.
Production asset base centers on Synthesis technology. Investment flow is strongest toward Catalysis optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The dimethyldichlorosilane industry traces its commercial origins to post-war industrial chemistry corridors in Germany and the United States, where direct-process technology first achieved scalable methylchlorosilane output.
United States
Semiconductor packaging thermal management materials and automotive battery thermal interface specifications drive electronics-grade DMDCS procurement. EPA oversight under revised Clean Air Act frameworks mandates closed-loop sampling infrastructure through 2027. The Gulf Coast chemical corridor hosts integrated chlorosilane-silicone production assets with established tank-car distribution networks.
Germany
REACH registration completion under ECHA frameworks has stabilized European import pathways for compliant suppliers. The Burghausen manufacturing complex anchors continental supply through captive siloxane downstream operations. Bavaria's integrated chemical clusters concentrate metallurgical silicon processing with chlorosilane synthesis in contiguous production corridors.
China
Domestic silicone capacity expansion around Yangtze River Delta manufacturing corridors concentrates procurement decisions toward Asia-Pacific supply bases. MEE enforcement of stricter VOC and hazardous chemical storage protocols elevates compliance costs for non-integrated traders. Shanghai and Jiangsu province host captive metallurgical silicon sources feeding integrated DMDCS-to-polymer production lines.
Japan
Advanced node semiconductor fabrication multiplies die-level protection requirements for conformal coating formulations. METI industrial standards govern chlorosilane purity specifications for electronics-grade applications. The Niigata prefecture complex maintains vertical control from metallurgical silicon through finished silicone polymers.
South Korea
Memory and logic chip packaging expansion drives demand for specialized silicone thermal management materials. National chemical safety frameworks align with semiconductor client cleanliness protocols. The Gyeonggi-do corridor clusters electronics materials formulators with imported chlorosilane intermediate processing capacity.
Dimethyldichlorosilane Market Competitive Environment
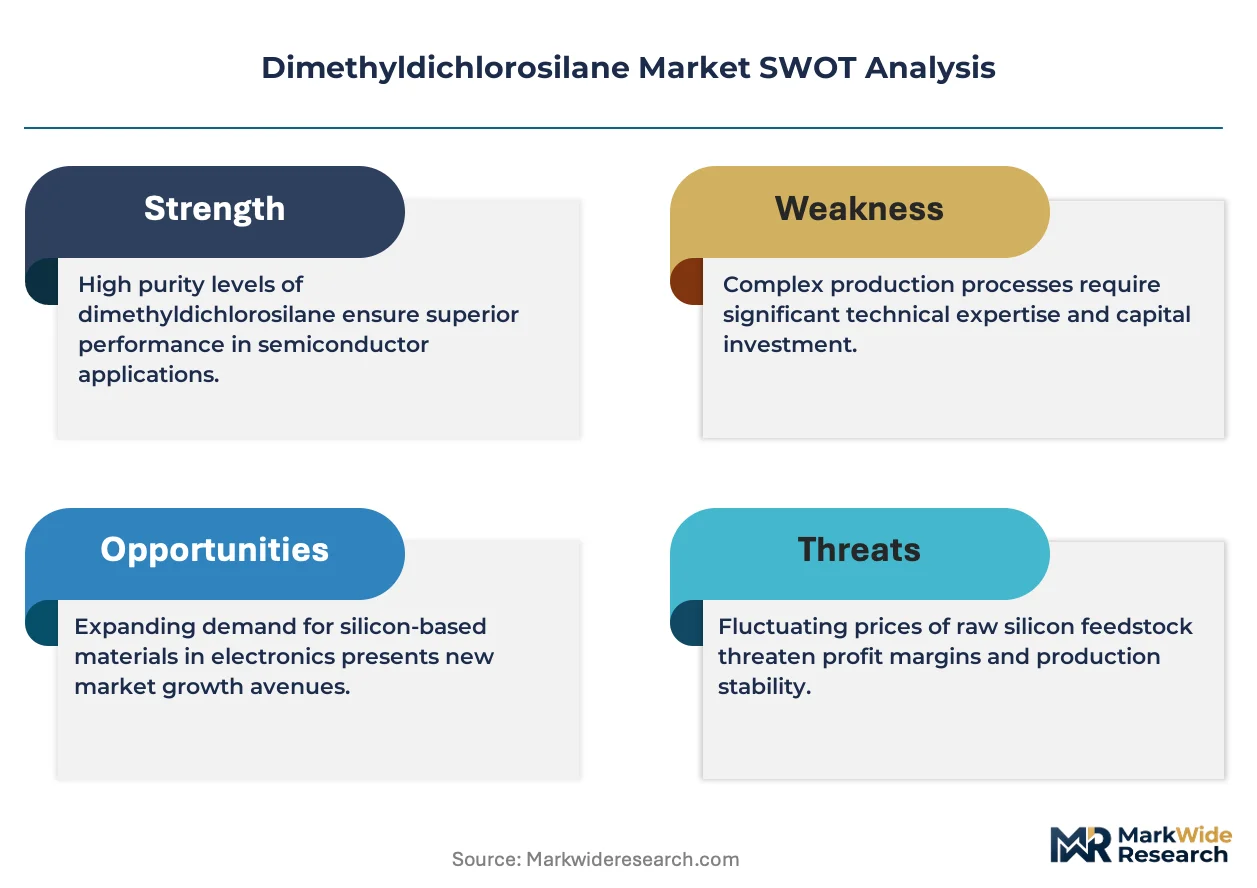
Premium-margin players sit above commodity-margin players across integration depth, with captive siloxane polymerization assets commanding superior offtake security versus merchant intermediate suppliers. The vendor base stratifies into three tiers: integrated silicone producers with backward metallurgical silicon control; regional chlorosilane specialists serving third-party formulators; and trading houses bundling logistics with purity certification. Dominant competitive moves center on continuous flow reactor technology licensing and multi-year specification-driven procurement contracts displacing spot market liquidity.
Within the integrated producer tier, Shin-Etsu Chemical Co., Ltd. and Wacker Chemie AG exemplify archetypes of vertical manufacturing control, while Dow Chemical Company occupies a position representing North American feedstock network consolidation. China National Bluestar (Group) Co., Ltd. anchors the Asia-Pacific supply base alongside domestic capacity expansion. These entities sit within a structure where metallurgical silicon sourcing security and captive polymerization throughput determine competitive positioning more than intermediate trading scale.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Elkem ASA |
| Dow Chemical Company |
| Merck KGaA |
| Momentive Performance Materials |
| Shin-Etsu Chemical Co., Ltd. |
| Gelest Inc. |
| China National Bluestar (Group) Co., Ltd. |
| Wacker Chemie AG |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed producers in China and family-controlled German chemical conglomerates anchor supply discipline through captive metallurgical silicon sourcing and long-term offtake contracting. This ownership pattern insulates integrated players from spot volatility while compressing margins for merchant traders lacking backward control over silicon metal and copper catalyst inputs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs commercial transactions. Price differentiation hinges on electronics-grade purity certification and bundled logistics services versus commodity spot delivery. Cost compression in standard-grade tiers is intensifying because China's Yangtze River Delta capacity expansion floods lower-specification segments. Chemical manufacturers with captive polymerization assets exhibit lowest price sensitivity; independent formulators purchasing spot volumes face acute margin pressure.
Supply Chain Analysis
Tank-car freight economics and ISO-tank intermodal costs structure procurement decisions across North American and European chemical corridors. Supply concentrates in Germany, Japan, and China, with captive siloxane operations at Burghausen and Niigata limiting third-party spot liquidity. The chain draws from metallurgical silicon, methyl chloride, and copper catalyst feedstocks. Single-source vulnerability pervades electronics-grade segments where Shin-Etsu and Wacker control qualified supply. Distribution runs through dedicated tank-farm terminals with purity certification documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA Clean Air Act enforcement timelines and REACH dossier completion deadlines synchronize procurement qualification cycles with compliance-driven demand spikes.
For Market Incumbents: Acquire continuous flow reactor technology assets to defend yield advantages against emerging Chinese producers scaling conventional stirred-tank capacity. Consolidate metallurgical silicon sourcing through long-term power purchase agreements with smelters in hydroelectric-rich geographies. Fluorosilicone substitution in aerospace seals threatens conventional silicone margins above 200°C thresholds. For New Entrants and Emerging Players: Capture India's specialty silicone formulation segment as PLI scheme incentives for electronics manufacturing create downstream demand for imported chlorosilane intermediates. Target pharmaceutical-grade silicone opportunities where healthcare traceability requirements favor new entrants with clean documentation systems. Partner with certified tank-farm operators to bypass MEE hazardous chemical storage compliance barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional chlorosilane specialists lacking captive siloxane polymerization assets. Five-to-ten-year viability favors backward-integrated producers with metallurgical silicon control. Monitor EPA closed-loop sampling infrastructure compliance deadlines as inflection indicator for facility upgrade capital requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallurgical Silicon | Secures feedstock cost stability against electricity price volatility in smelter operations. |
| Continuous Flow Reactor Deployment | Shin-Etsu and Wacker pilots demonstrate yield improvements that compress batch-to-batch variation. |
| Electronics-Grade Purity Certification Investment | Qualifies supply for semiconductor conformal coating specifications from Tesla and Rivian. |
| Long-Term Supply Agreement Structuring | Bundles purity certification with dedicated tank-car logistics to displace spot market liquidity. |
| Joint Venture in India Specialty Formulation | Leverages PLI scheme incentives to capture downstream silicone polymerization demand. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region synthesized through structured interviews. Plant managers at integrated chlorosilane facilities, procurement leads at downstream silicone formulators, distribution channel partners operating tank-farm terminals, and technical R&D directors at catalyst suppliers provided operational data. Secondary validation drew from EPA enforcement databases, ECHA REACH registration filings, SEC 10-K disclosures from listed chemical producers, and customs trade statistics. Bottom-up capacity modeling triangulated against top-down demand aggregation from end-use industries.
Granularity-level modeling distinguished silicone production, coatings, adhesives, and sealants by purity grade tier and end-use industry across the projection horizon. Electronics-grade versus standard industrial specifications, liquid versus gas phase handling formats, and captive versus merchant supply structures segmented volume and value outputs. CAGRs derived from production capacity expansion timelines correlated with semiconductor fabrication node advancement and automotive thermal interface material adoption curves. Metallurgical silicon price elasticity and electricity cost trajectories in key smelter regions informed input cost assumptions.
Underlying measurement precision varies by segment; electronics-grade purity tiers carry tighter precision than commodity industrial grades due to documented qualification protocols. Forecasts reflect assumptions about regulatory enforcement timelines, technology adoption rates, and feedstock cost trajectories that could shift with energy policy changes or substitution material breakthroughs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Isooctyl Alcohol Market
Chemicals
Hexamethylenetetramine (HMTA) Market
Chemicals
Canada Methanol Market
Chemicals
Laboratory Chemical Reagents Market
Chemicals
Phenylethyl Market
Chemicals
Household Insecticides Market
Chemicals
Global Aluminum Hydroxide Market
Chemicals
Hydroxyzine Imine Market
Chemicals
Butylated Triphenyl Phosphate Market
Chemicals
Metal Finishing Chemicals Market
Chemicals
Cupric Chloride Market
Chemicals
1,3-Dibromoadamantane Market
Chemicals
Flame Retardants Chemicals Market
Chemicals
Fluorochemicals Market
Chemicals
Nonaisoprenol Market
Chemicals
Sodium Cyanide Market