
 Global Recovered Carbon Black Market | 2026-2036
Global Recovered Carbon Black Market Size, Share, and Industry Trends Forecast 2026-2036
Global Recovered Carbon Black Market Intelligence
Procurement power within the tire manufacturing sector is consolidating around a few large-volume purchasers seeking consistent, high-grade rCB. This shift favors suppliers with scalable production. Cabot Corporation leverages its established global distribution network to serve these key accounts. Meanwhile, Scandinavian Enviro Systems AB differentiates through its patented pyrolysis technology, and Bolder Industries specializes in creating specific rCB grades for non-tire applications.
Recovered Carbon Black is a material reclaimed from the thermal decomposition of end-of-life tires through pyrolysis. Its performance characteristics, such as particle size and ash content, determine its suitability as a reinforcing agent in rubber and plastic compounds. The primary application remains tire manufacturing, which consumes the largest volume of rCB. In terms of product type, pellet forms offer superior handling and dispersion properties compared to powder, commanding a premium in plastic reinforcement applications.
The market's trajectory is heavily influenced by circular economy mandates and chemical safety rules. Regulations such as the EU's REACH and the US EPA's oversight on waste-derived materials set critical quality and safety benchmarks for rCB producers. These frameworks directly incentivize the substitution of virgin carbon black in industrial goods. The key decision for producers now revolves around achieving consistent quality at scale to meet the specifications of demanding end-users.
Market Dynamics
The push to standardize material quality from variable end-of-life tire feedstock is the central force shaping the recovered carbon black market. Pyrolysis technology must consistently meet the stringent performance demands of industrial end-users.
Growth Catalysts
- Circular Economy Mandates:The EU Green Deal compels tire and rubber manufacturers to use more recycled content, stimulating demand for rCB as a substitute for virgin materials.
- Automotive Sector Demand:Tire manufacturers are actively seeking sustainable material inputs to reduce the carbon footprint of their products, making rCB a preferred reinforcing agent.
- Pyrolysis Technology Advancement:Continuous improvements in reactor design and process control are enhancing the quality and consistency of rCB, making it suitable for more demanding applications.
Market Restraints
- Material Inconsistency:Batch-to-batch variations in key properties like particle size, surface area, and ash content remain a significant technical barrier to adoption in high-performance applications.
- Feedstock Fragmentation:The dispersed and inconsistent supply of end-of-life tires creates logistical hurdles and cost inefficiencies for producers trying to operate pyrolysis plants at industrial scale.
- High Capital Costs:The substantial upfront investment required to construct and commission industrial-grade pyrolysis facilities presents a major financial barrier for new entrants and capacity expansion.
Strategic Opportunities
- Specialty Applications:Developing specific rCB grades for non-tire rubber goods like industrial hoses and belts opens a high-margin market segment less sensitive to virgin carbon black pricing.
- Geographic Expansion:Industrializing economies in Southeast Asia and Latin America represent underpenetrated markets where new recycling mandates could accelerate rCB adoption.
- Regulatory Incentives:Policy mechanisms, such as those within the US IRA that favor recycled content, create direct financial incentives for manufacturers to substitute virgin materials with rCB.
Industry Challenges
- Standardization Deficit:The absence of global ASTM or ISO standards for rCB creates purchasing friction, as buyers cannot easily compare products, slowing widespread adoption.
- Talent Scarcity:A shortage of chemical engineers and plant operators with specialized expertise in pyrolysis and material characterization for rCB limits operational excellence and innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Recovered Carbon Black Market |
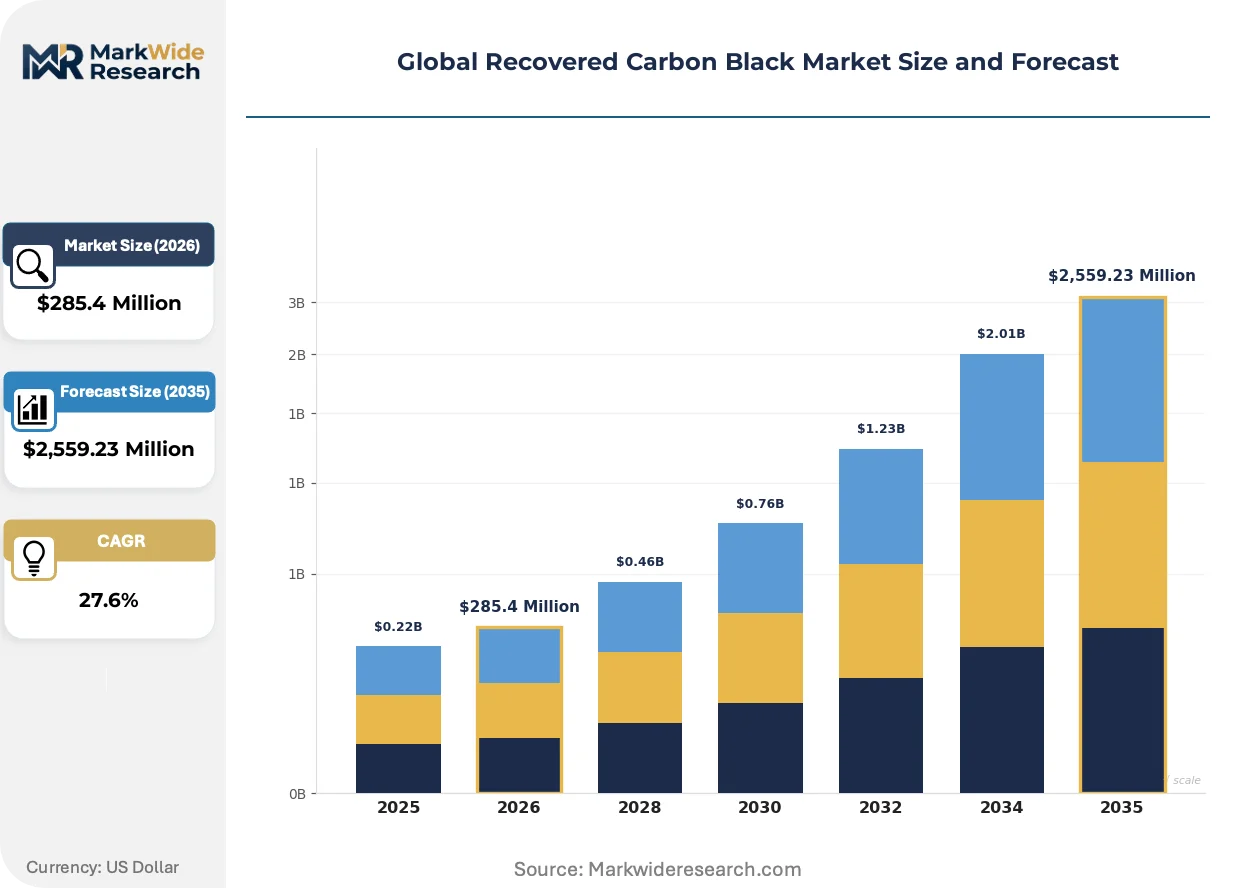
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $2,559.23 Million |
| CAGR (2026 – 2036) | 27.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Pellet, Paste, Extruded, Modified Application: Tire Manufacturing, Ink Production, Paints Coatings, Plastic Reinforcement, Textile Pigmentation Technology: Pyrolysis, Thermal Recovery, Chemical Recovery, Hydrocarbon Thermal, Furnace Process End User Industry: Tire Makers, Ink Manufacturers, Paint Producers, Plastic Processors, Textile Fabricators |
| Companies Covered | Pyrum Innovations, Cabot Corporation, Scandinavian Enviro Systems AB, Gravita India Limited, Tokai Carbon Co., Ltd., Bolder Industries, Klean Industries, Mitsubishi Chemical Corporation, Black Bear Carbon B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Recovered Carbon Black Market Strategic Shifts & Innovations
Maturation of pyrolysis technology and intensifying regulatory pressures are transforming the market. Recovered carbon black is shifting from a niche recycling output into a specified industrial material, creating new supply chain dynamics and performance benchmarks.
Advanced pyrolysis combined with post-treatment refining removes impurities like silica and ash from the recovered material. High-performance plastics compounders and specialty coatings formulators are adopting these purified rCB grades. This improved material consistency is expanding into demanding applications previously reserved for semi-reinforcing virgin carbon black.
The EU’s REACH regulation imposes strict chemical safety and registration requirements on substances derived from waste streams. This policy forces rCB producers to conduct extensive testing, increasing compliance costs but also validating material safety for buyers. The European tire and technical rubber goods sectors are most affected, now making REACH compliance a non-negotiable term for new supply contracts.
A significant behavioral shift involves the move toward long-term offtake agreements between rCB producers and large-volume buyers. This replaces the older model of opportunistic spot purchasing, as tire manufacturers seek to secure stable supply lines. This trend is most prominent in North America and Europe, where automotive sustainability mandates are driving procurement strategies.
Global Recovered Carbon Black Market Segmentation
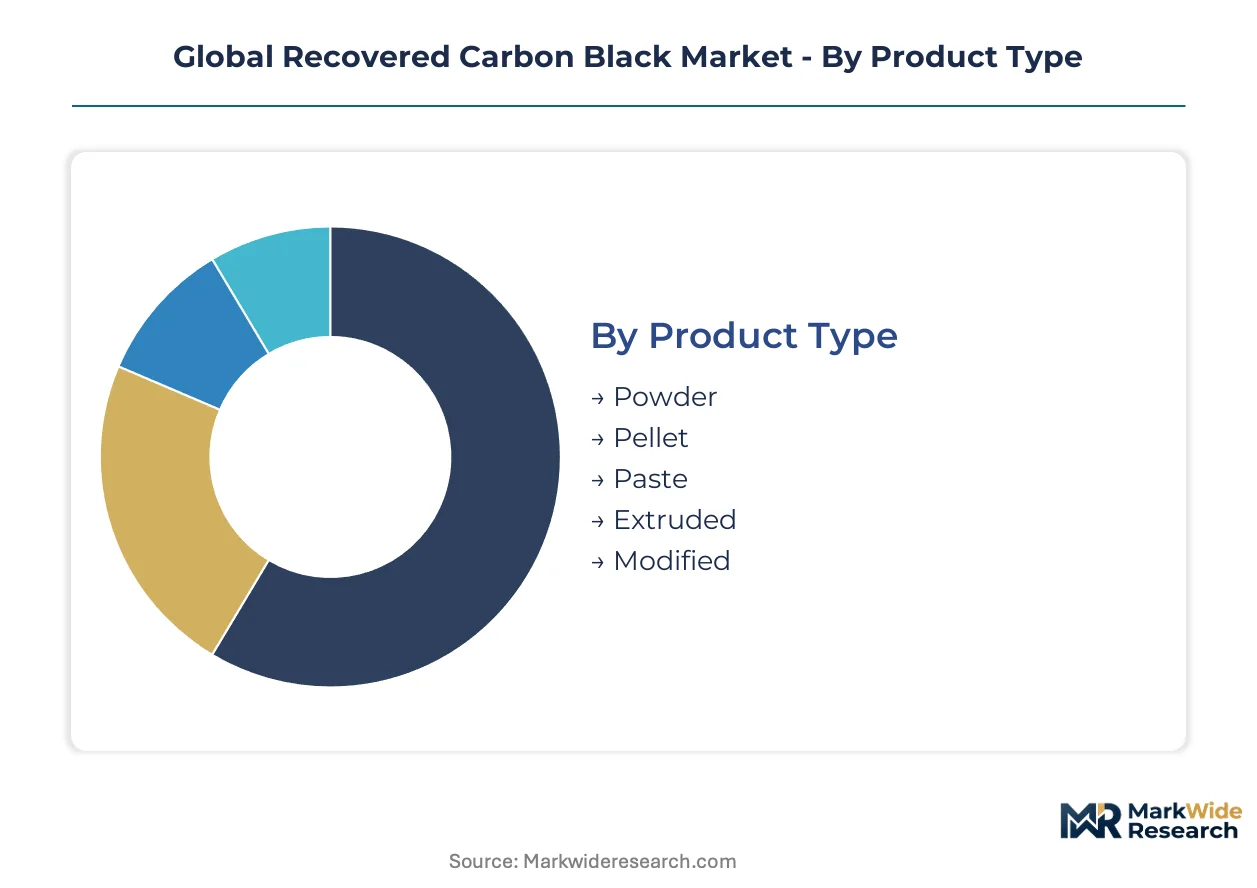
The segmentation of the global recovered carbon black market provides a granular view of the supply and demand dynamics across distinct product forms, end-use applications, and processing technologies. Understanding these divisions helps stakeholders identify key value pools and strategic growth areas within the circular economy framework.
Product Type:
The physical form and processing specifications of recovered carbon black significantly influence its suitability for various industrial applications.
- Pellet:This product type consists of densified rCB particles, offering superior handling characteristics, reduced dusting, and improved dispersion properties in rubber and plastic compounds. Demand for pellets is concentrating in plastic reinforcement applications, where consistent dispersion enhances material performance.
- Powder:Representing the fundamental form of rCB, powder offers a high surface area suitable for various compounding needs, but presents challenges in handling and dispersion. Its demand remains strong in tire manufacturing and ink production, where its reinforcing and pigmentation properties are critical.
- Paste:Recovered carbon black paste integrates rCB into a liquid carrier, facilitating easier incorporation into certain formulations, particularly in specialized coatings.
- Extruded:Extruded rCB undergoes a process that compacts the material into a specific shape, often improving flow characteristics for continuous manufacturing processes.
- Modified:Modified rCB involves surface treatment or chemical alteration to enhance specific properties like compatibility with polymers or electrical conductivity for advanced applications.
Mature deployment sits with Powder. Newer deployment is concentrated in Pellet.
Application:
Application segmentation highlights the primary demand centers for recovered carbon black, reflecting varying volume requirements across industries.
- Tire Manufacturing:This application segment utilizes rCB as a reinforcing filler in rubber compounds for new tire production, reducing reliance on virgin carbon black. The global automotive sector's sustainability mandates are driving this substantial demand.
- Plastic Reinforcement:Recovered carbon black improves the mechanical strength, UV resistance, and pigmentation of plastic compounds, broadening their application in various goods. Demand for rCB in plastic reinforcement is concentrating in automotive interiors and consumer durable goods due to circular economy goals.
- Ink Production:rCB serves as a crucial pigment in various printing inks, providing deep black coloration and opacity for packaging and publication applications.
- Paints Coatings:In paints and coatings, rCB provides pigmentation, UV protection, and conductivity, enhancing the durability and aesthetic appeal of finished surfaces.
- Textile Pigmentation:rCB is employed for coloring textile fibers and fabrics, offering a cost-effective and sustainable alternative for black pigmentation in the textile industry.
Tire Manufacturing remains the largest application, while Plastic Reinforcement represents the fastest-growing trajectory.
Technology:
The maturity and efficiency of processing technologies are critical in determining the quality and consistency of recovered carbon black output.
- Pyrolysis:This thermal decomposition process separates end-of-life tires into recovered carbon black, oil, and gas in an oxygen-free environment. Pyrolysis technology is central to rCB production, with significant investments in Europe and North America to enhance material quality.
- Thermal Recovery:Thermal recovery methods apply high temperatures to reclaim carbon black from waste materials, often encompassing pyrolysis as a primary technique. This technology is widely adopted in tire recycling facilities, driven by efficiency in material yield.
- Chemical Recovery:Chemical recovery processes utilize solvents or reagents to extract carbon black from composite materials, potentially yielding purer rCB grades.
- Hydrocarbon Thermal:This technology variant focuses on the thermal breakdown of hydrocarbon-rich waste streams, including tires, to recover carbon black and other valuable components.
- Furnace Process:The furnace process typically refers to the traditional method of producing virgin carbon black, but adapted versions can be used for post-treatment or specific rCB refinement.
Pyrolysis technology is widely adopted, with Chemical Recovery methods gaining traction for specialized material properties.
End User Industry:
End-user industries dictate specific quality parameters and procurement volumes, shaping the supply chain dynamics for recovered carbon black.
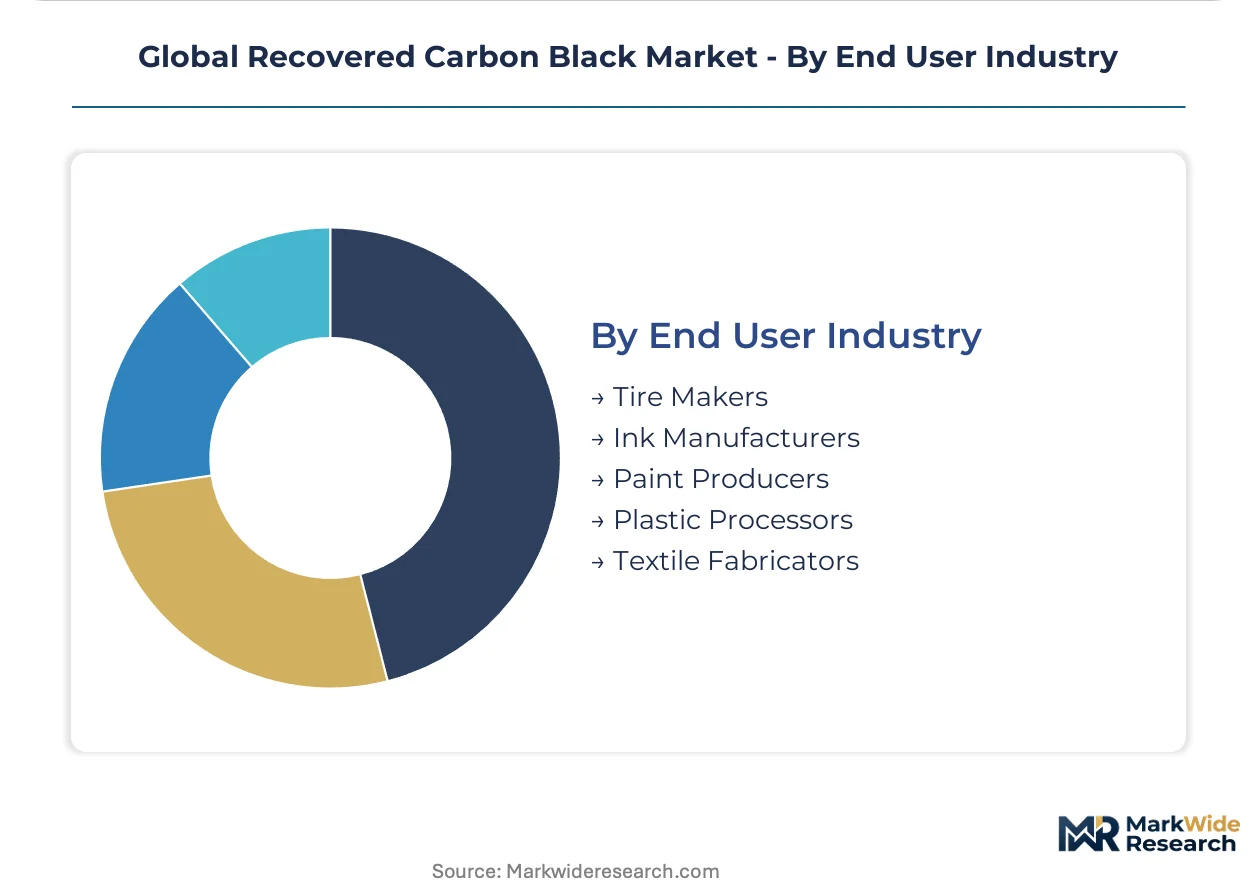
- Tire Makers:These manufacturers integrate rCB directly into their rubber formulations for new tire production, driven by regulatory mandates like the EU Green Deal and corporate sustainability targets. Tire makers represent the largest volume purchasers globally.
- Plastic Processors:Plastic processors use rCB for pigmentation, UV stabilization, and to enhance the mechanical and electrical properties of various plastic products. Demand from plastic processors demonstrates a strong expansion in automotive and consumer electronics sectors.
- Ink Manufacturers:Ink manufacturers procure rCB as a primary pigment to produce black printing inks for diverse applications, including packaging and graphic arts.
- Paint Producers:Paint producers utilize rCB to formulate black paints and coatings, valuing its color intensity, UV protection, and cost-effectiveness.
- Textile Fabricators:Textile fabricators incorporate rCB for coloring fibers and fabrics, seeking sustainable and durable black pigments for apparel and industrial textiles.
Tire Makers are the dominant end-users, with Plastic Processors demonstrating a strong expansion in demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for recovered carbon black is concentrating in industrial centers across developed economies. Tire manufacturers in these regions prioritize sustainable materials, driven by circular economy mandates. This focus on green procurement is reshaping supply chain dynamics.
United States
The United States sees strong demand for rCB from its automotive sector and plastic processors. The US IRA provides significant incentives for manufacturers to use recycled content. Industrial hubs in the Midwest, particularly around Detroit, are integrating rCB into new vehicle components.
Germany
Germany's robust tire manufacturing and specialty coatings industries create substantial demand for high-grade rCB. The EU Green Deal and REACH regulations compel German companies to prioritize recycled materials and ensure chemical safety. The Rhine-Ruhr region, a major chemical and rubber hub, is a focal point for rCB production and adoption.
China
China's vast tire production sector and expanding plastic reinforcement applications drive significant rCB consumption. The country's dual carbon goals and evolving GB standards for recycled content accelerate adoption rates. Manufacturing centers in the Yangtze River Delta are actively scaling rCB integration into diverse industrial goods.
India
India's rapidly expanding automotive industry and textile sector are increasing their demand for sustainable rCB inputs. The PLI scheme encourages domestic manufacturing, including recycled material usage, while BIS standards define quality. Maharashtra, with its prominent automotive and textile production, is witnessing rising rCB procurement.
Brazil
Brazilian tire manufacturers and producers of industrial rubber goods show a growing interest in rCB for cost and sustainability benefits. ANVISA regulations and national environmental policies are gradually promoting the use of recycled content. São Paulo, a key automotive and rubber industry hub, is exploring greater rCB integration.
Global Recovered Carbon Black Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized rCB grades for high-performance applications. The market structure is evolving from fragmented local players to an increasingly consolidated tier of industrial-scale suppliers. Strategic partnerships between rCB producers and large tire manufacturers are common. Capacity expansion and technology licensing are dominant competitive moves.
Within the technology-differentiated tier, Scandinavian Enviro Systems AB exemplifies innovation through its patented pyrolysis technology, focusing on consistent material quality. Cabot Corporation leverages its established global distribution network to serve key accounts, representing the established large-volume supplier archetype. Pyrum Innovations occupies a position focused on industrial-scale pyrolysis solutions, emphasizing operational efficiency and scalability. These players anchor the market's shift towards consistent, high-grade recovered carbon black, meeting the stringent performance demands of industrial end-users. Their distinct approaches highlight the diverse strategies employed to capture market share.
| Leading Market Players |
|---|
| Pyrum Innovations |
| Cabot Corporation |
| Scandinavian Enviro Systems AB |
| Gravita India Limited |
| Tokai Carbon Co., Ltd. |
| Bolder Industries |
| Klean Industries |
| Mitsubishi Chemical Corporation |
| Black Bear Carbon B.V. |
| Others |
Cost & Logistics Intelligence
Circular economy mandates and automotive sustainability goals are compelling tire manufacturers to increase recycled content, which demands consistent rCB supply and influences pricing power across the value chain.
Pricing Analysis
The market exhibits a volume-versus-margin split, with large-volume tire applications commanding lower per-unit pricing compared to specialized non-tire grades. Contract-based long-term offtake agreements dominate for established suppliers, providing stability for both producers and large buyers. Price differentiation stems from material quality, particularly particle size and ash content, and adherence to chemical safety regulations like EU REACH. Pricing softness for standard rCB reflects ongoing feedstock inconsistency, while specialty grades maintain premium-mid-economy pricing differentiation. Tire makers remain highly price-sensitive, whereas high-performance plastics compounders prioritize consistent quality over marginal cost savings.
Supply Chain Analysis
Logistics and freight costs significantly influence regional rCB pricing, particularly given the dispersed nature of end-of-life tire collection. Supply concentration for recovered carbon black production is emerging in industrial hubs across Germany, the United States, and China. The supply chain relies heavily on end-of-life tires as the primary raw material, which presents a structural feedstock fragmentation risk due to inconsistent collection infrastructure. Distribution runs primarily through direct sales channels to large industrial end-users, facilitated by long-term strategic partnerships between rCB producers and major manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The recovered carbon black market is undergoing a technology-transition phase, with advanced pyrolysis solutions displacing traditional waste disposal methods for end-of-life tires.
For Market Incumbents:Deploy capacity expansion in strategic geographies like the US Midwest and Germany's Rhine-Ruhr region to meet consolidating procurement demand. Invest in advanced pyrolysis technology and post-treatment refining to improve material consistency and broaden application suitability. Secure long-term feedstock supply agreements to mitigate feedstock fragmentation risks. Pursue certifications like REACH compliance to reinforce market position against emerging entrants.
For New Entrants and Emerging Players:Enter via specialized applications such as non-tire rubber goods or high-performance plastics, targeting segments less sensitive to virgin carbon black pricing. Focus on developing specific rCB grades with enhanced properties like electrical conductivity or UV resistance. Geographic expansion into underpenetrated markets like Southeast Asia offers significant white-space opportunities. Leverage patented pyrolysis technology to differentiate on consistent quality and tailored material specifications.
For Investors and Strategic Acquirers:The window for entry favors patient capital seeking long-term growth driven by circular economy mandates and automotive sector sustainability goals. Target industrial-scale rCB producers with proven pyrolysis technology and established long-term offtake agreements with major tire manufacturers. Focus on companies demonstrating consistent quality output and a clear path to achieving global ASTM or ISO standardization. The signal to watch is the successful development and widespread adoption of global quality standards for recovered carbon black.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Europe | Increases supply of rCB to meet EU Green Deal mandates from tire and rubber manufacturers. |
| Advanced Pyrolysis R&D | Enhances rCB quality and consistency, expanding its suitability for demanding applications. |
| Long-Term Offtake Agreements | Secures stable demand for rCB producers and guarantees supply for major industrial buyers. |
| Specialty Grade Development | Unlocks high-margin non-tire markets and reduces reliance on virgin carbon black pricing. |
| REACH Compliance Investment | Validates material safety for European buyers and becomes a non-negotiable term for new contracts. |
Research Approach
EU Green Deal documents, US EPA reports, and company annual reports formed the secondary backbone, complemented by primary interviews with rCB producers, tire manufacturers, plastic processors, and chemical engineers. This approach combined bottom-up market sizing with top-down validation, ensuring comprehensive data triangulation. Customs and trade data also provided crucial insights into regional supply flows and demand patterns.
A bottom-up analytical lens was applied to quantify market segments by product type, application, technology, end-user industry, and geographic region over the projection horizon. CAGRs were derived from historical growth analysis and future market drivers, including end-of-life tire generation rates and pyrolysis technology adoption curves. The framework also incorporated regulatory incentive impacts and material substitution trends across various industrial sectors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of rapid regulatory change or significant feedstock supply disruptions. Forecasts reflect assumptions regarding technological advancements and market acceptance of rCB as a virgin carbon black substitute. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Alunite Market
Bulk Chemicals
Rubidium Bromide Market
Bulk Chemicals
North America Malic Acid Market
Bulk Chemicals
Powdered Cellulose Market
Bulk Chemicals
LAMEA Glacial Acrylic Acid Market
Bulk Chemicals
Malathion Market
Bulk Chemicals
Sulfur Market
Bulk Chemicals
Sodium Sulfide Market
Bulk Chemicals
Global Plastics Market
Bulk Chemicals
Sodium Hydrogen Sulphite Market
Bulk Chemicals
Sodium Bromate Market
Bulk Chemicals
Barium Sulfite Market
Bulk Chemicals
North America Glycerol Market
Bulk Chemicals
United Kingdom Lime Market
Bulk Chemicals
Glucaric Acid Market
Bulk Chemicals
Potassium Carbonate Market