
 Organic Peroxide Market | 2026-2036
Organic Peroxide Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Peroxide Market Intelligence
Specialty chemical distribution is reconfiguring as regional compliance requirements multiply and buyer consolidation intensifies. NOF Corporation leverages captive production networks across Asia-Pacific to sustain supply security for radical initiator grades. Arkema S.A. dominates European distribution through integrated logistics platforms that bypass traditional wholesale layers. Pergan GmbH specializes in temperature-controlled last-mile delivery systems for peroxide formulations.
Organic peroxides are thermally labile compounds containing a peroxide functional group (R-O-O-R') that decomposes to generate free radicals, typically manufactured through controlled oxidation of alcohols or ketones under precise temperature and pressure parameters. Their primary commercial purpose centers on initiating polymerization reactions and cross-linking elastomers. Dibenzoyl peroxide leads product type revenue due to established use in acrylic polymerization, while methyl ethyl ketone peroxide captures expanding share in unsaturated polyester curing for marine and construction composites. Polymerization applications command the largest application segment as thermoplastics capacity expands, though curing agent formulations retain premium margin pools in aerospace-grade rubber specifications.
REACH registration requirements in Europe, OSHA Process Safety Management standards in the United States, and China's GB standards under SAMR oversight collectively mandate rigorous thermal stability testing and hazard classification documentation for commercial organic peroxide shipments. These frameworks elevate compliance costs for smaller distributors while creating structural advantages for integrated manufacturers with in-house regulatory affairs capabilities. Stakeholders must monitor evolving transport classification protocols and assess backward integration into precursor alcohol feedstocks as volatility buffers.
Market Dynamics
Polymerization-grade organic peroxide supply chains are compressing as integrated manufacturers bypass wholesale intermediaries to capture margin pools previously absorbed by distributors handling temperature-controlled logistics and REACH documentation.
Growth Catalysts
- REACH Registration Mandates:European ECHA compliance requirements for thermal stability documentation are eliminating non-specialized traders and concentrating procurement with certified suppliers capable of in-house hazard classification testing.
- Marine Composite Fabrication:Unsaturated polyester curing for wind turbine blades and yacht hulls is pulling methyl ethyl ketone peroxide demand along China's eastern seaboard manufacturing clusters.
- Acrylic Polymerization:Dibenzoyl peroxide consumption in PMMA and acrylic sheet production is accelerating with automotive lightweighting specifications across German and Japanese tier-one supplier networks.
Market Restraints
- Acetone Feedstock Volatility:Ketone precursor costs fluctuate with propylene derivative markets, compressing formulation margins for non-integrated peroxide manufacturers lacking captive alcohol oxidation capacity.
- China Supply Concentration:SAMR-licensed production capacity clusters in Jiangsu and Shandong provinces, creating single-geography dependency risks for international buyers sourcing radical initiator grades.
- Photoinitiator Substitution:UV-curable epoxy and acrylate systems are displacing thermal peroxide initiation in certain coating applications, particularly in electronics potting and optical fiber manufacturing.
Strategic Opportunities
- India Chemical Processing Corridor:Dahej and Mundra port zones offer underpenetrated demand for cross-linking peroxides as domestic rubber and plastics compounding capacity expands under PLI scheme incentives.
- Aerospace Elastomer Specifications:Premium-grade dicumyl peroxide for fluorocarbon rubber curing commands margin premiums as FAA and EASA certification requirements tighten for sealing applications in next-generation aircraft platforms.
- Digital Hazard Documentation:Blockchain-anchored supply chain traceability systems are emerging as a channel innovation, enabling real-time thermal excursion monitoring during last-mile delivery of temperature-sensitive formulations.
Industry Challenges
- Process Safety Engineering Talent:OSHA PSM and EU Seveso III compliance requires scarce specialists in thermal runaway modeling and relief system design, constraining capacity expansion timelines for new peroxide production facilities.
- Cryogenic Storage Capex:Bulk organic peroxide warehousing demands nitrogen-inerted, refrigerated infrastructure with redundant cooling systems, elevating facility investment thresholds beyond mid-scale distributor capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Peroxide Market |
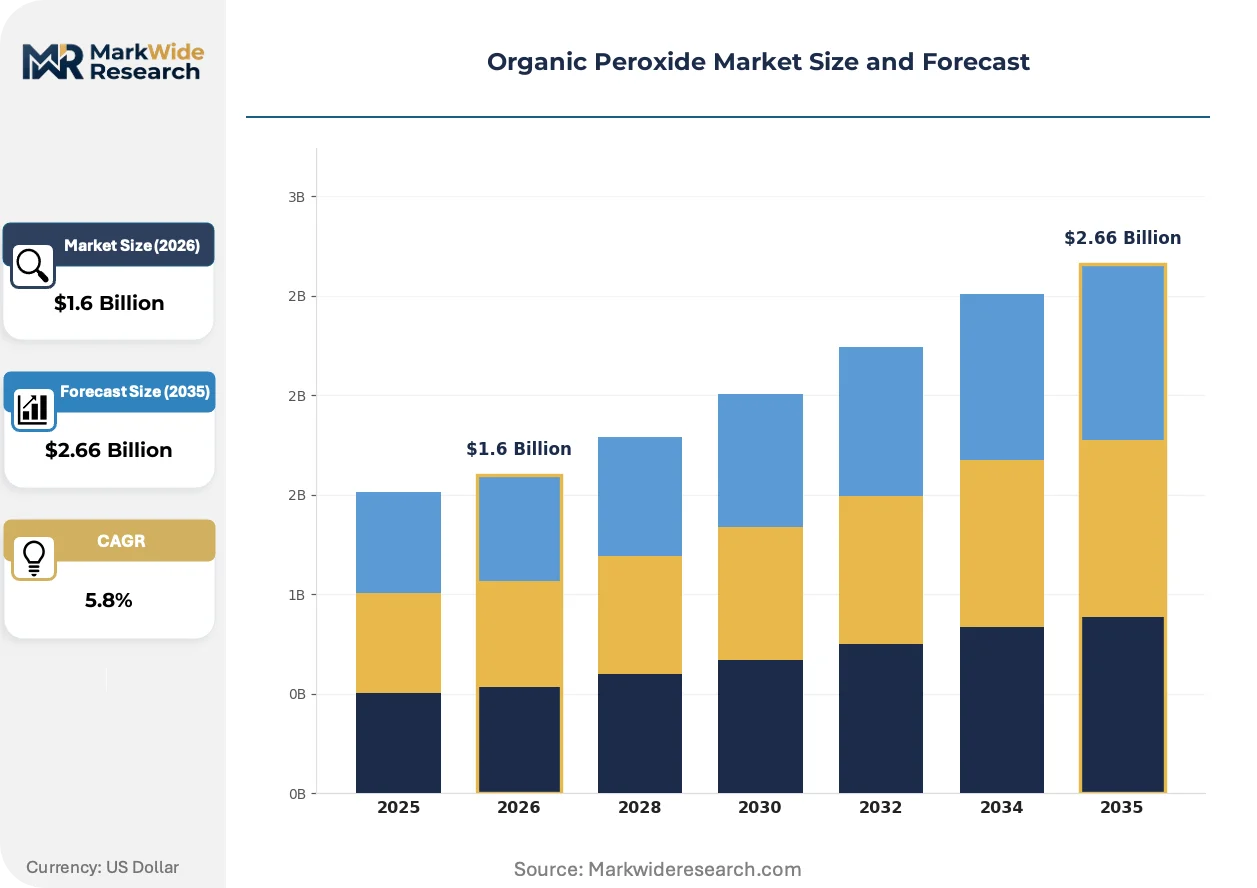
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $2.66 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dibenzoyl Peroxide, Methyl Ethyl Ketone Peroxide, Tertiary Butyl Peroxide, Acetyl Peroxide End Use Industry: Plastics, Rubber, Wood, Coatings Distribution Channel: Online, Direct Sales, Wholesalers, Retail Application: Curing Agent, Radical Initiator, Bleaching Agent, Polymerization |
| Companies Covered | NOF Corporation, Akzo Nobel N.V., Nouryon, Lanzhou Auxiliary Agent Plant Co., Ltd., Solvay SA, Arkema S.A., Pergan GmbH, Chinasun Specialty Products Co., Ltd., United Initiators GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Peroxide Market Strategic Shifts & Innovations
Digital twin technology and predictive decomposition modeling are reconfiguring how manufacturers manage thermal stability risk across formulation, transport, and end-use application stages.
Computational chemistry platforms are virtualizing traditional empirical testing protocols for peroxide shelf-life validation. Arkema and Nippon Oil & Fats are deploying molecular dynamics simulation to predict radical generation kinetics under variable temperature profiles, compressing new product qualification cycles from months to weeks. This capability is virtualizing the competitive advantage of legacy manufacturers with decades of empirical formulation databases.
ECHA's 2023 update to REACH Annex VIII classification criteria for organic peroxides is mandating additional adiabatic calorimetry data for transport authorization. The regulation is forcing reformulation of several diaryl peroxide grades previously grandfathered under older hazard profiles, with German and Benelux chemical distributors absorbing compliance documentation costs to maintain UN-certified shipping permissions. Affected product categories include paste and liquid formulations above 35% active oxygen content.
Specification-driven procurement is consolidating buyer power among multinational polymer producers. BASF and LyondellBasell are unbundling peroxide supply from general chemical distribution contracts, establishing direct technical service relationships with initiator manufacturers for just-in-time delivery to polymerization reactors. This pattern is most visible in Texas and Louisiana petrochemical corridors, where integrated producers are bypassing regional distributors to secure batch-traceable radical initiator supply with embedded thermal stability guarantees.
Organic Peroxide Market Segmentation
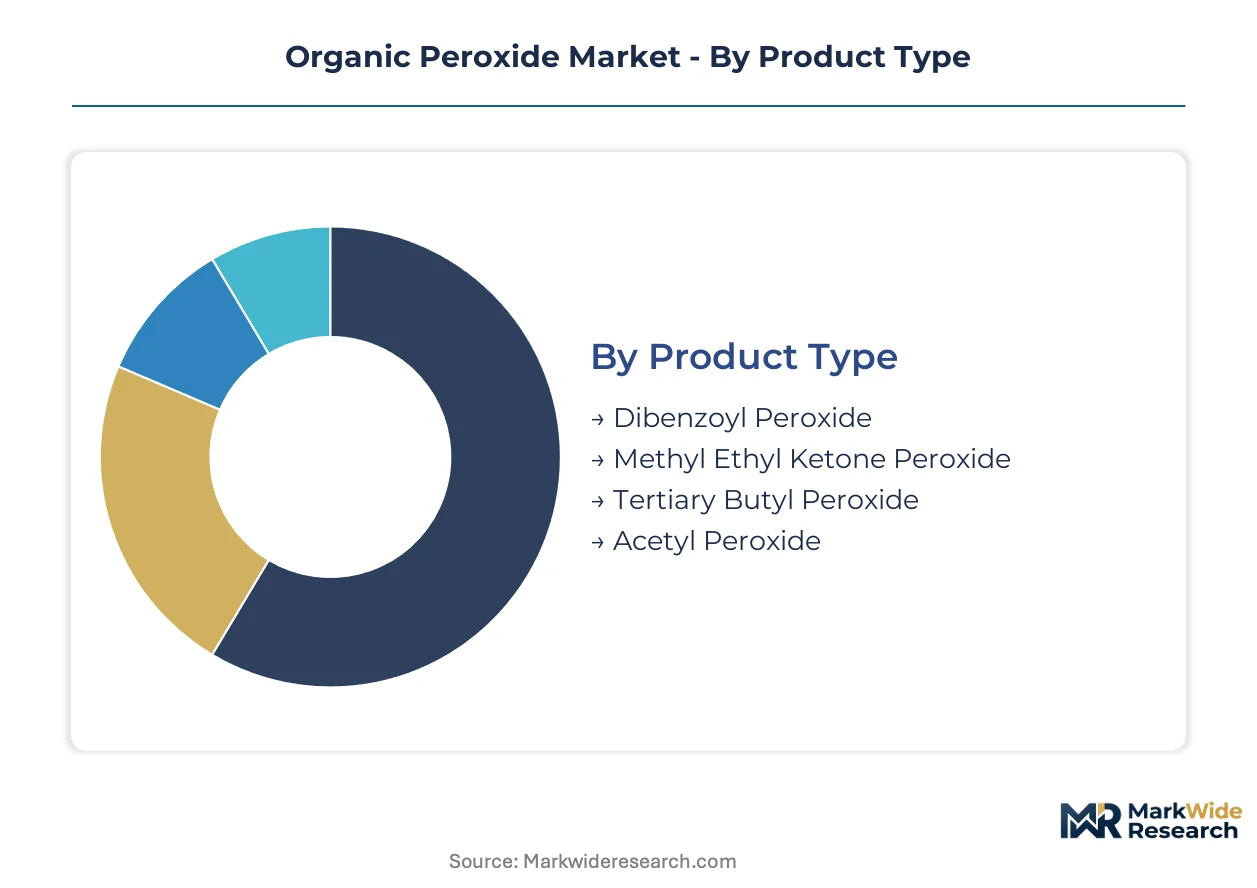
Organic peroxide segmentation reflects divergent maturity curves across product chemistries and end-use specifications. Thermal stability requirements and regulatory documentation burdens reshape competitive boundaries within each category.
Product Type:
Mature diaryl peroxides dominate revenue pools while emerging ketone-based formulations capture growth in specialized curing applications.
- Dibenzoyl Peroxide:The diaryl peroxide contains two benzoyl groups attached to a peroxide bridge, manufactured through controlled oxidation of benzoyl chloride with alkaline hydrogen peroxide. Acrylic polymerization for PMMA sheet production in Germany and Japan anchors demand, with automotive lightweighting specifications tightening purity requirements for optical-grade applications.
- Methyl Ethyl Ketone Peroxide:A mixture of peroxyketals and hydroperoxides derived from methyl ethyl ketone and hydrogen peroxide, characterized by lower decomposition temperatures than diaryl alternatives. Unsaturated polyester curing for wind turbine blade fabrication along China's Jiangsu and Shandong coastlines drives volume, with marine composite specifications expanding into yacht hull manufacturing.
- Tertiary Butyl Peroxide:Alkyl peroxide with high thermal stability used in high-temperature polymerization processes.
- Acetyl Peroxide:Diacyl peroxide with high active oxygen content requiring stringent refrigerated handling protocols.
Dibenzoyl peroxide handles the majority of throughput; methyl ethyl ketone peroxide is expanding most quickly on share.
End Use Industry:
Cost tier stratification separates commodity polymer applications from premium elastomer specifications with embedded certification requirements.
- Plastics:Thermoplastic polymerization consumes the largest peroxide volumes, with specification-grade PMMA and polystyrene production requiring batch-traceable initiator supply with thermal stability guarantees.
- Rubber:Cross-linking applications for fluoroelastomer and EPDM compounds command premium margins, with FAA and EASA certification requirements for aircraft sealing applications tightening purity thresholds.
- Wood:Polymer-impregnated timber treatments utilize peroxide-initiated resin curing for dimensional stability enhancement.
- Coatings:Industrial finishes and gel-coat formulations employ peroxide curing in automotive and marine protective layers.
Plastics absorbs the highest absolute tonnage; rubber captures the steepest margin expansion trajectory.
Distribution Channel:
Channel selection correlates directly with hazard classification tier and customer technical service requirements.
- Direct Sales:Integrated manufacturers bypass wholesale layers for polymerization-grade supply to multinational producers, embedding thermal stability documentation and just-in-time delivery guarantees.
- Wholesalers:Temperature-controlled logistics specialists handle paste and liquid formulations for mid-scale compounders lacking refrigerated warehousing infrastructure.
- Online:Digital procurement platforms emerge for standardized laboratory-grade peroxides with lower active oxygen content.
- Retail:Limited to small-volume consumer epoxy and polyester repair kits through hardware channels.
Direct sales channels command the highest value throughput; online platforms are gaining share fastest among research-grade segments.
Application:
Functional differentiation separates radical generation mechanisms from oxidative bleaching chemistry in end-use specifications.
- Polymerization:Free radical initiation for vinyl monomer conversion commands the largest application segment, with batch-scale consistency requirements driving supplier consolidation among initiator manufacturers.
- Curing Agent:Cross-linking applications for thermoset resins and elastomers retain premium positioning, with aerospace-grade fluorocarbon rubber specifications mandating dicumyl peroxide purity levels.
- Radical Initiator:Specialized grades for controlled degradation and graft copolymerization in polypropylene modification.
- Bleaching Agent:Oxidative bleaching for textile and pulp applications, declining as enzymatic alternatives displace peroxide chemistry.
Polymerization handles the dominant share of volume; curing agent applications deliver the highest margin realization per kilogram.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry between Chinese manufacturing clusters and German specialty chemical corridors defines regional competitive dynamics. Jiangsu and Shandong provinces concentrate SAMR-licensed production capacity for methyl ethyl ketone peroxide, while Bavaria and North Rhine-Westphalia anchor REACH-compliant formulation and distribution networks commanding premium realizations.
China
Wind turbine blade fabrication along the Jiangsu coastline and yacht hull manufacturing in Shandong drive methyl ethyl ketone peroxide consumption. SAMR GB standards mandate thermal stability documentation for transport authorization, tightening compliance thresholds for domestic producers. Ningbo and Qingdao chemical processing zones host expanding unsaturated polyester curing operations serving marine composite exporters.
Germany
Automotive lightweighting specifications from BMW and Mercedes-Benz tier-one networks accelerate dibenzoyl peroxide demand for PMMA sheet production. ECHA REACH Annex VIII updates require adiabatic calorimetry data for diaryl peroxide transport classification, elevating documentation burdens. Ludwigshafen and Marl chemical corridors integrate polymerization-grade initiator supply with captive logistics platforms.
United States
Texas and Louisiana petrochemical corridors concentrate thermoplastic polymerization capacity from BASF and LyondellBasell operations. OSHA Process Safety Management standards enforce thermal runaway modeling requirements for peroxide storage facilities, constraining new warehouse permitting. Houston Ship Channel distribution nodes handle temperature-controlled bulk formulations for Gulf Coast polymer producers.
Japan
Optical-grade acrylic sheet production for automotive display applications tightens dibenzoyl peroxide purity specifications. METI chemical handling guidelines align with international transport classification protocols for peroxide shipments. Chiba and Yokkaichi industrial zones maintain integrated initiator manufacturing for domestic PMMA and polystyrene polymerization.
India
Dahej and Mundra port zones attract cross-linking peroxide demand as domestic rubber compounding capacity expands under PLI scheme incentives. BIS certification requirements for chemical imports create entry barriers for non-specialized traders. Gujarat chemical processing corridors develop temperature-controlled warehousing infrastructure for peroxide distribution to Maharashtra polymer converters.
Organic Peroxide Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with formulation and logistics capabilities. The vendor base compresses around integrated manufacturers with captive regulatory affairs and temperature-controlled distribution assets. Three archetypes dominate: multinational chemical conglomerates with polymerization reactor partnerships, regional specialists in hazard-classified last-mile delivery, and state-affiliated producers serving domestic industrial clusters. Competitive moves center on backward integration into precursor alcohol feedstocks and direct technical service relationships bypassing wholesale intermediaries.
Among Asia-Pacific-based producers, NOF Corporation exemplifies the integrated manufacturing archetype with captive oxidation capacity. European specialists occupy the premium distribution tier: Arkema S.A. anchors integrated logistics platforms, while Pergan GmbH represents temperature-controlled last-mile delivery capabilities. These three names illustrate how geographic origin and corporate structure map to competitive positioning in hazard-classified chemical supply chains.
| Leading Market Players |
|---|
| NOF Corporation |
| Akzo Nobel N.V. |
| Nouryon |
| Lanzhou Auxiliary Agent Plant Co., Ltd. |
| Solvay SA |
| Arkema S.A. |
| Pergan GmbH |
| Chinasun Specialty Products Co., Ltd. |
| United Initiators GmbH |
| Others |
Cost & Logistics Intelligence
Jiangsu and Shandong province production clusters anchor global methyl ethyl ketone peroxide supply, concentrating margin capture with integrated manufacturers while distributors absorb temperature-controlled logistics costs and REACH documentation burdens. This upstream geography directly dictates where pricing power accumulates downstream.
Pricing Analysis
Configured-to-order pricing for aerospace-grade dicumyl peroxide commands substantial premiums over standard polymerization grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with FAA and EASA qualification tiers separating margin pools. Pricing pressure stems from acetone feedstock volatility in ketone-based formulations, compressing margins for non-integrated producers. Commodity polymerization grades exhibit highest buyer price sensitivity; aerospace elastomer specifications show lowest sensitivity due to embedded technical service requirements.
Supply Chain Analysis
Extended payment terms from integrated manufacturers to specialty distributors are restructuring working capital requirements across the channel. Supply concentrates in China, Germany, and the United States as SAMR-licensed Jiangsu facilities, REACH-compliant Bavarian formulation sites, and OSHA-regulated Texas corridors anchor production. Raw material dependencies include benzoyl chloride, methyl ethyl ketone, and hydrogen peroxide feedstocks. Single-source vulnerability from China concentration creates contingency planning imperatives for international buyers. Distribution runs through direct manufacturer relationships for polymerization-grade supply, bypassing wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as specification-driven procurement unbundles peroxide supply from general chemical contracts, creating niche positions for hazard-classified logistics specialists and certification-focused formulators.
For Market Incumbents: Insulate margin pools by deepening backward integration into precursor alcohol oxidation capacity and embedding thermal stability guarantees into direct technical service relationships with polymer producers. Photoinitiator substitution in electronics coatings and UV-curable systems threatens thermal peroxide initiation volumes; counter through captive regulatory affairs capabilities that accelerate REACH documentation cycles for diaryl peroxide reformulation. For New Entrants and Emerging Players: Build out temperature-controlled last-mile delivery infrastructure in India's Dahej and Mundra chemical corridors, where PLI scheme incentives expand domestic rubber compounding capacity and BIS certification requirements create entry barriers for non-specialized traders. Marine composite fabrication for wind turbine blades along China's eastern seaboard offers penetrable demand; pursue direct relationships with unsaturated polyester compounders bypassing established distribution layers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional distributors possessing refrigerated warehousing networks but lacking backward integration into precursor production. Long-term viability hinges on regulatory compliance capabilities and captive oxidation capacity across the projection horizon. Monitor ECHA transport classification updates as inflection indicators; adiabatic calorimetry mandates for diaryl peroxides above 35% active oxygen content force portfolio rebalancing toward integrated manufacturers with in-house thermal stability testing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Feedstocks | Captive benzoyl chloride and methyl ethyl ketone oxidation capacity buffers acetone volatility and secures margin control. |
| Digital Hazard Documentation Systems | Blockchain-anchored thermal excursion monitoring during last-mile delivery differentiates temperature-controlled logistics specialists. |
| Aerospace Elastomer Certification Investment | FAA and EASA-qualified dicumyl peroxide production commands premium realizations in fluorocarbon rubber curing applications. |
| India Chemical Corridor Expansion | Dahej and Mundra port zone warehousing infrastructure captures PLI-driven rubber compounding demand growth. |
| Direct Technical Service Relationships | Bypassing wholesale intermediaries for just-in-time polymerization reactor supply embeds thermal stability guarantees and locks volume. |
Research Approach
A spread of perspectives from polymerization plant managers, downstream OEM procurement leads, peroxide distribution channel partners, and technical R&D directors converged on the working assumptions driving this analysis. Primary fieldwork combined with secondary validation from customs and trade data, Cefic chemical industry reports, SEC 10-K filings, and SAMR licensing databases established baseline supply and demand parameters. Bottom-up volume modeling across product chemistries and end-use specifications triangulated against top-down market sizing from production capacity assessments.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation dimensions including product type chemistry, end-use industry grade tier, application function, and regional production hub regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for capacity expansion timelines, regulatory compliance cost escalations, and substitution threat intensity. Industry-specific forecast inputs incorporated polymerization reactor buildout schedules in Texas and Louisiana corridors, wind turbine blade fabrication capacity along China's Jiangsu coastline, and automotive lightweighting specification adoption in German tier-one supplier networks.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by mid-scale distributors or rapid photoinitiator substitution acceleration in electronics applications would shift outcomes. Macroeconomic deviation in propylene derivative markets, regulatory tightening in transport classification protocols, or breakthroughs in computational chemistry shelf-life prediction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Oryzenin Market
Organic Chemicals
Cycloalkanes Market
Organic Chemicals
Organic Polysulfide Market
Organic Chemicals
2-Methylbutanoic Acid Market
Organic Chemicals
Diethyl Ketone Market
Organic Chemicals
North America Biphenyl Market
Organic Chemicals
Europe Lactic Acid Market
Organic Chemicals
Oxo Chemicals Market
Organic Chemicals
Organic Chemicals Market
Organic Chemicals
Organic Rheological Modifiers Market
Organic Chemicals
1,3-Dichloroacetone Market
Organic Chemicals
Phenolic Board Market
Organic Chemicals
Global Benzoic Acid Market
Organic Chemicals
Asia-Pacific Synthetic Camphor Market
Organic Chemicals
Cyclic Ketones Market
Organic Chemicals
Cyclohexanone Market