
 Global Intumescent Coatings Market | 2026-2036
Global Intumescent Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intumescent Coatings Market Foresight
Consolidation among construction contractors and infrastructure developers is repositioning procurement power toward fewer, larger buyers with centralized fire safety specification teams. PPG Industries leverages its architectural coatings distribution network to secure specification slots on major commercial projects. AkzoNobel sustains R&D intensity in water-based intumescent systems for European regulatory compliance. Jotun anchors its position through marine and offshore platform specialization where fireproofing overlaps with corrosion protection requirements.
Intumescent coatings are reactive polymer systems that expand into thick, thermally insulating char layers when exposed to temperatures above their activation threshold, typically forming a carbonaceous foam that insulates steel substrates from critical failure temperatures for specified durations. These formulations incorporate acid sources such as ammonium polyphosphate, carbonific agents like pentaerythritol, and blowing agents including melamine to achieve expansion ratios of 25 to 100 times original thickness. Water-based formulations lead in new construction applications where low VOC emissions align with LEED and BREEAM certification requirements, while epoxy-based systems dominate retrofit and industrial environments where solvent resistance and substrate adhesion under aggressive conditions command premium positioning. Epoxy intumescence represents the fastest-growing technology subsegment as infrastructure developers seek combined fire and corrosion protection in bridge and tunnel applications.
ASTM E119 and UL 263 testing standards in the United States, the EU Construction Products Regulation with CE marking requirements, and China's GB 14907 fire resistance standard collectively shape product development cycles and market access barriers across major demand centers. ECHA's REACH framework restricts certain halogenated flame retardant chemistries, forcing reformulation toward phosphorus-nitrogen systems that maintain performance without restricted substances. Stakeholders must monitor divergence between regional certification protocols, as testing methodology differences between ASTM char-rating criteria and European EN 13381 reaction-to-fire classifications create compliance fragmentation that favors manufacturers with multi-jurisdictional testing capabilities.
Market Dynamics
Steel-framed construction is accelerating specification of intumescent coatings as fire safety mandates harden across commercial high-rise developments, with reformulation cycles compressing as ECHA REACH restrictions and ASTM E119 protocol updates force simultaneous compliance with multiple certification regimes.
Growth Catalysts
- EU Construction Products Regulation:CE marking requirements for fire resistance ratings are mandating intumescent coating installation on structural steel across commercial buildings in Germany, France, and the Netherlands.
- Epoxy intumescence technology:Bridge and tunnel infrastructure developers are specifying dual-function coatings that combine fire protection with corrosion resistance in aggressive environments.
- China state-backed infrastructure:GB 14907 standard updates are driving specification volume in steel-framed buildings across Beijing, Shanghai, and Shenzhen metropolitan corridors.
Market Restraints
- Ammonium polyphosphate supply concentration:Acid source raw material production clusters in Chinese chemical manufacturing zones create input cost volatility and supply security exposure for Western formulators.
- REACH substance restrictions:ECHA's phased halogenated flame retardant prohibitions are forcing costly reformulation cycles that extend product development timelines by 18-24 months.
- Water-based performance ceiling:Epoxy systems retain adhesion superiority under humid curing conditions, limiting water-based penetration in marine and offshore platform applications.
Strategic Opportunities
- India infrastructure buildout:National highway expansion and metro rail construction in Mumbai, Delhi, and Bangalore are creating first-mover specification opportunities as BIS fire safety standards mature.
- Offshore wind platform fireproofing:North Sea and Baltic Sea wind farm developments require combined thermal and corrosion protection for jacket structures and substation platforms.
- LEED and BREEAM certification convergence:Low-VOC water-based formulations are capturing specification slots in premium commercial developments targeting dual green building credentials.
Industry Challenges
- Multi-jurisdictional testing capability:Manufacturers must maintain parallel certification pathways for ASTM E119 char-rating criteria and EN 13381 reaction-to-fire classifications, duplicating laboratory infrastructure.
- Application technician certification:Specified fire resistance ratings depend on spray application thickness uniformity, creating skills bottlenecks as contractor consolidation reduces specialized workforce depth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intumescent Coatings Market |
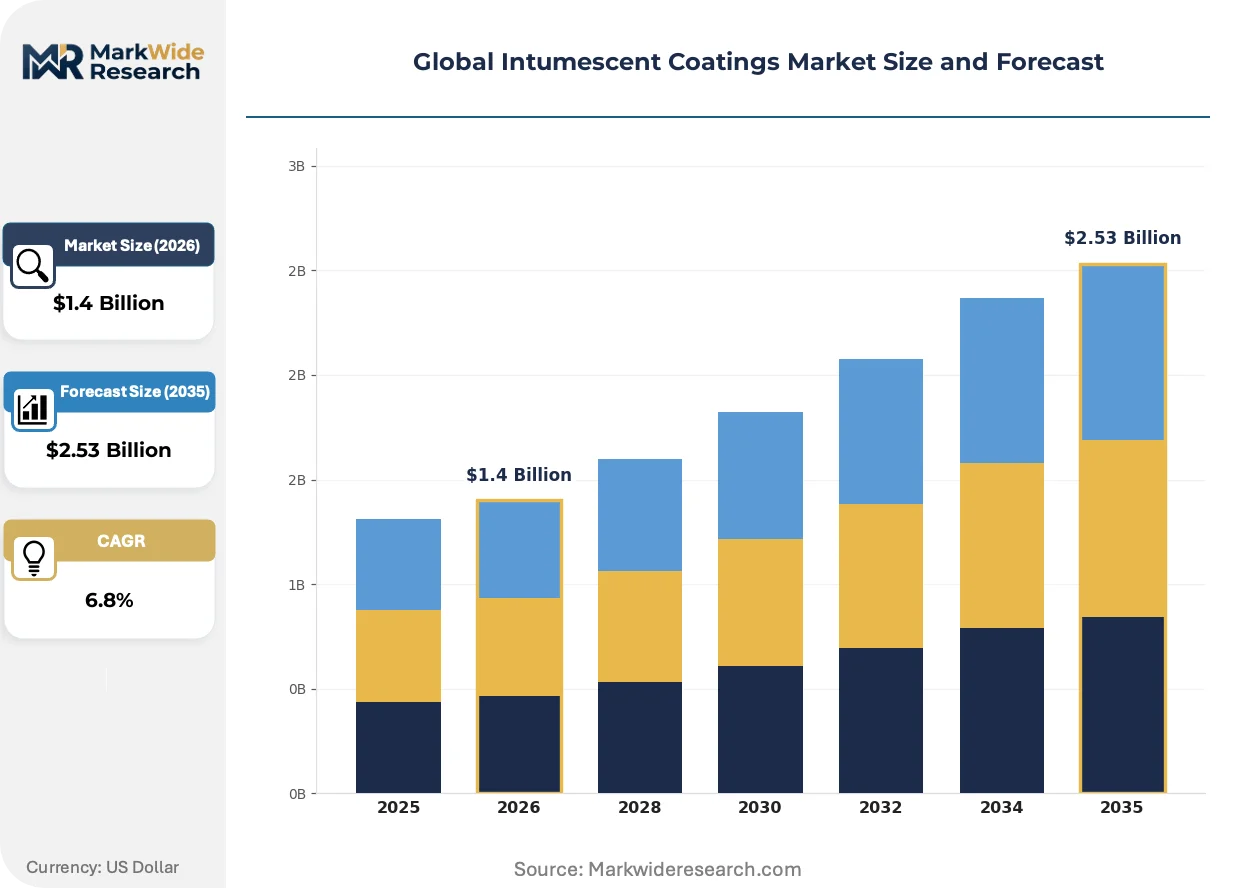
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Epoxy, Acrylic, Silicone, Polyester Application: Fireproofing, Thermal Insulation, Corrosion Protection, Soundproofing, Decorative Finishing, Surface Preparation End User: Construction Contractors, Shipbuilders, Aerospace Manufacturers, Fire Safety Consultants, Industrial Fabricators, Infrastructure Developers Technology: Intumescence, Cementitious, Hydrophobic, Cement-Modified, Self-Healing, Graphic Coatings |
| Companies Covered | AkzoNobel, PPG Industries, Sherwin-Williams, Jotun, Hempel, BASF, Sika, Kansai Paint, RPM International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intumescent Coatings Market Shifts & Advancements
Formulation chemistry and specification workflows are undergoing parallel transformation as reactive polymer systems evolve toward higher expansion ratios and digital tools compress certification timelines.
Automated thickness monitoring systems using ultrasonic and laser scanning are automating quality assurance on large-scale steel fabrication projects. Infrastructure contractors in the United States and Germany are deploying these systems to eliminate manual inspection gaps. The technology is automating compliance documentation for ASTM E119 and UL 263 testing protocols, reducing certification cycle uncertainty.
ECHA's REACH framework is systematically restricting halogenated flame retardant chemistries across European manufacturing. Formulators are pivoting toward phosphorus-nitrogen systems that maintain expansion performance without restricted substances. Water-based intumescent coatings for new construction are experiencing the most intensive reformulation pressure as CE marking deadlines approach.
Centralized fire safety specification teams at consolidated construction contractors are compressing vendor qualification cycles. Major commercial developers in China and the United Arab Emirates are consolidating procurement through approved product lists rather than project-by-project bidding. This concentration is most visible in high-rise residential and mixed-use towers across Dubai, Riyadh, and Singapore where repeatability and supply security outweigh unit cost considerations.
Global Intumescent Coatings Market Segmentation
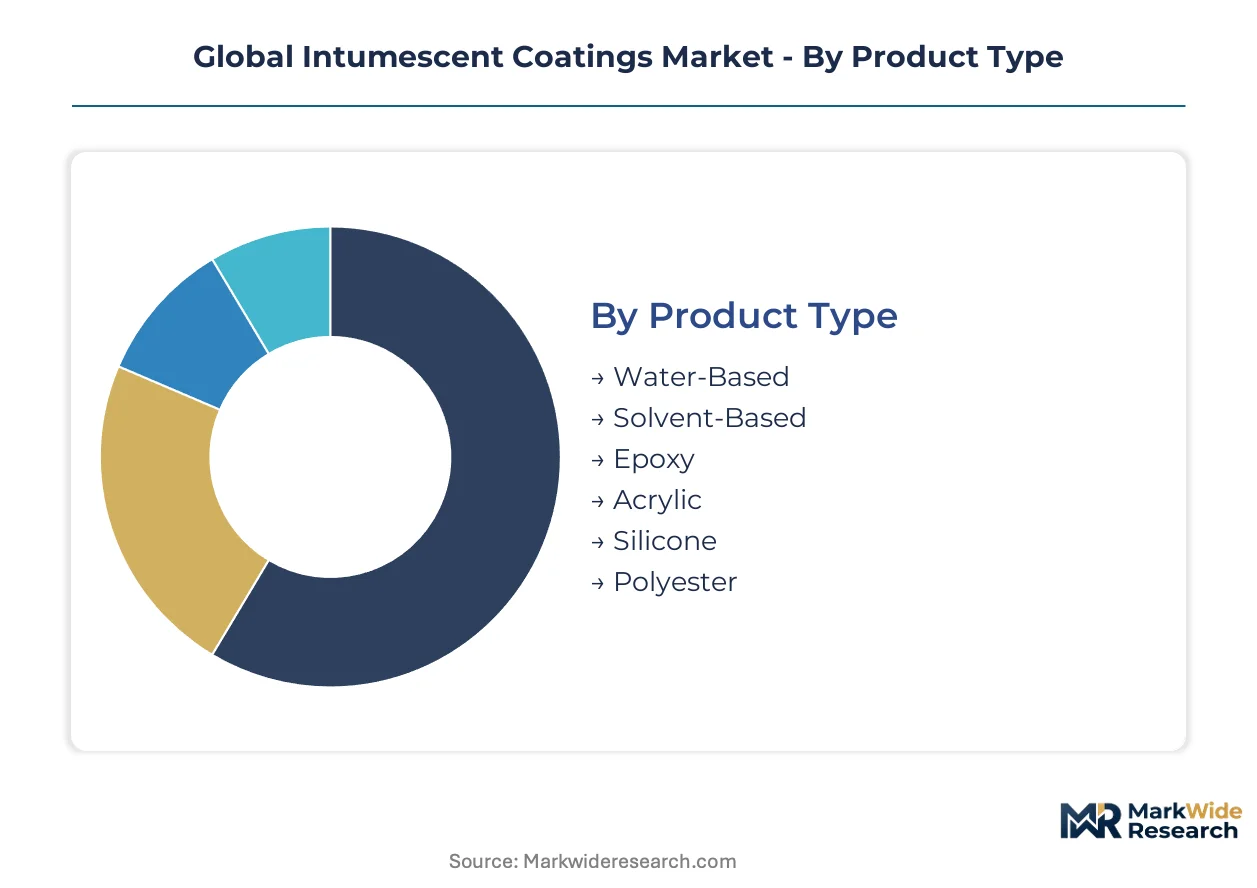
Intumescent coatings serve divergent performance requirements across construction, marine, and industrial environments where substrate conditions, regulatory exposure, and application constraints reshape procurement priorities. Specification teams weight expansion ratio, VOC compliance, and corrosion compatibility differently depending on project type and jurisdiction.
Product Type:
Formulation chemistry determines installation feasibility, cure conditions, and regulatory alignment across project environments.
- Water-Based:These systems employ water as the primary carrier, enabling low-VOC compliance for LEED and BREEAM-certified commercial developments. Demand concentrates in new high-rise construction across Germany, France, and the Netherlands where CE marking mandates intersect with green building specifications.
- Epoxy:Two-component thermoset systems deliver superior substrate adhesion and solvent resistance under humid curing conditions. Bridge and tunnel infrastructure developers in China and the United States specify these for combined fire and corrosion protection in aggressive environments.
- Solvent-Based:Traditional alkyd or acrylic solvent carriers dominate retrofit applications where rapid cure times override VOC considerations.
- Acrylic:UV-stable formulations serve exterior architectural applications requiring color retention and weathering resistance.
- Silicone:High-temperature stability suits industrial exhaust stacks and furnace proximity zones.
- Polyester:Cost-optimized systems target secondary structural elements with moderate fire rating requirements.
Water-based formulations lead on scale; epoxy systems lead on momentum in infrastructure applications.
Application:
Functional purpose reshapes specification criteria, with passive fire protection commanding premium testing and certification investment.
- Fireproofing:Reactive polymer systems expand into thermally insulating char layers when activated above threshold temperatures. Commercial high-rise developers across Beijing, Shanghai, and Shenzhen specify these for steel structural elements under GB 14907 compliance mandates.
- Corrosion Protection:Dual-function formulations integrate intumescent chemistry with barrier corrosion inhibitors. Offshore platform operators in the North Sea and Baltic Sea require these for jacket structures and substation platforms where fireproofing overlaps with salt spray exposure.
- Thermal Insulation:Energy conservation applications in industrial process equipment.
- Soundproofing:Mass-loaded intumescent layers for acoustic dampening in transportation infrastructure.
- Decorative Finishing:Pigmented topcoats for architectural visibility requirements.
- Surface Preparation:Priming systems ensuring substrate compatibility and adhesion.
Fireproofing dominates value concentration; corrosion protection is expanding most quickly in offshore wind developments.
End User:
Procurement consolidation among large developers is compressing vendor qualification cycles toward approved product lists.
- Construction Contractors:Consolidated commercial developers in Dubai, Riyadh, and Singapore maintain centralized fire safety specification teams that prioritize repeatability and supply security over unit cost. These buyers drive volume in high-rise residential and mixed-use towers.
- Infrastructure Developers:State-backed entities in China and national highway authorities in India specify intumescent coatings for bridge, tunnel, and metro rail steelwork. Metro rail construction in Mumbai, Delhi, and Bangalore creates first-mover opportunities as BIS standards mature.
- Shipbuilders:Marine classification society rules govern fire protection in accommodation and machinery spaces.
- Aerospace Manufacturers:FAA and EASA certification requirements for cabin and cargo bay applications.
- Fire Safety Consultants:Third-party specification influencers advising on code compliance pathways.
- Industrial Fabricators:Shop-applied coating for pre-engineered structural components.
Construction contractors anchor current volume; infrastructure developers are gaining share fastest in emerging market buildouts.
Technology:
Reaction mechanism and binder chemistry determine expansion performance, durability, and application method compatibility.
- Intumescence:Core technology incorporating ammonium polyphosphate acid sources, pentaerythritol carbonific agents, and melamine blowing agents to achieve 25-100x expansion ratios. ECHA REACH restrictions on halogenated alternatives are accelerating phosphorus-nitrogen system reformulation across European manufacturing.
- Cementitious:Spray-applied mineral wool or vermiculite-based systems for heavy industrial fireproofing where thickness and weight are acceptable.
- Hydrophobic:Water-repellent surface treatments for marine and coastal exposure zones.
- Cement-Modified:Hybrid systems combining cementitious durability with intumescent reactivity.
- Self-Healing:Microcapsule-based damage recovery for difficult-access installations.
- Graphic Coatings:Visual indicator systems for inspection and maintenance visibility.
Intumescence leads on specification prevalence; cementitious alternatives show steepest expansion trajectory in heavy industrial retrofit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China generates specification volume at roughly twice the intensity of Germany, though German formulators command premium positioning through CE marking compliance and water-based technology leadership.
United States
Commercial high-rise developers in New York, Chicago, and Los Angeles are expanding intumescent coating specifications as ASTM E119 testing protocols tighten. The Department of Transportation mandates fireproofing on bridge steelwork through Federal Highway Administration guidelines. Infrastructure contractors across the Pacific Northwest and Texas Gulf Coast are deploying automated thickness monitoring systems to compress certification cycles.
Germany
Industrial fabricators in the Ruhr region and Bavaria specify water-based systems for LEED-certified commercial developments. ECHA's REACH framework restricts halogenated flame retardants, forcing reformulation toward phosphorus-nitrogen chemistries. Cologne-based specification teams at consolidated contractors are compressing vendor qualification cycles toward approved product lists.
China
State-backed infrastructure investment in Beijing, Shanghai, and Shenzhen is driving steel-framed construction volume under updated GB 14907 fire resistance standards. The Ministry of Emergency Management enforces stricter commercial building fire safety mandates. Yangtze River Delta manufacturing clusters are absorbing ammonium polyphosphate supply for domestic formulators and Western joint ventures.
India
National highway expansion and metro rail construction in Mumbai, Delhi, and Bangalore are creating first-mover specification opportunities. BIS fire safety standards are maturing, with draft regulations circulating for steel structural protection. Infrastructure developers in Maharashtra and Karnataka are evaluating dual-function epoxy systems for bridge and tunnel applications.
United Arab Emirates
High-rise residential and mixed-use towers across Dubai and Riyadh are consolidating procurement through centralized fire safety specification teams. MOHAP building safety regulations mandate intumescent coating installation on structural steel above specified height thresholds. Consolidated developers in the Gulf Cooperation Council prioritize supply security and repeatability over unit cost in vendor selection.
Global Intumescent Coatings Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and specification channel access. The vendor base organizes into three tiers: multinational coatings groups with architectural distribution networks, marine and offshore specialists with corrosion-fire dual expertise, and regional formulators serving domestic certification requirements. Scale-driven players pursue backward integration into acid source raw materials while specialists deepen application technician certification partnerships with consolidated contractors.
Among diversified coatings conglomerates, AkzoNobel and PPG Industries exemplify the multinational archetype with multi-jurisdictional testing capabilities spanning ASTM E119 and EN 13381 protocols. Jotun occupies a specialist position where marine classification society relationships translate into offshore platform fireproofing specification. These three anchors represent divergent strategic postures: European regulatory compliance leadership, North American architectural channel dominance, and Nordic marine-offshore integration.
| Leading Market Players |
|---|
| AkzoNobel |
| PPG Industries |
| Sherwin-Williams |
| Jotun |
| Hempel |
| BASF |
| Sika |
| Kansai Paint |
| RPM International |
| Others |
Supply & Pricing Matrix
Epoxy intumescence technology migration toward dual-function fire-corrosion systems is simultaneously compressing formulation costs and redistributing procurement power toward infrastructure developers with multi-year project pipelines. Water-based phosphorus-nitrogen chemistry scale-up in European manufacturing is narrowing the cost gap with solvent-based legacy systems while tightening specification control among consolidated contractors.
Pricing Analysis
Capacity additions in China's Yangtze River Delta chemical manufacturing zones are reshaping price floors for ammonium polyphosphate feedstock. Three-tier pricing structure across premium certification-grade, standard commercial-grade, and economy retrofit-grade levels stratifies by UL 263 and CE marking compliance tier. Cost compression in water-based formulations is intensifying because REACH-compliant phosphorus-nitrogen R&D amortization is spreading across higher volumes. Regional formulators serving domestic GB 14907 certification requirements exhibit highest price sensitivity; multinational coatings groups with captive acid source supply exhibit lowest.
Supply Chain Analysis
Domestic-content mandates in India's infrastructure procurement guidelines are reshaping sourcing patterns for metro rail and highway steelwork protection. Ammonium polyphosphate production concentrates in China, Germany, and the United States; pentaerythritol carbonific agents draw from Chinese and Indian chemical manufacturing clusters. Single-source vulnerability runs through Yangtze River Delta acid source production zones exposed to environmental regulatory shutdowns. Distribution runs through architectural coatings distributors in commercial construction, direct specification relationships with consolidated infrastructure developers, and marine classification society channels for offshore platform applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
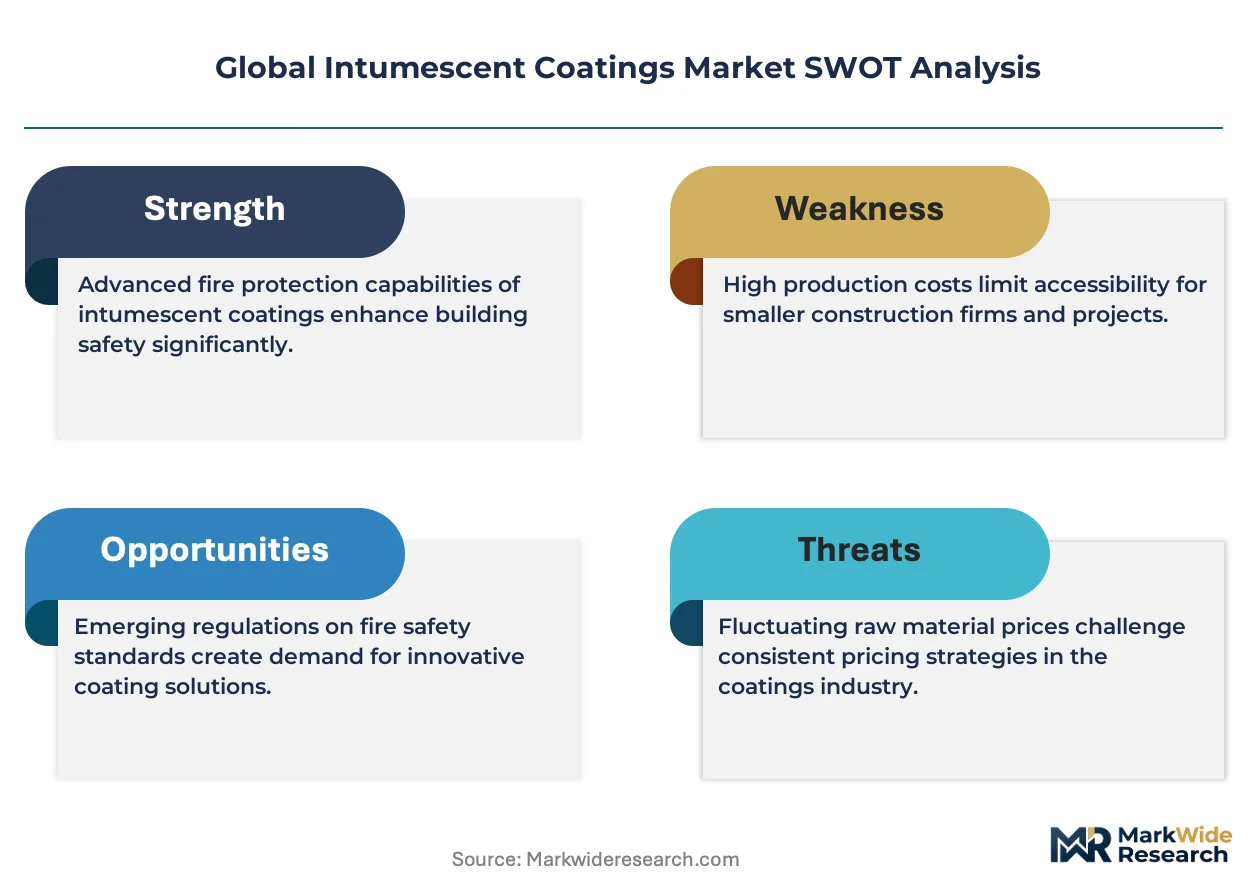
Margin expansion trajectories in this market rest on water-based formulation scale economies and premium-tier certification bundling. Reformulation cost absorption is concentrating among suppliers with backward integration into phosphorus-nitrogen chemistry.
For Market Incumbents: Cement specification control through captive application technician certification programs that lock in consolidated contractor approved product lists. Defend against regional formulator encroachment by accelerating multi-jurisdictional testing laboratory capacity additions in China and India. Prioritize upstream control over melamine blowing agent supply to neutralize input cost volatility. For New Entrants and Emerging Players: Infrastructure developers in India's Maharashtra and Karnataka highway corridors represent an underserved buyer archetype with maturing BIS fire safety standards and limited incumbent specification relationships. Bridge and tunnel epoxy intumescence applications offer penetrable white space where dual-function corrosion-fire performance commands premium positioning. Pursue direct specification partnerships with state-backed national highway authorities rather than competing through distributor channels. For Investors and Strategic Acquirers: Valuations sit cheapest among regional formulators with domestic certification capabilities in high-growth infrastructure markets but limited multi-jurisdictional testing infrastructure. Long-term viability centers on acquisition targets possessing captive phosphorus-nitrogen chemistry expertise or established marine classification society relationships for offshore wind expansion. Monitor GB 14907 enforcement intensity in China's provincial emergency management inspections as the signal for specification volume inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acid Source Raw Materials | Captive ammonium polyphosphate supply neutralizes Yangtze River Delta price volatility for Western formulators. |
| Multi-Jurisdictional Testing Laboratory Expansion | Parallel ASTM E119 and EN 13381 certification capability compresses vendor qualification cycles at consolidated contractors. |
| Application Technician Certification Partnerships | Specialized spray application training locks in specification repeatability with Dubai and Riyadh high-rise developers. |
| Water-Based Phosphorus-Nitrogen Formulation Scale-Up | REACH-compliant chemistry scale economies narrow cost gaps with solvent-based systems in LEED-certified commercial construction. |
| Offshore Wind Platform Fireproofing Specialization | North Sea and Baltic Sea jacket structure specifications combine thermal protection with corrosion resistance premiums. |
Research Methodology
Multiple input streams — technical specification interviews with fire safety consultants, procurement pattern discussions with consolidated construction contractor teams, and regulatory pathway mapping with certification laboratory directors — were reconciled against customs trade data, ECHA REACH substance restriction filings, and national fire code adoption records. Secondary validation drew from steel production statistics, commercial building permit databases, and infrastructure project development trackers. Bottom-up coating volume estimates by application and end-use segment were triangulated against top-down construction spending attribution across the analysis window.
Data-stream reconciliation across product type, application, end user, and technology dimensions anchored the analytical framework over the projection horizon. Expansion ratio performance tiers, VOC compliance categories, and corrosion protection integration levels were modeled as segmentation drivers. CAGRs were derived from elasticity-adjusted construction spending forecasts and regulatory mandate implementation timelines. Offshore wind installation pipelines and metro rail construction backlogs in emerging markets served as industry-specific volume inputs.
Underlying measurement precision varies by segment; water-based new construction and epoxy infrastructure applications carry tighter precision than solvent-based retrofit and specialty silicone formulations. Forecasts reflect assumptions regarding REACH substance restriction phase-in schedules, GB 14907 provincial enforcement consistency, and ammonium polyphosphate supply chain continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Consumer Appliance Coatings Market
Coatings
Corrosion Protection Coating Market
Coatings
Anti Soiling Coating Market
Coatings
Global Fire-Resistant Coating Market
Coatings
Global Conformal Coatings Market
Coatings
Camouflage Coatings Market
Coatings
Asia-Pacific Epoxy Powder Coatings Market
Coatings
Color-Shifting Coating Market
Coatings
Physical Vapor Deposition (PVD) Coatings Market
Coatings
Asia-Pacific Thermal Spray Market
Coatings
Intumescent Fire Retardant Coating Market
Coatings
Global Sputter Coater Market
Coatings
Global Diamond Coatings Market
Coatings
Superhydrophobic Coatings Market
Coatings
Acrylic Protective Coating Market
Coatings
Cold Gas Spray Coating Market