
 Global Diacetone Alcohol Market | 2026-2036
Global Diacetone Alcohol Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diacetone Alcohol Market Foresight
Specialty chemical distribution networks across Asia-Pacific are reconfiguring as regional buyers consolidate procurement volumes. Arkema S.A. leverages its integrated acetone derivatives platform to secure feedstock cost advantages. Solvay S.A. anchors European supply through its established solvent distribution infrastructure. Mitsubishi Chemical Corporation dominates technical-grade supply to Japanese electronics coatings manufacturers.
Diacetone alcohol is a beta-hydroxy ketone solvent with molecular formula C6H12O2, produced through the base-catalyzed condensation of acetone, and functions primarily as a high-boiling oxygenated solvent in industrial coating formulations. The compound exhibits a boiling point of approximately 166 degrees Celsius and miscibility with most organic solvents, making it suitable for lacquers, thinners, and cleaning applications requiring controlled evaporation rates. Purity-grade material commands premium positioning in pharmaceutical and electronics applications where residual impurity thresholds are stringent. Industrial-grade volumes sustain the largest revenue pool due to entrenched consumption in architectural and automotive coatings. Technical-grade supply competes aggressively in agrochemical formulation markets where cost sensitivity overrides specification stringency.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent volatility profiles in U.S. coatings production, while REACH registration requirements in Europe mandate comprehensive toxicity documentation for diacetone alcohol imports. China's MEE enforcement of volatile organic compound emission limits is redirecting domestic formulation practices toward compliant oxygenated solvents. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation-driven specification shifts and qualify alternative supply sources ahead of compliance deadlines.
Market Dynamics
Formulation chemistry across industrial coatings is pivoting toward oxygenated solvents with controlled evaporation profiles, compressing demand for conventional hydrocarbon alternatives and elevating specification stringency throughout diacetone alcohol supply chains.
Growth Catalysts
- EPA NESHAP volatility constraints:United States coatings manufacturers face mandatory solvent reformulation timelines, redirecting specification sheets toward compliant high-boiling oxygenated alternatives.
- Electronics-grade purity demand:Japanese semiconductor packaging and display coating facilities require sub-ppm impurity thresholds, creating premium-grade volume anchors.
- China MEE VOC enforcement:Provincial emission limit tightening across Jiangsu and Guangdong industrial clusters is accelerating compliant solvent substitution in architectural coatings.
Market Restraints
- Acetone feedstock volatility:Propylene-derived acetone pricing oscillates with petrochemical cycle swings, compressing margin predictability for condensation-based producers.
- Technical substitution pressure:Dipropylene glycol monomethyl ether competes aggressively in agrochemical formulation markets where cost sensitivity dominates specification decisions.
- REACH registration documentation burden:ECHA toxicity dossier requirements for diacetone alcohol imports create compliance friction for non-EU supply sources.
Strategic Opportunities
- India agrochemical formulation expansion:Domestic crop protection manufacturing under PLI scheme incentives is generating technical-grade solvent demand previously served by imports.
- Pharmaceutical extraction applications:cGMP-compliant high-purity grades command 40-60% price premiums over industrial material in active pharmaceutical ingredient processing.
- Waterborne coating co-solvent positioning:Hybrid formulation architectures integrating diacetone alcohol as a tail-solvent enable compliance with tightening VOC regulations.
Industry Challenges
- Specialized chemical engineering talent scarcity:Base-catalyzed condensation process optimization requires expertise increasingly concentrated among retiring European and Japanese technical workforces.
- Multi-jurisdiction certification timelines:Simultaneous EPA, REACH, and China GB standard compliance creates product qualification backlogs extending 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Diacetone Alcohol Market |
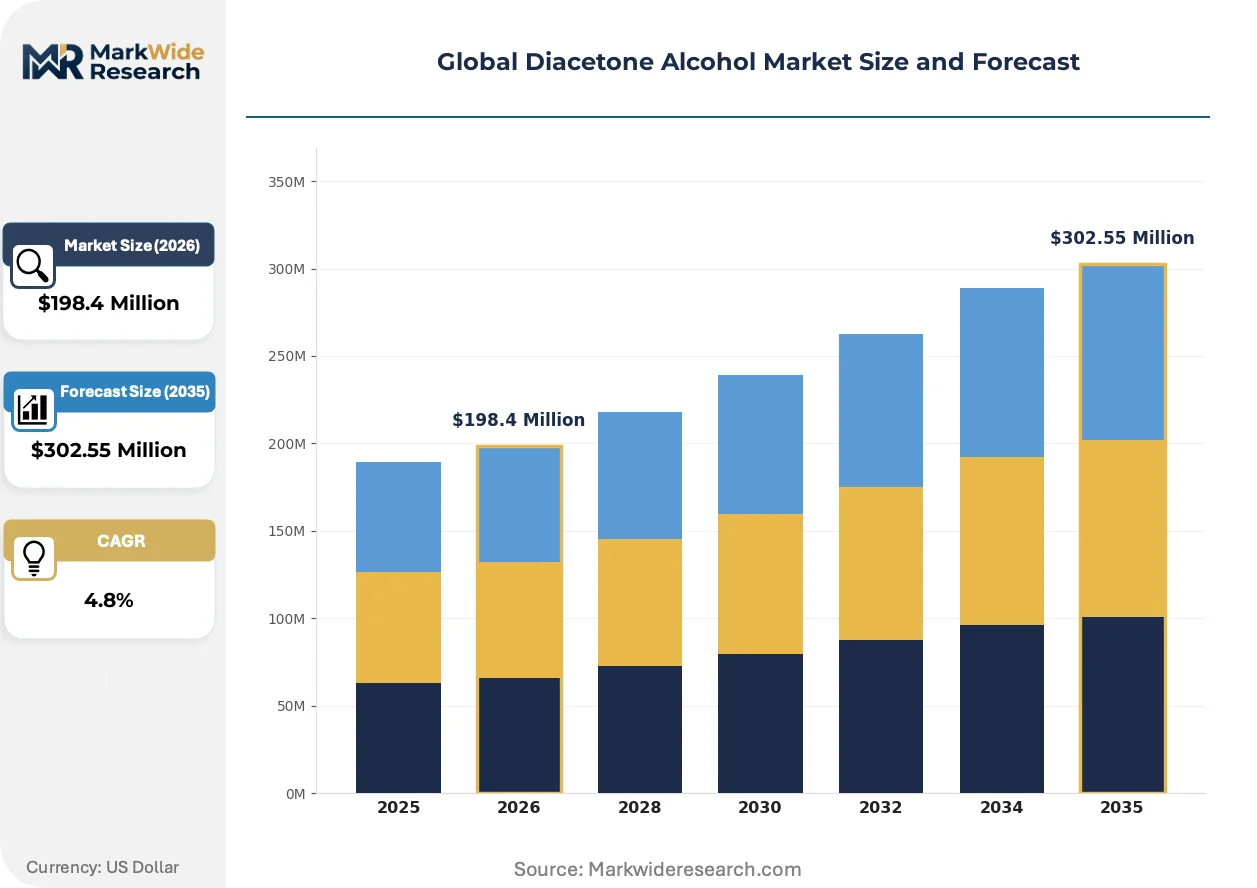
| Market Size in 2026 | $198.4 Million |
| Market Size in 2035 | $302.55 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purity Grade, Industrial Grade, Technical Grade, Reagent Grade Application: Paints & Coatings, Adhesives & Sealants, Plasticizers, Pharmaceuticals, Agrochemicals End User Industry: Manufacturing Plants, Chemical Processing Units, Pharmaceutical Formulations, Construction Material Producers Packaging Type: Drums, Bulk Tanks, Intermediate Bulk Containers, Bottles |
| Companies Covered | Monument Chemical Inc., SI Group, Inc., Arkema S.A., Solventis Ltd., Prasol Chemicals Limited, Solvay S.A., LG Chem Ltd., Tianjin Daofu Chemical New Technology Development, Mitsubishi Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diacetone Alcohol Market Shifts & Advancements
Active reformulation across protective and decorative coatings is compressing traditional solvent portfolios while elevating oxygenated alternatives with precise evaporation control, creating specification bifurcation between commodity and performance grades.
Membrane separation technology for diacetone alcohol purification is hybridizing with conventional distillation architectures, enabling producers to achieve pharmaceutical-grade purity without full column replacement. Specialty chemical facilities in Germany and Japan are retrofitting hybrid units to capture electronics coatings demand. This convergence is compressing capital barriers between industrial and technical-grade supply tiers.
REACH authorization list expansion is forcing downstream coatings manufacturers to document substitution feasibility for all SVHC-classified solvents, including certain ketone alternatives competing with diacetone alcohol. ECHA's 2024-2025 substance evaluation work program is accelerating toxicity data generation requirements. European formulators are pre-emptively qualifying compliant oxygenated solvents ahead of potential restriction proposals.
Consolidated procurement by multinational coatings manufacturers is displacing fragmented distributor relationships across Asia-Pacific supply chains. Arkema and Solvay are establishing direct supply agreements with Chinese and Indian architectural coatings producers, bypassing traditional chemical distribution intermediaries. This channel compression is most visible in high-volume industrial coatings segments where specification standardization enables direct contracting.
Global Diacetone Alcohol Market Segmentation
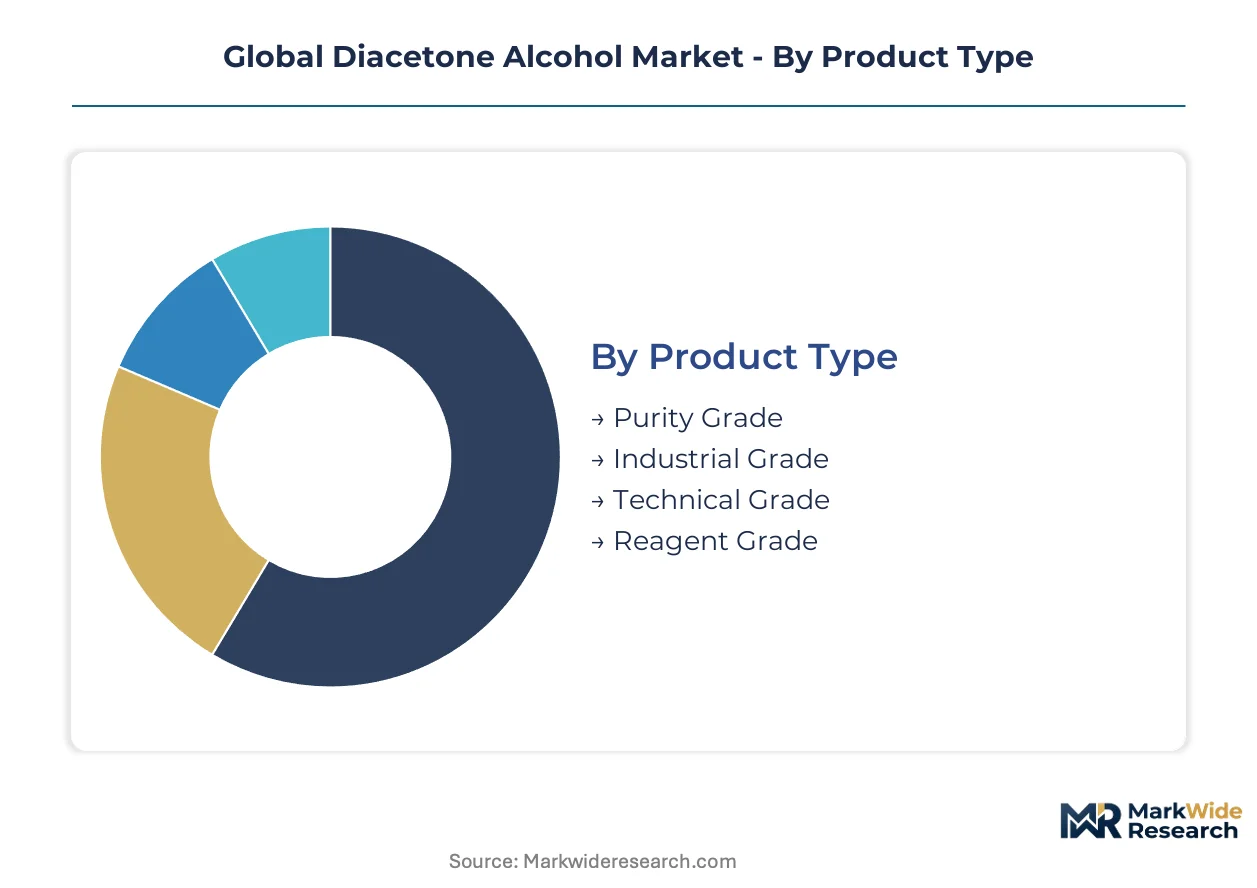
Diacetone alcohol specifications diverge sharply across downstream applications, with purity thresholds and packaging formats determining supply chain configuration. Technical support intensity varies by segment, driving distinct commercial models from spot chemical distribution to long-term formulation partnerships.
Product Type:
After-sales service intensity escalates with purity grade, as pharmaceutical and electronics customers require certificate-of-analysis documentation and batch traceability that industrial-grade buyers rarely demand.
- Purity Grade:Sub-ppm impurity specifications characterize material destined for semiconductor packaging and active pharmaceutical ingredient extraction. Japanese electronics manufacturers and European pharmaceutical compounders anchor premium demand, with REACH registration documentation creating compliance friction for non-EU supply sources.
- Industrial Grade:Architectural coatings producers in China and automotive OEM paint shops in Germany consume the largest volumes of this specification grade. MEE VOC enforcement across Jiangsu and Guangdong provinces is accelerating compliant solvent substitution, redirecting specification sheets toward this mid-tier category.
- Technical Grade:Agrochemical formulation facilities in India under PLI scheme incentives are expanding procurement of this cost-optimized specification.
- Reagent Grade:Analytical laboratories and research institutions require this highest-purity tier for chromatography and synthesis applications.
Industrial grade holds the largest share; momentum sits with purity grade as electronics and pharmaceutical applications expand.
Application:
Margin structures vary by application, with coatings commanding volume scale and pharmaceuticals extracting premium pricing through cGMP compliance requirements.
- Paints & Coatings:Waterborne and high-solids formulations integrate diacetone alcohol as a tail-solvent to achieve controlled evaporation profiles. EPA NESHAP volatility constraints in the United States and China MEE enforcement are redirecting demand from hydrocarbon alternatives toward this oxygenated solvent category.
- Pharmaceuticals:Extraction and purification processes for active pharmaceutical ingredients require cGMP-compliant material with comprehensive batch documentation. European and North American pharmaceutical manufacturers pay substantial premiums for certified supply chains with full toxicity dossier availability.
- Adhesives & Sealants:Pressure-sensitive adhesive manufacturers value the solvent's high boiling point and controlled evaporation for tape and label formulations.
- Plasticizers:Cellulose ester and synthetic resin modification applications consume steady volumes with moderate specification stringency.
- Agrochemicals:Technical-grade material competes with dipropylene glycol monomethyl ether in crop protection formulation markets where cost sensitivity dominates.
Paints and coatings command the dominant revenue position; pharmaceuticals are climbing the fastest as purity premiums widen.
End User Industry:
Customer concentration patterns shape procurement dynamics, with multinational coatings manufacturers consolidating volumes while fragmented construction material producers rely on distributor intermediaries.
- Manufacturing Plants:Integrated chemical producers with captive acetone derivatives platforms achieve feedstock cost advantages through backward integration into propylene supply chains.
- Chemical Processing Units:Specialty solvent blenders and toll manufacturers require flexible procurement of multiple grades to serve diverse downstream formulations.
- Pharmaceutical Formulations:cGMP compliance mandates drive long-term supply agreements with qualified producers capable of batch-level traceability and regulatory documentation.
- Construction Material Producers:Architectural coatings and sealant manufacturers in China and India represent high-volume, price-sensitive demand with limited specification differentiation.
Manufacturing plants hold the largest share; pharmaceutical formulations are gaining share fastest on premium pricing expansion.
Packaging Type:
Logistics economics favor bulk formats for high-volume industrial users, while pharmaceutical and electronics customers require smaller containers with contamination controls.
- Drums:Standard 200-liter steel drums serve mid-scale coatings producers and chemical distributors across Asia-Pacific supply chains.
- Bulk Tanks:Integrated coatings manufacturers with dedicated solvent storage infrastructure receive railcar and tank truck deliveries to minimize handling costs.
- Intermediate Bulk Containers:Flexible IBC formats with liner systems reduce cleaning costs for multi-product chemical processors.
- Bottles:Laboratory and small-batch pharmaceutical applications require amber glass or fluoropolymer bottles with inert atmosphere sealing.
Bulk tanks hold the largest share; intermediate bulk containers are expanding most quickly as chemical processors seek handling efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium-grade material commands 40-60% price markups in European pharmaceutical markets, while Chinese industrial-grade volumes trade at compressed margins due to feedstock cost advantages and aggressive local competition.
United States
Automotive OEM paint shops and architectural coatings manufacturers drive steady consumption of industrial-grade material. EPA NESHAP volatility constraints under the National Emission Standards for Hazardous Air Pollutants mandate solvent reformulation timelines that redirect specification sheets toward compliant high-boiling oxygenated alternatives. The Ohio River Valley chemical processing corridor hosts concentrated demand from pressure-sensitive adhesive manufacturers.
Germany
Specialty solvent blenders and toll manufacturers serving European coatings formulators constitute the primary demand base. REACH registration requirements administered by ECHA mandate comprehensive toxicity documentation for diacetone alcohol imports, creating compliance friction for non-EU supply sources. The BASF-Ludwigshafen industrial cluster anchors continental supply chain configuration for pharmaceutical-grade distribution.
China
Industrial coatings production capacity expansion across Jiangsu and Guangdong provinces sustains the largest regional volume consumption. MEE enforcement of volatile organic compound emission limits redirects domestic formulation practices toward compliant oxygenated solvents. The Yangtze River Delta petrochemical corridor concentrates acetone derivatives manufacturing with backward integration into propylene supply chains.
Japan
Semiconductor packaging and display coating facilities require sub-ppm impurity thresholds for electronics-grade material. METI industrial standards govern solvent purity specifications for domestic electronics manufacturers. The Kansai-Osaka chemical processing belt hosts specialized purification facilities serving technical-grade supply to precision coatings producers.
India
Domestic crop protection manufacturing under PLI scheme incentives generates technical-grade solvent demand previously served by imports. CDSCO pharmaceutical regulations drive cGMP compliance requirements for active pharmaceutical ingredient extraction applications. The Gujarat chemical manufacturing corridor concentrates agrochemical formulation capacity expansion with integrated solvent storage infrastructure.
Global Diacetone Alcohol Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The market structures around three distinct tiers: integrated petrochemical conglomerates with captive acetone supply, regional solvent distributors with formulation technical support capabilities, and specialty purification houses serving pharmaceutical and electronics specifications. Strategic moves concentrate on direct supply agreement establishment with multinational coatings manufacturers and hybrid purification technology retrofitting for grade-tier migration.
Among European-based chemical conglomerates, Arkema S.A. and Solvay S.A. exemplify platform integrators leveraging established solvent distribution infrastructure. Mitsubishi Chemical Corporation occupies a position within the Asia-Pacific technical-grade supply tier. Monument Chemical Inc. represents the North American regional specialist archetype with integrated acetone derivatives positioning.
| Leading Market Players |
|---|
| Monument Chemical Inc. |
| SI Group, Inc. |
| Arkema S.A. |
| Solventis Ltd. |
| Prasol Chemicals Limited |
| Solvay S.A. |
| LG Chem Ltd. |
| Tianjin Daofu Chemical New Technology Development |
| Mitsubishi Chemical Corporation |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta petrochemical corridor's freight economics compress industrial-grade margins while amplifying purity-grade premiums, as acetone feedstock concentration in eastern China enables aggressive spot pricing that European REACH-registered producers cannot match without sacrificing documentation compliance costs.
Pricing Analysis
Customization-premium spreads separate pharmaceutical-grade spot purchases from industrial-grade contract volumes. Three-tier pricing structure across premium, standard, and economy levels anchors the market, with cGMP certification and sub-ppm impurity thresholds driving 40-60% markups in pharmaceutical applications. Cost compression in technical-grade supply is intensifying because dipropylene glycol monomethyl ether substitutes aggressively in agrochemical markets. Construction material producers in China exhibit highest price sensitivity, while Japanese semiconductor packaging facilities accept premium positioning without volume negotiation.
Supply Chain Analysis
Contract-manufacturing concentration sits with Arkema's integrated acetone derivatives platform and Solvay's established European solvent distribution infrastructure. Supply concentrates in China, Germany, and Japan, with the Yangtze River Delta and BASF-Ludwigshafen corridor anchoring regional hubs. Feedstock draws from propylene supply chains and base-catalyzed condensation capacity. Single-source vulnerability persists in electronics-grade purification, where membrane separation technology hybridization requires specialized engineering talent concentrated among retiring European and Japanese workforces. Distribution runs through direct supply agreements with multinational coatings manufacturers, displacing traditional chemical distribution intermediaries across Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
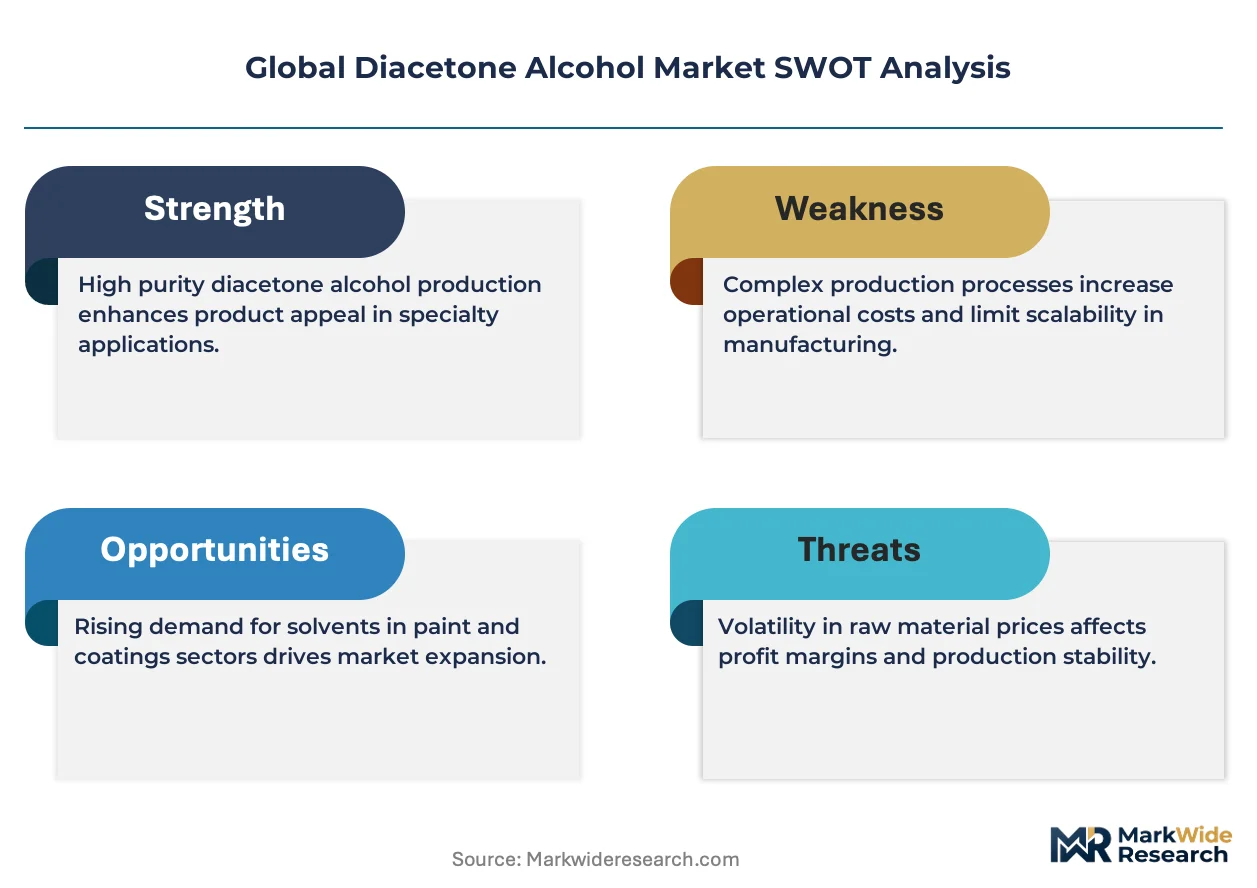
This market presents a defensive moat through regulatory entrenchment, as REACH registration documentation and multi-jurisdiction certification timelines create 18-24 month qualification backlogs that insulate qualified incumbents from rapid competitive entry.
For Market Incumbents: Harden supply chain control through backward integration into propylene feedstock and hybrid purification technology retrofitting for grade-tier migration. Secure direct supply agreements with Chinese and Indian architectural coatings producers before channel compression eliminates distributor intermediaries entirely. Prioritize certification investment to defend against emerging technical-grade competitors in India's PLI-supported agrochemical formulation expansion. For New Entrants and Emerging Players: India's technical-grade agrochemical formulation market offers the most penetrable white-space target, as PLI scheme incentives expand domestic crop protection manufacturing previously served by imports. Pharmaceutical extraction applications in cGMP-compliant high-purity grades present secondary entry opportunity with 40-60% price premium capture. Pursue toll manufacturing partnerships with established acetone derivatives platforms to bypass capital-intensive condensation capacity requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty purification houses with membrane-distillation hybrid capabilities serving electronics and pharmaceutical specifications. Long-term viability rests on regulatory documentation asset accumulation rather than commodity volume scale. Monitor ECHA substance evaluation work program acceleration as inflection signal for REACH restriction proposal timing and substitution feasibility documentation mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Feedstock | Arkema's captive acetone derivatives platform secures margin predictability against petrochemical cycle volatility. |
| Hybrid Purification Technology Retrofit | Membrane-distillation convergence enables German and Japanese facilities to capture electronics-grade demand without full column replacement. |
| Direct Supply Agreement Establishment | Solvay's bypass of Asia-Pacific chemical distributors compresses channel costs for high-volume industrial coatings segments. |
| REACH Registration Documentation Investment | ECHA toxicity dossier completion creates compliance friction that protects European incumbents from non-EU import competition. |
| Waterborne Coating Co-Solvent Positioning | Tail-solvent integration in hybrid formulations enables EPA NESHAP and China MEE compliance without hydrocarbon substitution. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with coatings formulators, pharmaceutical procurement managers, specialty chemical distributors, and acetone derivatives plant engineers. Secondary validation drew from customs and trade data, SEC 10-K filings, ECHA registration databases, and ACC and Cefic industry reports. Bottom-up volume modeling across grade tiers, end-use industries, and packaging formats was cross-checked against top-down macroeconomic indicators to ensure analytical consistency.
Calibration against historical price realizations and capacity utilization rates anchored the projection framework. Segmentation dimensions included purity grade, application category, end-user industry, and regional production hub across the analysis window. CAGRs were derived from regression analysis of demand drivers including coatings formulation shifts, pharmaceutical extraction growth, and agrochemical manufacturing expansion. Feedstock cost volatility and regulatory enforcement intensity served as key sensitivity inputs.
Practitioners should monitor acetone price oscillations, REACH authorization list expansion, and China MEE provincial enforcement tightening for early signals of forecast revision. Quarterly review of ECHA substance evaluation progress, propylene derivative margin spreads, and India PLI scheme disbursement rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Anhydrous Hydrogen Fluoride Market
Chemicals
Immunochemicals Market
Chemicals
Sodium Azide Market
Chemicals
Formalin Vials Market
Chemicals
Ruthenium Tetroxide Market
Chemicals
Antiozonant Market
Chemicals
Global Pine Chemicals Market
Chemicals
Calcium Disodium Ethylene Diamine Tetra-Acetate Market
Chemicals
Asia Pacific Waterproofing Chemicals Market
Chemicals
Global Boron Trifluoride Market
Chemicals
Whitening Ingredients Market
Chemicals
Diethylenetriamine (DETA) Market
Chemicals
Rocket Propellant Chemicals Market
Chemicals
Paint Stripper Market
Chemicals
Europe Flame Retardant Chemicals Market
Chemicals
Benzhydrol Market