
 Ceramic Sanitary Ware Market | 2026-2036
Ceramic Sanitary Ware Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Sanitary Ware Market Intelligence
The bundling of complete bathroom solutions, including fixtures, fittings, and furniture, is consolidating buyer preference towards single-brand ecosystems. This trend favors large-scale manufacturers with comprehensive product portfolios. Kohler Co. leverages its strong brand recognition and extensive distribution network to offer these integrated packages. TOTO Ltd. differentiates through its focus on high-tech and water-efficient innovations within its product suites, while Geberit AG specializes in behind-the-wall technology, integrating its systems with a wide range of visible ceramic products.
Ceramic sanitary ware comprises plumbing fixtures made from clay-based materials, such as vitreous china or porcelain, fired at high temperatures to achieve a non-porous, durable surface. These products primarily serve hygiene and sanitation functions in residential and commercial buildings. Water closets and washbasins constitute the largest product type segments by volume. The residential complexes segment remains the foundation of demand, while hospitality centers are driving growth in premium, wall-mounted installations that offer aesthetic appeal and easier cleaning.
Market access and product design are heavily influenced by water efficiency and safety regulations. The EPA's WaterSense program in the United States and the EU's CE marking requirements under the Construction Products Regulation mandate specific performance standards. In China, GB standards for sanitary ceramics govern product quality and safety. Stakeholders must now navigate the increasing complexity of material lifecycle assessments and circular economy principles in their product development and supply chain strategies.
Market Dynamics
The convergence of stringent water conservation regulations and rising consumer demand for aesthetic, wellness-oriented bathroom environments is the central force shaping the ceramic sanitary ware market. This dynamic compels manufacturers to innovate beyond basic functionality into high-design, technologically advanced products.
Growth Catalysts
- Government Housing Initiatives:Large-scale public housing and urban development programs, such as India's Pradhan Mantri Awas Yojana (PMAY), are creating substantial volume demand for essential sanitary ware products like water closets and washbasins, establishing a broad installation base.
- Hospitality Sector Renovations:The global hospitality industry's focus on modernization and enhancing guest experience drives investment in premium, design-forward sanitary ware, including wall-hung toilets and countertop basins that offer both aesthetic appeal and improved hygiene.
- Smart Bathroom Technology:The integration of digital features like touchless flushing, temperature control, and self-cleaning functions into sanitary ware is attracting a growing consumer segment focused on convenience, hygiene, and water efficiency, particularly in developed markets.
Market Restraints
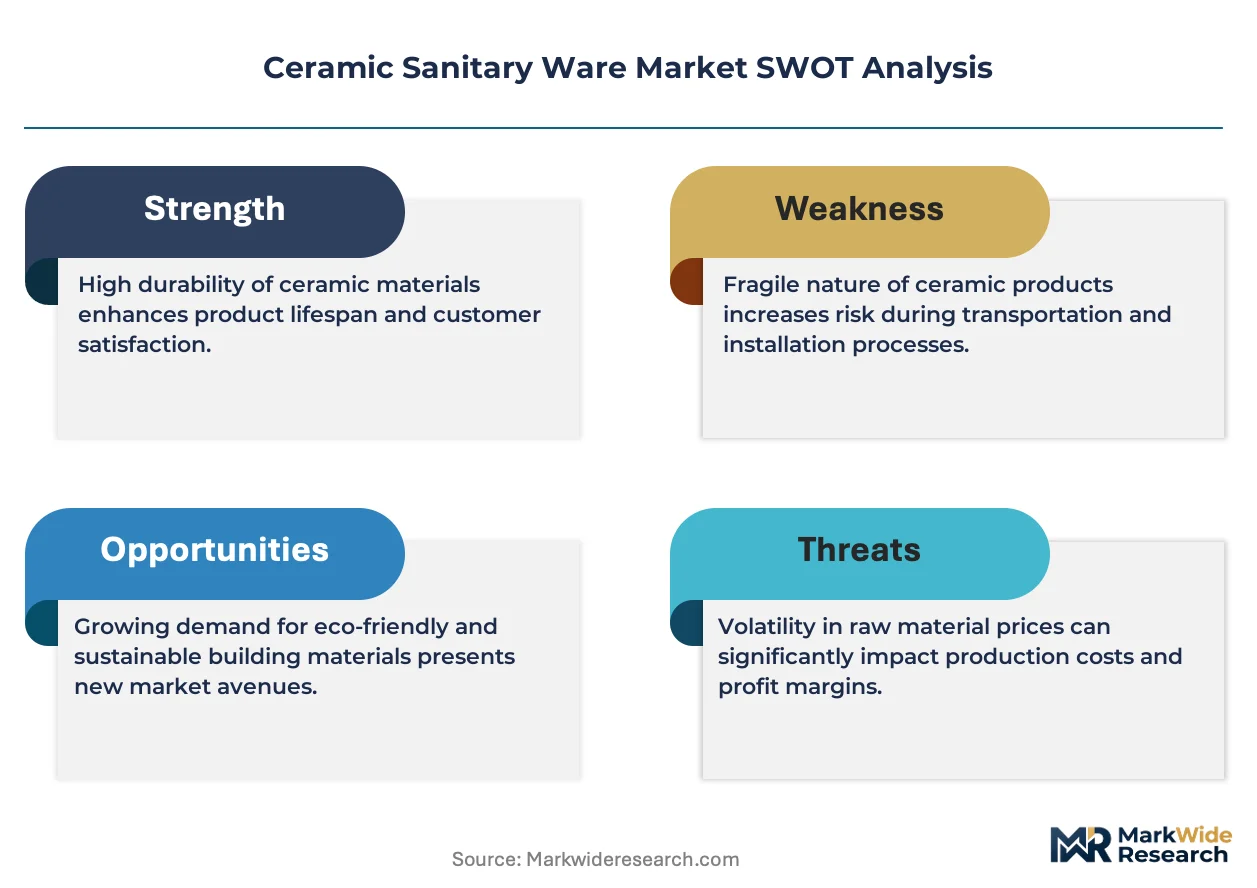
- Energy and Raw Material Volatility:Manufacturer profitability is constrained by fluctuations in the price of natural gas, a critical input for firing kilns, and key raw materials like high-quality clays, feldspar, and silica, which directly impact production costs.
- Logistical Complexities:The fragile and bulky nature of ceramic products results in high transportation and insurance costs, creating significant logistical hurdles that can limit geographic reach and favor manufacturers with localized production facilities.
- Threat from Alternative Materials:In the premium and luxury segments, ceramic faces competition from alternative materials like solid surface composites, engineered quartz, and natural stone, which offer different aesthetic qualities and design flexibility for washbasins and countertops.
Strategic Opportunities
- Expansion in Emerging Economies:Significant white space exists in developing regions of Africa and Southeast Asia, where rising disposable incomes, rapid urbanization, and improving sanitation infrastructure are creating new markets for both basic and mid-range sanitary ware.
- Circular Economy Product Design:There is a growing opportunity to develop products using recycled content or designed for easier disassembly and material recovery, aligning with evolving regulations and attracting environmentally conscious commercial and residential customers.
- Products for Aging Populations:Developing sanitary ware tailored to the needs of elderly users, such as comfort-height toilets and barrier-free washbasins with integrated grab bars, addresses a clear demographic trend in markets like Japan, Germany, and the United States.
Industry Challenges
- Navigating Divergent Global Standards:Manufacturers face operational complexity in ensuring products comply with a patchwork of regional water efficiency and safety standards, including the EPA's WaterSense in the US, CE marking in the EU, and GB standards in China.
- Capital-Intensive Modernization:Upgrading production facilities with energy-efficient kilns, automated glazing lines, and water recycling systems requires substantial capital investment, posing a barrier for smaller-scale producers and pressuring margins for all players.
- Supply Chain Resilience:The industry is challenged by the need to secure a stable supply of specific grades of clay and other minerals, forcing a re-evaluation of sourcing strategies to mitigate risks from geopolitical instability and trade disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Sanitary Ware Market |
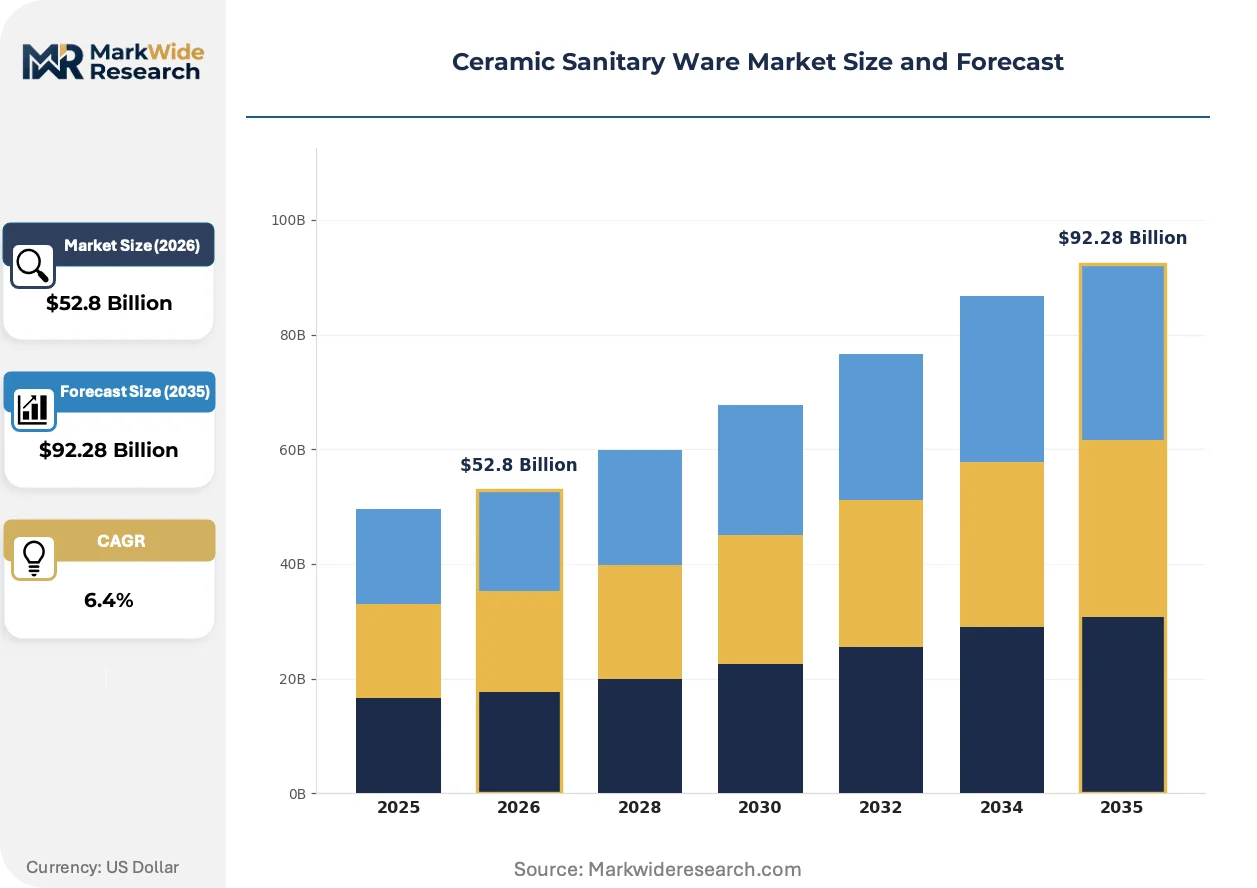
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $92.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Washbasins, Water Closets, Urinals, Bidets, Bathtubs Material Composition: Vitreous China, Porcelain, Fine Fire Clay, Stoneware Installation Type: Wall-mounted, Floor-mounted, Countertop, Pedestal End User: Residential Complexes, Commercial Establishments, Hospitality Centers, Educational Institutions |
| Companies Covered | Kohler Co., TOTO Ltd., Roca Sanitario S.A., Geberit AG, Villeroy & Boch AG, LIXIL Group Corporation, RAK Ceramics P.J.S.C, Grohe AG, Duravit AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Sanitary Ware Market Strategic Shifts & Innovations
Product evolution is defined by the integration of digital technology and sustainable design principles. This shift transforms sanitary ware from standalone utilitarian items into components of a connected, resource-efficient bathroom ecosystem, driven by both regulatory pressures and changing consumer expectations for hygiene and wellness.
Smart toilet technology, which incorporates features like automated flushing, bidet functions, and self-cleaning glazes, is a primary innovation. Adoption is accelerating in the luxury residential and hospitality sectors, particularly in East Asia, and is gaining momentum in North America. This technology is expanding into the development of fully integrated smart bathroom systems, where fixtures communicate to optimize water usage and personalize the user experience.
The EU's Circular Economy Action Plan is influencing product development and material specification across the industry. This regulatory framework compels manufacturers to increase transparency regarding material lifecycle, from sourcing to end-of-life recyclability, as mandated under the Construction Products Regulation. The premium segment is most impacted, with firms leveraging Environmental Product Declarations (EPDs) as a competitive differentiator to secure specifications in green building projects.
Buyer behavior is moving toward single-brand procurement for complete bathroom solutions that bundle ceramics with fittings, furniture, and accessories. This model disrupts traditional distribution channels, which historically relied on selling individual components from various brands. The trend is most visible in large-scale commercial and residential developments in Europe and the United States, where developers and contractors prioritize design consistency and simplified logistics.
Ceramic Sanitary Ware Market Segmentation
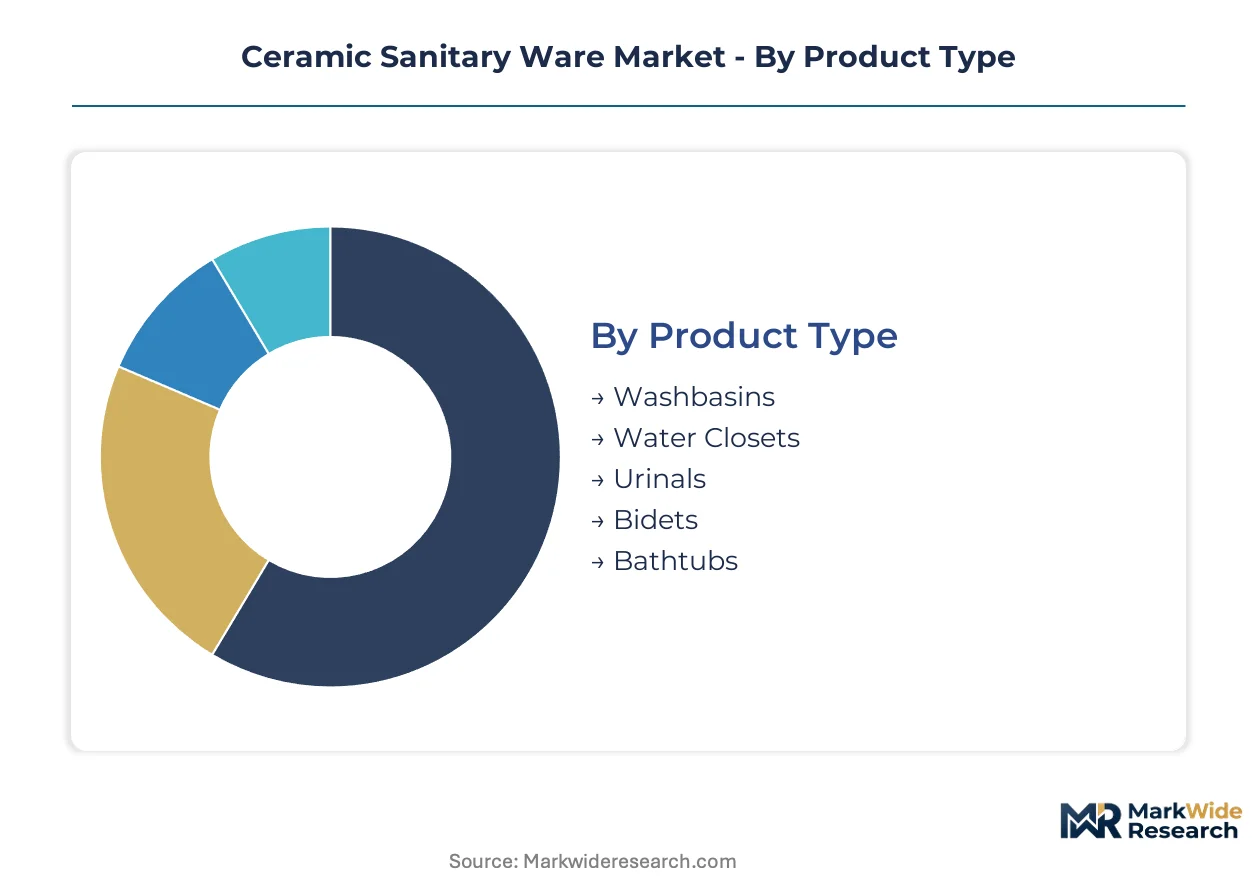
The ceramic sanitary ware market serves diverse needs across construction sectors, influencing product design and material selection. Understanding its segmentation reveals distinct demand patterns and supply chain configurations. This analysis highlights how specific product attributes and end-user requirements shape market dynamics for manufacturers.
Product Type:
Supply concentration in the ceramic sanitary ware market often aligns with the production scale and technological complexity of specific product types.
- Water Closets:These essential fixtures facilitate waste disposal, typically made from vitreous china or porcelain for durability and hygiene. Demand for water-efficient models is intensifying in India due to government housing initiatives like PMAY, emphasizing basic sanitation infrastructure.
- Washbasins:Comprising bowls for handwashing, these products vary from simple pedestal designs to integrated countertop units, primarily using fired clay materials. Residential complexes globally drive significant volume demand, with aesthetic considerations influencing premium segment growth in Europe and North America.
- Urinals:Designed for male urination, these fixtures prioritize water efficiency and hygiene in commercial and institutional settings.
- Bidets:These personal hygiene fixtures provide water for washing after toilet use, gaining traction in luxury residential and hospitality sectors in East Asia.
- Bathtubs:Large receptacles for bathing, bathtubs offer relaxation and aesthetic appeal, primarily demanded by high-end residential and hospitality projects.
Water Closets absorb the bulk of installed capacity; Bidets are expanding most quickly.
Material Composition:
The application of ceramic sanitary ware is fundamentally shaped by the material composition, which dictates performance, aesthetics, and cost profiles for diverse end-uses.
- Vitreous China:This material is a ceramic glaze applied to a ceramic body and fired at high temperatures, creating a non-porous, glossy, and highly durable surface. Its widespread use in water closets and washbasins reflects strong demand from residential complexes and commercial establishments in the United States, driven by cost-effectiveness and regulatory compliance.
- Porcelain:Fired at even higher temperatures than vitreous china, porcelain offers superior density, strength, and a more refined finish, resisting stains and scratches effectively. Premium hospitality centers in Germany and France increasingly specify porcelain for its aesthetic appeal and longevity, supporting luxury bathroom designs.
- Fine Fire Clay:This material allows for larger, more intricate designs, often used for farmhouse sinks and larger washbasins due to its inherent strength.
- Stoneware:Known for its rustic appearance and robustness, stoneware finds niche applications in decorative washbasins and specialized architectural projects.
The durability of Vitreous China drives its widespread adoption, while Porcelain caters to specialized aesthetic and performance requirements.
Installation Type:
Customer type significantly influences the preferred installation type, with different end-users prioritizing specific functional and aesthetic attributes in their sanitary ware choices.
- Wall-mounted:These fixtures are affixed directly to the wall, leaving the floor clear, which enhances visual space and simplifies cleaning. Hospitality centers in Japan and the United Kingdom increasingly favor wall-mounted toilets and washbasins for their modern aesthetic and improved hygiene, aligning with guest experience upgrades.
- Floor-mounted:The traditional installation method involves fixtures resting directly on the floor, providing robust stability and straightforward installation. Residential complexes in China and Brazil continue to drive high volume demand for floor-mounted water closets due to their proven reliability and lower installation costs.
- Countertop:Washbasins designed to sit on top of a vanity or counter offer design flexibility and a contemporary aesthetic, popular in modern residential bathrooms.
- Pedestal:Featuring a basin supported by a ceramic column, pedestal installations conceal plumbing and offer a classic, elegant look for residential and commercial restrooms.
The preference for Wall-mounted units dominates modern design specifications, whereas Floor-mounted options maintain their position in foundational infrastructure projects.
End User:
Margin opportunities within the ceramic sanitary ware market vary considerably across different end-user segments, reflecting distinct purchasing power and specification requirements.
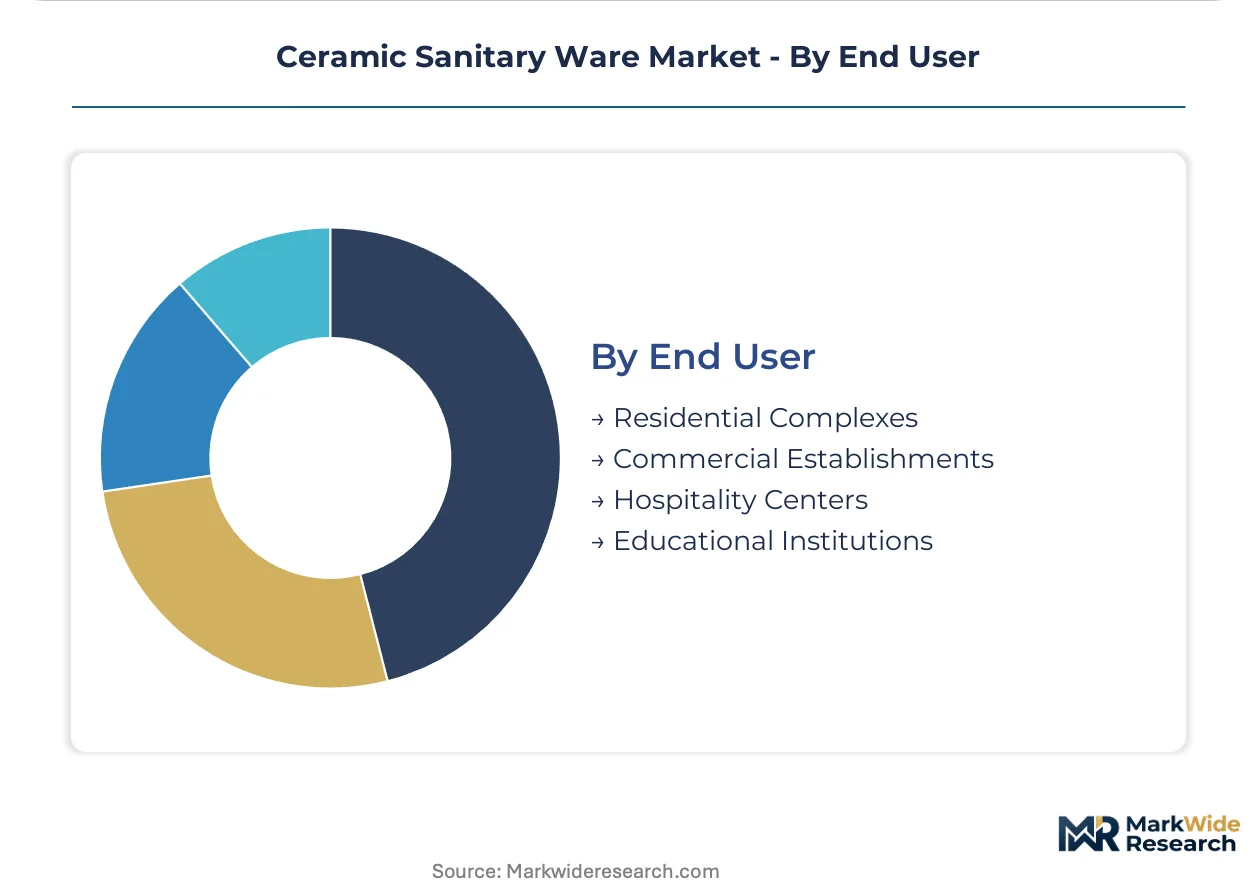
- Residential Complexes:This segment encompasses multi-unit dwellings and single-family homes, representing the largest volume demand for standard and mid-range sanitary ware. Government housing initiatives in India and Brazil, alongside general urban development, ensure a consistent, high-volume base for essential fixtures.
- Hospitality Centers:Hotels, resorts, and guesthouses constitute this segment, driving demand for premium, design-forward, and water-efficient sanitary ware. Renovations and new luxury hotel constructions in the UAE and Singapore prioritize sophisticated wall-mounted installations and smart bathroom technologies to enhance guest experience.
- Commercial Establishments:Offices, retail spaces, and public buildings require durable, high-traffic sanitary solutions that comply with public health and accessibility standards.
- Educational Institutions:Schools and universities demand robust, vandal-resistant, and easily maintainable sanitary ware, often prioritizing longevity and hygiene in high-use environments.
Demand from Residential Complexes provides market stability, with Hospitality Centers offering opportunities for premium product innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The production-vs-consumption divide shapes regional market dynamics, with large-scale manufacturing hubs supplying diverse demand centers. Emerging economies drive volume growth for essential sanitary ware, while developed markets focus on premium, technologically advanced solutions and replacement cycles. Regulatory frameworks for water efficiency and product safety also create distinct regional market conditions.
India
Extensive government housing initiatives like the Pradhan Mantri Awas Yojana (PMAY) are creating substantial demand for basic water closets and washbasins. The Bureau of Indian Standards (BIS) governs product quality and safety for ceramic sanitary ware in the country. Major manufacturing clusters in Gujarat, such as Morbi, are expanding capacity to meet both domestic and export requirements.
China
Residential complexes and urban infrastructure projects generate high volume demand for ceramic sanitary ware. China's GB standards for sanitary ceramics enforce strict quality and performance requirements for all products sold domestically. Production centers in Guangdong province, particularly in Foshan, remain global hubs for sanitary ware manufacturing and innovation.
United States
Renovations in residential and hospitality sectors drive demand for both standard and premium ceramic fixtures. The EPA's WaterSense program significantly influences product development, mandating water-efficient designs for toilets and faucets. Commercial construction in major metropolitan areas like New York and Los Angeles increasingly specifies durable, compliant sanitary ware.
Germany
Premium hospitality centers and high-end residential projects prioritize sophisticated, water-efficient sanitary ware. The EU's CE marking requirements under the Construction Products Regulation ensure products meet stringent safety and performance standards. Design and manufacturing excellence in regions like Bavaria and North Rhine-Westphalia support the European market for luxury bathroom solutions.
Japan
An aging population drives demand for comfort-height toilets and barrier-free washbasins, while smart toilet technology gains traction in luxury homes. Japanese Industrial Standards (JIS) ensure high product quality and performance for ceramic sanitary ware. Manufacturers in the Kansai region, including Osaka, focus on integrating advanced features and ergonomic designs into their product lines.
Ceramic Sanitary Ware Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the ceramic sanitary ware market. The industry exhibits a tiered structure, with global leaders offering comprehensive bathroom solutions and regional players specializing in specific product categories or price points. Strategic archetypes include integrated solution providers, technology innovators, and volume-driven manufacturers. Competitive moves primarily involve portfolio diversification to offer complete bathroom ecosystems and geographic expansion into high-growth emerging economies.
Among the integrated solution providers, Kohler Co. and TOTO Ltd. exemplify firms leveraging strong brand recognition and extensive distribution networks to offer bundled products. Geberit AG represents a specialist archetype, focusing on behind-the-wall technology that integrates with a wide range of visible ceramic products. These companies anchor their positions by offering comprehensive product portfolios that span various price segments and end-user requirements.
| Leading Market Players |
|---|
| Kohler Co. |
| TOTO Ltd. |
| Roca Sanitario S.A. |
| Geberit AG |
| Villeroy & Boch AG |
| LIXIL Group Corporation |
| RAK Ceramics P.J.S.C |
| Grohe AG |
| Duravit AG |
| Others |
Cost & Logistics Intelligence
Bundling complete bathroom solutions anchors both the supply position and the pricing power for large-scale manufacturers in the ceramic sanitary ware market. This strategic integration allows firms to offer comprehensive packages, influencing buyer preferences towards single-brand ecosystems.
Pricing Analysis
Margin tightening in the standard and economy segments reflects intense competition and volatile raw material costs. Per-unit transactional pricing dominates, especially for basic water closets and washbasins in high-volume residential projects. Price differentiation stems from brand premium, material quality (e.g., porcelain versus vitreous china), and adherence to specific regulatory standards like EPA's WaterSense. Residential complexes exhibit the highest price sensitivity, whereas luxury hospitality centers prioritize design and advanced features over cost.
Supply Chain Analysis
Regulatory compliance and certification requirements significantly gate supply chain access, particularly for products destined for the United States (EPA WaterSense) and the EU (CE marking). Geographic supply concentration centers on China, India, and Germany for manufacturing capacity and skilled labor. The industry draws from key raw materials including high-quality clays, feldspar, and silica. Commodity price volatility, especially for natural gas used in firing kilns, represents a significant structural risk. Distribution runs through traditional channels, though single-brand procurement models are gaining traction in commercial and large-scale residential developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation is accelerating, driven by the substantial capital investment required for modernization and compliance with diverse global standards. This pressure forces smaller, less-resourced players to exit or be acquired.
For Market Incumbents: Acquire specialized technology firms or mid-sized regional manufacturers to expand product portfolios and market access. This strategy mitigates the threat from alternative materials and strengthens channel control against emerging entrants. Invest in R&D for advanced water-saving technologies and circular economy principles to maintain a competitive edge and navigate evolving regulatory landscapes.
For New Entrants and Emerging Players: Aging populations represent an underserved buyer archetype, creating opportunities for comfort-height toilets and barrier-free washbasins. Target developing regions in Africa and Southeast Asia for basic and mid-range sanitary ware, leveraging rapid urbanization and improving sanitation infrastructure. A focused go-to-market angle on sustainable product design, supported by Environmental Product Declarations, can attract environmentally conscious commercial and residential customers.
For Investors and Strategic Acquirers: Exit pathways concentrate in vertically integrated mid-cap specialists with strong regional distribution networks or niche technology innovators. The market demonstrates long-term viability, underpinned by consistent residential demand and premium growth in hospitality. A sustained investment in smart bathroom technology, particularly touchless and self-cleaning features, serves as a key inflection indicator for future growth potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Portfolio Diversification | Expands market reach by offering complete bathroom solutions, consolidating buyer preference towards single-brand ecosystems. |
| Green Manufacturing Transition | Aligns operations with circular economy principles and attracts environmentally conscious commercial and residential customers. |
| Geographic Expansion | Accesses significant white space in developing regions of Africa and Southeast Asia, leveraging urbanization. |
| Technology Licensing | Integrates advanced features like touchless flushing and self-cleaning glazes, enhancing product differentiation for TOTO Ltd. |
| Digital Integration | Develops smart bathroom systems that optimize water usage and personalize user experience, particularly for luxury segments. |
Research Approach
Independent corroboration across industry experts, regulatory bodies, and financial reports underwrites the qualitative findings and quantitative projections within this study. Primary interviews with R&D directors, procurement managers, sustainability officers, and sales leads provided critical insights into market dynamics. Secondary data sources included EPA WaterSense program documents, EU CE marking guidelines, GB standards, and relevant company annual reports, supporting both bottom-up and top-down triangulation.
Rate-of-change decomposition informed the analytical framework for market sizing and forecasting across the analysis window. The model considered segmentation dimensions such as product type, material composition, installation type, end user, and regional regulatory clusters. Compound annual growth rates were derived from historical data and projected market shifts, with urbanization rates and construction spending forecasts serving as key industry-specific inputs.
Revisions become necessary when significant geopolitical instability or raw material supply disruptions materialize. Forecasts reflect assumptions documented from current market conditions and anticipated regulatory developments. A model refresh is warranted upon material change in global trade policies or construction activity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
USA and Canada Alumina Market
Ceramics
North America Activated Alumina Market
Ceramics
Refractories Market
Ceramics
Calcined Kaolin Market
Ceramics
Medical Ceramics Market
Ceramics
Ceramic Additives Market
Ceramics
Low Temperature Co-Fired Ceramic (LTCC) Market
Ceramics
Industrial Ceramics Market
Ceramics
Barium Carbonate Powder Market
Ceramics
Zirconia Ceramics Market
Ceramics
Global Ceramic Balls Market
Ceramics
Construction Ceramics Market
Ceramics
Cerium Carbonate Market
Ceramics
Ball Clay Market
Ceramics
Zeolite 4A Market
Ceramics
Earthenware Market