
 Rust Remover Market | 2026-2036
Rust Remover Market Size, Share, and Industry Trends Forecast 2026-2036
Rust Remover Market Outlook
Specialty chemical production in Germany's Rhine-Ruhr industrial belt is shifting toward low-VOC rust remover formulations. BASF SE leverages its integrated feedstock position to control input costs for phosphoric acid derivatives. Henkel AG & Co. KGaA anchors European professional channels with application-specific product lines. WD-40 Company competes through brand recognition in consumer retail segments across North America.
Rust removers are chemical formulations designed to dissolve iron oxide deposits through acid-base reactions, chelation, or reduction mechanisms, typically containing phosphoric acid, oxalic acid, or petroleum distillates with pH values ranging from strongly acidic to neutral for sensitive substrates. Their primary industrial purpose is surface preparation for coating adhesion, equipment longevity, and aesthetic restoration of ferrous metal components. Liquid formulations dominate volume sales due to immersion tank compatibility in automotive and industrial equipment applications, while gel products command premium positioning in vertical surface treatments where drip control matters. Aerosol spray formats are gaining traction among contractors and professional cleaners requiring portable, targeted application in field maintenance scenarios.
EPA regulations in the United States restrict volatile organic compound emissions from aerosol rust removers, pushing manufacturers toward propellant reformulation or compressed gas alternatives. REACH registration requirements in Europe mandate full chemical substance disclosure, raising compliance costs for importers but creating barriers that favor established regional producers. OSHA workplace exposure limits for acid mists influence product concentration specifications sold to industrial end users. Stakeholders must monitor evolving state-level restrictions on hydrofluoric acid content, as California and New Jersey have signaled tighter thresholds that could force formula redesign across national distribution networks.
Market Dynamics
REACH compliance in Europe is tightening allowable acid concentrations in consumer formulations, forcing manufacturers to reformulate phosphoric acid derivatives and accelerating the shift toward chelation-based alternatives across professional and retail channels.
Growth Catalysts
- Machine tool maintenance cycles:Germany's industrial corridor drives professional-grade consumption as precision metalwork shops expand preventive maintenance programs. Equipment longevity mandates from industrial end users sustain recurring demand.
- REACH registration requirements:Full chemical substance disclosure mandates raise compliance costs for importers but create structural barriers favoring established regional producers with captive technical documentation capabilities.
- Gel-based application technology:Automotive restoration workshops adopt precision formulations for vertical surface treatments where drip control matters, expanding addressable use cases beyond immersion tank compatibility.
Market Restraints
- Phosphoric acid feedstock volatility:Integrated producers like BASF SE control input costs through captive supply, but non-integrated formulators face margin compression from phosphate rock price swings and energy-intensive processing.
- Substitution threat from laser cleaning:Dry ablation systems eliminate chemical waste disposal costs for high-value aerospace components, capturing share in applications where substrate sensitivity permits thermal methods.
- OSHA workplace exposure limits:Acid mist thresholds constrain product concentration specifications sold to industrial end users, capping efficacy per application and extending treatment duration.
Strategic Opportunities
- Underpenetrated field maintenance segment:Contractors and professional cleaners in North America adopt portable aerosol formats for targeted application, creating channel expansion beyond traditional industrial distribution.
- EU Green Deal chemistry incentives:Low-VOC and bio-based formulation mandates open procurement preferences for compliant suppliers in public infrastructure and defense maintenance contracts.
- Convergence of chelation and surfactant chemistry:Hybrid systems combining EDTA derivatives with corrosion inhibitors enable neutral-pH operation on sensitive substrates previously requiring mechanical abrasion.
Industry Challenges
- Formulation chemist talent scarcity:Expertise in acid-base reaction kinetics and chelation stability is concentrating at specialty chemical majors, constraining mid-tier competitors' R&D velocity.
- State-level hydrofluoric acid thresholds:California and New Jersey signal tighter content restrictions that could force formula redesign across national distribution networks, fragmenting compliance architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rust Remover Market |
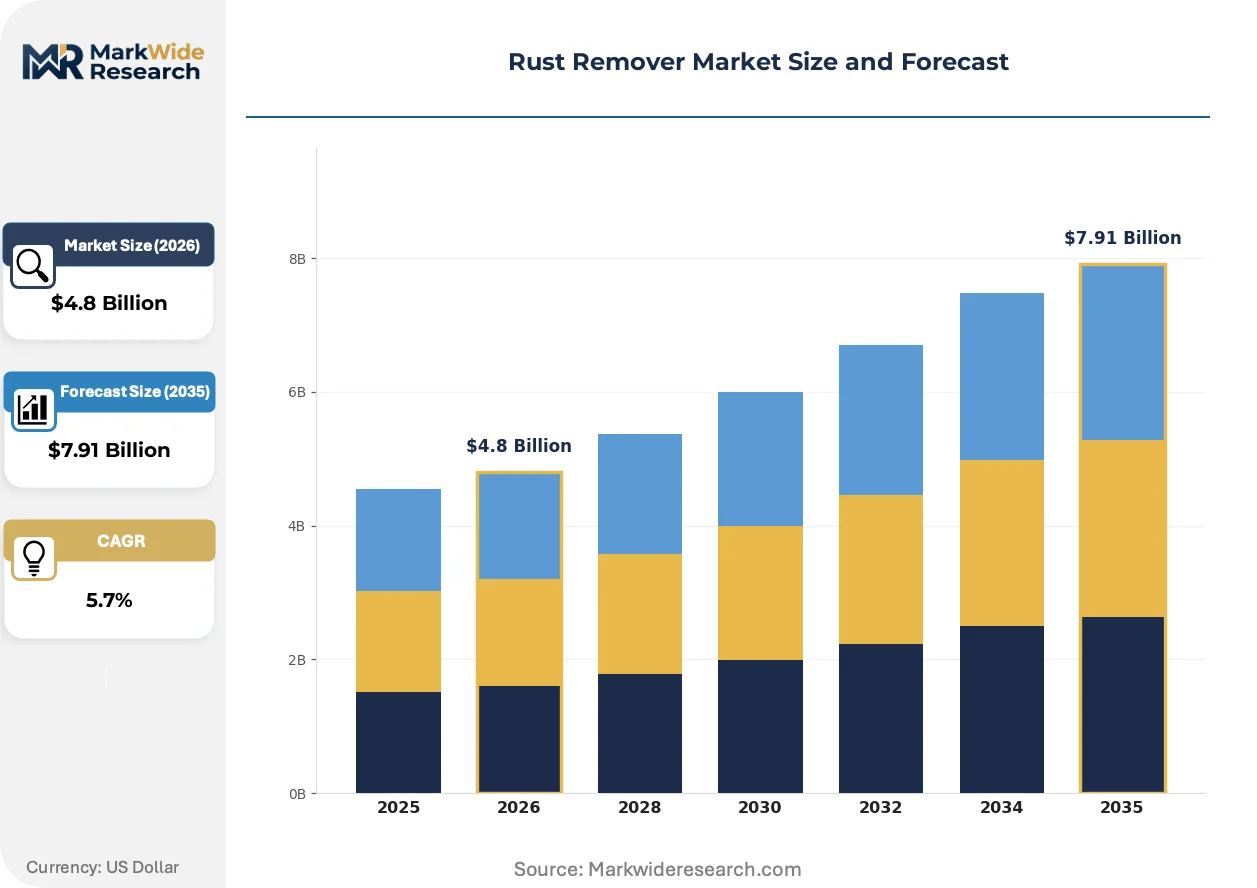
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerosol Spray, Gel, Liquid, Wipe Application: Automotive, Industrial Equipment, Household, Marine End User: Consumers, Professional Cleaners, Manufacturers, Contractors Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | RPM International Inc., BASF SE, Henkel AG & Co. KGaA, The Sherwin-Williams Company, Zep Inc., WD-40 Company, CRC Industries, Inc., Jelmar LLC, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rust Remover Market Strategic Shifts
Formulation chemistry is pivoting toward substrate-specific precision as end users reject universal solutions, while regulatory pressure on volatile organic compounds accelerates propellant and carrier system innovation.
Biodegradable chelating agents are decentralizing rust removal from centralized immersion operations toward point-of-use application. Automotive detailers and heritage railway restoration crews adopt citric acid and gluconate-based systems for on-site treatment without wastewater infrastructure. This decentralization compresses logistics costs and enables service revenue models previously captive to industrial tank operators.
EPA volatile organic compound restrictions on aerosol rust removers are forcing propellant reformulation toward compressed gas alternatives. Manufacturers face reformulation timelines compressed by state-level adoption of California Air Resources Board thresholds. Professional cleaning contractors in Texas and Florida maintenance corridors absorb price premiums for compliant products to retain municipal contract eligibility.
After-sales technical service is unbundling from product supply as buyer sophistication increases. Industrial procurement teams in Ohio and Michigan machine tool clusters now specify application training and substrate compatibility audits as separate contract line items. This bifurcation favors suppliers with field technical organizations over pure manufacturing competitors.
Rust Remover Market Segmentation
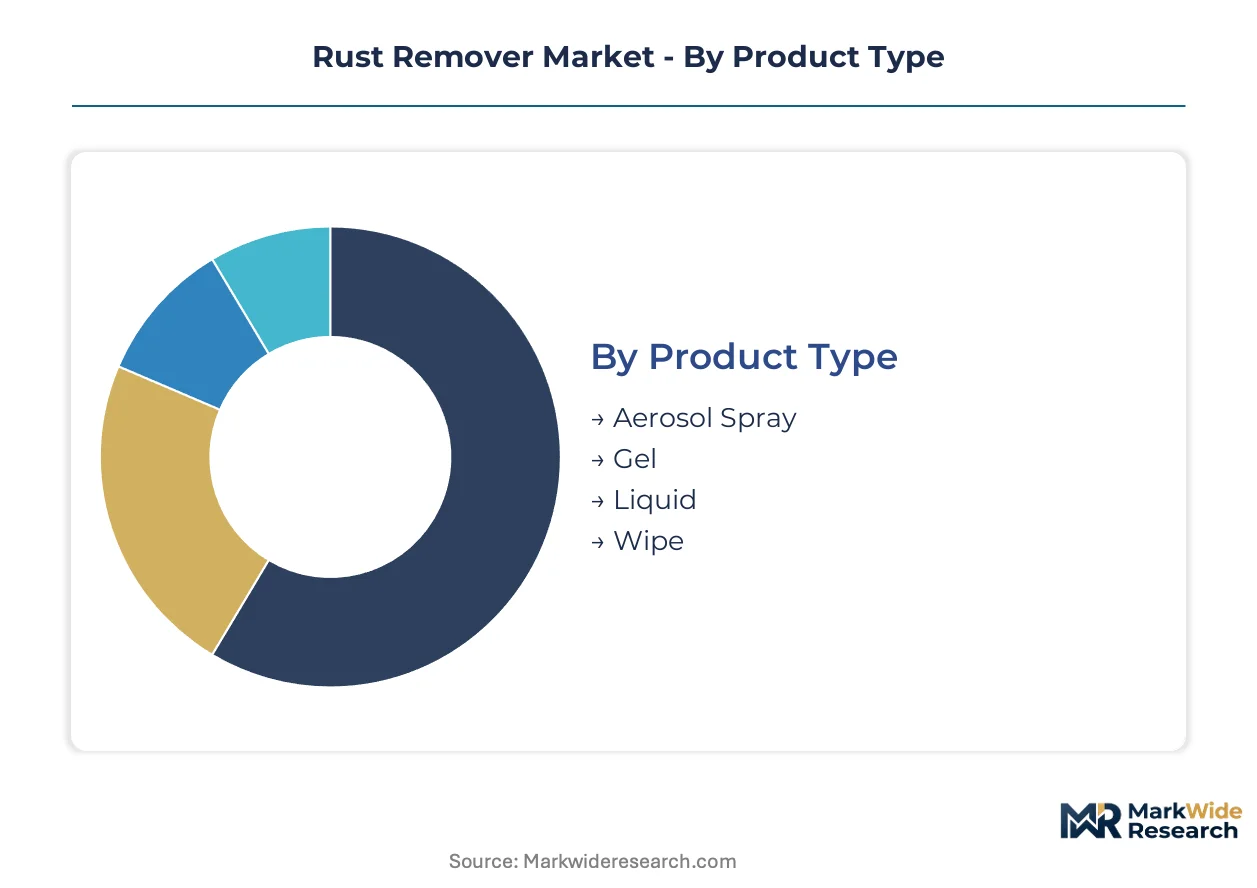
Product form and application context dictate capital requirements across the rust remover value chain, with immersion infrastructure and field portability creating divergent investment profiles. Channel structure further fragments procurement economics between bulk industrial supply and retail unit pricing.
Product Type:
Liquid formulations demand the heaviest upfront capital for immersion tank installation and wastewater handling systems in industrial settings.
- Liquid:Acidic or neutral-pH solutions formulated for tank immersion of large metal components. Demand concentrates in Germany's machine tool maintenance corridor, where equipment longevity mandates sustain recurring volume through preventive maintenance programs.
- Gel:Thickened formulations with controlled viscosity for vertical surface adhesion without drip loss. Automotive restoration workshops in Ohio and Michigan adopt precision application systems, expanding use cases beyond tank-based operations into on-site heritage metalwork.
- Aerosol Spray:Pressurized delivery systems using compressed gas or reformulated propellants for portable field application.
- Wipe:Pre-saturated substrates for consumer convenience and controlled dosage in household maintenance tasks.
Liquid absorbs the bulk of installed capacity; gel is expanding most quickly.
Application:
Cost tier stratification separates industrial surface preparation from consumer aesthetic restoration, with regulatory compliance adding overhead to professional segments.
- Automotive:OEM coating adhesion preparation and aftermarket restoration spanning collision repair to classic vehicle preservation. EPA volatile organic compound restrictions on aerosol formats push German suppliers toward low-VOC gel systems for professional detailers.
- Industrial Equipment:Preventive maintenance of machine tools, presses, and material handling systems. Germany's Rhine-Ruhr industrial belt anchors professional-grade consumption through mandated equipment longevity programs in precision metalwork shops.
- Household:Consumer-grade applications for garden tools, automotive touch-ups, and domestic metal maintenance.
- Marine:Saltwater corrosion treatment for hulls, rigging, and dock infrastructure requiring specialized formulations.
Industrial Equipment commands the largest revenue base; Automotive climbs the fastest as restoration culture spreads.
End User:
Customer sophistication determines specification stringency, with professional procurement teams unbundling technical service from product supply.
- Manufacturers:Industrial procurement teams in Ohio and Michigan machine tool clusters specify application training and substrate compatibility audits as separate contract line items.
- Professional Cleaners:Municipal and commercial maintenance contractors in Texas and Florida absorb price premiums for EPA-compliant aerosol formats to retain contract eligibility.
- Contractors:Field maintenance specialists requiring portable application systems for infrastructure and equipment servicing.
- Consumers:Retail purchasers prioritizing convenience and brand recognition over technical specifications.
Manufacturers dominate volume commitment; Professional Cleaners gain share fastest through municipal contract expansion.
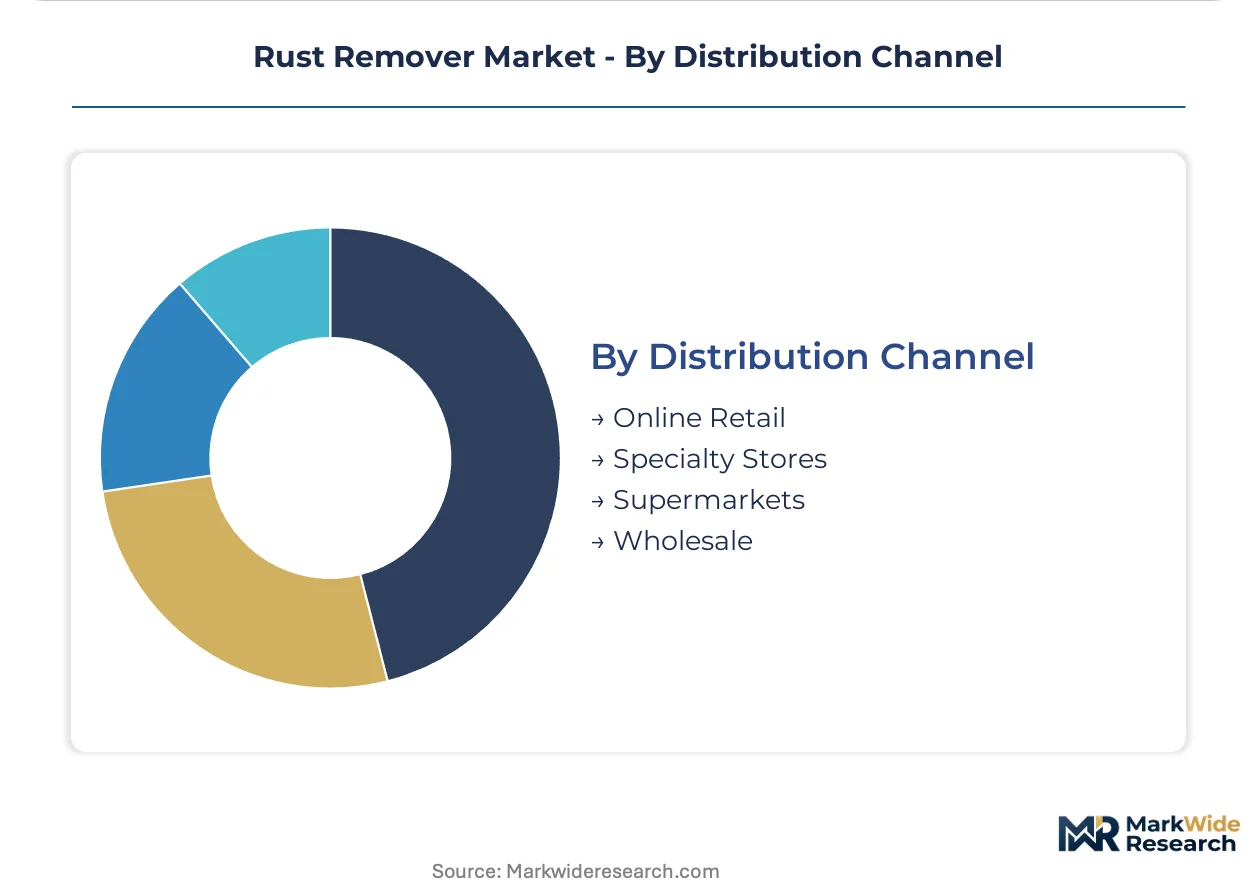
Distribution Channel:
Supply concentration favors established regional producers with captive technical documentation capabilities under REACH registration requirements.
- Wholesale:Bulk supply to industrial distributors serving machine tool clusters and automotive production facilities. BASF SE leverages integrated feedstock positions to control input costs for phosphoric acid derivatives in this channel.
- Specialty Stores:Professional supply outlets offering application equipment and technical consultation alongside chemical products. Henkel AG anchors European professional channels with application-specific product lines here.
- Online Retail:Direct-to-consumer and small-contractor procurement with logistics compression enabling point-of-use delivery.
- Supermarkets:Mass-market retail placement for consumer aerosol and wipe formats competing on brand recognition.
Wholesale channels carry the deepest volume; Online Retail is gaining share fastest as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phosphate rock deposits in Morocco and Florida anchor feedstock security for phosphoric acid derivatives, while manufacturing concentration clusters in Germany, the United States, China, and Japan shape regional formulation capabilities and regulatory compliance architectures.
Germany
Machine tool maintenance cycles in the Rhine-Ruhr industrial belt sustain professional-grade consumption through mandated equipment longevity programs. REACH registration requirements under ECHA jurisdiction raise compliance costs for importers while favoring established producers with captive technical documentation. BASF SE leverages its integrated Ludwigshafen feedstock position to control input costs for phosphoric acid derivatives serving automotive and industrial channels.
United States
Automotive restoration workshops in Ohio and Michigan adopt precision gel formulations for heritage metalwork and coating adhesion preparation. EPA volatile organic compound restrictions on aerosol formats push manufacturers toward compressed gas propellant alternatives. Professional cleaning contractors in Texas and Florida absorb price premiums for compliant products to retain municipal contract eligibility under state-level adoption of California Air Resources Board thresholds.
China
Industrial equipment manufacturing clusters in the Yangtze River Delta generate substantial surface preparation demand for coating adhesion and export compliance. National standards under SAMR and MIIT jurisdiction tighten chemical substance disclosure requirements for domestic formulations. Shanghai-based chemical producers expand chelation-based alternatives to serve automotive OEM specifications and reduce acid effluent treatment burdens.
Japan
Precision metalwork shops in the Nagoya industrial corridor maintain strict preventive maintenance programs for machine tool longevity. METI industrial chemical regulations influence workplace exposure specifications and product concentration limits. Osaka-based specialty chemical producers develop low-VOC formulations aligned with domestic environmental targets and aerospace substrate sensitivity requirements.
Rust Remover Market Competitive Environment
Global majors compete with regional champions across formulation chemistry and distribution channel depth. Market structure exhibits tiered consolidation, with integrated chemical conglomerates controlling upstream feedstock positions while mid-tier formulators compete on application-specific specialization. Three archetypes dominate: phosphate derivative producers with captive raw material access, specialty chemical houses with professional channel anchoring, and consumer-facing brands with retail distribution scale. Dominant competitive moves include backward integration into phosphate rock processing and geographic expansion through technical service unbundling.
Among German chemical conglomerates, BASF SE and Henkel AG & Co. KGaA occupy positions reflecting integrated feedstock control and professional channel specialization respectively. BASF SE exemplifies the upstream-integrated archetype through its Ludwigshafen manufacturing complex. Henkel AG represents application-specific product line development for European professional channels. WD-40 Company sits within the brand-recognition tier competing through consumer retail penetration across North American mass-market outlets.
| Leading Market Players |
|---|
| RPM International Inc. |
| BASF SE |
| Henkel AG & Co. KGaA |
| The Sherwin-Williams Company |
| Zep Inc. |
| WD-40 Company |
| CRC Industries, Inc. |
| Jelmar LLC |
| 3M Company |
| Others |
Value Chain & Pricing Dynamics
Captive integration into phosphate rock processing anchors both feedstock security and pricing power for phosphoric acid derivative producers. BASF SE's Ludwigshafen complex demonstrates how upstream control insulates margin positions against phosphate rock volatility while enabling competitive pressure on non-integrated formulators.
Pricing Analysis
After-sales technical service unbundling is reshaping contract structures as industrial procurement teams in Ohio and Michigan separate application training from product supply. Three-tier pricing structure across premium, standard, and economy levels stratifies by formulation concentration and REACH documentation depth. Pricing pressure stems from OSHA workplace exposure limits capping acid mist concentrations and extending treatment duration. Professional cleaners in Texas and Florida absorb premiums for EPA-compliant aerosols, while consumer segments exhibit highest price sensitivity.
Supply Chain Analysis
EU Green Deal local-content mandates for bio-based feedstocks are reshaping sourcing patterns toward European chelation chemistry producers. Phosphate rock deposits in Morocco and Florida anchor raw material security, while phosphoric acid processing concentrates in Germany, China, and the United States. Supply chain risk centers on single-source vulnerability for EDTA derivatives concentrated with Asian manufacturers. Distribution runs through wholesale industrial distributors serving machine tool clusters, with online retail compressing logistics for small-contractor procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemist talent scarcity constrains R&D velocity across mid-tier competitors, propping pricing for specialty chemical majors with captive expertise pipelines.
For Market Incumbents: Acquire chelation chemistry specialists to secure EDTA derivative capabilities before laser cleaning substitutes capture aerospace share. Backward integration into phosphate rock processing defends margin positions against feedstock volatility. Invest in REACH technical documentation capabilities to maintain importer barriers. For New Entrants and Emerging Players: Begin with biodegradable chelating agent formulations for heritage railway restoration crews lacking wastewater infrastructure. Target field maintenance contractors in Texas and Florida corridors seeking EPA-compliant portable formats. Pursue municipal contract eligibility through compressed gas propellant certification. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chemical conglomerates seeking professional channel anchoring. Long-term viability favors formulators with hybrid chelation-surfactant chemistry patents and field technical organizations. Watch California and New Jersey hydrofluoric acid threshold enforcement as regulatory inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive phosphate rock processing insulates BASF SE from Moroccan supply disruptions. |
| Green Manufacturing Transition | Low-VOC formulations unlock EU Green Deal procurement preferences for public infrastructure contracts. |
| Long-term Supply Agreement | Machine tool clusters in Germany's Rhine-Ruhr belt lock in recurring preventive maintenance volumes. |
| Joint Venture | Chelation chemistry partnerships accelerate citric acid derivative scale-up for automotive OEM specifications. |
| Capacity Expansion | Gel formulation lines in Ohio and Michigan serve precision automotive restoration workshop demand. |
Study Parameters
Trade databases, SEC 10-K filings, and ECHA REACH registration records formed the secondary backbone, cross-referenced with primary interviews involving formulation chemists, industrial procurement managers at machine tool clusters, automotive restoration workshop operators, and specialty chemical distribution channel heads. Bottom-up and top-down triangulation validated volume estimates across product form and application segments.
Bottom-up modeling anchored projections, with top-down macro validation across the analysis window. Segmentation dimensions included product form, application context, end-user sophistication tier, and regional regulatory cluster. CAGRs derived from historical trajectory analysis and elasticity-adjusted demand drivers, incorporating phosphate rock price volatility and REACH compliance cost escalation as industry-specific inputs.
Underlying measurement precision varies by segment; liquid immersion formulations carry tighter precision than emerging aerosol alternatives due to established tank infrastructure visibility. Forecasts reflect assumptions about OSHA enforcement continuity and EU Green Deal procurement rollout pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
High-Performance Descaling and Deliming Chemicals for HoReCa Equipment Market
Cleaning Chemicals
Fabric Softener Market
Cleaning Chemicals
Instrument Detergents for Manual Cleaning Market
Cleaning Chemicals
North America Metal Cleaning Chemicals Market
Cleaning Chemicals
Global Dust Suppression and Control Chemicals Market
Cleaning Chemicals
Cleaning Nozzles Market
Cleaning Chemicals
Europe Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Housekeeping Chemicals for Hotels and Resorts Market
Cleaning Chemicals
Dust Suppressant Market
Cleaning Chemicals
Concentrated Laundry Powder Market
Cleaning Chemicals
Latin America Detergent Market
Cleaning Chemicals
Chemical Dust Suppressants Market
Cleaning Chemicals
Europe Mastic Remover Market
Cleaning Chemicals
Lens Cleaning Product Market
Cleaning Chemicals
Soap and Detergent Market
Cleaning Chemicals
Firefighting Chemicals Market