
 Crude Tall Oil Derivative Market | 2026-2036
Crude Tall Oil Derivative Market Size, Share, and Industry Trends Forecast 2026-2036
Crude Tall Oil Derivative Market Intelligence
REACH registration timelines for tall oil derivatives is collapsing the competitive field to producers with dedicated compliance teams. Kraton Corporation leverages its integrated refinery network to sustain qualification across multiple downstream grades. Forchem Oyj anchors Nordic supply through its Rauma biorefinery, while Ingevity Corporation differentiates via specialized rosin acid derivatives for adhesives and coatings.
Crude tall oil derivative encompasses the fractionated products of crude tall oil, a byproduct of kraft pulp manufacturing containing fatty acids, rosin acids, and neutral compounds separated through vacuum distillation at temperatures between 200°C and 300°C. These derivatives serve as renewable feedstocks for adhesives, coatings, biodiesel, and specialty chemicals, replacing petroleum-based alternatives in applications demanding bio-based content. Fatty acids command the largest volume share due to their versatility in surfactants and fuel applications, while biodiesel represents the fastest-expanding application segment driven by renewable fuel mandates. Rosin acids concentrate margin pools in adhesives and ink resins where performance specifications limit substitution.
The EU Green Deal and REACH framework govern chemical registration and carbon intensity thresholds for bio-based materials entering European industrial supply chains. ECHA classification rules for tall oil derivatives determine labeling requirements and downstream handling protocols across member states. Stakeholders must monitor evolving biofuel certification schemes and pulp mill capacity decisions, as these upstream variables determine derivative availability and pricing trajectories more directly than downstream demand shifts.
Market Dynamics
EU Green Deal carbon intensity thresholds are restructuring offtake economics for biodiesel producers, collapsing margins for non-compliant feedstock suppliers while concentrating procurement around Nordic integrated pulp-to-chemicals complexes with verified low-carbon tall oil fatty acid streams.
Growth Catalysts
- Renewable Fuel Mandates:EU member state blending obligations under the Renewable Energy Directive are locking in long-term offtake agreements for tall oil fatty acids as transport fuel decarbonization accelerates.
- REACH Compliance Collapse:Registration timelines and data requirements under ECHA frameworks are eliminating smaller traders, consolidating volume around producers with dedicated regulatory teams and full dossier submissions.
- Nordic Supply Clustering:Finland and Sweden anchor integrated kraft pulp biorefinery networks that capture crude tall oil at source, securing feedstock cost advantages unavailable to merchant processors.
Market Restraints
- Kraft Pulp Capacity Volatility:Softwood pulp mill curtailments in Sweden and Finland directly constrain crude tall oil availability, creating supply inelasticity that amplifies price spikes during downstream demand surges.
- Petroleum Feedstock Substitution:Low-cost palm fatty acid distillate and used cooking oil compete for biodiesel feedstock slots, compressing tall oil fatty acid pricing power when vegetable oil markets soften.
- Fractionation Energy Intensity:Vacuum distillation at 200°C to 300°C demands substantial thermal input, exposing Nordic producers to natural gas price volatility that erodes margin stability.
Strategic Opportunities
- Specialty Rosin Acid Derivatives:Adhesives and ink resin applications command premium pricing due to performance specifications that limit substitution, rewarding producers with purified rosin acid capabilities.
- Biorefinery Integration:Captive crude tall oil streams from kraft pulp operations enable backward integration into fractionation, eliminating merchant feedstock exposure and securing margin capture across the value chain.
- Carbon Certification Arbitrage:ISCC and RSB certification schemes for biofuels create tiered pricing structures that reward producers with verified supply chain traceability and low-carbon intensity scores.
Industry Challenges
- Fractionation Specialist Scarcity:Vacuum distillation process engineering expertise resides with a limited cohort of operators, constraining capacity expansion and technology transfer to new market entrants.
- Multi-Jurisdictional Registration Burden:Separate REACH, TSCA, and DSL compliance pathways for tall oil derivative grades fragment regulatory resources and extend product qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crude Tall Oil Derivative Market |
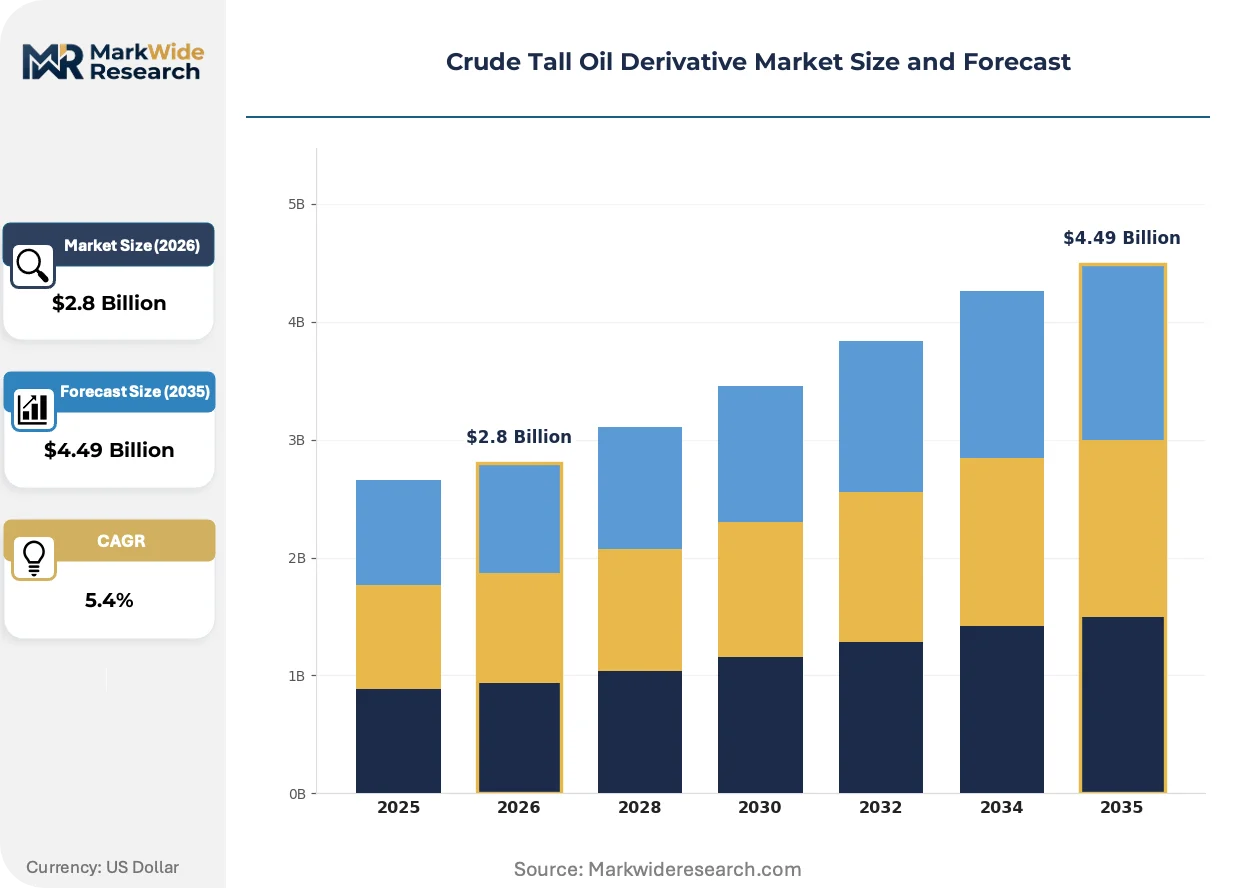
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fatty Acids, Rosin Acids, Tall Oil Pitch, Distillates Application: Adhesives, Coatings, Inks, Biodiesel End User: Pulp & Paper, Personal Care, Construction, Automotive Grade: Technical, Industrial, Food, Pharmaceutical |
| Companies Covered | Kraton Corporation, Forchem Oyj, Ingevity Corporation, SunPine AB, Les Dérives Résiniques Et Terpéniques, UPM, Neste Oyj, Mercer International Inc., Pine Chemical Group Oy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crude Tall Oil Derivative Market Strategic Shifts & Innovations
Process intensification and regulatory data automation are compressing qualification cycles while reshaping competitive access to European industrial supply chains for bio-based chemical feedstocks.
Membrane separation pretreatment of crude tall oil is displacing conventional acid refining steps in Nordic biorefineries. Adhesives manufacturers in Germany and the Netherlands are qualifying membrane-refined fatty acid grades for pressure-sensitive applications. This technology is displacing energy-intensive chemical purification routes while enabling producers to capture neutral compound fractions for higher-value specialty chemical streams.
REACH Annex XV dossier submissions for endocrine disruption screening are expanding data requirements for tall oil derivative importers. ECHA classification updates are triggering downstream handling protocol revisions across coatings and lubricant formulators. Nordic producers with existing IUCLID databases and toxicology packages are accelerating dossier updates while non-EU suppliers face registration delays that freeze market access.
Long-term offtake contracting is replacing spot market procurement among European biodiesel producers seeking supply security under tightening RED III compliance deadlines. Integrated pulp mill operators are capturing margin through direct sales relationships with fuel blenders, bypassing traditional merchant distributors. This pattern concentrates most visibly in the Baltic Sea region where Rauma and Kemi biorefineries anchor supply corridors to Rotterdam and Hamburg fuel terminals.
Crude Tall Oil Derivative Market Segmentation
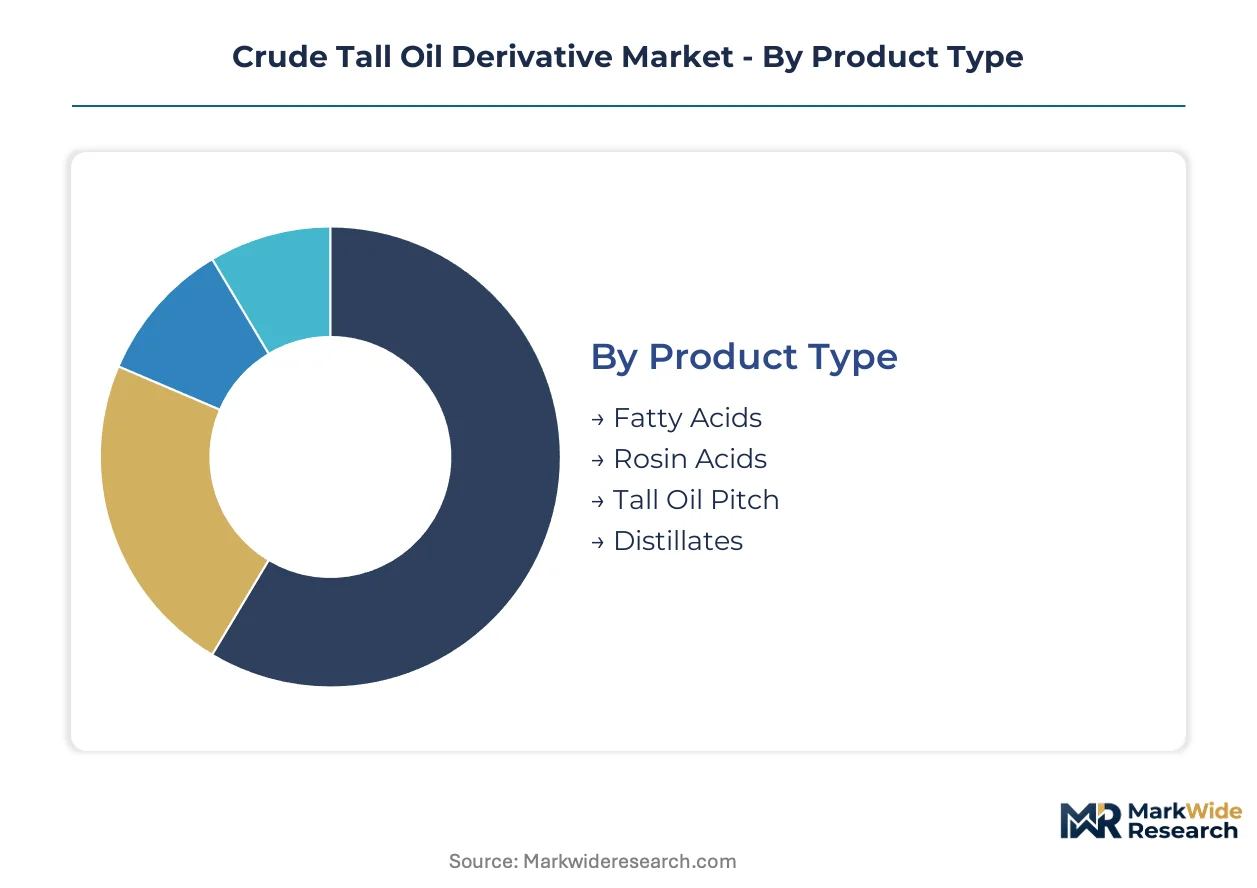
Segmentation in crude tall oil derivatives reveals where substitution pressure from petroleum alternatives and vegetable oil feedstocks concentrates competitive risk. Understanding these fault lines guides resource allocation across fractionation capacity and regulatory compliance investments.
Product Type:
Fatty acids face the most intense substitution pressure from palm fatty acid distillate and used cooking oil in biodiesel applications, while rosin acids defend margin through performance-locked adhesive specifications.
- Fatty Acids:Comprising oleic, linoleic, and linolenic acid fractions separated through vacuum distillation, these serve as renewable surfactant precursors and biodiesel feedstocks. Demand concentrates in EU fuel terminals around Rotterdam and Hamburg where RED III compliance deadlines lock in long-term offtake contracts for low-carbon intensity streams.
- Rosin Acids:Abietic and pimaric acid fractions deliver tackifying performance in pressure-sensitive adhesives and ink resins where petroleum rosin substitutes fail specification thresholds. German and Dutch formulators pay premium spreads for purified grades that meet ECHA classification requirements without downstream handling protocol revisions.
- Tall Oil Pitch:The heavy residual fraction remaining after fatty and rosin acid distillation, burned for boiler fuel or upgraded to binder applications in road construction.
- Distillates:Intermediate boiling range fractions capturing neutral compounds and unsaponifiables, routed to specialty chemical intermediates or further refined for lubricant base stocks.
Fatty acids anchor the volume base while rosin acids gain share at the steepest rate.
Application:
Application segmentation tracks how carbon certification schemes and performance specifications partition pricing power across end-use markets.
- Adhesives:Pressure-sensitive tape and hot-melt formulations consume purified rosin acid derivatives where tack and thermal stability specifications exclude petroleum alternatives. Nordic biorefineries in Rauma and Kemi direct specialty fractions to German automotive tier suppliers under ISCC-certified supply agreements.
- Biodiesel:Tall oil fatty acid methyl esters qualify as advanced biofuels under EU RED III frameworks, commanding premium pricing against conventional vegetable oil blends when carbon intensity scores fall below 20 gCO2eq/MJ.
- Coatings:Alkyd resins and epoxy curing agents incorporate tall oil fatty acids for bio-based content claims in architectural and industrial protective applications.
- Inks:Publication gravure and flexographic printing rely on rosin-derived resins for solvent release and gloss characteristics in high-speed press operations.
Biodiesel commands the steepest expansion trajectory while adhesives defend the most durable margin structure.
End User:
End user segmentation exposes how pulp mill integration decisions and construction cycle volatility transmit demand shocks upstream.
- Pulp & Paper:Integrated kraft mills consume crude tall oil internally or supply captive biorefineries, eliminating merchant market exposure for the largest Nordic producers.
- Construction:Tall oil pitch and fatty acid derivatives serve asphalt modifiers and concrete admixtures, tying demand to infrastructure spending cycles in Sweden and Finland.
- Personal Care:Refined fatty acids enter surfactant formulations for EU cosmetic applications subject to REACH Annex XV endocrine disruption screening protocols.
- Automotive:Pressure-sensitive adhesives for electric vehicle battery assembly and interior trim specify rosin acid derivatives with verified low-volatile organic compound profiles.
Pulp and paper controls captive supply while automotive specifications drive the fastest qualification activity.
Grade:
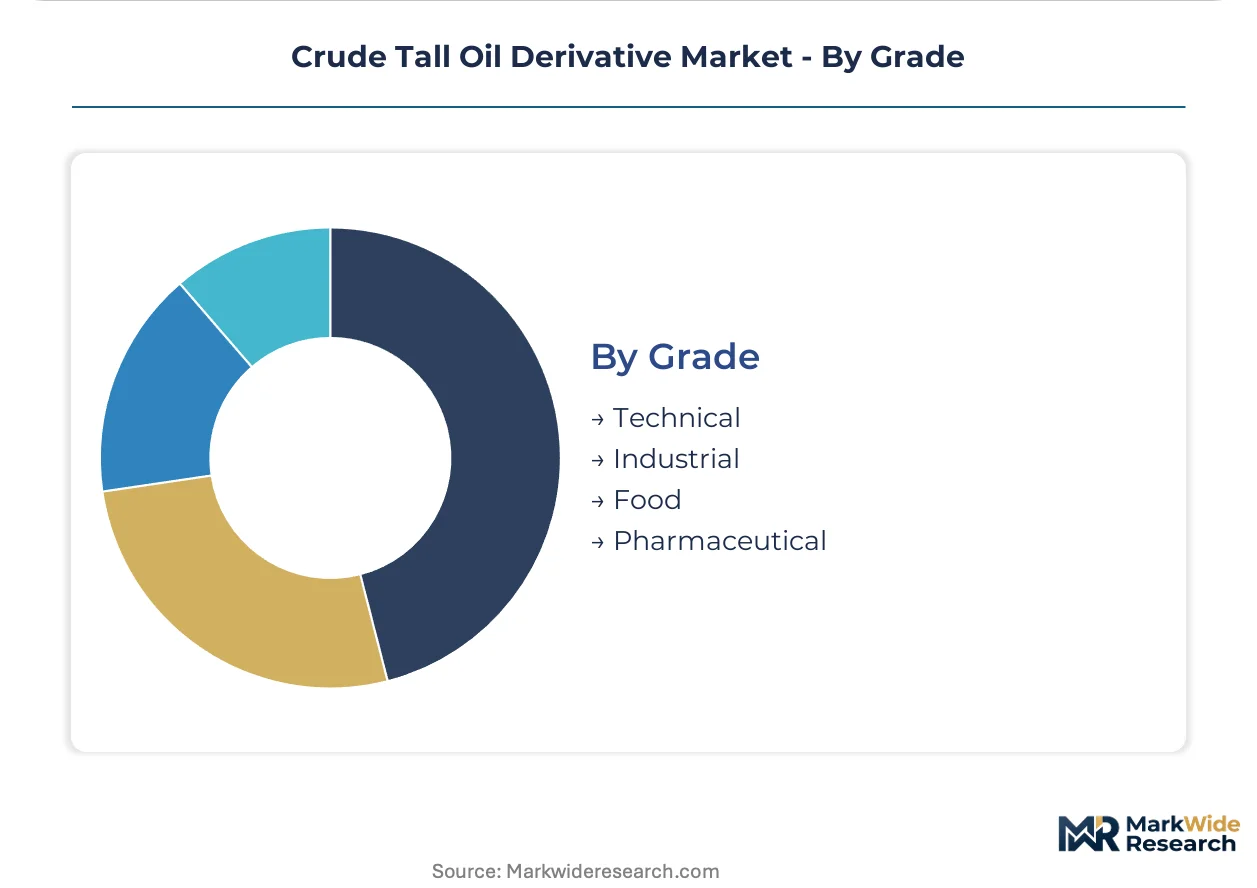
Grade segmentation reflects the regulatory burden gradient separating commodity industrial streams from qualified pharmaceutical and food grades.
- Technical:Unrefined or minimally processed fractions meeting basic industrial specifications for fuel and boiler applications, produced at lowest cost by merchant fractionators without dedicated compliance teams.
- Industrial:Standardized fatty acid and rosin acid cuts meeting REACH registration requirements for coatings, adhesives, and lubricant applications across EU member states.
- Food:Refined tall oil fatty acids meeting EFSA purity specifications for food contact materials and indirect food additive applications in packaging adhesives.
- Pharmaceutical:Highest purity grades requiring full toxicology dossiers and GMP manufacturing compliance, commanding significant price premiums for excipient and active pharmaceutical ingredient applications.
Industrial grade anchors the volume base while pharmaceutical grade captures the widest margin spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biodiesel blenders and adhesives formulators dominate procurement, clustering around Nordic pulp-to-chemicals corridors and German industrial hubs where carbon certification and REACH compliance filter supplier access.
Sweden
Pulp mill curtailments in Sundsvall and Örnsköldsvik constrain crude tall oil feedstock for SunPine AB and similar biorefineries. The Swedish Environmental Protection Agency enforces national carbon intensity benchmarks that exceed EU minimums. Gothenburg terminals channel tall oil fatty acid methyl esters to Rotterdam fuel blending facilities under ISCC-certified supply agreements.
Finland
Integrated kraft-to-chemicals complexes in Rauma and Kemi anchor European supply security for low-carbon biodiesel feedstocks. ECHA registration requirements under REACH Annex XV accelerate compliance investments by domestic fractionators. Finnish producers leverage captive crude tall oil streams from UPM and Metsä Group pulp operations to bypass merchant market volatility.
Germany
Adhesives manufacturers in Hamburg and Cologne qualify purified rosin acid derivatives for automotive pressure-sensitive applications. The German Federal Institute for Risk Assessment enforces EFSA-aligned food contact material standards for packaging adhesives. Ruhr region chemical distributors consolidate procurement through direct biorefinery relationships rather than spot market exposure.
United States
Specialty chemical demand in the Southeast and Great Lakes regions absorbs tall oil fatty acids for lubricant and surfactant applications. EPA renewable fuel standard pathways for biomass-based diesel create compliance arbitrage opportunities for importers. Gulf Coast refineries process imported crude tall oil derivatives when domestic kraft pulp byproduct availability tightens.
France
Ink resin formulators in Lyon and Paris specify rosin acid derivatives for high-speed gravure printing operations. ANSM and CNIL oversight of chemical handling protocols intersects with ECHA classification rules for tall oil derivative labeling. Bordeaux-area adhesives producers source through Rotterdam intermediaries when direct Nordic supply contracts face allocation constraints.
Crude Tall Oil Derivative Market Key Industry Players
Player mix skews toward integrated pulp-to-chemicals operators with captive feedstock access and specialized fractionators serving premium adhesive and coating grades. Market structure concentrates around Nordic biorefinery clusters where kraft mill proximity eliminates merchant crude tall oil procurement. Two strategic archetypes dominate: backward-integrated pulp producers capturing margin across the value chain, and independent refiners competing on fractionation technology and regulatory qualification speed. Competitive moves center on biorefinery capacity expansion and REACH dossier automation to compress product qualification cycles.
Within the integrated operator tier, Kraton Corporation and Forchem Oyj exemplify archetypes of multi-site refinery networks and single-location biorefinery excellence respectively. Ingevity Corporation occupies a position representing specialized rosin acid derivative capabilities for adhesives and coatings applications. These three entities anchor competitive dynamics through differentiated access to either captive pulp mill feedstock streams or purified fraction technology for performance-specified end uses.
| Leading Market Players |
|---|
| Kraton Corporation |
| Forchem Oyj |
| Ingevity Corporation |
| SunPine AB |
| Les Dérives Résiniques Et Terpéniques |
| UPM |
| Neste Oyj |
| Mercer International Inc. |
| Pine Chemical Group Oy |
| Others |
Cost & Logistics Intelligence
EU Green Deal carbon intensity thresholds gate both biorefinery qualification and price differentiation across tall oil derivative grades, concentrating premium pricing power with Nordic producers holding ISCC certification and verified low-carbon supply chains.
Pricing Analysis
Cost-plus contracts indexed to Rotterdam palm fatty acid distillate benchmarks dominate tall oil fatty acid procurement, with ISCC-certified streams commanding spreads against uncertified alternatives. Three-tier pricing structure across premium certified, standard industrial, and technical boiler fuel grades reflects carbon intensity scoring and REACH registration completeness. Pricing pressure stems from used cooking oil competition in biodiesel feedstock slots, compressing margins for non-certified tall oil fatty acid suppliers. Merchant processors show highest price sensitivity, while integrated pulp-to-chemicals operators absorb feedstock volatility through captive supply.
Supply Chain Analysis
Baltic Sea port congestion and container availability constraints on the Rauma-Rotterdam trade lane amplify lead time variability for German and Dutch formulators sourcing Nordic fractions. Supply concentrates in Finland, Sweden, and the United States, with Finnish biorefineries drawing from UPM and Metsä Group pulp operations. Raw material dependencies center on softwood kraft pulp byproduct availability, natural gas for vacuum distillation thermal input, and specialized fractionation catalysts. Single-source vulnerability runs through Sundsvall and Örnsköldsvik pulp mill curtailments. Distribution runs through direct biorefinery relationships with fuel terminals and adhesives formulators, bypassing traditional merchant distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of vacuum distillation process engineering expertise constrains capacity expansion and technology transfer, making qualified fractionation assets the critical bottleneck for market participation.
For Market Incumbents: Shield margin capture by deepening backward integration into captive kraft pulp feedstock streams and accelerating REACH Annex XV dossier automation to compress qualification cycles against emerging merchant processors. Prioritize ISCC certification maintenance as palm fatty acid distillate substitution threatens pricing power in biodiesel applications. For New Entrants and Emerging Players: ISCC-EU certification fast-track programs offer the most penetrable entry path for North American and Baltic producers seeking access to Rotterdam fuel terminal procurement. Target specialty rosin acid derivatives for German automotive pressure-sensitive adhesives where performance specifications exclude petroleum substitutes and ECHA compliance requirements filter competition. For Investors and Strategic Acquirers: RED III implementation deadlines reshape the acquisition landscape toward Nordic integrated biorefineries with verified low-carbon intensity scores and existing IUCLID toxicology databases. Five-to-ten-year viability hinges on regulatory qualification speed rather than scale alone. Watch for pulp mill capacity decisions in Sweden and Finland as the inflection signal for feedstock availability trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Pulp Operations | Captive crude tall oil supply eliminates merchant feedstock exposure for Rauma and Kemi biorefineries. |
| ISCC Certification Program Expansion | Verified supply chain traceability unlocks premium pricing tiers at Rotterdam biodiesel blending terminals. |
| Membrane Separation Technology Deployment | Energy-efficient pretreatment displaces conventional acid refining in Nordic fractionation facilities. |
| REACH Dossier Automation Investment | Accelerated ECHA registration timelines compress product qualification cycles against non-compliant importers. |
| Long-term Offtake Agreement Structuring | Direct biorefinery relationships with Hamburg and Cologne formulators replace spot market procurement volatility. |
Research Approach
A standing panel of biorefinery operations managers, biodiesel procurement leads at Rotterdam fuel terminals, adhesives formulators in Germany and the Netherlands, and ECHA regulatory affairs specialists provided ongoing calibration across primary interview rounds. Secondary validation drew from customs trade databases, SEC filings by listed pulp and chemical companies, ECHA IUCLID registration repositories, and Cefic sector reports. Bottom-up tall oil derivative volume estimates triangulated against top-down kraft pulp capacity and yield assumptions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, application end-use, grade tier, and regional production hub. CAGRs derived from regression analysis of historical price-volume relationships and forward-looking capacity expansion announcements. Industry-specific forecast inputs incorporated pulp mill curtailment schedules and EU RED III carbon intensity threshold trajectories.
Decision-makers should treat outputs as directional under base assumptions of sustained EU renewable fuel mandates and stable Nordic kraft pulp operating rates; material deviation would warrant model refresh. Specific risk factors include petroleum feedstock price collapse, REACH registration timeline extensions, and unplanned softwood pulp mill closures. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Isobutanol Market
Bulk Chemicals
2-Ethylhexanoyl Chloride Market
Bulk Chemicals
Manganese Sulfate Market
Bulk Chemicals
Hydrochloric Acid Electrolysis Market
Bulk Chemicals
Global Ferrous Sulfate Market
Bulk Chemicals
Phosphorus Market
Bulk Chemicals
Potassium Fluoborate Market
Bulk Chemicals
Global Naphthalene Derivatives Market
Bulk Chemicals
Granular Urea Market
Bulk Chemicals
Global Benzaldehyde Market
Bulk Chemicals
Bulk Molding Compounds Market
Bulk Chemicals
Furfural Market
Bulk Chemicals
Powdered Cellulose Market
Bulk Chemicals
Global Sodium Chloride Market
Bulk Chemicals
Global Semiconductor Grade Nitric Acid Market
Bulk Chemicals
Isobutene Market