
 Structural Composites Market | 2026-2036
Structural Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Structural Composites Market Intelligence
Automotive-grade structural qualification is unwinding legacy cost barriers that long confined carbon fiber to motorsport and aerospace niches. Toray Industries leverages its precursor-to-prepreg vertical integration to lock in aerospace-grade fiber supply. Owens Corning anchors North American glass fiber capacity for wind blade and construction applications. Hexcel Corporation differentiates through calibrated resin chemistry optimized for out-of-autoclave processing cycles.
Structural composites are engineered materials combining high-strength reinforcing fibers with polymer matrices to achieve specific stiffness-to-weight ratios exceeding 150 GPa per g/cm³ in aerospace grades. These systems replace metallic assemblies in load-bearing applications where mass reduction directly improves fuel efficiency or energy capture. Glass fiber dominates by volume across wind turbine blade spar caps and marine hull structures due to cost-efficient pultrusion throughput. Carbon fiber commands premium positioning in aerospace primary structures and sporting goods where prepreg layup delivers directional strength tailoring. Resin transfer molding is gaining share in automotive structural nodes as cycle-time compression challenges thermoset legacy economics.
FAA certification standards for composite damage tolerance and EPA emissions controls on styrene-based resin systems shape product development roadmaps and factory capital allocation. EU REACH substance restrictions and CE marking mechanical testing protocols govern market access for European structural fabricators and Tier-1 providers. Stakeholders must monitor evolving hydrogen storage pressure vessel standards and railcar crashworthiness mandates as emerging volume outlets beyond established aerospace and wind energy channels.
Market Dynamics
Automotive OEMs are compressing thermoset cycle times through out-of-autoclave resin transfer molding, forcing aerospace-grade suppliers to defend prepreg premiums against cost-engineered alternatives. This process substitution is redrawing qualification boundaries between performance tiers.
Growth Catalysts
- EU REACH substance restrictions:Chemical traceability mandates are accelerating qualified material supplier consolidation, locking in incumbent aerospace certification holders against unqualified entrants.
- Wind blade spar cap demand:Glass fiber pultrusion throughput in turbine manufacturing is absorbing excess roving capacity, stabilizing input costs for construction and marine hull applications.
- Automotive structural nodes:Resin transfer molding adoption in electric vehicle platforms is validating carbon fiber for crash-critical assemblies beyond motorsport niche volumes.
Market Restraints
- Acrylonitrile price volatility:Carbon fiber precursor costs swing with propylene feedstock markets, compressing margin visibility for mid-scale prepreg converters lacking backward integration.
- German supply chain concentration:Airbus Hamburg and Premium Aerotec anchor European aerostructure fabrication, creating single-source vulnerability for Tier-2 laminate suppliers.
- Thermoplastic welding limitations:Automated fiber placement with in-situ consolidation remains unproven for primary aerospace structures, constraining recycling pathway development.
Strategic Opportunities
- Hydrogen pressure vessel standards:Emerging ISO 19881 and regional safety protocols for Type IV composite tanks are opening filament-wound carbon fiber demand beyond established aerospace channels.
- Railcar crashworthiness mandates:European EN 15227 and comparable structural energy absorption rules are qualifying glass-reinforced sandwich panels for mass transit interior applications.
- Prepreg-to-fabricator direct distribution:Digital inventory platforms are collapsing distributor layers, enabling small-batch aerospace job shops to access aerospace-grade material without volume commitments.
Industry Challenges
- Certified NDI technician scarcity:FAA-approved ultrasonic and thermography inspectors for composite damage tolerance verification command wage premiums that constrain MRO capacity expansion.
- Multi-material joining complexity:Dissimilar coefficient of thermal expansion between carbon fiber and aluminum substructures demands specialized adhesive qualification protocols that extend OEM approval cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Structural Composites Market |
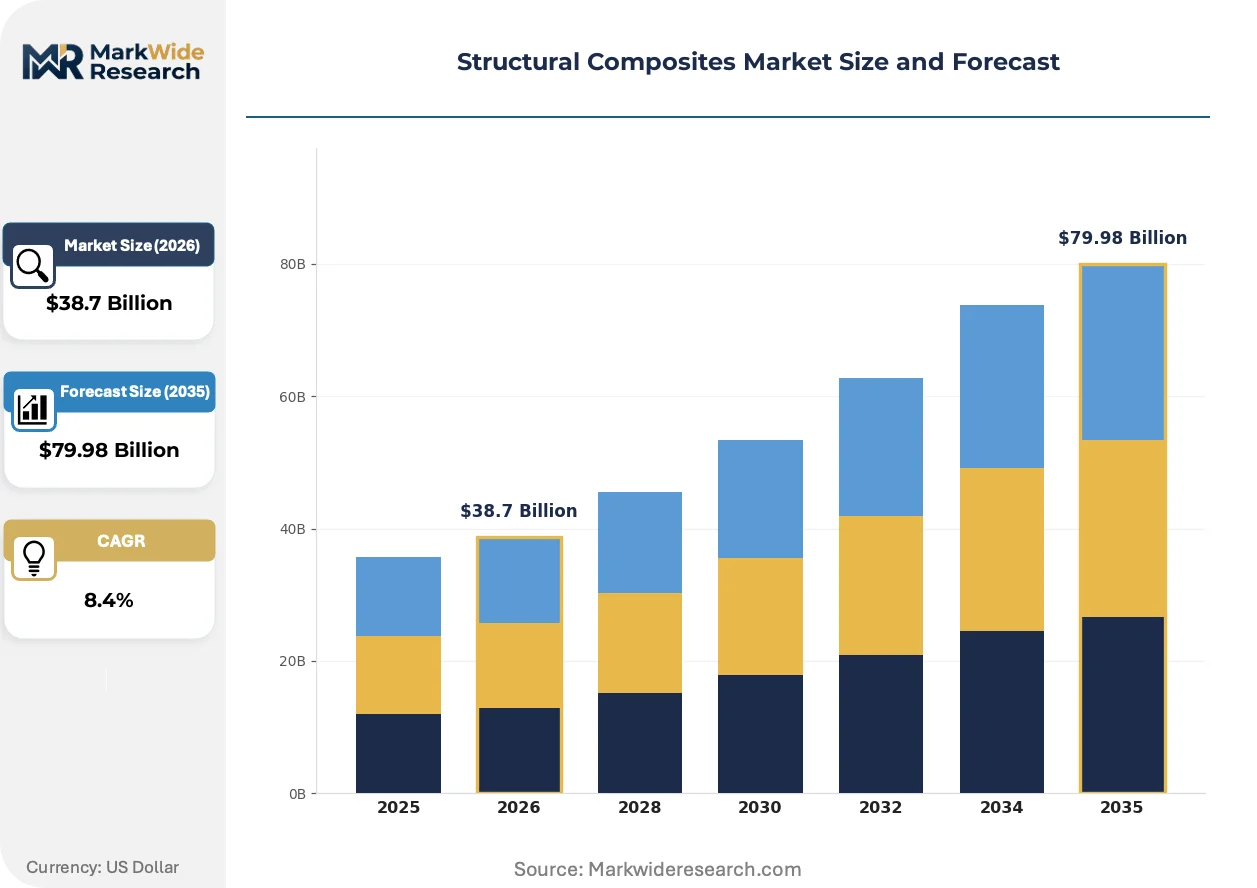
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Fiber, Glass Fiber, Aramid Fiber, Basalt Fiber Technology: Prepreg, Pultrusion, Resin Transfer Molding, Vacuum Infusion Application: Aerospace, Marine Vessels, Wind Turbines, Sporting Goods End User: OEM Manufacturers, Aftermarket Suppliers, Tier-1 Providers, Structural Fabricators |
| Companies Covered | Solvay, Mitsubishi Chemical Holdings Corporation, Toray Industries, Owens Corning, Gurit Holding, Hexcel Corporation, Teijin Limited, Huntsman Corporation, SGL Carbon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Structural Composites Market Strategic Shifts & Innovations
Process automation and regulatory chemistry controls are bifurcating the supply base between mass-market converters and certified aerospace specialists. Material qualification protocols are becoming the primary competitive moat.
Thermoplastic unidirectional tape systems are fragmenting the prepreg landscape by enabling automated fiber placement with in-situ consolidation, eliminating autoclave bottlenecks. Automotive Tier-1s are piloting these systems for bumper beam and seat pan applications at cycle times incompatible with thermoset curing. The technology is fragmenting equipment vendor hierarchies by demanding new press and consolidation tooling architectures.
EU REACH Annex XIV authorization requirements for styrene-based unsaturated polyester resins are forcing marine and construction fabricators toward vinyl ester and epoxy alternatives. Industrial consequence includes reformulation costs and supply chain requalification for open-mold operations. German and Dutch boatbuilders are responding fastest, with Nordic markets lagging due to smaller scale and limited regulatory enforcement resources.
Buyer consolidation among wind turbine OEMs is compressing blade supplier margins and forcing composite converters toward long-term fixed-price resin contracts. Vestas and Siemens Gamesa procurement teams are unbundling spar cap fabrication from full blade assembly, creating standalone carbon fiber preform suppliers. This pattern is most visible in Denmark and Spain, where blade manufacturing clusters face the most concentrated OEM purchasing power.
Structural Composites Market Segmentation
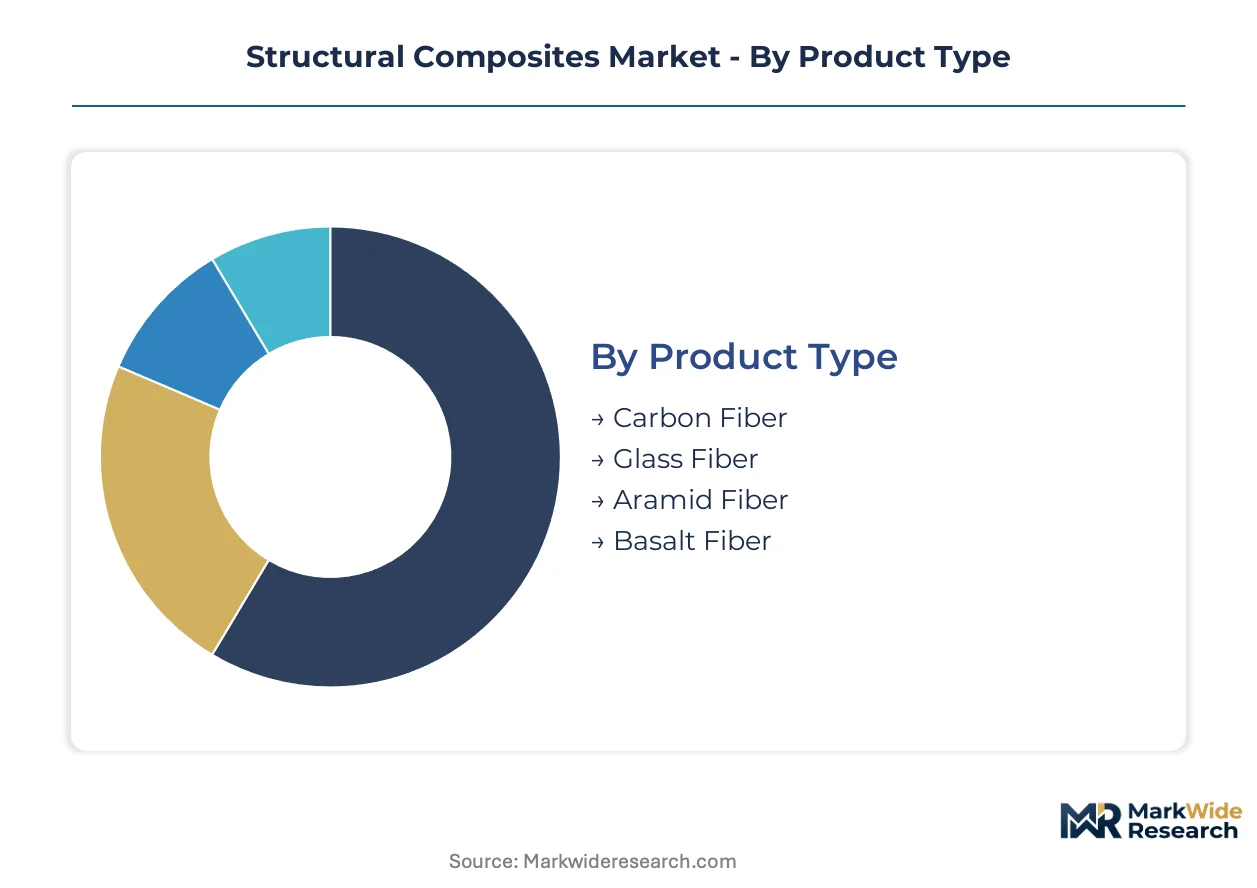
Structural composites demand fragments across fiber grades, processing technologies, and qualification tiers that dictate channel access. OEM procurement teams route aerospace-grade carbon fiber through certified prepreg distributors while construction-grade glass fiber flows direct to pultrusion houses.
Product Type:
Carbon fiber commands aerospace and premium automotive channels through prepreg qualification protocols. Glass fiber saturates wind energy and construction markets via high-throughput pultrusion lines. Aramid fiber and basalt fiber occupy specialized protective and corrosion-resistant niches with limited distributor overlap.
- Carbon Fiber:PAN-based tow systems deliver modulus values exceeding 230 GPa for primary aerostructures. Airbus Hamburg and Boeing Charleston anchor demand concentration, with FAA damage tolerance certification gating supplier entry. Acrylonitrile feedstock volatility compresses margin visibility for non-integrated converters.
- Glass Fiber:E-glass and S-glass rovings achieve 70-85 GPa modulus at cost points enabling wind blade spar cap scaling. Vestas blade factories in Denmark and Siemens Gamesa facilities in Spain absorb volume through direct mill relationships, bypassing traditional distribution layers.
- Aramid Fiber:Para-aramid reinforcements serve ballistic protection and high-tension marine rigging applications with specialized handling requirements.
- Basalt Fiber:Volcanic rock-derived filaments offer intermediate modulus and chemical resistance for rebar and high-temperature insulation markets.
Glass fiber dominates installed base. Carbon fiber is where expansion concentrates.
Technology:
Process selection locks manufacturers into capital equipment footprints and qualification timelines that reshape competitive positioning. Thermoset legacy systems face cycle-time pressure from emerging thermoplastic alternatives.
- Prepreg:Refrigerated B-stage resin systems enable precise fiber volume fraction control for aerospace primary structures. Autoclave curing requirements constrain throughput and concentrate supply among Hexcel, Toray, and Solvay qualification holders.
- Pultrusion:Continuous resin bath impregnation pulls reinforced profiles through heated dies at line speeds exceeding 2 meters per minute. Owens Corning and Jushi Group anchor roving supply into construction and wind energy channels.
- Resin Transfer Molding:Closed-mold injection processes compress automotive structural node cycle times toward thermoplastic competitiveness.
- Vacuum Infusion:Single-sided tooling with membrane vacuum pressure suits marine hull and architectural panel fabrication.
Prepreg commands qualification premiums. Resin transfer molding is climbing the fastest as automotive volumes validate process economics.
Application:
End-use performance requirements stratify supply chains across damage tolerance, environmental exposure, and aesthetic finish specifications. Aerospace and marine channels demand certified material traceability absent from construction markets.
- Aerospace:Wing spars, fuselage barrels, and control surfaces require T800H and IM7 fiber grades with documented batch testing. FAA airworthiness directives and EASA certification protocols govern every laminate ply.
- Wind Turbines:Glass fiber pultruded spar caps and carbon fiber shear webs scale with turbine nameplate capacity expansion. Blade OEMs unbundle fabrication steps, creating standalone preform supplier tiers.
- Marine Vessels:Hull laminates and superstructures balance styrene emission controls against open-mold economics.
- Sporting Goods:Bicycle frames, hockey sticks, and golf shafts absorb prepreg offcuts and lower-modulus carbon fiber grades.
Wind turbines anchor volume demand. Aerospace is where value expansion concentrates.
End User:
Procurement authority and technical specification control vary sharply across the value chain, with OEMs dictating material selection and Tier-1s managing process conversion risk.
- OEM Manufacturers:Airbus, Boeing, and automotive platforms specify qualified material grades and approved supplier lists, capturing specification power.
- Tier-1 Providers:Premium Aerotec and Spirit AeroSystems convert prepreg into aerostructure assemblies, bearing laminate fabrication risk.
- Structural Fabricators:Job shops access aerospace-grade material through digital inventory platforms collapsing traditional distributor markups.
- Aftermarket Suppliers:MRO channels for composite repair patches and replacement panels face certified NDI technician scarcity constraints.
OEM manufacturers dictate material selection. Tier-1 providers are where margin pressure concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Structural composites trade flows reflect aerospace certification concentration and wind energy manufacturing clustering. Export-import balances favor countries with integrated precursor-to-prepreg supply chains and established OEM aerostructure procurement relationships.
United States
Boeing Charleston and Gulfstream Savannah anchor carbon fiber demand for commercial and business jet primary structures. FAA damage tolerance certification protocols govern material qualification timelines for domestic suppliers. The Pacific Northwest hosts Toray Industries' precursor operations feeding Boeing's 787 fuselage barrel production.
Germany
Airbus Hamburg and Premium Aerotec concentrate European aerostructure fabrication demand for T800H and IM7 fiber grades. EU REACH Annex XIV chemical authorization requirements accelerate qualified material supplier consolidation against unqualified entrants. Bavaria's Munich-Augsburg corridor hosts SGL Carbon's carbon fiber operations serving automotive and aerospace channels.
China
COMAC C919 narrowbody certification drives domestic carbon fiber qualification for wing and fuselage applications. MIIT industrial material standards and GB certification protocols shape local supplier entry requirements. The Yangtze River Delta clusters wind blade manufacturing around Vestas and Goldwind facilities absorbing glass fiber roving volume.
Japan
Toray Industries, Teijin Limited, and Mitsubishi Chemical Holdings anchor global PAN-based carbon fiber precursor supply. METI strategic material initiatives support aerospace-grade fiber capacity expansion against Korean and Chinese competition. The Nagoya-Toyohashi industrial corridor concentrates prepreg conversion serving Boeing and Airbus Tier-1 networks.
Spain
Siemens Gamesa blade factories in Zamora and Burgos absorb carbon fiber shear web and glass fiber spar cap preforms. EU Green Deal renewable energy targets accelerate wind turbine nameplate capacity expansion requiring composite structural scaling. The Basque Country hosts specialized marine fabricators transitioning from styrene-based polyester toward REACH-compliant vinyl ester systems.
Structural Composites Market Key Industry Players
Listed leaders compete with private specialists across qualification tier and fiber grade integration depth. The vendor base stratifies between aerospace-certified prepreg incumbents and construction-grade glass fiber volume players. Three archetypes dominate: backward-integrated precursor-to-prepreg operators, specialized carbon fiber converters, and diversified glass fiber multinationals. Capacity expansion and strategic partnerships represent the dominant competitive moves as automotive OEMs validate resin transfer molding economics.
Within the backward-integrated tier, Toray Industries and Mitsubishi Chemical Holdings exemplify captive precursor control securing aerospace-grade fiber supply against acrylonitrile volatility. Owens Corning occupies a position among scale-driven glass fiber multinationals anchoring North American wind blade and construction throughput. Hexcel Corporation represents the specialized prepreg converter archetype, differentiated through calibrated resin chemistry optimized for out-of-autoclave processing cycles.
| Leading Market Players |
|---|
| Solvay |
| Mitsubishi Chemical Holdings Corporation |
| Toray Industries |
| Owens Corning |
| Gurit Holding |
| Hexcel Corporation |
| Teijin Limited |
| Huntsman Corporation |
| SGL Carbon |
| Others |
Cost & Logistics Intelligence
Resin transfer molding displacement of thermoset prepreg in automotive crash structures simultaneously redraws supply geography toward German and Chinese automotive clusters and compresses pricing premiums for aerospace-grade fiber grades. This process substitution forces carbon fiber suppliers to defend margin structures against cost-engineered alternatives while redirecting capacity investments toward filament winding for hydrogen pressure vessels.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in structural composites. Price differentiation separates FAA-certified prepreg batches with full traceability documentation from construction-grade glass fiber sold on modulus specifications alone. Pricing pressure stems from Vestas and Siemens Gamesa procurement teams unbundling blade fabrication steps and forcing fixed-price resin contracts on Tier-2 converters. Wind energy buyers exhibit highest price sensitivity due to direct mill relationships bypassing distribution markups, while aerospace OEMs accept premiums for damage tolerance certification.
Supply Chain Analysis
Acrylonitrile feedstock transit through Rotterdam and Singapore refining hubs underwrites carbon fiber precursor economics for PAN-based tow production. Geographic supply concentration centers on Japan, the United States, and Germany for aerospace-grade fiber, with China expanding domestic capacity for COMAC C919 qualification. Raw material dependencies include propylene derivatives, epoxy resin systems, and specialized sizing chemistries. Single-source vulnerability concentrates in Airbus Hamburg and Premium Aerotec aerostructure fabrication, creating chokepoint risk for European Tier-2 laminate suppliers. Distribution runs through certified prepreg distributors for aerospace channels, while construction-grade glass fiber flows direct to pultrusion houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Structural composites sit at a process disruption inflection as thermoplastic automated fiber placement with in-situ consolidation threatens thermoset autoclave economics, accelerated by EU REACH chemical authorization timelines compressing qualified supplier windows.
For Market Incumbents: Fortify aerospace certification moats through accelerated FAA damage tolerance protocol investment and captive precursor capacity expansion in South Carolina and Nagoya corridors. Resin transfer molding adoption by automotive OEMs threatens prepreg premium structures, demanding out-of-autoclave resin chemistry differentiation to defend margin position against cost-engineered alternatives. For New Entrants and Emerging Players: Lead with hydrogen pressure vessel filament winding as the most penetrable white-space channel beyond established aerospace procurement relationships. Railcar crashworthiness mandates under EN 15227 offer secondary entry point for glass-reinforced sandwich panel qualification. Target digital inventory platform partnerships to access small-batch aerospace job shops without volume commitment barriers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors backward-integrated precursor-to-prepreg operators with captive acrylonitrile supply. Long-term viability hinges on qualification tier positioning rather than commodity volume scale. Watch ISO 19881 hydrogen tank standard finalization as signal for filament-wound carbon fiber demand inflection beyond aerospace channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Toray Industries' captive PAN supply locks in aerospace-grade fiber margins against acrylonitrile volatility. |
| Out-of-Autoclave Resin Chemistry Development | Hexcel Corporation's calibrated formulations defend prepreg premiums against resin transfer molding cost pressure. |
| Digital Inventory Platform Partnership | Direct prepreg-to-fabricator distribution collapses traditional markups for small-batch aerospace job shops. |
| Hydrogen Pressure Vessel Certification Investment | Filament-wound carbon fiber qualification under ISO 19881 opens demand beyond established aerospace channels. |
| EU REACH Compliant Formulation Transition | German boatbuilders' shift from styrene-based polyester to vinyl ester systems accelerates supply chain requalification. |
Research Approach
A spread of perspectives from aerospace procurement directors, wind blade manufacturing engineers, automotive Tier-1 composite specialists, and certified NDI technicians converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through FAA airworthiness directives, EASA certification protocols, EU REACH Annex XIV substance restrictions, and SEC filings from listed fiber and prepreg manufacturers. Bottom-up volume modeling across fiber grades, processing technologies, and application channels triangulated against top-down OEM procurement spend analysis.
Segmentation dimensions modeled include fiber type, manufacturing process technology, qualification tier, end-use application, and geographic production cluster across the projection horizon. CAGRs were derived from regression analysis of historical capacity expansion announcements correlated with OEM platform launch timelines. Industry-specific forecast inputs incorporated wind turbine nameplate capacity expansion trajectories and hydrogen storage infrastructure deployment scenarios.
Underlying assumptions cover continued FAA-EASA regulatory harmonization on composite damage tolerance, with deviation risk concentrated in acrylonitrile feedstock price volatility and thermoplastic welding technology maturation timelines. Practitioners should keep alternative scenarios live as automotive OEM resin transfer molding adoption rates and EU chemical authorization enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
FRP Reactor Market
Composite Materials
Scrim Reinforced Films Market
Composite Materials
Automotive Carbon Fiber Materials Market
Composite Materials
Global Carbon Fiber Reinforced Polymer Market
Composite Materials
Pultrusion Market
Composite Materials
Composites Testing Market
Composite Materials
Europe Wood-Plastic Composite (WPC) Market
Composite Materials
Glass Fiber Reinforced Plastic (GFRP) Market
Composite Materials
Composite Coatings Market
Composite Materials
Non-Honeycomb Sandwich Panel Core Materials Market
Composite Materials
Global Carbon Felt and Graphite Felt Market
Composite Materials
North America Molded FRP Grating Market
Composite Materials
Tow Prepreg Market
Composite Materials
Thermoset Composites Market
Composite Materials
Case Material Market
Composite Materials
Fiber Reinforced Composite Tapes Market