
 Flame Retardant Polyester Resins Market | 2026-2036
Flame Retardant Polyester Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Flame Retardant Polyester Resins Market Analytics
A capital-intensity divergence between integrated petrochemical producers and specialty compounders is reorganizing competitive tiers in flame retardant polyester resins. BASF SE leverages backward integration into phosphorus intermediates to secure feedstock cost advantages. Polynt Composites USA Inc. anchors its position through dedicated unsaturated resin production lines serving North American building material fabricators. Scott Bader differentiates via long-fiber reinforced formulations for transportation OEMs requiring UL 94 V-0 certification.
Flame retardant polyester resins are thermoset or thermoplastic polymers incorporating halogenated, phosphorus, or mineral flame retardant additives, typically processed via bulk molding or pultrusion to achieve limiting oxygen indices above 28 percent for fire-critical applications. Reinforced resins dominate value generation due to their substitution of metal components in aerospace interior panels where weight reduction intersects with FAA fireworthiness standards. Unsaturated resins represent the fastest-expanding product category as marine structure builders adopt low-styrene emission grades to satisfy MARPOL workplace exposure limits. Electrical components application margins concentrate in high-voltage connector housings where CTI tracking resistance requirements exceed 600 volts.
EPA regulations on persistent organic pollutants constrain brominated additive formulations in US-manufactured automotive interiors, while REACH authorization procedures under ECHA progressively restrict decabromodiphenyl ether across European electrical component supply chains. China's GB 8624 building material fire classification standard, enforced by the Ministry of Emergency Management, mandates B1-grade combustion performance for public structure polyester composites. Stakeholders must monitor regulatory divergence between phosphorus-based and mineral hydrate formulation pathways as regional fire safety frameworks harden compliance thresholds without harmonization.
Market Dynamics
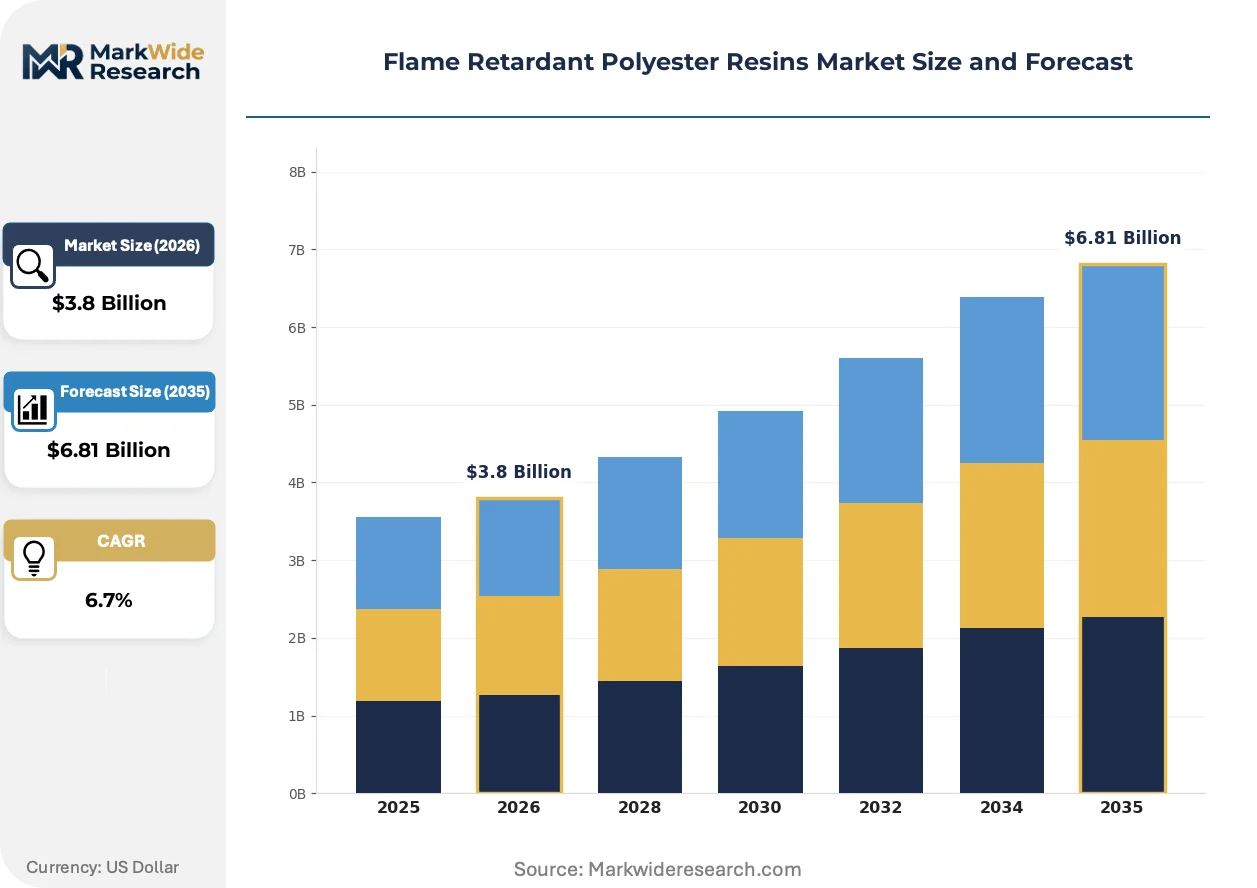
Phosphorus-based chemistry is displacing legacy halogenated formulations as REACH authorization procedures and China's GB 8624 enforcement harden compliance thresholds without harmonization, forcing compounders to rebuild formulation portfolios around mineral hydrate and intumescent additive systems.
Growth Catalysts
- High-rise construction mandates:China's Ministry of Emergency Management enforces B1-grade combustion performance for public structure polyester composites, concentrating resin procurement in curtain wall and cladding applications.
- REACH authorization pressure:ECHA's progressive restrictions on decabromodiphenyl ether redirect electrical component supply chains toward phosphorus-based alternatives.
- Pultrusion automation:Continuous fiber reinforcement processing achieves limiting oxygen indices above 28 percent for aerospace interior panels requiring FAA fireworthiness certification.
Market Restraints
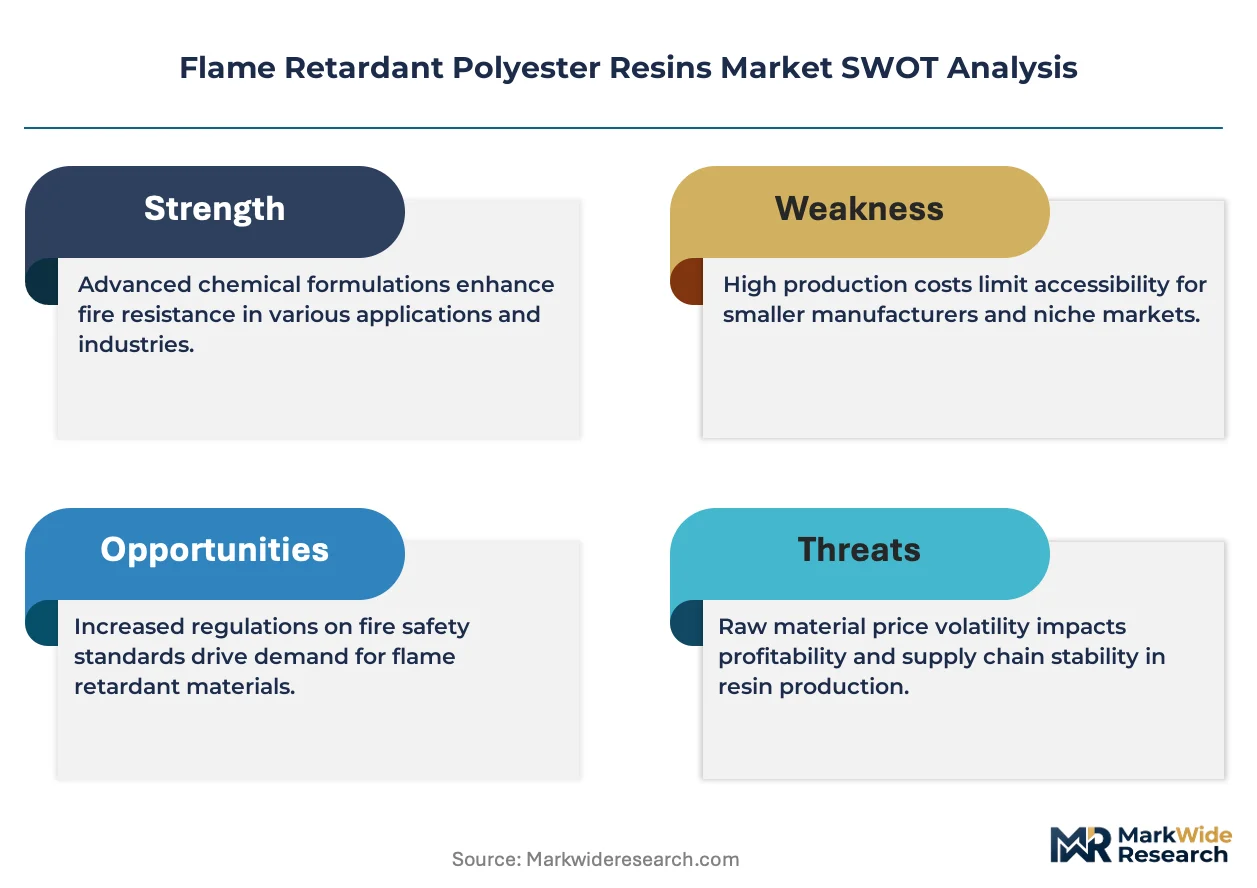
- Phosphorus intermediate concentration:Integrated petrochemical producers control upstream supply of phosphorus pentoxide and phosphoric acid esters, constraining specialty compounder margins.
- Mineral hydrate loading limits:Aluminum hydroxide and magnesium hydroxide formulations require 50-65 percent filler content, degrading mechanical properties in thin-wall electrical housings.
- EPA persistent organic pollutant constraints:Brominated additive restrictions on US-manufactured automotive interiors force dual-track formulation development for transatlantic supply chains.
Strategic Opportunities
- Marine structure low-styrene grades:MARPOL workplace exposure limits are accelerating unsaturated resin adoption in shipbuilding and offshore platform construction.
- Long-fiber reinforced transportation:UL 94 V-0 certified formulations enable metal substitution in rail interior panels and commercial vehicle engine compartments.
- CTI 600V+ electrical housing:High-voltage connector applications for electric vehicle powertracks create specification premiums above standard flame retardant grades.
Industry Challenges
- Formulation requalification timelines:OEMs require 18-24 month certification cycles for new flame retardant systems, locking compounders into existing additive portfolios.
- Dual-carbon compliance integration:China's MEE enforcement of embodied carbon reporting conflicts with energy-intensive phosphorus intermediate production, forcing process redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flame Retardant Polyester Resins Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unsaturated Resins, Thermoplastic Resins, Reinforced Resins, Casting Resins Application: Building Materials, Automotive Interiors, Electrical Components, Marine Structures End User: Construction, Transportation, Aerospace, Electronics Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Ashland Global Holdings Inc., BASF SE, Polynt Composites USA Inc., Covestro AG, Ineos Composites, Scott Bader, Huntsman Corporation, Mitsubishi Chemical Corporation, Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flame Retardant Polyester Resins Market Evolving Landscape
Reactive phosphorus monomer incorporation is displacing additive blending as the dominant flame retardancy architecture, enabling permanent polymer-bound protection without leaching or migration risks in long-service applications.
Intumescent coating-compatible resin grades are fragmenting the specification landscape as architects specify passive fire protection systems combining inherent polymer flame retardancy with external intumescent layers for structural steel encasement. Building material fabricators in Germany and France are qualifying these hybrid systems for Euroclass B-s1,d0 ratings. The resulting formulation complexity is compressing margins for unsaturated polyester producers lacking in-house fire testing laboratories.
REACH authorization procedures under ECHA are systematically removing brominated diphenyl ethers from electrical component supply chains, compelling compounders to revalidate CTI tracking resistance and glow-wire ignition properties with phosphorus alternatives. Wire and cable housing manufacturers face 12-18 month requalification cycles with appliance OEMs. The regulatory friction is most acute in small household appliance supply chains where incumbent brominated systems previously dominated.
Specification consolidation among tier-one automotive OEMs is compressing supplier bases as Volkswagen, Stellantis, and Ford Motor Company harmonize interior material flammability standards across global vehicle platforms. Tier-two compounders must now support multi-continent technical service from single formulation approvals. The behavioral shift is most visible in seating and dashboard substrate procurement where regional specification variance previously sustained fragmented supply relationships.
Flame Retardant Polyester Resins Market Segmentation
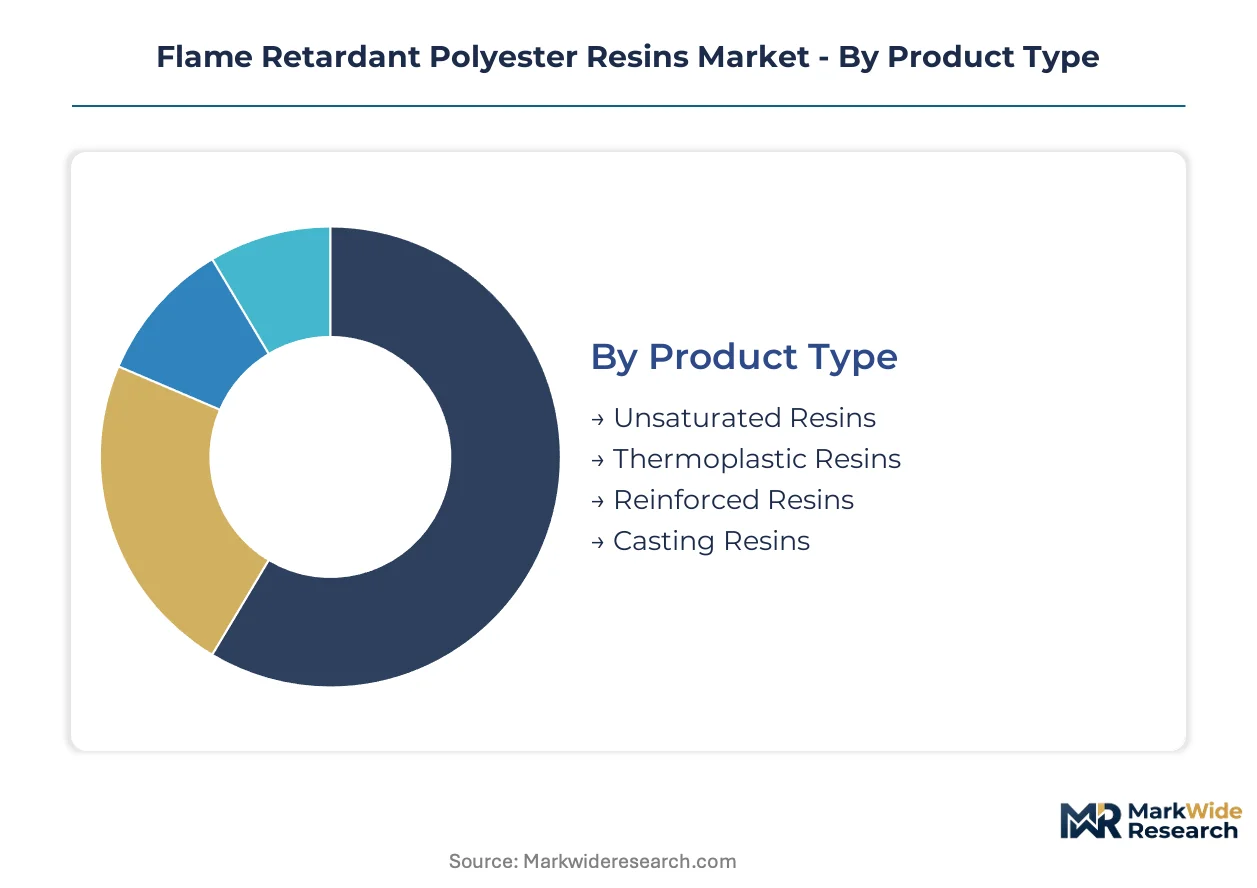
Flame retardant polyester resins fragment across four structural dimensions that determine pricing power and technical service intensity. Product chemistry governs raw material exposure, while application verticals dictate certification complexity and end-user concentration shapes channel economics.
Product Type:
Margin pools concentrate in reinforced and specialized unsaturated grades where formulation expertise creates defensible pricing.
- Reinforced Resins:Long-fiber or glass-reinforced thermosets achieve limiting oxygen indices above 28 percent through continuous fiber architectures. Aerospace interior panel fabricators in Germany and Japan specify these grades for FAA fireworthiness compliance, with procurement concentrating among tier-one airframe subcontractors.
- Unsaturated Resins:Low-styrene emission formulations serve marine structure builders seeking MARPOL workplace exposure compliance. China's shipyards and offshore platform constructors in the Bohai Rim are accelerating procurement of these grades as state-owned yards modernize emission controls.
- Thermoplastic Resins:Halogen-free phosphorus-modified polyesters processed via injection molding for thin-wall electrical housings.
- Casting Resins:Encapsulation-grade systems for high-voltage transformer and capacitor potting applications.
The dominant share belongs to reinforced resins, while unsaturated resins are closing the gap fastest.
Application:
Volume concentrates in building materials, though specification premiums concentrate in electrical and transportation applications with multi-certification requirements.
- Building Materials:Curtain wall cladding and structural composites face China's GB 8624 B1-grade combustion mandates enforced by the Ministry of Emergency Management. High-rise developers in Shanghai and Shenzhen are consolidating procurement around halogen-free formulations to satisfy both fire performance and dual-carbon reporting requirements.
- Electrical Components:High-voltage connector housings and wire insulation demand CTI tracking resistance above 600 volts combined with UL 94 V-0 certification. Electric vehicle powertrack applications in South Korea and Germany command specification premiums due to simultaneous thermal cycling and flame retardancy requirements.
- Automotive Interiors:Dashboard substrates and seating components face EPA persistent organic pollutant constraints on brominated additives.
- Marine Structures:Hull laminates and superstructure panels adopt low-styrene unsaturated grades for MARPOL compliance.
Building materials generate the largest volume base, though electrical components are expanding most quickly.
End User:
Customer sophistication varies sharply, with aerospace and electronics demanding 18-24 month qualification cycles that lock in supplier relationships.
- Construction:General contractors and specialty fabricators procure standard-grade resins through distributors, with China's state-mandated high-rise standards concentrating demand among SOE-backed developers.
- Electronics:Appliance OEMs and industrial control manufacturers require revalidated CTI and glow-wire properties as REACH authorization removes brominated alternatives.
- Transportation:Tier-one automotive suppliers harmonize interior material standards across Volkswagen, Stellantis, and Ford platforms.
- Aerospace:Airframe manufacturers and interior integrators specify long-fiber reinforced grades with FAA fireworthiness certification.
Construction absorbs the highest absolute volume, while electronics is gaining share fastest.
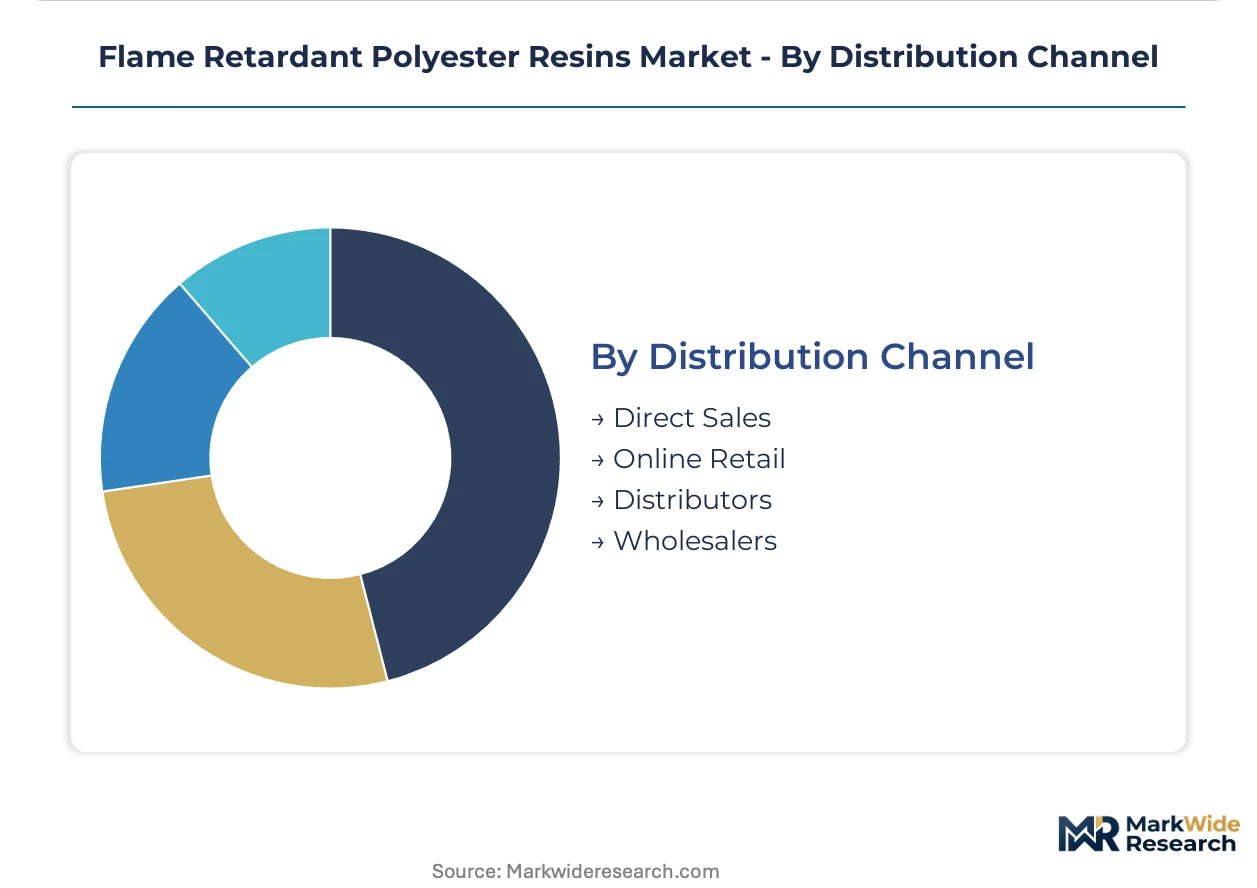
Distribution Channel:
Channel selection tracks order size and technical service requirements, with direct relationships dominating specification-grade procurement.
- Direct Sales:Integrated petrochemical producers and specialty compounders serve automotive and aerospace OEMs through dedicated technical service teams.
- Distributors:Regional stocking distributors support building material fabricators with just-in-time delivery and formulation customization.
- Online Retail:Standard-grade unsaturated resins for small marine repair yards and artisan composite shops.
- Wholesalers:Bulk volume handlers serving construction contractors with price-sensitive commodity grades.
Direct sales commands the highest value share, while distributors are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese compounders command pricing premiums on phosphorus-modified grades while US producers absorb compliance costs from EPA persistent organic pollutant constraints, creating a transatlantic margin asymmetry that favors feedstock-integrated Asian suppliers.
China
State-owned developers in Shanghai and Shenzhen are consolidating procurement around halogen-free formulations for high-rise curtain wall applications. The Ministry of Emergency Management enforces GB 8624 B1-grade combustion standards across public structures. Yangtze River Delta resin compounders are expanding phosphorus intermediate capacity to serve Bohai Rim shipyards adopting low-styrene unsaturated grades.
United States
Dashboard substrate manufacturers face EPA restrictions on brominated additives in automotive interiors, forcing dual-track formulation development. Tier-one automotive suppliers are harmonizing flammability standards across Volkswagen, Stellantis, and Ford platforms. Southeast building material fabricators qualify intumescent-compatible resin grades for structural steel encasement projects.
Germany
ECHA REACH authorization procedures are systematically removing decabromodiphenyl ether from electrical component supply chains. Wire and cable housing manufacturers face extended requalification cycles with appliance OEMs. Bavarian aerospace interior panel fabricators specify long-fiber reinforced grades for FAA fireworthiness compliance.
Japan
Electric vehicle powertrack applications in Kansai and Chubu regions command specification premiums for CTI 600V+ connector housings. METI standards intersect with OEM thermal cycling requirements. Tokyo-based electronics manufacturers are revalidating glow-wire ignition properties as brominated alternatives phase out.
South Korea
Busan-Ulsan shipbuilders are accelerating procurement of MARPOL-compliant low-styrene unsaturated resins for hull laminate applications. The Seoul Capital Area concentrates electric vehicle component manufacturing demanding simultaneous flame retardancy and thermal management. Domestic compounders are investing in reactive phosphorus monomer capabilities.
Flame Retardant Polyester Resins Market Competitive Landscape
Concentration sits with integrated petrochemical producers controlling upstream phosphorus intermediate supply. Specialty compounders occupy mid-tier positions through dedicated production lines and formulation expertise. Three archetypes dominate: feedstock-integrated multinationals, regional unsaturated resin specialists, and long-fiber reinforced transportation-focused compounders. Competitive moves center on backward integration into phosphorus pentoxide supply and geographic expansion through technical service teams.
Among European-based chemical conglomerates, BASF SE exemplifies feedstock-integrated positioning through captive phosphorus intermediate production. Covestro AG and Huntsman Corporation occupy positions within the specialty polymer tier, with geographic suffixes indicating German and US origins respectively. Scott Bader, a UK-registered entity, represents the specialist archetype focused on reinforced formulation segments.
| Leading Market Players |
|---|
| Ashland Global Holdings Inc. |
| BASF SE |
| Polynt Composites USA Inc. |
| Covestro AG |
| Ineos Composites |
| Scott Bader |
| Huntsman Corporation |
| Mitsubishi Chemical Corporation |
| Wacker Chemie AG |
| Others |
Value Network & Pricing Analysis
REACH authorization procedures on decabromodiphenyl ether simultaneously gate supplier qualification and stratify price tiers, as compounders lacking phosphorus intermediate integration absorb requalification costs while feedstock-integrated producers extract certification premiums from electrical component OEMs facing 18-24 month approval cycles.
Pricing Analysis
Configured-to-order pricing for FAA fireworthiness-certified long-fiber reinforced grades commands spreads against standard unsaturated resin spot pricing. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by UL 94 certification tier and phosphorus intermediate integration depth. Cost compression in standard unsaturated grades is intensifying because China's state-owned shipyards consolidate procurement volume. Building material fabricators exhibit highest price sensitivity due to distributor channel commoditization, while aerospace interior integrators show lowest sensitivity given weight-reduction imperatives.
Supply Chain Analysis
Phosphorus pentoxide supply from integrated producers in Germany, China, and the United States anchors formulation cost structures for specialty compounders. Feedstock sourcing draws from phosphate rock mining in Morocco, China, and Jordan, with phosphoric acid ester processing concentrated along the Yangtze River Delta and Gulf Coast petrochemical corridors. Single-source vulnerability persists in high-purity phosphorus intermediate supply, where three producers control capacity for CTI 600V+ electrical grades. Distribution runs through direct technical service teams for automotive and aerospace OEMs, with regional distributors serving building material fabricators on just-in-time contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among tier-one automotive OEMs harmonizing interior material standards across global platforms, fragmenting supplier relationships that previously sustained regional specification variance.
For Market Incumbents: Secure captive phosphorus intermediate supply through backward integration or long-term offtake agreements with Yangtze River Delta producers, insulating margin structures from feedstock volatility as REACH authorization accelerates formulation requalification demand. Defend aerospace certification relationships by expanding in-house fire testing laboratory capacity, reducing OEM requalification timelines that currently lock compounders into existing additive portfolios.
For New Entrants and Emerging Players: Anchor in MARPOL-compliant low-styrene unsaturated grades for Bohai Rim shipyards, where state-owned yard modernization is outpacing incumbent compounder technical service capacity. Target marine structure applications through direct sales teams co-located with Busan-Ulsan shipbuilding clusters, leveraging 12-18 month requalification friction to establish specification footholds before brominated alternatives fully phase out.
For Investors and Strategic Acquirers: ECHA's scheduled decabromodiphenyl ether sunset dates reshape the acquisition landscape toward phosphorus-modified formulation specialists with validated CTI tracking resistance portfolios. Five-to-ten year viability favors compounders with reactive phosphorus monomer capabilities and dual-carbon compliance integration in China. Target acquisition archetype: mid-tier European compounders with REACH-compliant portfolios but constrained technical service geographic coverage. The signal to watch is GB 8624 enforcement intensity in China's third-tier cities, where B1-grade mandates will concentrate procurement among qualified suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphorus Intermediates | Captive supply of phosphorus pentoxide secures feedstock cost advantages against REACH-driven formulation shifts. |
| Long-term Supply Agreement with Shipbuilders | MARPOL-compliant grade commitments from Bohai Rim yards lock in volume through state-owned procurement consolidation. |
| In-house Fire Testing Laboratory Investment | Reduced OEM requalification timelines compress competitor windows for specification displacement in aerospace panels. |
| Reactive Phosphorus Monomer Capacity Expansion | Permanent polymer-bound protection architectures displace additive blending in long-service electrical housing applications. |
| Joint Venture with Yangtze River Delta Compounders | Dual-carbon compliance integration addresses China's MEE embodied carbon reporting for high-rise building material supply chains. |
Research Methodology
A standing panel of plant managers at unsaturated resin production facilities, procurement leads at Tier 1 automotive suppliers, distribution channel partners in marine composites, and technical R&D directors at phosphorus intermediate producers provided ongoing calibration across the study period. Primary interview insights were cross-validated against secondary sources including customs and trade data from major exporting jurisdictions, ACC and Cefic industry association reports, SEC 10-K filings from listed chemical conglomerates, and GB standard enforcement disclosures from China's Ministry of Emergency Management. Bottom-up volume modeling by product grade and application was reconciled with top-down market sizing derived from petrochemical feedstock consumption patterns.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including resin chemistry type, reinforcement architecture, end-use industry certification requirements, and regional regulatory cluster. CAGRs were derived from regression analysis of historical procurement patterns correlated with enforcement intensity of fire safety codes. Industry-specific forecast inputs incorporated pultrusion automation adoption rates and electric vehicle powertrack content per vehicle assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained REACH authorization timelines and GB 8624 enforcement continuity; material deviation in regulatory phase-out schedules or dual-carbon policy intensity would warrant model refresh. Practitioners should keep alternative scenarios live as phosphorus intermediate capacity expansion and marine structure emission control adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
PCR Polyolefins Market
Polymers & Resins
Polymer Foam Market
Polymers & Resins
Indonesia Flooring Resins Market
Polymers & Resins
Sustainable Polymers Market
Polymers & Resins
Photocure Resins Market
Polymers & Resins
Cross-Linked Polyethylene (XLPE) Market
Polymers & Resins
Fluorinated Polyimide Market
Polymers & Resins
Polymers for Electric Vehicle (EV) Market
Polymers & Resins
Polyphenylene Sulfide (PPS) Resin Market
Polymers & Resins
Polydicyclopentadiene (Pdcpd) Market
Polymers & Resins
India Epoxy Resins Market
Polymers & Resins
Flexible Epoxy Resin Market
Polymers & Resins
Synthetic Polymer Waxes Market
Polymers & Resins
North America Linear Low-Density Polyethylene Market
Polymers & Resins
Styrene-Butadiene-Styrene Block Copolymer Market
Polymers & Resins
Asia-Pacific Polyamide Market