
 Specialty Glass Market | 2026-2036
Specialty Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Glass Market Outlook
Buyer concentration among display panel manufacturers is hardening as OLED and microLED fabs consolidate procurement around fewer qualified substrate vendors. Corning Incorporated leverages its fusion-draw process to anchor supply relationships with premium electronics brands. SCHOTT AG differentiates through deep specialization in borosilicate pharmaceutical tubing and thermal expansion-matched sealing glasses. AGC Inc. competes aggressively on automotive head-up display substrates, sustaining volume through long-term platform contracts with tier-one module suppliers.
Specialty glass denotes engineered silica-based materials formulated with precise thermal, optical, or chemical properties through controlled additions of boron oxide, alumina, or rare earth elements, typically manufactured via fusion drawing, float casting, or precision redrawing to achieve tight dimensional tolerances below 0.1 mm. Its primary purpose spans protective cover lenses for electronic devices, optical systems requiring minimal chromatic aberration, and architectural envelopes demanding selective solar transmission. Display glass leads value generation as panel makers prioritize thinner chemically strengthened substrates with higher scratch resistance and dielectric performance. Optical glass occupies mature margin pools in semiconductor lithography and medical imaging, where germanium-doped and fluorophosphate compositions command premium positioning. Automotive glass is accelerating fastest as electrified vehicles integrate larger curved displays, augmented reality windshields, and sensor-transparent encapsulants.
FDA standards govern pharmaceutical packaging compositions in the United States, while REACH and RoHS frameworks in Europe restrict hazardous substance migration across medical and consumer electronics applications. China's GB standards and MIIT directives enforce localized certification for display substrates deployed in domestic electronics manufacturing. Japan's METI circular economy guidelines are pressuring manufacturers to demonstrate closed-loop cullet recovery and reduced melting energy intensity. Stakeholders must monitor how diverging regional purity specifications reshape qualification timelines and capital allocation for new melting capacity.
Market Dynamics
Display panel manufacturers are consolidating procurement around fewer qualified substrate vendors, hardening buyer concentration and compressing qualification timelines for new melting capacity entrants.
Growth Catalysts
- Chemically Strengthened Substrates:Electronics manufacturers in East Asia are expanding orders for thinner display glass with higher dielectric performance and scratch resistance.
- Automotive Electrification:Electrified vehicles are integrating larger curved displays, augmented reality windshields, and sensor-transparent encapsulants across German and Chinese automotive clusters.
- REACH Compliance:Tightening compositional requirements for borosilicate and alkali-free formulations in Europe are accelerating premium grade substitution.
Market Restraints
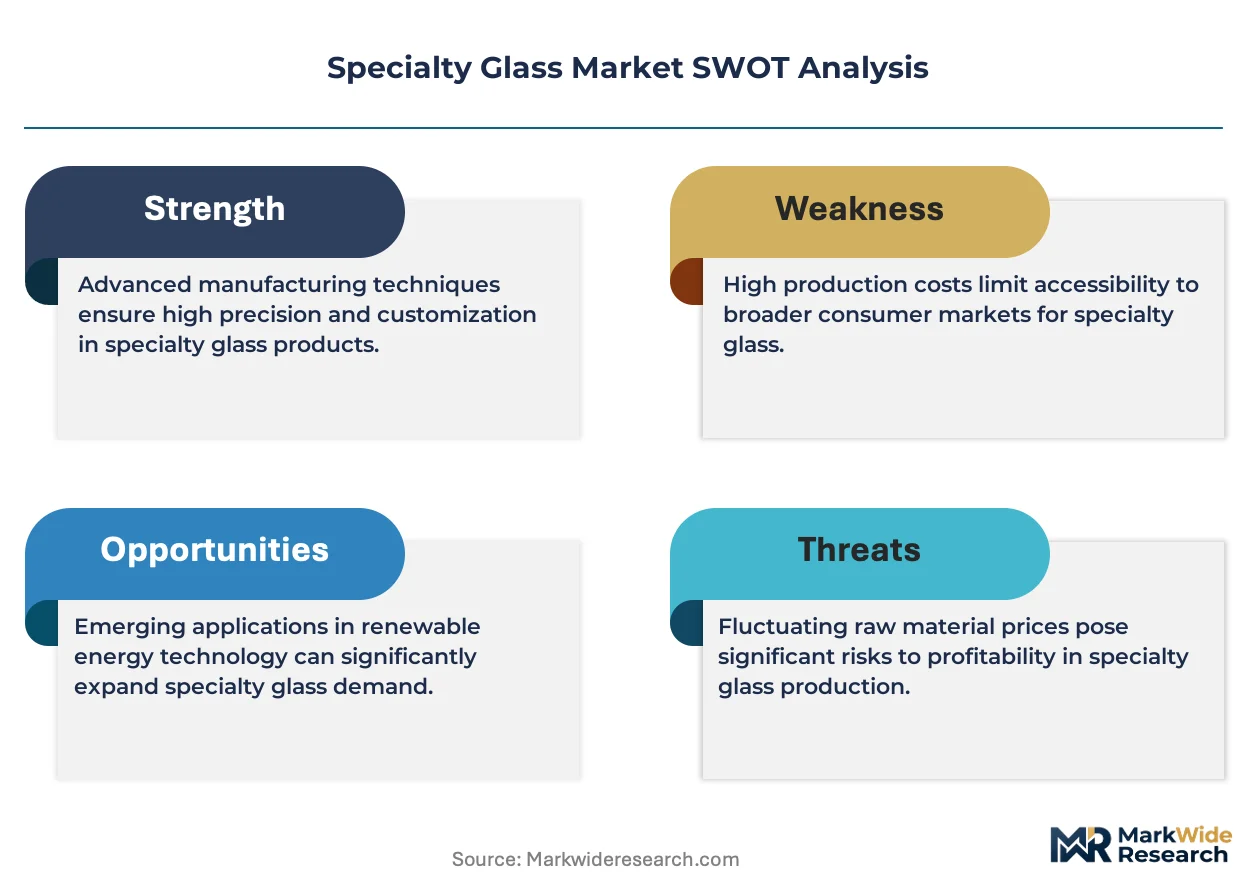
- Fusion-Draw Capital Intensity:New melting capacity requires billion-dollar furnace investments with decade-long depreciation cycles, freezing out mid-scale entrants.
- Rare Earth Input Volatility:Germanium and rare earth oxide prices fluctuate with Chinese export quota policies, destabilizing optical glass margin pools.
- Substitution by Polycarbonate:Automotive HUD covers and consumer electronics lenses face displacement from high-index polymers in cost-sensitive tiers.
Strategic Opportunities
- MicroLED Substrate Qualification:Panel makers are pre-qualifying next-generation substrates before fab ramp, creating first-mover lock-in for qualified vendors.
- Pharmaceutical Tubing Expansion:Borosilicate pharmaceutical tubing demand is outpacing supply in India's injectables manufacturing corridor.
- Closed-Loop Cullet Recovery:Japan's METI circular economy guidelines are rewarding manufacturers demonstrating reduced melting energy intensity through recycled feedstock.
Industry Challenges
- Melting Engineer Scarcity:Fusion-draw furnace operation requires decades of apprenticeship; retirement waves at established plants are creating knowledge transfer gaps.
- Dual Certification Timelines:Simultaneous FDA and NMPA approval for pharmaceutical packaging extends qualification cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Glass Market |
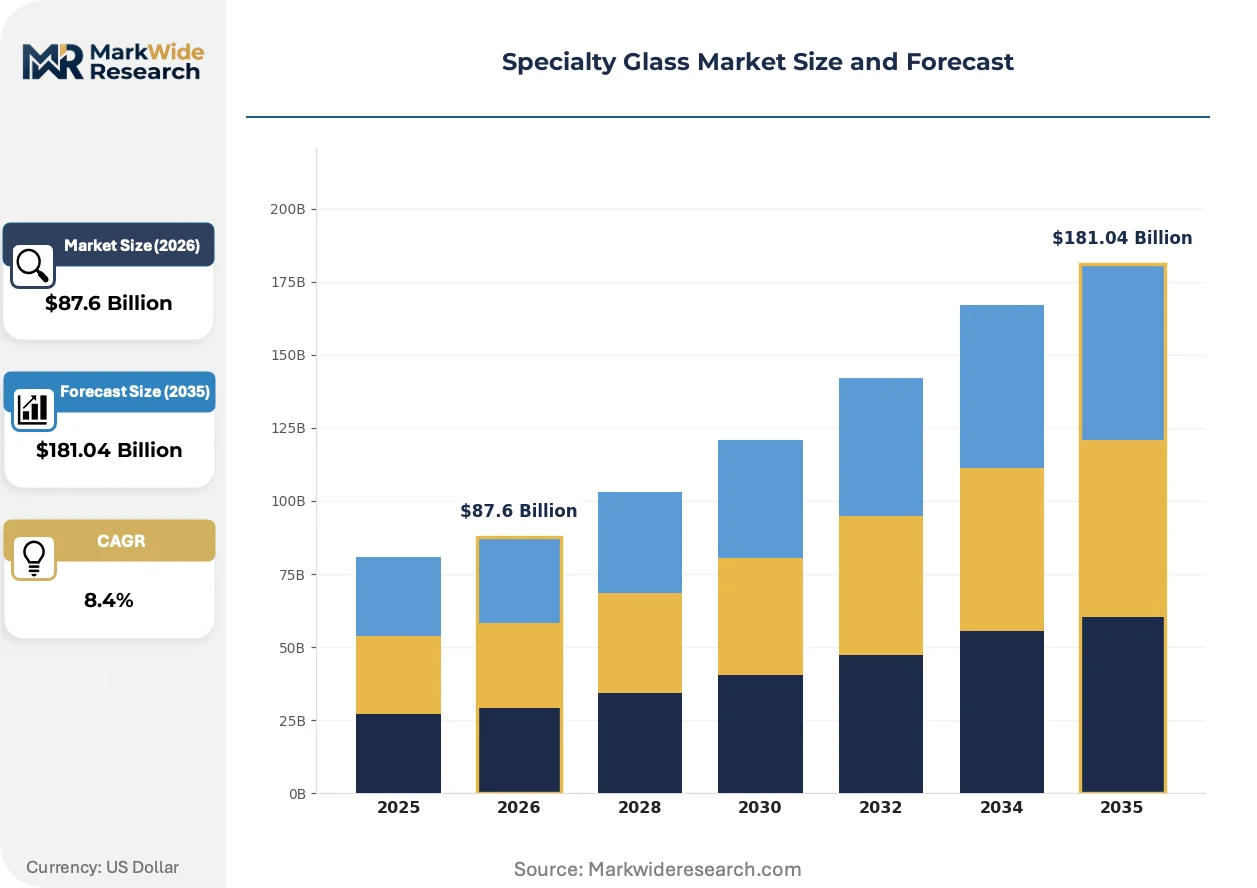
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $181.04 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Architectural Glass, Optical Glass, Display Glass, Automotive Glass Application: Building Construction, Electronics, Automotive, Consumer Goods End User: Manufacturers, Contractors, Retailers, Consumers Technology: Tinting, Coating, Laminating, Toughening |
| Companies Covered | Nippon Electric Glass Co., Ltd., Cardinal Glass Industries, Inc., AGC Inc., Gerresheimer AG, CSG Holding Co., Ltd., Corning Incorporated, SCHOTT AG, Fuyao Glass Industry, Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Glass Market Strategic Shifts
Precision manufacturing and compositional engineering are converging to enable sub-0.1 mm tolerances in substrates previously considered technically infeasible, while regulatory fragmentation is forcing parallel qualification tracks.
Alkali-free borosilicate glass is converging with atomic-layer deposition coating systems to create integrated substrate-barrier solutions. Semiconductor lithography equipment makers are adopting these stacks for next-generation EUV mask blanks. The convergence is compressing the supplier base for high-NA lithography components.
China's GB standards and MIIT directives are enforcing localized certification for display substrates deployed in domestic electronics manufacturing. Foreign substrate vendors must maintain parallel formulation libraries to serve Chinese fabs. Domestic panel makers are accelerating substitution timelines to comply with import-substitution mandates.
Long-term platform contracts with tier-one automotive module suppliers are displacing spot purchasing for HUD and display substrates. German and Korean automotive clusters are locking in volume commitments through 2030 to secure allocation during capacity constraints. Contract structures now embed price adjustment clauses tied to energy input indices.
Specialty Glass Market Segmentation
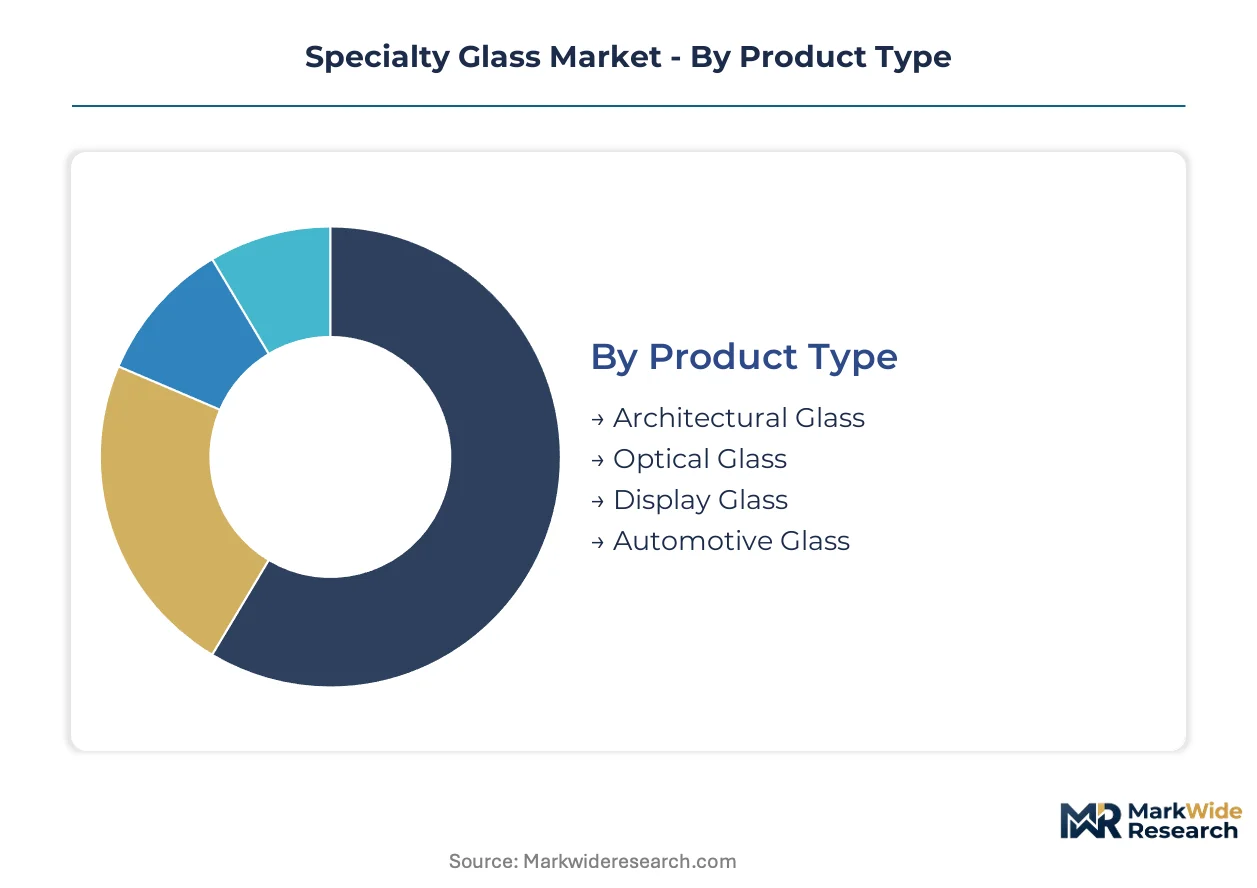
Specialty glass manufacturers configure melting capacity around divergent thermal and optical specifications, making segment-level targeting critical for capital allocation. Each product category demands distinct furnace chemistries and forming processes that resist rapid reconfiguration.
Product Type:
Supply concentration clusters around display substrates and optical grades where fusion-draw and precision redrawing technologies create steep barriers to entry.
- Display Glass:Chemically strengthened alkali-free borosilicate formulations achieve sub-0.1 mm thickness tolerances through fusion-draw processing. East Asian electronics manufacturers in the Yangtze River Delta cluster are consolidating procurement around qualified vendors capable of high-dielectric performance substrates.
- Optical Glass:Germanium-doped and fluorophosphate compositions engineered for minimal chromatic aberration serve semiconductor lithography and medical imaging equipment. Demand concentrates in Germany's precision optics corridor where tight thermal expansion specifications command sustained premium positioning.
- Automotive Glass:Curved HUD substrates and sensor-transparent encapsulants for electrified vehicles.
- Architectural Glass:Selective solar transmission formulations for high-performance building envelopes.
Display glass absorbs the bulk of installed capacity; automotive glass is expanding most quickly.
Application:
Customer procurement patterns diverge sharply between long-term platform contracts in automotive and spot purchasing volatility in construction.
- Electronics:OLED and microLED fabs are pre-qualifying next-generation substrates before fab ramp, compressing vendor selection timelines. China's MIIT directives enforce localized certification requirements that foreign substrate makers must satisfy through parallel formulation libraries.
- Automotive:German and Korean automotive clusters are locking in volume commitments through 2030 for HUD and display substrates, embedding price adjustment clauses tied to energy input indices.
- Building Construction:Project-based procurement with specification-driven bidding for solar control and safety glazing.
- Consumer Goods:Cost-sensitive lens and cover applications facing displacement pressure from high-index polymers.
Electronics commands the deepest supplier relationships; automotive is gaining share fastest through electrification-driven display integration.
End User:
Direct procurement by manufacturers dominates value capture while intermediary channels handle fragmented construction and retail demand.
- Manufacturers:Display panel makers, semiconductor equipment builders, and pharmaceutical packagers drive specification-setting. FDA and NMPA dual certification requirements for pharmaceutical tubing extend qualification cycles by 18-24 months, favoring incumbents with established regulatory dossiers.
- Contractors:Construction project managers sourcing architectural grades through competitive bidding.
- Retailers:Consumer electronics and automotive aftermarket distribution.
- Consumers:Replacement and upgrade purchases with minimal technical specification involvement.
Manufacturers absorb the bulk of technical sales engagement; contractors represent the most price-sensitive tier.
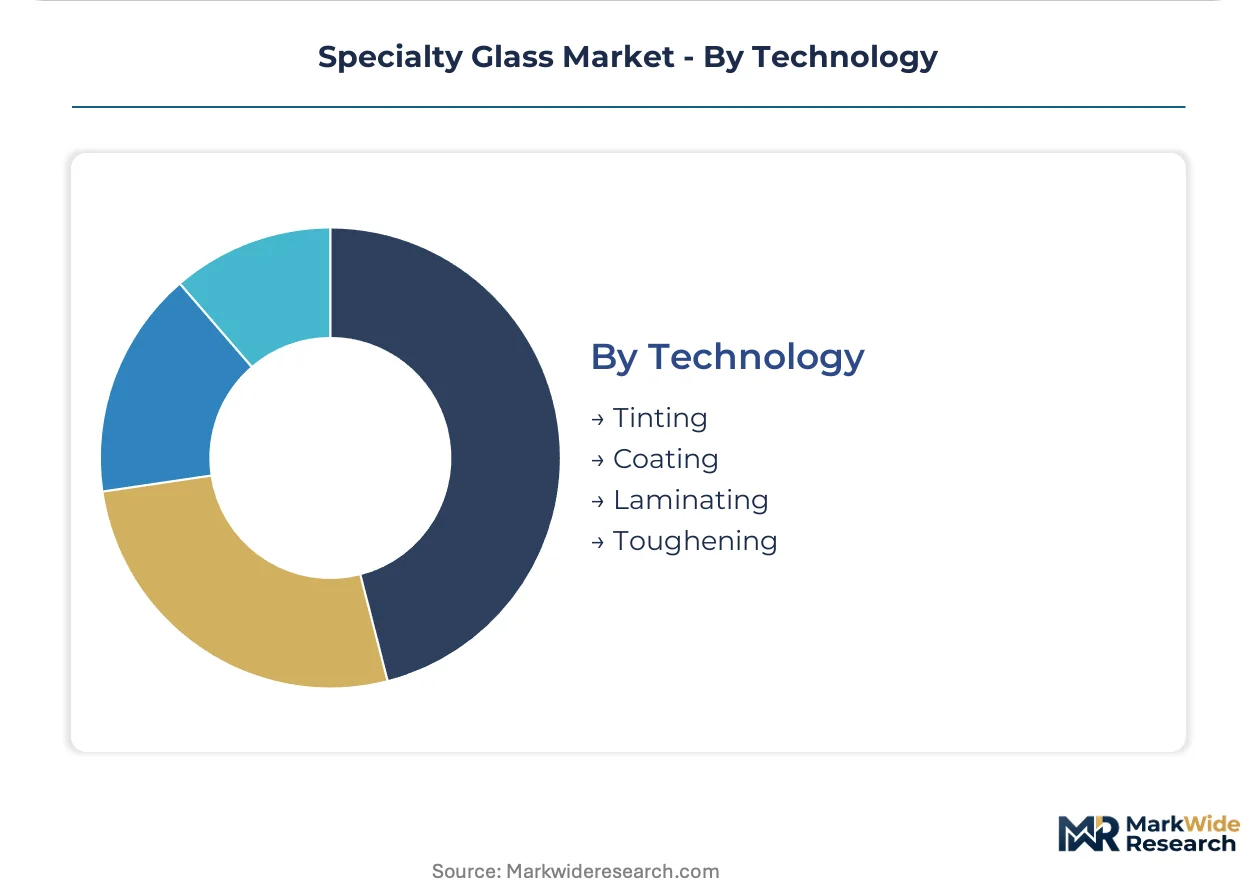
Technology:
Process selection locks in product performance ceilings and capital recovery timelines across decade-long depreciation cycles.
- Fusion Draw:Premium substrate manufacturing achieving pristine surface quality without grinding or polishing. Corning Incorporated anchors supply relationships with electronics brands through this proprietary process, sustaining billion-dollar furnace investments.
- Coating:Atomic-layer deposition systems creating integrated substrate-barrier stacks for EUV mask blanks in semiconductor lithography. The convergence with alkali-free borosilicate glass is compressing the supplier base for high-NA lithography components.
- Toughening:Chemical strengthening via ion exchange for impact-resistant display covers and automotive glazing.
- Laminating:Interlayer bonding for safety and acoustic performance in architectural and automotive applications.
- Tinting:Bulk and surface coloration for solar control and aesthetic specifications.
Fusion draw commands the heaviest capital commitment; coating is climbing the fastest through lithography equipment demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Display panel procurement concentrates in East Asian manufacturing corridors and German precision optics clusters, with regulatory divergence forcing parallel formulation tracks across major demand centers.
China
MIIT directives enforce localized certification for display substrates deployed in domestic electronics manufacturing. GB standards and evolving compositional requirements are tightening for borosilicate and alkali-free formulations. The Yangtze River Delta display cluster anchors procurement consolidation among OLED and microLED fabs.
Germany
Precision optics demand concentrates in semiconductor lithography and medical imaging equipment requiring minimal chromatic aberration. REACH compliance is accelerating premium grade substitution for borosilicate pharmaceutical tubing. The precision optics corridor commands sustained premium positioning through tight thermal expansion specifications.
United States
FDA standards govern pharmaceutical packaging compositions while electronics manufacturers source chemically strengthened substrates for protective cover lenses. The fusion-draw process anchors billion-dollar furnace investments with decade-long depreciation cycles. Premium electronics brands consolidate supply relationships around qualified substrate vendors.
Japan
METI circular economy guidelines pressure manufacturers to demonstrate closed-loop cullet recovery and reduced melting energy intensity. Optical glass demand serves semiconductor lithography equipment makers adopting alkali-free borosilicate stacks. Fusion-draw furnace operation faces knowledge transfer gaps from retirement waves at established plants.
South Korea
Automotive electrification drives integration of larger curved displays and augmented reality windshields across domestic automotive clusters. Long-term platform contracts with tier-one module suppliers lock in volume commitments through 2030. Price adjustment clauses tied to energy input indices now embed in contract structures.
Specialty Glass Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue adjacent coating and laminating specializations. The supplier base stratifies around fusion-draw scale players, precision redrawing specialists, and regional float casting operators. Three archetypes dominate: proprietary process holders with captive electronics relationships, pharmaceutical tubing specialists with regulatory dossiers, and automotive platform contractors with long-term volume commitments. Competitive moves center on pre-qualification lock-in for next-generation substrates and backward integration into rare earth oxide supply.
Within the proprietary process tier, Corning Incorporated and AGC Inc. exemplify scale-driven positions anchored by fusion-draw capacity investments. SCHOTT AG occupies a specialization-focused position in borosilicate pharmaceutical tubing and thermal expansion-matched sealing glasses. Among diversified materials conglomerates, Saint-Gobain represents the multi-segment archetype spanning automotive, architectural, and industrial glass categories.
| Leading Market Players |
|---|
| Nippon Electric Glass Co., Ltd. |
| Cardinal Glass Industries, Inc. |
| AGC Inc. |
| Gerresheimer AG |
| CSG Holding Co., Ltd. |
| Corning Incorporated |
| SCHOTT AG |
| Fuyao Glass Industry |
| Saint-Gobain |
| Others |
Value Chain & Pricing Dynamics
Captive fusion-draw capacity in the Yangtze River Delta and precision optics corridors anchors supply positions while simultaneously underwriting pricing power through decade-long depreciation cycles and steep qualification barriers. This integration pattern forces buyers into long-term platform contracts with embedded price adjustment clauses tied to energy input indices.
Pricing Analysis
Volume commitments through 2030 absorb the bulk of high-margin capacity while spot purchasing for architectural and consumer goods applications faces persistent cost compression. Pricing stratifies across premium fusion-draw substrates, standard float-cast grades, and economy float glass tiers, with differentiation driven by certification level and customization depth. Margins are tightening in automotive HUD covers due to polycarbonate substitution pressure. Contractors in building construction exhibit the highest price sensitivity; semiconductor lithography equipment makers show the least.
Supply Chain Analysis
Qualification gating through FDA, REACH, and MIIT certification libraries compresses the supplier base to incumbents with established regulatory dossiers. Manufacturing concentrates in China, Germany, and Japan, with rare earth oxide feedstocks drawing from Chinese export quotas. Single-source vulnerability runs through germanium-doped optical glass precursor supply. Distribution runs through direct procurement by display panel manufacturers and tier-one automotive module suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty glass operates as a cost-of-compliance market where REACH, FDA, and MIIT certification timelines create 18-24 month moats that freeze out unqualified entrants and reward incumbents with amortized regulatory dossiers.
For Market Incumbents: Deploy backward integration into rare earth oxide supply to destabilize optical glass margin pools threatened by Chinese export quota volatility. Anchor capacity additions in India's pharmaceutical tubing corridor where borosilicate demand outpaces qualified supply. Lock in microLED substrate pre-qualification before fab ramp to freeze out emerging fusion-draw entrants. For New Entrants and Emerging Players: Atomic-layer deposition coating systems for EUV mask blanks offer a technology-first wedge into semiconductor lithography equipment supply. Target India's injectables manufacturing corridor for borosilicate pharmaceutical tubing where FDA-NMPA dual certification scarcity favors agile qualification investment. Pursue joint development agreements with domestic Chinese panel makers facing MIIT import-substitution mandates. For Investors and Strategic Acquirers: Exit pathways concentrate in proprietary process holders with captive electronics relationships and decade-long platform contracts. Five-to-ten year viability hinges on fusion-draw furnace operation expertise transfer as retirement waves create knowledge gaps at established plants. Watch for microLED substrate qualification announcements as inflection indicators for first-mover lock-in value.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Supply | Captive germanium oxide sourcing insulates optical glass margins from Chinese quota volatility. |
| MicroLED Substrate Pre-Qualification | Early vendor lock-in with panel makers before fab ramp secures decade-long volume commitments. |
| Closed-Loop Cullet Recovery Investment | METI-compliant recycled feedstock demonstration unlocks Japanese automotive and electronics procurement. |
| Dual FDA-NMPA Certification Pursuit | Simultaneous pharmaceutical packaging approval in US and China extends incumbency moats by 18-24 months. |
| Atomic-Layer Deposition Coating Scale-Up | Integrated substrate-barrier stacks for EUV lithography compress supplier base and command premium positioning. |
Study Parameters
Independent corroboration across melting engineers at fusion-draw facilities, procurement directors at OLED and microLED fabs, and regulatory affairs specialists at pharmaceutical packagers underwrites the qualitative findings. Secondary validation drew from SEC 10-K filings, ECHA REACH registration databases, MIIT directive publications, and customs trade data for rare earth oxide flows. Bottom-up capacity modeling triangulated against top-down demand segmentation across display, optical, automotive, and pharmaceutical end-uses.
Comparable-period anchoring to historical furnace utilization rates, qualification timeline distributions, and platform contract renewal patterns structured the projection horizon. The analytical framework modeled product type, application, end user, and technology dimensions alongside regional regulatory cluster differentiation. CAGRs derived from melt capacity expansion schedules, substitution elasticity estimates for polycarbonate in automotive HUDs, and import-substitution mandate compliance timelines in Chinese domestic electronics manufacturing.
Several conditions sit outside the modeled scope, including abrupt Chinese export quota suspension for germanium and rare earth oxides, breakthrough polymer formulations displacing chemically strengthened substrates in consumer electronics, and unilateral REACH compositional requirement tightening. Forecasts reflect assumptions regarding sustained electrification-driven display integration in automotive platforms and stable dual-certification timeline differentials. A model refresh is warranted upon material change in microLED fab ramp schedules or fusion-draw furnace operator retirement rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals & Materials
Protein Purification Resin Market
Chemicals & Materials
Bio-Based Polycarbonate Market
Chemicals & Materials
Global Boric Acid Market
Chemicals & Materials
Global Polyethylene Pipes and Fittings Market
Chemicals & Materials
Zinc Eugenol Market
Chemicals & Materials
Methyl Isobutyl Carbinol Market
Chemicals & Materials
Amino Silicone Oil Market
Chemicals & Materials
Global Magnesium Oxide Market
Chemicals & Materials
Global Antimony Market
Chemicals & Materials
Global Medical Membranes Market
Chemicals & Materials
High Nickel Cathode Materials Market
Chemicals & Materials
Global 2-Ethylhexanoic Acid Market
Chemicals & Materials
Maleic Anhydride Market
Chemicals & Materials
Global Carbon Fiber Resin Market
Chemicals & Materials
RDP Powder Market
Chemicals & Materials
Carbon Foam Market