
 Sol-Gel Coatings Market | 2026-2036
Sol-Gel Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Sol-Gel Coatings Market Intelligence
ISO 12944 certification for corrosion protection is rotating market access toward suppliers with documented performance data. This standard requires extensive testing, favoring established players. PPG Industries Inc. leverages its significant R&D infrastructure to qualify new formulations for automotive clients. BASF SE specializes in advanced organic-inorganic hybrid coatings for demanding electronics applications, while AkzoNobel N.V. positions its portfolio to meet stringent environmental standards in the European construction sector.
Sol-gel coatings are thin, functional films produced through a wet chemical process involving the hydrolysis and condensation of chemical precursors, typically metal alkoxides. These coatings create dense, hard, and transparent layers on various substrates, providing properties like scratch resistance, anti-corrosion, and hydrophobicity. Silica-based coatings represent a mature, high-volume segment due to their cost-effectiveness. In contrast, organic-inorganic hybrid coatings are the fastest-growing product type, driven by demand from high-performance automotive and electronics applications.
The regulatory environment is defined by chemical safety mandates like the EU's REACH framework and the US EPA's Toxic Substances Control Act (TSCA). These regulations restrict specific volatile organic compounds and precursor materials, compelling manufacturers to invest in water-based or low-VOC formulations. Compliance with national material standards, such as China's GB standards, is also critical for market access. The key decision for formulators now is how to balance performance enhancements with an increasingly stringent and fragmented global regulatory landscape.
Market Dynamics
The central tension in the sol-gel coatings market is the need to meet escalating performance requirements in advanced manufacturing while navigating a tightening, fragmented global regulatory framework for chemical precursors and volatile organic compounds.
Growth Catalysts
- Automotive Sector Demand:The automotive industry's requirement for scratch-resistant, anti-corrosion, and hydrophobic clear coats on body panels, lighting, and glass surfaces is a significant demand driver, particularly within Germany's production centers.
- Regulatory Compliance Push:The EU's REACH framework is compelling a transition toward water-based and low-VOC sol-gel formulations, creating a catalyst for innovation and adoption of compliant coatings in construction and industrial applications.
- Renewable Energy Expansion:Growth in solar and wind energy installations creates new demand for protective coatings that improve efficiency and durability of solar panels and wind turbine blades against environmental degradation.
Market Restraints
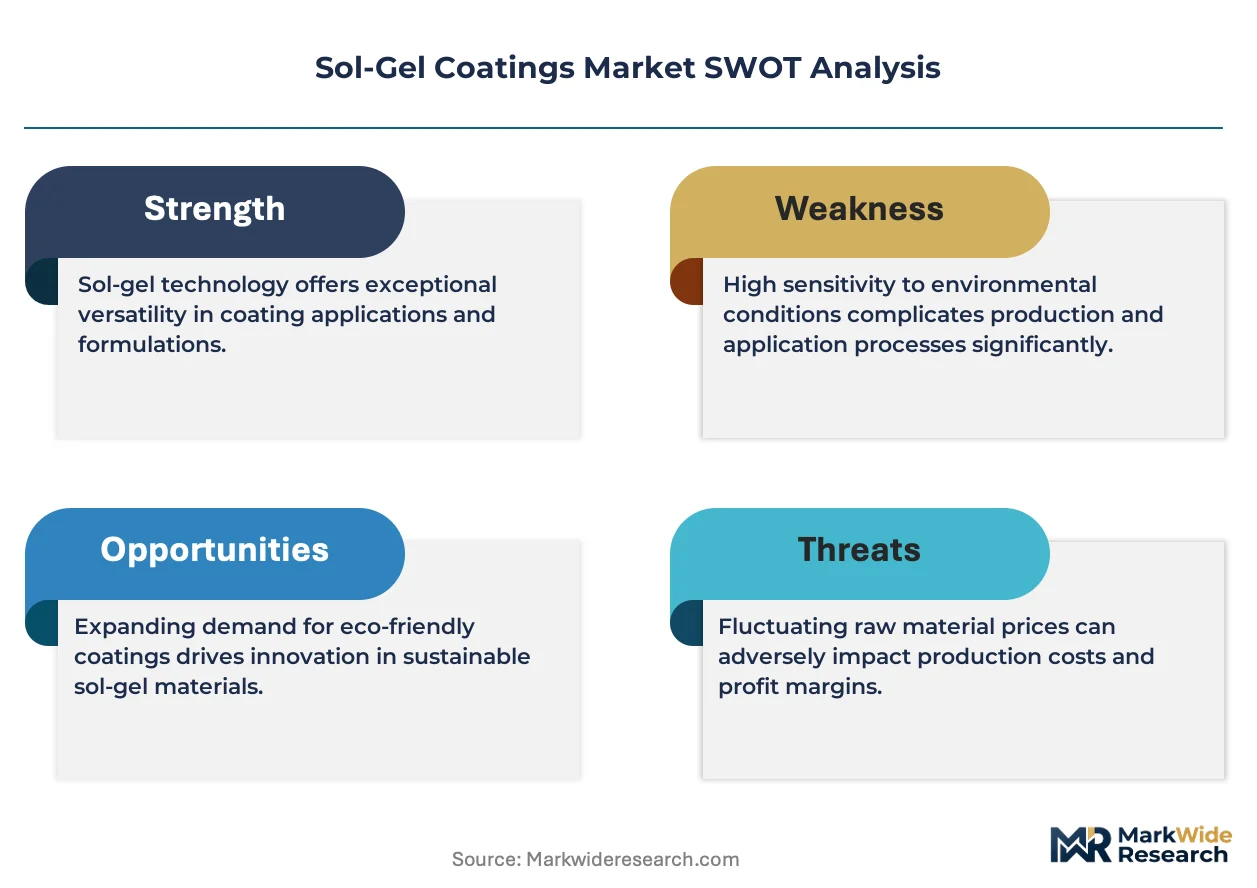
- Raw Material Cost:The high cost and price volatility of key metal alkoxide precursors, such as tetraethoxysilane (TEOS) and titanium alkoxides, can make sol-gel coatings less competitive against conventional polymer coatings for some applications.
- Processing Limitations:The requirement for specific curing temperatures and controlled environments for the sol-gel process can limit its application on heat-sensitive substrates and increase manufacturing complexity and cost.
- Technical Expertise Barrier:Formulation and application of sol-gel coatings demand specialized knowledge in chemistry and material science, creating a barrier to entry for non-specialist firms and limiting wider adoption.
Strategic Opportunities
- Biomedical Applications:Developing biocompatible and antimicrobial sol-gel coatings for medical implants, surgical instruments, and healthcare surfaces presents a high-value opportunity, driven by infection control priorities.
- Self-Healing Functionality:Formulating coatings with self-healing properties that can autonomously repair minor scratches offers a significant performance advantage for high-end automotive, aerospace, and electronics applications.
- Textile and Fabric Finishing:Applying hydrophobic and oleophobic sol-gel coatings to textiles creates performance apparel and protective fabrics with enhanced water and stain resistance, opening a new consumer-facing market segment.
Industry Challenges
- Formulation Stability:Ensuring the long-term stability and shelf-life of sol-gel precursor solutions is a persistent technical challenge, as premature hydrolysis or condensation can render batches unusable and increase waste.
- Certification Timelines:The extensive testing and documentation required to achieve performance certifications, such as ISO 12944 for corrosion protection, impose significant time and cost burdens on manufacturers launching new products.
- Production Scale-Up:Translating successful laboratory-scale formulations to large-volume, consistent industrial production without defects or performance degradation remains a critical operational hurdle for many producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sol-Gel Coatings Market |
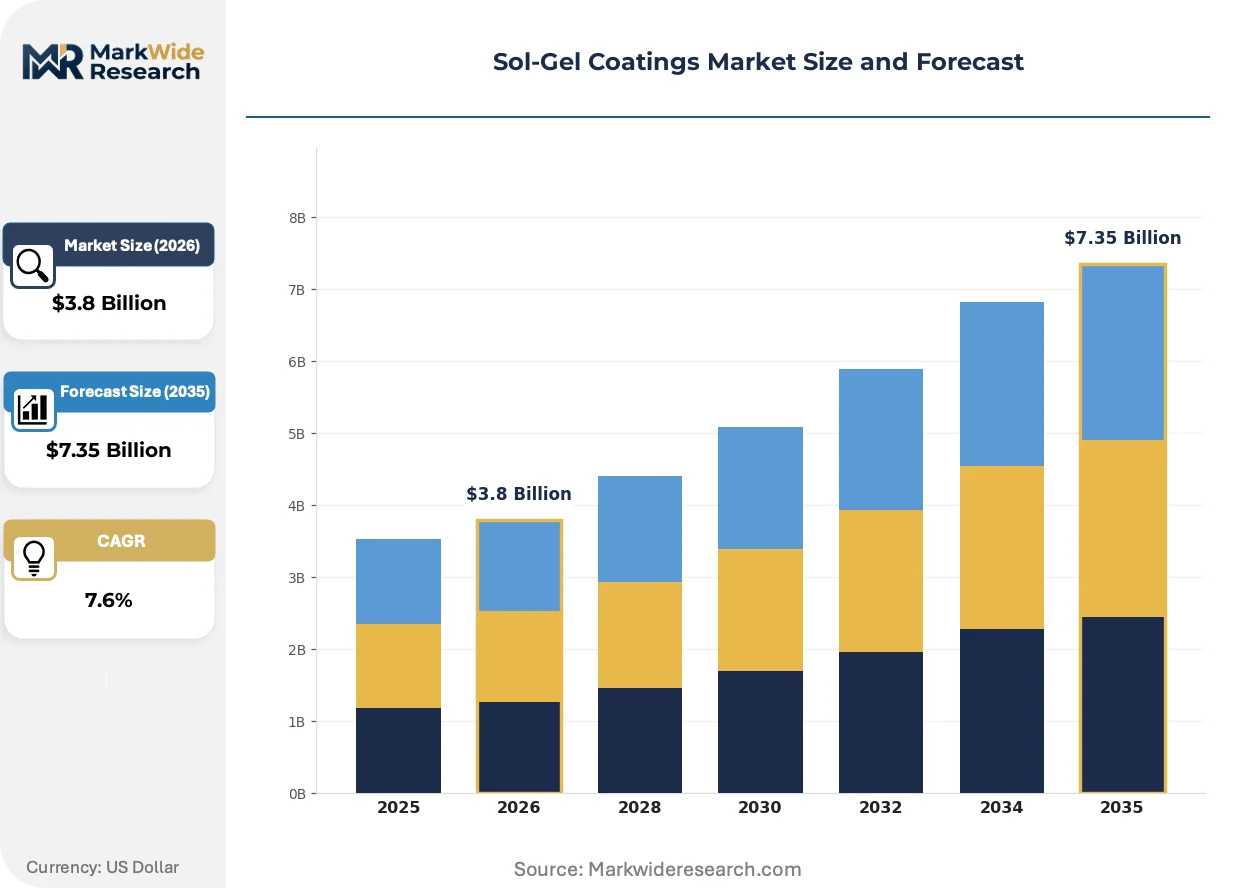
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silica-Based Coatings, Alumina-Based Coatings, Organic-Inorganic Hybrid Coatings, Ceramics Application: Automotive, Electronics, Construction, Healthcare Technology: Dip Coating, Spray Coating, Spin Coating, Brush Coating End User: Manufacturers, Contractors, OEMs, Researchers |
| Companies Covered | Toray Industries Inc., PPG Industries Inc., AkzoNobel N.V., Covestro AG, Nippon Paint Holdings Co. Ltd., 3M Company, Asian Paints Ltd., Sol-Gel Technologies Ltd., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sol-Gel Coatings Market Strategic Shifts & Innovations
Material science advancements are enabling the creation of multifunctional coatings with precisely engineered properties. This evolution is moving sol-gel technology from single-purpose protective layers toward integrated systems that enhance the core function of the underlying product.
Organic-inorganic hybrid coatings integrate the hardness of a ceramic matrix with the flexibility of a polymer network. The electronics sector is adopting these materials to protect sensitive micro-components from moisture and abrasion. This development is miniaturizing the protective layers on flexible displays and wearable sensors, enabling more compact and durable device designs.
Regulations like the EU's REACH and the US EPA's Toxic Substances Control Act (TSCA) are progressively restricting specific precursor chemicals and solvents. This action compels a market-wide shift from traditional solvent-based systems to more environmentally benign water-based or high-solids formulations. The architectural and automotive refinishing segments are most affected, investing in R&D to develop compliant products that maintain performance standards.
A notable shift in buyer behavior is the increasing emphasis on documented performance data against recognized standards. This trend moves purchasing decisions away from price-centric evaluations toward a total-cost-of-ownership model, where coating longevity and reliability are paramount. This dynamic is most pronounced in the aerospace and marine industries, where coating failure carries substantial operational and safety risks.
Sol-Gel Coatings Market Segmentation
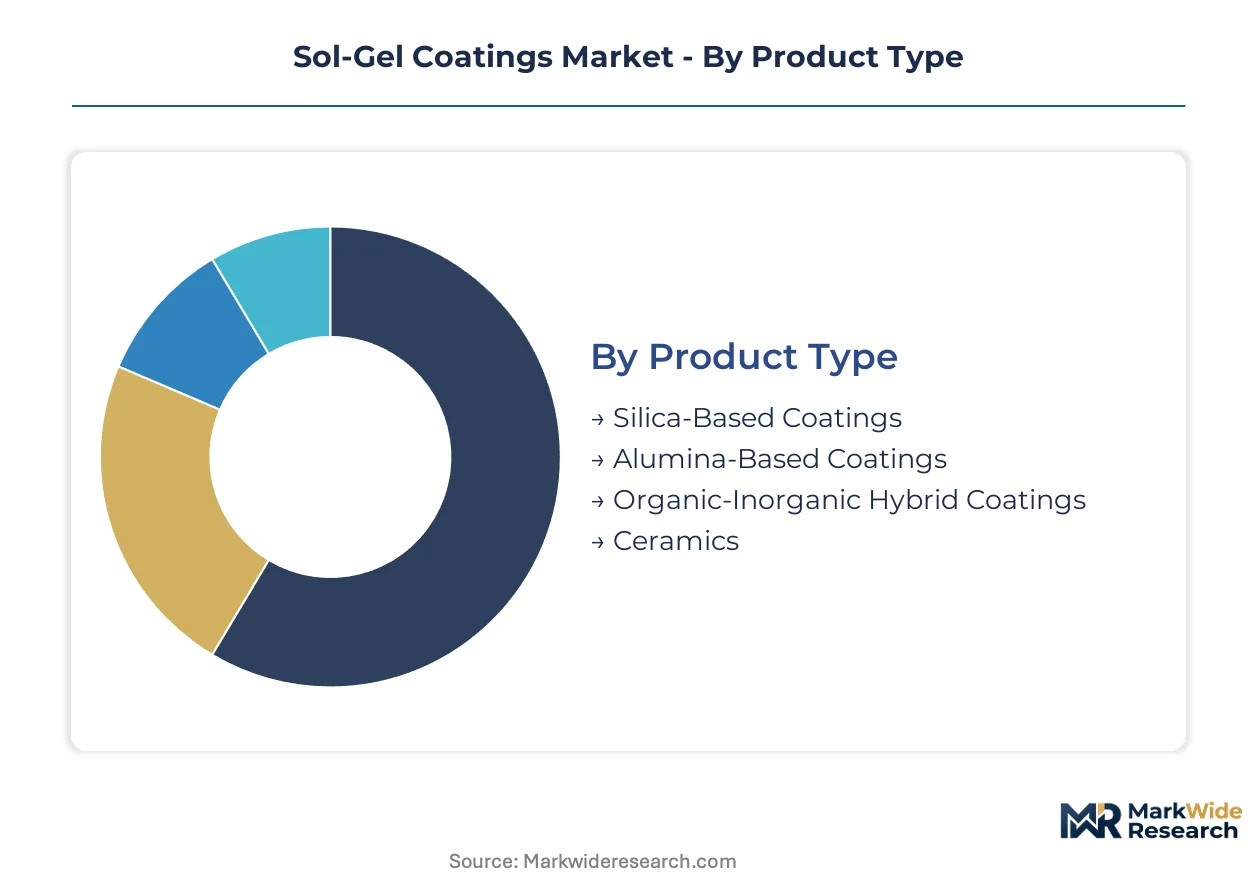
The sol-gel coatings market segments based on distinct material compositions, application areas, deposition technologies, and end-user types. Each segment reflects unique performance requirements and regulatory pressures shaping product development. Understanding these divisions helps identify specific demand pockets and technological advancement trajectories within the industry.
Product Type:
Regulatory differentiation increasingly influences product type selection in the sol-gel coatings market, driving innovation in compliant material chemistries.
- Organic-Inorganic Hybrid Coatings:These materials combine ceramic hardness with polymer flexibility, offering enhanced performance for demanding applications. Demand from the electronics sector for protecting sensitive micro-components against moisture and abrasion drives their rapid expansion.
- Silica-Based Coatings:Composed primarily of silicon dioxide precursors, these coatings offer cost-effectiveness and mature production processes. They form the high-volume segment, providing scratch resistance and anti-corrosion properties in general industrial applications.
- Alumina-Based Coatings:Utilizing aluminum oxide precursors, these coatings provide superior hardness and thermal stability for specialized high-temperature applications.
- Ceramics:This broad category includes advanced inorganic compounds, offering extreme durability and chemical inertness for highly specialized protective layers.
Established volume favors Silica-Based Coatings; emerging adoption favors Organic-Inorganic Hybrid Coatings.
Application:
Application-specific performance requirements dictate the selection and formulation of sol-gel coatings across diverse industrial sectors.
- Automotive:This sector requires durable clear coats for body panels, lighting, and glass, providing scratch resistance, anti-corrosion, and hydrophobic properties. Germany's advanced manufacturing centers represent a significant demand concentration for these protective layers.
- Electronics:Sol-gel coatings protect sensitive micro-components and flexible displays from moisture, abrasion, and electrical interference. BASF SE specializes in advanced organic-inorganic hybrid coatings tailored for these demanding electronics applications.
- Construction:Coatings in this segment enhance durability and environmental resistance for building materials, meeting stringent EU environmental standards.
- Healthcare:Biomedical applications leverage sol-gel coatings for their biocompatibility and antimicrobial properties on implants and surgical instruments.
Specific application environments dictate material selection, with Electronics showing the steepest expansion trajectory and Automotive maintaining consistent volume.
Technology:
Processing complexity and substrate compatibility are critical factors influencing the choice of sol-gel coating deposition technologies.
- Spray Coating:This method allows for rapid and uniform application over large or complex surfaces, making it suitable for industrial-scale production. It is widely adopted in automotive and construction sectors due to its efficiency and versatility.
- Dip Coating:Substrates are immersed into the sol-gel solution, providing excellent uniform coverage and precise thickness control. This technique is favored for intricate parts and optical components requiring high precision.
- Spin Coating:Primarily used for flat substrates, this technique applies a thin, uniform film by spinning the substrate at high speeds.
- Brush Coating:A simple, manual application method suitable for small areas or repair work where precision is less critical.
Efficiency and precision drive selection, with Spray Coating offering broad industrial utility and Dip Coating enabling high-tolerance deposition.
End User:
End-user types are differentiated by their value chain position and operational needs, impacting product specifications and procurement patterns.
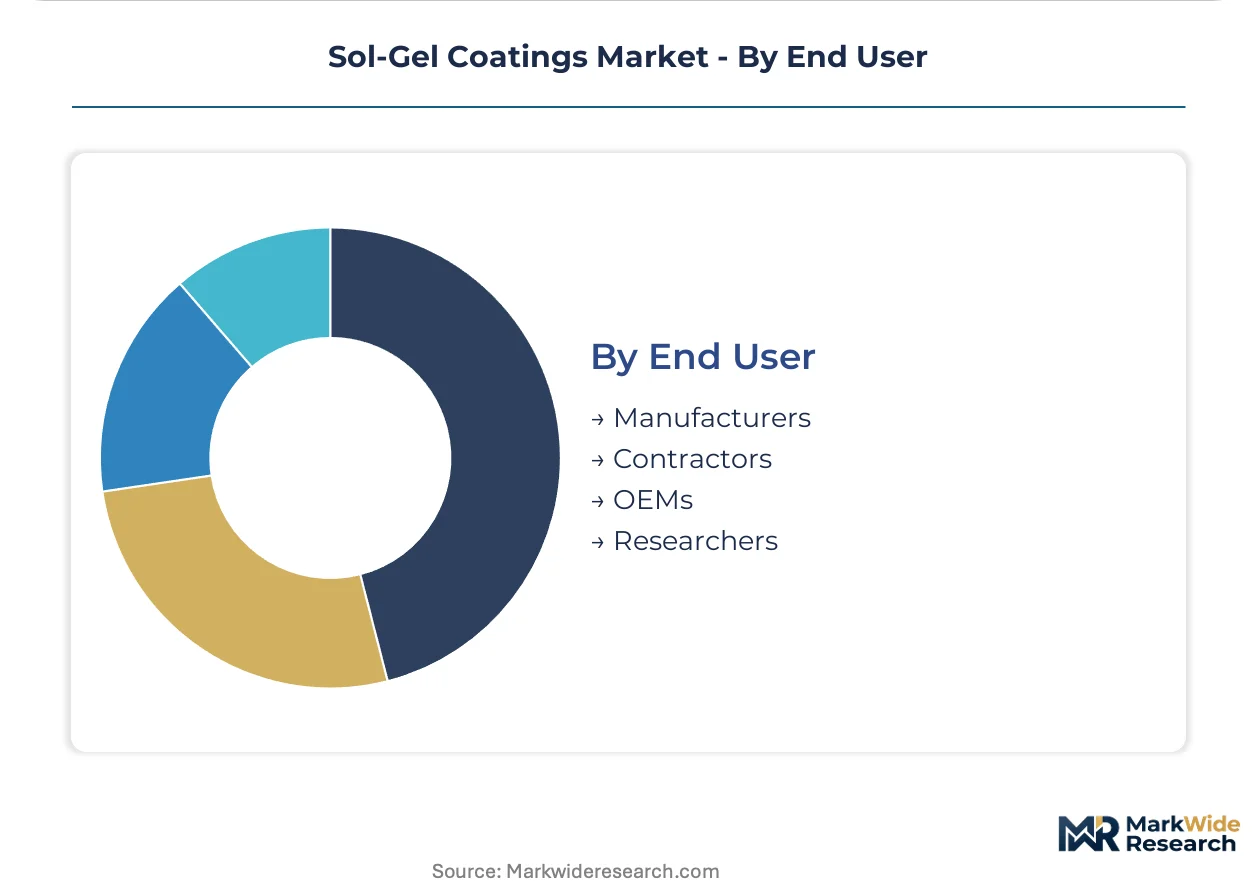
- OEMs:Original Equipment Manufacturers integrate sol-gel coatings directly into their products, such as automotive components or electronic devices. Their demand focuses on high-performance, validated formulations that meet specific product lifecycle requirements and quality standards.
- Manufacturers:These entities produce various goods that utilize sol-gel coatings as a protective or functional layer, ranging from industrial equipment to consumer products. They seek reliable, scalable solutions for their production lines.
- Contractors:These service providers apply sol-gel coatings on-site for construction, infrastructure, or maintenance projects.
- Researchers:Academic and corporate research institutions develop new sol-gel formulations and applications, driving future market innovation.
Direct integration by OEMs shapes product specifications, while Manufacturers influence broader market adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU's REACH framework and similar global chemical safety mandates are progressively influencing regional market dynamics, compelling innovation in water-based and low-VOC sol-gel formulations. This regulatory push is reshaping material development and adoption across key industrial centers. Demand for advanced protective layers in the automotive sector, especially within Germany, remains a primary application driver for these specialized coatings.
Germany
Automotive manufacturing and advanced engineering create significant demand for scratch-resistant and anti-corrosion sol-gel clear coats. Germany's KBA regulations for vehicle components drive material compliance and performance standards. The Stuttgart region, a hub for automotive production, concentrates much of this specialized coating demand.
United States
Electronics and aerospace sectors require high-performance sol-gel coatings for sensitive components and durable surfaces. The US EPA's Toxic Substances Control Act (TSCA) influences the formulation of compliant materials. Silicon Valley in California, a major technology cluster, drives innovation and adoption for electronics protection.
China
Rapid industrialization and a growing automotive industry fuel demand for cost-effective and functional sol-gel solutions. China's GB standards for materials and environmental protection shape product development and market access. The Yangtze River Delta, with its extensive manufacturing base, represents a significant consumption center.
Japan
Precision manufacturing and advanced electronics industries seek sol-gel coatings for their optical and protective properties. Japan's METI policies encourage the development of high-performance, environmentally friendly materials. The Kanto region, including Tokyo, houses numerous research and manufacturing facilities driving this demand.
Sol-Gel Coatings Market Key Industry Players
Player mix skews toward established chemical conglomerates and specialized materials firms, with a fragmented tier of regional and niche solution providers. Strategic archetypes include large-scale diversified chemical producers, focused high-performance material specialists, and application-specific formulators. Dominant competitive moves involve significant R&D investment for regulatory compliance and strategic partnerships to expand application knowledge.
On the premium-tier vector, PPG Industries Inc. exemplifies a major coatings producer leveraging extensive R&D infrastructure for automotive clients. BASF SE, a global chemical giant, represents a diversified player specializing in advanced organic-inorganic hybrid coatings for demanding electronics applications. AkzoNobel N.V. occupies a position as a leading paint and coatings company, positioning its portfolio to meet stringent environmental standards in the European construction sector.
| Leading Market Players |
|---|
| Toray Industries Inc. |
| PPG Industries Inc. |
| AkzoNobel N.V. |
| Covestro AG |
| Nippon Paint Holdings Co. Ltd. |
| 3M Company |
| Asian Paints Ltd. |
| Sol-Gel Technologies Ltd. |
| BASF SE |
| Others |
Cost & Logistics Intelligence
The EU's REACH framework, alongside ISO 12944 certification, simultaneously gates sol-gel coating supply qualification and influences price differentiation. These stringent standards dictate material formulation and documented performance data for market access.
Pricing Analysis
Certification level, like ISO 12944 for corrosion protection, creates the primary spread in sol-gel coating pricing. Performance specifications for scratch resistance and thermal stability drive premium valuations. Pricing pressure stems from the high cost and volatility of key metal alkoxide precursors. General industrial applications using silica-based coatings are most price-sensitive, while aerospace and electronics applications prioritize performance over cost.
Supply Chain Analysis
Inventory management and lead-time stability are critical due to the specialized nature of sol-gel precursors. Supply of metal alkoxide precursors, such as TEOS and titanium alkoxides, concentrates in chemical manufacturing hubs like China, Germany, and Japan. The market draws from a limited pool of specialized chemical producers. Raw material price volatility represents a significant supply chain risk. Distribution runs through direct sales channels to large OEMs and through specialized distributors for smaller manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sol-gel coatings market is a high-growth disruption, with material science advancements enabling multifunctional coatings. This evolution integrates enhanced properties directly into product functionality.
For Market Incumbents: Secure intellectual property around novel hybrid formulations and compliant water-based systems. Invest heavily in R&D infrastructure to qualify new products against ISO 12944, mitigating threats from emerging niche specialists. Strategic partnerships with automotive OEMs deepen application knowledge. Expand production capacity for high-volume silica-based coatings in key regional markets.
For New Entrants and Emerging Players: Differentiate on specialized performance in high-value, underpenetrated segments like biomedical applications. Focus on developing biocompatible and antimicrobial sol-gel coatings for healthcare surfaces, a niche requiring specific regulatory approvals. A go-to-market angle emphasizing rapid certification for specific medical device classes offers a competitive advantage. Textile and fabric finishing also presents a penetrable segment for hydrophobic treatments.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across organic-inorganic hybrid coatings as R&D and certification costs rise. This market offers long-term viability due to the critical performance enhancements sol-gel technology provides across industries. Target specialized firms with proprietary formulations, strong R&D pipelines, or established application expertise in electronics or aerospace. The signal to watch is the adoption rate of self-healing coating technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Improves supply reliability for high-volume automotive demand in Germany. |
| Green Manufacturing Transition | Aligns product portfolio with stringent EU environmental standards like REACH. |
| Technology Licensing | Accelerates adoption of self-healing functionality for aerospace clients. |
| Joint Venture | Develops specialized organic-inorganic hybrid coatings for electronics applications in Silicon Valley. |
| Strategic Partnership | Expands market access for compliant water-based formulations in European construction. |
Research Approach
A standing panel of R&D directors, procurement managers, application engineers, and regulatory compliance officers provided ongoing calibration for market trends. This approach combined extensive primary interviews with industry stakeholders and rigorous secondary validation. Secondary data sources included industry association reports, chemical trade data, government environmental agency publications, and corporate financial filings. Bottom-up and top-down triangulation ensured data consistency and accuracy.
Outputs were validated against external benchmarks and existing market intelligence to ensure consistency across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, technology, end-user type, and regional regulatory clusters. CAGRs were derived from historical trends and projected market drivers, reflecting anticipated shifts. Automotive production volumes and electronics manufacturing output served as key industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside raw material price shocks or sudden shifts in environmental regulations would require recalibration. Forecasts reflect assumptions regarding technological adoption and market dynamics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Pipe Coatings Market
Coatings
Acrylic Surface Coating Market
Coatings
Pure Epoxy Powder Coatings Market
Coatings
Saudi Arabia Industrial Coatings Market
Coatings
Anti-Adhesion Coatings Market
Coatings
Asia-Pacific Automotive Refinish Coatings Market
Coatings
Thailand Architectural Coatings Market
Coatings
Insulation Coating Market
Coatings
North America Anti-Friction Coatings Market
Coatings
Global Antiviral Coatings Market
Coatings
Solvent Borne Coatings Market
Coatings
Global Surface Protection Films Market
Coatings
2K Protective Coatings Market
Coatings
Europe Thermal Spray Market
Coatings
Dispersion Coating Market
Coatings
Marine Anti Fouling Coatings Market