
 High-Barrier Pouches Market | 2026-2036
High-Barrier Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
High-Barrier Pouches Market Analysis
Foodservice distribution channels is narrowing as retail and e-commerce direct-to-consumer routes capture share of pouch-format packaged goods. Amcor leverages its global converting footprint to supply multinational food brands with customized barrier structures. Mondi Group anchors European demand through integrated kraft paper and film operations in Austria and Germany. ProAmpac competes on short-run flexibility for regional specialty food processors requiring rapid turnaround on printed pouch orders.
High-barrier pouches are multi-layer laminated flexible containers engineered with oxygen transmission rates below 0.1 cc/m²/day and moisture vapor transmission rates under 0.1 g/m²/day, typically constructed from coextruded or adhesive-laminated combinations of PET, aluminum foil, nylon, and sealant layers through blown or cast film processes followed by pouch forming and sealing. Stand-up pouches with spout closures command premium positioning in liquid food and beverage applications where shelf stability and dispensing convenience converge. Flat pouches dominate pharmaceutical unit-dose packaging where foil-based structures provide light and moisture protection for moisture-sensitive APIs. PET-containing laminates face margin compression as brand owners evaluate mono-material alternatives against evolving recyclability requirements.
FDA regulations govern food-contact barrier materials under 21 CFR 177, while the EU Packaging and Packaging Waste Regulation sets mandatory recyclability targets and extended producer responsibility frameworks that reshape material selection across the value chain. ECHA oversight of substances of very high concern under REACH restricts certain adhesive chemistries and coatings used in legacy multi-layer constructions. Stakeholders must monitor regulatory divergence between US and European recyclability standards when designing next-generation barrier platforms.
Market Dynamics
Recyclability mandates from the EU Packaging and Packaging Waste Regulation are forcing material re-engineering across the high-barrier pouches value chain, compressing demand for aluminum-foil laminates while accelerating mono-material and paper-based alternatives.
Growth Catalysts
- Retort pouch adoption:Food processors in the United States are converting shelf-stable ready-to-eat lines from cans to retort pouches for logistics efficiency and consumer convenience.
- EU regulatory pressure:Extended producer responsibility frameworks under the EU Packaging and Packaging Waste Regulation create compliance-driven demand for certified recyclable barrier structures.
- Pharmaceutical unit-dose expansion:Foil-based flat pouches for moisture-sensitive APIs are penetrating generic drug manufacturing in India and Brazil.
Market Restraints
- Aluminum foil supply concentration:Chinese smelter consolidation and energy-cost volatility create input price instability for multi-layer laminators dependent on foil barriers.
- Technical limitation of mono-materials:Current polyethylene and polypropylene mono-materials fail to match the oxygen transmission rates of foil-based structures below 0.1 cc/m²/day.
- REACH chemical restrictions:ECHA oversight of substances of very high concern limits legacy adhesive chemistries used in nylon-foil laminations.
Strategic Opportunities
- Underpenetrated pharmaceutical cold chain:Biologic drug manufacturers in Germany and Switzerland require ultra-high-barrier pouches for temperature-sensitive injectables.
- Regulatory tailwind from deposit-return schemes:Italy and Spain are piloting extended producer responsibility models that reward recyclable flexible packaging with fee reductions.
- Technology convergence:Integration of printed electronics for freshness indicators with barrier substrates creates smart packaging differentiation in premium food segments.
Industry Challenges
- Adhesive formulation expertise gap:Converters lack chemists capable of developing water-based laminating adhesives that meet both bond strength and recyclability standards.
- Certification timeline compression:FDA food-contact notification reviews under 21 CFR 177 now average 18-24 months for novel barrier materials, delaying commercialization.
- Legacy equipment retrofit costs:Slitting and sealing lines designed for aluminum-foil structures require six-figure capital outlays to handle thinner, heat-sensitive mono-material films.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Barrier Pouches Market |
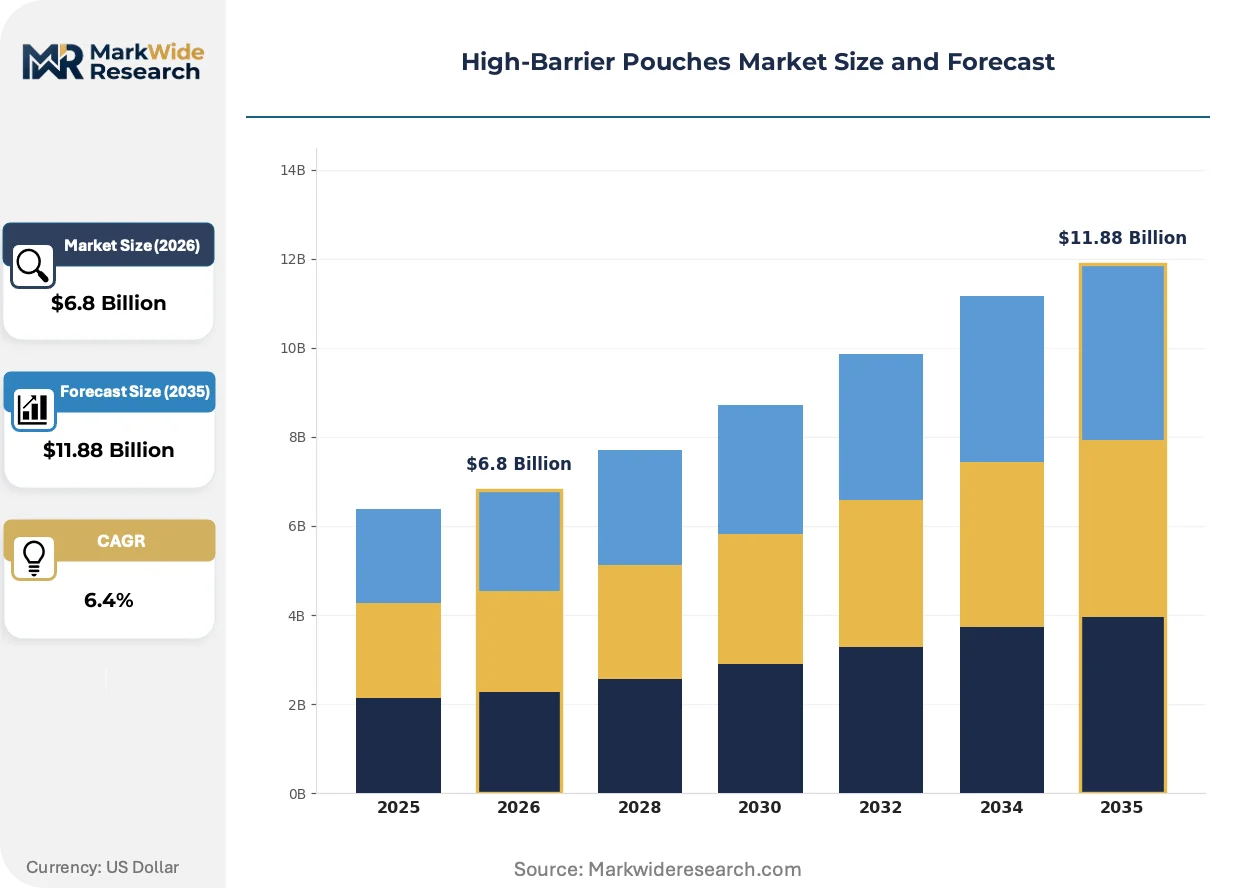
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Zipper Pouches, Pillow Pouches Material: Foil, PET, Nylon, LDPE End User: Food & Beverage, Pharmaceuticals, Personal Care, Household Products Closure Type: Zip Lock, Heat Seal, Tear Notch, Spout |
| Companies Covered | Amcor, Mondi Group, Sealed Air, Sonoco Products, Bemis, Berry Global, Constantia Flexibles, Huhtamaki, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Barrier Pouches Market Emerging Trajectories
Barrier technology is pivoting from passive oxygen exclusion toward active and intelligent functions, while regulatory jurisdictions compete to set the recyclability standard that will dominate next-generation material specifications.
Metallized polyethylene terephthalate films with enhanced barrier coatings are displacing aluminum foil in snack and dry food applications where moderate oxygen protection suffices. European brand owners are adopting these structures fastest to preempt compliance costs under the EU Packaging and Packaging Waste Regulation. The technology is migrating from premium positioning toward mid-tier private label lines as coating consistency improves and unit economics compress.
REACH authorization requirements for phthalate-based plasticizers and certain epoxy-based coatings are eliminating legacy chemistries from food-contact laminates. The regulation forces converters to validate alternative adhesion promoters and heat-seal layers through accelerated aging protocols. Small and mid-sized European converters face disproportionate testing burdens compared to integrated multinationals with captive laboratories.
Direct-to-consumer subscription models for specialty foods are fragmenting order sizes and compressing production runs. Regional specialty food processors now specify digital printing with variable data to support SKU proliferation without plate costs. This pattern concentrates in the United States and United Kingdom where e-commerce penetration in packaged foods exceeds continental European levels.
High-Barrier Pouches Market Segmentation
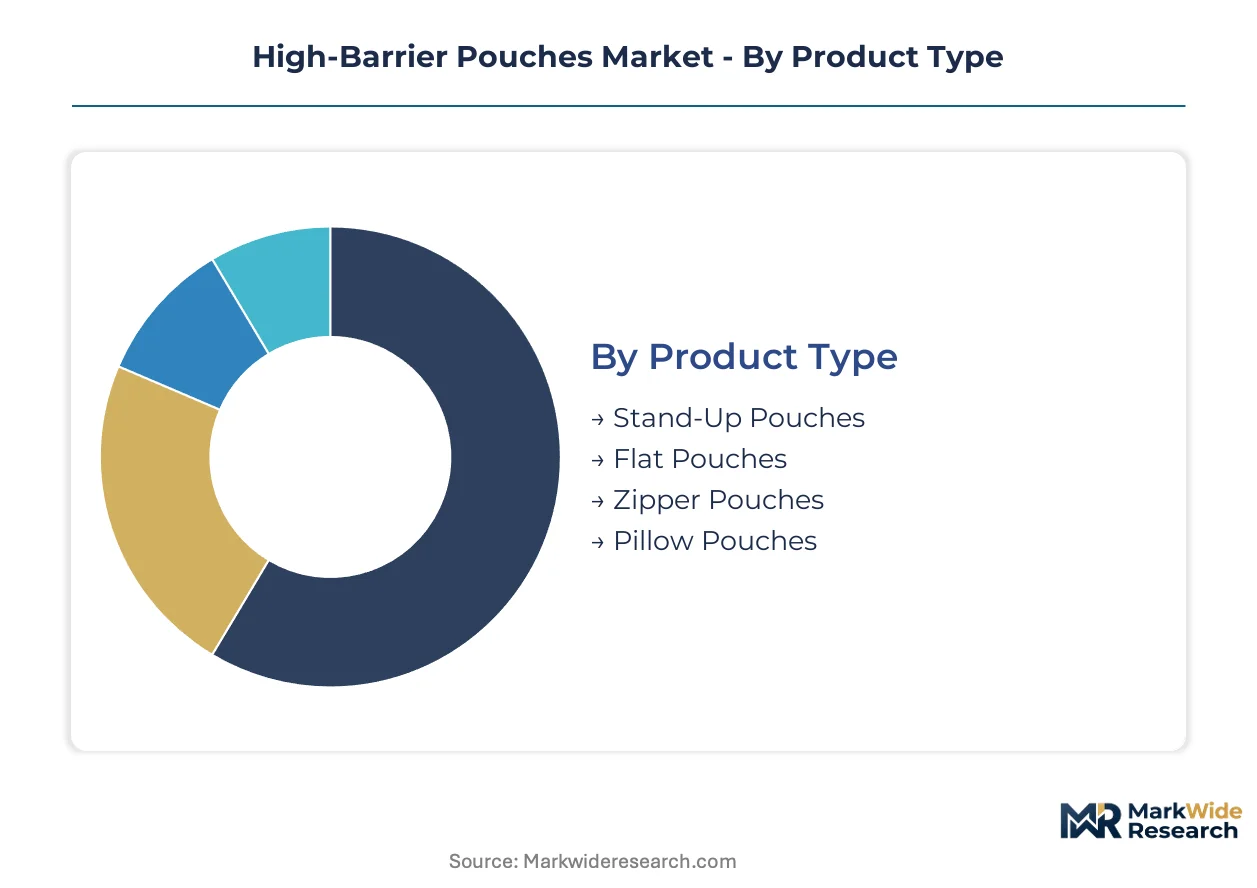
High-barrier pouch specifications diverge sharply across application requirements, with oxygen transmission rates and mechanical durability demands dictating material selection and closure architecture. Each segmentation axis reveals distinct margin profiles and regulatory exposure that reshape competitive positioning.
Product Type:
Mature formats dominate volume while emerging configurations capture premium positioning through functional differentiation.
- Stand-Up Pouches:Gusseted bottom structures with multi-layer PET/foil/PE laminations provide shelf stability and vertical display efficiency for liquid foods. Retort-capable versions are penetrating US ready-to-eat meal lines as processors abandon rigid cans.
- Flat Pouches:Three- or four-side-seal foil laminates deliver sub-0.1 cc/m²/day oxygen barriers for pharmaceutical unit-dose packaging in India and Brazil. Demand concentrates in generic drug manufacturing where moisture protection for APIs is non-negotiable.
- Zipper Pouches:Reclosable track systems integrated with barrier substrates serve snack and dry goods segments requiring repeated access without compromising shelf life.
- Pillow Pouches:Simple two-seal formats with moderate barrier properties address cost-sensitive dry food and confectionery applications where extended shelf life is secondary to unit economics.
Flat pouches retain volume leadership in pharmaceutical applications; stand-up pouches with spout integration hold the steepest expansion curve in liquid food segments.
Material:
Cost tiers separate commodity polymers from engineered barrier layers, with recyclability mandates compressing demand for legacy multi-layer constructions.
- Foil:Aluminum layers at 6-9 micron thickness deliver the benchmark oxygen and moisture barriers for pharmaceutical and retort applications. Chinese smelter consolidation and energy-cost volatility are destabilizing input pricing for European and North American laminators.
- PET:Biaxially oriented films with metallized or oxide coatings are displacing foil in snack applications where moderate barriers suffice. European brand owners are adopting these structures fastest to preempt EU Packaging and Packaging Waste Regulation compliance costs.
- Nylon:Polyamide layers provide puncture resistance and thermal stability in retort pouches and vacuum-packaged proteins.
- LDPE:Sealant layers and mono-material substrate candidates face technical limitations in matching foil-grade oxygen transmission rates below 0.1 cc/m²/day.
Foil retains barrier performance leadership; PET-based alternatives are climbing fastest as recyclability requirements harden.
End User:
Application-driven specifications create divergent certification and volume requirements across customer categories.
- Food & Beverage:Retort pouches for shelf-stable meals and barrier bags for specialty coffee drive the largest absolute demand. FDA food-contact notifications under 21 CFR 177 govern material approvals, with review timelines stretching 18-24 months for novel barrier substrates.
- Pharmaceuticals:Foil-based unit-dose packaging for moisture-sensitive APIs commands the highest per-unit margins. Swiss and German biologic drug manufacturers are emerging as demand centers for ultra-high-barrier cold chain applications.
- Personal Care:Moderate barrier requirements for creams and serums favor cost-optimized PET/PE constructions with aesthetic printing.
- Household Products:Aggressive chemical resistance needs in detergents and cleaners drive nylon-heavy laminations with enhanced seal integrity.
Food and beverage retains volume leadership; pharmaceutical applications hold the steepest margin expansion trajectory.
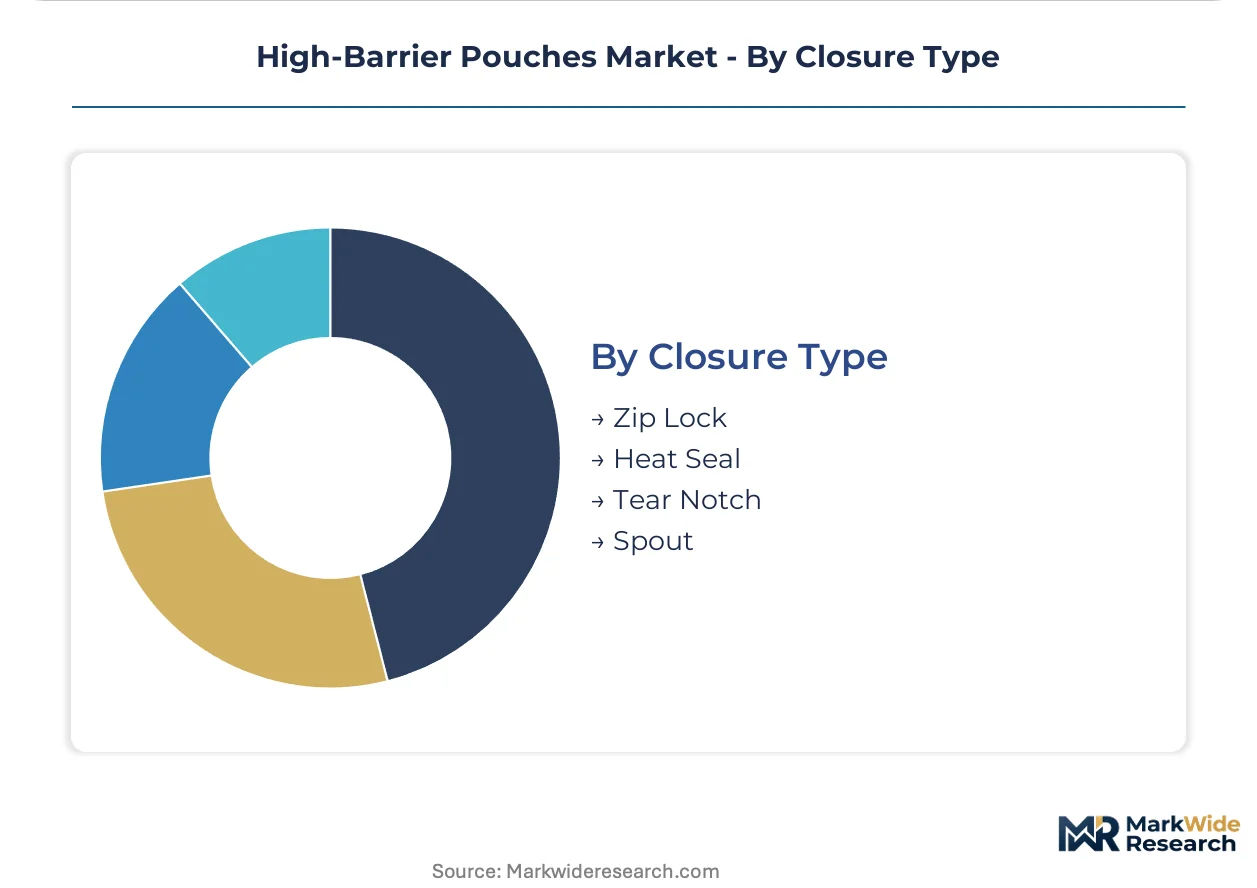
Closure Type:
Customer type and dispensing convenience requirements determine closure complexity and cost layering.
- Zip Lock:Integral track systems enable repeated reclosure in snack and household segments without compromising barrier integrity.
- Heat Seal:Permanent fusion bonds provide tamper evidence and maximum barrier protection for pharmaceutical and retort applications.
- Tear Notch:Controlled-opening features balance accessibility with seal integrity in single-serve food and personal care formats.
- Spout:Fitment-integrated closures command premium positioning in liquid food and beverage applications where controlled dispensing converges with shelf stability requirements.
Heat seal retains volume leadership across barrier-critical applications; spout closures are expanding most quickly in premium liquid food segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extended producer responsibility frameworks are redirecting investment flows toward recyclable barrier technologies, with regulatory divergence between jurisdictions creating distinct compliance obligations for multinational converters.
United States
Retort pouch adoption for shelf-stable ready-to-eat meals is accelerating as food processors abandon rigid cans for logistics efficiency. FDA food-contact notifications under 21 CFR 177 govern material approvals, with review timelines stretching 18-24 months for novel substrates. Flexible packaging demand concentrates in the Midwest manufacturing corridor around Chicago and Milwaukee.
Germany
The EU Packaging and Packaging Waste Regulation is tightening recyclability mandates for multi-layer structures, forcing material re-engineering across the value chain. ECHA oversight of substances of very high concern under REACH restricts legacy adhesive chemistries used in nylon-foil laminations. Hamburg and Munich anchor the country's flexible packaging cluster where brand owners pilot mono-material alternatives.
India
Foil-based flat pouches for moisture-sensitive APIs are penetrating generic drug manufacturing, commanding premium margins in pharmaceutical unit-dose packaging. FSSAI food safety standards and CDSCO pharmaceutical regulations create dual compliance frameworks for converters serving both sectors. Ahmedabad and Mumbai house the dominant converting operations supplying domestic and export markets.
Switzerland
Biologic drug manufacturers require ultra-high-barrier pouches for temperature-sensitive injectables, creating demand for cold-chain-compatible barrier structures. Swissmedic pharmaceutical regulations enforce stringent stability requirements for packaging materials. Basel and Zurich host specialized converters serving the country's precision pharmaceutical manufacturing base.
Brazil
Generic pharmaceutical manufacturing expansion is driving foil-based unit-dose packaging demand for moisture-sensitive APIs. ANVISA pharmaceutical regulations govern packaging material approvals with emphasis on tropical stability testing. São Paulo state concentrates the country's flexible packaging converting capacity.
High-Barrier Pouches Market Vendor Landscape
On the supply side, the industry is consolidating around integrated multinationals with captive laboratory capabilities and regional specialists competing on short-run flexibility. Tier-one players combine global converting footprints with customized barrier engineering, while mid-sized converters focus on rapid turnaround for specialty food processors. Strategic archetypes include integrated material-science conglomerates, regional flexible packaging specialists, and private-equity-backed roll-up platforms. Dominant competitive moves center on backward integration into film extrusion and geographic expansion through asset-light partnerships.
Within the integrated multinational tier, Amcor and Mondi Group exemplify scale-driven positioning, while ProAmpac occupies a specialist niche. Amcor leverages its global converting footprint across multiple continents. Mondi Group anchors European demand through integrated kraft paper and film operations. ProAmpac competes on short-run flexibility for regional specialty food processors requiring rapid turnaround on printed pouch orders.
| Leading Market Players |
|---|
| Amcor |
| Mondi Group |
| Sealed Air |
| Sonoco Products |
| Bemis |
| Berry Global |
| Constantia Flexibles |
| Huhtamaki |
| ProAmpac |
| Others |
Supply Flow & Price Mechanics
Hamburg's flexible packaging cluster anchors European converting capacity for high-barrier laminates, with its integrated film extrusion and metallization assets concentrating pricing power among German and Austrian converters serving brand owners under tightening EU recyclability mandates. This geographic concentration creates asymmetric leverage where multi-layer foil specialists command premium positioning against mono-material challengers facing technical performance gaps.
Pricing Analysis
Certification level (FDA-grade under 21 CFR 177 versus standard industrial grades) creates the primary spread between premium and economy tiers in high-barrier pouches. Three-tier pricing structure across premium, standard, and economy levels reflects material complexity, with foil-based pharmaceutical laminates at the apex and commodity PE constructions at the base. Cost compression in standard-tier snack packaging is intensifying because European brand owners are fast-tracking metallized PET adoption to preempt extended producer responsibility fees. Regional specialty food processors exhibit highest price sensitivity due to fragmented order sizes, while Swiss biologic drug manufacturers show lowest sensitivity given non-negotiable barrier performance requirements.
Supply Chain Analysis
Upstream feedstock dynamics center on aluminum ingot flows from Chinese smelters, biaxially oriented PET resin from Germany and South Korea, and polyamide grades from Belgium and the United States. High-barrier pouch manufacturing draws from these concentrated raw material streams, with foil laminators particularly tethered to Asian metal supply subject to energy-cost volatility. Single-source vulnerability in 6-9 micron aluminum foil creates structural risk for European converters dependent on Chinese smelter consolidation patterns. Distribution runs through integrated multinational direct accounts for multinational food brands, with regional converters serving specialty processors via distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high-barrier pouches market is experiencing high-growth disruption as EU Packaging and Packaging Waste Regulation recyclability mandates force material re-engineering across the value chain, compressing legacy multi-layer demand while accelerating certified mono-material and paper-based alternatives.
For Market Incumbents: Insulate core pharmaceutical and retort food accounts through backward integration into captive film extrusion and metallization assets, particularly in Germany and Austria where regulatory pilot programs reward recyclable structures with fee reductions. Prioritize FDA food-contact notification investments for novel barrier substrates to secure 18-24 month approval runway ahead of competitors, while defending against mono-material challengers through performance guarantees on oxygen transmission rates below 0.1 cc/m²/day. For New Entrants and Emerging Players: Establish a beachhead in India's generic pharmaceutical unit-dose packaging segment, where foil-based flat pouch demand is penetrating rapidly and incumbent converter capacity lags CDSCO regulatory compliance requirements. Target Swiss and German biologic cold-chain applications as the most penetrable ultra-high-barrier niche, leveraging water-based adhesive expertise gaps among legacy converters as a technical differentiation angle for temperature-sensitive injectables. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with integrated laboratory capabilities and geographic diversification across EU regulatory jurisdictions. Long-term viability hinges on material-science adaptability rather than scale economies, making mid-sized European specialists with captive R&D and established brand-owner relationships the preferred acquisition archetype. Monitor ECHA REACH authorization timelines for phthalate-based plasticizers and epoxy coatings as the critical signal for competitive inflection, as these restrictions will eliminate legacy chemistries and reward early alternative validation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive supply of metallized PET and nylon reduces input price volatility from Chinese and German resin markets. |
| FDA Food-Contact Notification Investment | Early validation of novel barrier substrates under 21 CFR 177 secures 18-24 month competitive moat in pharmaceutical applications. |
| Water-Based Adhesive R&D Partnership | Collaboration with European chemical suppliers addresses REACH restrictions while meeting bond strength and recyclability standards. |
| Mono-Material Pilot Program Enrollment | Participation in Italy and Spain extended producer responsibility pilots positions converters for fee reduction rewards. |
| Digital Printing Capability Expansion | Variable data printing supports SKU proliferation for direct-to-consumer specialty food processors without plate cost penalties. |
Methodological Framework
Desk research of FDA food-contact notification filings, ECHA REACH substance restriction updates, EU Packaging and Packaging Waste Regulation implementation documents, and flexible packaging trade association technical reports preceded structured interviews with converting plant managers, brand owner packaging engineers, adhesive supplier technical directors, and pharmaceutical regulatory affairs specialists. Primary fieldwork combined with secondary validation across customs records, SEC 10-K filings of listed packaging companies, and industry production databases enabled bottom-up and top-down triangulation of market sizing.
Assumptions regarding EU regulatory enforcement timelines, aluminum smelter capacity utilization in China, and pharmaceutical cold-chain expansion rates were held fixed across baseline scenarios while varying mono-material barrier performance improvement trajectories and extended producer responsibility fee structures in sensitivity cases. Segmentation modeling incorporated product type, material composition, end-use application, and closure architecture dimensions, with CAGRs derived from regression analysis against historical patent filing trends and capital expenditure announcements from integrated multinationals.
Stress conditions across Chinese energy policy volatility, FDA review timeline extensions, and REACH authorization scope expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and acknowledge that ECHA substance restrictions or breakthrough mono-material barrier technologies could materially revise trajectory. Cross-checking against European flexible packaging production statistics and pharmaceutical packaging import data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Wrap-Around Packers Market
Pouch
Vacuum Chamber Pouches Market
Pouch
North America Stand-Up Pouch Packaging Market
Pouch
Middle East and Africa Pouch Packaging Market
Pouch
Recyclable PE Pouch Market
Pouch
Global Boil-In Bags Market
Pouch
Stand-Up Pouches Market
Pouch
Italy Pouch Packaging Market
Pouch
Standcap Pouch Market
Pouch
Morocco Pouch Packaging Market
Pouch
Aluminum-Free Food Pouch Market
Pouch
Doyen Style Pouches Market
Pouch
PCR Pouches Market
Pouch
UAE Pouch Packaging Market
Pouch
GCC Retort Pouches Market
Pouch
United States Retort Pouches Market